
 Global Focal Segmental Glomerulosclerosis Market | 2026-2036
Global Focal Segmental Glomerulosclerosis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Focal Segmental Glomerulosclerosis Market Intelligence
The integration of genetic sequencing and biomarker discovery into clinical trial design is reconfiguring the therapeutic development pipeline for FSGS. This shift enables more targeted drug candidates, moving beyond broad-spectrum immunosuppressants. Travere Therapeutics leverages its expertise in rare kidney disease pathways. Chinook Therapeutics specializes in precision medicines for kidney diseases, while Novartis AG anchors its strategy with large-scale immunology research platforms.
Focal segmental glomerulosclerosis (FSGS) is a rare kidney disease characterized by scarring in parts of the glomeruli, the kidney's filtering units. The primary clinical objective of treatment is to reduce proteinuria and slow the progression towards end-stage renal disease. Within therapy areas, nephrology and immunology command the majority of R&D investment and clinical focus. Specialty clinics and academic hospitals represent the primary end-user segments, serving as centers for both advanced patient care and pivotal clinical trials.
Regulatory frameworks from the U.S. FDA, the European Medicines Agency (EMA), and Japan's PMDA are critical for market entry. These agencies' orphan drug designations and accelerated approval pathways directly influence development timelines and commercial viability for new FSGS therapies. The key decision for developers will be navigating the evolving diagnostic criteria that differentiate subtypes of the disease for targeted treatment.
Market Dynamics
The central force shaping the FSGS market is the scientific reclassification of the disease from a single entity into multiple subtypes defined by genetic and molecular signatures. This shift is steering investment away from broad immunosuppressants toward precision therapies targeting specific pathogenic pathways.
Growth Catalysts
- Orphan Drug Incentives:Regulatory frameworks, including the FDA's orphan drug designation and the EMA's parallel program, offer market exclusivity and tax credits, significantly de-risking investment in novel FSGS therapies for biopharmaceutical companies.
- Genomic Technology Advancement:The increasing accessibility and decreasing cost of next-generation sequencing enable the identification of specific genetic mutations, such as those in APOL1, which is facilitating the design of targeted clinical trials.
- Clinical Trial Infrastructure:A high concentration of specialized nephrology centers and academic hospitals in countries like the United States and Germany provides a robust platform for conducting complex, multi-center studies required for new drug approvals.
Market Restraints
- Diagnostic Complexity:The reliance on invasive kidney biopsies and the subjective nature of histopathological interpretation create diagnostic delays and inconsistencies, complicating patient recruitment and stratification for clinical trials.
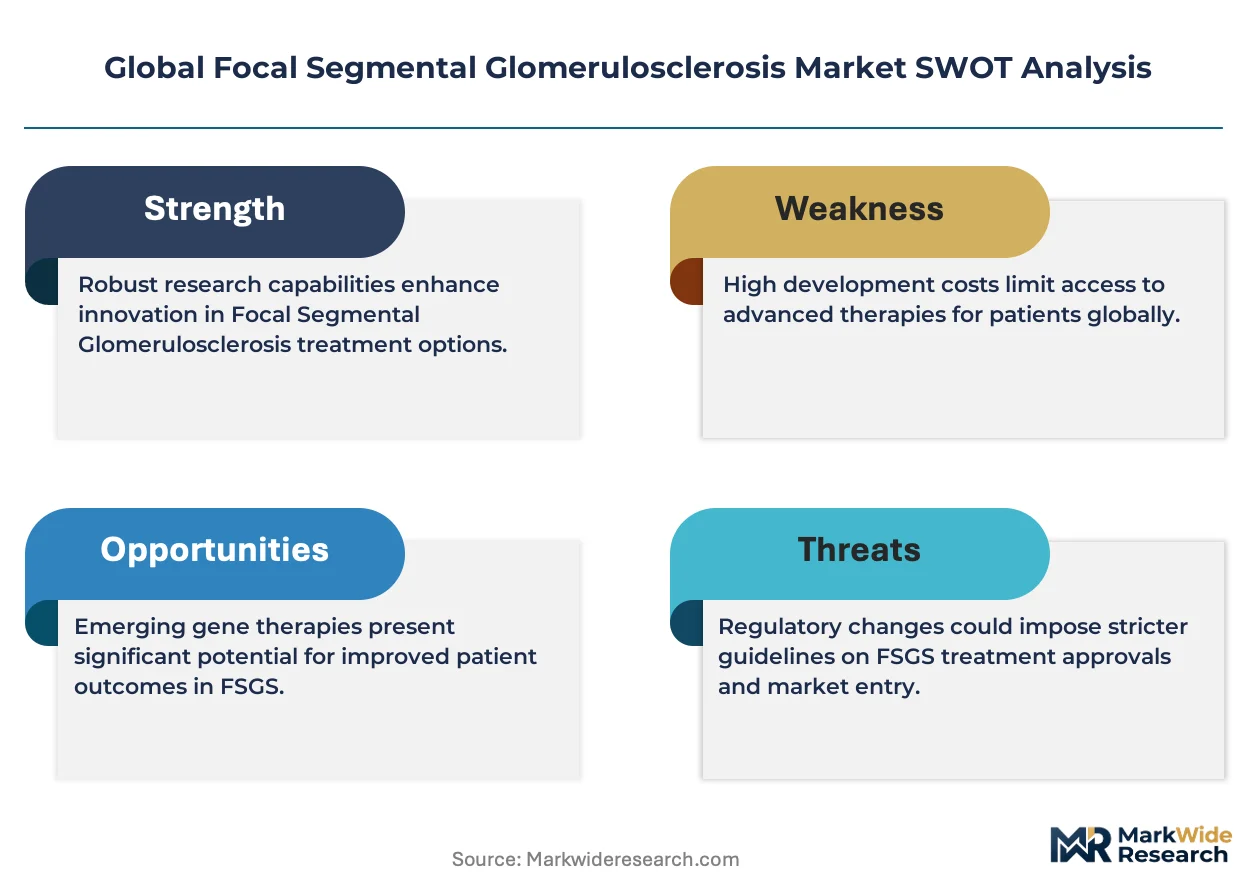
- High Development Costs:The long duration required to assess primary endpoints like progression to end-stage renal disease, combined with the rarity of the patient population, results in extremely high per-patient costs for pivotal trials.
- Heterogeneous Disease Progression:The variable rate at which FSGS progresses among patients, even within the same subtype, makes it difficult to demonstrate a drug's efficacy conclusively, posing a significant hurdle for regulatory approval.
Strategic Opportunities
- Biomarker Discovery:Developing and validating non-invasive biomarkers, such as specific proteins in urine or blood, that can predict treatment response or disease progression represents a major commercial and clinical opportunity for diagnostic and pharma companies.
- Pediatric Population Focus:There is a significant unmet need for safe and effective FSGS treatments specifically approved for children, creating an opportunity for developers to pursue pediatric indications with dedicated regulatory support.
- Targeting Podocyte Biology:A deeper understanding of the podocyte's role in glomerular filtration offers a fertile area for therapeutic innovation, with opportunities for drugs that protect or restore podocyte function and integrity.
Industry Challenges
- Patient Recruitment Bottlenecks:The rarity of FSGS makes it exceptionally difficult to enroll sufficient numbers of patients into clinical trials, often requiring global, multi-year recruitment efforts that delay development timelines.
- Endpoint Standardization:A lack of universal agreement on surrogate endpoints for clinical trials, particularly the level of proteinuria reduction that reliably predicts long-term kidney preservation, creates regulatory uncertainty for drug developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Focal Segmental Glomerulosclerosis Market |
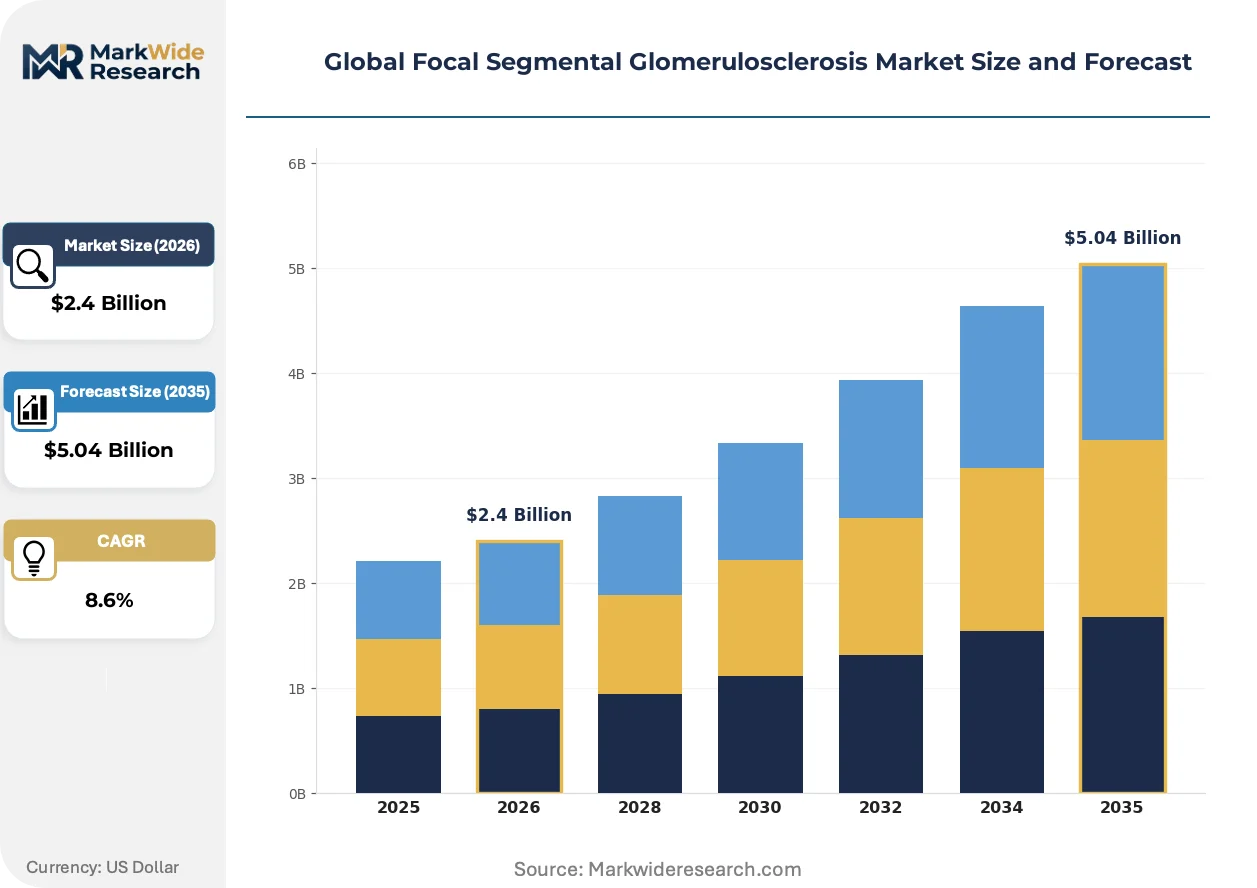
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.04 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Nephrology, Immunology, Genetic Disorders, Renal Replacement, Proteinuria Management Dosage Form: Oral Tablets, Injectable Solutions, Infusion, Topical Applications, Sublingual Drops Route of Administration: Intravenous, Subcutaneous, Oral, Intramuscular, Transdermal End User: Specialty Clinics, Dialysis Centers, Research Institutes, Pharmaceutical Companies, Academic Hospitals |
| Companies Covered | Pfizer Inc., Variant Pharmaceuticals, Inc., Travere Therapeutics, Retrophin, Inc., ChemoCentryx, Inc., Novartis AG, Chinook Therapeutics, Dimerix Limited, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Focal Segmental Glomerulosclerosis Market Strategic Shifts & Innovations
Precision medicine is fundamentally altering the FSGS therapeutic landscape. The convergence of genomic data, advanced diagnostics, and targeted drug design is moving treatment protocols beyond generalized care and toward patient-specific interventions based on molecular drivers of the disease.
Digital pathology platforms that incorporate artificial intelligence are gaining traction in clinical research. These systems use algorithms to quantify scarring and cellular changes in kidney biopsy images with high precision, reducing inter-observer variability. Academic medical centers are adopting this technology to standardize endpoint assessment in trials, as it is digitizing the historically subjective process of histopathological analysis and generating more reliable data for regulatory submissions.
The U.S. FDA's accelerated approval pathway is a critical factor influencing development strategy. This program allows for earlier approval of drugs for serious conditions that fill an unmet medical need based on a surrogate endpoint, such as a significant reduction in proteinuria. Biopharmaceutical firms targeting FSGS are designing trials around these endpoints to shorten time-to-market, though they must commit to post-approval studies to verify clinical benefit.
A shift toward patient-centric trial design is changing how efficacy is measured. This involves incorporating patient-reported outcomes (PROs) and quality-of-life metrics as key secondary endpoints, moving beyond purely clinical data like proteinuria levels. This trend, strongly advocated by patient groups in the United States and Europe, is forcing sponsors to demonstrate that a new therapy not only improves lab values but also tangibly benefits a patient's daily life.
Global Focal Segmental Glomerulosclerosis Market Segmentation
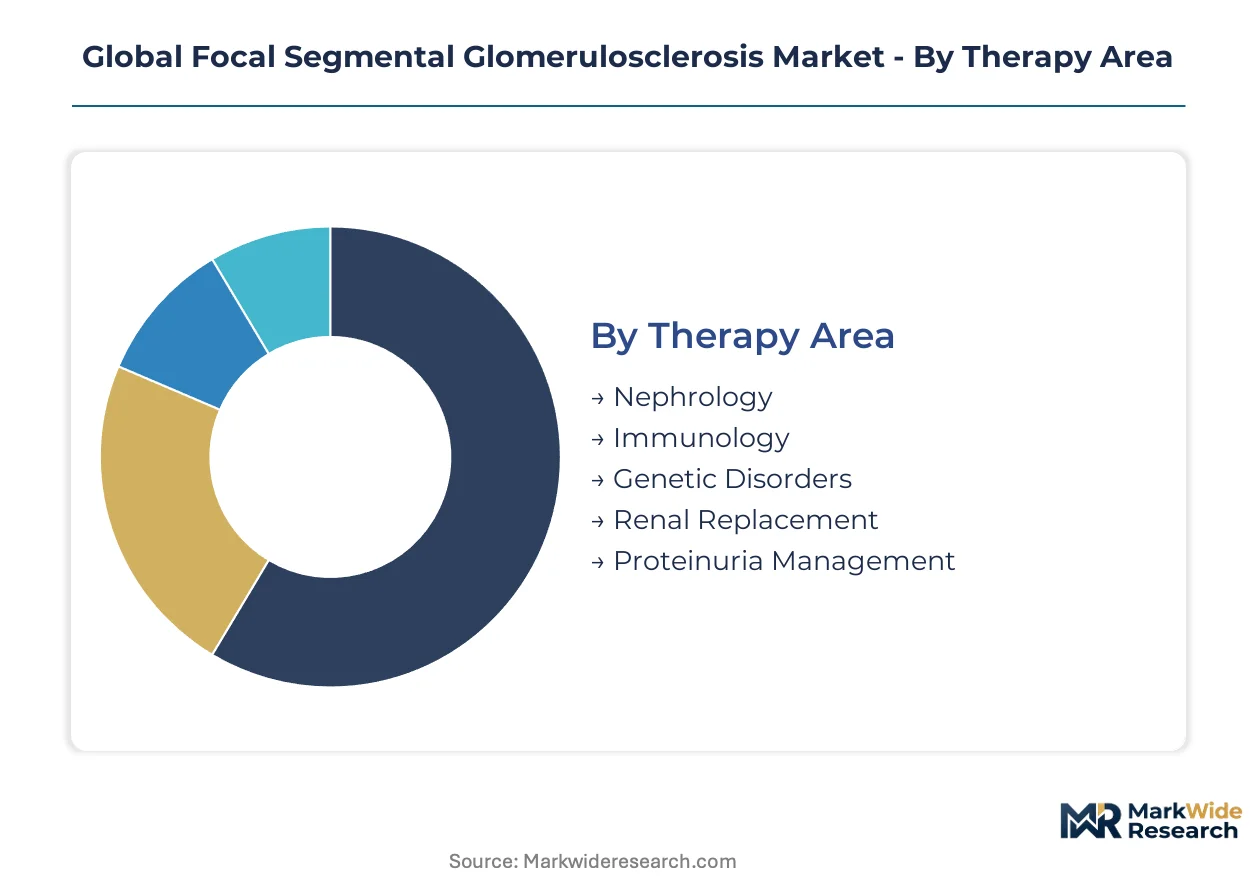
The Global Focal Segmental Glomerulosclerosis Market is comprehensively analyzed across key segmentation parameters, revealing distinct demand patterns and therapeutic approaches. This structured breakdown highlights where investment and patient care converge for this rare kidney disease, guiding strategic development.
Therapy Area:
The after-sales-service intensity for FSGS therapies varies significantly across therapy areas, reflecting the specialized medical oversight required for patient management.
- Nephrology:This area focuses on the diagnosis, treatment, and management of kidney diseases, including FSGS, utilizing a range of pharmacological and supportive interventions. Demand for advanced nephrology treatments is highest in countries with established healthcare systems like the United States, driven by a concentration of specialized clinics.
- Immunology:This segment involves therapies targeting the immune system, which often plays a role in the pathogenesis of FSGS, encompassing immunosuppressants and immunomodulators. Investment in immunology research is significant within academic hospitals, particularly in Germany, due to its strong research infrastructure.
- Genetic Disorders:This segment addresses FSGS subtypes linked to specific genetic mutations, opening avenues for gene-targeted therapies and precision medicine.
- Renal Replacement:This category includes dialysis and kidney transplantation, serving as life-sustaining treatments for patients progressing to end-stage renal disease.
- Proteinuria Management:Therapies in this area aim to reduce protein leakage in urine, a primary clinical objective for slowing disease progression in FSGS patients.
Nephrology therapies represent the largest segment by patient volume. Immunology therapies are expanding rapidly due to targeted research.
Dosage Form:
The cost tier of FSGS dosage forms directly impacts patient access and healthcare system budgets, with advanced formulations often incurring higher expenses.
- Injectable Solutions:These formulations deliver therapeutic agents directly into the bloodstream or subcutaneous tissue, often preferred for biologics and fast-acting medications. Injectable solutions are frequently administered in specialty clinics for precise dosing and patient monitoring.
- Oral Tablets:Oral tablets provide a convenient and non-invasive method of drug delivery, supporting long-term adherence for chronic FSGS management. Patient preference and ease of administration drive demand for oral options in home-based care.
- Infusion:Infusion therapies involve administering large volumes of medication slowly into a patient's vein, commonly used for complex biologics or high-dose treatments.
- Topical Applications:This segment includes treatments applied directly to the skin, though less common for systemic FSGS management, it may be explored for localized effects.
- Sublingual Drops:Sublingual drops offer rapid absorption through mucous membranes under the tongue, providing an alternative for certain medications.
Injectable Solutions provide rapid systemic delivery. Oral Tablets offer patient convenience for chronic management.
Route of Administration:
The application scope for FSGS therapies dictates the preferred route of administration, influencing treatment efficacy and patient adherence.
- Intravenous:This route involves administering drugs directly into a vein, ensuring rapid and complete systemic availability, crucial for acute interventions or complex biologics. Intravenous administration is central to treatment protocols within academic hospitals for severe FSGS cases.
- Oral:Oral administration allows patients to take medication by mouth, offering significant convenience for long-term maintenance therapies. The oral route dominates outpatient management of stable FSGS patients.
- Subcutaneous:Subcutaneous injections deliver medication into the tissue layer just under the skin, suitable for self-administration and sustained release.
- Intramuscular:Intramuscular injections introduce medication into a muscle, providing a slower release than intravenous but faster than subcutaneous routes.
- Transdermal:Transdermal patches deliver medication through the skin, offering a continuous and controlled release over an extended period.
Intravenous administration is critical for acute interventions. Oral routes support long-term therapeutic regimens.
End User:
The customer type for FSGS treatment and research is highly specialized, demanding specific infrastructure and expertise for patient care and clinical trials.
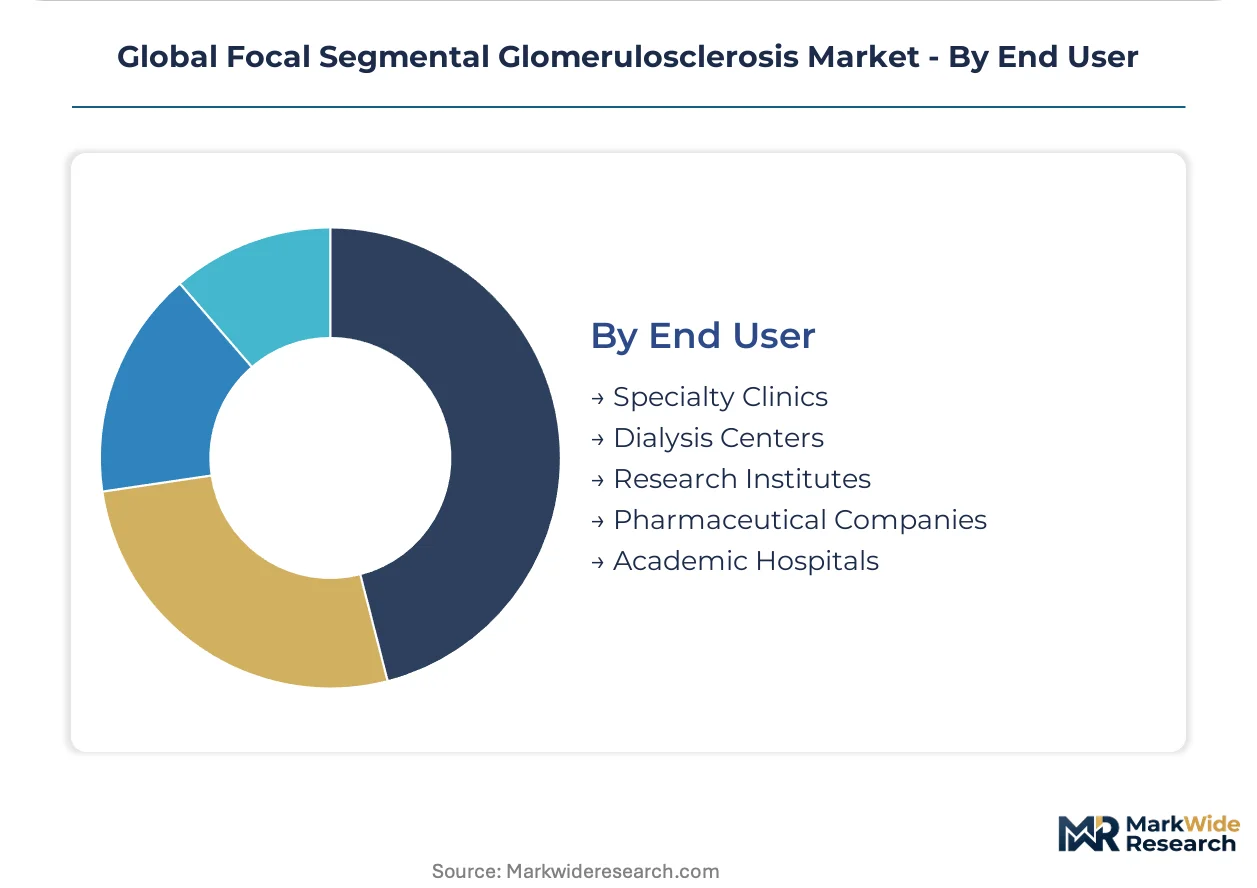
- Specialty Clinics:These facilities focus exclusively on specific medical conditions, offering advanced diagnostic capabilities and specialized treatment regimens for FSGS patients. Specialty clinics in the United States attract significant patient volumes due to their focused expertise.
- Academic Hospitals:Academic hospitals combine patient care with medical education and research, serving as crucial centers for pivotal clinical trials and the development of novel FSGS therapies. These institutions, particularly in Germany, drive innovation through their research platforms.
- Dialysis Centers:Dialysis centers provide life-sustaining renal replacement therapy for FSGS patients who have progressed to end-stage renal disease.
- Research Institutes:These organizations are dedicated to scientific investigation, contributing to biomarker discovery and the understanding of FSGS pathogenesis.
- Pharmaceutical Companies:Pharmaceutical companies are key end-users as they conduct extensive research and development for new FSGS treatments, often collaborating with academic centers.
Specialty Clinics and Academic Hospitals serve as primary hubs for advanced FSGS care. Research Institutes drive foundational scientific discoveries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty clinics and academic hospitals in the United States concentrate significant demand for advanced FSGS therapies. These centers drive clinical trial activity and early adoption of novel treatments. The robust research infrastructure supports complex therapeutic development.
United States
Demand for FSGS treatments is high, driven by a concentration of specialized nephrology centers and advanced research capabilities. The FDA's orphan drug designation pathway significantly incentivizes novel therapy development. Major academic medical centers in Boston and San Francisco lead pivotal clinical trials.
Germany
Academic hospitals and a strong research infrastructure underpin demand for immunology-focused FSGS therapies. The European Medicines Agency (EMA) provides accelerated approval pathways for rare diseases. Research clusters in Berlin and Munich are advancing biomarker discovery.
Japan
Patient demand for effective FSGS treatments reflects a well-developed healthcare system and a focus on precision medicine. The PMDA's regulatory framework supports the entry of innovative therapies. Clinical research institutions in Tokyo are actively participating in global trials.
Switzerland
Investment in novel FSGS therapies benefits from a strong pharmaceutical industry and specialized research facilities. Swissmedic regulations facilitate the development of advanced biologics. Basel's life sciences hub contributes significantly to rare disease drug discovery.
India
The growing patient population and increasing access to advanced diagnostics are driving demand for FSGS management. The country's national pharmaceutical regulator is streamlining clinical trial approvals. Major metropolitan centers like Mumbai and Delhi are expanding specialized nephrology services.
Global Focal Segmental Glomerulosclerosis Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in the FSGS therapeutic landscape. The market exhibits a tiered structure, with established pharmaceutical giants alongside nimble biotech firms focused on orphan diseases. Strategic archetypes include large-scale immunology research platforms, rare kidney disease pathway experts, and precision medicine developers. Companies are pursuing both technology licensing and strategic partnerships to expand their pipelines and accelerate drug development.
Within the rare kidney disease specialist archetype, Travere Therapeutics Inc. exemplifies focused development on specific disease pathways, leveraging its expertise for orphan indications. Chinook Therapeutics Inc. occupies a position as a precision medicine developer for kidney diseases, emphasizing molecularly targeted interventions. Novartis AG, a Swiss pharmaceutical company, anchors the large-scale immunology research platform segment, leveraging its extensive R&D capabilities for broader therapeutic applications in complex conditions like FSGS. These companies collectively represent distinct approaches to addressing the complex pathogenesis of FSGS, from targeted genetic interventions to broad immunomodulation strategies.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Variant Pharmaceuticals, Inc. |
| Travere Therapeutics |
| Retrophin, Inc. |
| ChemoCentryx, Inc. |
| Novartis AG |
| Chinook Therapeutics |
| Dimerix Limited |
| GlaxoSmithKline plc |
| Others |
Cost & Logistics Intelligence
Research clusters in Berlin and Munich, driving innovation in biomarker discovery, influence the downstream pricing power for novel FSGS therapies. The specialized nature of drug development for rare diseases, particularly biologics, often correlates with premium pricing structures and complex supply logistics.
Pricing Analysis
Cost-plus contract patterns, often indexed to clinical development milestones, underpin initial pricing strategies for novel FSGS therapies. Price differentiation stems from orphan drug designation, the level of clinical efficacy demonstrated in reducing proteinuria, and specialized after-sales patient support programs. Pricing pressure tends to be upward, driven by extensive research and development costs and the specialized manufacturing requirements for advanced biologics. Payer organizations exhibit the highest price sensitivity, while academic hospitals and specialty clinics prioritize therapeutic effectiveness and patient outcomes.
Supply Chain Analysis
Export-control regimes for advanced biological materials and specialized manufacturing technologies limit the free flow of key inputs for FSGS therapies. Supply concentration centers in the United States, Germany, and Switzerland, countries with robust pharmaceutical manufacturing and R&D infrastructure. Raw material dependencies include highly specialized cell culture media, recombinant proteins, and purification reagents essential for biologics production. Single-source vulnerability for these specialized inputs or contract manufacturing organizations represents a significant supply chain risk. Distribution runs through highly specialized channels, primarily direct-to-specialty-clinic and academic hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Focal Segmental Glomerulosclerosis Market presents a significant service-attach opportunity, with advanced diagnostic services and long-term patient monitoring expanding faster than the core therapeutic products.
For Market Incumbents: Insulate core market share by investing heavily in next-generation precision medicine R&D, particularly gene-targeted therapies. Deepen partnerships with leading academic hospitals to secure early access to pivotal clinical trial data. This strategy mitigates the threat from nimble biotech firms developing highly targeted interventions. Focus R&D on novel mechanisms of action beyond broad immunosuppression to maintain a competitive edge.
For New Entrants and Emerging Players: Pursue niche segments with significant unmet medical need, such as pediatric FSGS indications or specific genetic subtypes. Developing non-invasive biomarkers represents a highly penetrable segment with strong commercial potential. Leverage orphan drug designation pathways and accelerated approval processes to gain rapid market entry and secure early revenue streams, focusing on clear clinical endpoints.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger pharmaceutical companies divesting non-core rare disease assets, or from biotech firms with promising early-stage clinical candidates. The long-term viability for therapies addressing rare diseases with high unmet need remains robust over the next decade. A critical signal to watch is positive clinical trial readouts for genetically targeted FSGS therapies, indicating a significant inflection point for investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates drug development timelines and generates critical efficacy data for regulatory submissions. |
| Regulatory Approval Pathway | Secures market access for novel FSGS therapies, leveraging designations like FDA orphan drug status. |
| Licensing Agreement | Expands therapeutic pipelines by integrating external innovation from specialized biotech firms. |
| Manufacturing Scale-Up | Ensures commercial supply of complex biologics for a growing patient population. |
| Pipeline Diversification | Mitigates risk by addressing multiple FSGS subtypes with varied therapeutic approaches. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary research validation. Primary research included conversations with drug development executives, regulatory affairs leads, formulary directors, and practicing nephrologists. Secondary sources comprised FDA filings, EMA submissions, ClinicalTrials.gov, and peer-reviewed academic publications, triangulated through both bottom-up and top-down approaches.
Forecast inputs being considered included historical market performance, current clinical trial landscapes, and anticipated regulatory developments across the analysis window. The analytical framework modeled segmentation dimensions such as therapy area, dosage form, route of administration, end-user, patient population, and regional regulatory cluster. Compound Annual Growth Rates were derived from an assessment of historical growth patterns and projected market dynamics, incorporating disease prevalence rates and clinical trial success rates.
Sensitivities concentrate around regulatory policy shifts, unexpected clinical trial outcomes, and new biomarker discoveries. Forecasts reflect assumptions regarding disease heterogeneity, diagnostic complexity, and patient recruitment challenges. Cross-checking against national health registries and pharmaceutical sales data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Animal Hormone Therapy Market
Specialty Medicine
Pharyngitis Treatment Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
Bipolar Disorder (BPD) Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Palmoplantar Pustulosis Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Transthyretin (TTR) Amyloidosis Market
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Global Alopecia Market