
 Hypertrophic Cardiomyopathy (HCM) Therapeutics Market | 2026-2036
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market Foresight
FDA breakthrough therapy designation is realigning the cost-of-entry calculus for developers of cardiac myosin inhibitors. Cytokinetics leverages its specialized focus on muscle biology to anchor clinical development in this mechanism. Bristol-Myers Squibb sustains broad cardiovascular infrastructure that competes across multiple therapy areas. Novartis differentiates through integrated hospital and specialty pharmacy channels.
Hypertrophic cardiomyopathy therapeutics comprise pharmacological and surgical interventions that reduce left ventricular outflow tract obstruction and mitigate arrhythmia risk through beta-adrenergic blockade, calcium channel antagonism, or surgical myectomy procedures requiring precise septal thickness reduction. Their primary purpose centers on symptom relief, sudden cardiac death prevention, and functional capacity restoration in patients with asymmetric septal hypertrophy. Beta-blockers occupy the dominant position in first-line medical management, while the arrhythmia therapy area captures expanding clinical attention due to device-therapy integration opportunities. Oral delivery modes retain the largest volume share, though intravenous formulations command premium positioning in acute settings.
FDA, EMA, and the EU MDR collectively shape HCM therapeutic development through divergent evidentiary requirements for novel mechanisms and post-market surveillance obligations. The FDA's breakthrough therapy pathway accelerates review timelines, while EMA's adaptive pathways pilot creates conditional access frameworks that reshape commercial launch sequencing. Stakeholders must monitor how payer evidence requirements evolve alongside regulatory approvals to align pricing and access strategies with differentiated clinical value demonstrations.
Market Dynamics
The FDA breakthrough therapy pathway is compressing development timelines for cardiac myosin inhibitors, forcing developers to accelerate evidence generation while payers simultaneously tighten reimbursement criteria for novel HCM mechanisms.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's accelerated review framework reduces time-to-market for novel cardiac myosin inhibitors, attracting venture funding into HCM-focused biotech pipelines.
- Specialized Cardiovascular Centers:Academic medical centers in the United States are establishing dedicated HCM clinics that drive early adoption of next-generation pharmacological interventions.
- Device-Therapy Integration:Implantable cardioverter-defibrillator manufacturers are partnering with pharmaceutical developers to bundle arrhythmia management solutions, creating combined revenue streams.
Market Restraints
- Specialized Manufacturing Concentration:Active pharmaceutical ingredient production for cardiac myosin inhibitors concentrates among a limited set of contract manufacturers in Switzerland and Germany.
- EMA Conditional Access Friction:The European Medicines Agency's adaptive pathways pilot creates reimbursement uncertainty across EU member states, delaying commercial launch sequencing.
- Surgical Myectomy Substitution:Established septal reduction procedures at Cleveland Clinic and Mayo Clinic retain preference among symptomatic patients resistant to pharmacological management.
Strategic Opportunities
- Underpenetrated Japanese Market:Japan's Ministry of Health, Labour and Welfare has streamlined orphan drug designation for HCM therapies, opening access to the world's oldest patient population.
- Telemedicine-Enabled Screening:Remote cardiac monitoring platforms are identifying undiagnosed HCM in rural populations, expanding the addressable patient pool beyond tertiary referral centers.
- EU Green Deal Alignment:Sustainable manufacturing incentives under the European Green Deal are creating cost advantages for developers investing in continuous flow chemistry for small-molecule production.
Industry Challenges
- Cardiovascular Geneticist Shortage:The limited pool of physicians trained in sarcomeric protein interpretation constrains patient stratification for genotype-specific therapies.
- Biomarker Validation Timelines:The FDA's evolving evidentiary requirements for surrogate endpoints in HCM trials are extending Phase III study durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypertrophic Cardiomyopathy (HCM) Therapeutics Market |
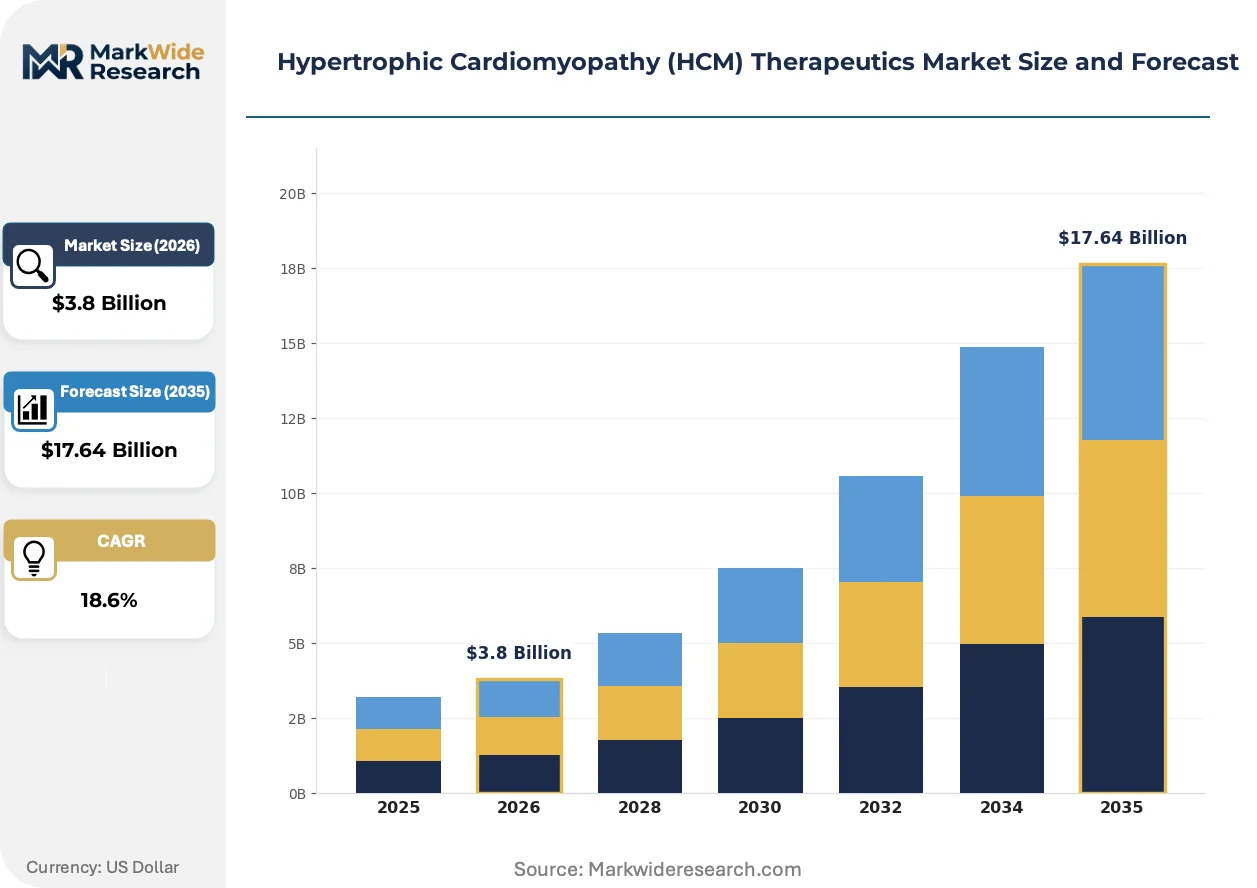
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta-Blockers, Calcium Channel Blockers, Anticoagulants, Myectomy Therapy Area: Heart Failure, Chest Pain, Arrhythmias, Syncope Delivery Mode: Oral, Intravenous, Injectable, Transdermal End User: Hospitals, Cardiology Clinics, Research Institutes, Home Care |
| Companies Covered | Bristol-Myers Squibb, Cytokinetics, Novartis AG, Pfizer Inc., Sanofi, AstraZeneca, Merck & Co., Amgen Inc., Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market Shifts & Advancements
Cardiac myosin inhibition is displacing beta-blocker dominance in symptomatic obstructive HCM, while regulatory frameworks on both sides of the Atlantic are rewriting commercialization economics for rare cardiovascular conditions.
Cardiac myosin inhibitors function by reducing sarcomere hypercontractility without compromising cardiac output. Tertiary cardiovascular centers are adopting these agents ahead of formal guidelines, driven by patient advocacy demand. The mechanism is expanding into non-obstructive HCM phenotypes previously managed conservatively.
The EU Medical Device Regulation's heightened clinical evidence requirements are forcing device-therapy combination developers to pursue parallel pharmaceutical and device approvals. This dual-track obligation is reshaping partnership structures between biotech firms and cardiac rhythm management manufacturers. Germany's Diagnosis-Related Group system is responding by creating separate reimbursement codes for pharmacological-device bundled interventions.
Hospital formulary committees are compressing evaluation cycles for novel HCM therapies from eighteen months to six months, driven by competitive pressure from patient advocacy organizations. Specialty pharmacy distributors are displacing traditional wholesale channels for oral cardiac myosin inhibitors, capturing higher service fees through risk evaluation and mitigation program administration. This channel migration is most visible in United States integrated delivery networks where pharmacy benefit managers own specialty dispensing assets.
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market Segmentation
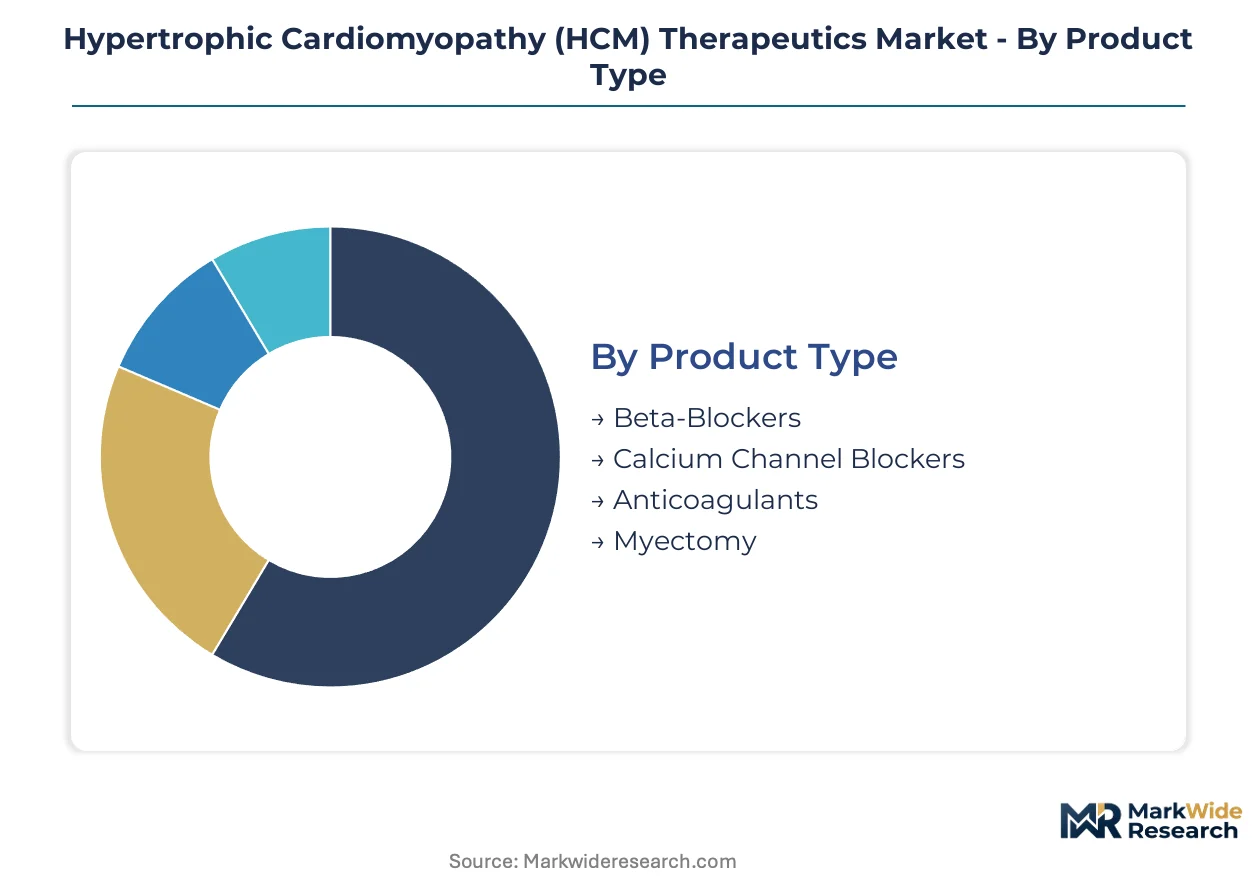
Hypertrophic cardiomyopathy therapeutics segment across multiple clinical and commercial dimensions, each shaping how developers allocate R&D resources and how payers structure reimbursement tiers. Understanding these segment boundaries reveals where pricing power concentrates and where commoditization pressures emerge.
Product Type:
Cardiac myosin inhibitors are displacing beta-blocker dominance as clinicians upgrade first-line therapy for symptomatic obstructive patients.
- Beta-Blockers:Propranolol, metoprolol, and atenolol reduce heart rate and contractility through competitive beta-adrenergic receptor antagonism. Demand concentrates in primary care settings across the United States where generic substitution rates exceed 90 percent and cost containment dominates formulary decisions.
- Calcium Channel Blockers:Verapamil and diltiazem provide alternative negative inotropic effects for patients intolerant of beta-blockade. German cardiology practices favor these agents for rate control in patients with concomitant atrial fibrillation, though their use is narrowing as cardiac myosin inhibitors enter guidelines.
- Anticoagulants:Direct oral anticoagulants and vitamin K antagonists address stroke prevention in HCM-related atrial fibrillation.
- Myectomy:Surgical septal reduction procedures retain preference at Cleveland Clinic and Mayo Clinic for refractory symptomatic patients.
Volume placements concentrate in Beta-Blockers; the steepest expansion trajectory belongs to emerging cardiac myosin inhibitors not yet captured in legacy category definitions.
Therapy Area:
Cost tier differentiation separates acute intervention from chronic maintenance, with device-therapy bundles commanding premium positioning.
- Heart Failure:Diuretic combinations and afterload reduction strategies manage diastolic dysfunction in non-obstructive phenotypes. Academic medical centers in Massachusetts and California are establishing dedicated HCM heart failure clinics that drive specialized referral patterns and concentrated prescribing of novel mechanisms.
- Arrhythmias:Antiarrhythmic drugs and implantable cardioverter-defibrillator therapy address sudden cardiac death risk. Device manufacturers in Minnesota are partnering with pharmaceutical developers to create bundled reimbursement codes that capture combined revenue streams across the therapy area.
- Chest Pain:Symptom management focuses on outflow tract obstruction reduction through pharmacological or surgical means.
- Syncope:Evaluation and prevention strategies target hemodynamic instability and bradyarrhythmia mechanisms.
Revenue concentration sits with Arrhythmias due to device integration; the fastest volume climb belongs to Heart Failure as non-obstructive phenotypes gain diagnostic attention.
Delivery Mode:
Application setting determines formulation choice, with acute care requiring rapid onset and outpatient maintenance favoring adherence-optimized designs.
- Oral:Extended-release tablets and capsules dominate chronic maintenance therapy for outpatient populations. Specialty pharmacy distributors in United States integrated delivery networks are displacing wholesale channels for oral cardiac myosin inhibitors, capturing higher service fees through risk evaluation and mitigation program administration.
- Intravenous:Acute formulations command premium positioning in emergency department and intensive care settings where rapid hemodynamic stabilization is required. Hospital formulary committees are compressing evaluation cycles for these agents from eighteen months to six months.
- Injectable:Subcutaneous depot formulations serve bridge-to-surgery scenarios and perioperative management.
- Transdermal:Patch-based delivery remains experimental for HCM-specific indications, with limited commercial penetration.
Patient days concentrate in Oral formulations; the margin expansion opportunity sits with Intravenous products in tertiary cardiovascular centers.
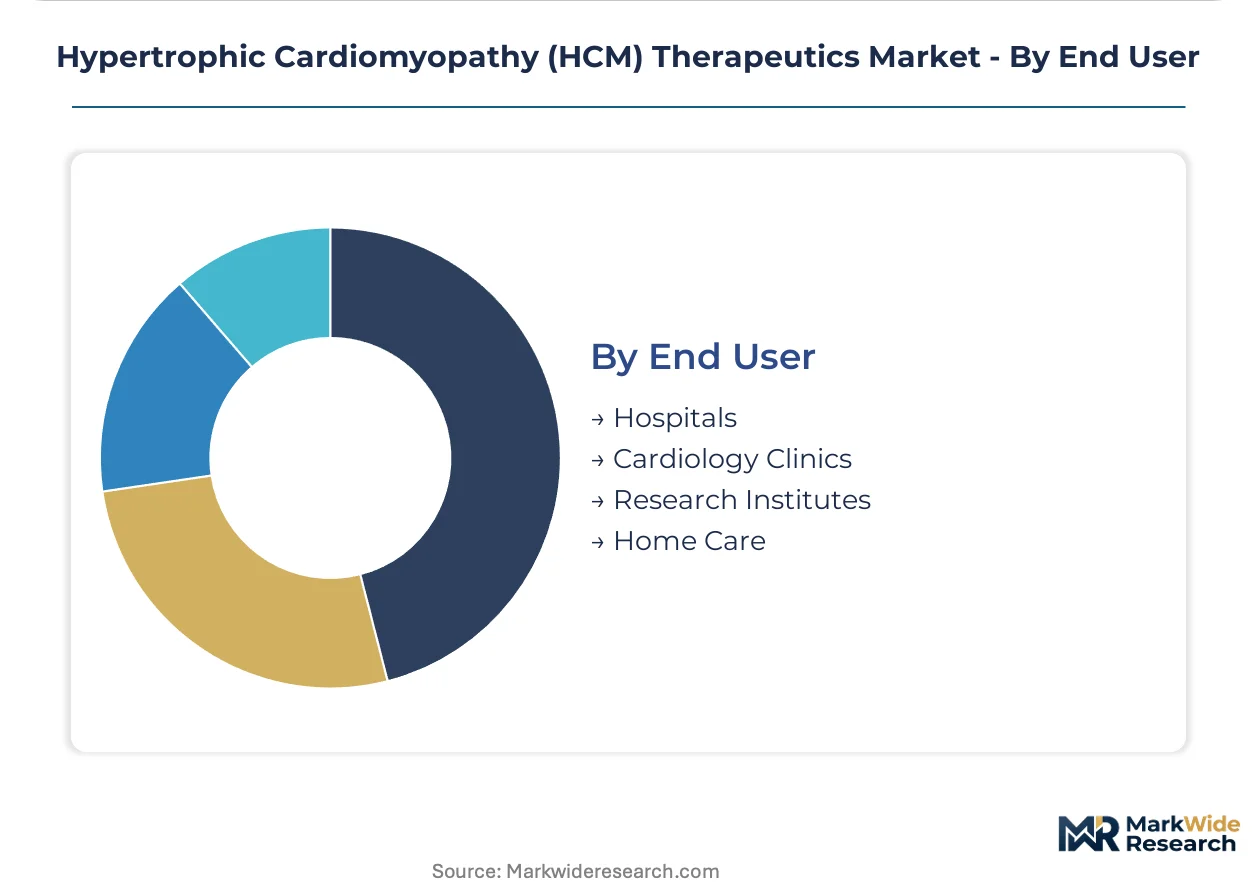
End User:
Customer type segmentation aligns with care complexity, from high-acuity surgical centers to distributed home monitoring platforms.
- Hospitals:Tertiary and quaternary centers perform myectomy procedures and manage acute decompensations. The Cleveland Clinic and Mayo Clinic surgical programs anchor United States volume for septal reduction interventions, with outcomes data driving referral patterns from surrounding states.
- Cardiology Clinics:Dedicated HCM centers at academic medical centers drive early adoption of next-generation pharmacological interventions. These clinics are expanding across the United States as the FDA accelerates breakthrough therapy designations, creating concentrated prescribing of novel cardiac myosin inhibitors.
- Research Institutes:Academic centers conduct genotype-phenotype correlation studies and early-phase clinical trials.
- Home Care:Remote cardiac monitoring platforms are identifying undiagnosed HCM in rural populations, expanding the addressable patient pool beyond traditional referral networks.
Procedure volume concentrates in Hospitals; the patient identification expansion belongs to Home Care through telemedicine-enabled screening platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers concentrate demand for next-generation cardiac myosin inhibitors, with specialized HCM clinics driving early adoption ahead of formal guideline updates.
United States
The Cleveland Clinic and Mayo Clinic anchor surgical myectomy volume while Massachusetts General Hospital and Stanford Medicine establish dedicated HCM pharmacology programs. FDA breakthrough therapy designations for novel cardiac myosin inhibitors compress commercial launch timelines. Pharmacy benefit managers in integrated delivery networks are consolidating specialty dispensing for oral inhibitors.
Germany
Baden-Württemberg and Bavaria host concentrated cardiology practices favoring calcium channel blockers for rate control in atrial fibrillation patients. EMA adaptive pathways pilot creates conditional access frameworks that reshape launch sequencing across EU member states. Heidelberg and Munich academic centers drive genotype-phenotype correlation research for sarcomeric protein interpretation.
Japan
PMDA orphan drug designation streamlines regulatory pathways for HCM therapies targeting the world's oldest patient population. Tokyo and Osaka cardiovascular centers are expanding screening programs for undiagnosed hypertrophic phenotypes. METI incentives under the Sakigake designation accelerate priority review for novel mechanisms addressing unmet cardiovascular need.
Switzerland
Basel and Zurich anchor active pharmaceutical ingredient production for cardiac myosin inhibitors, with contract manufacturers supplying global clinical trial materials. Swissmedic maintains alignment with EMA evidentiary standards while offering expedited access pathways for rare disease therapeutics. The country's precision manufacturing infrastructure supports continuous flow chemistry investments.
United Kingdom
London and Manchester academic centers participate in early-phase cardiac myosin inhibitor trials through the NHS England Early Access to Medicines Scheme. The MHRA operates post-Brexit recognition procedures that parallel EMA approvals for cardiovascular therapies. Scottish cardiovascular networks are integrating telemedicine-enabled screening to identify rural HCM cases.
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market Competitive Landscape
United States biotech developers anchor the innovation tier; Swiss and German pharmaceutical incumbents hold established cardiovascular infrastructure. The market structure concentrates around three strategic archetypes: muscle biology specialists pursuing mechanism-specific development, diversified cardiovascular players leveraging broad hospital formularies, and integrated delivery network partners capturing specialty pharmacy channels. Competitive moves center on breakthrough therapy pursuit and device-therapy bundling arrangements.
Within the muscle biology specialist tier, Cytokinetics exemplifies focused sarcomere-targeting development. Among diversified cardiovascular incumbents, Bristol-Myers Squibb and Novartis AG occupy positions shaped by hospital channel integration and specialty pharmacy infrastructure. These three names represent distinct competitive vectors: mechanism depth, commercial breadth, and distribution control.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Cytokinetics |
| Novartis AG |
| Pfizer Inc. |
| Sanofi |
| AstraZeneca |
| Merck & Co. |
| Amgen Inc. |
| Boehringer Ingelheim |
| Others |
Supply & Pricing Matrix
Captive API manufacturing for cardiac myosin inhibitors anchors both supply security and pricing power, with developers maintaining in-house production or exclusive contract arrangements in Switzerland and Germany to protect proprietary synthesis routes and command premium positioning against generic beta-blocker alternatives.
Pricing Analysis
Volume placements concentrate in generic beta-blockers where 90 percent substitution rates compress margins, while cardiac myosin inhibitors capture premium positioning through FDA breakthrough therapy designation and limited manufacturing licenses. Price differentiation rests on regulatory tier—breakthrough-designated agents command hospital formulary priority—and vertical integration depth, with captive API producers insulating against cost volatility. Pricing pressure stems from Cleveland Clinic and Mayo Clinic surgical myectomy programs retaining preference for refractory patients, forcing pharmacological developers to demonstrate superior value. Primary care settings exhibit highest price sensitivity, while tertiary cardiovascular centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
EMA and FDA qualification requirements for cardiac myosin inhibitor manufacturing concentrate active pharmaceutical ingredient production in Switzerland, Germany, and select United States facilities capable of continuous flow chemistry validation. Raw material dependencies include specialized sarcomere-targeting intermediates, high-purity solvents, and chromatography resins for impurity profiling. Single-source vulnerability characterizes contract manufacturing for clinical trial materials, with Basel and Zurich suppliers anchoring global development programs. Distribution runs through specialty pharmacy channels in United States integrated delivery networks, displacing traditional wholesale routes for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiac myosin inhibition is displacing beta-blocker dominance as the mechanism-of-choice for symptomatic obstructive HCM, creating a technology-transition window where mechanism-specific developers can capture share from established cardiovascular incumbents.
For Market Incumbents: Anchor formulary position through Cleveland Clinic and Mayo Clinic surgical partnership programs that bundle pharmacological-device interventions, while investing in genotype-specific biomarker platforms to defend against Cytokinetics' sarcomere-focused development. Cardiovascular geneticist shortage threatens patient stratification capabilities; backward integration into diagnostic services preserves access to prescriber networks. For New Entrants and Emerging Players: FDA breakthrough therapy designation in the United States opens a window for mechanism-first developers to secure priority review timelines and attract venture funding ahead of guideline updates. Target Japan's PMDA orphan drug pathway for fastest regulatory access to the world's oldest patient population, with METI Sakigake incentives accelerating commercial launch sequencing. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified cardiovascular players seeking mechanism-specific assets to round out hospital formularies. Muscle biology specialists with Phase III cardiac myosin inhibitors represent the highest-probability target archetype. Watch FDA evidentiary requirements for surrogate endpoints in HCM trials as the inflection signal—tightening standards would extend development timelines and compress valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Therapy Pursuit | FDA designation compresses review timelines and attracts specialist prescriber attention ahead of guidelines. |
| Specialty Pharmacy Channel Control | United States integrated delivery network partnerships capture risk evaluation and mitigation program administration fees. |
| Device-Therapy Bundling | Implantable cardioverter-defibrillator manufacturer partnerships create combined reimbursement codes with Minnesota-based cardiac rhythm management firms. |
| Continuous Flow Chemistry Investment | EU Green Deal alignment generates sustainable manufacturing cost advantages for Swiss and German API producers. |
| Telemedicine-Enabled Screening | Remote cardiac monitoring platforms expand addressable patient pools beyond tertiary referral centers into rural populations. |
Research Methodology
Multi-period observation of FDA breakthrough therapy designations, EMA adaptive pathway approvals, and hospital formulary adoption rates anchored the trend analysis, supplemented by interviews with drug development executives at cardiac myosin inhibitor developers, regulatory affairs leads navigating FDA and EMA parallel submissions, formulary directors at United States academic medical centers, and payer access specialists at integrated delivery networks. Secondary validation drew from FDA filings, EMA scientific advice letters, ClinicalTrials.gov protocol registries, and hospital procurement databases. Bottom-up patient-flow modeling triangulated against top-down revenue estimates across therapy areas and delivery modes.
Segment-weighting approaches applied differential growth assumptions to cardiac myosin inhibitors versus established beta-blocker and calcium channel blocker categories, with patient population stratification by obstructive versus non-obstructive phenotype and genotype-positive versus genotype-negative status. CAGRs were derived from epidemiological prevalence projections, diagnosis rate improvements, and therapy penetration curves across the analysis window. Forecast inputs included specialist cardiologist workforce expansion rates and device-therapy integration partnership announcements.
The model assumes a particular technology adoption path where cardiac myosin inhibitors displace beta-blockers as first-line therapy for symptomatic obstructive HCM; alternative pathways where surgical myectomy retains preference or where genotype-specific therapies fragment the market would alter the outlook. Forecasts reflect assumptions about FDA evidentiary standards for surrogate endpoints and EMA conditional access reimbursement harmonization across EU member states. A model refresh is warranted upon material change in FDA breakthrough therapy designation criteria or EMA adaptive pathway pilot scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Alcoholic Liver Diseases Treatment Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market
Specialty Medicine
Respiratory Syncytial Virus (RSV) Therapeutics Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Skin Cancer Therapeutics Market
Specialty Medicine
Animal Hormone Therapy Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Paronychia Treatment Market
Specialty Medicine
Hemophilia Market
Specialty Medicine
Pharyngitis Treatment Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Ankylosing Spondylitis Market