
 Global Dairy Market | 2026-2036
Global Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dairy Market Intelligence
The EU Green Deal is recalibrating procurement standards across European dairy supply chains, forcing processors to document farm-level emissions. Danone leverages its specialized nutrition portfolio to command premium shelf positioning in Asian pharmacies. Lactalis anchors its competitiveness through backward integration into cheese aging infrastructure across France and Italy. Fonterra dominates oceania milk powder exports through long-term supply contracts with Chinese infant formula manufacturers.
Dairy encompasses fluid milk, fermented products, and fat derivatives extracted from mammalian lactation, typically standardized to specific protein and butterfat percentages before pasteurization or homogenization. Milk and cheese categories generate the majority of volume throughput, though yogurt commands higher margin per kilogram through probiotic positioning and functional health claims. Supermarkets and hypermarkets still control the largest share of packaged dairy volume, while online channels capture disproportionate growth in subscription-based fresh delivery models across urban China and South Korea.
EFSA governs nutrition and health claims on dairy labels across EU member states, directly constraining how processors market functional benefits to consumers. The FDA enforces Grade A Pasteurized Milk Ordinance standards that determine interstate shipment eligibility for US fluid milk products. China's SAMR implements GB national food safety standards that foreign exporters must meet for dairy import clearance. Stakeholders must monitor how divergent carbon accounting methodologies between Brussels and Beijing reshape competitive access to premium retail slots.
Market Dynamics
The EU Green Deal is forcing farm-level methane documentation across European procurement networks, creating structural cost differentiation between compliant and non-compliant suppliers. This regulatory pressure cascades through cheese aging infrastructure, fluid milk distribution, and powder export contracts.
Growth Catalysts
- EU Green Deal compliance mandates:Processors investing in herd management monitoring systems secure preferential shelf access in German and French retail chains. Documentation requirements are accelerating capital deployment into precision livestock farming.
- Chinese infant formula demand:Oceania milk powder exporters maintain long-term supply contracts with domestic manufacturers facing GB standard clearance requirements. Powder specifications now prioritize protein stability metrics.
- Fermented product functional positioning:Probiotic yogurt commands pharmacy channel placement in South Korea and urban China. Health claim substantiation drives R&D allocation toward strain-specific cultures.
Market Restraints
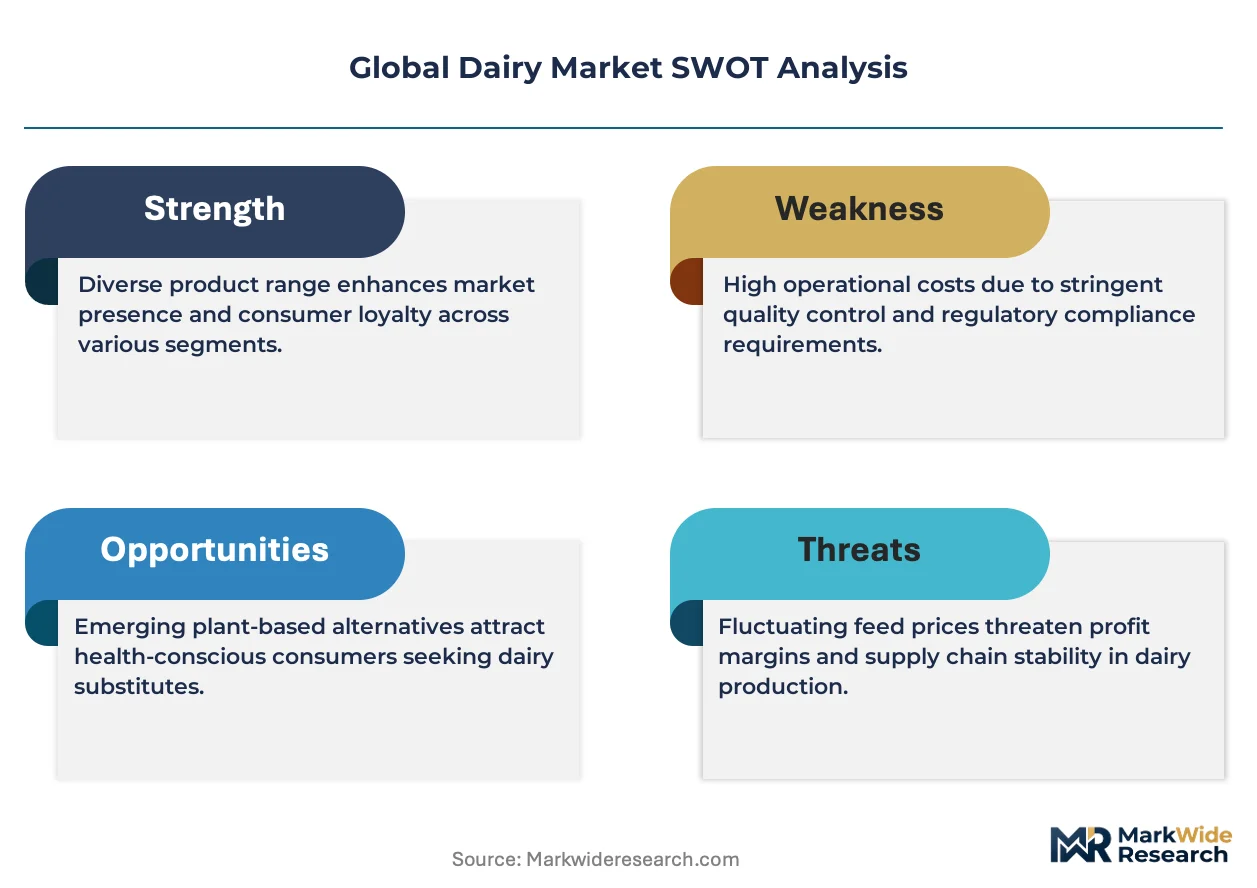
- Feed input cost volatility:Soybean and alfalfa price swings compress margin predictability for pasture-dependent operations in New Zealand and Australia. Hedging instruments remain underdeveloped in cooperative structures.
- Cheese aging infrastructure concentration:Controlled-humidity cave networks cluster in northern Italy and eastern France, limiting new entrant capacity expansion. Regional terroir certification creates geographic lock-in.
- Plant-based dairy substitution:Oat and almond protein isolates capture lactose-intolerant consumer segments in North American and Nordic markets. Blended product formulations erode pure dairy volume in food service.
Strategic Opportunities
- Underpenetrated Indonesian food service:Menu diversification programs in Jakarta and Surabaya hotels expand butter and cream procurement. Local cold chain gaps favor UHT and powder formats over fresh delivery.
- Carbon credit monetization frameworks:Methane capture installations on large-scale Dutch and Danish farms generate tradable offset certificates. Verification protocols under development align with CSRD disclosure timelines.
- Subscription fresh delivery channel innovation:Urban Chinese platforms integrate AI-driven demand forecasting with refrigerated last-mile logistics. Consumer lock-in through recurring orders reduces price sensitivity.
Industry Challenges
- Veterinary epidemiology skill scarcity:Foot-and-mouth and avian influenza surveillance protocols require specialized diagnostic capacity lacking in emerging production zones. Training pipelines fail to match biosecurity mandate expansion.
- Legacy system integration complexity:Farm management software from 1990s-era cooperatives resists API connectivity with cloud-based emissions tracking platforms. Data migration costs stall compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dairy Market |
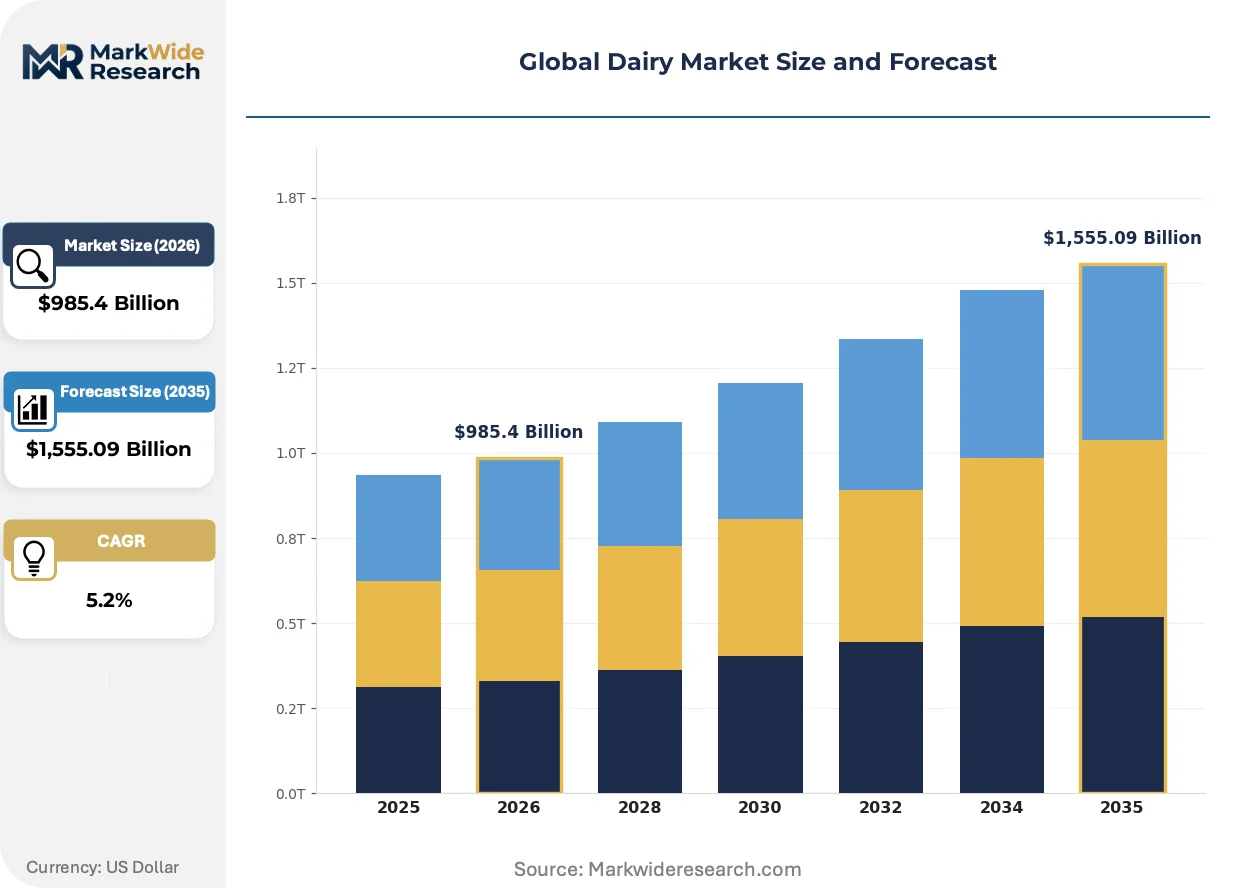
| Market Size in 2026 | $985.4 Billion |
| Market Size in 2035 | $1,555.09 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter Distribution Channel: Supermarkets, Online, Convenience Stores, Specialty Shops End User: Households, Food Services, Manufacturers, Retailers Packaging Type: Cartons, Bottles, Tetra Briks, Pouches |
| Companies Covered | Danone, Arla Foods, Lactalis, FrieslandCampina, Fonterra, Nestlé, Yili, Saputo, Dairy Farmers of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dairy Market Strategic Shifts & Innovations
Precision fermentation and anaerobic digesters are compressing the carbon intensity of milk solids production. Regulatory disclosure requirements and consumer-facing carbon labeling converge on common data infrastructure needs.
Precision fermentation platforms using microbial cell cultures are unifying protein production away from mammalian lactation systems. Ingredient buyers in sports nutrition and bakery applications are piloting whey protein identicals at commercial scale. This technology is unifying supply chains previously separated by animal welfare and land-use constraints.
China's SAMR enforcement of GB 19644 infant formula standards is tightening import clearance documentation for foreign powder exporters. Third-party laboratory certification requirements extend batch testing timelines by several weeks. European and Oceania processors are responding with pre-positioned inventory in bonded Shanghai and Tianjin warehouses.
Pharmacy channel positioning for medical nutrition products is displacing traditional supermarket placement for specialized dairy formats. Elderly care facilities in Japan and South Korea specify texture-modified yogurts with documented probiotic counts. This channel migration concentrates margin capture in regulatory-compliant manufacturing clusters.
Global Dairy Market Segmentation
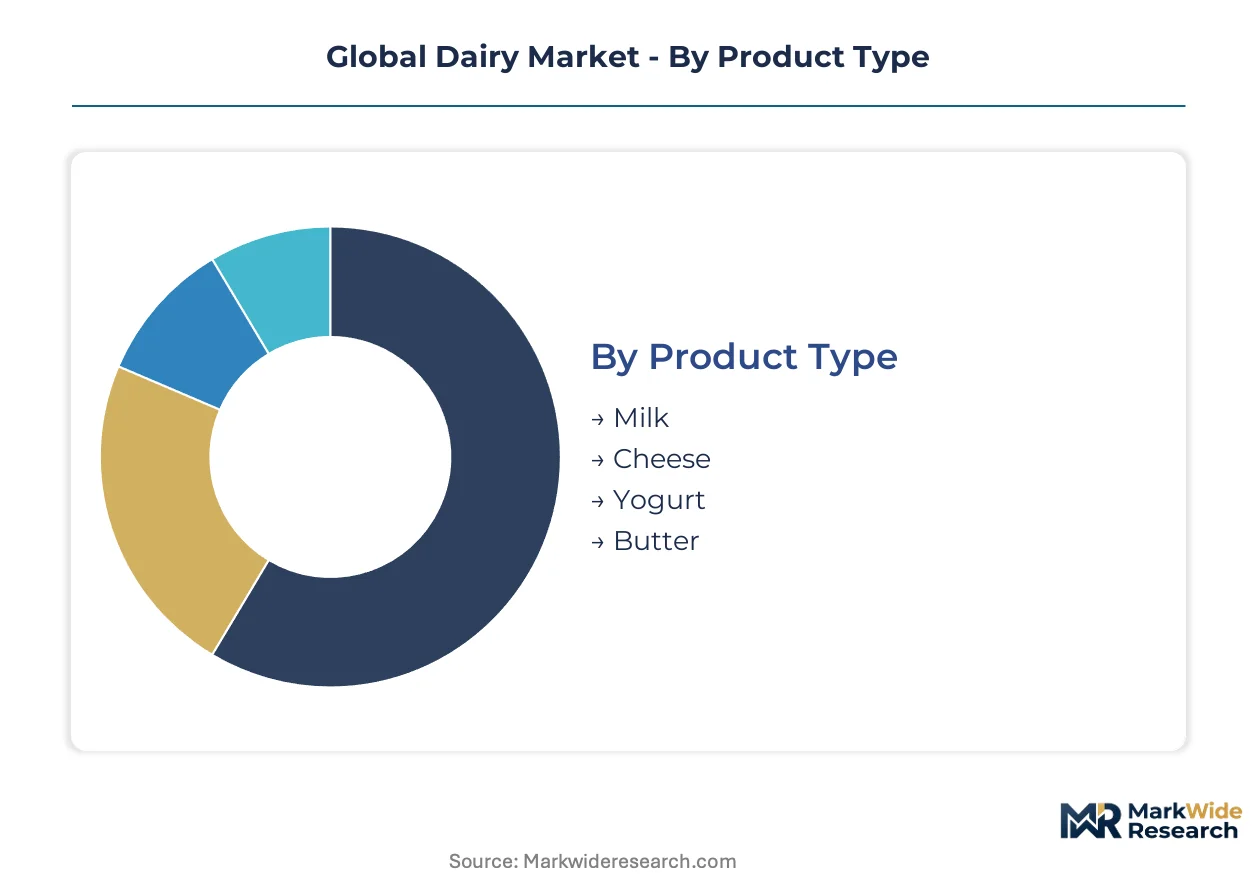
Dairy market segmentation reveals distinct margin structures across product formats and channel economics. Category boundaries determine where processors capture value versus where commoditization pressures concentrate.
Product Type:
Fluid milk operates as a standalone staple with minimal processing depth, while fermented and fat-derivative categories embed into broader food manufacturing systems.
- Milk:Standardized fluid products with defined protein and butterfat percentages serve direct consumption and ingredient feedstock roles. Indian cooperative networks and Chinese fresh delivery platforms anchor procurement concentration. EFSA and FDA pasteurization mandates shape cross-border shipment eligibility.
- Cheese:Controlled-humidity aging infrastructure in northern Italy and eastern France creates geographic lock-in for premium positioning. Terroir certification systems limit new entrant capacity expansion. Food service operators in Southeast Asian hotels drive butter and cream procurement for menu diversification.
- Yogurt:Pharmacy channel placement commands premium positioning through probiotic strain documentation.
- Butter:Fat derivative specifications standardize bakery and food service applications.
Volume placements concentrate in Milk; the faster expansion belongs to Yogurt.
Distribution Channel:
Channel selection determines cold chain investment requirements and margin capture potential across urban versus rural geographies.
- Supermarkets:Controlled-temperature retail infrastructure dominates packaged dairy throughput in European and North American markets. Shelf positioning fees and promotional calendars compress net margins for processors. German and French retail chains now require farm-level emissions documentation under EU Green Deal procurement standards.
- Online:Subscription-based fresh delivery models capture disproportionate growth in urban China and South Korea. AI-driven demand forecasting integrates with refrigerated last-mile logistics to reduce spoilage rates. Consumer lock-in through recurring orders diminishes price sensitivity.
- Convenience Stores:UHT and extended-shelf-life formats suit limited refrigeration capacity.
- Specialty Shops:Curated selections target premium positioning and regional terroir authentication.
Supermarkets retain the largest throughput base; Online channels are gaining share fastest.
End User:
End-user segmentation separates direct consumption demand from industrial ingredient procurement with divergent specification requirements.
- Households:Individual consumption units drive packaged format preferences toward portion-controlled and resealable designs. Urban Chinese platforms and South Korean subscription services reshape purchasing patterns. SAMR GB standards and FDA Grade A ordinances govern product safety expectations.
- Food Services:Hotels in Jakarta and Surabaya expand dairy procurement for menu diversification programs. Local cold chain infrastructure gaps favor UHT and powder formats over fresh delivery. Butter and cream specifications standardize across institutional bakery and restaurant applications.
- Manufacturers:Powder exports to Chinese infant formula producers require protein stability metrics and third-party laboratory certification.
- Retailers:Private label sourcing concentrates purchasing power among consolidated supermarket chains.
Households generate the highest transaction frequency; Food Services show the steepest expansion trajectory.
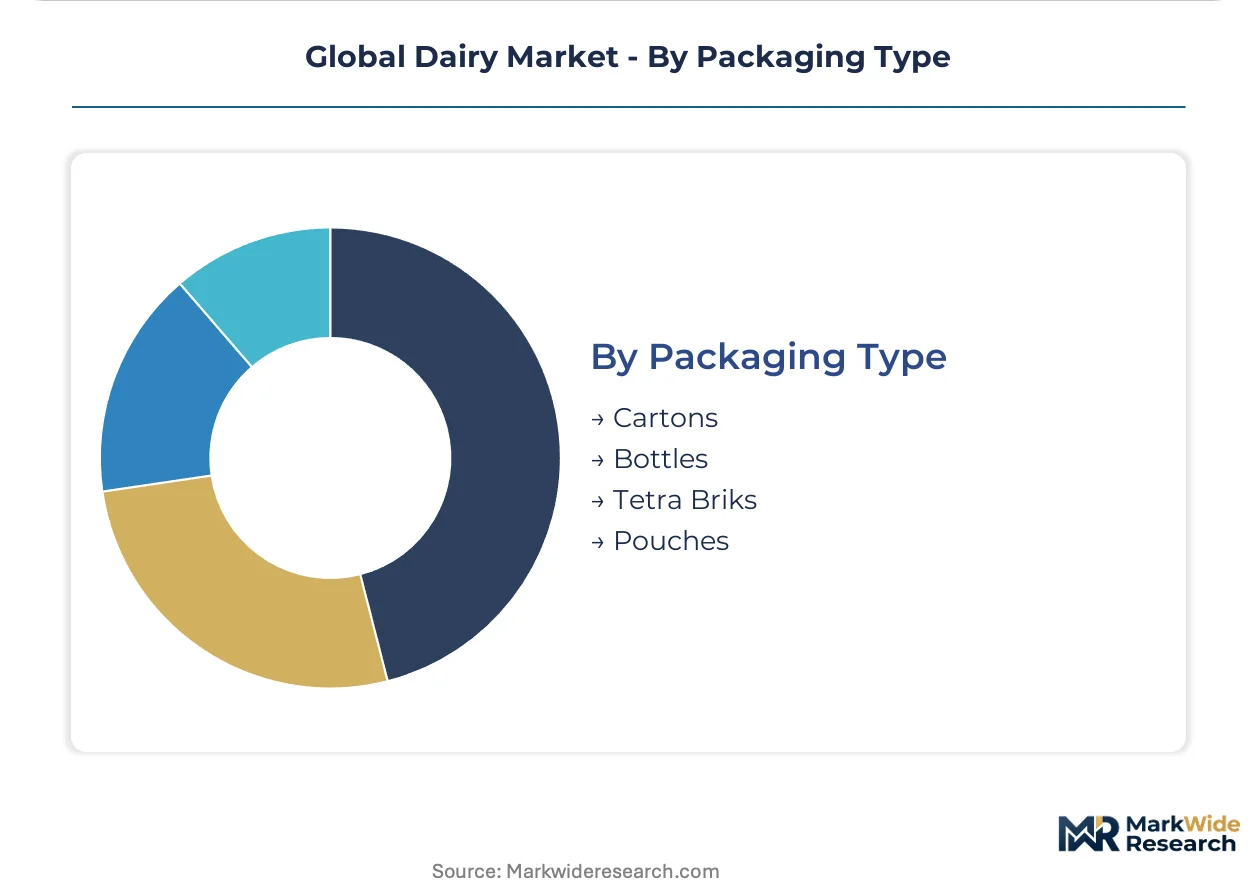
Packaging Type:
Packaging technology selection balances shelf-life extension against material cost and recycling compliance requirements.
- Cartons:Multi-layer paperboard structures suit ambient distribution with aseptic filling lines. European recycling infrastructure and extended producer responsibility frameworks increase compliance costs. Carton formats dominate school nutrition programs and institutional procurement.
- Bottles:HDPE and PET formats serve fresh fluid milk with shorter distribution radius requirements. Deposit-return schemes in German and Nordic markets create reverse logistics obligations. Bottled formats retain preference for premium positioning in specialty retail.
- Tetra Briks:Aseptic brick packs enable long-distance export without refrigeration.
- Pouches:Flexible formats reduce material intensity for price-sensitive market segments.
Cartons hold the broadest geographic penetration; Bottles maintain the strongest premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in temperate grazing zones while consumption gravity shifts toward urbanizing Asian markets. New Zealand and Australia anchor milk powder exports. European processors face compliance costs from the EU Green Deal. Indian cooperatives dominate liquid milk distribution.
United States
Fluid milk consumption declines while cheese and whey protein exports expand. The FDA enforces Grade A Pasteurized Milk Ordinance standards that determine interstate shipment eligibility. Wisconsin and California dairy clusters supply ingredients to Chinese infant formula manufacturers facing SAMR certification delays.
China
Urban fresh delivery platforms and pharmacy channel positioning drive yogurt demand growth. SAMR implements GB national food safety standards that foreign exporters must meet for dairy import clearance. Yangtze River Delta logistics hubs pre-position Oceania milk powder to circumvent extended batch testing timelines.
Germany
Retail chains now require farm-level emissions documentation under EU Green Deal procurement standards. EFSA governs nutrition and health claims on dairy labels across EU member states. Bavarian precision livestock farming deployments accelerate capital deployment into herd management monitoring systems.
India
Cooperative-led liquid milk distribution networks concentrate demand growth in Gujarat and Maharashtra. FSSAI standards govern packaged dairy safety while informal channels dominate raw milk throughput. Anand dairy cluster infrastructure anchors national cooperative procurement systems.
Indonesia
Hotel menu diversification programs in Jakarta and Surabaya expand butter and cream procurement. Local cold chain gaps favor UHT and powder formats over fresh delivery. Java-based food service distributors source from Australian and New Zealand exporters with established halal certification.
Global Dairy Market Key Industry Players
The competitive structure tilts toward diversified nutrition conglomerates with backward integration into cheese aging infrastructure. Processing capacity clusters in France, Italy, and the Netherlands alongside Oceania milk powder export specialists. Three archetypes dominate: cooperative exporters with long-term supply contracts, European dairy majors with terroir-certified aging facilities, and Asian nutrition platforms with pharmacy channel access. Competitive moves concentrate on carbon credit monetization frameworks and subscription fresh delivery channel innovation.
Among European dairy majors, Lactalis and FrieslandCampina occupy positions anchored in controlled-humidity cave networks and cooperative procurement structures. Danone exemplifies the nutrition platform archetype through specialized portfolio positioning. Fonterra represents cooperative export specialists with long-term supply relationships. These three sit within distinct strategic vectors: terroir-authenticated aging, cooperative scale, and functional nutrition claims.
| Leading Market Players |
|---|
| Danone |
| Arla Foods |
| Lactalis |
| FrieslandCampina |
| Fonterra |
| Nestlé |
| Yili |
| Saputo |
| Dairy Farmers of America |
| Others |
Cost & Logistics Intelligence
Global Dairy Trade auction indices and Chicago Mercantile Exchange spot milk prices cascade through procurement networks into three-tier pricing structures across premium, standard, and economy levels. Feed input volatility in New Zealand and Australia compresses margin predictability for pasture-dependent cooperatives, forcing processors to hedge through long-term offtake contracts with Chinese infant formula manufacturers.
Pricing Analysis
Yield-per-cow metrics and protein stability specifications anchor value-based pricing for Oceania milk powder exports to SAMR-regulated Chinese buyers. Three-tier pricing separates terroir-certified Parmigiano-Reggiano from industrial block cheese from commodity whey powder, with EU Green Deal compliance documentation commanding shelf-access premiums in German and French retail chains. Cost compression in standard-tier fluid milk is intensifying because Indian cooperative networks flood regional markets with subsidized liquid distribution. Household subscribers on urban Chinese fresh delivery platforms show least price sensitivity, while Southeast Asian food service operators buying UHT and powder formats exhibit highest elasticity.
Supply Chain Analysis
Veterinary epidemiology skill scarcity across Brazilian and Argentine grazing zones constrains herd expansion timelines for processors seeking South American supply diversification. Raw material flows draw from New Zealand pasture systems, Ukrainian feed grain corridors, and Brazilian soybean protein concentrates. Single-source vulnerability concentrates in northern Italian and eastern French controlled-humidity cave networks for premium cheese aging. Distribution runs through cooperative collection depots, ocean freight bulk powder terminals, and refrigerated last-mile platforms in Yangtze River Delta logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal methane documentation mandates are forcing sub-scale European processors into distressed asset sales, consolidating procurement leverage among compliant majors with capital reserves for precision livestock farming deployment.
For Market Incumbents: Deploy backward integration into cheese aging infrastructure across France and Italy to lock in terroir-authenticated capacity expansion. Capture carbon credit monetization frameworks through anaerobic digester installations on Dutch and Danish farms before CSRD disclosure timelines harden verification protocols. Plant-based dairy substitution in North American markets threatens pure dairy volume; defend through probiotic strain documentation for pharmacy channel placement in South Korea and urban China.
For New Entrants and Emerging Players: The premium-to-economy price gap in Indonesian butter and cream procurement offers white-space entry through halal-certified UHT formats for Jakarta and Surabaya hotel menu diversification. Target underpenetrated subscription fresh delivery channels in tier-two Chinese cities with AI-driven demand forecasting partnerships. Go-to-market leverage rests on cold chain gap exploitation favoring powder over fresh formats.
For Investors and Strategic Acquirers: The window for entry favors cooperative exporters with long-term supply contracts to SAMR-cleared Chinese infant formula manufacturers. Five-to-ten-year viability hinges on protein stability metric differentiation and pre-positioned bonded warehouse inventory in Shanghai and Tianjin. Watch for GB 19644 standard enforcement tightening as inflection signal triggering inventory write-downs among non-compliant Oceania processors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cheese Aging Infrastructure | Terroir certification in northern Italy and eastern France creates geographic lock-in against new entrants. |
| Carbon Credit Monetization Framework Deployment | Methane capture installations on Dutch and Danish farms generate tradable offsets aligned with CSRD timelines. |
| Pharmacy Channel Positioning for Medical Nutrition | Texture-modified yogurts with documented probiotic counts capture elderly care facility specifications in Japan and South Korea. |
| Subscription Fresh Delivery Channel Innovation | Urban Chinese platforms integrate AI forecasting with refrigerated last-mile logistics to reduce spoilage rates. |
| Halal Certification for Southeast Asian Food Service | Java-based distributors source from Australian and New Zealand exporters meeting hotel menu diversification demand. |
Research Approach
USDA dairy production statistics, Fonterra global dairy auction records, and EU Farm Accountancy Data Network filings formed the secondary backbone for volume and value estimation. Primary interviews with herd management technology vendors, cooperative procurement directors, infant formula regulatory affairs specialists, and cold chain logistics operators in China and Southeast Asia validated input assumptions. Bottom-up farm-gate production tallies triangulated against top-down retail throughput audits across Indian cooperative networks and Chinese fresh delivery platforms.
Historical trendline analysis of fluid milk, cheese, yogurt, and butter category volumes informed baseline trajectory calibration across the projection horizon. Segmentation modeling captured product type, distribution channel, end user, and packaging format dimensions alongside regional regulatory cluster differentiation between EFSA-governed EU markets and SAMR-regulated Chinese clearance pathways. CAGRs derived from elasticity-adjusted demand curves incorporating feed input cost volatility and pharmacy channel migration patterns for probiotic-positioned formats.
Inputs from cooperative procurement directors and infant formula regulatory specialists were available through the study window; gaps in real-time methane emissions verification data introduce uncertainty bands around carbon credit monetization forecasts. Forecasts reflect documented assumptions regarding EU Green Deal enforcement timelines and SAMR batch testing protocol stability. Material deviation in GB 19644 standard interpretation or CSRD disclosure acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Lactic Butter Market
Dairy Products
Low Calorie Whipped Cream Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
South America Yogurt Market
Dairy Products
North America Milk Powder Market
Dairy Products
Mozzarella Cheese Market
Dairy Products
Lactose and Derivative Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
Reconstituted Milk Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
Yogurt Drink Market
Dairy Products
India Milk Protein Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Sweetened Condensed Milk Market