
 Cheddar Cheese Market | 2026-2036
Cheddar Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Cheddar Cheese Market Analysis
American dairy cooperatives is expanding cheddar processing capacity across the Upper Midwest to capture growing food service demand. Kraft Heinz leverages its brand architecture and retail shelf presence to sustain volume leadership in sliced and shredded formats. Fonterra Co-operative Group anchors Oceania's export supply, competing aggressively in Asian premium channels. Arla Foods Group differentiates through cooperative-owned milk sourcing and European sustainability certifications.
Cheddar cheese is a firm, cow's milk cheese with minimum milkfat content of 50 percent by weight of solids and maximum moisture content of 39 percent, produced through cheddaring—a process of cutting, stacking, and turning curd to develop characteristic texture and flavor profile before aging. Its primary commercial purpose spans direct retail consumption, ingredient supply for processed foods, and food service melting applications. Block formats dominate manufacturing procurement due to lower per-unit cost and custom shredding flexibility, while grated and shredded segments capture faster growth through convenience-driven retail and quick-service restaurant demand. Premium and aged grades concentrate margin pools among specialty affineurs and export-focused producers, whereas mild cheddar occupies high-volume, price-sensitive channels.
The U.S. FDA enforces pasteurized milk standards and labeling requirements that govern interstate commerce and export eligibility, while the USDA Grade Shield program shapes quality differentiation at retail. The EU EFSA and national regulators such as France's DGCCRF enforce protected designation rules and microbiological thresholds that constrain non-European market access. Canada's CFIA and Dairy Farmers of Canada's supply management system regulate import volumes and domestic pricing structures. Stakeholders must monitor evolving front-of-pack labeling mandates and carbon accounting requirements that will reshape procurement criteria and facility investment decisions.
Market Dynamics
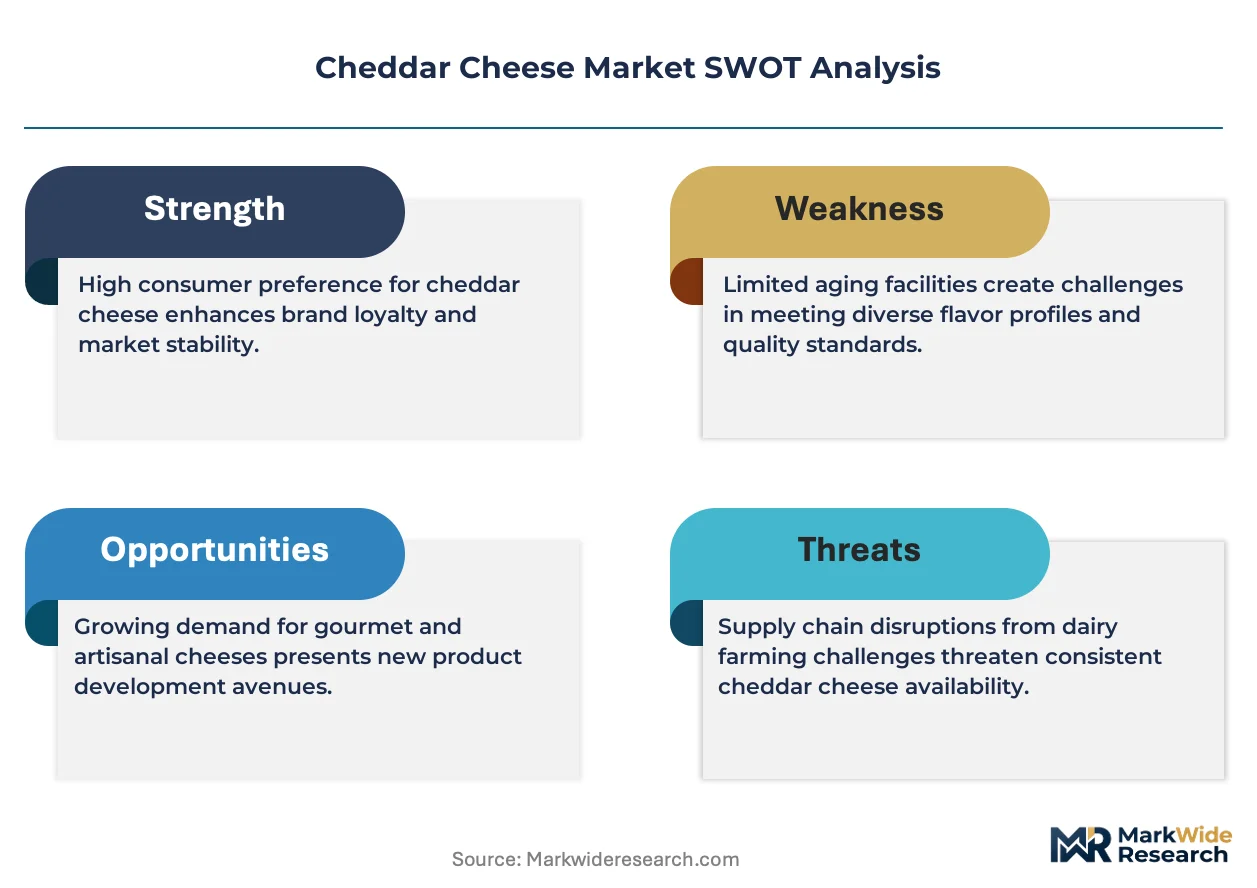
Food service operators are reshaping cheddar procurement by shifting from commodity block contracts toward specification-grade shredded and sliced formats, compressing traditional manufacturing margins while rewarding processors with flexible aging and cutting capabilities.
Growth Catalysts
- Quick-service restaurant expansion:Burger chains and pizza operators in the United States are doubling down on melted-format menu items, pulling volume through shredded and sauce-grade cheddar channels.
- FDA pasteurized milk ordinance alignment:Export-oriented facilities upgrading to FDA-compliant standards are unlocking access to Asian and Middle Eastern dairy-import regimes that restrict raw-milk cheese entry.
- Cheddaring automation:Continuous curd-handling systems are cutting labor intensity in large-scale plants, enabling 24-hour production cycles without batch interruption.
Market Restraints
- Feed cost volatility:Dairy farm margins swing with alfalfa and corn futures, transmitting price instability through cooperative milk pricing pools to processor input costs.
- Oceania supply concentration:Fonterra's dominance in New Zealand milk solids creates single-source risk for Asian buyers dependent on cheddar powder and bulk ingredient supply.
- Plant-based analog substitution:Fermented protein isolates and cultured cashew bases are capturing shelf space in retail premium segments where ethical positioning outweighs taste differentiation.
Strategic Opportunities
- Southeast Asian cold-chain buildout:Vietnam and Indonesia are expanding refrigerated distribution networks, creating first-mover advantage for aged-cheddar exporters with temperature-controlled logistics partnerships.
- EU Green Deal carbon accounting:Farm-level methane monitoring and renewable energy verification will become procurement gatekeepers for European retail banners sourcing cheddar outside the bloc.
- Direct-to-foodservice platform sales:Specialized B2B marketplaces are disintermediating traditional distributor layers, letting regional processors quote specification-grade product directly to restaurant chains.
Industry Challenges
- Affineur skill scarcity:Traditional cave-aging expertise is retiring faster than training programs replenish it, constraining premium aged-cheddar capacity expansion.
- Legacy ERP integration:Batch-oriented dairy management systems require expensive middleware to connect with modern traceability platforms demanded by retail and export customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheddar Cheese Market |
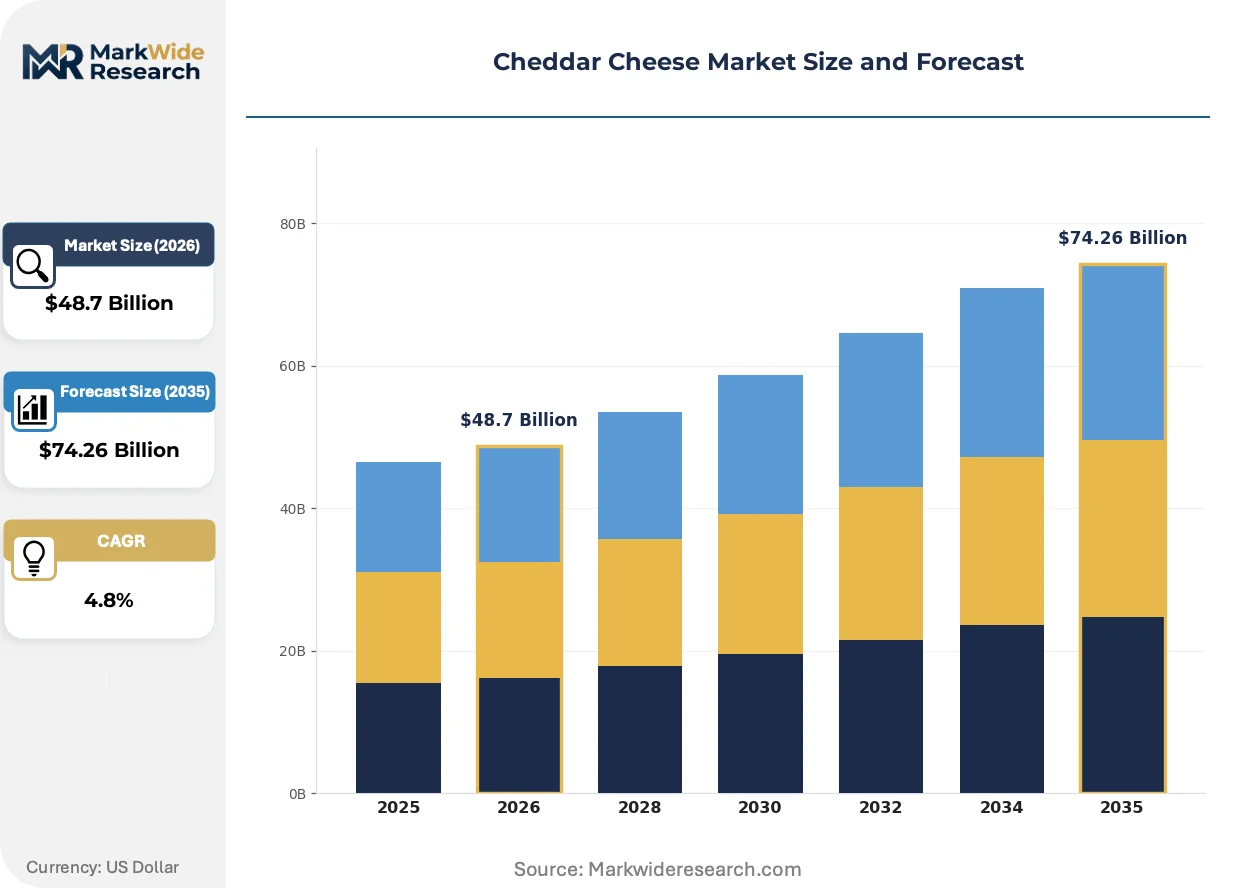
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $74.26 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block, Grated, Sliced, Shredded Grade: Premium, Aged, Mild, Sharp Packaging Type: Vacuum Sealed, Wrapped, Plastic Tub, Recyclable End Use: Household, Food Service, Retail, Food Manufacturing |
| Companies Covered | Arla Foods Group, Kraft Heinz, Lactalis Group, Dairy Farmers of America, Great Lakes Cheese, Fonterra Co-operative Group, FrieslandCampina, Agropur Cheese, Saputo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheddar Cheese Market Emerging Trajectories
Automation, regulatory transparency mandates, and channel restructuring are converging to separate capital-intensive processors from artisan-scale competitors, rewarding investment in data infrastructure and flexible manufacturing lines.
Continuous cheddaring systems using enclosed stainless-steel belts and automated curd-turning arms are electrifying throughput economics in high-volume plants. Mid-sized cooperatives in Wisconsin and Ireland are retrofitting batch houses with semi-continuous modules to capture food service specification business. This electrifying capital deployment is compressing the cost gap between commodity block production and value-added shredding operations.
The EU EFSA is tightening microbiological surveillance of dairy imports through enhanced border sampling and whole-genome sequencing of pathogen isolates. Non-European exporters must now maintain dual-laboratory certification regimes to satisfy both home-country regulators and European import gatekeepers. Aged cheddar categories face disproportionate scrutiny due to extended production timelines that complicate lot-traceability documentation.
Restaurant procurement teams are consolidating supplier rosters from twelve-plus regional distributors to three or four national partners with guaranteed supply and fixed-price contracts. This buyer-side consolidation is squeezing mid-tier processors without sufficient scale to meet volume minimums or geographic coverage requirements. The shift is most visible in United States quick-service chains, where procurement centralization has eliminated spot-market purchasing for core menu ingredients.
Cheddar Cheese Market Segmentation
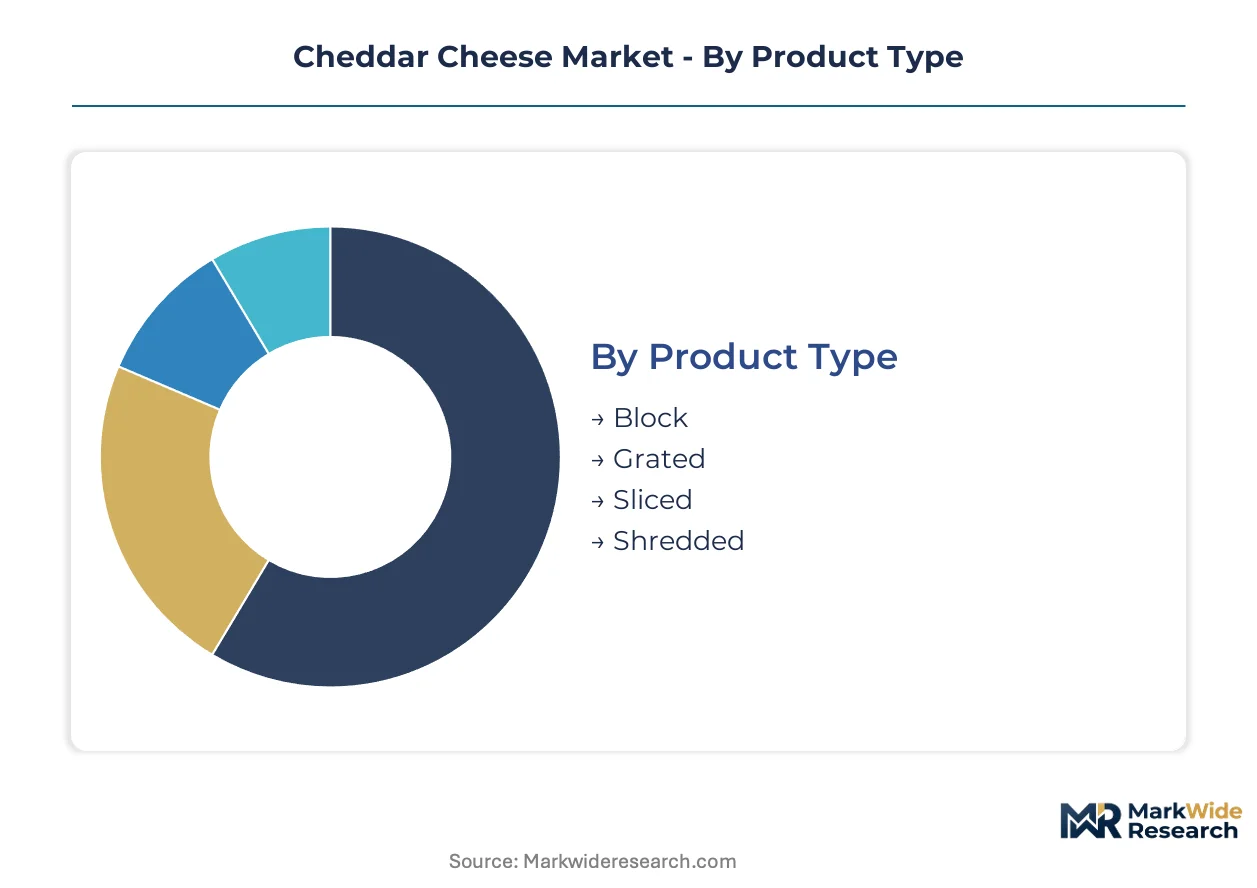
Cheddar cheese segmentation reflects divergent capital requirements across production formats. Block manufacturing demands heavy cheddaring infrastructure, while shredded and sliced lines require precision cutting and packaging automation that reshapes facility investment priorities.
Product Type:
Block cheddar production absorbs the highest fixed-capital deployment through continuous cheddaring belts and aging warehouse infrastructure. Shredded and sliced formats concentrate variable-capital intensity in high-speed cutting, anti-caking systems, and modified-atmosphere packaging lines.
- Block:Firm rectangular formats aged in vacuum-sealed or wax-coated configurations. Food manufacturers in the United States and export-oriented Irish facilities dominate procurement, drawn by custom shredding flexibility and lower per-unit input costs for large-scale processing operations.
- Shredded:Pre-cut strands with cellulose or potato starch anti-caking coatings. Quick-service restaurant chains and pizza operators are consolidating supply around specification-grade partners with guaranteed shred length distributions and melt-performance consistency.
- Grated:Fine particulate formats targeting home cooking and ingredient manufacturing. Retail demand clusters in European convenience channels where resealable pouches with zip-lock closures command shelf space.
- Sliced:Uniform thickness cuts for sandwich and burger assembly. Deli counter and fast-casual channels in North America specify exact milimeter tolerances and peel-release characteristics that constrain supplier qualification.
Block absorbs the bulk of installed capacity; shredded is expanding most quickly.
Grade:
Grade segmentation stratifies across flavor intensity profiles that determine aging duration, inventory carrying costs, and margin capture potential. Premium and aged categories extend working-capital cycles while commanding price premiums in specialty retail and export channels.
- Mild:Young cheddar aged under three months with creamy texture and subtle tang. High-volume retail and commodity food manufacturing in the United States concentrate demand here, prioritizing consistent melt behavior and cost-controlled procurement.
- Sharp:Extended aging between six and twelve months developing pronounced bite and crystalline texture. Specialty grocers and food service distributors in Canada and Australia specify sharp grades for premium sandwich and burger applications.
- Premium:Artisan-scale production with farm-specific milk sourcing and small-batch cheddaring. Affineurs in Somerset, England and Vermont, United States command dedicated shelf space in European and North American specialty food retail.
- Aged:Extended maturation exceeding twelve months with granular texture and intense flavor concentration. Asian import channels in Japan and South Korea absorb limited supply from verified cave-aging facilities with documented temperature and humidity logs.
Mild cheddar dominates volume throughput; aged grades are climbing the fastest on per-kilogram value metrics.
Packaging Type:
Packaging selection determines shelf-life extension, retail presentation, and compliance with emerging sustainability mandates. Vacuum and modified-atmosphere systems require precision equipment investments that separate national-scale processors from regional competitors.
- Vacuum Sealed:Oxygen-extracted barrier films extending refrigerated shelf life to six months or more. Block cheddar for food manufacturing and export shipment relies on this format for mold prevention and moisture retention.
- Wrapped:Wax or parchment paper coverings for traditional retail presentation. Farm shop and farmers market channels in the United Kingdom and Ireland favor wrapped formats for authenticity signaling.
- Plastic Tub:Rigid containers with resealable lids for shredded and grated formats. North American retail convenience demand drives specification here, though recyclability constraints are pressuring format transition.
- Recyclable:Mono-material films and paper-based barriers aligned with EU packaging waste directives. European retail banners are mandating recyclable formats as procurement gatekeepers, forcing packaging line retrofits.
Vacuum sealed carries the majority of industrial throughput; recyclable formats are gaining share fastest on regulatory pull.
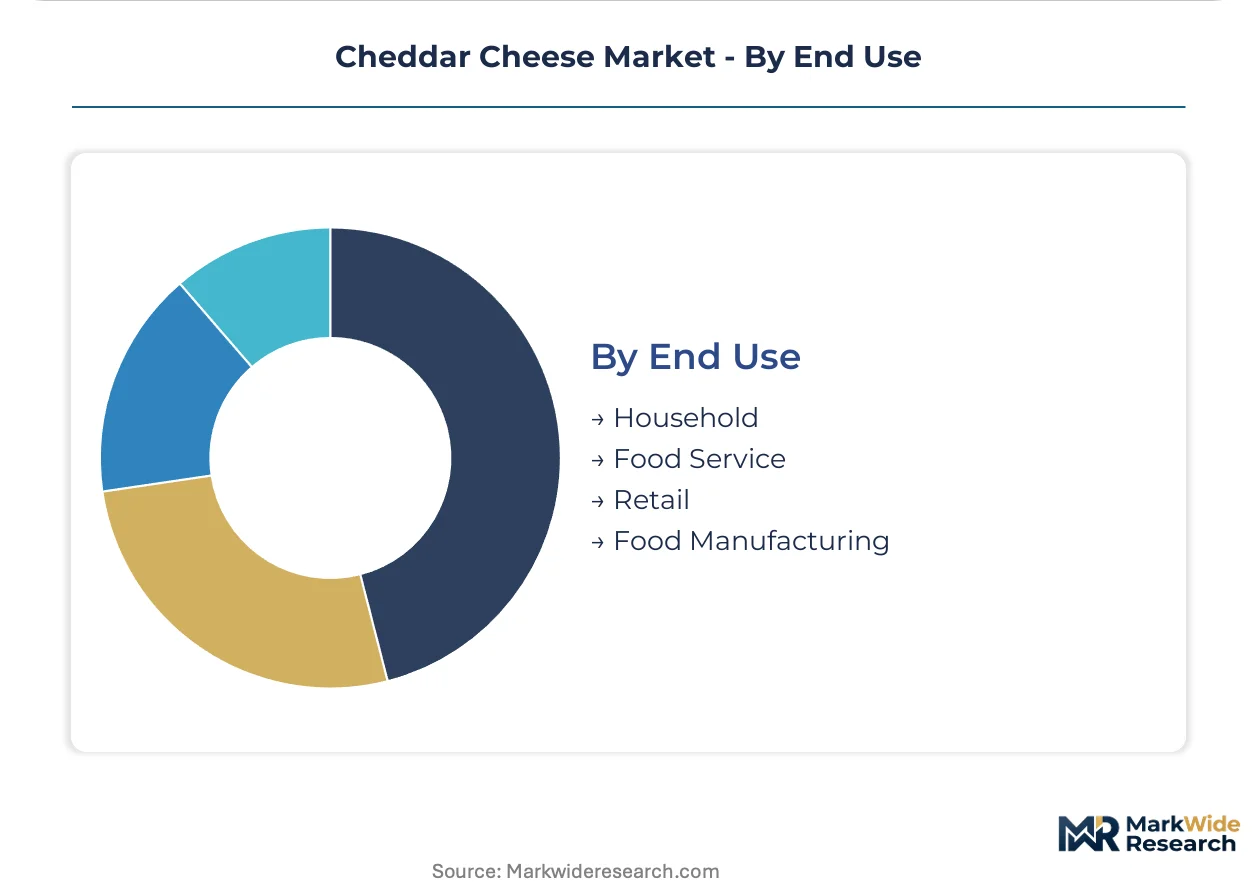
End Use:
End-use segmentation channels cheddar through distinct procurement systems with divergent specification rigor, volume scale, and relationship structures. Food service and manufacturing buyers consolidate supplier rosters while household demand fragments across retail formats.
- Food Manufacturing:Ingredient supply for processed foods, frozen meals, and sauce formulations. Large-scale buyers in the United States and Mexico negotiate annual contracts with fixed-price mechanisms and volume minimums.
- Food Service:Direct supply to restaurants, cafeterias, and catering operations. Burger chains and pizza operators are shifting from commodity block to specification-grade shredded with guaranteed melt-performance metrics.
- Retail:Packaged cheese for supermarket, specialty store, and e-commerce distribution. Private-label and branded competition concentrates margin pressure in this channel, with shelf-space fees and promotional funding requirements.
- Household:Consumer-direct consumption through traditional grocery and emerging subscription channels. Convenience-driven demand favors pre-shredded and individually wrapped sliced formats with resealable packaging.
Food manufacturing absorbs the bulk of block cheddar capacity; food service is expanding most quickly on specification-grade shredded demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grassland dairy belts across Wisconsin, Normandy, Canterbury Plains, Gujarat, and São Paulo anchor cheddar production capacity. These pasture zones concentrate milk solids supply within trucking distance of large-scale cheddaring facilities.
United States
Quick-service restaurant chains in the Midwest and Southeast are pulling specification-grade shredded volume through dedicated supply contracts. The FDA's pasteurized milk ordinance shapes interstate commerce standards and export eligibility protocols. Wisconsin's Fox River Valley hosts the densest cluster of cooperative-owned processing plants, where continuous cheddaring belt systems run 24-hour production cycles.
France
Specialty affineurs in Normandy and Brittany supply aged grades to Japanese and South Korean import channels. The DGCCRF enforces protected designation rules and microbiological thresholds that constrain non-European market access. The Pays d'Auge dairy corridor maintains cave-aging traditions with documented temperature and humidity logs for premium export verification.
New Zealand
Fonterra's bulk ingredient supply anchors Asian cheddar powder demand for sauce and processed food manufacturing. The country's Ministry for Primary Industries aligns export certification with EU EFSA surveillance protocols. Canterbury Plains milk solids flow through Timaru and Edendale processing sites for bulk shipment to Southeast Asian food manufacturers.
India
Urban quick-service restaurant expansion in Mumbai and Delhi is creating pull for processed cheese variants derived from cheddar base. The FSSAI governs dairy product standards and interstate labeling requirements for organized retail distribution. Gujarat's Anand and Mehsana districts concentrate cooperative dairy processing within the Amul supply network.
Brazil
Food service operators in São Paulo and Rio de Janeiro are expanding burger and pizza menu lines requiring melted-format cheese supply. ANVISA regulates dairy import quotas and domestic production licensing for pasteurized milk derivatives. Minas Gerais dairy cooperatives around Uberaba are retrofitting batch houses to capture specification-grade food service contracts.
Cheddar Cheese Market Vendor Landscape
Global majors compete with regional champions across aging expertise and cold-chain reach. The vendor base stratifies into three tiers: multinational dairy conglomerates with integrated milk supply, national cooperatives leveraging domestic brand equity, and artisan affineurs commanding specialty retail premiums. Strategic moves concentrate on cheddaring automation investments and direct-to-foodservice platform partnerships that disintermediate traditional distributor layers.
Within the cooperative tier, Dairy Farmers of America and Fonterra Co-operative Group exemplify member-owned structures that anchor milk supply pools across multiple processing sites. Kraft Heinz occupies a position among branded consumer goods conglomerates with retail shelf presence in sliced and shredded formats. These three entities represent divergent scale logics: cooperative milk aggregation, multinational brand architecture, and export-focused bulk ingredient supply.
| Leading Market Players |
|---|
| Arla Foods Group |
| Kraft Heinz |
| Lactalis Group |
| Dairy Farmers of America |
| Great Lakes Cheese |
| Fonterra Co-operative Group |
| FrieslandCampina |
| Agropur Cheese |
| Saputo Inc. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon-accounting mandates gate qualified supply and premium-tier pricing access, forcing exporters to document farm-level methane monitoring and renewable energy verification before European retail banners will contract aged-cheddar volumes.
Pricing Analysis
Warranty-style service bundling separates contract structures in this market. Three-tier pricing stratifies across premium cave-aged, specification-grade food service, and commodity block tiers. Price differentiation hinges on aging documentation and FDA pasteurized milk ordinance compliance grade. Cost compression in mild cheddar is intensifying because quick-service restaurant procurement centralization squeezes mid-tier processors. Food manufacturing buyers exhibit highest price sensitivity; Asian import channels for aged grades show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Fonterra's dominance in New Zealand milk solids. Supply concentrates in the United States, New Zealand, and Ireland. Raw material dependencies draw from alfalfa feed, corn futures, and cellulose anti-caking inputs. Tariff exposure on European dairy imports creates structural risk for non-EU exporters. Distribution runs through cooperative-owned processing pools, national distributor networks, and emerging direct-to-foodservice B2B platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cheddar processing is becoming a vertical-integration race, with cooperatives and private processors racing to lock in captive milk supply through member equity structures and long-term farm contracts.
For Market Incumbents: Hedge against plant-based analog substitution by investing in cheddaring automation and specification-grade shredding capacity. Kraft Heinz and Dairy Farmers of America should deepen backward integration into farm-level milk supply pools to defend margin position against feed cost volatility. Certification investment in EU Green Deal compliance will secure European retail access. For New Entrants and Emerging Players: The price-point gap between premium aged cheddar and economy mild grades offers white-space opportunity. Target Southeast Asian cold-chain buildout in Vietnam and Indonesia with temperature-controlled logistics partnerships. Food service specification-grade shredded contracts present the most penetrable entry vector. For Investors and Strategic Acquirers: Affineur skill scarcity is the leading indicator that premium aged-cheddar capacity will command scarcity premiums. Long-term viability favors processors with documented cave-aging expertise and dual-laboratory certification regimes. Watch for consolidation signals when regional processors fail to meet quick-service restaurant volume minimums.| Strategic Initiative | Industry Significance |
|---|---|
| Cheddaring Automation Investment | Continuous belt systems at Wisconsin cooperatives cut labor intensity and enable 24-hour production cycles. |
| Direct-to-Foodservice Platform Launch | Specialized B2B marketplaces disintermediate distributor layers and let regional processors quote restaurant chains directly. |
| EU Green Deal Compliance Certification | Farm-level methane monitoring and renewable verification become procurement gatekeepers for European retail banners. |
| Southeast Asian Cold-Chain Partnership | Temperature-controlled logistics alliances in Vietnam and Indonesia create first-mover advantage for aged-cheddar exporters. |
| Dual-Laboratory Certification Regime | Non-European exporters must maintain home-country and EU EFSA laboratory certification to satisfy European import surveillance. |
Methodological Framework
Independent corroboration across cooperative milk pricing data, FDA import inspection records, and EU EFSA border sampling reports underwrites the qualitative findings. Primary interviews with dairy cooperative procurement directors, food service chain buyers, affineur operations managers, and packaging line engineers combined with secondary validation from USDA Grade Shield program documentation, customs trade statistics, and SEC processor filings. Bottom-up facility capacity estimates and top-down consumption surveys were triangulated.
Comparable historical reference periods anchored volume and value projections across the analysis window. The analytical framework modeled segmentation dimensions including product format, grade tier, packaging type, and end-use channel. CAGRs were derived from trend extrapolation calibrated against milk solids supply growth and food service menu expansion rates. Forecast inputs incorporated alfalfa and corn futures volatility bands, quick-service restaurant unit expansion plans, and cold-chain infrastructure investment pipelines.
Inputs from cooperative milk pricing pools and FDA inspection databases were available through the study window; gaps in real-time affineur capacity utilization introduce uncertainty bands around premium aged-cheddar supply forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Dairy Products Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Concentrated Milk Fat Market
Dairy Products
Europe Flavored Milk Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Global Butter Market
Dairy Products
Organic Dairy Products Market
Dairy Products
UHT Whipping Cream Market
Dairy Products
Europe Cheese Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
Camel Dairy Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Cream Market
Dairy Products
Colombia Dairy Market