
 Autopsy Equipment Market | 2026-2036
Autopsy Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Autopsy Equipment Market Analytics
Germany is fragmenting the competitive map for autopsy equipment as regional pathology hubs diversify suppliers beyond legacy incumbents. Kugel Medical leverages its domestic manufacturing base to sustain delivery advantages across Central European government tenders. Mopec competes through specialized dissection table configurations that anchor its position in North American academic medical centers. Thermo Fisher Scientific extends its forensic portfolio breadth to occupy premium segments in digital imaging integration.
Autopsy equipment encompasses instruments, workstations, and protective systems engineered for post-mortem examination, typically fabricated from corrosion-resistant stainless steel with sealed fluid-management surfaces rated for biohazard containment. These systems serve forensic pathology, medical education, and legal evidence preservation by enabling sterile tissue sampling and documentation. Examination tables and autopsy saws dominate installed base value, while digital imaging and automated systems capture expanding margin pools as teaching institutions and research laboratories retrofit legacy facilities. Protective gear remains a high-velocity replenishment category driven by single-use protocols and OSHA bloodborne pathogen compliance cycles.
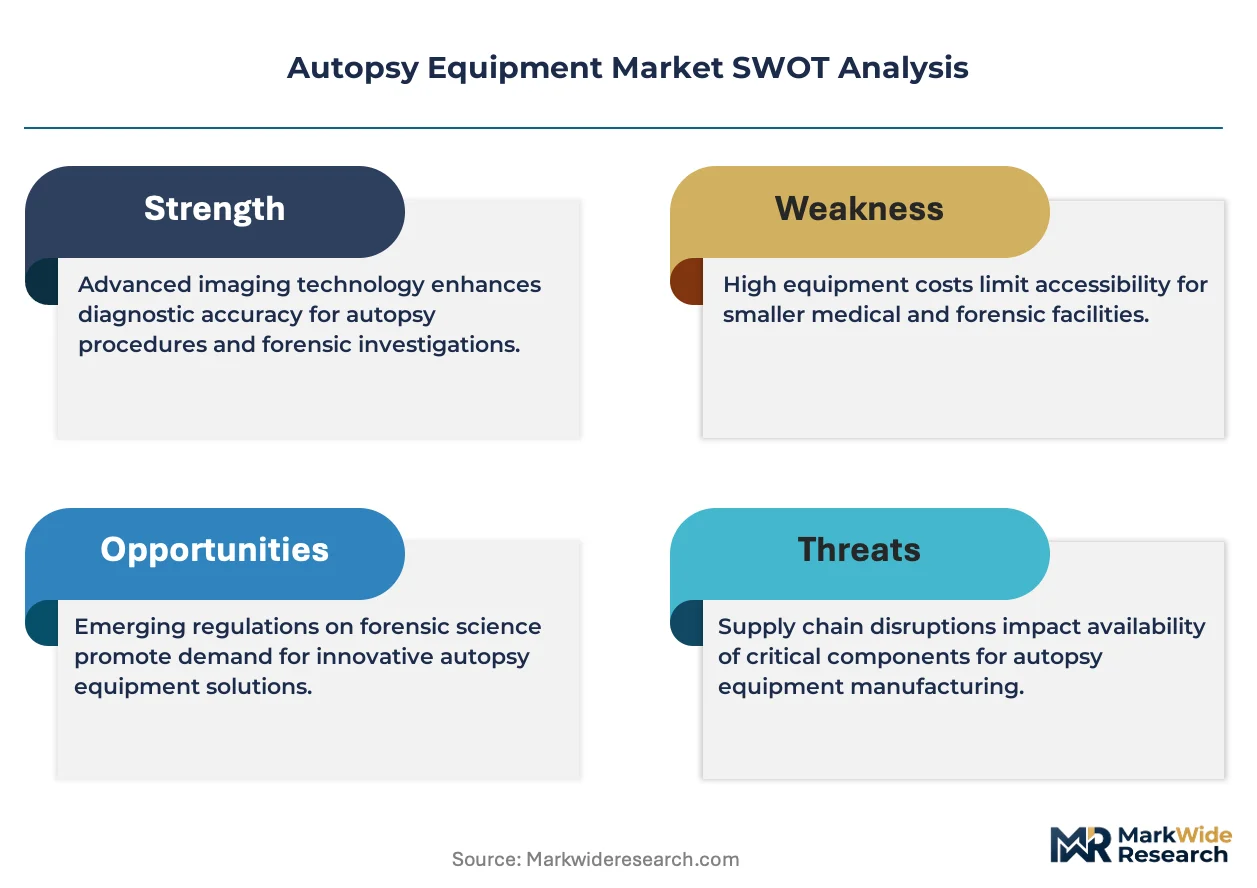
FDA device classification rules and OSHA bloodborne pathogen standards shape product design and channel access for United States suppliers, while the EU MDR and REACH chemical restrictions impose conformity costs on protective material formulations entering European markets. The analysis indicates stakeholders must monitor regulatory divergence between FDA 510(k) pathways and MDR clinical evidence requirements when configuring multi-region product platforms.
Market Dynamics
Government pathology networks are consolidating procurement authority into centralized tenders, compressing vendor margins while demanding integrated digital documentation suites that merge autopsy workflows with laboratory information management systems.
Growth Catalysts
- EU MDR sterilization mandates:The Medical Device Regulation is forcing replacement cycles for legacy instruments across German federal morgues, creating equipment refresh demand that favors modular workstation designs.
- Forensic pathology backlog:Criminal case volume expansion in government medical examiner offices is driving multi-table suite installations with automated fluid capture systems.
- Stainless steel supply localization:Central European mills are securing corrosion-grade sheet capacity, shortening delivery windows for table fabricators serving regional hospital networks.
Market Restraints
- Capital intensity barriers:Autopsy suite construction requires HVAC containment and drainage infrastructure that exceeds standard hospital renovation budgets, limiting retrofit opportunities.
- Specialized stainless input concentration:Surgical-grade 316L sheet supply concentrates among three European mills, exposing fabricators to alloy surcharge volatility.
- Substitution from imaging:Post-mortem CT and MRI adoption in select jurisdictions is reducing invasive examination frequency for certain case types.
Strategic Opportunities
- Teaching hospital digitization:Medical education institutions are retrofitting legacy facilities with video capture and teleconferencing integration for remote pathology instruction.
- REACH compliance tailwinds:The EU chemical framework is phasing legacy protective material formulations, opening replacement markets for bio-based nitrile and fluoropolymer alternatives.
- Modular workstation convergence:Height-adjustable tables with integrated weighing and imaging arms are capturing premium positioning against fixed-height legacy installations.
Industry Challenges
- Forensic pathologist scarcity:Training program bottlenecks are extending equipment utilization cycles and compressing capital deployment timelines for new suite construction.
- Legacy system integration friction:Digital imaging retrofit requires proprietary interface development with incumbent laboratory information systems, extending deployment schedules.
- OSHA bloodborne pathogen recertification:Protective equipment vendors face compressed compliance cycles that strain quality assurance bandwidth across multi-product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autopsy Equipment Market |
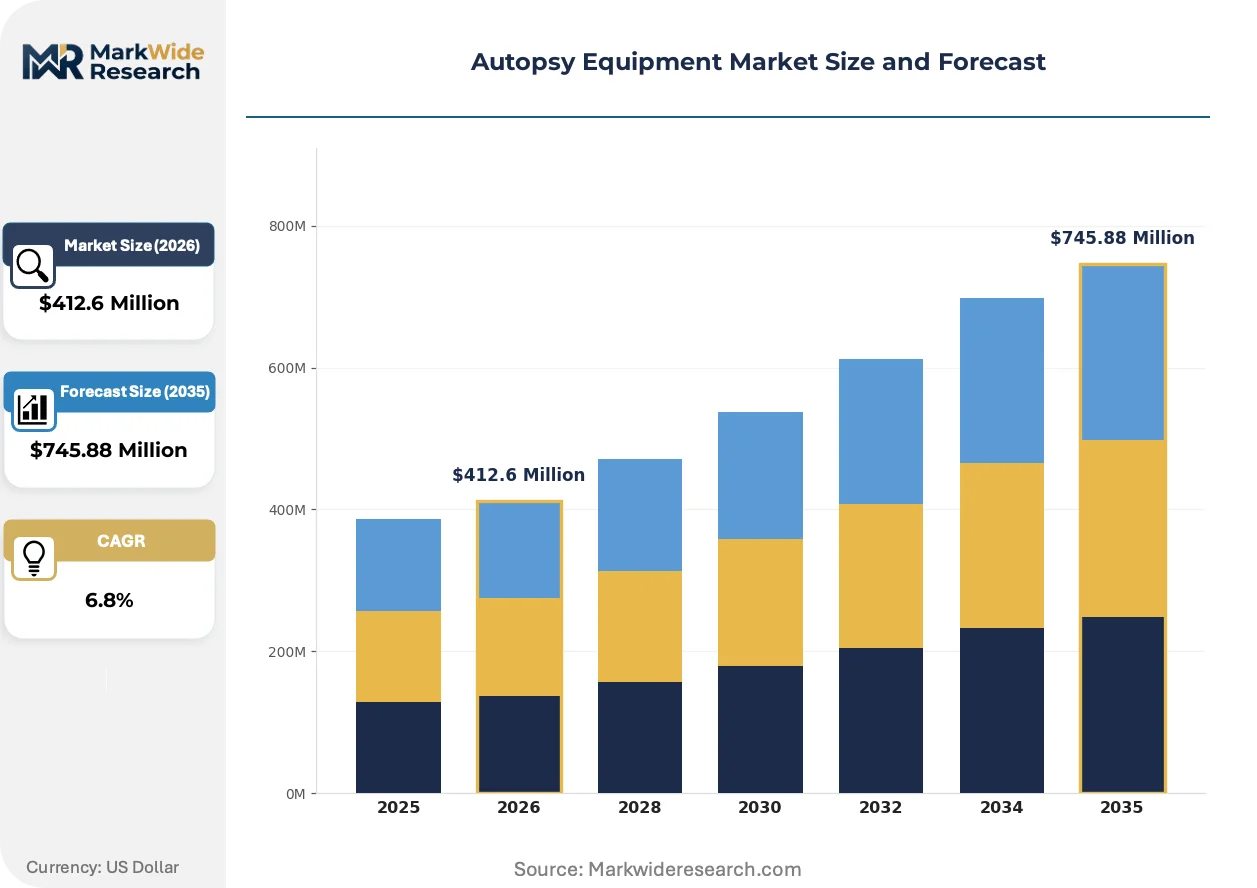
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dissection Tools, Protective Gear, Examination Tables, Autopsy Saw Application: Forensic Investigation, Medical Research, Teaching Institutions, Legal Proceedings End User: Government Hospitals, Private Clinics, Academic Institutions, Research Laboratories Technology: Digital Imaging, 3D Modeling, Automated Systems, Traditional Techniques |
| Companies Covered | Kugel Medical, Mopec, Mortech Manufacturing, Thermo Fisher Scientific, LEEC, Ferno-Washington, Angelantoni Life Science, HYGECO, Barber of Sheffield, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autopsy Equipment Market Evolving Landscape
Digital documentation systems are compressing the gap between physical examination and forensic reporting, enabling real-time collaboration between on-site pathologists and remote specialists while embedding chain-of-custody verification into workflow automation.
Three-dimensional imaging software is virtualizing external examination protocols, allowing medical examiner offices to capture surface documentation and preliminary trauma assessment without immediate table occupancy. German federal pathology hubs are piloting these systems for high-volume case screening, compressing suite utilization rates and enabling throughput expansion without physical capacity expansion. The technology is virtualizing traditional workflow sequencing by decoupling documentation from dissection scheduling.
The EU MDR is tightening clinical evidence requirements for reusable surgical instruments, forcing autopsy saw and scalpel manufacturers to compile biocompatibility documentation that exceeds prior self-certification thresholds. German notified bodies are extending review timelines for Class IIa instrument registrations, compressing product launch windows for European market entry. Forensic instrument specialists are responding by consolidating regulatory affairs functions and pre-submission engagement with BfArM.
Consolidated procurement frameworks are displacing decentralized purchasing across German state pathology networks, compressing vendor relationship structures into framework agreements with multi-year service bundling. Academic medical centers in North America are adopting similar centralized sourcing, unbundling maintenance contracts from initial capital purchases. This pattern is most visible in Baden-Württemberg and Bavaria, where regional purchasing cooperatives are aggregating demand from county-level medical examiner offices.
Autopsy Equipment Market Segmentation
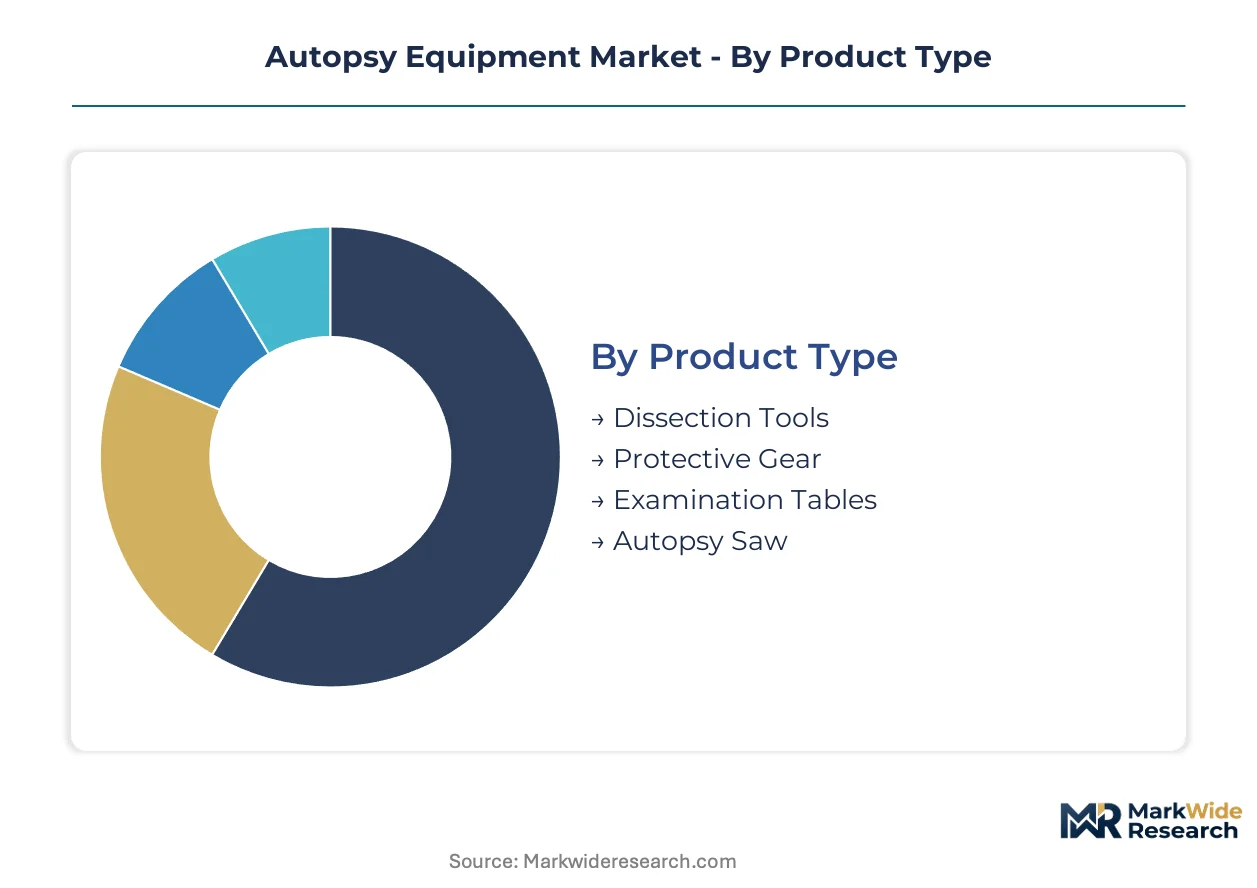
Equipment configuration varies sharply across procurement contexts, with government tenders favoring integrated suites while academic buyers prioritize modular retrofit compatibility. Service intensity differs by segment, with automated systems demanding specialized technical support contracts that reshape vendor margin structures over multi-year ownership cycles.
Product Type:
After-sales service intensity peaks with powered instruments and integrated workstation systems, where calibration protocols and biohazard containment validation create recurring revenue streams for manufacturers.
- Examination Tables:Fabricated from 316L stainless steel with sealed fluid-management troughs and height-adjustable hydraulic systems, these workstations anchor capital expenditure in federal pathology network modernizations across Germany. Procurement specifications increasingly mandate integrated weighing modules and imaging arm mounts.
- Autopsy Saw:Oscillating blade systems with vacuum-assisted aerosol containment dominate high-volume forensic installations, with EU MDR biocompatibility documentation requirements extending replacement cycles for legacy pneumatic units in German state morgues. Demand concentrates where criminal case backlogs strain existing capacity.
- Dissection Tools:Reusable scalpels, forceps, and rib shears fabricated from surgical-grade alloys face REACH compliance pressure on sterilization chemistries.
- Protective Gear:Single-use nitrile barriers and face shields operate on high-velocity replenishment cycles tied to OSHA bloodborne pathogen recertification schedules.
Examination Tables holds the largest share; momentum sits with Autopsy Saw as MDR-driven replacement accelerates.
Application:
Cost tier stratification separates capital-intensive forensic installations from discretionary academic budgets, with legal proceedings funding commanding premium pricing tolerance.
- Forensic Investigation:Government medical examiner offices deploy multi-table suites with automated fluid capture and chain-of-custody documentation systems, with German federal networks consolidating procurement into framework agreements that bundle maintenance and digital integration services.
- Teaching Institutions:Medical education facilities retrofit legacy facilities with video capture and teleconferencing modules for remote pathology instruction, with North American academic medical centers driving demand for configurable dissection stations that accommodate variable cohort sizes.
- Medical Research:Tissue sampling protocols for pharmaceutical studies require specialized containment configurations.
- Legal Proceedings:Evidence preservation standards mandate redundant documentation systems for courtroom admissibility.
Forensic Investigation commands the dominant revenue position; Teaching Institutions are climbing the fastest as digitization retrofits accelerate.
End User:
Customer type determines procurement authority concentration, with centralized tenders displacing decentralized purchasing across regional pathology networks.
- Government Hospitals:Federal and state pathology networks in Germany aggregate demand through purchasing cooperatives in Baden-Württemberg and Bavaria, compressing vendor margins while demanding integrated digital documentation suites that merge autopsy workflows with laboratory information management systems.
- Academic Institutions:University medical centers balance curriculum requirements against research collaboration needs, with procurement committees prioritizing modular workstation designs that accommodate both undergraduate instruction and specialized forensic fellowships.
- Research Laboratories:Pharmaceutical and biotech facilities require specialized sampling protocols.
- Private Clinics:Limited autopsy volume constrains capital deployment to essential instrument configurations.
Government Hospitals holds the largest share; momentum sits with Academic Institutions as remote instruction infrastructure expands.
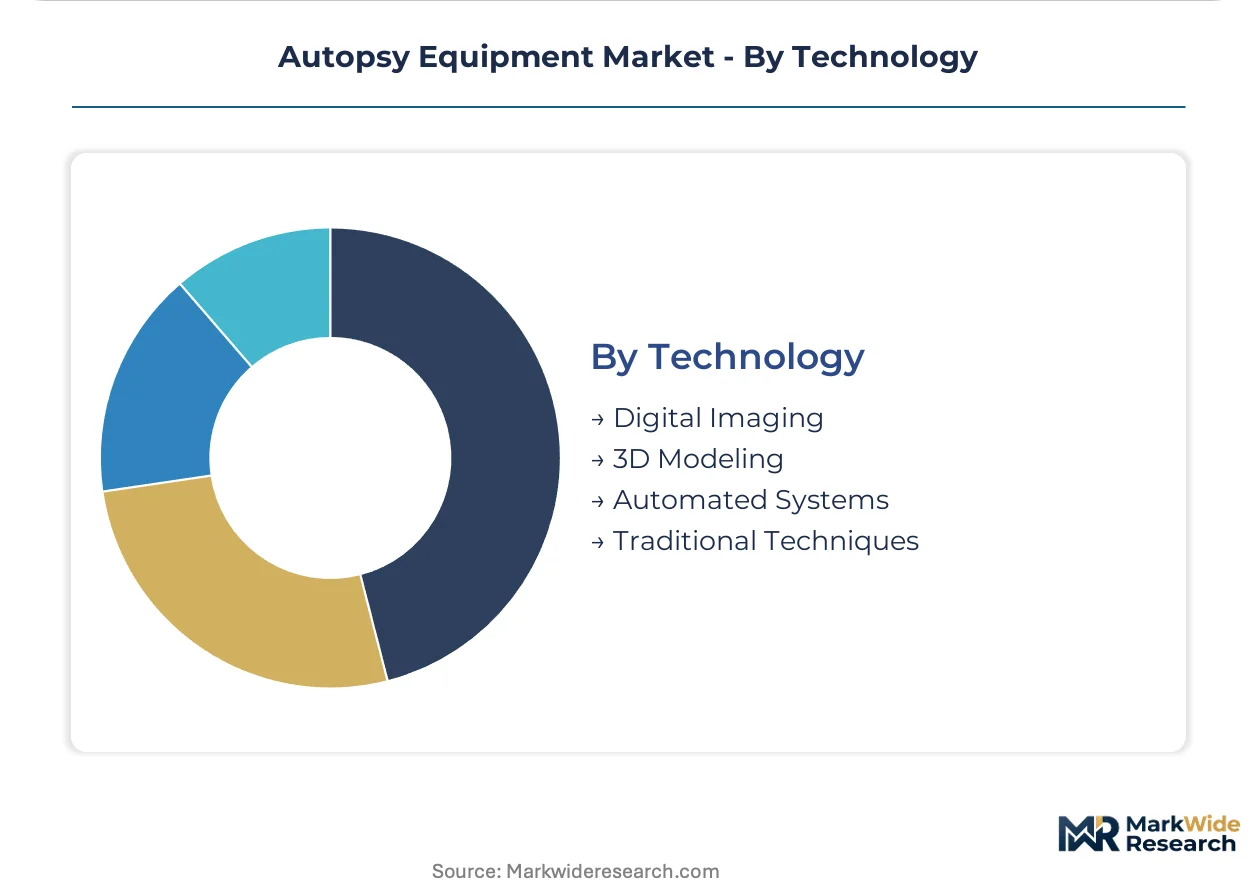
Technology:
Margin tier separation widens between premium digital integration and commoditized mechanical systems, with software-enabled workflows capturing expanding service attach rates.
- Digital Imaging:High-resolution capture systems with embedded chain-of-custody verification enable real-time collaboration between on-site pathologists and remote specialists, with German federal hubs piloting three-dimensional surface documentation for high-volume case screening that compresses physical suite utilization.
- Automated Systems:Robotic fluid management and specimen tracking reduce pathologist exposure hours while standardizing documentation protocols, with integration friction against incumbent laboratory information systems extending deployment schedules for multi-vendor environments.
- 3D Modeling:Virtual external examination protocols decouple preliminary trauma assessment from dissection scheduling.
- Traditional Techniques:Manual instrumentation persists in budget-constrained installations and jurisdictions with limited technical support infrastructure.
Digital Imaging holds the largest share; momentum sits with Automated Systems as labor scarcity pressures operational efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU MDR anchors procurement dynamics across Germany's federal pathology networks, with sterilization mandates and traceability requirements compressing replacement cycles for legacy instruments. German state purchasing cooperatives in Baden-Württemberg and Bavaria consolidate demand from county-level medical examiner offices, reshaping vendor access patterns across Central Europe.
Germany
Federal pathology networks are modernizing regional morgue infrastructure through centralized tenders that bundle maintenance contracts with digital documentation suites. The EU MDR's biocompatibility documentation requirements extend review timelines for Class IIa instrument registrations through BfArM. Baden-Württemberg's purchasing cooperative aggregates demand from Stuttgart, Mannheim, and Freiburg medical examiner offices, compressing vendor margins while demanding integrated LIMS compatibility.
United States
Academic medical centers drive retrofit demand for video capture and teleconferencing modules that support remote pathology instruction. FDA device classification rules and OSHA bloodborne pathogen standards shape product design and channel access for domestic suppliers. The Greater Boston cluster of teaching hospitals prioritizes configurable dissection stations, while Texas medical examiner offices expand multi-table suite installations for criminal case backlogs.
United Kingdom
Forensic pathology services consolidate procurement authority under regional hubs that prioritize modular workstation designs for legacy facility retrofit. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for post-Brexit market access. London's academic medical centers and Manchester's regional pathology networks anchor demand concentration, with Scottish medical examiner offices piloting three-dimensional imaging for high-volume case screening.
France
ANSM notification requirements and REACH chemical restrictions impose conformity costs on protective material formulations entering forensic markets. The Île-de-France region concentrates demand through Parisian teaching hospitals and national forensic institutes, while Auvergne-Rhône-Alpes medical examiner offices modernize suite configurations. Lyon and Marseille pathology hubs diversify supplier relationships beyond legacy incumbents.
Japan
PMDA medical device regulations and JIS standards govern instrument registration for forensic pathology applications. METI industrial policy supports domestic stainless steel fabrication capacity for corrosion-grade medical equipment. The Kanto region's Tokyo metropolitan medical examiner offices and Kansai's Osaka academic medical centers anchor demand, with Nagoya teaching institutions retrofitting facilities for undergraduate instruction and specialized forensic fellowships.
Autopsy Equipment Market Competitive Landscape
Specialized forensic fabricators and diversified laboratory conglomerates split the market into distinct capability tiers. The vendor base concentrates around three structural positions: domestic manufacturers leveraging proximity to government tenders, multinational instrument platforms extending forensic portfolio breadth, and niche workstation specialists anchoring academic retrofit segments. Consolidated procurement frameworks and multi-year service bundling represent the dominant competitive moves, compressing standalone equipment margins while expanding recurring revenue attach rates.
Within the domestic-manufacturer tier, Kugel Medical anchors Central European positioning through proximity to German federal tenders. Mopec occupies the specialized-workstation vector, with its dissection table configurations serving North American academic medical centers. Thermo Fisher Scientific exemplifies the diversified-platform archetype, extending forensic portfolio breadth to capture premium segments in digital imaging integration.
| Leading Market Players |
|---|
| Kugel Medical |
| Mopec |
| Mortech Manufacturing |
| Thermo Fisher Scientific |
| LEEC |
| Ferno-Washington |
| Angelantoni Life Science |
| HYGECO |
| Barber of Sheffield |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp corridor freight rates for corrosion-grade stainless steel sheet directly compress margin pools for examination table fabricators serving German federal tenders, while downstream pricing stratifies across premium digital-integrated suites, standard modular workstations, and economy fixed-height configurations bound for budget-constrained county medical examiner offices.
Pricing Analysis
Price spreads between German domestic tenders and North American academic retrofit contracts exceed twenty percent on equivalent table specifications, with premium-mid-economy pricing differentiation anchored by EU MDR certification tier, integrated LIMS compatibility, and multi-year service bundling. Cost compression in standard mechanical tiers intensifies as Baden-Württemberg purchasing cooperatives aggregate county-level demand, while forensic investigation buyers show lowest price sensitivity due to legal proceedings funding and evidence preservation mandates. Academic institutions exhibit highest price sensitivity, prioritizing modular retrofit compatibility over integrated digital suites.
Supply Chain Analysis
Surgical-grade 316L stainless steel feedstock concentrates among German, Swedish, and Finnish specialty mills, with autopsy equipment fabrication drawing from corrosion-grade sheet, precision hydraulic components, and sealed biohazard containment systems. Single-source vulnerability sits with the three-mill concentration for certified surgical alloy, exposing fabricators to alloy surcharge volatility and extended lead times during capacity constraints. Distribution runs through regional medical device distributors serving government pathology networks, with direct manufacturer relationships reserved for multi-suite federal tenders and academic medical center retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forensic pathologist training program bottlenecks constrain equipment utilization cycles and compress capital deployment timelines, creating acute scarcity in specialized technical support capabilities for digital-integrated autopsy suites.
For Market Incumbents: Build switching-cost moats through multi-year LIMS integration contracts that embed proprietary interface protocols, locking government pathology networks into recurring service revenue streams. Consolidate regulatory affairs functions to compress EU MDR review timelines through pre-submission engagement with BfArM. Add dedicated calibration technical support capacity in Stuttgart and Munich to defend against emerging workstation specialists targeting Bavarian retrofit demand. For New Entrants and Emerging Players: Build out remote pathology instruction infrastructure partnerships with North American academic medical centers, where configurable dissection stations for variable cohort sizes remain underpenetrated relative to integrated forensic suites. Target teaching hospital digitization white space through video capture and teleconferencing module bundling, bypassing capital-intensive government tender barriers. Pursue GPO channel relationships with university procurement committees rather than direct federal contracting. For Investors and Strategic Acquirers: Niche forensic workstation specialists with established academic medical center relationships and modular retrofit IP represent the most defensible acquisition archetype within a five-to-ten year viability window. Prioritize targets with proprietary digital imaging integration capabilities and existing BfArM notification body rapport. Monitor EU MDR Class IIa instrument registration backlogs as inflection indicator for regulatory capacity constraints that favor incumbent consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Accelerates BfArM review timelines for Class IIa autopsy instruments entering German federal tenders. |
| LIMS Integration Partnership | Embeds vendor workflows into government pathology network laboratory information management systems. |
| Regional Service Hub Expansion | Shortens response times for calibration and biohazard containment validation across Central European installations. |
| Academic Medical Center GPO Channel | Bypasses capital-intensive federal tender processes for teaching institution retrofit demand. |
| 3D Surface Documentation Pilot | Positions vendor for German federal hub virtualization initiatives compressing physical suite utilization. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with forensic pathologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EU MDR notified body registration databases, German federal procurement portal awards, and hospital capital expenditure disclosures. Bottom-up equipment shipment estimates triangulated against top-down pathology network modernization budget allocations across the analysis window.
Forecast inputs considered product type segmentation across examination tables, autopsy saws, dissection tools, and protective gear; application splits between forensic investigation, teaching institutions, medical research, and legal proceedings; and technology tiers spanning digital imaging, automated systems, 3D modeling, and traditional techniques. CAGRs were derived from equipment replacement cycle analysis, EU MDR-driven sterilization mandate compliance deadlines, and criminal case backlog expansion trajectories across government medical examiner offices.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified laboratory conglomerates would shift outcomes beyond modeled ranges. Cross-checking against German federal pathology network capital budget appropriations and BfArM Class IIa registration throughput is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Medical Automation Market
Medical Equipment
New-Born Screening Equipment Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Global Countertop Platelet Incubator Market
Medical Equipment
Global Surgical Lights Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
ECG Equipment Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
Global Medical Equipment Calibration Market