
 Global Core Materials Market | 2026-2036
Global Core Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Core Materials Market Intelligence
The competitive landscape for core materials is shifting as the performance gap between high-specification aerospace-grade foams and lower-cost alternatives for construction widens. Gurit specializes in balsa wood and PET foams, targeting the high-performance marine and wind energy segments. Diab Group leverages its global manufacturing footprint to supply a broad range of foam core solutions. Hexcel Corporation differentiates through advanced honeycomb systems for demanding aerospace applications.
Core materials are lightweight structural components placed between two stiff facings to create a sandwich panel. Their primary function is to increase panel stiffness and strength with minimal weight penalty, using structures like foam or honeycomb. Foam products, including PET and PVC variants, dominate market volume, driven by their extensive use in wind turbine blades. Honeycomb materials, while a smaller segment by volume, hold high value in aerospace applications for OEM manufacturers.
Material specifications for aerospace applications are heavily governed by bodies like the FAA in the United States and EASA in Europe. In parallel, chemical regulations such as the EU's REACH framework and EPA rules in the US influence the types of blowing agents and resins used in foam core production. Navigating the dual pressures of stringent performance certification and evolving environmental compliance is a central challenge for material suppliers.
Market Dynamics
The core materials market is defined by a fundamental tension between performance requirements and sustainability mandates. Demand from wind energy and aerospace sectors for lighter, stronger components pushes material innovation, while global regulations like the EU's REACH framework simultaneously restrict chemical inputs, forcing complex reformulations.
Growth Catalysts
- Wind Energy Expansion:Government-led renewable energy targets, including the EU Green Deal and China's dual carbon goals, are accelerating the construction of larger wind turbines, which require significant volumes of foam and balsa core materials for longer, lighter blades.
- Aerospace Modernization:The drive for fuel efficiency in next-generation aircraft sustains demand for high-value honeycomb and certified foam cores in interiors, nacelles, and control surfaces, where weight reduction is a primary design objective.
- Industrial Lightweighting:In transportation and construction, core materials are increasingly substituting traditional materials like steel and aluminum to create lightweight, stiff, and corrosion-resistant composite panels for applications like truck bodies, railcars, and bridge decks.
Market Restraints
- Raw Material Price Volatility:The cost of key inputs for foam cores, particularly petrochemical-derived resins like PET, PVC, and the associated blowing agents, is subject to fluctuations in global energy markets, impacting manufacturer margins and final product pricing.
- Stringent Certification Barriers:Gaining airworthiness certification from bodies like the FAA and EASA for aerospace-grade core materials is a time-consuming and expensive process, limiting the number of qualified suppliers and slowing the introduction of new materials.
- Technical Processing Complexity:Manufacturing high-consistency foam and honeycomb cores requires significant capital investment in specialized equipment and stringent process controls to manage properties like density and cell size, creating a high barrier to entry.
Strategic Opportunities
- Circular and Bio-Based Materials:Developing core materials from recycled sources, such as rPET foam, or from bio-based feedstocks presents a significant opportunity to meet corporate sustainability goals and appeal to environmentally conscious end-users in packaging and consumer goods.
- Electric Vehicle Components:The automotive industry's shift to electric vehicles opens new applications for lightweight core materials in battery enclosures, floor pans, and body panels, where reducing weight is critical for maximizing vehicle range and performance. *Automated Kitting Solutions: Offering pre-cut, numbered, and packaged core material kits for specific large-scale components like turbine blades or boat hulls provides a value-added service that reduces customer labor costs and material waste, creating a competitive advantage.
Industry Challenges
- Process Standardization:A lack of standardized testing and quality control protocols across different regions and suppliers for non-aerospace applications can lead to performance inconsistencies, complicating material selection for engineers in the marine and industrial sectors.
- Complex Supply Chain Management:The geographic concentration of foam production in Asia, particularly China, creates long and fragile supply chains for customers in Europe and North America, exposing them to logistical delays and geopolitical risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Core Materials Market |
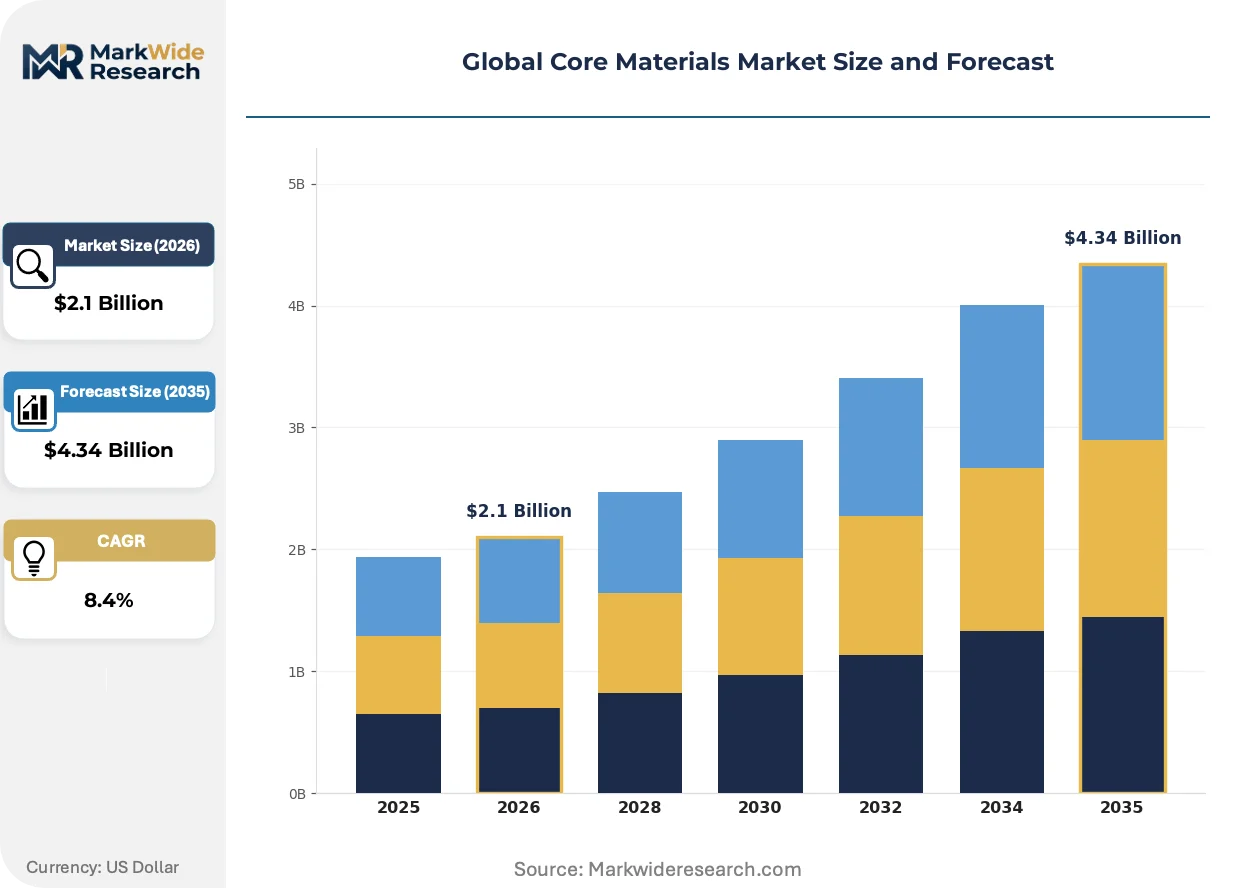
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balsa Wood, Honeycomb, Foam, Paper, Non-Woven Fabrics Form: Sheet, Block, Roll, Panel, Molded Application: Aerospace, Marine Vessels, Wind Turbines, Sports Equipment, Construction End User: OEM Manufacturers, Composite Fabricators, Aftermarket Providers, Tier-1 Suppliers, Repair Workshops |
| Companies Covered | 3A Composites, Diab Group, Gurit, Hexcel Corporation, Armacell, Euro-Composites, Evonik Industries, Plascore Incorporated, The Gill Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Core Materials Market Strategic Shifts & Innovations
Material science advancements are converging with circular economy principles, reshaping product development. Innovations focus on creating core materials that not only deliver superior strength-to-weight ratios but also offer improved recyclability and a lower carbon footprint, responding directly to regulatory pressures and OEM sustainability targets.
Thermoplastic foams, especially Polyethylene Terephthalate (PET), provide a recyclable and highly thermoformable core material solution. The wind energy industry is a primary adopter, using PET in turbine blades as a sustainable alternative to traditional PVC and balsa wood. Originally used for less critical parts, improved PET foam formulations are expanding into more structurally demanding applications, challenging incumbent materials.
The EU's REACH regulation imposes stringent controls on chemical substances, directly influencing material composition. This framework affects the production of foam cores by restricting certain blowing agents and flame retardants, forcing chemical suppliers and foam manufacturers to invest heavily in research and development. European producers of PVC and polyurethane foams are most impacted, accelerating their shift toward compliant and greener formulations to maintain market access.
Buyers are increasingly seeking integrated supply solutions rather than just raw material sheets. This trend disrupts the role of traditional distributors, as OEMs in the marine and wind sectors now favor suppliers who can provide pre-cut, 3D-formed, and kitted core components directly to their assembly lines. This demand for value-added services is most visible in Europe and North America, where high labor costs make pre-fabrication economically attractive.
Global Core Materials Market Segmentation
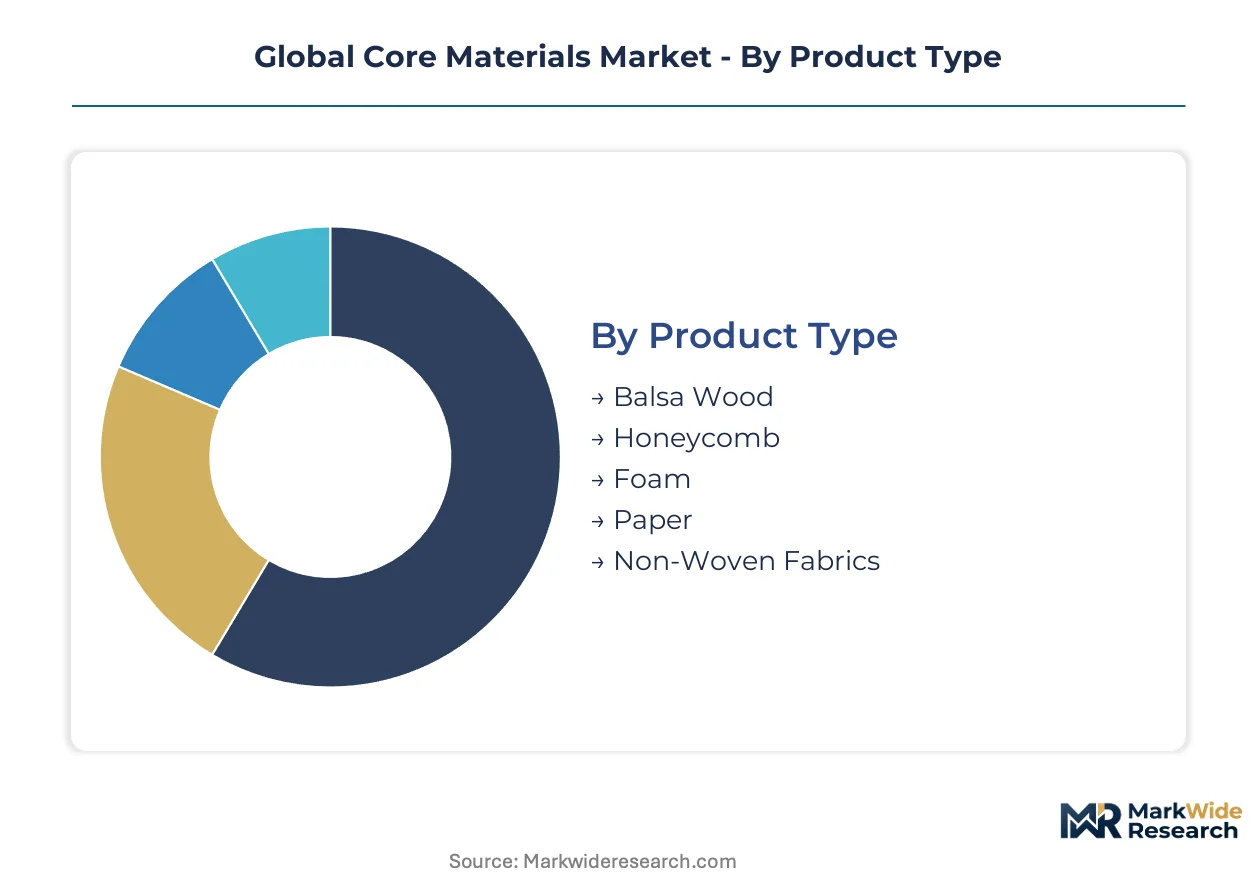
Segmentation provides a granular view of the core materials market, highlighting diverse product specifications and end-use applications. Understanding these distinct segments helps manufacturers tailor material properties and supply chain strategies. This detailed analysis reveals where innovation is most impactful and where demand is most concentrated.
Product Type:
The core materials market experiences continuous product evolution, driven by the replacement cycle for older, heavier materials with advanced, lightweight composites.
- Balsa Wood:Balsa wood, a natural core material, offers high shear strength and sustainability, primarily used in marine and wind turbine applications.
- Honeycomb:Honeycomb materials, typically made from aramid paper or aluminum, provide superior stiffness and impact resistance due to their cellular structure. Aerospace applications for OEM manufacturers sustain high-value demand, where strict airworthiness certification is paramount for flight safety.
- Foam:Foam products, including PET and PVC variants, offer excellent strength-to-weight ratios and insulation properties. Demand from the wind energy sector, particularly for large turbine blades, drives significant volume, as manufacturers seek lighter, more durable structures.
- Paper:Paper cores, often impregnated with resin, find use in less demanding applications such as interior panels and packaging.
- Non-Woven Fabrics:Non-woven fabrics are utilized as core materials in specific composite structures, providing structural integrity and laminate thickness.
Foam sits at the top of the volume ranking, with Honeycomb climbing the fastest in high-value segments.
Form:
The diverse forms of core materials cater to specific manufacturing processes and application requirements across various industries.
- Sheet:Sheet core materials are widely used as flat stock for general composite layups, offering versatility for cutting and shaping. High-volume demand comes from construction and marine vessel fabrication, where large flat surfaces are common.
- Block:Block forms of core materials allow for custom shaping and machining into complex geometries for specialized components.
- Roll:Roll core materials are suitable for continuous production processes, particularly in applications requiring long, flexible sections.
- Panel:Panel forms represent pre-fabricated sandwich structures, integrating core materials between facings for immediate use in structural applications. OEM manufacturers in transportation benefit from reduced assembly times and consistent quality.
- Molded:Molded core materials are pre-formed into specific shapes, reducing waste and labor in complex component manufacturing.
The preference for specific forms often correlates directly with the scale and complexity of the end-use manufacturing process.
Application:
The volume requirements for core materials vary significantly across different application sectors, influencing material selection and supply chain dynamics.
- Aerospace:Aerospace applications demand high-performance, certified core materials like honeycomb and specialized foams for structural components and interiors. The drive for fuel efficiency in next-generation aircraft sustains high-value demand for weight reduction.
- Marine Vessels:Marine vessels utilize core materials for hull, deck, and superstructure components, reducing weight and enhancing fuel efficiency.
- Wind Turbines:Wind turbines represent a substantial market for core materials, particularly foam and balsa wood, used in the construction of long, lightweight blades. Government-led renewable energy targets in China and the EU drive this segment's expansion.
- Sports Equipment:Sports equipment, including skis and surfboards, benefits from core materials for lightweight strength and improved performance.
- Construction:Construction applications use core materials in panels for insulation, lightweight cladding, and bridge decks, replacing traditional heavy materials.
Each application segment presents unique material specifications and certification hurdles for suppliers.
End User:
Core material demand is shaped by the specific operational needs and procurement strategies of various end-user types within the composite supply chain.
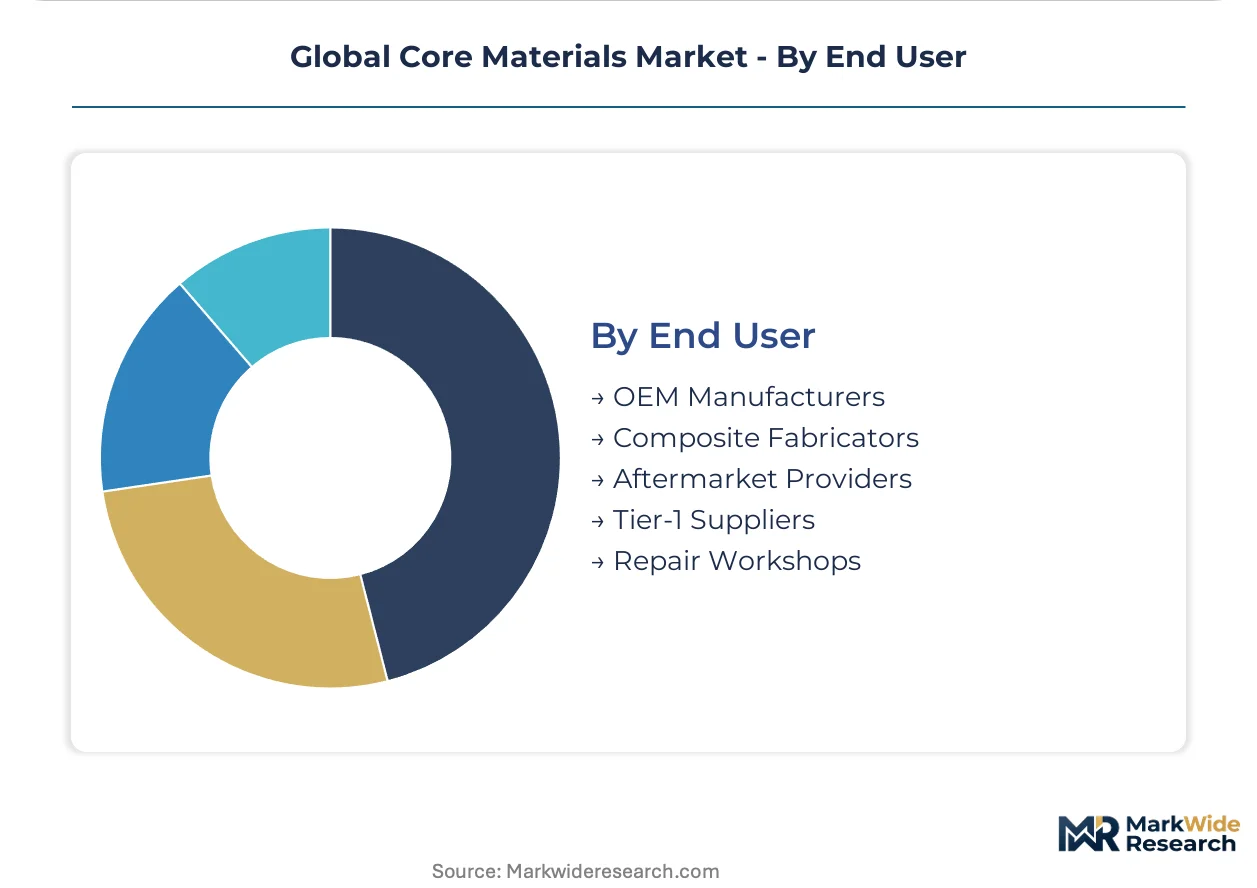
- OEM Manufacturers:OEM manufacturers, such as aircraft builders and wind turbine producers, require large volumes of precisely specified and certified core materials directly for their assembly lines. Value-added services like kitting are increasingly preferred by these large-scale buyers.
- Composite Fabricators:Composite fabricators purchase core materials to produce components for diverse industries, offering specialized processing and assembly services. They often seek a balance between material cost, workability, and performance for their varied client projects.
- Aftermarket Providers:Aftermarket providers supply core materials for upgrades and modifications to existing composite structures.
- Tier-1 Suppliers:Tier-1 suppliers integrate core materials into sub-assemblies delivered to OEM manufacturers, ensuring compliance with strict specifications.
- Repair Workshops:Repair workshops use core materials for structural repairs and maintenance of composite parts, requiring versatile and adaptable products.
Procurement patterns across these end-user segments increasingly favor integrated supply solutions over raw material sheets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's rapid expansion in wind energy contrasts with the United States' sustained demand from aerospace and defense sectors for core materials. Both nations drive innovation in lightweight composites. European countries like Germany and France also contribute significantly to material advancements.
China
China's extensive wind energy expansion creates substantial demand for foam and balsa core materials for turbine blades. The nation's dual carbon goals provide strong incentives for domestic production and sustainable material development. The Yangtze River Delta region concentrates foam core production for its vast renewable energy projects.
United States
Aerospace modernization and industrial lightweighting initiatives sustain high-value demand for advanced core materials in the United States. FAA airworthiness certification for aircraft components sets stringent performance standards for suppliers. The aerospace cluster in Seattle, Washington, focuses on developing high-performance honeycomb and specialized foam cores for next-generation aircraft designs.
Germany
German demand for core materials stems from its robust automotive industry, including electric vehicles, and a growing wind energy sector. The EU Green Deal and REACH framework significantly influence material composition and sustainability requirements for foam core producers. Bavaria serves as a hub for advanced material research and production, particularly for high-performance composites in transportation.
India
Emerging demand for lightweight construction and transportation solutions drives core material consumption in India. BIS standards increasingly impact material selection for infrastructure projects, promoting durable and efficient composites. Gujarat is witnessing growth in composite manufacturing, catering to industrial lightweighting and nascent wind energy projects.
France
French aerospace and marine sectors are significant consumers of high-performance core materials for structural integrity and weight reduction. EASA certification for aviation components ensures strict quality and safety compliance. The Toulouse region, a major aerospace hub, drives demand for advanced honeycomb and foam cores for aircraft manufacturing and assembly.
Global Core Materials Market Key Industry Players
Top-tier vendors anchor the global core materials market, while a fragmented base of regional specialists and niche providers addresses specific application needs. The competitive landscape features a blend of large, integrated material suppliers and specialized innovators focusing on high-performance applications. Companies pursue portfolio diversification to serve multiple end-use sectors and form strategic partnerships to expand geographic reach or technical capabilities. Strategic mergers and acquisitions also play a role in consolidating market share and acquiring new technologies.
Among established material suppliers, Diab Group exemplifies a global footprint in foam core solutions, serving diverse industries with a broad product portfolio. Gurit occupies a strong position as a specialist in balsa wood and PET foams, primarily targeting the high-performance marine and wind energy segments with sustainable options. Hexcel Corporation anchors the high-value aerospace sector with its advanced honeycomb systems, representing a focus on demanding, certified applications where weight reduction and structural integrity are paramount. These companies collectively illustrate the market's segmentation by material type and end-use specialization.
| Leading Market Players |
|---|
| 3A Composites |
| Diab Group |
| Gurit |
| Hexcel Corporation |
| Armacell |
| Euro-Composites |
| Evonik Industries |
| Plascore Incorporated |
| The Gill Corporation |
| Others |
Cost & Logistics Intelligence
Petrochemical-derived resin prices, influenced by global energy markets, cascade through the core materials supply chain, directly impacting pricing tiers for foam products. This volatility creates a fundamental tension between material cost and performance requirements for end-users.
Pricing Analysis
Capacity additions in China are reshaping price floors for high-volume foam cores, particularly PET and PVC variants. The dominant pricing structure involves contract-based long-term offtake agreements for large OEM manufacturers. Price differentiation stems from certification level, especially for aerospace-grade materials requiring FAA and EASA approval, and the level of value-added services like kitting. Pricing softness reflects raw material price volatility for petrochemical inputs; composite fabricators exhibit higher price sensitivity compared to OEM manufacturers seeking certified, integrated solutions.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns support the global core materials market, balancing localized demand with concentrated production. Geographic supply concentration sits primarily in China for foam cores, serving vast renewable energy projects, while high-value honeycomb materials are produced in the United States and Europe. The supply chain draws from petrochemical-derived resins and balsa wood, with logistical delays and geopolitical risks representing a structural supply chain risk for customers in Europe and North America. The distribution model increasingly favors direct integrated supply solutions to OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the premium-tier shift towards highly certified aerospace materials and value-added kitting solutions. Manufacturers can improve profitability by focusing on advanced material formulations and integrated supply.
For Market Incumbents: Lock in long-term supply agreements for key raw materials to mitigate price volatility. Invest in advanced R&D for compliant, high-performance materials, particularly rPET and bio-based foams, to counter evolving environmental compliance regulations like REACH. Expand value-added services, such as automated kitting, to deepen relationships with OEM manufacturers and defend against emerging component suppliers. Certification investment for FAA and EASA standards remains a critical lever for high-value segments. For New Entrants and Emerging Players: Underserved small-to-medium composite fabricators present a clear entry point for specialized core materials. Target white-space opportunities in bio-based core materials for packaging or lightweight components for electric vehicle battery enclosures. The industrial lightweighting segment, outside of aerospace, offers a penetrable application area due to less stringent certification. A go-to-market angle focusing on sustainable, cost-effective alternatives with localized supply chains can differentiate offerings. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized material innovators developing next-generation sustainable core solutions. The market offers sustained long-term viability over the next decade, propelled by lightweighting and sustainability mandates across multiple industries. Acquisition targets should include companies with proprietary rPET or bio-based foam technology, or those possessing advanced automated kitting capabilities. The adoption rates of bio-based core materials in non-wind and non-aerospace sectors will serve as a key inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in rPET Foam | Increases supply of sustainable core materials for wind energy and automotive applications. |
| Certification Investment for Aerospace Grades | Unlocks access to high-value aerospace applications with stringent FAA and EASA requirements. |
| Automated Kitting Solutions Development | Reduces customer labor costs and material waste for OEM manufacturers, enhancing stickiness. |
| Long-Term Balsa Wood Supply Agreements | Secures critical natural core material for wind turbine blades, mitigating supply chain risks. |
| Joint Venture for Bio-Based Material Research | Accelerates development of novel sustainable core materials, addressing future regulatory demands. |
Research Approach
Multiple input streams — industry expert interviews, company annual reports, and regulatory filings — were reconciled to build a comprehensive view of the core materials market. This approach combined primary interviews with R&D directors, procurement leads at OEMs, and composite fabricators with secondary validation from SEC 10-K filings and national renewable energy agency reports. Bottom-up data aggregation and top-down market sizing provided triangulation for accuracy.
Data-stream reconciliation integrated historical market performance with projected demand drivers across the analysis window. The analytical framework modeled segmentation dimensions including product type, form, application, end-user, and material composition. Compound annual growth rates were derived from historical trends and projected future demand for lightweight components. Key industry-specific forecast inputs included wind turbine blade length trends and new aircraft program schedules.
Underlying measurement precision varies by segment; aerospace and wind turbine applications carry tighter precision than others due to established certification processes. Forecasts reflect documented assumptions regarding technological advancements and regulatory stability. Geopolitical shifts affecting supply chains or unforeseen regulatory changes could revise these forecasts, and decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Boron Nitride Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Global Electrochromic Materials Market
Advanced Materials
Anisotropic Conductive Films (ACF) Market
Advanced Materials
Si-C Anode Material Market
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Global Thermal Interface Materials Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
Hexagonal Boron Nitride (HBN) Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
Corundum Market
Advanced Materials
Inorganic Non-Metallic Materials Market
Advanced Materials
Cathode Materials Market
Advanced Materials
Global Advanced Materials Market