
 Densified Silica Fume Market | 2026-2036
Densified Silica Fume Market Size, Share, and Industry Trends Forecast 2026-2036
Densified Silica Fume Market Analytics
Skilled concrete technologist availability is rotating toward scarcity in mature markets while expanding in Asia-Pacific production hubs. Elkem leverages its integrated ferrosilicon-to-microsilica refining network to sustain raw material security across Nordic and North American supply chains. Sika Corporation anchors its position through formulation expertise that binds densified silica fume into proprietary admixture systems for infrastructure clients. BASF competes on R&D intensity, operating dedicated centers that optimize pozzolanic reactivity in blended cement applications.
Densified silica fume consists of amorphous silicon dioxide particles recovered from ferrosilicon and silicon metal furnace off-gases, compacted to bulk densities of 500–700 kg/m³ to improve handling and dosing precision in concrete production. Its primary industrial purpose centers on enhancing compressive strength, reducing permeability, and extending service life in aggressive environments for marine, nuclear, and high-rise structures. Cement additive formulations dominate volume absorption due to mature specification pipelines in infrastructure procurement, while polymer composite applications represent the fastest-growing segment as automotive and electronics manufacturers seek flame-retardant, high-fill thermoset systems. Concrete admixture channels carry the deepest margin pools where suppliers bundle technical service with material supply.
EPA emissions standards for ferroalloy production shape raw material availability and recovery economics in the United States, while REACH registration requirements in Europe constrain importer access and elevate documentation burdens for non-EU producers. China's GB standards for silica fume in hydraulic cement and India's BIS certification for pozzolanic materials create divergent compliance thresholds that fragment market access protocols. Stakeholders must monitor regulatory convergence between carbon-border adjustment mechanisms and national building codes to anticipate which certification investments will unlock premium specification tiers.
Market Dynamics
EU Green Deal carbon-border adjustment mechanisms are compressing specification windows for cementitious materials, forcing procurement officers to validate embodied carbon in every silica fume shipment while ferrosilicon smelter closures in Europe tighten raw material flows.
Growth Catalysts
- REACH registration thresholds:European importers face elevated documentation burdens that favor compliant suppliers with established EU supply chains, consolidating procurement toward certified Nordic and North American producers.
- Bridge and tunnel infrastructure resilience mandates:Transportation agencies in China, India, and the United States specify high-performance concrete with densified silica fume for chloride exposure protection in marine and deicing salt environments.
- Ferrosilicon furnace off-gas recovery:Integrated metallurgical operations capture amorphous silicon dioxide as a byproduct stream, securing raw material economics for densification and concrete admixture processing.
Market Restraints
- Ferrosilicon price volatility:Silicon metal and ferroalloy feedstock costs swing with electricity pricing and Chinese industrial policy, transmitting margin pressure through the silica fume value chain.
- Supply concentration in Nordic ferrosilicon corridors:Norwegian and Icelandic smelter clusters dominate high-purity microsilica generation, creating single-source exposure for specification-grade densified product.
- Fly ash and slag substitution:Lower-cost supplementary cementitious materials compete in non-critical concrete applications, capping silica fume penetration in standard-grade construction.
Strategic Opportunities
- Polymer composite flame-retardant formulations:Automotive and electronics manufacturers specify high-fill thermoset systems where densified silica fume replaces halogenated additives in battery enclosures and circuit substrates.
- Indian BIS pozzolanic certification expansion:Bureau of Indian Standards recognition opens specification pathways for imported densified silica fume in national highway and metro rail concrete procurement.
- Carbon capture integration at ferrosilicon smelters:Norwegian producers pilot emissions abatement that qualifies recovered silica fume for green procurement premiums under EU taxonomy alignment.
Industry Challenges
- Concrete technologist scarcity:Mature markets face retiring specialist cohorts while Asia-Pacific training pipelines lag megaproject demand for mix design optimization with silica fume.
- GB standard divergence from ASTM C1240:Chinese hydraulic cement specifications create testing protocol fragmentation that complicates multi-source qualification for international contractors.
- Densification equipment capex cycles:Bulk density upgrading to 500–700 kg/m³ requires pneumatic compaction investments that strain mid-scale processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Densified Silica Fume Market |
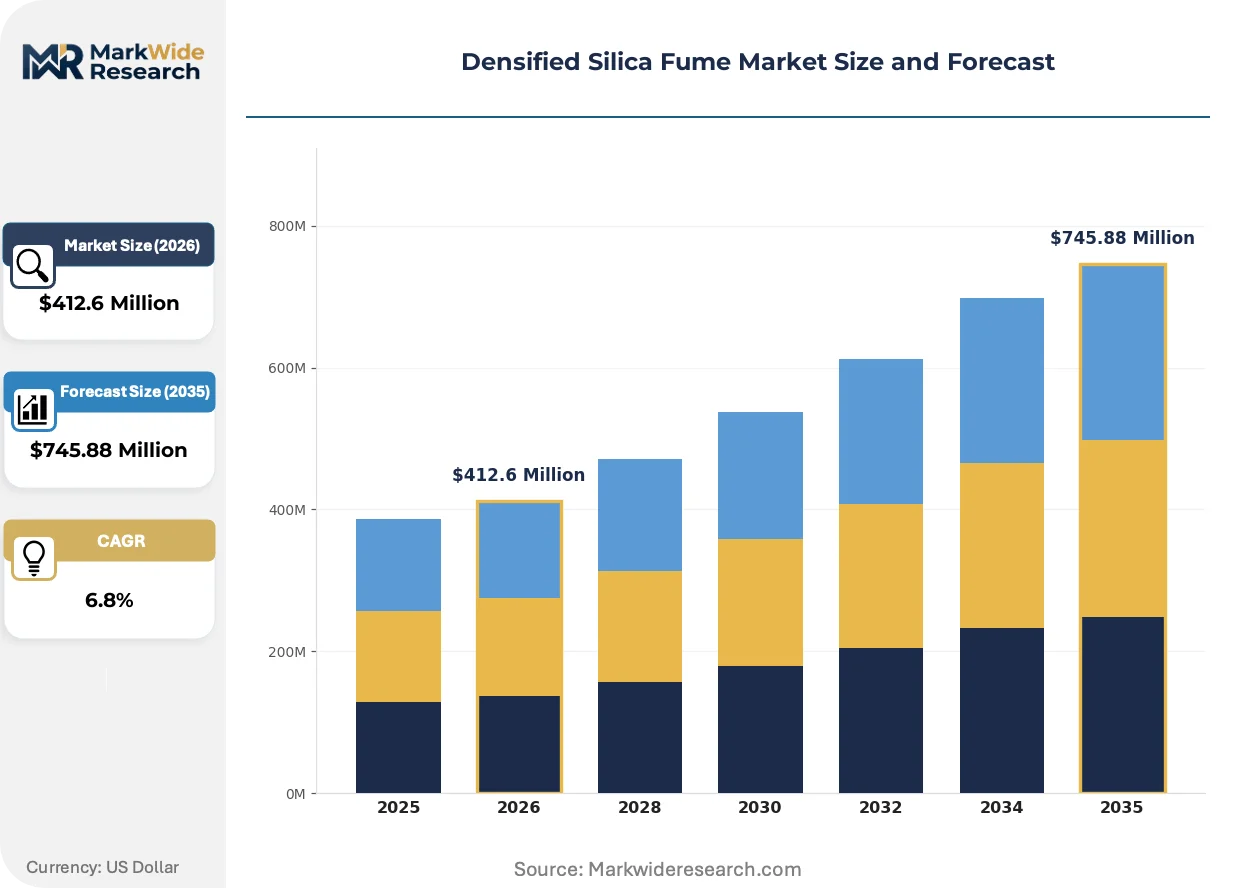
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement Additive, Concrete Admixture, Polymer Composite, Sealants Application: Construction, Infrastructure, Oil & Gas, Electronics End User: Construction Companies, Manufacturing Units, Chemical Producers, Research Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF, Sika Corporation, Elkem, Kryton International, Norchem Inc, Xypex Australia, Chryso Inc, Wuhan Newreach Microsilica Co., Ltd, Scancem Materials (Singapore) Pte Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Densified Silica Fume Market Evolving Landscape
Specification-grade densified silica fume is bifurcating into carbon-accounted premium tiers and commodity admixture grades as procurement platforms embed environmental product declarations into supplier scorecards.
Advanced densification with controlled agglomeration is supplanting basic mechanical compaction in specification-grade production. Marine concrete contractors in the United States and Nordic tunnel consortia specify these engineered particle structures for guaranteed dosing precision in automated batching systems. The technology is compressing quality variance allowances in infrastructure procurement contracts, locking out undifferentiated commodity suppliers.
EU Green Deal carbon-border adjustment mechanisms are tightening embodied carbon thresholds for imported cementitious materials. European concrete producers now require third-party verified carbon footprints on every silica fume delivery, shifting procurement toward Nordic smelters with hydroelectric power profiles. The regulation is fragmenting supplier access between premium carbon-compliant channels and price-driven Mediterranean and Asian import streams.
Buyers are consolidating annual silica fume contracts around technical service bundling rather than spot material procurement. Infrastructure contractors in Germany and Japan now specify admixture system performance guarantees that bind densified silica fume dosing to compressive strength and permeability outcomes. The model is visible most acutely in Japanese public works procurement, where Sika and BASF compete on integrated formulation service rather than standalone material supply.
Densified Silica Fume Market Segmentation
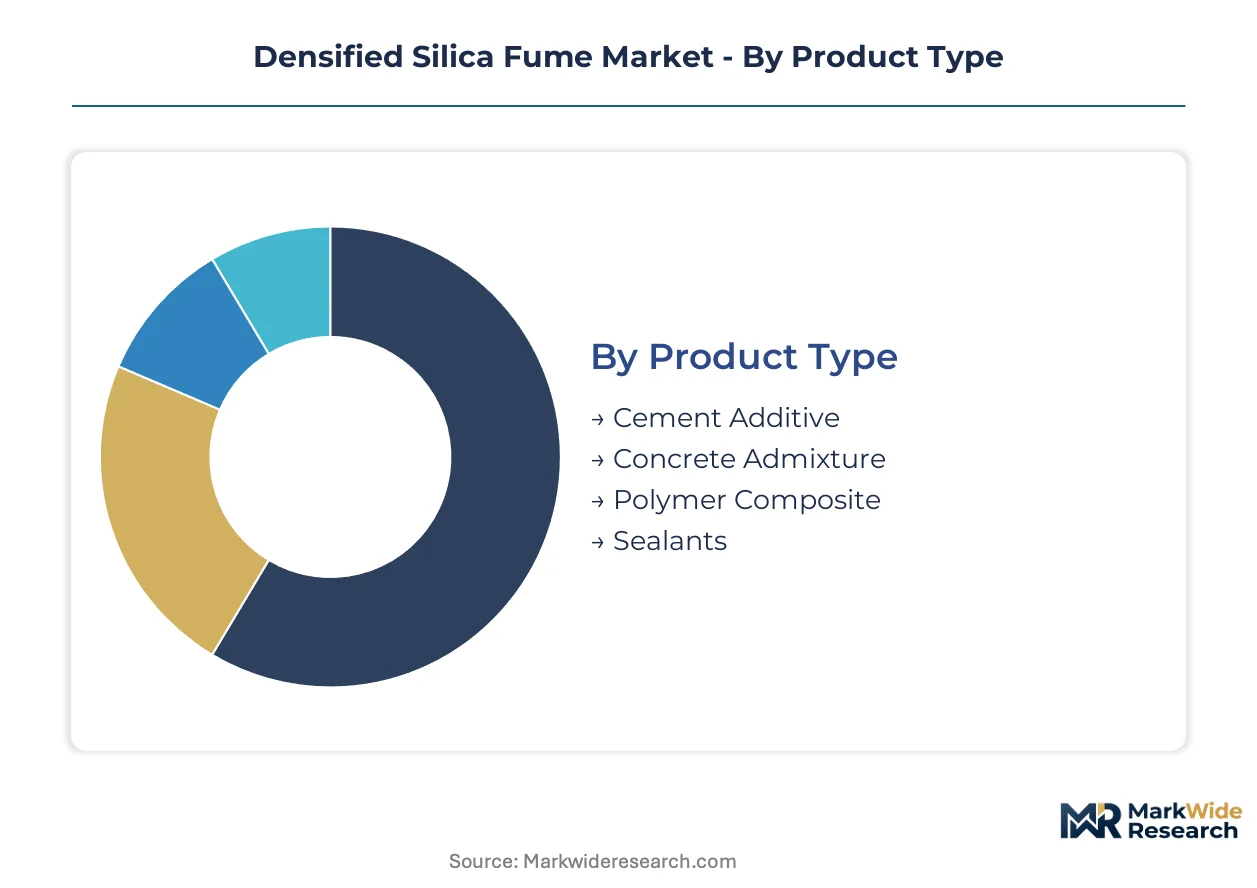
Densified silica fume procurement splits across four distinct category axes, each governing how suppliers capture value and how buyers qualify material streams. Product type determines technical specification intensity, while application and end-user categories shape service bundling requirements and contract structures.
Product Type:
Margin pools concentrate in concrete admixture channels where technical service bundling commands premium pricing, while polymer composite formulations are rotating up the value chain fastest as flame-retardant specifications tighten.
- Concrete Admixture:Specification-grade densified silica fume delivered in bulk or silo systems for automated batching in high-performance concrete. Transportation agencies in China and the United States specify this grade for chloride exposure protection in bridge decks and marine structures. Service bundling with mix design consulting locks in multi-year supply contracts.
- Cement Additive:Blended cement formulations incorporate densified silica fume at grinding stages to enhance pozzolanic reactivity and compressive strength. Mature procurement pipelines in European infrastructure projects absorb the largest volume flows, though price competition from fly ash and slag caps margin expansion.
- Polymer Composite:High-fill thermoset systems for automotive battery enclosures and electronics substrates. Flame-retardant specifications displacing halogenated additives are driving formulation trials at tier-one automotive suppliers.
- Sealants:Specialty grouting and waterproofing applications requiring ultra-low permeability. Niche volume concentrated in Nordic tunnel consortia and nuclear containment specifications.
Concrete Admixture holds installed capacity. Polymer Composite is rotating up the share rankings.
Application:
Volume concentration sits with infrastructure resilience mandates, while electronics applications are climbing the fastest as semiconductor packaging demands thermal stability.
- Infrastructure:Bridge, tunnel, and marine concrete requiring chloride resistance and extended service life. China's national highway program and India's metro rail procurement specify densified silica fume for aggressive environment protection. REACH-compliant Nordic suppliers dominate European tunnel consortia.
- Construction:High-rise and commercial building concrete where compressive strength targets exceed standard-grade capabilities. Japanese public works contractors bundle admixture system performance guarantees with material supply.
- Oil & Gas:Well cementing and offshore platform grouting demanding sulfate resistance and low permeability. Specification-grade procurement concentrates with integrated service providers.
- Electronics:Encapsulation compounds and circuit substrate fillers where thermal stability and flame retardancy converge. Battery enclosure specifications at automotive OEMs are expanding addressable demand.
Infrastructure commands procurement volume. Electronics is gaining share fastest.
End User:
Contractor consolidation is compressing supplier counts toward construction companies with in-house concrete technology capabilities, while chemical producers are deepening backward integration into ferrosilicon off-gas recovery.
- Construction Companies:Megaproject contractors in China, India, and the United States with dedicated concrete technology teams. These buyers specify performance-based contracts linking silica fume dosing to compressive strength and permeability outcomes.
- Manufacturing Units:Automotive and electronics OEMs qualifying densified silica fume for polymer composite and sealant formulations. Procurement emphasizes carbon-accounted material streams for EU taxonomy alignment.
- Chemical Producers:Integrated ferrosilicon smelters with captive microsilica recovery and densification capacity. Norwegian and Icelandic operators leverage hydroelectric power profiles for green procurement premiums.
- Research Institutions:Universities and national laboratories developing next-generation pozzolanic systems. Low volume but high influence over emerging specification protocols.
Construction Companies anchor demand volume. Chemical Producers are climbing the specification ladder fastest.
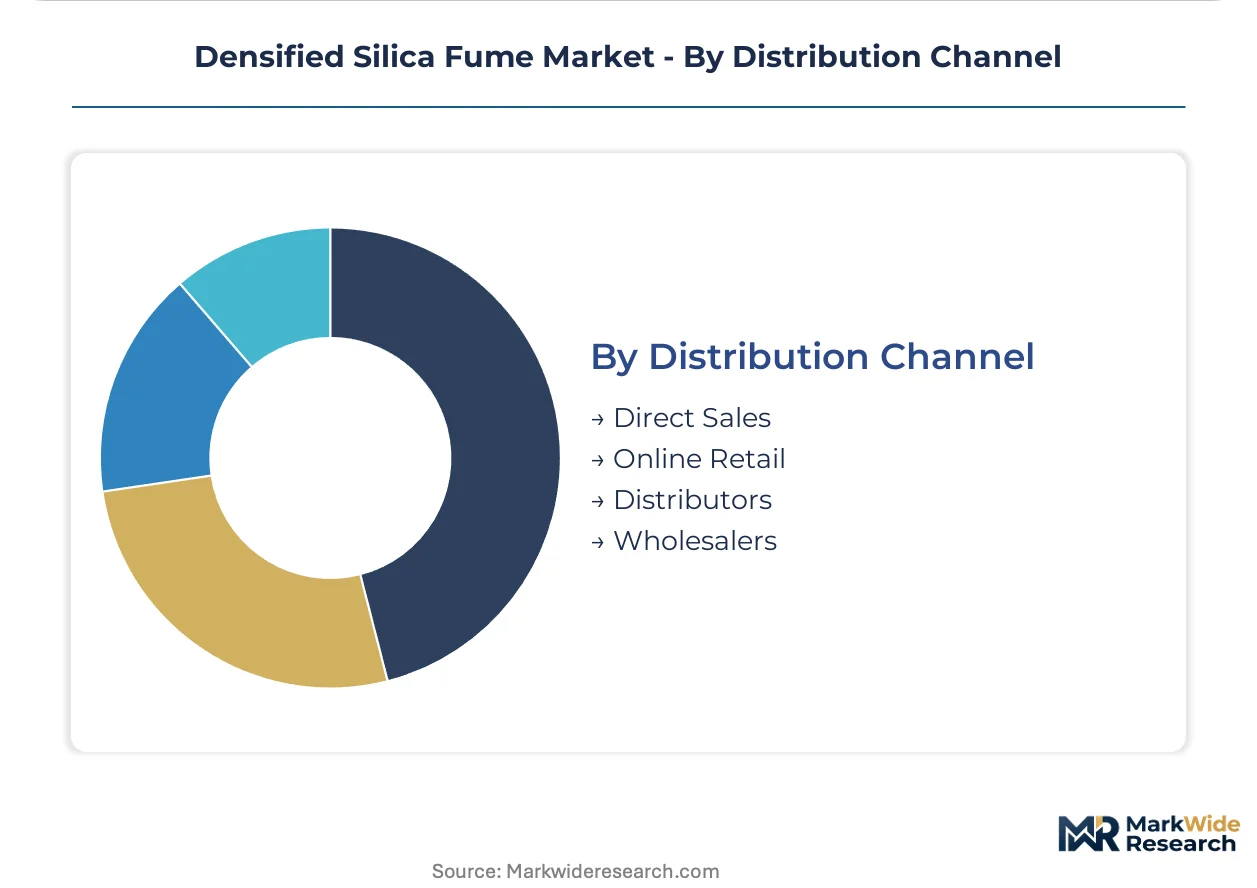
Distribution Channel:
Direct sales capture the deepest margin pools through technical service integration, while distributor networks are fragmenting as procurement platforms consolidate toward annual contract structures.
- Direct Sales:Supplier technical teams embed with infrastructure contractors for mix design optimization and batching system calibration. German and Japanese public works procurement mandates this channel for performance-guaranteed admixture systems.
- Distributors:Regional material handlers stocking specification-grade product for mid-scale concrete producers. REACH registration burdens favor distributors with established EU supply chain documentation.
- Wholesalers:Bulk volume handlers serving commodity-grade applications where price sensitivity dominates. Fly ash and slag substitution pressures limit silica fume penetration in this channel.
- Online Retail:Emerging platform for small-batch research and specialty sealant procurement. Limited current volume but expanding for BIS-certified imports into Indian metro rail projects.
Direct Sales holds relationship lock-in. Distributors are rotating up the channel rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Norway and Iceland feed premium carbon-accounted supply into EU infrastructure, while China and India absorb volume for domestic megaprojects, and the United States balances between coastal import dependence and domestic ferroalloy recovery.
China
National highway and metro rail programs specify densified silica fume for chloride-resistant concrete in coastal provinces. GB standards for silica fume in hydraulic cement diverge from ASTM protocols, complicating multi-source procurement for international contractors. The Yangtze River Delta concentrates domestic ferrosilicon smelting and microsilica recovery operations serving regional concrete admixture processors.
United States
Transportation agencies mandate high-performance concrete with silica fume for bridge decks exposed to deicing salts and marine environments. EPA emissions standards for ferroalloy production shape raw material availability and recovery economics across Ohio Valley smelter corridors. The Pacific Northwest and Gulf Coast rely on Nordic imports for specification-grade densified product where domestic supply falls short.
Norway
Hydroelectric-powered ferrosilicon smelters generate high-purity microsilica streams qualifying for EU Green Deal carbon-border adjustment premiums. REACH registration requirements favor established Nordic supply chains over Mediterranean and Asian import competitors. Rana and Mo i Rana industrial clusters anchor integrated refining-to-densification capacity serving European tunnel consortia.
India
Bureau of Indian Standards pozzolanic certification opens procurement pathways for imported densified silica fume in national highway and metro rail concrete. Central Public Works Department specifications increasingly reference silica fume for aggressive environment protection in coastal infrastructure. Gujarat and Maharashtra cement grinding facilities trial blended formulations with imported densified microsilica.
Germany
Public works procurement mandates technical service bundling that binds silica fume supply to compressive strength and permeability performance guarantees. EU Green Deal embodied carbon thresholds compress specification windows toward Nordic hydroelectric-sourced material. Rhine-Ruhr infrastructure contractors consolidate annual contracts around integrated admixture system suppliers rather than standalone material vendors.
Densified Silica Fume Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in densified silica fume supply. The upper tier captures premium specification flows through captive ferrosilicon off-gas recovery and hydroelectric power profiles. The specialist tier competes on regional densification capacity and distributor relationships. Three archetypes dominate: integrated metallurgical operators with upstream smelter control, formulation-anchored admixture system suppliers, and regional densification processors serving commodity-grade channels. Competitive moves concentrate on backward integration into ferroalloy recovery and technical service embedding with infrastructure contractors.
Among integrated metallurgical operators, Elkem exemplifies the hydroelectric-powered Nordic archetype with smelter-to-microsilica refining networks. Sika Corporation occupies a position within the formulation-anchored tier, bundling densified silica fume into proprietary admixture systems for performance-guaranteed procurement. BASF represents the R&D-intensive archetype, anchoring competitive position through dedicated centers optimizing pozzolanic reactivity in blended cement applications.
| Leading Market Players |
|---|
| BASF |
| Sika Corporation |
| Elkem |
| Kryton International |
| Norchem Inc |
| Xypex Australia |
| Chryso Inc |
| Wuhan Newreach Microsilica Co., Ltd |
| Scancem Materials (Singapore) Pte Ltd |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles at Nordic ferrosilicon smelters compress procurement windows for specification-grade densified silica fume, amplifying pricing power for hydroelectric-powered producers while spot-market buyers absorb volatility from electricity-cost swings in Chinese ferroalloy corridors.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated metallurgical operators and infrastructure contractors, locking in volume commitments against ferrosilicon price volatility while spot transactions serve polymer composite formulators with project-based demand spikes. Price differentiation hinges on carbon-accounted certification tiers and REACH registration status, with EU Green Deal compliance commanding substantial premiums over commodity-grade Mediterranean imports. Cost compression in standard admixture channels is intensifying because fly ash and slag substitution pressures cap silica fume penetration in non-critical concrete. Manufacturing units qualifying material for automotive battery enclosures exhibit the lowest price sensitivity, whereas mid-scale regional concrete producers buying through distributor networks drive hardest bargain negotiations.
Supply Chain Analysis
Thirty-to-forty-five day lead times from Norwegian and Icelandic smelter clusters to European tunnel consortia contrast sharply with extended ocean freight cycles from Chinese Yangtze River Delta processors to Indian west coast cement grinding facilities. Raw material flows draw from ferrosilicon furnace off-gas recovery, silicon metal production streams, and metallurgical-grade quartzite inputs. Single-source vulnerability concentrates in Nordic high-purity microsilica generation, where Rana and Mo i Rana industrial clusters anchor specification-grade densification capacity. Distribution runs through direct technical service embedding with megaproject contractors in Germany and Japan, supplemented by REACH-registered distributor networks serving mid-scale European concrete producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized concrete technologist cohorts are thinning across mature markets while Asia-Pacific training pipelines lag megaproject specification complexity, creating a capability scarcity that rewards suppliers embedding mix design expertise into material supply relationships.
For Market Incumbents: Secure backward integration into ferrosilicon off-gas recovery assets to insulate margin structures from silicon metal feedstock volatility, while expanding carbon-capture pilot qualifications at Norwegian smelters to capture EU taxonomy-aligned procurement premiums. Channel control through technical service bundling with German and Japanese infrastructure contractors defends position against formulation-anchored admixture system competitors. For New Entrants and Emerging Players: Differentiate on BIS-certified supply into Indian national highway and metro rail procurement, where pozzolanic certification expansion opens specification pathways for imported densified microsilica. Polymer composite flame-retardant formulations for automotive battery enclosures represent the most penetrable white-space segment, with tier-one OEM qualification trials offering a credible go-to-market angle through formulation partnership rather than standalone material supply. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement platform embedding and REACH registration barriers favor scaled integrated operators over fragmented regional processors. Target acquisition archetypes include Nordic ferrosilicon smelters with captive microsilica recovery and densification capacity, or Japanese admixture formulators with locked-in public works procurement relationships. The signal to watch is carbon-border adjustment mechanism enforcement intensity at EU ports, which would accelerate premium-tier procurement consolidation toward hydroelectric-sourced supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrosilicon Recovery | Captive off-gas streams at Norwegian smelters secure raw material economics against electricity price volatility. |
| Carbon-Capture Qualification Program | Emissions abatement pilots at Rana industrial clusters unlock EU Green Deal premium procurement tiers. |
| BIS Certification Expansion | Indian Bureau of Standards recognition opens national highway concrete procurement to imported specification-grade supply. |
| Technical Service Embedding | Mix design consulting bundled with silo-system delivery locks multi-year contracts with German infrastructure contractors. |
| Polymer Composite Formulation Partnership | Automotive OEM battery enclosure trials position densified silica fume as halogen-free flame-retardant filler. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, ferroalloy production disclosures, and infrastructure procurement specifications, with concrete technologists, ferrosilicon plant managers, and admixture procurement leads at transportation agencies providing operational validation. Cement additive formulators, polymer composite R&D directors, and REACH compliance officers contributed specification-grade demand perspectives. Bottom-up volume modeling triangulates against top-down macroeconomic drivers across the analysis window.
Segmentation dimensions modeled include product type tier, application intensity, end-user consolidation stage, and distribution channel structure, with regional regulatory clusters capturing EU Green Deal, REACH, EPA, and BIS compliance thresholds. CAGRs derive from historical trajectory analysis adjusted for policy inflection points and raw material cost cycle positioning. Forecast inputs incorporate ferrosilicon smelter capacity utilization trends and infrastructure resilience mandate adoption curves.
Decision-makers should treat outputs as directional under sustained infrastructure spending assumptions and stable ferroalloy electricity cost structures; material deviation in Chinese industrial policy or EU carbon-border enforcement would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Global Core Materials Market
Advanced Materials
Boron Nitride Market
Advanced Materials
Rigid Foam Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Global Diamond-Like Carbon (DLC) Market
Advanced Materials
Nomex Honeycomb Market
Advanced Materials
Transparent Wood Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Inorganic Non-Metallic Materials Market
Advanced Materials
Carbon Prepreg Market
Advanced Materials
Reinforcement Materials Market
Advanced Materials
Cubic Boron Nitrates Market
Advanced Materials
Thermal Spray Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
US Graphene Market