
 Glass Reinforced Vinyl Ester (GRV) Market | 2026-2036
Glass Reinforced Vinyl Ester (GRV) Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Reinforced Vinyl Ester (GRV) Market Insights
Chemical processing is realigning GRV procurement toward fire-resistant and chemical-resistant grades for aggressive acid service. INEOS Composites leverages integrated vinyl ester resin supply to capture downstream margin. Scott Bader Company Ltd. anchors its position through specialized corrosion formulations for European process industries. Swancor Holding Co., Ltd. dominates Asian marine and chemical infrastructure bids with localized compounding capabilities.
Glass reinforced vinyl ester comprises a thermoset matrix of vinyl ester resin reinforced with E-glass fiber, typically formulated with 25-35% glass content by weight and cured via peroxide initiation to achieve HDT above 120°C for structural load-bearing in corrosive environments. Pultrusion technology leads volume output for structural profiles and grating, while filament winding captures premium margin pools in pressure vessel and pipe fabrication. Chemical-resistant GRV commands the fastest expansion trajectory as refineries and chlor-alkali plants replace carbon steel with composite alternatives.
EPA New Source Performance Standards and OSHA Process Safety Management rules mandate corrosion-resistant materials in hazardous chemical service, directly elevating GRV specification rates in US process industries. REACH registration requirements in Europe restrict certain styrene-based formulations, pushing reformulation toward low-styrene or styrene-free vinyl ester chemistries. Stakeholders must monitor evolving F-Gas Regulation implications for composite manufacturing emissions and position supply chains for dual certification across EPA and ECHA compliance frameworks.
Market Dynamics
Corrosion-resistant material mandates from EPA and OSHA are forcing chemical processors to accelerate carbon steel replacement schedules, compressing specification cycles and concentrating procurement authority among engineering-procurement-construction firms with composite qualification expertise.
Growth Catalysts
- EPA New Source Performance Standards:Mandated corrosion-resistant materials in hazardous chemical service directly elevate GRV specification rates across US refineries and chlor-alkali facilities.
- Pultrusion technology maturation:Automated continuous fiber impregnation reduces structural profile production costs and enables high-volume grating supply for chemical plant infrastructure.
- US Gulf Coast petrochemical corridor:Concentrated capacity expansion in Texas and Louisiana generates localized demand density for fire-resistant and chemical-resistant GRV grades.
Market Restraints
- Styrene price volatility:Vinyl ester resin formulations remain exposed to petrochemical feedstock fluctuations, compressing compounder margins during crude oil spikes.
- E-glass fiber supply concentration:Chinese furnace capacity dominates global reinforcement supply, creating geographic single-source risk for non-integrated fabricators.
- REACH registration friction:European ECHA requirements restrict certain styrene-based chemistries, forcing costly reformulation toward low-styrene alternatives without performance equivalence guarantees.
Strategic Opportunities
- Offshore wind foundation jackets:Corrosion resistance requirements in North Sea installations open specification pathways for GRV structural components in marine renewable energy.
- Modular skid-mounted process units:Fabricators are specifying lightweight GRV piping and vessels to reduce transport costs and field assembly labor for remote chemical processing deployments.
- EU Green Deal industrial decarbonization incentives:Carbon footprint reduction credits for durable infrastructure materials accelerate composite adoption in European process industry retrofits.
Industry Challenges
- Peroxide handling certification gaps:Curing agent safety protocols require specialized technician training that outpaces vocational program updates in mature manufacturing regions.
- Legacy asset integration complexity:GRV pressure vessel retrofits demand custom flange geometries and metallurgy transition joints that extend engineering timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Reinforced Vinyl Ester (GRV) Market |
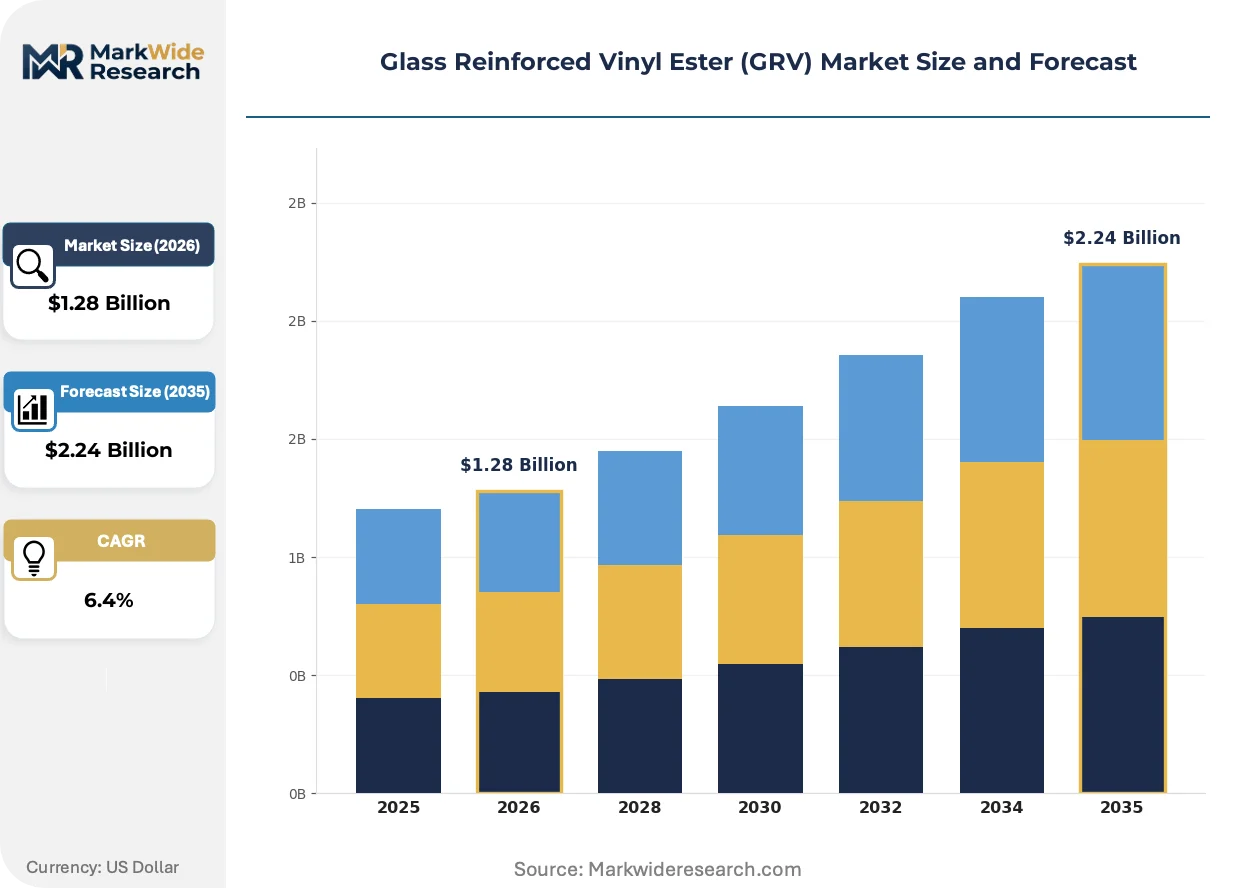
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard GRV, High-Performance GRV, Modified GRV, Fire-Resistant GRV, Chemical-Resistant GRV Application: Chemical Processing, Marine Craft, Electrical Insulation, Construction Panels, Corrosion Protection Technology: Hand Layup, Spray Up, Pultrusion, Filament Winding, Compression Molding End User Industry: Oil & Gas Operators, Aerospace Fabricators, Water Treatment Plants, Infrastructure Developers |
| Companies Covered | INEOS Composites, Polynt-Reichhold Group, Scott Bader Company Ltd., AOC, Interplastic Corporation, Hexion Inc., Ashland Global Holdings Inc., BASF SE, Swancor Holding Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Reinforced Vinyl Ester (GRV) Market Trends and Innovations
Material science advances and regulatory stringency are converging to reshape specification protocols across corrosive service applications, with performance validation moving from prescriptive standards to predictive lifecycle modeling.
Fire-retardant vinyl ester formulations incorporating ATH and intumescent additives are overtaking standard brominated systems in offshore platform specifications. North Sea operators now mandate IMO Level 3 fire ratings for structural composites, compressing approval cycles and disqualifying legacy resin systems without updated certification packages. This chemistry migration is enabling fabricators to bid integrated fire-structural solutions rather than segmented material supply.
REACH authorization procedures for styrene monomer are tightening occupational exposure thresholds across European chemical processing jurisdictions. ECHA's 2023-2025 substance evaluation wave forces reformulation investments toward styrene-free vinyl ester alternatives derived from methacrylate and dicyclopentadiene chemistries. German process engineering firms are accelerating qualification programs for low-emission resin systems to maintain EPC eligibility for EU public infrastructure tenders.
Engineering-procurement-construction firms are consolidating material qualification authority previously dispersed among owner-operators and specialty contractors. Major EPCs now maintain approved vendor lists with captive composite testing protocols, compressing market access for unqualified compounders. This buyer concentration is most pronounced in US Gulf Coast petrochemical construction, where Bechtel, Fluor, and McDermott qualification status determines specification viability regardless of resin performance metrics.
Glass Reinforced Vinyl Ester (GRV) Market Segmentation
GRV procurement patterns diverge sharply across performance tiers and fabrication methods. Specification authority concentrates among engineering-procurement-construction firms that maintain captive testing protocols for each segment category.
Product Type:
Customization intensity spans from commodity formulations to application-engineered systems requiring certified fire and chemical resistance ratings.
- Standard GRV:Base vinyl ester resin with E-glass reinforcement at 25-30% fiber content serves general structural applications. Demand concentrates in construction panels across US Gulf Coast industrial zones where cost sensitivity dominates over extreme service conditions.
- Chemical-Resistant GRV:Formulated with bisphenol-A or novolac vinyl ester backbones for aggressive acid and caustic service. Chlor-alkali plants in Texas and Louisiana specify this grade for brine handling equipment under EPA corrosion prevention mandates.
- High-Performance GRV:Hybrid resin systems with elevated HDT and tensile properties for structural load-bearing.
- Modified GRV:Elastomer-modified or toughened formulations for impact-critical applications.
- Fire-Resistant GRV:ATH-filled or intumescent systems meeting IMO Level 3 ratings for offshore platforms.
Most installed capacity flows through Standard GRV. Expansion is steepest in Chemical-Resistant GRV.
Application:
End-use differentiation tracks corrosion severity, fire exposure risk, and structural load requirements across industrial environments.
- Chemical Processing:Pressure vessels, piping, and storage tanks handling sulfuric acid, chlorine, and hydrocarbons. US refineries and European chlor-alkali facilities specify GRV for carbon steel replacement under tightening OSHA and REACH material mandates.
- Marine Craft:Hull structures, decks, and supercomponents for commercial vessels and offshore platforms. North Sea operators drive specification toward fire-structural integrated solutions with IMO certification.
- Corrosion Protection:Tank linings, ductwork, and fume exhaust systems for aggressive chemical environments.
- Electrical Insulation:Transformer housings and switchgear enclosures requiring dielectric stability.
- Construction Panels:Architectural cladding and industrial building facades.
Volume leadership sits with Chemical Processing. Marine Craft climbs fastest on offshore wind foundation demand.
Technology:
Fabrication method selection hinges on part geometry complexity, production volume, and fiber orientation requirements.
- Pultrusion:Automated continuous fiber impregnation through heated dies produces structural profiles and grating at high throughput. Chemical plant infrastructure in the US Gulf Coast corridor consumes pultruded sections for platforms, walkways, and support structures.
- Filament Winding:Computer-controlled fiber placement onto rotating mandrels yields optimized hoop and axial strength for pressure containment. Premium-margin pipe and vessel fabrication for chemical service relies on this precision method.
- Hand Layup:Manual fiber placement and roller consolidation for complex geometries and low-volume production.
- Spray Up:Chopped fiber and resin deposition for rapid coverage of large surface areas.
- Compression Molding:Matched-die forming of sheet molding compound for high-volume discrete parts.
Pultrusion commands the greatest installed equipment base. Filament winding captures the steepest margin expansion trajectory.
End User Industry:
Buyer sophistication and qualification requirements vary from owner-operator specifications to EPC-managed procurement.
- Oil & Gas Operators:Upstream and downstream facilities specify fire-resistant and chemical-resistant grades for platform decks, process vessels, and flare systems. US Gulf Coast petrochemical corridor concentration drives localized demand density for qualified fabricators.
- Water Treatment Plants:Municipal and industrial desalination facilities deploy GRV for chlorine contact chambers and brine handling.
- Aerospace Fabricators:Secondary structures and interior components requiring flame-smoke-toxicity compliance.
- Infrastructure Developers:Bridge decks, seawalls, and coastal protection systems.
Oil & Gas Operators channel the dominant procurement volume. Water Treatment Plants are expanding fastest on desalination capacity builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting GRV fabrication capacity toward jurisdictions with streamlined chemical safety approvals and lower peroxide handling compliance costs. Producers are relocating compounding operations to exploit gaps between EPA corrosion mandates and REACH registration burdens.
United States
EPA New Source Performance Standards and OSHA Process Safety Management rules mandate corrosion-resistant materials in hazardous chemical service. The US Gulf Coast petrochemical corridor concentrates demand density for fire-resistant and chemical-resistant GRV grades. Texas and Louisiana refineries specify bisphenol-A vinyl ester formulations for brine handling and acid service equipment replacement programs.
Germany
REACH authorization procedures for styrene monomer tighten occupational exposure thresholds across European chemical processing jurisdictions. ECHA's substance evaluation wave forces reformulation investments toward styrene-free vinyl ester alternatives. German process engineering firms in North Rhine-Westphalia accelerate qualification programs for low-emission resin systems to maintain EPC eligibility for EU public infrastructure tenders.
China
Domestic chlor-alkali capacity expansion drives specification of chemical-resistant GRV for chlorine contact chambers and brine handling infrastructure. National standards for corrosion-resistant materials in chemical process industries elevate composite adoption rates. Yangtze River Delta fabricators scale pultrusion output for chemical plant infrastructure serving the regional petrochemical cluster.
Saudi Arabia
Downstream petrochemical investments in the Eastern Province generate localized demand for high-performance GRV pressure vessels and piping systems. National industrial diversification programs prioritize corrosion-resistant materials for aggressive acid service. Jubail Industrial City operators specify filament-wound composite alternatives to carbon steel in sulfuric acid handling applications.
India
Desalination capacity builds in coastal states drive procurement of chemical-resistant GRV for chlorine contact chambers and brine handling equipment. Central Electricity Authority guidelines for durable materials in water treatment infrastructure support composite specification. Gujarat chemical processing zones deploy GRV storage tanks and ductwork under tightening state pollution control mandates.
Glass Reinforced Vinyl Ester (GRV) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated resin producers capturing downstream margin pools while independent fabricators compete on qualification speed. The vendor base concentrates around three tiers: multinational chemical conglomerates with captive vinyl ester supply, regional compounders with localized testing protocols, and project-specific fabricators bidding EPC-managed construction packages. Strategic differentiation hinges on backward integration into resin production, captive EPC qualification status, and geographic proximity to petrochemical construction corridors. Competitive moves center on M&A to secure resin supply agreements and capacity expansion adjacent to US Gulf Coast demand clusters.
Among integrated chemical producers, INEOS Composites and BASF SE exemplify the resin-backward archetype, leveraging in-house vinyl ester production to capture formulation margin and ensure supply security for qualified fabricators. Scott Bader Company Ltd. occupies a position within the specialized corrosion formulation tier, anchoring European process industry relationships through application-engineered systems. Swancor Holding Co., Ltd. sits within the Asia-Pacific regional champion archetype, compounding proximity advantages for marine and chemical infrastructure bids across East Asian construction markets.
| Leading Market Players |
|---|
| INEOS Composites |
| Polynt-Reichhold Group |
| Scott Bader Company Ltd. |
| AOC |
| Interplastic Corporation |
| Hexion Inc. |
| Ashland Global Holdings Inc. |
| BASF SE |
| Swancor Holding Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Vinyl ester resin feedstock costs cascade through three pricing tiers before reaching end-use fabricators, with styrene monomer volatility compressing compounder margins most acutely in standard-grade formulations serving US Gulf Coast construction panels.
Pricing Analysis
Distributor margins widen most dramatically between resin producers and qualified fabricators, with EPC-preferred vendors capturing 15-20 point markups over commodity compounders. Pricing stratifies across certified fire-structural, chemical-resistant, and standard construction grades, with IMO Level 3 certification commanding substantial premia over uncertified alternatives. Cost compression in standard GRV intensifies because Chinese E-glass oversupply erodes fiber reinforcement pricing power. Water treatment municipalities exhibit highest price sensitivity, while North Sea offshore operators prioritize performance over unit cost.
Supply Chain Analysis
Freight costs from Chinese furnace operations to US compounding facilities add 12-18% to landed E-glass reinforcement costs, incentivizing regional fiber production investments. Raw material sourcing draws from Saudi Arabian petrochemical complexes for vinyl ester monomers, Chinese furnace capacity for E-glass fiber, and German specialty chemical producers for peroxide curing agents. Single-source vulnerability concentrates in Chinese E-glass supply, where three furnace operators control 70% of global reinforcement output. Distribution runs through EPC-managed approved vendor lists that bypass traditional distribution channels for major petrochemical construction projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EPA corrosion mandates and REACH registration burdens creates geographic margin opportunities, with US Gulf Coast fabrication commanding 8-12% pricing premia over European equivalents despite identical resin formulations.
For Market Incumbents: Hedge styrene price exposure through backward integration into vinyl ester resin production or long-term offtake agreements with Saudi petrochemical suppliers. Secure captive EPC qualification status with Bechtel, Fluor, and McDermott to defend specification access against unqualified compounders. Prioritize fire-resistant grade certification investments as North Sea operators consolidate procurement around IMO Level 3 compliant vendors. For New Entrants and Emerging Players: EPA New Source Performance Standards in the United States open a window for specialized corrosion formulation suppliers to capture share in chlor-alkali and refinery replacement cycles. Target modular skid-mounted process unit fabricators in Texas and Louisiana, where lightweight GRV piping demand outpaces qualified supplier capacity. Pursue direct EPC qualification pathways rather than distributor relationships to bypass incumbent margin capture. For Investors and Strategic Acquirers: Consolidation pressure builds where EPC qualification requirements exceed capital availability for regional compounders. Five-to-ten year viability hinges on resin-backward integration and geographic proximity to US Gulf Coast demand clusters. Acquire regional fabricators with captive testing protocols and established EPC relationships rather than greenfield capacity builds. Monitor ECHA substance evaluation timelines for styrene authorization restrictions as inflection indicator for European asset repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Ester Resin Production | Captures formulation margin and insulates compounders from styrene feedstock volatility. |
| IMO Level 3 Fire Certification Investment | Unlocks North Sea offshore platform specifications and disqualifies uncertified competitors. |
| US Gulf Coast Capacity Expansion | Positions fabrication assets adjacent to Texas and Louisiana petrochemical construction corridors. |
| Styrene-Free Formulation Development | Ensures European market access as ECHA tightens REACH authorization thresholds. |
| EPC Qualification Partnership | Secures approved vendor status with engineering-procurement-construction firms managing major projects. |
Research Methodology
Multiple input streams — executive interviews with resin producers, procurement leads at downstream EPCs, and technical directors at compounding facilities — were reconciled against customs trade data, ACC industry reports, and SEC filings from integrated chemical producers. Primary fieldwork captured specification protocols, qualification timelines, and vendor selection criteria across US Gulf Coast, German, and Chinese chemical processing construction markets. Bottom-up volume estimates from fabrication capacity and utilization rates were cross-validated against top-down resin consumption figures reported by vinyl ester producers.
Historical shipment patterns were cross-referenced against expert panel assessments of regulatory implementation timelines and capacity expansion announcements. Segmentation modeling captured product type tiers, fabrication technology methods, end-use industry verticals, and regional production hub clusters. CAGRs were derived from trend-line extrapolation of replacement cycle acceleration and new build activity, with sensitivity testing against styrene price scenarios and E-glass supply disruption assumptions.
Revisions become necessary when EPA enforcement intensity shifts, ECHA authorization timelines accelerate, or Chinese E-glass furnace capacity rationalizes. Forecasts reflect documented assumptions about regulatory implementation speed, EPC qualification pipeline depth, and resin formulation substitution elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Magnetic Shielding Sheets Market
Advanced Materials
Global Aluminum Honeycomb Market
Advanced Materials
2D Materials Market
Advanced Materials
Global Core Materials Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
Artificial Marble Products Market
Advanced Materials
Advanced Composite Materials Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Wood Foam Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
Liquid Thermal Interface Materials Market
Advanced Materials
Global Advanced Phase Change Materials Market
Advanced Materials
North America Next Generation Anode Materials Market
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market