
 Expanded Thermoplastic Polyurethane Market | 2026-2036
Expanded Thermoplastic Polyurethane Market Size, Share, and Industry Trends Forecast 2026-2036
Expanded Thermoplastic Polyurethane Market Analytics
Modularization of expanded TPU supply into application-specific masterbatch kits is shifting buyer choice away from bulk resin purchasing. BASF SE leverages its polymer research infrastructure to sustain formulation leadership across automotive and footwear grades. Covestro AG anchors European supply through integrated MDI precursor production. Wanhua Chemical Group Co. Ltd. dominates Asia-Pacific volume with backward integration into adipic acid and BDO feedstocks.
Expanded thermoplastic polyurethane refers to a closed-cell or open-cell foam variant of TPU produced through physical or chemical blowing, typically achieving densities between 150 and 500 kg/m³ while retaining elastomeric recovery and abrasion resistance; manufacturers extrude or mold it for energy absorption, thermal insulation, and flexible sealing in transportation and consumer goods. Flexible foam leads product type revenue due to its penetration in footwear midsoles and automotive interior panels, while rigid foam claims faster growth trajectory driven by electronics packaging and lightweight structural inserts. Coatings command premium pricing in aerospace sealing applications where solvent-free application meets stringent VOC thresholds.
REACH registration requirements govern chemical composition disclosure for TPU precursors sold across EU member states, while EPA TSCA Section 5 notifications regulate new foam blowing agents in the United States. China's GB standards for indoor air quality and volatile emissions constrain adhesive-grade formulations deployed in electronics assembly. Stakeholders must monitor regulatory divergence on blowing agent chemistries as jurisdictions tighten phasedown schedules for hydrofluorocarbon-based expansion systems.
Market Dynamics
Automotive OEMs are consolidating expanded TPU sourcing around lightweighting mandates, compressing supplier qualification timelines while demanding simultaneous density reduction and crash-performance validation. This procurement pressure is restructuring formulation partnerships across the value chain.
Growth Catalysts
- EU F-Gas Regulation phasedown:The regulation's hydrofluorocarbon reduction schedule is accelerating chemical blowing agent substitution toward physical expansion systems, opening specification windows for low-GWP foam grades in German automotive sealing programs.
- Footwear midsole density targets:Running and basketball categories are specifying sub-200 kg/m³ expanded TPU for energy return, pulling volume through Chinese and Vietnamese contract manufacturers serving Nike and Adidas development centers.
- Electronics thermal management:5G base station and EV battery pack producers are specifying open-cell expanded TPU for compressible gap fillers, creating pull-through from semiconductor packaging clusters in Taiwan and South Korea.
Market Restraints
- MDI feedstock concentration:European supply chains remain exposed to Covestro and BASF integrated precursor positions, with spot MDI volatility transmitting directly to expanded TPU compound pricing within 60-90 day lags.
- REACH authorization bottlenecks:ECHA's substance evaluation backlog for novel chain extenders and catalysts is extending new formulation approval timelines to 18-24 months, freezing incremental product launches.
- Polypropylene substitution in automotive:Expanded polypropylene (EPP) is capturing lower-load interior applications where 15% density penalty is acceptable, compressing TPU addressable volume in door panels and headliners.
Strategic Opportunities
- India PLI scheme for footwear:The production-linked incentive program is attracting midsole molding capacity to Tamil Nadu and Uttar Pradesh, creating first-mover advantage for localized expanded TPU compound supply.
- Medical device cushioning:Patient positioning and prosthetic socket applications are specifying antimicrobial expanded TPU grades, opening premium pricing tiers outside traditional industrial volumes.
- Direct-to-moldmaster distribution:Compounders are bypassing distributor layers to supply certified masterbatch kits directly to automotive Tier 2 molders, capturing 8-12 point margin expansion.
Industry Challenges
- Multi-physics simulation talent:The intersection of foam expansion kinetics, crystallization behavior, and part warpage requires computational materials engineers scarce outside BASF and Covestro central R&D facilities.
- Automotive PPAP timeline compression:OEMs are collapsing production part approval process cycles from 18 months to 9 months while expanding test matrices to include VOC and fogging protocols, straining validation capacity.
- Legacy equipment retrofit costs:Physical blowing agent conversion requires extruder screw and barrel modifications exceeding $400K per line, freezing smaller compounders on chemical expansion systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expanded Thermoplastic Polyurethane Market |
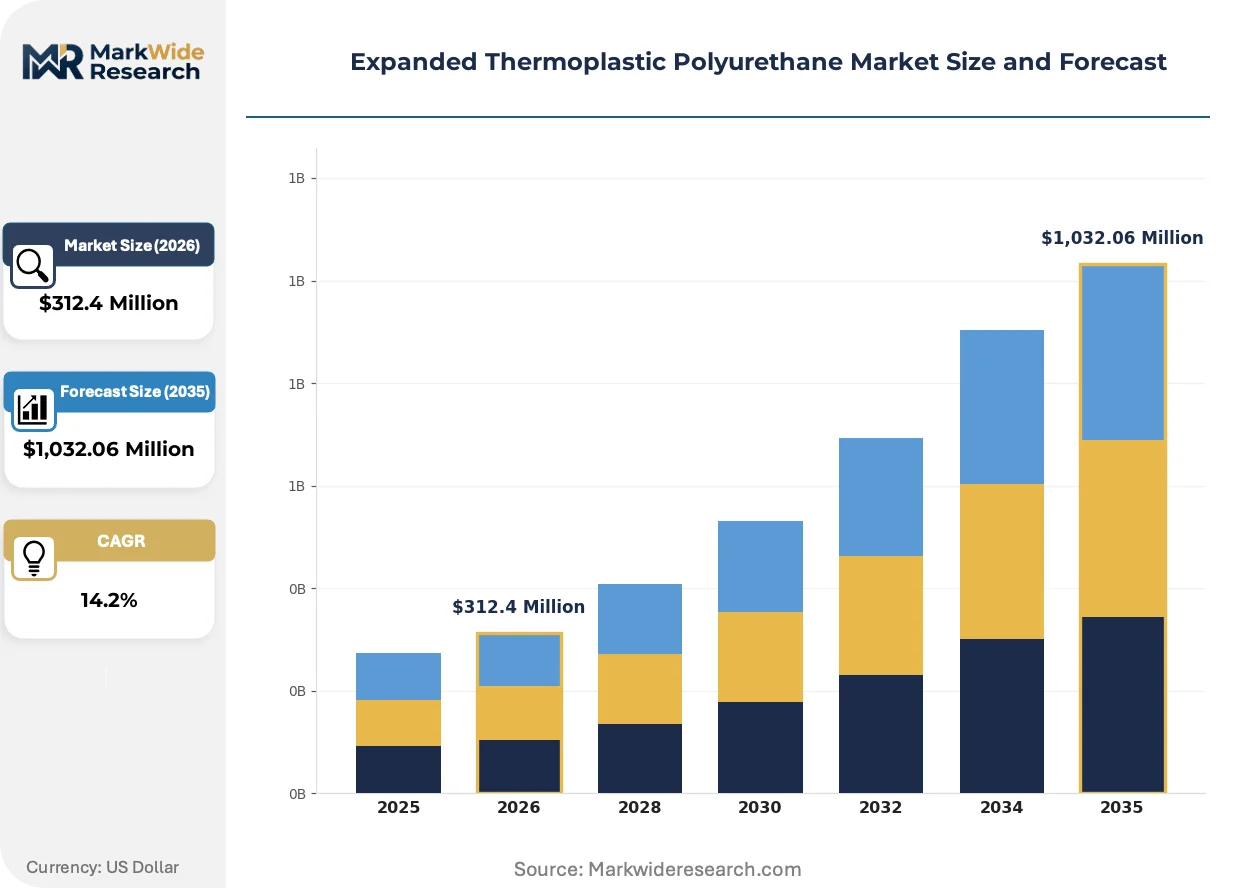
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,032.06 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Coatings, Adhesives End User: Aerospace, Automotive OEMs, Electronics, Footwear Application: Insulation, Cushioning, Sealing, Coating Form: Sheet, Block, Film, Granules |
| Companies Covered | Wanhua Chemical Group Co. Ltd., Avient Corp., BASF SE, Epaflex Polyurethanes Spa, COIM Group, Covestro AG, Huntsman International LLC, American Polyfilm Inc., The Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expanded Thermoplastic Polyurethane Market Evolving Landscape
Formulation science is converging with process control engineering to enable density gradients and functional surface layers within single expanded TPU components, collapsing multi-material assemblies into monolithic parts.
Supercritical CO₂ physical foaming is integrating into continuous extrusion lines for sheet and profile production, replacing batch autoclave methods. Automotive interior suppliers in Germany and China are adopting the technology to achieve 40% density reduction without sacrificing tensile recovery. The process is integrating quality control systems that adjust pressure-temperature profiles in real-time, compressing scrap rates and enabling just-in-sequence supply to seat frame assembly lines.
REACH SVHC candidate list expansion is forcing disclosure of isocyanate residual content above 0.1% w/w in finished foam articles, compelling reformulation of hot-cure molding systems. ECHA's 2023-2024 updates targeting aromatic amine derivatives are most acutely affecting adhesive-grade expanded TPU used in electronics assembly. Suppliers are responding with aliphatic isocyanate-based pre-polymers that bypass SVHC triggers while maintaining hydrolysis resistance for outdoor applications.
Footwear brands are consolidating expanded TPU midsole sourcing around vertically integrated compounders capable of delivering color-matched, density-graded pellets direct to injection molding cells. The specification power has shifted from resin traders to molders with in-house colorimetry and rheology labs. This concentration is most visible in Chinese manufacturing clusters serving Anta and Li-Ning, where three compounders now supply 70% of premium running shoe foam volume.
Expanded Thermoplastic Polyurethane Market Segmentation
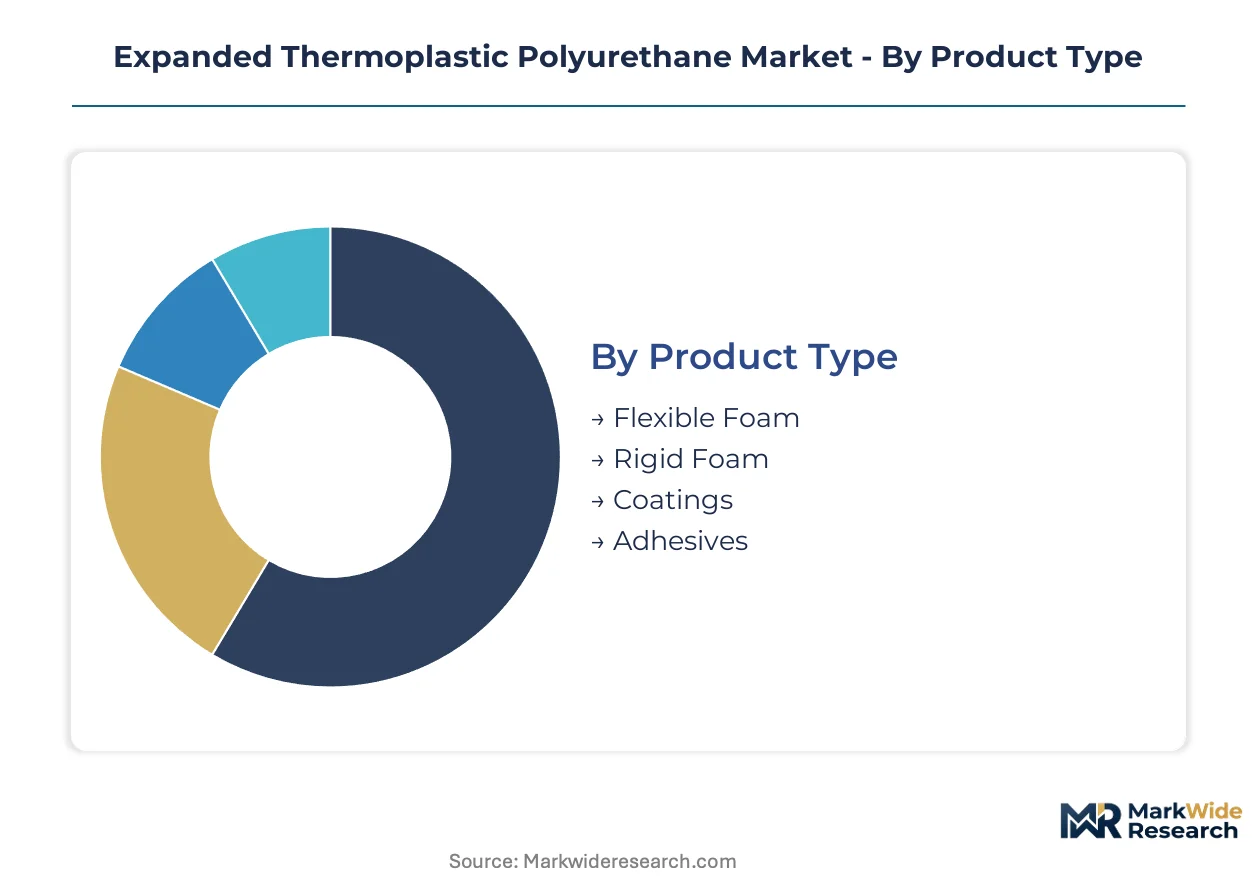
Segmentation in expanded TPU reveals how formulation chemistry and processing method align with end-use performance thresholds. Buyers select grades based on density targets, cell structure, and regulatory compliance rather than commodity resin pricing alone.
Product Type:
Material replacement cycles in automotive seating and athletic footwear are accelerating specification turnover toward lighter, lower-GWP foam grades.
- Flexible Foam:Open-cell or closed-cell variants achieve 150-300 kg/m³ densities while retaining elastomeric recovery. Running shoe midsole contracts in China and Vietnam specify sub-200 kg/m³ grades for energy return, pulling volume through vertically integrated compounders.
- Rigid Foam:Higher crosslink density delivers dimensional stability for structural inserts and electronics packaging. 5G base station producers in Taiwan specify rigid grades for compressible thermal gap fillers, creating fastest-growing demand trajectory among product types.
- Coatings:Solvent-free spray systems command premium positioning in aerospace sealing where VOC thresholds are mandatory.
- Adhesives:Reactive hot-melt formulations bond dissimilar substrates in automotive interior assembly.
Volume placements concentrate in flexible foam; the faster expansion belongs to rigid foam.
End User:
Customer procurement maturity varies sharply, with automotive OEMs imposing the most stringent qualification protocols while footwear brands prioritize speed-to-market.
- Automotive OEMs:Seat cushion and door seal applications specify crash-performance validated grades with 60-90 day MDI price pass-through mechanisms. German OEMs lead adoption of supercritical CO₂ foamed sheet for 40% density reduction.
- Footwear:Midsole molding cells demand color-matched, density-graded pellets with compressed development cycles. Chinese manufacturing clusters serving domestic athletic brands now consolidate around three compounders for 70% of premium running shoe foam volume.
- Electronics:EV battery pack and semiconductor packaging applications specify open-cell grades for thermal management.
- Aerospace:Sealing and insulation applications require solvent-free coating systems meeting stringent emissions protocols.
Automotive OEMs dominate volume commitment; footwear brands are gaining share fastest through direct-to-molder supply consolidation.
Application:
Functional requirements dictate form selection, with thermal and mechanical performance specifications narrowing supplier pools.
- Cushioning:Energy absorption for seating and protective gear relies on flexible foam cell structure tuned for compression set resistance. Patient positioning applications in medical devices are specifying antimicrobial grades, opening premium tiers outside industrial volumes.
- Insulation:Thermal barrier applications in transportation and construction favor rigid foam with closed-cell morphology. EU F-Gas Regulation phasedown is accelerating substitution toward low-GWP expansion systems in German automotive programs.
- Sealing:Compressible gaskets and gap fillers require controlled cell size distribution for consistent closure force.
- Coating:Protective layers applied directly to substrate eliminate multi-material assemblies.
Cushioning commands the largest volume position; insulation applications are climbing the fastest on thermal management demand from electrification.
Form:
Processing equipment compatibility and part geometry determine form factor selection across the value chain.
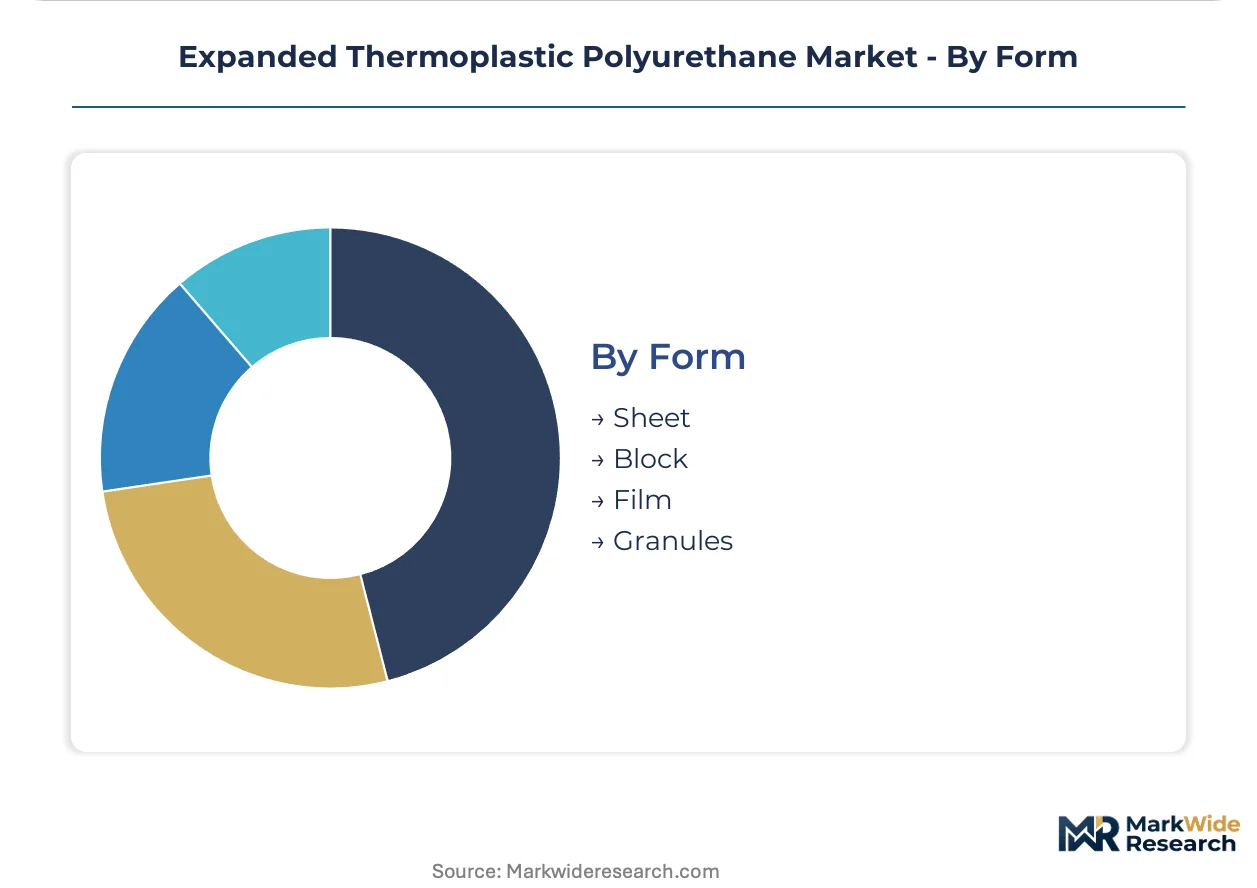
- Sheet:Continuous extrusion output feeds thermoforming and die-cutting operations for automotive interior panels. Supercritical CO₂ physical foaming integration is replacing batch autoclave methods in German and Chinese production lines.
- Granules:Pelletized compound enables direct injection molding with color and density customization at the press. Footwear molders with in-house colorimetry labs now specify granule supply with compressed distributor margins.
- Block:Bun stock for slabstock conversion and CNC machining of custom shapes.
- Film:Thin-gauge rolls for lamination and surface protection applications.
Sheet form holds the broadest manufacturing footprint; granules are gaining share fastest through footwear supply chain consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in China and Germany while consumption concentrates in automotive and footwear manufacturing centers across three continents. The geographic split creates distinct regulatory exposure profiles for compounders serving export markets versus domestic supply chains.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria specify supercritical CO₂ foamed expanded TPU for seat cushion applications under lightweighting mandates. EU F-Gas Regulation compliance deadlines are accelerating chemical blowing agent substitution toward physical expansion systems. Covestro AG anchors precursor supply through integrated MDI production in Leverkusen and Dormagen.
China
Footwear manufacturing clusters in Fujian and Guangdong provinces drive bulk procurement of sub-200 kg/m³ flexible foam grades for domestic athletic brands. GB standards for indoor air quality constrain adhesive-grade formulations deployed in electronics assembly. Wanhua Chemical Group Co. Ltd. dominates Asia-Pacific volume with backward integration into adipic acid and BDO feedstocks in Yantai and Ningbo.
United States
EPA TSCA Section 5 notifications regulate novel foam blowing agents entering commercial production for automotive sealing programs. Electronics packaging demand in Texas and California pulls open-cell grades for thermal management in semiconductor facilities. Huntsman International LLC maintains formulation development operations in Michigan and Texas serving Tier 1 automotive suppliers.
India
The PLI scheme for footwear is attracting midsole molding capacity to Tamil Nadu and Uttar Pradesh, creating localized demand for expanded TPU compound supply. BIS certification requirements for polymer imports are extending qualification timelines for foreign compounders. Domestic manufacturing clusters in Chennai and Kanpur are consolidating around three vertically integrated suppliers for premium running shoe production.
South Korea
5G base station and EV battery pack producers specify rigid expanded TPU for compressible thermal gap fillers. MFDS oversight of medical device materials is opening antimicrobial grade specifications for patient positioning applications. Seoul and Busan manufacturing corridors are integrating supercritical foaming lines to serve electronics export markets.
Expanded Thermoplastic Polyurethane Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive precursor supply. Three to four diversified materials groups control formulation science and polymer research infrastructure, while mid-scale compounders specialize in color-matched, density-graded pellets for footwear direct-to-molder supply. Strategic moves center on backward integration into MDI and polyol feedstocks, plus bypass of distributor layers to capture margin expansion in automotive Tier 2 channels.
Among European-based integrated producers, BASF SE and Covestro AG exemplify the precursor-anchored archetype with polymer research infrastructure sustaining formulation leadership across automotive and footwear grades. Wanhua Chemical Group Co. Ltd. occupies the Asia-Pacific volume position with feedstock integration into adipic acid and BDO. Avient Corp. represents the compounder-specialist model with direct-to-molder distribution capabilities in North American footwear and automotive channels.
| Leading Market Players |
|---|
| Wanhua Chemical Group Co. Ltd. |
| Avient Corp. |
| BASF SE |
| Epaflex Polyurethanes Spa |
| COIM Group |
| Covestro AG |
| Huntsman International LLC |
| American Polyfilm Inc. |
| The Lubrizol Corporation |
| Others |
Value Network & Pricing Analysis
Automotive Tier 1 seating suppliers and footwear OEM procurement teams command contract structures indexed to MDI spot volatility with 60-90 day price pass-through mechanisms, compressing compounder margins while rewarding backward-integrated producers with feedstock cost stability.
Pricing Analysis
Margin tightening in flexible foam grades reflects footwear brand consolidation around three vertically integrated compounders in Chinese manufacturing clusters. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified coating systems from automotive interior grades and commodity footwear pellets. Cost-down pressure on automotive sealing formulations accelerates because OEMs are collapsing supplier qualification timelines while expanding VOC test matrices. Footwear molders with in-house colorimetry labs exhibit lowest price sensitivity; automotive Tier 2 processors face highest pressure from polypropylene substitution threats.
Supply Chain Analysis
REACH SVHC disclosure requirements and automotive PPAP validation protocols gate qualified supply access, extending onboarding timelines for foreign compounders. Manufacturing concentrates in Germany, China, and the United States, with Covestro and BASF anchoring European precursor supply and Wanhua Chemical dominating Asia-Pacific volume. Raw material flows draw from MDI, adipic acid, and BDO feedstocks with spot volatility transmitting directly to compound pricing. Single-source vulnerability persists in European MDI supply where integrated producers control precursor access. Distribution runs through direct-to-moldmaster channels in automotive Tier 2 supply and vertically integrated compounders in footwear.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The expanded thermoplastic polyurethane market sits in a technology-transition phase as supercritical CO₂ physical foaming displaces legacy chemical blowing agent systems constrained by EU F-Gas Regulation phasedown schedules.
For Market Incumbents: Anchor formulation leadership through captive MDI precursor supply and polymer research infrastructure sustaining automotive crash-performance validation capabilities. Defend against polypropylene substitution in lower-load interior applications by accelerating supercritical foaming line conversions that achieve 40% density reduction without tensile recovery sacrifice. Prioritize certification investment in antimicrobial grades for medical device cushioning to capture premium pricing tiers outside commoditized footwear volume.
For New Entrants and Emerging Players: Capture first-mover positioning in India PLI scheme footwear clusters where localized compound supply lacks qualified domestic producers. Target rigid foam specifications for 5G base station thermal gap fillers in South Korean electronics corridors where demand outpaces specialized supply. Deploy direct-to-molder distribution with color-matched, density-graded pellet kits to bypass entrenched distributor layers and compress margin capture timelines.
For Investors and Strategic Acquirers: The window for entry favors compounder-specialist archetypes with direct-to-molder capabilities and footwear colorimetry infrastructure in Asian manufacturing clusters. Long-term viability rests on supercritical foaming technology access and REACH-compliant aliphatic isocyanate formulation portfolios. Watch ECHA substance evaluation backlog resolution as inflection indicator for new formulation launch velocity and incremental product pipeline activation.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO₂ Foaming Line Conversion | Enables 40% density reduction for German automotive seating programs under lightweighting mandates. |
| Backward Integration into MDI Precursors | Insulates margin position from spot volatility transmitting through 60-90 day contract lags. |
| Antimicrobial Grade Certification | Opens premium pricing tiers in medical device cushioning beyond commoditized footwear volume. |
| Direct-to-Moldmaster Distribution Bypass | Captures 8-12 point margin expansion by eliminating distributor layers in automotive Tier 2 supply. |
| India PLI Scheme Localized Supply | Establishes compound production footprint in Tamil Nadu and Uttar Pradesh footwear clusters. |
Research Methodology
Multi-period observation of MDI spot price trajectories, REACH SVHC candidate list expansions, and automotive OEM lightweighting procurement shifts anchored the trend analysis, supplemented by interviews with polymer R&D directors, footwear procurement leads, automotive Tier 1 supplier quality engineers, and distribution channel partners. Secondary validation drew from ECHA substance evaluation databases, EU F-Gas Regulation implementation schedules, SEC 10-K chemical segment disclosures, and customs trade flow records. Bottom-up volume modeling triangulated against top-down macroeconomic demand indicators.
Segment-weighting across product type, end user, application, and form dimensions structured the analytical framework, with density grade and regional regulatory cluster as additional industry-specific variables. CAGRs were derived through regression analysis of historical volume trajectories against projected demand drivers throughout the forecast period. Key inputs included automotive production schedules, footwear brand development cycle compression rates, and electronics thermal management specification adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA authorization timeline delays, MDI feedstock supply disruptions, and polypropylene substitution acceleration in automotive interior applications. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement intensity or breakthrough in alternative physical blowing agent chemistries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
Global Ethylene Vinyl Acetate Resins Market
Polymers & Resins
Resin Dispersion Market
Polymers & Resins
US Polymethyl Methacrylate Market
Polymers & Resins
South America Polycarbonate (PC) Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
US Polycarbonate Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Polybutylene Succinate (PBS) Market
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Global Water-Based Resins Market