
 Automotive IC Market | 2026-2036
Automotive IC Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive IC Market Intelligence
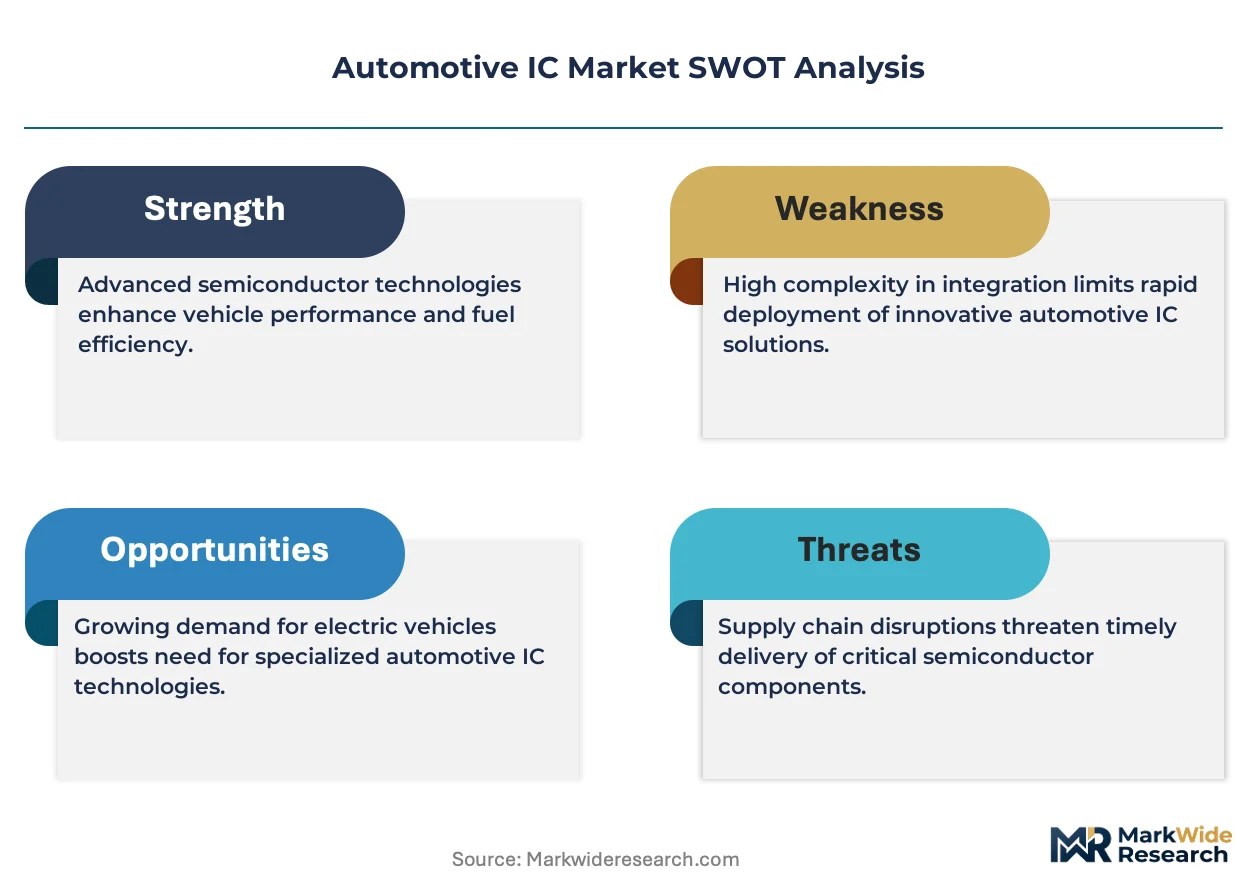
Custom logic design for application-specific automotive functions is fragmenting the traditional microcontroller margin pool. NXP Semiconductors leverages its leadership in secure connectivity and in-vehicle networking to capture this strategic shift. Infineon Technologies sustains its dominant market position through a deep focus on power semiconductors and sensor systems for electric vehicles. Texas Instruments competes with its broad portfolio of analog and embedded processing products, targeting diverse automotive applications from infotainment to powertrain.
Automotive integrated circuits are semiconductor devices specifically engineered to operate reliably in the harsh environments of vehicles, withstanding extreme temperatures, shock, and vibration. These ICs perform critical functions in real-time control, high-fidelity sensing, and rapid data processing within all modern automotive electronic systems. Advanced driver assistance systems (ADAS) applications represent the fastest-growing segment, demanding complex microcontrollers and specialized sensors. Within product types, power management ICs are critical for managing the intricate energy requirements of electric and hybrid vehicle powertrains.
Automotive safety integrity levels (ASIL) defined by the ISO 26262 standard dictate stringent design, verification, and validation requirements for safety-critical ICs. Concurrently, emissions mandates from the EPA in the United States and vehicle safety rules from Germany's KBA directly influence powertrain and chassis control IC development. Supplier success will depend on navigating the complex qualification cycles and functional safety certifications required by global automotive OEMs and their Tier-1 partners.
Market Dynamics
The architectural evolution toward zonal and domain controllers is the central force redefining the automotive IC market. This shift away from a distributed model of one hundred or more individual ECUs per vehicle fundamentally alters the type, complexity, and value of semiconductors required, concentrating processing power into fewer, more powerful chips.
Growth Catalysts
- Silicon Carbide Adoption:The transition to high-voltage electric vehicle powertrains drives demand for silicon carbide (SiC) power ICs, which offer superior thermal performance and energy efficiency compared to traditional silicon.
- Emissions and Safety Mandates:Regulations from bodies like the US EPA and Germany's KBA compel automakers to adopt more sophisticated powertrain and chassis control ICs to meet stringent fuel economy, emissions, and vehicle stability standards.
- ADAS Feature Proliferation:The rapid mainstreaming of advanced driver assistance systems (ADAS) in mass-market vehicles, beyond the luxury segment, creates sustained demand for a wide array of camera, radar, and LiDAR sensor ICs and their associated processors.
Market Restraints
- Extreme Qualification Cycles:The rigorous, multi-year qualification and validation processes required to meet automotive-grade reliability standards, such as AEC-Q100, significantly slow the introduction of cutting-edge semiconductor technologies into vehicles.
- Supply Chain Concentration:The geographic concentration of leading-edge semiconductor fabrication, particularly in Taiwan and South Korea, exposes the global automotive industry to significant supply disruption risks from geopolitical events or natural disasters.
- High Development Costs:Designing ICs to comply with the ISO 26262 functional safety standard, especially for higher Automotive Safety Integrity Levels (ASIL C/D), requires substantial investment in specialized design, verification, and validation resources.
Strategic Opportunities
- In-Cabin Sensing Systems:The development of ICs for driver and occupant monitoring systems, driven by Euro NCAP safety ratings and OEM interest in user experience, represents a significant greenfield application area for sensor and AI inference chips.
- V2X Connectivity:Government initiatives and pilot programs in the United States and China promoting vehicle-to-everything (V2X) communication create a new market for secure, low-latency wireless ICs to enable cooperative safety applications.
- AI and MCU Convergence:The integration of dedicated neural processing units (NPUs) with traditional microcontroller functionalities on a single SoC opens opportunities for cost-effective, high-performance solutions in next-generation ADAS and digital cockpit applications.
Industry Challenges
- Functional Safety Talent Gap:A persistent shortage of engineers with dual expertise in both advanced semiconductor design and the nuances of automotive functional safety standards like ISO 26262 hinders development capacity across the industry.
- Legacy System Integration:Integrating advanced, high-speed SoCs and networking ICs with existing legacy vehicle architectures and communication protocols like CAN and LIN presents significant software and hardware compatibility challenges for OEMs and Tier-1 suppliers.
- Software Complexity Management:As hardware consolidates into powerful domain controllers, the corresponding software complexity explodes, creating immense challenges in validation, verification, and ensuring real-time performance for safety-critical functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive IC Market |
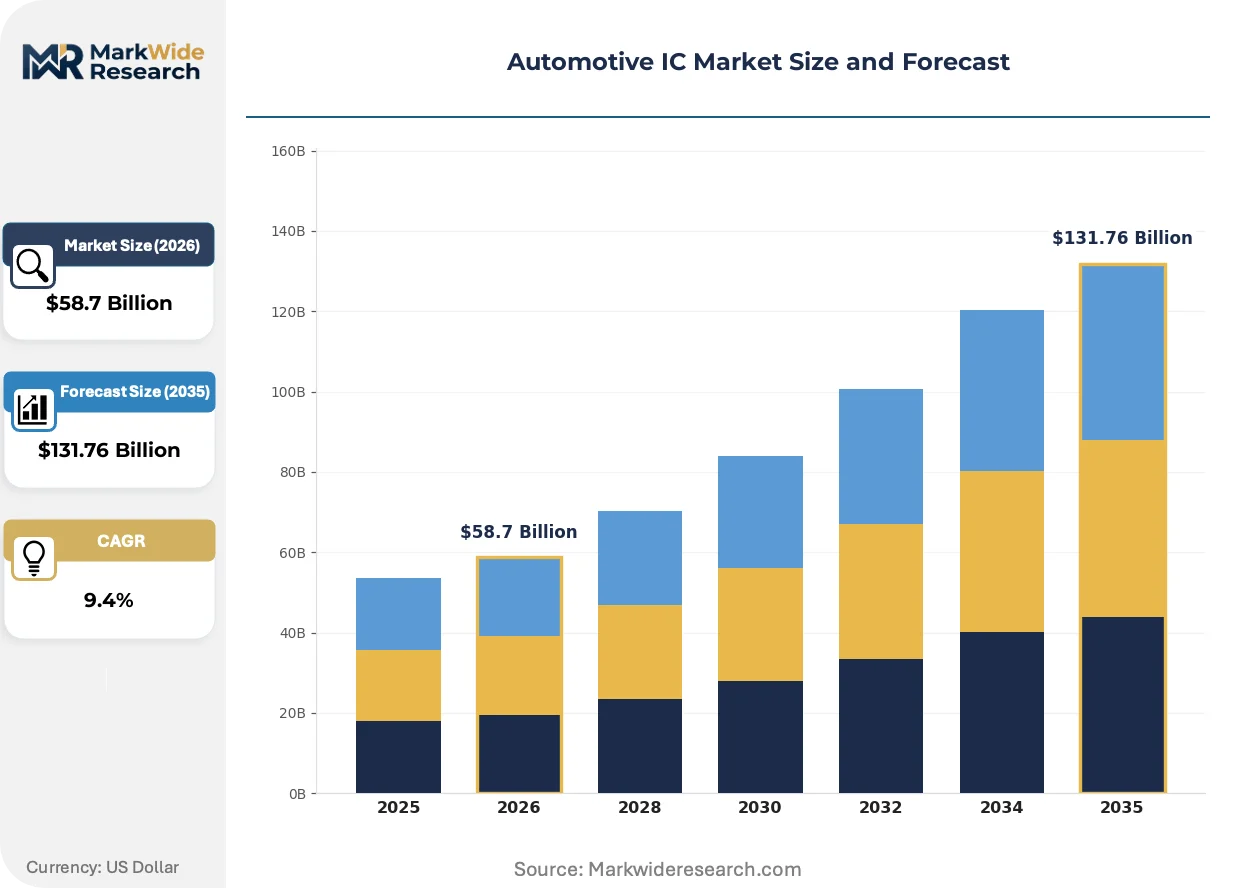
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Power Management ICs, Sensors, Transceivers Technology: Analog, Digital, Mixed-Signal, RF End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Infotainment Systems, Advanced Driver Assistance Systems, Powertrain, Body Electronics |
| Companies Covered | Infineon Technologies, NXP Semiconductors, STMicroelectronics, Texas Instruments, Renesas Electronics, ON Semiconductor, Analog Devices, Robert Bosch, Qualcomm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive IC Market Strategic Shifts & Innovations
The transition toward the software-defined vehicle is fundamentally reshaping the underlying hardware requirements. This trend prioritizes centralized, high-performance computing and secure connectivity, moving value from discrete hardware components to integrated, updatable software functions running on powerful SoCs.
System-on-Chip (SoC) platforms with integrated hardware virtualization support are designed to consolidate tasks previously handled by numerous discrete ECUs. Automakers and Tier-1 suppliers are rapidly adopting these SoCs for new zonal electronic architectures, especially in EV and premium vehicle lines. This consolidation is virtualizing dozens of separate hardware boxes into software-defined functions running on a single, powerful processor, drastically reducing physical complexity and weight.
European Union regulations, specifically the UNECE WP.29 R155 cybersecurity standard, now mandate verifiable security measures for all new vehicle types. This directive compels automakers to implement end-to-end security, from component design through to over-the-air updates in the field. Consequently, the in-vehicle networking and telematics control unit segments now require ICs featuring dedicated hardware security modules (HSMs) and cryptographic accelerators to meet compliance.
Automotive OEMs are increasingly altering their sourcing strategies to engage directly with semiconductor firms for the co-development of custom silicon. This model disrupts the traditional tiered supply chain where Tier-1 suppliers managed component selection and integration. The pattern is most visible in the United States and China for the development of proprietary SoCs that power autonomous driving, ADAS, and unique digital cockpit experiences.
Automotive IC Market Segmentation
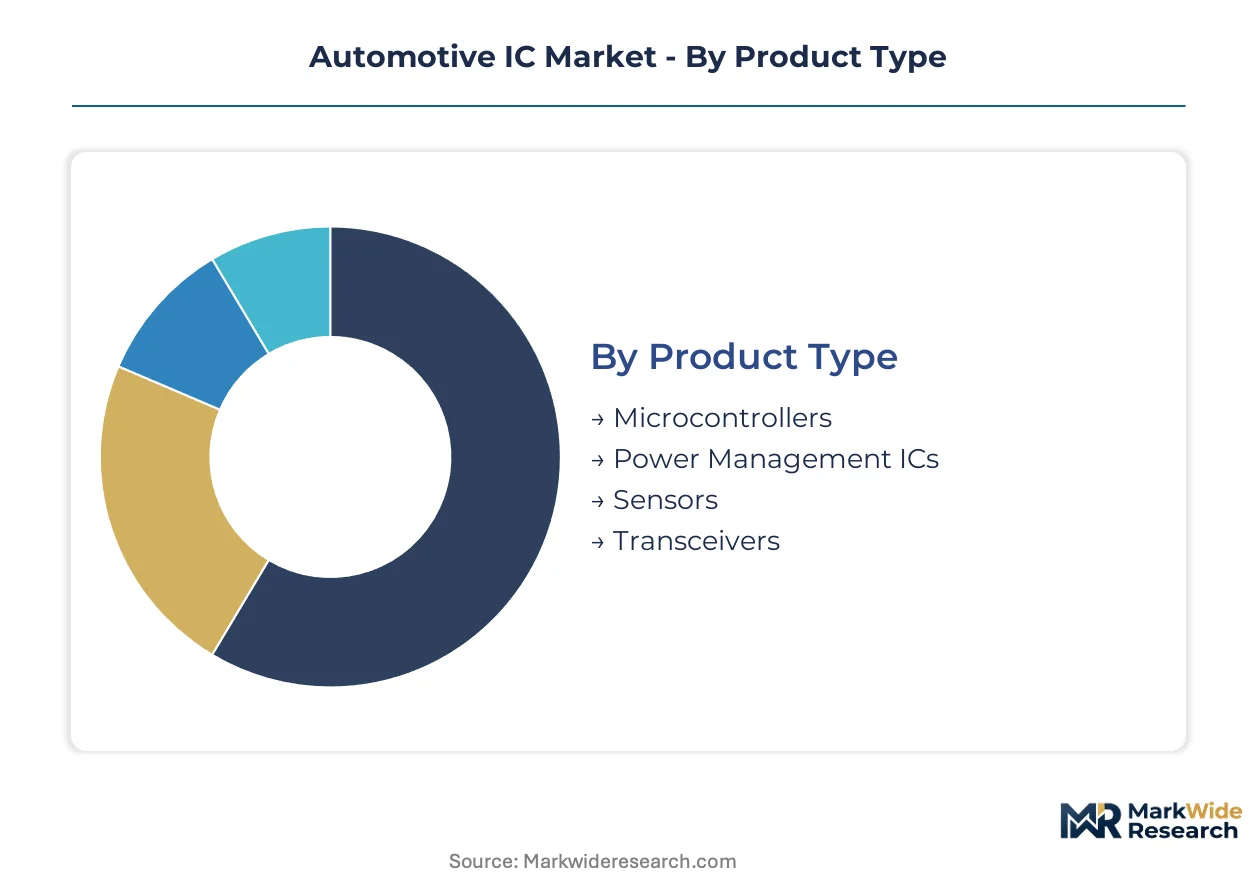
The Automotive IC market segmentation provides granular insights into the diverse technological and application landscapes driving semiconductor demand in vehicles. Understanding these distinct segments helps manufacturers align product development with evolving automotive architectures and specific end-user requirements.
Product Type:
The maturity spectrum for product types shows Microcontrollers as a foundational, mature segment, while Power Management ICs are experiencing significant innovation driven by electrification.
- Microcontrollers:These programmable devices execute control functions, process data from sensors, and manage communication protocols within various vehicle systems. Demand remains high for advanced 32-bit and 64-bit MCUs in ADAS and digital cockpit applications across European and North American markets.
- Power Management ICs:These semiconductors regulate and distribute electrical power efficiently throughout the vehicle, essential for battery life and system stability. The transition to high-voltage electric vehicle powertrains in China and Germany drives substantial demand for robust PMICs.
- Sensors:Devices converting physical phenomena like pressure, temperature, or light into electrical signals for vehicle control and safety systems.
- Transceivers:Integrated circuits facilitating data transmission and reception within in-vehicle networks and external communication systems.
Microcontrollers handle the majority of throughput; Power Management ICs are the fastest mover on share.
Technology:
Application-driven demand dictates the prominence of various IC technologies, with digital and mixed-signal solutions increasingly converging for complex automotive functions.
- Digital:These ICs process discrete signals, handling complex computations and logic operations for advanced control units and infotainment systems. High-performance digital ICs are crucial for autonomous driving platforms in the United States and Japan.
- Mixed-Signal:These integrated circuits combine both analog and digital functionalities on a single chip, enabling efficient interfacing between real-world analog signals and digital processing. The proliferation of sensor fusion and complex ADAS modules in Germany and South Korea drives demand for advanced mixed-signal ICs.
- Analog:Integrated circuits that process continuous electrical signals, vital for power management, signal conditioning, and interface functions.
- RF:Radio frequency integrated circuits enable wireless communication functionalities like V2X, keyless entry, and telematics systems.
Digital technology dominates advanced processing needs; Mixed-Signal solutions are expanding most quickly for integrated functions.
End User:
Customer type dictates procurement patterns, with Tier-1 suppliers historically acting as the primary interface, though OEMs are increasingly engaging directly with semiconductor firms.
- OEMs:Original Equipment Manufacturers directly integrate automotive ICs into their vehicle designs and increasingly engage in co-development of custom silicon. Automakers in the United States and China are leading this shift for proprietary ADAS and infotainment systems.
- Tier-1 Suppliers:These companies design and manufacture complete automotive subsystems, procuring ICs from semiconductor vendors for integration into their modules. Major Tier-1s in Germany and Japan drive significant volume demand for standard and custom ICs.
- Aftermarket Providers:Companies supplying components and systems for vehicles after their initial sale, including replacement parts and upgrade kits.
- Vehicle Assemblers:Entities primarily focused on the final assembly of vehicles from components supplied by OEMs and Tier-1s.
Tier-1 Suppliers represent the largest volume purchasers; OEMs are increasingly driving custom silicon development.
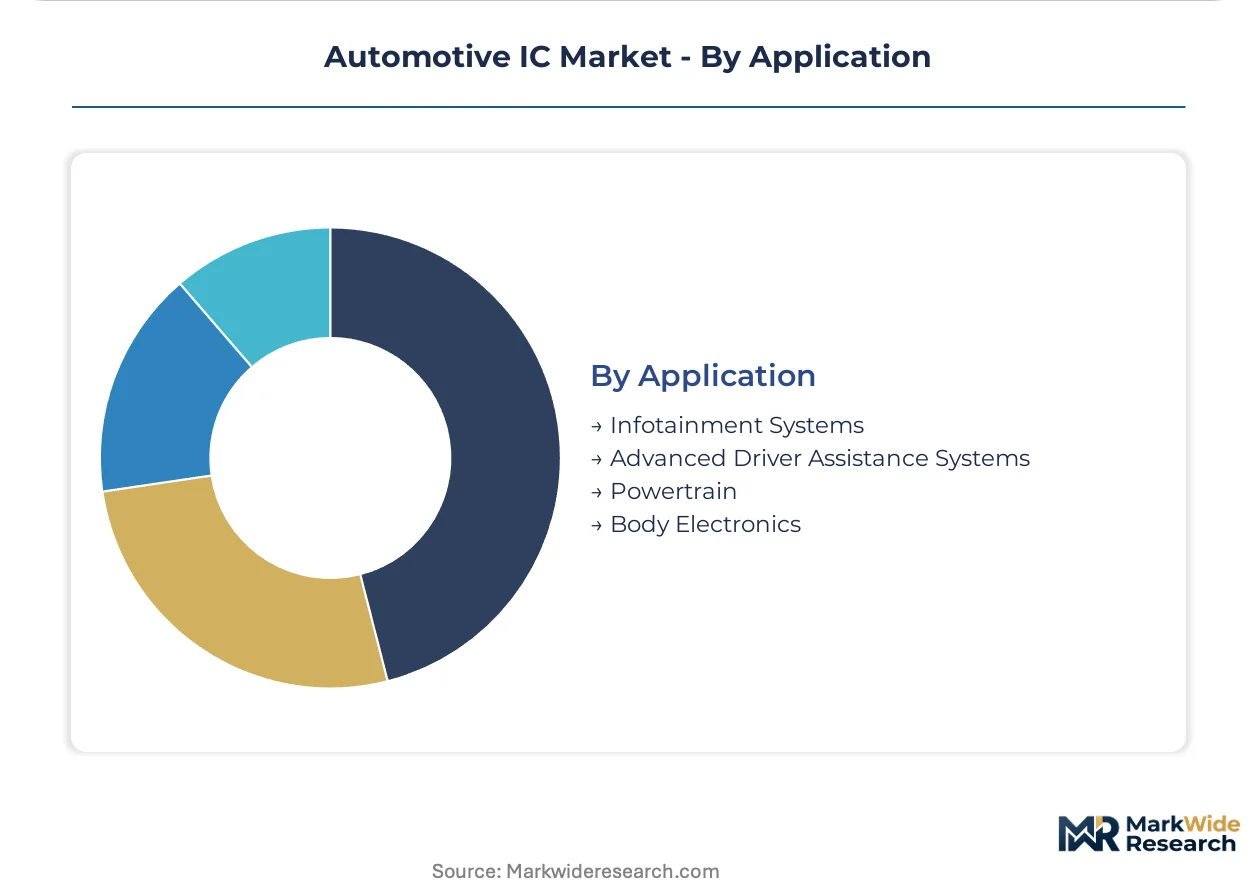
Application:
Margin profiles vary significantly across applications, with safety-critical and high-performance segments commanding higher value due to stringent functional safety requirements.
- Advanced Driver Assistance Systems:This segment includes ICs for camera, radar, LiDAR, and ultrasonic sensors, along with their associated processing units for features like adaptive cruise control and lane keeping. The rapid mainstreaming of ADAS features in Europe and North America drives substantial IC demand.
- Powertrain:ICs designed for engine control units, transmission control units, and electric vehicle inverters, focusing on efficiency, emissions reduction, and power delivery. Regulations from the US EPA and Germany's KBA compel innovation in powertrain ICs.
- Infotainment Systems:Integrated circuits powering in-car entertainment, navigation, and connectivity features, including display controllers, audio processors, and communication modules.
- Body Electronics:ICs managing comfort and convenience features such as lighting control, window operation, climate control, and passive safety systems.
Advanced Driver Assistance Systems applications command premium pricing; Powertrain ICs maintain consistent demand due to regulatory compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Automotive IC Market exhibits diverse consumption patterns across key automotive production regions, reflecting varying priorities in electrification, ADAS adoption, and regulatory compliance. United States demand centers on high-performance digital ICs for autonomous driving, while Chinese demand gravitates toward power management ICs for electric vehicles.
United States
Demand for automotive ICs in the United States is driven by the rapid proliferation of advanced driver assistance systems and the development of autonomous driving platforms. EPA emissions mandates influence powertrain IC development, pushing for greater efficiency and reduced environmental impact. Silicon Valley and Detroit represent critical hubs for IC design and automotive integration, fostering co-development initiatives between tech firms and OEMs.
Germany
Germany's automotive IC market is characterized by strong demand for mixed-signal ICs, particularly for sensor fusion in ADAS applications and robust power management ICs for electric vehicle powertrains. KBA vehicle safety rules directly influence chassis control IC development, ensuring high functional safety standards. The automotive clusters in Bavaria and Baden-Württemberg lead innovation in advanced automotive electronics and IC integration.
China
China's Automotive IC market is propelled by the aggressive transition to high-voltage electric vehicle powertrains, creating substantial demand for silicon carbide power ICs. The dual carbon goals and government initiatives promoting V2X communication drive secure, low-latency wireless IC development. The Yangtze River Delta and Pearl River Delta regions are central to EV component manufacturing and custom silicon co-development.
Japan
Japan demonstrates significant demand for high-performance digital ICs, essential for advanced autonomous driving platforms and sophisticated infotainment systems. METI policies support domestic semiconductor innovation, encouraging investment in next-generation automotive technologies. The Nagoya region, a major automotive manufacturing center, anchors the integration of these advanced ICs into new vehicle architectures.
South Korea
South Korea's automotive IC sector experiences robust demand for advanced mixed-signal ICs, crucial for complex ADAS modules and sensor systems that enhance vehicle safety. National automotive policies prioritize the development of smart mobility solutions, including advanced in-cabin sensing systems. The Seoul Capital Area serves as a key hub for automotive R&D, driving innovation in semiconductor design for future vehicle platforms.
Automotive IC Market Key Industry Players
Capability concentration sits with one tier of semiconductor firms, while scale advantage sits with another in the automotive IC market. The market structure involves a mix of large, diversified semiconductor giants and specialized niche players. Strategic archetypes include broad portfolio providers, power semiconductor specialists, and secure connectivity experts. Dominant competitive moves include strategic partnerships with OEMs and continuous portfolio diversification into emerging automotive applications.
Specialists in secure connectivity and in-vehicle networking, like NXP Semiconductors, leverage their expertise to capture strategic shifts in automotive architecture. Infineon Technologies maintains its dominant market position by focusing deeply on power semiconductors and sensor systems for electric vehicles. Texas Instruments anchors its competitive stance with a broad portfolio of analog and embedded processing products, targeting diverse automotive applications from infotainment to powertrain control.
| Leading Market Players |
|---|
| Infineon Technologies |
| NXP Semiconductors |
| STMicroelectronics |
| Texas Instruments |
| Renesas Electronics |
| ON Semiconductor |
| Analog Devices |
| Robert Bosch |
| Qualcomm |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta's concentrated semiconductor manufacturing capacity influences pricing for electric vehicle power management ICs, particularly as demand for SiC components surges. This regional capacity dynamic directly impacts the cost structures for global automotive OEMs and Tier-1 suppliers.
Pricing Analysis
Long-term contract-based offtake agreements dominate pricing for automotive ICs, especially for critical components like microcontrollers and power management ICs. Price differentiation stems from Automotive Safety Integrity Levels (ASIL D certification) and the degree of customization required for specific ADAS functions. Pricing softness runs through standard logic and analog components due to increased competition and volume scaling. OEMs seeking cost-effective solutions for mass-market electric vehicles are the most price-sensitive buyers, while those developing proprietary autonomous driving platforms are less so.
Supply Chain Analysis
Extended payment terms and dedicated supply-chain finance facilities are increasingly common as semiconductor manufacturers invest heavily in advanced automotive-grade fabs. Geographic supply concentration centers in Taiwan, South Korea, and China, particularly for leading-edge process nodes and specialized power ICs. Raw material dependencies include high-purity silicon wafers and specialized ceramic substrates for power devices. Single-source vulnerability for advanced microcontroller units represents a significant structural risk. Distribution runs through a dual model, with direct sales to OEMs for co-developed custom silicon and established channels via Tier-1 suppliers for standard components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive IC market presents a fragmentation opportunity, driven by the architectural shift toward software-defined vehicles creating numerous specialized niches.
For Market Incumbents:
Entrench existing relationships by deepening co-development partnerships with major automotive OEMs for proprietary System-on-Chip (SoC) solutions. Invest heavily in functional safety talent development to mitigate the industry-wide talent gap. This strategy counters the threat of new entrants specializing in niche AI inference chips. Expand capacity for silicon carbide (SiC) power ICs in strategic geographies to leverage the electrification trend.
For New Entrants and Emerging Players:
Specialized AI inference accelerators for in-cabin sensing systems represent a highly penetrable entry point, particularly in the Chinese market. Focus on developing certified IP blocks for specific ADAS functions that can be easily integrated into larger domain controllers. A robust go-to-market angle involves offering comprehensive software development kits and integration support to Tier-1s and smaller OEMs.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors vertically integrated specialists with strong intellectual property in secure connectivity or functional safety verification. Long-term viability rests on securing positions in the evolving software-defined vehicle architectures over the next decade. The signal to watch is increased OEM direct investment in semiconductor foundries or design houses, indicating a shift in control over the silicon roadmap.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen OEM Co-development | Secures long-term design wins and integrates semiconductor expertise directly into vehicle platforms. |
| Invest in Functional Safety Expertise | Mitigates talent shortages and ensures compliance with stringent ISO 26262 requirements for safety-critical ICs. |
| Expand SiC Manufacturing Capacity | Addresses the surging demand for efficient power electronics driven by electric vehicle adoption. |
| Target In-Cabin Sensing Solutions | Captures growth in new safety and user experience applications, driven by Euro NCAP mandates. |
| Acquire AI Software Specialists | Integrates crucial artificial intelligence capabilities, enhancing value proposition for next-generation ADAS and digital cockpit. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings from the EPA and KBA, industry association reports, and academic research on automotive electronics. This approach ensures robust data validation. Primary interviews included OEM platform engineers, Tier-1 procurement leads, semiconductor design architects, and functional safety specialists across key regions.
Forecast inputs considered volume-based and value-based projections across the analysis window, segmented by product type, technology, end-user, application, and vehicle electrification level. Compound annual growth rates were derived from historical data and projected market dynamics, incorporating industry-specific inputs like automotive production forecasts by region and ADAS feature penetration rates.
Practitioners should monitor geopolitical shifts, rapid technological disruption, and changes in regulatory mandates for early signals of market shifts. Forecasts reflect assumptions regarding these factors. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
China Logic Integrated Circuits Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
Digital Audio IC Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Monolithic Microwave IC (MMIC) Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Global Application Specific Consumer Analog Integrated Circuit Market
IC (Integrated Circuits)
3D IC and 2.5D IC Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market