
 Consumer Healthcare Market | 2026-2036
Consumer Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Healthcare Market Analysis
ISO 13485 certification for medical device quality management is redrawing competitive boundaries in consumer healthcare manufacturing. Johnson & Johnson leverages its vertically integrated supply chain to control raw material sourcing for OTC analgesics. GlaxoSmithKline anchors its position through R&D intensity in respiratory self-care formulations. Pfizer differentiates via pharmacy-exclusive distribution partnerships that limit generic substitution.
Consumer healthcare encompasses self-administered products for disease prevention, symptom management, and wellness maintenance, typically formulated with standardized active pharmaceutical ingredients at sub-prescription dosages and manufactured through direct compression or liquid-fill processes for stability and bioavailability. Over-the-Counter Medications command the largest revenue pool due to recurring demand for analgesics and cold remedies, while Dietary Supplements represent the fastest-expanding segment as consumers shift from treatment to prevention paradigms. E-commerce channels are capturing margin pools previously held by brick-and-mortar pharmacies through subscription models and direct-to-consumer branding.
The FDA's OTC monograph reform and the EU's MDR framework for borderline medical devices are tightening evidence requirements for efficacy claims, forcing reformulation investments and relabeling cycles across multinational portfolios. India's CDSCO and the BIS standards for Ayurvedic formulations add parallel compliance layers for botanical-based products entering formal retail channels. Stakeholders must monitor how regulator convergence on digital health claims reshapes the boundary between wellness marketing and regulated medical indications.
Market Dynamics
OTC monograph modernization by the FDA is compressing approval timelines for new active ingredients while simultaneously elevating evidence standards, forcing manufacturers to restructure R&D pipelines and reformulation strategies around real-world efficacy data rather than traditional clinical trial architectures.
Growth Catalysts
- Preventive wellness pivot:Aging demographics in Germany and Japan are reallocating household health expenditure toward sub-prescription prophylactic formulations, expanding addressable demand beyond acute symptom management.
- Telehealth platform expansion:Pharmacy chains in India's tier-two cities are integrating digital consultation interfaces, extending OTC product access beyond traditional metropolitan distribution nodes.
- MDR framework harmonization:The EU's Medical Device Regulation is creating clearer pathways for borderline products, enabling respiratory self-care devices to enter formal retail channels with standardized quality benchmarks.
Market Restraints
- Excipient supply concentration:Microcrystalline cellulose and croscarmellose sodium sourcing clusters in select Asian manufacturing hubs expose formulators to input volatility and geopolitical transit friction.
- Labeling compliance fragmentation:Divergent botanical claim standards between India's BIS Ayurvedic specifications and the FDA's structure-function rules force parallel packaging runs and inventory segmentation.
- Generic substitution pressure:Pharmacy benefit managers in the United States are accelerating therapeutic equivalence protocols that compress branded OTC margin pools for analgesic categories.
Strategic Opportunities
- Subscription commerce models:Direct-to-consumer platforms are capturing recurring revenue streams for dietary supplement regimens, displacing traditional brick-and-mortar replenishment cycles with personalized dosing algorithms.
- Respiratory device convergence:Integration of nebulizer hardware with smartphone-connected adherence tracking is opening pharmacy-exclusive distribution partnerships that limit price-based competition.
- PLI scheme manufacturing incentives:India's production-linked incentive framework for active pharmaceutical ingredients is attracting contract manufacturing investment for export-oriented OTC formulation facilities.
Industry Challenges
- ISO 13485 certification timelines:Medical device quality management system implementation for combination products requires 18-24 month validation cycles that delay market entry against faster pure-drug competitors.
- Legacy ERP integration:Track-and-trace serialization mandates are forcing mid-tier manufacturers to reconfigure warehouse management systems around unit-level identification without disrupting existing batch-processing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Healthcare Market |
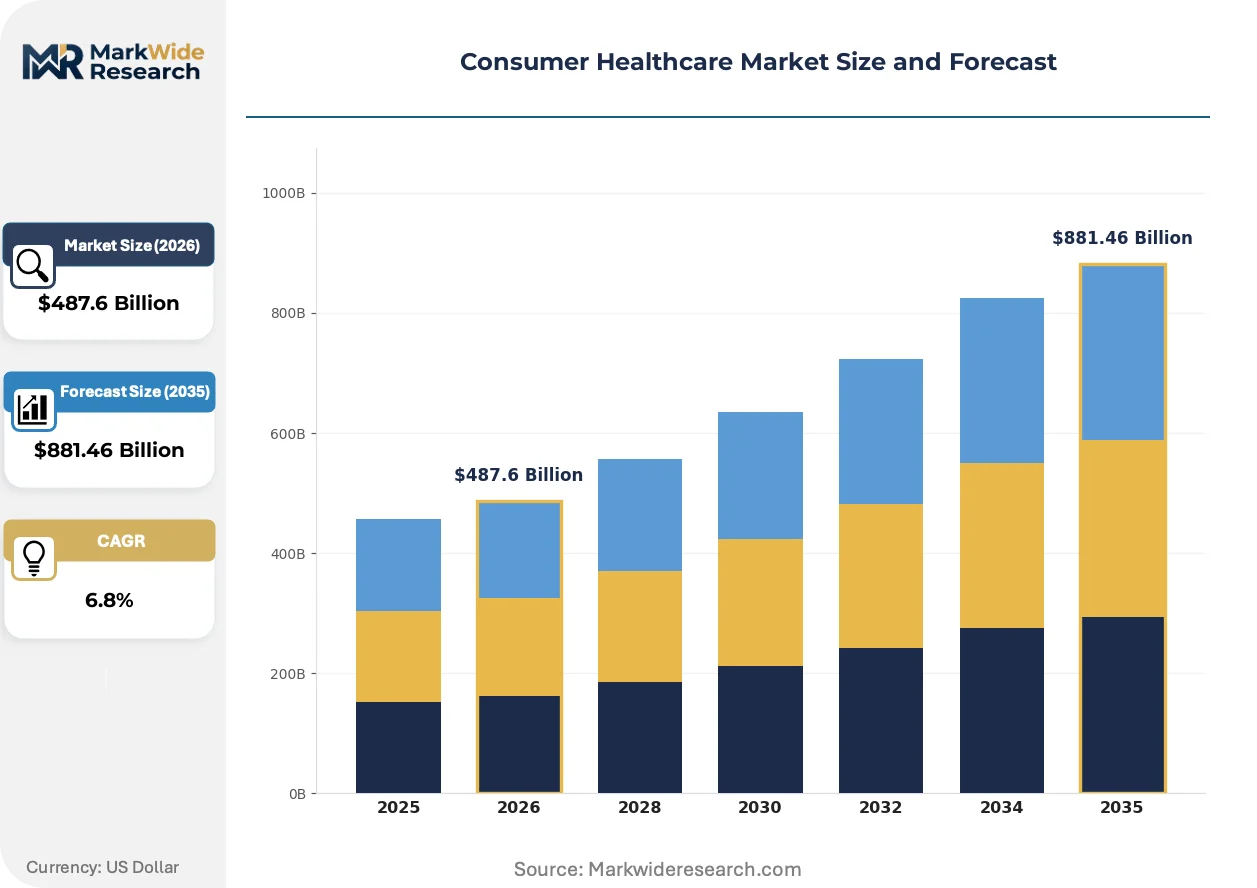
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-the-Counter Medications, Dietary Supplements, Personal Care Products, Skin Care Distribution Channel: Pharmacies, E-commerce, Supermarkets, Health Stores Customer Type: Adults, Children, Seniors, Caregivers Usage Occasion: Everyday Health, Seasonal Allergies, Sports Recovery, Wellness |
| Companies Covered | Johnson & Johnson, GlaxoSmithKline, Procter & Gamble, Bayer AG, Pfizer, Novartis International AG, Sanofi, Abbott Laboratories, Reckitt Benckiser Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Healthcare Market Emerging Trajectories
Dosage form innovation and digital connectivity are converging to transform how consumers interact with self-care products, compressing the boundary between pharmaceutical efficacy and wellness experience design.
Connected inhaler technology is miniaturizing sensor arrays and Bluetooth transmission modules into handheld respiratory devices that capture usage patterns and environmental trigger data. Pharmacy chains in Germany are piloting these systems for asthma management protocols, enabling clinicians to adjust therapeutic regimens remotely. This capability is compressing the traditional gap between acute symptom relief and chronic disease monitoring, positioning OTC respiratory products as entry points to longitudinal care relationships.
The FDA's OTC monograph reform is eliminating the time-and-extent application pathway for new active ingredients, replacing it with a standardized administrative order process that demands contemporary efficacy evidence. Manufacturers must now generate real-world data or controlled clinical studies for ingredients previously grandfathered under 1970s safety determinations. Analgesic and antacid categories face the most immediate relabeling investments, with reformulation costs concentrated in portfolios dependent on legacy active compounds.
Subscription-based replenishment is displacing episodic pharmacy purchasing for chronic-condition OTC categories, with consumers in the United States and United Kingdom accepting automated delivery schedules for allergy, digestive, and sleep-aid products. Direct-to-consumer brands are capturing this behavioral shift through mobile-first ordering interfaces that bypass traditional wholesale and retail margin structures. This channel migration is most visible in dietary supplements, where personalized dosing algorithms and loyalty program integration sustain higher customer lifetime values than conventional retail economics permit.
Consumer Healthcare Market Segmentation
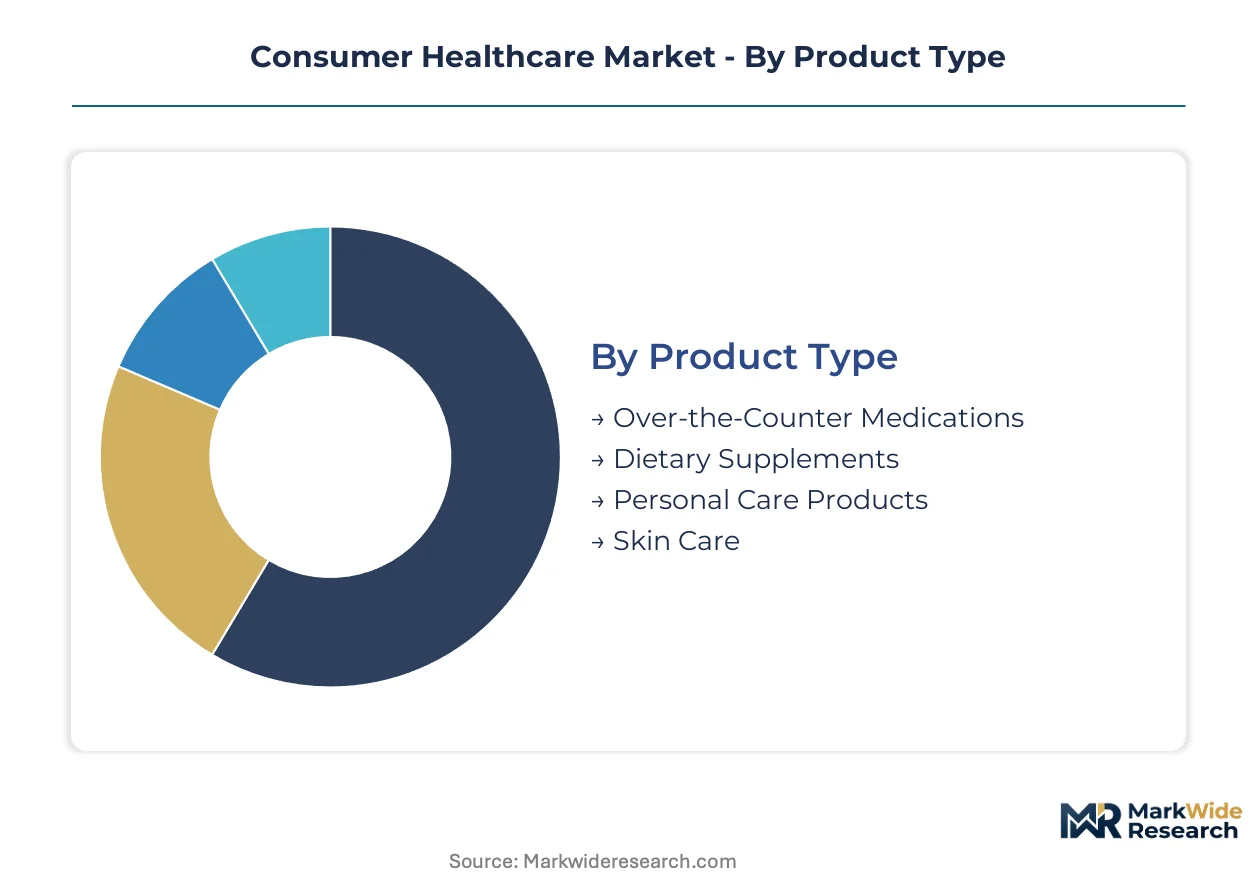
Segmentation in consumer healthcare reveals distinct margin architectures across product categories and channel configurations. Manufacturers calibrate formulation investments and packaging specifications against the purchasing patterns of specific demographic cohorts and usage contexts.
Product Type:
Premium pricing power concentrates in formulations with clinical validation or dermatological endorsement, while mass-market categories compete on shelf velocity and promotional intensity.
- Over-the-Counter Medications:Standardized active pharmaceutical ingredients at sub-prescription dosages formulated for stability through direct compression or liquid-fill processes. Demand clusters around analgesic and cold remedy categories in Germany, where pharmacy chains maintain exclusive distribution relationships that limit generic substitution pressure.
- Dietary Supplements:Botanical, mineral, and vitamin compounds manufactured under varying regulatory frameworks including India's BIS Ayurvedic standards and the FDA's structure-function claim rules. India's tier-two cities are driving volume expansion as telehealth platforms extend access beyond metropolitan pharmacy networks.
- Personal Care Products:Hygiene and grooming formulations with therapeutic positioning, subject to borderline medical device scrutiny under the EU's MDR framework.
- Skin Care:Dermatological and cosmetic preparations, where efficacy claims trigger divergent compliance pathways between cosmetic and pharmaceutical regulators.
The dominant share belongs to Over-the-Counter Medications, while Dietary Supplements is closing the gap fastest.
Distribution Channel:
Channel selection determines margin retention, with direct-to-consumer platforms capturing recurring revenue streams that wholesale-dependent formats cannot replicate.
- Pharmacies:Brick-and-mortar and digital pharmacy networks with licensed dispensing protocols. Germany's pharmacy chains are piloting connected inhaler programs that integrate hardware with remote monitoring capabilities.
- E-commerce:Direct-to-consumer platforms and marketplace aggregators operating subscription replenishment models. These channels are displacing traditional wholesale margin structures through personalized dosing algorithms and loyalty integration.
- Supermarkets:Mass retail outlets with high-velocity replenishment cycles and promotional pricing pressure on standard OTC categories.
- Health Stores:Specialty retailers focused on natural and botanical formulations, where India's BIS Ayurvedic certification requirements create inventory segmentation challenges.
Pharmacies retain the largest revenue pool, though E-commerce is expanding most quickly through subscription capture.
Customer Type:
Purchasing authority and reimbursement access vary sharply across age cohorts, with seniors commanding the highest per-capita expenditure on preventive formulations.
- Adults:Working-age consumers with employer-sponsored wellness programs and direct purchasing authority for symptom management products.
- Children:Pediatric formulations with stricter dosing specifications and guardian-mediated purchasing decisions.
- Seniors:Aging populations in Germany and Japan reallocating household expenditure toward sub-prescription prophylactic formulations beyond acute symptom management.
- Caregivers:Proxy purchasers managing regimens for dependent populations, with demand concentrated in chronic-condition categories.
Seniors account for the dominant expenditure share, while Caregivers are gaining purchasing influence fastest through chronic disease management responsibilities.
Usage Occasion:
Occasion-based positioning determines formulation packaging, dosing convenience, and marketing claim architecture across the product lifecycle.
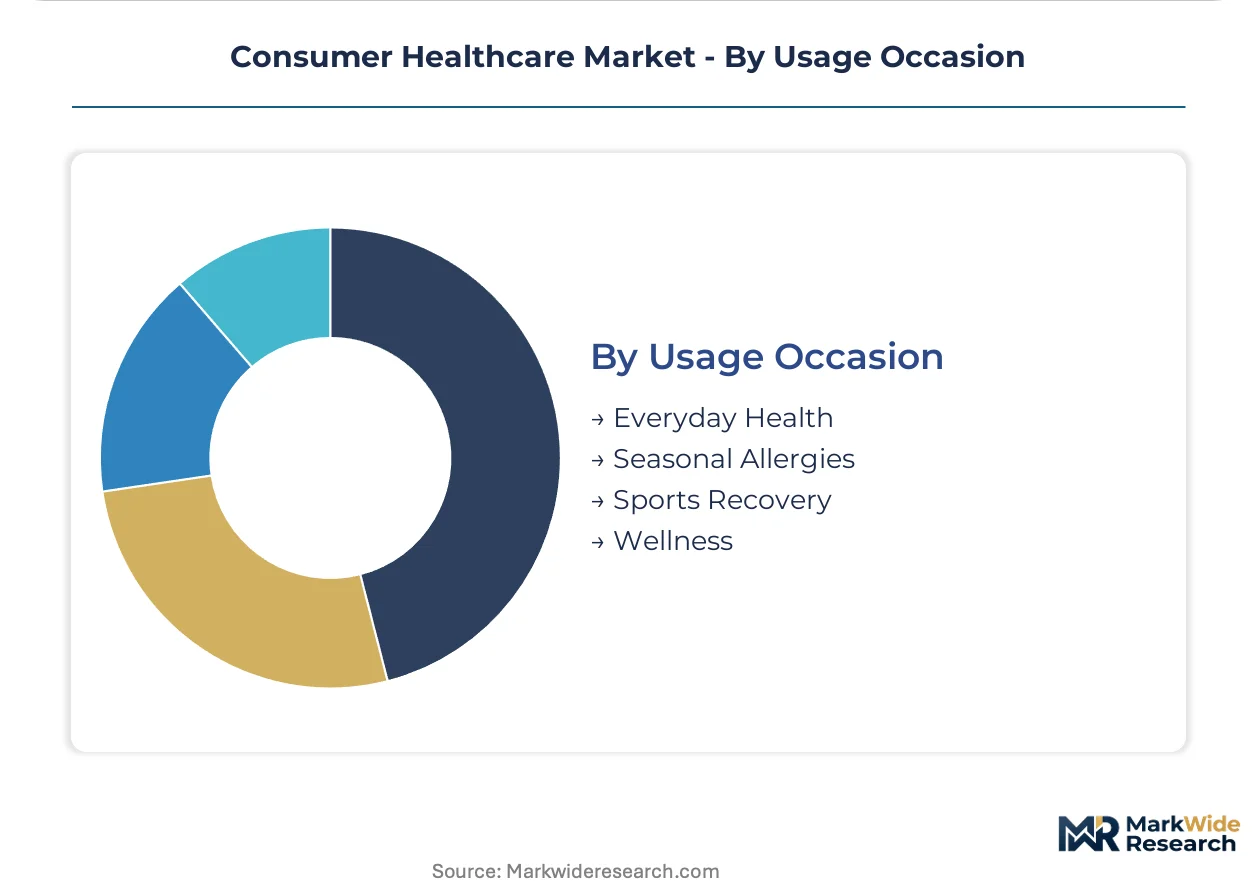
- Everyday Health:Maintenance and preventive regimens with subscription-compatible replenishment profiles, including digestive and sleep-aid categories.
- Seasonal Allergies:Cyclical demand patterns with pre-season inventory build and promotional timing calibrated to pollen forecasting data.
- Sports Recovery:Athletic performance and musculoskeletal support products, where anti-inflammatory positioning intersects with supplement and OTC boundaries.
- Wellness:Lifestyle-oriented consumption spanning stress management, immunity, and aesthetic outcomes with the least regulatory claim constraint.
Everyday Health holds the dominant position, while Wellness is climbing the fastest as consumers shift from treatment to prevention paradigms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for active pharmaceutical ingredients is attracting contract manufacturing investment for export-oriented OTC formulation facilities. Germany's pharmacy chains are piloting connected inhaler programs that integrate hardware with remote monitoring capabilities. Japan's aging demographics are reallocating household expenditure toward sub-prescription prophylactic formulations.
United States
Employer-sponsored wellness programs and direct-to-consumer subscription models are expanding recurring revenue streams for dietary supplement regimens. The FDA's OTC monograph reform is compressing approval timelines for new active ingredients while elevating evidence standards. Pharmacy benefit managers are accelerating therapeutic equivalence protocols that compress branded OTC margin pools for analgesic categories.
Germany
Self-directed wellness adoption among aging populations is accelerating purchases of preventive OTC formulations beyond acute symptom management. The EU's MDR framework is creating clearer pathways for borderline respiratory self-care devices to enter formal retail channels. Pharmacy chains in Berlin and Munich are maintaining exclusive distribution relationships that limit generic substitution pressure.
India
Telehealth platform expansion in tier-two cities is extending OTC product access beyond traditional metropolitan distribution nodes. CDSCO and BIS standards for Ayurvedic formulations add parallel compliance layers for botanical-based products entering formal retail channels. Manufacturing clusters in Maharashtra and Gujarat are scaling contract formulation facilities under PLI scheme incentives.
Japan
Senior households are reallocating expenditure toward sub-prescription prophylactic formulations as preventive wellness pivots displace reactive treatment patterns. METI and PMDA oversight maintains stringent quality benchmarks for self-care products entering formal retail. The Kanto region around Tokyo anchors domestic formulation manufacturing with integrated supply chains for excipient sourcing.
United Kingdom
Subscription-based replenishment is displacing episodic pharmacy purchasing for chronic-condition OTC categories including allergy and digestive products. MHRA alignment with EU MDR frameworks is tightening evidence requirements for efficacy claims on borderline medical devices. E-commerce platforms in London and the Southeast are capturing recurring revenue streams through personalized dosing algorithms.
Consumer Healthcare Market Vendor Landscape
Player mix skews toward diversified pharmaceutical conglomerates with vertically integrated supply chains and specialized OTC-focused divisions. Tier-one positions concentrate around manufacturers controlling raw material sourcing for analgesics and respiratory formulations. Two strategic archetypes dominate: vertically integrated pharmaceutical majors leveraging captive ingredient supply, and consumer goods specialists deploying direct-to-consumer branding. Competitive moves center on pharmacy-exclusive distribution partnerships and subscription commerce platform development.
Among diversified healthcare conglomerates, Johnson & Johnson and GlaxoSmithKline exemplify the vertically integrated archetype, while Pfizer occupies a position within the pharmacy-partnership tier. These entities represent contrasting strategic postures toward channel control and formulation specialization.
| Leading Market Players |
|---|
| Johnson & Johnson |
| GlaxoSmithKline |
| Procter & Gamble |
| Bayer AG |
| Pfizer |
| Novartis International AG |
| Sanofi |
| Abbott Laboratories |
| Reckitt Benckiser Group plc |
| Others |
Supply Flow & Price Mechanics
Microcrystalline cellulose substitution for croscarmellose sodium in direct-compression tablet formulations is redrawing active pharmaceutical ingredient procurement geography while compressing excipient cost structures across European and Asian manufacturing hubs.
Pricing Analysis
Cost-plus contracts with API indexation anchor pricing structures for OTC analgesic and respiratory categories, with premium tiers commanding dermatological endorsement premiums while standard formulations face margin compression from pharmacy benefit manager therapeutic equivalence protocols. Price differentiation rests on ISO 13485 certification status and volume scale commitments, with private-label supermarket tiers exhibiting highest price sensitivity and pharmacy-exclusive branded portfolios maintaining lowest elasticity. Pricing pressure stems from generic substitution acceleration in United States distribution channels.
Supply Chain Analysis
Strait of Malacca transit underwrites excipient supply security for microcrystalline cellulose and croscarmellose sodium shipments moving from Indian and Chinese manufacturing clusters to European formulation facilities. Raw material dependencies center on cellulose pulp feedstocks, specialty-grade sodium compounds, and botanical extracts subject to India's BIS Ayurvedic certification requirements. Single-source vulnerability concentrates in select Asian hubs for critical disintegrants. Distribution runs through vertically integrated pharmaceutical majors and contract manufacturing organizations with captive warehouse networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The consumer healthcare market functions as a defensive-moat arena where FDA OTC monograph entrenchment and pharmacy-exclusive distribution relationships erect structural barriers against price-based competition.
For Market Incumbents: Fortify ISO 13485 certification pipelines for combination respiratory devices to delay competitor entry against 18-24 month validation cycles, while deepening backward integration into microcrystalline cellulose sourcing to buffer excipient volatility from Asian hub concentration. Channel control through pharmacy-exclusive partnerships limits generic substitution pressure from pharmacy benefit managers.
For New Entrants and Emerging Players: Subscription-layer service gaps in chronic-condition replenishment for allergy and digestive categories expose white-space opportunities where incumbents under-serve automated dosing algorithm demand. India's tier-two telehealth platform expansion offers the most penetrable geography, with direct-to-consumer mobile interfaces bypassing wholesale margin structures as the optimal go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors vertically integrated manufacturers with captive API supply and established monograph compliance. Long-term viability favors entities controlling raw material sourcing and distribution infrastructure rather than pure-brand plays. The signal to watch is FDA administrative order issuance timelines for legacy active ingredient reformulation mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Medical device quality management validation compresses competitor entry timelines for combination products. |
| Backward Integration into API Supply | Captive sourcing of microcrystalline cellulose buffers excipient cost volatility from Asian hub concentration. |
| Pharmacy-Exclusive Distribution Partnership | Exclusive retail relationships limit generic substitution pressure from pharmacy benefit managers. |
| Subscription Commerce Platform Development | Automated replenishment algorithms capture recurring revenue streams beyond traditional wholesale economics. |
| Connected Inhaler Hardware Integration | Bluetooth-enabled respiratory devices with remote monitoring open longitudinal care relationships. |
Methodological Framework
A standing panel of regulatory affairs leads, pharmacy chain procurement directors, and contract manufacturing executives provided ongoing calibration against primary fieldwork with OTC brand managers and telehealth platform operators. Secondary validation drew from FDA OTC monograph filings, CDSCO registration databases, EMA borderline device determinations, and Indian PLI scheme disclosure records. Bottom-up volume modeling triangulated against top-down expenditure flow analysis.
Consistency checks validated segment-level outputs against external regulatory filing benchmarks and channel shipment data across the projection horizon. The analytical framework modeled product type, distribution channel, customer cohort, and usage occasion dimensions alongside regional regulatory cluster variations. CAGRs derived from expenditure trend extrapolation with inputs from aging demographic projections and digital health platform penetration curves.
Forecasts assume regulatory continuity in FDA monograph modernization, EU MDR enforcement, and India's CDSCO-BIS alignment; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as OTC-to-prescription boundary disputes and telehealth reimbursement rulings evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Artificial Saliva Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Incontinence Products Market
Healthcare Products
Nursing Products Market
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
Toothbrush Sanitizer Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
Organ Care Products Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
North America Adult Incontinence Products Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Global Life Science Products Market
Healthcare Products
Global Consumer Healthcare Products Market