
 Air Data Testers Market | 2026-2036
Air Data Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Air Data Testers Market Insights
DO-178C software compliance standards for avionics verification is expanding the addressable market for precision calibration equipment. Safran SA leverages its integrated aerospace electronics portfolio to sustain long-term service contracts with European military operators. Fortive Corporation anchors its position through Fluke's metrology heritage and channel density in North American MRO networks. Parker Hannifin Corporation competes via its fluid control expertise extended into pneumatic test systems for pitot-static validation.
Air data testers are precision instruments that simulate altitude, airspeed, and Mach number conditions to verify aircraft pitot-static systems, typically achieving accuracy within 0.1% of reading through digitally controlled pressure generation. These devices serve as mandatory verification tools during type certification, scheduled maintenance, and depot-level overhaul across civil and military aviation fleets. Portable testers lead the product type segment due to line-maintenance mobility requirements and reduced aircraft downtime. Software-integrated solutions are displacing legacy analog architectures as airlines seek automated test sequencing and digital record-keeping for regulatory traceability. Military end users represent the most concentrated margin pool given program longevity and specification rigor.
FAA airworthiness directives mandate periodic pitot-static system verification under Part 43 and Part 91 regulations, while EASA CS-25 certification rules enforce equivalent standards across European-registered transport aircraft. The EPA's National Emission Standards for Hazardous Air Pollutants indirectly shapes demand by accelerating fleet modernization programs that require updated test infrastructure. Stakeholders must monitor evolving MIL-STD-1553 and ARINC 429 interface requirements as next-generation military platforms integrate digital air data computers with legacy analog test protocols.
Market Dynamics
DO-178C software compliance mandates are compressing equipment refresh cycles as military and commercial operators replace analog test architectures with digitally integrated validation systems. This regulatory pressure is redistributing competitive advantage toward vendors with embedded software certification capabilities.
Growth Catalysts
- FAA Part 43 mandates:Periodic pitot-static verification requirements under US airworthiness directives sustain replacement demand across aging civil fleets. Operators must maintain calibrated test equipment to retain operating certificates.
- Military depot modernization:Extended-life fighter and transport programs in the United States defense sector are upgrading test infrastructure to support digital air data computer architectures. Program longevity creates sustained procurement windows.
- Pneumatic simulation advances:Digitally controlled pressure generation achieving 0.1% accuracy is enabling faster line-maintenance turnaround. Airlines reduce aircraft downtime through portable tester deployment.
Market Restraints
- Specialized sensor input costs:Precision pressure transducers and quartz reference standards face supply concentration among Japanese and German component suppliers. Input cost volatility compresses margin for mid-tier equipment manufacturers.
- DO-178C certification friction:Software validation documentation requirements extend product development timelines by 18-24 months for new market entrants. Regulatory burden protects incumbent positions.
- Consolidated MRO procurement:North American airline maintenance networks concentrate purchasing through approved vendor lists, limiting access for specialized regional suppliers.
Strategic Opportunities
- India defense aviation expansion:Indigenous fighter and transport programs under the country's military modernization roadmap require pitot-static validation infrastructure. Local production incentives create partnership pathways for foreign test equipment vendors.
- ARINC 429 interface convergence:Integration of legacy analog test protocols with digital air data computer buses opens retrofit markets for software-integrated solutions. Military platforms are prioritizing backward-compatible architectures.
- Automated test sequencing:Digital record-keeping capabilities aligned with EASA CS-25 traceability requirements enable premium positioning in European carrier MRO contracts.
Industry Challenges
- Embedded software certification expertise:DO-178C Level A validation requires specialized aerospace software engineering talent that concentrates among defense contractors. Commercial equipment vendors face recruitment competition from prime integrators.
- Legacy analog system integration:Mixed-fleet operators require test equipment bridging MIL-STD-1553 and modern digital interfaces. Engineering complexity extends customization cycles and strains technical support resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Data Testers Market |
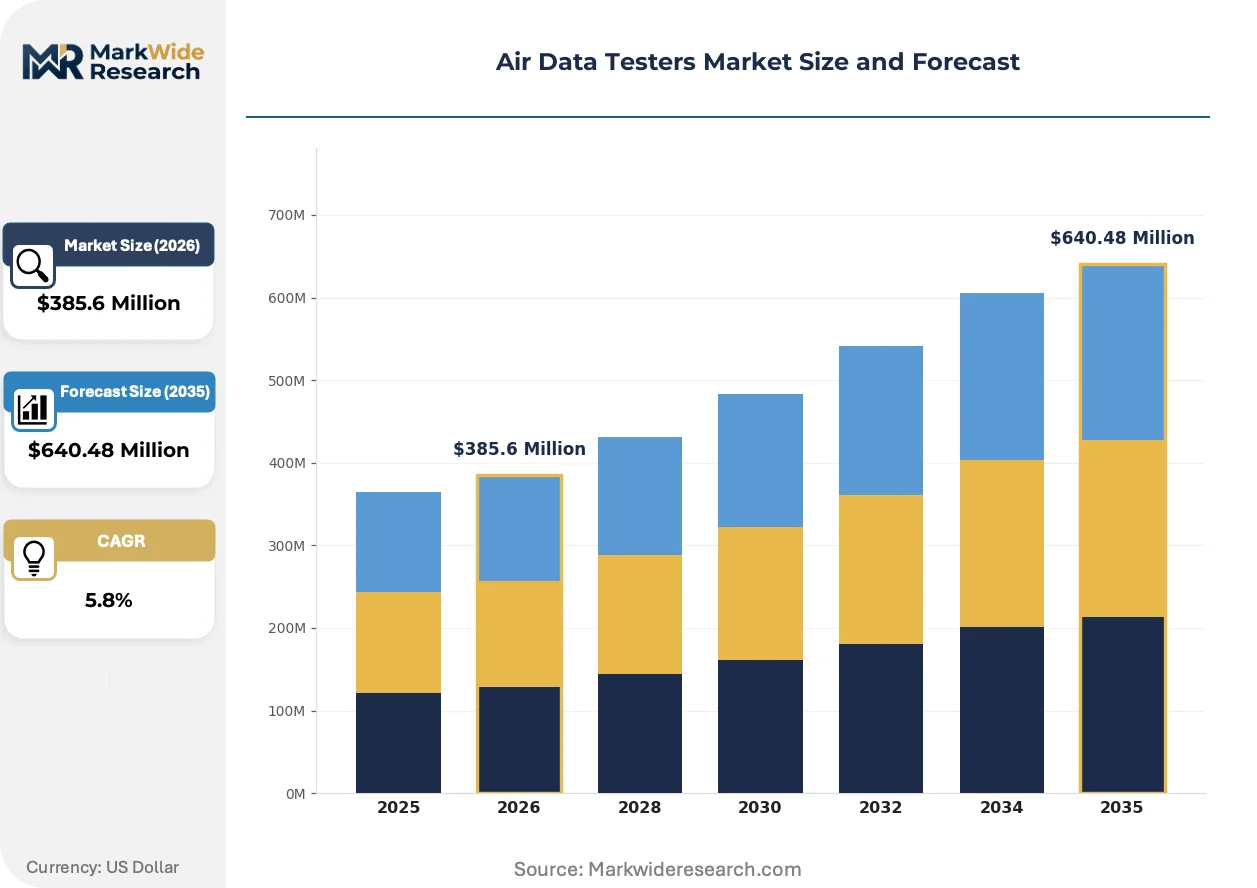
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Testers, Ground Testers, In-Flight Testers, Fixed Test Stations Technology: Digital Sensors, Analog Sensors, Software-Integrated Solutions, Wireless Systems End User: Aerospace Manufacturers, Aviation Maintenance Organizations, Flight Training Schools, Military Application: Aircraft Maintenance, Flight Testing, Calibration Services, Research & Development |
| Companies Covered | Safran SA, Fortive Corporation, General Electric Company, Parker Hannifin Corporation, Honeywell International Inc., Raytheon Technologies Corporation, Teledyne Technologies Incorporated, Thales Group, ATEQ Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Data Testers Market Trends and Innovations
Software-defined test architectures are displacing hardware-centric designs as operators prioritize automated calibration workflows and digital audit trails. This shift is compressing product lifecycles while elevating vendor capabilities in embedded systems engineering.
Modular pressure generation systems are modularizing traditional monolithic tester designs into field-swappable component assemblies. Military depot maintenance operators are adopting these configurations to reduce spare parts inventory and accelerate repair turnaround. The architecture is modularizing supply chain relationships as vendors compete on subsystem interoperability rather than integrated system dominance.
EASA CS-25 certification amendments are tightening documentation requirements for pitot-static system verification across European-registered transport aircraft. Airlines must demonstrate traceable calibration records spanning equipment serial numbers, technician certifications, and environmental conditions during test execution. Narrow-body operators are responding by consolidating vendor relationships to simplify compliance audit preparation.
Maintenance outsourcing is consolidating test equipment procurement decisions into specialized MRO networks rather than individual airline engineering departments. Third-party providers in the United States and Germany are unbundling after-sales service from hardware acquisition, creating recurring revenue streams for calibration and firmware update subscriptions. This pattern is most visible among low-cost carriers seeking to eliminate captive maintenance infrastructure.
Air Data Testers Market Segmentation
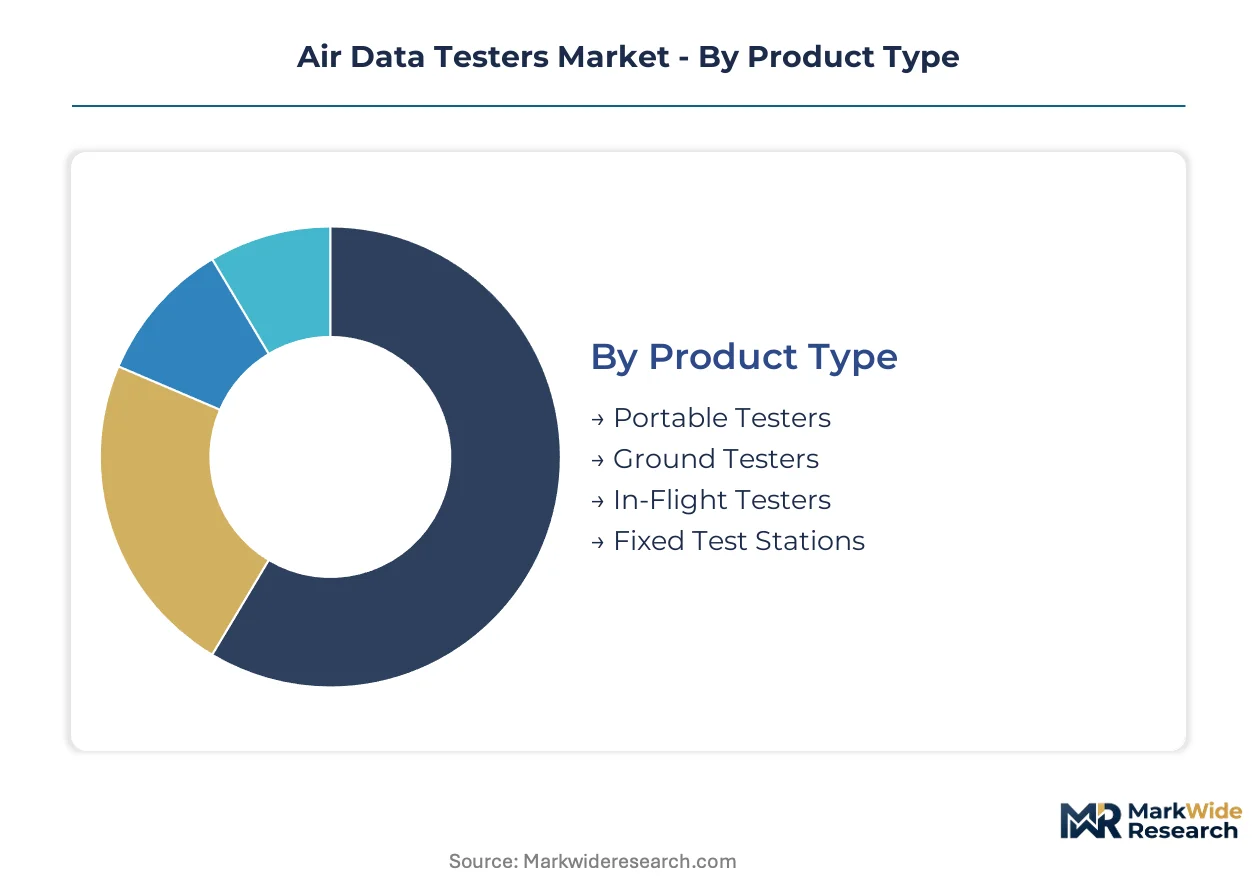
Air data tester procurement concentrates around four distinct axes: mobility requirements for line maintenance, sensor architecture transitions, operator certification mandates, and application-critical accuracy thresholds. Each segmentation dimension reflects divergent supply chain configurations and margin structures that vendors must navigate.
Product Type:
Supply concentration in portable and ground-based systems creates divergent channel economics, with military depot networks and commercial MROs demanding fundamentally different form factors.
- Portable Testers:Battery-powered units weighing under 15 kilograms achieve 0.1% accuracy through quartz-crystal pressure references. Demand clusters in United States airline line-maintenance operations where FAA Part 43 turnaround requirements compress deployment windows.
- Ground Testers:Trolley-mounted systems integrate multi-channel pressure generation for simultaneous pitot-static and angle-of-attack validation. European carrier MROs in Germany and France prioritize these configurations for hangar-based heavy checks under EASA CS-25 documentation rules.
- In-Flight Testers:Ruggedized units with ARINC 429 interfaces validate air data computers during actual flight regimes.
- Fixed Test Stations:Permanent installations serve military depot facilities with automated sequencing capabilities.
Today's leader: Portable Testers. Tomorrow's challenger: Fixed Test Stations.
Technology:
Component sourcing for precision pressure transducers and embedded processors concentrates among Japanese and German suppliers, creating tiered cost structures across digital and legacy architectures.
- Digital Sensors:MEMS-based pressure transducers with 24-bit ADC resolution enable automated calibration drift compensation. United States defense aviation programs specify these for next-generation fighter platforms requiring MIL-STD-1553 bus integration.
- Software-Integrated Solutions:DO-178C compliant firmware architectures automate test sequencing and generate audit-ready calibration records. Commercial airlines in the United States adopt these fastest to satisfy FAA airworthiness directive traceability requirements.
- Analog Sensors:Potentiometric and strain-gauge designs persist in legacy fleet support contracts.
- Wireless Systems:Bluetooth-enabled pressure modules reduce cable routing complexity during line maintenance.
Software-Integrated Solutions are climbing the fastest as regulatory documentation burdens intensify.
End User:
Procurement authority fragmentation across engineering, maintenance, and training departments creates multiple sales cycles with divergent technical specifications.
- Military:Program-of-record specifications under MIL-PRF-9490 mandate extended environmental qualification and software certification. United States Air Force and Navy depot modernization sustain the most concentrated margin pool through multi-year indefinite-delivery contracts.
- Aviation Maintenance Organizations:Third-party MROs in the United States and Germany consolidate purchasing through approved vendor lists, favoring vendors with integrated calibration service networks.
- Aerospace Manufacturers:Type certification support during new aircraft programs drives peak accuracy requirements.
- Flight Training Schools:Simulator synchronization needs create secondary demand for mid-tier accuracy equipment.
Today's leader: Military. Tomorrow's challenger: Aviation Maintenance Organizations.
Application:
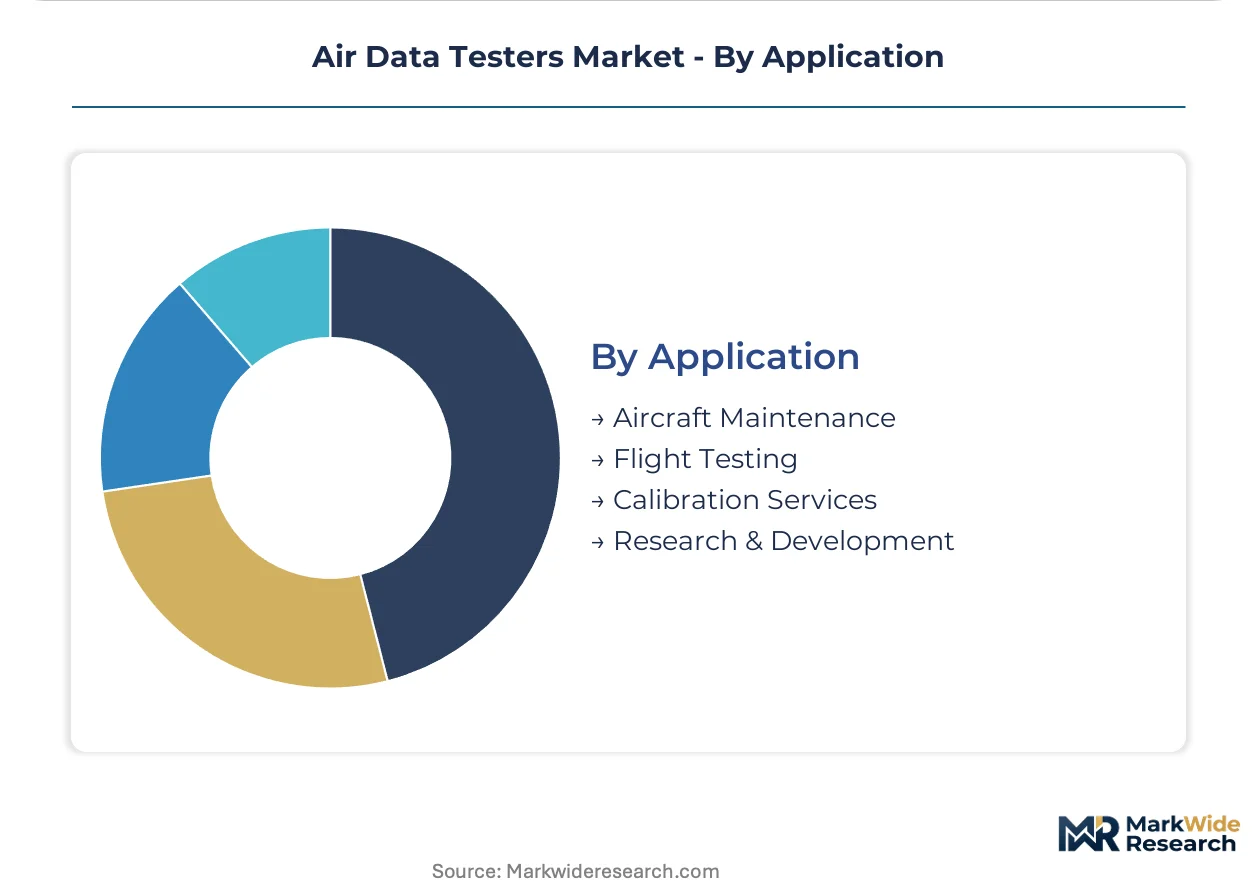
Accuracy specifications and documentation rigor vary sharply across maintenance, certification, and research contexts, fragmenting vendor specialization.
- Aircraft Maintenance:Scheduled pitot-static verification under FAA Part 43 and EASA Part-M sustains the largest volume base. United States regional airlines drive replacement demand as aging analog testers fail calibration tolerance.
- Calibration Services:ISO 17025-accredited laboratories require primary standard traceability to national metrology institutes. German and Japanese service providers concentrate demand for highest-tier quartz reference systems.
- Flight Testing:Type certification programs demand expanded altitude and Mach number simulation ranges.
- Research & Development:University and government laboratory procurement follows grant funding cycles with irregular volume.
Aircraft Maintenance dominates current procurement volume. Calibration Services present the steepest expansion trajectory as outsourcing consolidates metrology infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace engineering talent clusters in the United States, France, and Germany anchor the geographic distribution of air data tester demand. Defense procurement offices and commercial aviation MRO networks concentrate equipment specification authority in these markets.
United States
United States Air Force and Navy depot modernization programs sustain the largest concentrated procurement pool for precision pneumatic test equipment. FAA Part 43 and Part 91 airworthiness directives mandate periodic pitot-static verification across civil fleets, compressing replacement cycles for aging analog testers. Dallas-Fort Worth and Seattle-Tacoma MRO corridors consolidate purchasing through approved vendor lists serving legacy and next-generation aircraft platforms.
Germany
EASA CS-25 certification amendments tighten documentation requirements for European-registered transport aircraft, elevating demand for software-integrated validation systems. German calibration laboratories accredited under ISO 17025 concentrate primary standard traceability demand for quartz reference systems. Hamburg and Munich aerospace clusters host major MRO providers unbundling after-sales service from hardware acquisition.
France
Indigenous fighter programs under the country's military aviation roadmap require pitot-static validation infrastructure with extended environmental qualification. French national aerospace regulators enforce software certification standards aligned with DO-178C for embedded avionics verification. Toulouse and Paris-Saclay engineering centers sustain long-term service contracts with European military operators.
United Kingdom
Royal Air Force fleet sustainment programs generate recurring procurement for trolley-mounted multi-channel pressure generation systems. UK Civil Aviation Authority regulations mirror EASA documentation requirements for traceable calibration records across narrow-body operator fleets. Farnborough and Broughton aerospace corridors concentrate MRO consolidation trends among third-party maintenance providers.
India
Indigenous fighter and transport programs under the country's military modernization roadmap create partnership pathways for foreign test equipment vendors. Local production incentives through defense offset policies encourage technology transfer arrangements with established aerospace electronics suppliers. Bangalore and Hyderabad defense aviation manufacturing clusters require pitot-static validation infrastructure for domestic platform development.
Air Data Testers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the air data tester landscape, with integrated aerospace conglomerates holding distinct advantages in long-term military service contracts. The vendor base stratifies between precision metrology specialists and diversified industrial conglomerates extending fluid control or avionics portfolios into pneumatic test systems. Three archetypes dominate: aerospace-integrated electronics suppliers, standalone test equipment manufacturers, and industrial automation platforms leveraging channel density. Competitive dynamics center on embedded software certification capabilities and MRO network penetration rather than manufacturing scale alone.
Among aerospace-integrated conglomerates, Safran SA and Thales Group exemplify the electronics-portfolio archetype, while Fortive Corporation occupies a position representing metrology heritage and North American channel density. Parker Hannifin Corporation anchors the industrial-diversification vector, with Honeywell International Inc. and Raytheon Technologies Corporation sitting within the defense-prime tier extending test capabilities from broader avionics platforms.
| Leading Market Players |
|---|
| Safran SA |
| Fortive Corporation |
| General Electric Company |
| Parker Hannifin Corporation |
| Honeywell International Inc. |
| Raytheon Technologies Corporation |
| Teledyne Technologies Incorporated |
| Thales Group |
| ATEQ Aviation |
| Others |
Pricing and Supply Chain Analysis
DO-178C software certification mandates from the FAA and EASA are forcing equipment refresh cycles that compress procurement timelines and elevate supplier qualification barriers. Military depot operators and commercial MROs now demand bundled firmware update subscriptions alongside hardware acquisition, reshaping how vendors structure long-term revenue streams and component sourcing strategies.
Pricing Analysis
Bundled service contracts versus unbundled hardware-only transactions now define the dominant pricing split across military and commercial segments. Three-tier pricing structure across premium, standard, and economy levels separates DO-178C Level A certified systems from line-maintenance portable units and legacy analog support equipment. Price differentiation rests on certification grade and after-sales calibration network density rather than manufacturing scale alone. Cost compression in mid-tier portable testers is intensifying because Japanese and German precision pressure transducer suppliers face input concentration risks. Low-cost carriers operating narrow-body fleets exhibit highest price sensitivity, while United States Air Force depot programs demonstrate lowest sensitivity due to program-of-record longevity.
Supply Chain Analysis
Certification and qualification gating for DO-178C compliance and MIL-STD-1553 interface validation concentrates approved supplier pools among established aerospace electronics vendors. Component manufacturing draws from Japan, Germany, and the United States for quartz-crystal pressure references, MEMS transducers, and embedded processors. Raw material dependencies include precision-machined aluminum housings, high-purity pneumatic seals, and radiation-hardened microcontrollers. Single-source vulnerability persists for 24-bit ADC resolution chipsets qualified to aerospace temperature ranges. Distribution runs through authorized MRO vendor lists in Dallas-Fort Worth and Seattle-Tacoma corridors, with military procurement channeling through Defense Logistics Agency indefinite-delivery contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air data testers function as a regulatory compounder where each FAA airworthiness directive and EASA CS-25 amendment expands mandatory verification scope and sustains replacement demand across aging and next-generation fleets alike.
For Market Incumbents: Acquire embedded software certification capabilities to defend against analog-to-digital displacement threats from avionics integrators extending into test equipment. Consolidate calibration service network density in United States MRO corridors to tighten channel control against emerging modular subsystem vendors. Invest in backward integration of precision pressure transducer sourcing to mitigate Japanese supplier concentration risks.
For New Entrants and Emerging Players: Begin with ARINC 429 interface retrofit modules targeting mixed-fleet operators bridging legacy analog and digital air data computer architectures. White-space concentration sits with Indian defense aviation manufacturing clusters seeking foreign partnership pathways under local production incentives. A calibration-as-a-service subscription model offers the most penetrable go-to-market angle against hardware-centric incumbents.
For Investors and Strategic Acquirers: Asymmetric upside sits with software-defined test architecture specialists holding DO-178C Level A validation expertise and military depot relationships. Long-term viability over a multi-year window favors vendors with recurring firmware revenue streams rather than transactional hardware models. Watch for EASA documentation rule amendments tightening traceability requirements as the inflection signal for accelerated software-integrated solution adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| DO-178C Software Certification Investment | FAA and EASA compliance mandates elevate embedded firmware capabilities above hardware parity. |
| MRO Channel Consolidation Partnership | Approved vendor list penetration in Dallas-Fort Worth and Seattle-Tacoma corridors secures recurring procurement. |
| Modular Subsystem Interoperability Development | Field-swappable component architectures reduce military depot spare parts inventory burdens. |
| India Defense Offset Joint Venture | Local production incentives under military modernization roadmap create technology transfer pathways. |
| Calibration Service Network Expansion | ISO 17025-accredited laboratory density captures outsourcing consolidation in German and United States metrology markets. |
Research Methodology
Multiple input streams — primary interviews with military depot engineering officers, commercial airline maintenance directors, and avionics procurement leads; secondary validation through FAA airworthiness directive filings, EASA CS-25 certification amendments, and MIL-STD specification releases; plus customs trade data and aerospace electronics SEC disclosures — were reconciled through bottom-up equipment shipment analysis and top-down MRO spending triangulation.
Data-stream reconciliation across the projection horizon applied segment-specific modeling for portable versus ground-based form factors, digital versus analog sensor architectures, and military versus commercial end-use concentrations. CAGRs were derived from equipment replacement cycle analysis tied to regulatory mandate timelines and fleet modernization program schedules. Forecast inputs incorporated pitot-static verification interval changes under Part 43 amendments and software-integrated solution penetration curves in European carrier MRO contracts.
Several conditions sit outside the modeled scope, including geopolitical disruption to Japanese precision component supply, unanticipated EASA documentation rule reversals, and military program cancellation decisions. Forecasts reflect documented assumptions about regulatory enforcement continuity and certification standard stability. A model refresh is warranted upon material change in FAA or EASA pitot-static verification mandate scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Attitude and Heading Reference System (AHRS) Market
Aircraft Data and Diagnostics
Global Aircraft Health Monitoring Market
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Aircraft Flight Recorder Market
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market
Aircraft Data and Diagnostics
United States Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Flight Data Recorder (FDR) Market