
 Air Data Systems Market | 2026-2036
Air Data Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Air Data Systems Market Analysis
European sensor foundries and North American avionics integrators is broadening the qualified supplier base for calibrated air data modules. Honeywell International leverages its integrated flight-deck architecture to bundle air data computers with inertial reference units. Collins Aerospace sustains dual-source relationships across military and commercial channels, while Curtiss-Wright Corporation anchors defense-specific pitot-static programs with radiation-hardened variants.
Air data systems comprise pitot tubes, static pressure sensors, angle of attack sensors, and air data computers that measure barometric altitude, airspeed, and angle of attack through differential pressure transduction, typically calibrated to operate across temperature extremes from minus 55 degrees Celsius to plus 70 degrees Celsius. These measurements feed flight control computers, autopilot systems, and cockpit displays with real-time aerodynamic state vectors essential for safe aircraft operation. Pitot tubes and air data computers command the largest share of product-type revenue due to their non-negotiable presence on every certified airframe, while MEMS-based sensor technology is gaining traction in unmanned aerial systems where size and power constraints override legacy analog architectures. Commercial airlines represent the most concentrated end-user segment for replacement demand, though defense contractors drive specifications for extreme-environment performance.
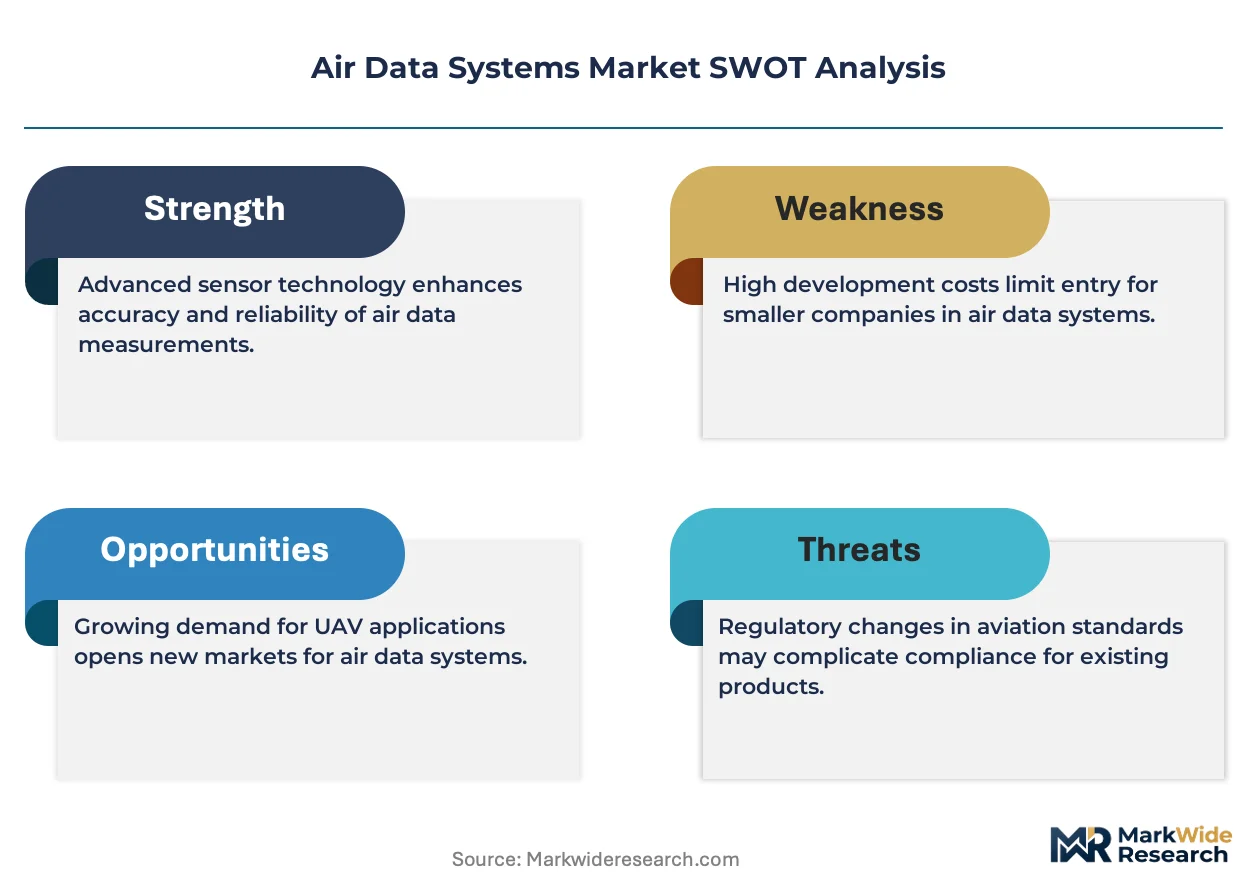
FAA Technical Standard Orders govern pitot-static system certification in the United States, while EASA CS-25 airworthiness codes enforce equivalent standards across European Union member states, and both frameworks are elevating icing-contamination resilience requirements. Compliance with these evolving standards extends development timelines and raises barrier thresholds for new entrants lacking established qualification histories. Stakeholders must monitor how emerging urban air mobility platforms and optionally piloted aircraft will stretch existing certification paradigms beyond traditional manned-aircraft assumptions.
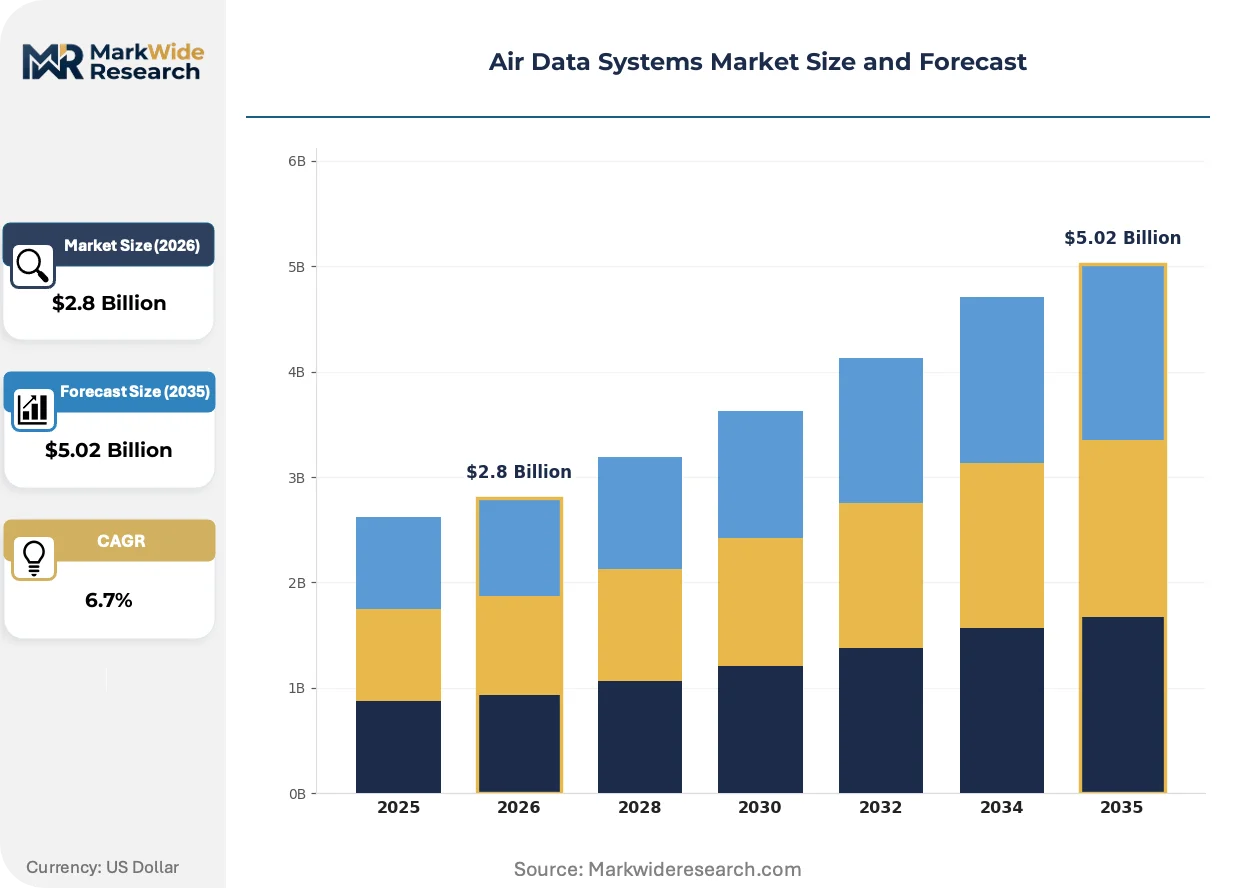
Market Dynamics
Fleet modernization mandates across narrow-body and wide-body platforms are compressing replacement cycles for pitot-static systems, while FAA icing-resilience thresholds and EASA CS-25 airworthiness updates are forcing recertification of legacy architectures.
Growth Catalysts
- FAA Technical Standard Order Updates:Tightened reliability thresholds for pitot-static systems after icing-related incidents are mandating sensor upgrades across in-service fleets.
- MEMS Sensor Miniaturization:Micro-electromechanical pressure transducers are penetrating unmanned aerial systems where size and power constraints override legacy analog designs.
- Defense Prime Procurement:Radiation-hardened air data computer specifications for extreme-environment military platforms are sustaining dual-source contracting volumes.
Market Restraints
- Extended Qualification Timelines:FAA and EASA certification protocols for new sensor architectures stretch development cycles beyond 18 months.
- Specialized Foundry Concentration:European MEMS foundries and North American avionics integrators control qualified supplier access for calibrated air data modules.
- Titanium Alloy Input Volatility:Pitot tube manufacturing depends on aerospace-grade titanium whose spot pricing fluctuates with defense procurement cycles.
Strategic Opportunities
- Urban Air Mobility Certification Gap:Emerging eVTOL platforms in the United States lack established air data system paradigms, creating first-mover qualification advantages.
- Integrated Flight Deck Convergence:Bundling air data computers with inertial reference units is compressing supplier count per airframe.
- India Defense Modernization:Indigenous fighter programs under the country's PLI scheme are localizing pitot-static procurement away from import dependence.
Industry Challenges
- Aerospace Sensor Calibration Expertise Scarcity:Differential pressure transduction engineering talent concentrates among legacy avionics houses with decades of FAA qualification history.
- Legacy System Integration Friction:New MEMS-based architectures must interface with analog flight control computers through signal conditioning layers that add weight and failure modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Data Systems Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pitot Tubes, Static Pressure Sensors, Angle of Attack Sensors, Air Data Computers Technology: Digital, Analog, MEMS, Optical End User: Aerospace Manufacturers, Defense Contractors, Research Institutions, Commercial Airlines Application: Flight Control Systems, Navigation, Weather Monitoring, Test Equipment |
| Companies Covered | Honeywell International, Collins Aerospace, Curtiss-Wright Corporation, AMETEK, Meggitt PLC, Aeroprobe Corporation, Astronautics Corporation of America, Shadin Avionics, Thommen Aircraft Equipment Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Data Systems Market Emerging Trajectories
Sensor fusion architectures are collapsing discrete measurement functions into unified aerodynamic state vectors, while regulatory pressure on icing resilience is accelerating materials science investment in heated probe designs.
MEMS-based pressure transducers are integrating temperature-compensated calibration algorithms directly into sensor dies, eliminating external signal conditioning boards. Unmanned aerial system manufacturers are adopting these chips at pace to hit sub-gram weight budgets. This integration is compressing the traditional air data computer supply chain into single-package solutions.
EASA CS-25 airworthiness codes are elevating icing-contamination resilience requirements for angle-of-attack sensors and pitot tubes operating across European Union member states. Manufacturers must now demonstrate heated probe performance through supercooled large droplet conditions. Wide-body platforms with extended over-water routes are absorbing the steepest compliance costs.
Commercial airlines are unbundling air data system overhaul contracts from full-flight-deck service agreements, creating direct procurement relationships with sensor OEMs. Maintenance, repair, and overhaul channels are losing exclusivity as carriers seek parts traceability. This pattern is most visible in the United States where fleet scale justifies dedicated logistics infrastructure.
Air Data Systems Market Segmentation
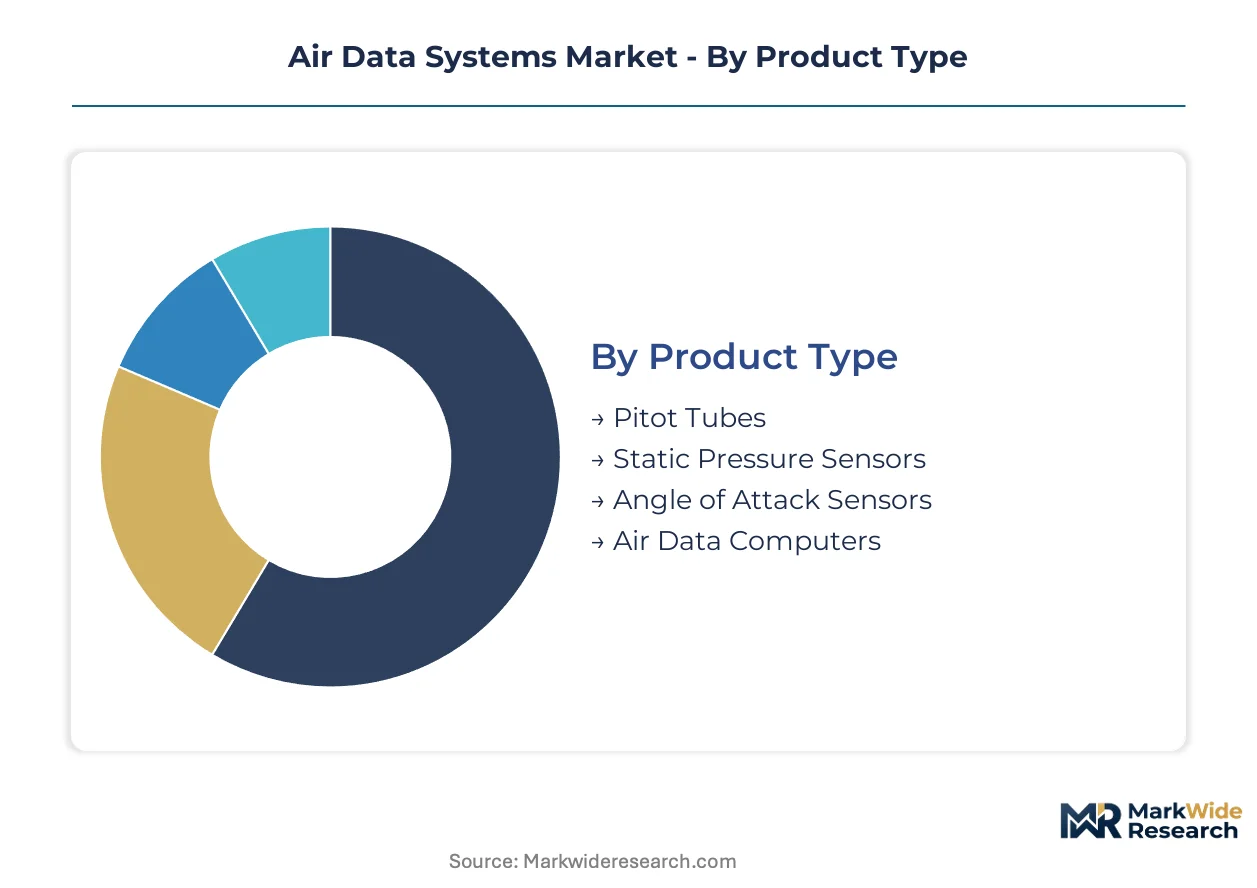
Segmentation in air data systems reveals divergent engineering requirements across manned and unmanned platforms, with integration depth determining whether sensors operate as standalone modules or embedded subsystems within unified flight decks. Procurement patterns split sharply between line-fit installations at airframe assembly and aftermarket replacement cycles driven by FAA-mandated reliability upgrades.
Product Type:
Pitot tubes and air data computers anchor standalone installations with dedicated housing and signal conditioning, while static pressure sensors and angle-of-attack probes increasingly embed into integrated probe architectures.
- Pitot Tubes:These differential pressure probes measure total air pressure through forward-facing orifices, typically machined from aerospace-grade titanium or stainless steel with integrated heating elements. Demand concentrates in United States narrow-body fleet retrofits where FAA icing-resilience mandates are compressing replacement cycles. Titanium alloy input volatility shapes procurement timing.
- Air Data Computers:Centralized processing units convert raw pressure signals into calibrated airspeed, altitude, and Mach number outputs through ARINC 429 digital buses. Defense contractors in the United States drive specifications for radiation-hardened variants sustaining dual-source contracting volumes. Integration with inertial reference units is compressing supplier count per airframe.
- Static Pressure Sensors:Flush-mounted or external probes measure ambient atmospheric pressure for barometric altitude calculation, requiring temperature compensation across minus 55 to plus 70 degrees Celsius operational envelopes.
- Angle of Attack Sensors:Vane or probe-based devices detect airflow incidence angle, with heated configurations now mandatory under EASA CS-25 supercooled large droplet requirements for European-registered wide-body platforms.
Pitot tubes lead volumes today; air data computers are gaining share fastest through flight-deck bundling strategies.
Technology:
Cost tiers separate legacy analog architectures from emerging solid-state designs, with MEMS and optical approaches commanding premium positioning in weight-constrained applications.
- Digital:ARINC 429 and MIL-STD-1553 protocol-based systems dominate commercial and military certified platforms, offering deterministic latency and fault tolerance through redundant channel architectures. Commercial airlines in the United States specify these for fleet-wide standardization.
- MEMS:Micro-electromechanical pressure transducers integrate temperature-compensated calibration algorithms directly into sensor dies, eliminating external signal conditioning. Unmanned aerial system manufacturers adopt these chips at pace to hit sub-gram weight budgets.
- Analog:Voltage-output pressure transducers persist in legacy aircraft with analog flight control computers, requiring signal conditioning layers that add weight and failure modes.
- Optical:Fiber-optic pressure sensors exploit immunity to electromagnetic interference for extreme-environment military platforms, though foundry qualification remains concentrated among European sensor houses.
Digital architectures dominate installed base; MEMS is climbing the fastest as unmanned platform procurement accelerates.
End User:
Customer type determines specification authority, with aerospace manufacturers controlling line-fit decisions while commercial airlines increasingly unbundle overhaul contracts from full-flight-deck service agreements.
- Commercial Airlines:Fleet operators in the United States drive aftermarket replacement demand, seeking direct procurement relationships with sensor OEMs for parts traceability. Maintenance channels are losing exclusivity as carriers justify dedicated logistics infrastructure.
- Defense Contractors:Prime contractors specify radiation-hardened and extreme-environment performance for fighter, transport, and rotary-wing platforms, anchoring dual-source contracting volumes.
- Aerospace Manufacturers:Boeing's supply chain and airframe integrators control line-fit procurement for new production aircraft.
- Research Institutions:National laboratories and university flight-test programs drive low-volume, high-customization orders for experimental aerodynamics research.
Commercial airlines anchor replacement volumes today; defense contractors sustain the steepest specification escalation for hardened variants.
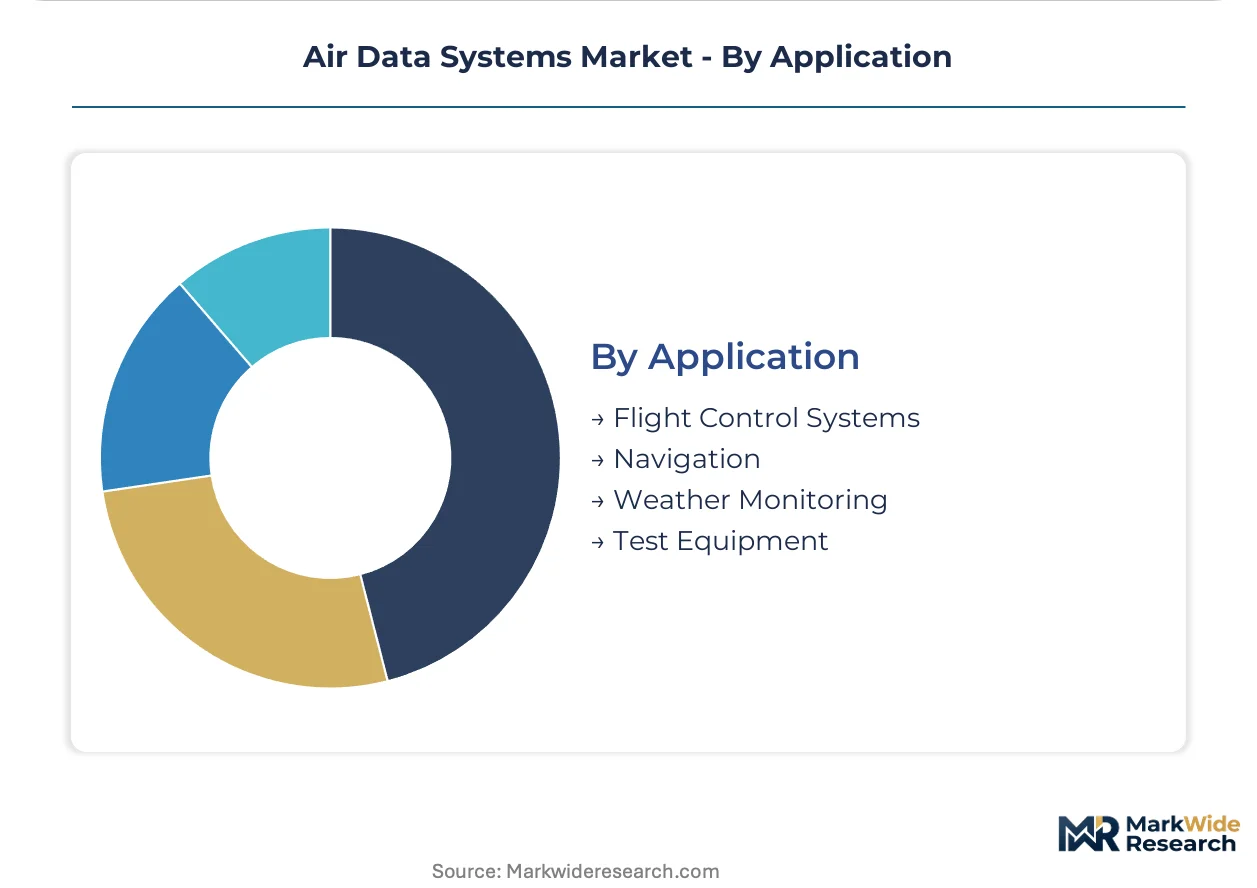
Application:
Functional criticality varies across flight control integration versus auxiliary monitoring, with navigation and weather applications tolerating lower redundancy than primary flight control channels.
- Flight Control Systems:Primary air data feeds to fly-by-wire computers require triple-redundant architectures with dissimilar sensor technologies to prevent common-mode failures. FAA certification thresholds are tightest here.
- Navigation:Barometric altitude and true airspeed inputs to flight management systems support trajectory optimization and fuel burn calculations, with accuracy requirements less stringent than flight control channels.
- Weather Monitoring:Auxiliary air data supports windshear detection and atmospheric research, typically using non-heated probes with reduced qualification burden.
- Test Equipment:Calibration rigs and wind tunnel instrumentation demand traceable reference standards with NIST- or national metrology institute-linked certification chains.
Flight control systems dominate critical-path procurement; navigation applications show the steepest expansion trajectory as trajectory optimization algorithms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers seek qualified foundry access while navigating divergent FAA and EASA certification timelines. Cost-of-compliance gaps between jurisdictions are accelerating supplier migration toward established aerospace clusters.
United States
Boeing's supply chain and defense prime procurement anchor North American demand for pitot-static systems and air data computers. FAA Technical Standard Orders govern certification timelines that stretch beyond eighteen months for new sensor architectures. Seattle-Tacoma and Wichita aerospace corridors concentrate line-fit installations and military specification programs.
Germany
Airbus supply chain integration and regional jet programs sustain demand for EASA CS-25 compliant angle-of-attack sensors. REACH regulation and EU Green Deal carbon accounting requirements are elevating materials traceability standards for titanium alloy inputs. Munich-Stuttgart industrial corridor hosts avionics integrators serving both commercial and defense channels.
France
Dassault Aviation and Thales flight control programs drive specifications for extreme-environment air data systems. EASA supercooled large droplet icing requirements are forcing heated probe redesigns for wide-body platforms serving transatlantic routes. Toulouse aerospace cluster anchors European certification expertise for integrated flight deck architectures.
United Kingdom
BAE Systems defense procurement and Rolls-Royce engine integration programs sustain demand for radiation-hardened variants. Post-Brexit regulatory divergence from EASA frameworks is creating dual-track qualification burdens for suppliers serving both UK and EU-registered fleets. Bristol and Farnborough corridors concentrate flight test and calibration infrastructure.
India
Indigenous fighter programs under the PLI scheme are localizing pitot-static procurement away from import dependence. DGFT licensing requirements and BIS standards are tightening component traceability for defense applications. Bangalore-Hyderabad aerospace corridor is emerging as a maintenance hub for narrow-body fleet retrofits serving South Asian carriers.
Air Data Systems Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue MEMS miniaturization for unmanned platforms and urban air mobility applications. The vendor base stratifies across three tiers: integrated flight deck architects bundling air data computers with inertial reference units; standalone sensor specialists qualifying pitot-static components for aftermarket replacement; and foundry-linked chip designers serving weight-constrained drone manufacturers. Dominant competitive moves include backward integration into MEMS fabrication capacity and strategic partnerships with urban air mobility platforms seeking first-mover certification advantages.
Within the integrated systems tier, Honeywell International and Collins Aerospace exemplify flight-deck bundling strategies that compress supplier count per airframe. Curtiss-Wright Corporation anchors the defense-specific segment through radiation-hardened specifications. Among standalone sensor specialists, Aeroprobe Corporation and Shadin Avionics occupy positions serving aftermarket channels and experimental aircraft programs respectively. AMETEK and Meggitt PLC represent diversified industrial conglomerates with avionics divisions that benefit from cross-divisional manufacturing scale.
| Leading Market Players |
|---|
| Honeywell International |
| Collins Aerospace |
| Curtiss-Wright Corporation |
| AMETEK |
| Meggitt PLC |
| Aeroprobe Corporation |
| Astronautics Corporation of America |
| Shadin Avionics |
| Thommen Aircraft Equipment Ltd |
| Others |
Supply Flow & Price Mechanics
Calibration engineering talent concentrated in the Seattle-Tacoma and Toulouse aerospace corridors feeds directly into tiered labor-cost spreads across pitot-static system pricing. FAA-qualified sensor architects command premium compensation that manufacturers pass through to defense and wide-body line-fit contracts, while MEMS foundry automation in European sensor houses compresses unit economics for unmanned platform suppliers.
Pricing Analysis
Direct-to-OEM channels handle fleet-scale procurement with volume-negotiated discounts off list pricing, while aftermarket distributors retain 15-25 point markups on replacement pitot tubes for narrow-body retrofits. Three-tier pricing structure across premium, standard, and economy levels separates radiation-hardened military specifications from commercial-grade heated probes and unheated legacy variants. Cost compression in the standard tier is intensifying because titanium alloy spot volatility forces foundries to hedge through long-term offtake clauses. Defense contractors show the least price sensitivity due to specification lock-in, while urban air mobility startups negotiate aggressively for MEMS-based single-package solutions.
Supply Chain Analysis
Direct-to-OEM channels anchor demand from Boeing's supply chain and Airbus integration programs, with aftermarket distributors serving fragmented commercial airline procurement. European MEMS foundries in Germany and France, alongside North American avionics integrators in the United States, concentrate qualified supplier access for calibrated air data modules. Raw material dependencies draw from aerospace-grade titanium ingots, high-reliability ceramic substrates for sensor dies, and specialized heating element alloys. Single-source vulnerability persists at the radiation-hardened semiconductor tier where qualified foundry capacity rests on two European sensor houses. Distribution runs through authorized avionics distributors with FAA traceability certification, bypassing general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air data systems market represents a late-cycle quality story where FAA icing-resilience mandates and EASA supercooled large droplet requirements are elevating specification floors toward premium heated probe architectures.
For Market Incumbents: Acquire MEMS fabrication capacity to capture unmanned platform procurement migrating from analog architectures. Consolidate aftermarket distributor relationships before commercial airlines complete direct-to-OEM procurement transitions. Defend against MEMS-first entrants by accelerating integration of temperature-compensated calibration algorithms into legacy product lines. For New Entrants and Emerging Players: Solid-state optical pressure sensing offers a technology-first wedge into extreme-environment military platforms where electromagnetic immunity justifies qualification investment. Urban air mobility certification gaps in the United States present the most penetrable white-space, with sub-gram weight budgets favoring chip-scale MEMS solutions over discrete sensor assemblies. Pursue strategic partnerships with eVTOL developers seeking first-mover FAA qualification advantages rather than competing for established narrow-body retrofit contracts. For Investors and Strategic Acquirers: Flight deck integrators are the most active acquirer in this space, bundling air data computers with inertial reference units to compress supplier count per airframe. Long-term viability centers on qualification moats rather than manufacturing scale, with five-to-ten year windows favoring targets with established FAA Technical Standard Order histories. Monitor EASA CS-25 amendment timelines as the critical inflection signal for heated probe redesign cycles and associated recertification spending.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Capacity Expansion | Captures unmanned platform procurement migrating from legacy analog architectures. |
| FAA TSO Pre-Qualification Investment | Accelerates certification timelines for emerging urban air mobility platforms. |
| Heated Probe Materials Science R&D | Addresses EASA supercooled large droplet requirements for European wide-body fleets. |
| Direct Airline Procurement Channel Development | Bypasses maintenance channel markups as carriers unbundle overhaul contracts. |
| Optical Sensor Foundry Partnership | Accesses European sensor house qualification for extreme-environment military specifications. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged avionics procurement executives at commercial airlines, FAA certification engineers, defense prime subsystem architects, MEMS foundry technical directors, and aftermarket distributor operations heads. Secondary sources included FAA Technical Standard Order filings, EASA CS-25 airworthiness code amendments, customs records for titanium alloy trade flows, and SEC 10-K disclosures from diversified industrial conglomerates with avionics divisions. Bottom-up unit demand estimates triangulated against top-down fleet projection models.
Rate-of-change decomposition structured the analytical framework across the projection horizon, with volume trajectories built from installed base aging curves and replacement cycle compression factors. Segmentation dimensions modeled include product architecture, technology tier, end-user procurement authority, and application criticality, alongside airframe platform generation as an aerospace-specific dimension. CAGRs derived from regression against historical certification-driven replacement waves and fleet modernization program announcements. Forecast inputs incorporated FAA mandate implementation schedules and defense procurement cycle visibility.
The model holds under stable regulatory implementation timelines; deviation in EASA-FAA harmonization delays or titanium supply disruption would shift replacement cycle phasing. Forecasts reflect documented assumptions regarding fleet retirement rates and urban air mobility certification pathway clarity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Global Aircraft Health Monitoring Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Global Flight Inspection Market
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Aircraft Flight Recorder Market
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
United States Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
NDT in the Aerospace and Defense Market
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market