
 NDT in the Aerospace and Defense Market | 2026-2036
NDT in the Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
NDT in the Aerospace and Defense Market Foresight
Space exploration is restructuring procurement priorities for NDT service providers. Baker Hughes Company leverages its oil and gas inspection heritage to compete in rocket propulsion component testing. Waygate Technologies anchors the digital radiography segment with in-house production of high-resolution detector arrays. Olympus Corporation specializes in phased array ultrasonic systems for turbine blade inspection, occupying a defensible niche in Japan and North America.
Non-destructive testing in aerospace and defense encompasses ultrasonic, radiographic, eddy current, and magnetic particle methods that detect subsurface flaws without damaging structural components, typically resolving defects at resolutions below one millimeter depending on the modality and material thickness. These technologies verify the integrity of flight-critical titanium alloys, carbon fiber composites, and nickel-based superalloys before operational deployment. Ultrasonic testing leads the product type landscape due to its portability and established calibration protocols for thick-section airframe joints. Phased array ultrasonic technology within the technology dimension captures the fastest growth trajectory as militaries adopt automated scanning for complex geometries. Digital radiography holds mature margin pools in commercial aviation maintenance hubs where throughput speed determines contract economics.
FAA airworthiness directives and EASA Part 145 maintenance regulations mandate recurring NDT intervals for fatigue-critical structures, directly expanding scheduled inspection volumes across certified repair stations. Military procurement specifications from the US Department of Defense and NATO standardization agreements further require vendor qualification to AS9100 and Nadcap accreditation, raising barriers for uncertified competitors. Stakeholders must monitor how emerging additive manufacturing qualification standards from ISO and ASTM reshape acceptable NDT methodologies for 3D-printed aerospace components.
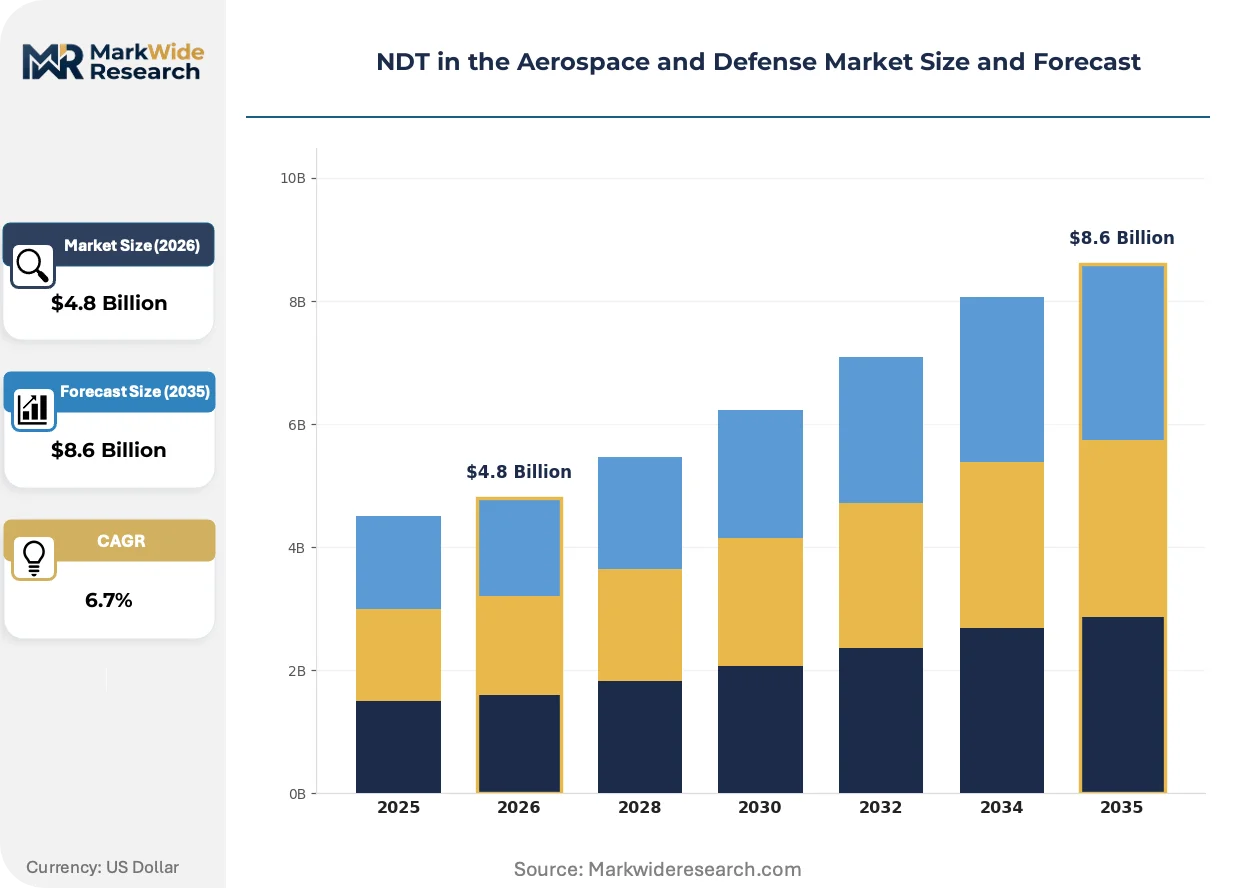
Market Dynamics
Phased array ultrasonic testing is compressing inspection cycles for complex aerospace geometries while FAA and EASA mandates expand mandatory NDT volumes across certified repair stations worldwide.
Growth Catalysts
- FAA Airworthiness Directives:Recurring inspection intervals for fatigue-critical structures expand scheduled maintenance volumes at US-certified repair stations.
- Carbon fiber composite airframes:Boeing 787 and Airbus A350 fleets require specialized ultrasonic protocols, creating dedicated service demand.
- Defense procurement in Germany:NATO standardization agreements and Bundeswehr modernization programs accelerate vendor qualification to AS9100 and Nadcap standards.
Market Restraints
- Helium supply volatility:Digital radiography and leak testing depend on constrained helium reserves, with price spikes affecting contract economics.
- Detector array manufacturing concentration:High-resolution digital radiography sensors concentrate in Japanese and German production facilities, creating single-source vulnerability.
- AS9100D certification timelines:Eighteen-month accreditation cycles for new market entrants delay revenue recognition and tie up working capital.
Strategic Opportunities
- Additive manufacturing qualification:ISO and ASTM standards for 3D-printed aerospace components remain unsettled, opening first-mover advantage for NDT protocol developers.
- Space launch propulsion testing:Reusable rocket programs in the United States require novel thermal protection system inspection methods.
- Automated scanning convergence:Integration of robotic positioning with phased array systems enables unmanned inspection of unmanned aerial vehicle airframes.
Industry Challenges
- Phased array technician scarcity:ASNT Level III certification for complex geometry interpretation requires 2,400 documented hours, constraining field deployment capacity.
- Legacy radiography equipment integration:Film-based systems in military depots resist digital retrofitting due to classified data handling protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NDT in the Aerospace and Defense Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Testing, Radiographic Testing, Eddy Current Testing, Magnetic Particle Testing Application: Aerospace Inspection, Structural Integrity, Component Testing, Quality Assurance Technology: Digital Radiography, Phased Array Ultrasonic, Computerized Tomography, Remote Visual Inspection End User: Commercial Aviation, Military Applications, Space Exploration, Manufacturing Sector |
| Companies Covered | Intertek Group plc, Waygate Technologies, Baker Hughes Company, Acuren, Element Materials Technology, Mistras Group Inc., Applus Services SA, Olympus Corporation, SGS SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NDT in the Aerospace and Defense Market Shifts & Advancements
Computational automation and real-time data processing are restructuring how aerospace manufacturers validate structural integrity across production and maintenance cycles.
Artificial intelligence defect classification is integrating with conventional ultrasonic and radiographic modalities to reduce false-positive rates in automated inspection lines. Tier-one suppliers in the United States and Germany deploy machine learning-assisted phased array systems for turbine blade verification. This convergence is compressing interpretation timelines from hours to minutes while elevating technician productivity thresholds.
EASA Part 145 maintenance regulations now mandate digital record retention for all fatigue-critical NDT results, forcing repair stations to retire paper-based reporting systems. The directive affects commercial aviation hubs in France, the Netherlands, and the United Kingdom most acutely. MRO providers respond by consolidating software platforms to satisfy both European and FAA audit requirements simultaneously.
Service contracting for inspection capacity is fragmenting from long-term sole-source agreements toward multi-vendor panels with performance-based allocation. Airlines in China and the United Arab Emirates now rotate NDT providers based on turnaround time metrics rather than historical relationships. This behavioral shift rewards inspection houses with distributed geographic presence and 24-hour reporting capability.
NDT in the Aerospace and Defense Market Segmentation
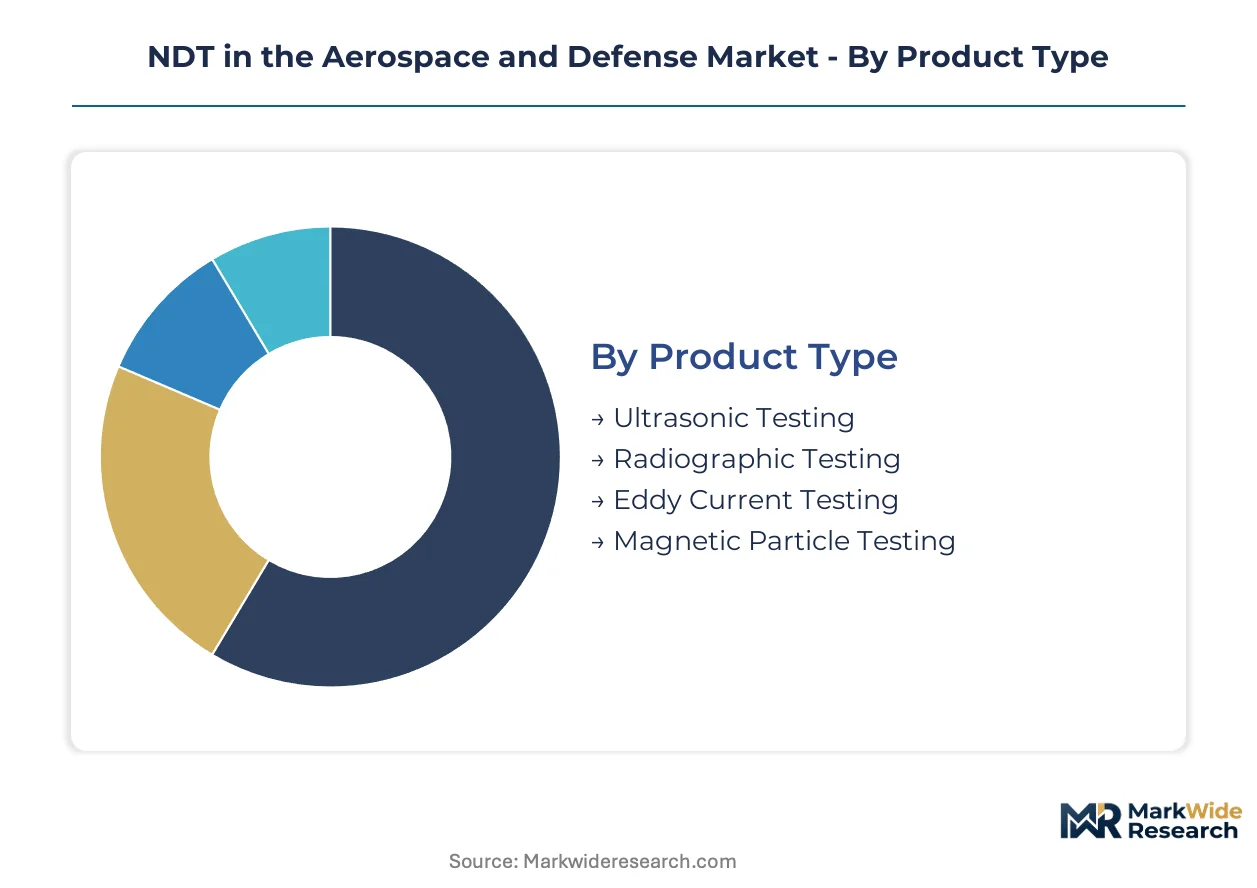
NDT procurement in aerospace and defense fragments across multiple technical dimensions, with upgrade cycles and regulatory recertification driving replacement demand. Equipment refresh timelines vary dramatically by modality, creating distinct revenue windows for vendors serving military depots versus commercial MRO facilities.
Product Type:
Replacement cycles for legacy inspection systems are accelerating as FAA and EASA mandates force retirement of analog equipment that cannot generate compliant digital records.
- Ultrasonic Testing:Portable pulse-echo and through-transmission systems dominate field deployment for thick-section airframe joints. Commercial aviation MRO stations in the United States and Germany standardize on equipment with ASME-compliant calibration protocols, compressing procurement evaluation timelines.
- Radiographic Testing:Film-based and digital systems detect subsurface porosity and cracks in cast turbine components. Military depots resist digital retrofitting due to classified data handling constraints, extending legacy equipment lifecycles beyond commercial norms.
- Eddy Current Testing:Surface and near-surface flaw detection for conductive materials including aluminum skins and fastener holes.
- Magnetic Particle Testing:Ferromagnetic component inspection for landing gear and engine mounts in heavy maintenance environments.
Ultrasonic Testing sits at the top of the volume ranking, with Radiographic Testing climbing the fastest as digital detector arrays displace film in commercial settings.
Application:
Cost tiering separates scheduled maintenance contracts from capital-intensive production-line integration, with margin structures diverging sharply between these procurement modes.
- Aerospace Inspection:Flight-critical airframe and engine examinations mandated by airworthiness directives. Airlines in China and the United Arab Emirates now rotate providers based on turnaround metrics rather than historical relationships.
- Structural Integrity:Fatigue monitoring and damage tolerance assessment for aging fleets. Boeing 787 and Airbus A350 carbon fiber composite airframes require specialized ultrasonic protocols, creating dedicated service demand.
- Component Testing:Individual part verification before assembly into larger systems.
- Quality Assurance:Process control during manufacturing rather than post-production verification.
Aerospace Inspection commands the highest contract values, while Structural Integrity is expanding most quickly as fleet age profiles deepen across North America and Europe.
Technology:
Customer type segmentation reveals divergent technology adoption patterns between military specification-driven procurement and commercial aviation efficiency optimization.
- Digital Radiography:High-resolution detector arrays replace film cassettes in maintenance hubs where throughput speed determines contract economics. Japanese and German sensor manufacturing concentration creates single-source vulnerability for repair station supply chains.
- Phased Array Ultrasonic:Electronic beam steering enables automated scanning of complex geometries without mechanical probe repositioning. US Department of Defense and NATO standardization agreements accelerate vendor qualification to Nadcap accreditation standards.
- Computerized Tomography:Volumetric reconstruction for additive manufactured components with complex internal features.
- Remote Visual Inspection:Borescope and robotic camera systems for confined space examination.
Digital Radiography maintains mature margin pools in commercial hubs, with Phased Array Ultrasonic gaining share fastest as militaries automate complex geometry inspection.
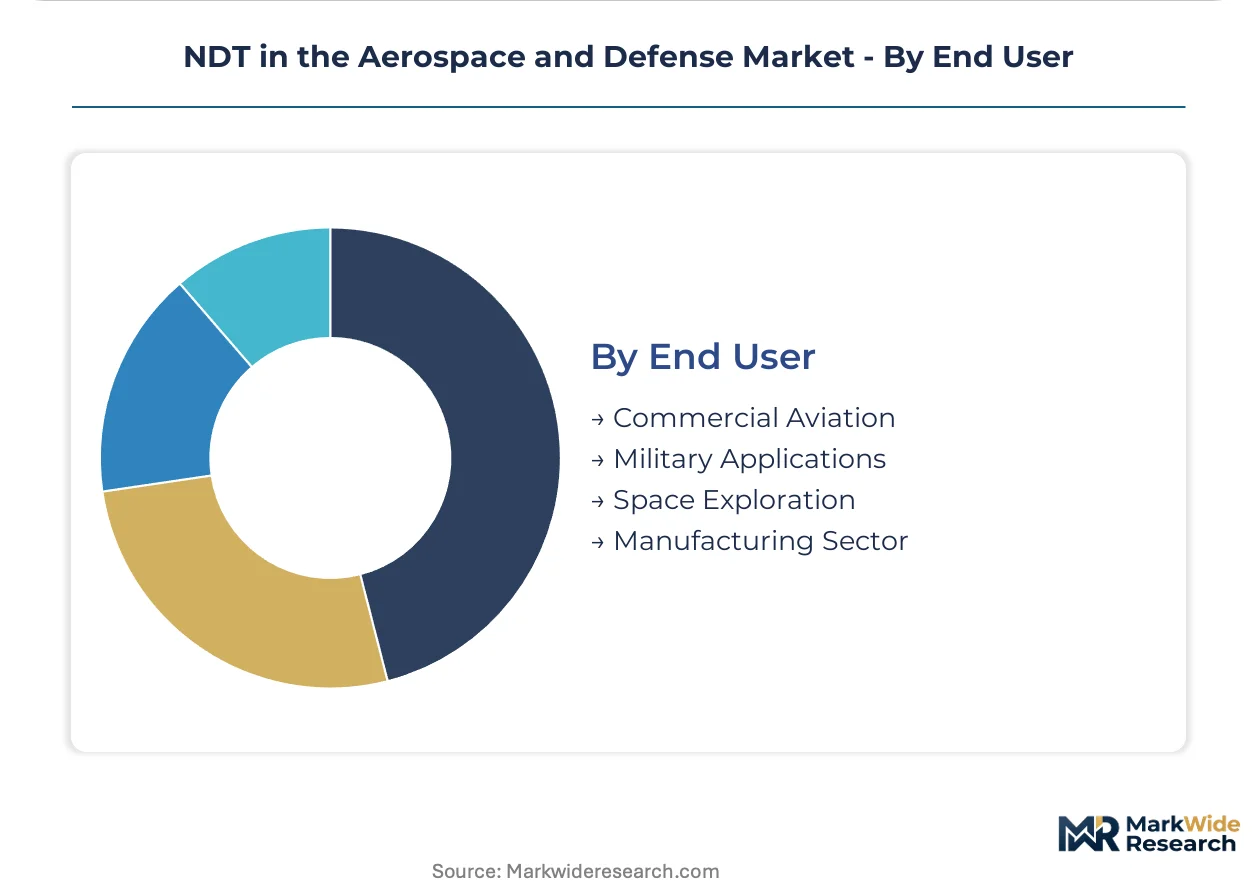
End User:
Geographic concentration of demand centers on defense procurement corridors and commercial aviation maintenance clusters with distinct regulatory compliance requirements.
- Commercial Aviation:Scheduled maintenance and unscheduled damage assessment for airline and lessor fleets. EASA Part 145 regulations now mandate digital record retention for fatigue-critical results, forcing repair stations in France, the Netherlands, and the United Kingdom to retire paper systems.
- Military Applications:Platform sustainment and overhaul programs governed by AS9100D and Nadcap accreditation. Bundeswehr modernization in Germany and NATO standardization agreements tighten vendor qualification cycles.
- Space Exploration:Reusable rocket propulsion and thermal protection system validation for launch vehicle programs.
- Manufacturing Sector:Production-line quality control for tier-one and tier-two suppliers.
Commercial Aviation anchors procurement volumes, with Space Exploration representing the steepest expansion trajectory as reusable launch programs scale in the United States.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where aerospace NDT providers establish certified facilities, with compliance cost differentials between jurisdictions driving investment toward markets offering faster accreditation timelines and clustered defense procurement corridors.
United States
FAA airworthiness directives mandate recurring inspection intervals for fatigue-critical structures, expanding scheduled maintenance volumes at certified repair stations. The Department of Defense and NASA procurement specifications require AS9100D and Nadcap accreditation, tightening vendor qualification cycles. Seattle-Tacoma and Wichita clusters concentrate Boeing and Spirit AeroSystems supplier networks, driving localized demand for ultrasonic and radiographic testing capacity.
Germany
Bundeswehr modernization programs and NATO standardization agreements accelerate defense procurement for platform sustainment and overhaul. EASA Part 145 maintenance regulations enforce digital record retention for fatigue-critical NDT results, forcing repair stations to retire paper-based systems. The Bavaria and Baden-Württemberg industrial corridors host Airbus Defence and Space operations alongside MTU Aero Engines, creating dense supplier ecosystems for phased array ultrasonic services.
China
Commercial aviation fleet expansion and indigenous airframe programs generate dedicated demand for carbon fiber composite inspection protocols. The country's national aviation regulator enforces airworthiness certification parallel to FAA and EASA frameworks, though accreditation timelines remain compressed relative to Western standards. The Yangtze River Delta and Beijing-Tianjin-Hebei clusters concentrate COMAC final assembly and tier-one supplier facilities, attracting regional NDT service investment.
United Kingdom
EASA Part 145 regulations post-Brexit transition maintain alignment with European digital record retention mandates for commercial aviation MRO. The national defense procurement office specifies AS9100 and Nadcap accreditation for platform sustainment contracts. The Midlands and Southwest England clusters host Rolls-Royce engine manufacturing and BAE Systems airframe assembly, sustaining localized demand for eddy current and magnetic particle testing capacity.
Japan
Domestic aerospace supply chains serving Boeing and Airbus tier-one contracts require specialized ultrasonic protocols for titanium alloy and superalloy components. METI industrial standards coordinate with ISO frameworks for additive manufacturing qualification, opening protocol development opportunities. The Chubu-Nagoya and Kanto-Tokyo clusters concentrate Mitsubishi Heavy Industries and Kawasaki Heavy Industries operations, anchoring regional NDT service demand.
NDT in the Aerospace and Defense Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to bridge capability gaps without absorbing eighteen-month AS9100D certification timelines. The vendor base fragments across four distinct tiers: multinational inspection houses with Nadcap-accredited global networks, regional specialists serving single-country defense procurement, equipment manufacturers backward-integrating into service provision, and emerging automated scanning integrators. Portfolio diversification and technology licensing represent the dominant competitive moves, with equipment producers licensing detector array designs to service providers and inspection houses acquiring software platforms for digital record compliance.
Within the multinational inspection house tier, Intertek Group plc, SGS SA, and Element Materials Technology exemplify the geographic scale and accreditation breadth required for NATO and US Department of Defense vendor qualification. Waygate Technologies and Olympus Corporation occupy positions as equipment-originators with captive service networks, leveraging in-house production of high-resolution detector arrays and phased array ultrasonic systems respectively. Baker Hughes Company represents the cross-sector archetype, transferring oil and gas inspection heritage into rocket propulsion component testing for space exploration programs.
| Leading Market Players |
|---|
| Intertek Group plc |
| Waygate Technologies |
| Baker Hughes Company |
| Acuren |
| Element Materials Technology |
| Mistras Group Inc. |
| Applus Services SA |
| Olympus Corporation |
| SGS SA |
| Others |
Supply & Pricing Matrix
EASA Part 145 digital record retention mandates gate both qualified supply and premium-tier pricing access, as repair stations in France and the Netherlands must retire paper-based systems to maintain certification. This regulatory filter compresses procurement timelines for AS9100D-accredited providers while elevating pricing power for inspection houses with compliant software platforms and Nadcap-accredited facilities.
Pricing Analysis
Distributor margins for digital radiography detector arrays concentrate in the 15-25% range for Japanese and German sensor channels, while direct-to-OEM phased array ultrasonic contracts command volume discounts tied to multi-year fleet service agreements. Pricing stratifies across Nadcap-accredited premium tiers, AS9100D-compliant standard tiers, and uncertified economy service providers. Cost compression in the economy tier intensifies because Chinese MRO providers now rotate vendors based on turnaround metrics rather than historical relationships. Airlines in the United Arab Emirates exhibit the highest price sensitivity for scheduled maintenance contracts, whereas US Department of Defense procurement shows minimal elasticity due to mandated vendor qualification requirements.
Supply Chain Analysis
Dual-sourcing requirements from Boeing and Airbus tier-one suppliers mandate multi-supplier qualification for high-resolution detector arrays, forcing repair stations to maintain relationships with both Japanese and German sensor manufacturers. Supply concentrates in Japan, Germany, and the United States for phased array ultrasonic transducers, digital radiography sensors, and helium for leak testing respectively. The supply chain draws from constrained helium reserves, rare earth elements for piezoelectric crystals, and specialized semiconductor substrates for detector fabrication. Single-source vulnerability in Japanese and German sensor manufacturing creates structural risk for repair station supply chains. Distribution runs through certified repair station networks, OEM service subsidiaries, and independent inspection houses with Nadcap accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
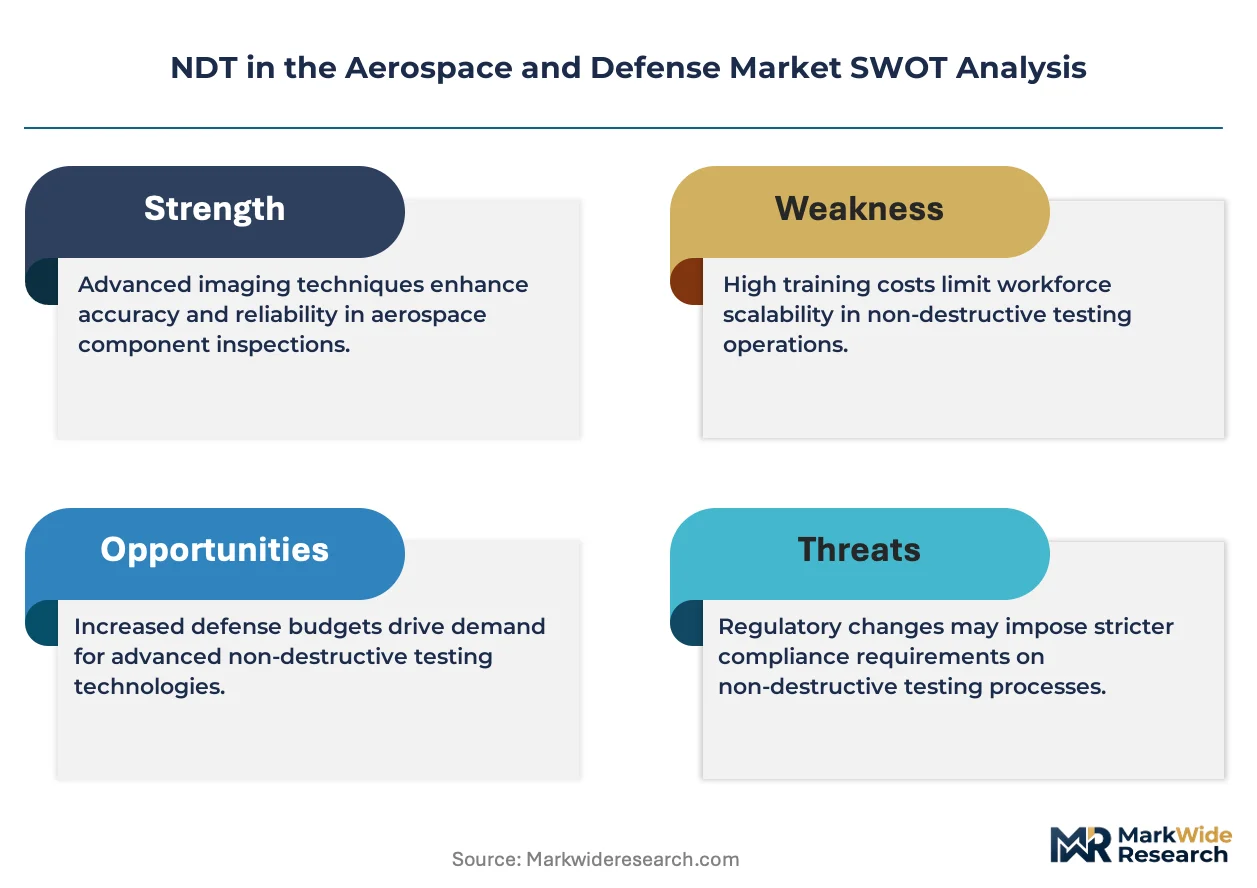
This market functions as a regulatory compounder where FAA airworthiness directives and EASA safety mandates continuously expand mandatory inspection volumes, embedding recurring revenue streams for qualified providers.
For Market Incumbents: Deepen backward integration into high-resolution detector array production to reduce exposure to Japanese and German single-source concentration. Expand Nadcap-accredited capacity in the Yangtze River Delta to capture COMAC fleet growth. The threat of automated scanning integrators with robotic positioning capabilities demands preemptive capability investment in unmanned inspection protocols for UAV airframes. For New Entrants and Emerging Players: Launch via additive manufacturing qualification services for 3D-printed aerospace components, where ISO and ASTM standards remain unsettled and first-mover advantage persists. Target space exploration propulsion testing in the United States, where reusable rocket programs require novel thermal protection system inspection methods absent established vendor relationships. The most penetrable segment is automated scanning integration for unmanned aerial vehicle airframes, where ASNT Level III technician scarcity constrains incumbent deployment capacity. For Investors and Strategic Acquirers: Roll-up economics work for regional inspection houses with AS9100D accreditation because eighteen-month certification timelines create artificial scarcity and captive customer relationships. Long-term viability centers on consolidation of software platforms for digital record compliance, as EASA and FAA audit convergence forces repair stations toward unified reporting systems. The signal to watch is helium supply price volatility, which would compress margins for digital radiography-dependent providers and accelerate substitution toward ultrasonic alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Nadcap Accreditation Investment | AS9100D certification opens US Department of Defense and NATO procurement channels. |
| Phased Array Ultrasonic Capability Expansion | Electronic beam steering captures military automation contracts for complex geometry inspection. |
| Digital Radiography Detector Array Backward Integration | In-house sensor production mitigates Japanese and German single-source supply risk. |
| Additive Manufacturing Qualification Protocol Development | ISO/ASTM standard uncertainty creates first-mover advantage in 3D-printed component testing. |
| Automated Scanning Platform Integration | Robotic positioning with phased array systems addresses ASNT Level III technician scarcity constraints. |
Research Methodology
Bottom-up aerospace MRO demand modeling reconciled against top-down equipment manufacturer shipment tracking forms the analytical core of this study. Primary interviews with ASNT Level III certified technicians, Nadcap audit program managers, airline procurement directors, and defense platform sustainment officers combined with secondary validation against FAA airworthiness directive databases, EASA Part 145 regulatory filings, and AS9100D certification registries. The approach triangulates inspection volume data from certified repair stations with vendor qualification timelines from accreditation bodies.
Input-output matrices map ultrasonic, radiographic, eddy current, and magnetic particle equipment deployment across commercial aviation, military applications, space exploration, and manufacturing end uses throughout the forecast period. Segmentation dimensions include product type, application, technology, and end user, with CAGRs derived from regression analysis against fleet age profiles and regulatory mandate expansion rates. Industry-specific forecast inputs incorporate Boeing 787 and Airbus A350 carbon fiber composite inspection protocol adoption curves and Bundeswehr modernization program procurement schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under helium supply disruption scenarios or accelerated additive manufacturing qualification standard settlement. Projections reflect assumptions regarding FAA and EASA regulatory enforcement continuity and defense procurement authorization levels. Deviation in phased array technician certification throughput would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Air Data Testers Market
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
Flight Data Monitoring and Analysis (FDMA) Market
Aircraft Data and Diagnostics
Global Aircraft Health Monitoring Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Global Connected Aircraft Solutions Market
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Aviation Analytics Market