
 Attitude and Heading Reference System (AHRS) Market | 2026-2036
Attitude and Heading Reference System (AHRS) Market Size, Share, and Industry Trends Forecast 2026-2036
Attitude and Heading Reference System (AHRS) Market Intelligence
Modular sensor packaging is hardening as the dominant procurement preference, with buyers favoring integrated modules over discrete component assemblies. Honeywell International Inc. leverages its aerospace heritage to sustain dominance in ring laser gyroscope platforms. Safran S.A. competes through European defense channels with specialized fiber optic systems. Garmin Ltd. anchors the general aviation segment with compact, commercially certified units.
An Attitude and Heading Reference System computes orientation using gyroscopes, accelerometers, and magnetometers to deliver pitch, roll, and heading data with precision typically exceeding 0.1 degrees per hour drift. Strapdown architectures have displaced gimbaled platforms across most new installations due to lower mechanical complexity and maintenance burden. Microelectromechanical Systems technology leads volume shipments in unmanned vehicles and robotics, where size and power constraints dominate selection criteria. Fiber Optic Gyroscope and Ring Laser Gyroscope categories retain premium positioning in defense aerospace applications where jamming resistance and accuracy thresholds are non-negotiable.
FAA Part 25 airworthiness standards and EU MDR-equivalent aerospace directives shape product certification timelines and testing expenditure for manufacturers seeking commercial or dual-use market access. Military procurement channels impose additional compliance layers through NIST traceable calibration and ITAR-controlled component restrictions. Stakeholders must monitor evolving urban air mobility certification frameworks and unmanned traffic management integration requirements as these emerging regulatory domains will determine which sensor architectures achieve design-lock positions in next-generation platforms.
Market Dynamics
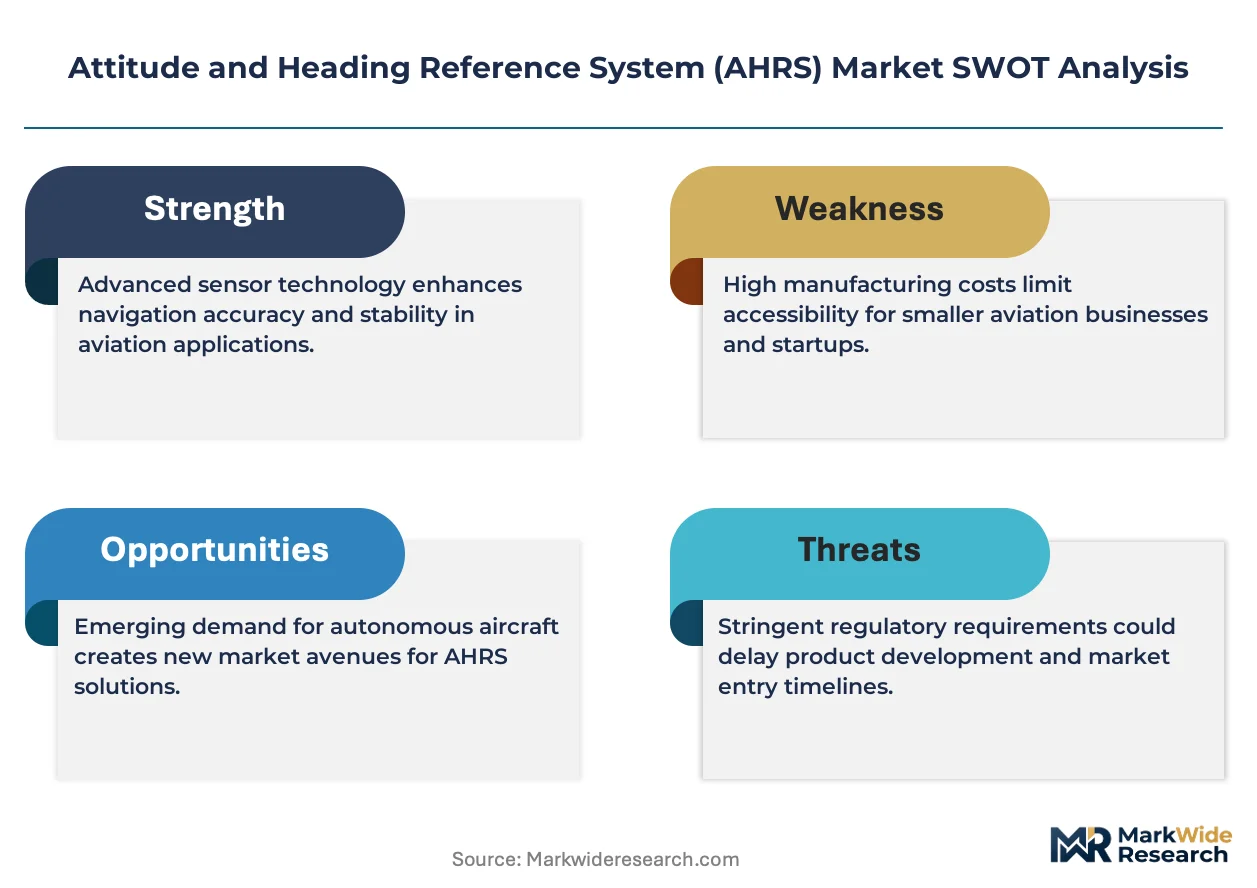
Strapdown MEMS architectures are compressing cost structures across unmanned platforms while FAA Part 25 certification timelines extend lead times for commercial aviation entrants.
Growth Catalysts
- Urban Air Mobility Certification:FAA's Special Class Airworthiness Criteria for powered-lift aircraft is creating dedicated sensor procurement channels for eVTOL developers in the United States.
- Defense Robotics Modernization:Unmanned ground vehicle programs across NATO member states are specifying hardened AHRS units for navigation-denied environments.
- ITAR-Controlled Component Flows:Restricted technology transfer protocols are concentrating premium fiber optic gyroscope production within domestic supply bases, insulating qualified vendors from price-based competition.
Market Restraints
- Precision Quartz Substrate Supply:Ring laser gyroscope manufacturing depends on specialized fused silica boules sourced from limited European and Japanese suppliers, exposing production schedules to geological-grade material scarcity.
- Dual-Use Export Licensing:State Department ITAR classifications impose 90-180 day review cycles on international shipments, freezing order-to-delivery timelines for non-domestic defense customers.
- MEMS Temperature Drift Limitations:Silicon-based inertial sensors exhibit heading error accumulation beyond 0.5 degrees per minute in thermally uncontrolled environments, disqualifying them from manned commercial aviation primary navigation roles.
Strategic Opportunities
- Autonomous Maritime Surface Vessels:Uncrewed cargo and survey ships operating in GPS-denied polar regions require magnetometer-aided AHRS configurations with ice-hardened packaging.
- EU MDR-Aligned Aerospace Directives:Convergence between medical device and aviation sensor quality standards is opening cross-certified manufacturing facilities for dual-use component suppliers in Germany and France.
- AI-Assisted Sensor Fusion:Machine learning error-correction algorithms running on edge compute modules are enabling lower-grade MEMS hardware to achieve navigation-grade performance thresholds.
Industry Challenges
- Calibration Technician Scarcity:NIST-traceable inertial test facility operation requires specialized expertise in laser interferometry and gravitational modeling, with qualified personnel concentrated at defense contractor and national laboratory sites.
- Legacy Platform Integration:ARINC 429 and MIL-STD-1553 data bus architectures in existing aircraft fleets constrain adoption of modern Ethernet-based AHRS outputs without expensive avionics retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Attitude and Heading Reference System (AHRS) Market |
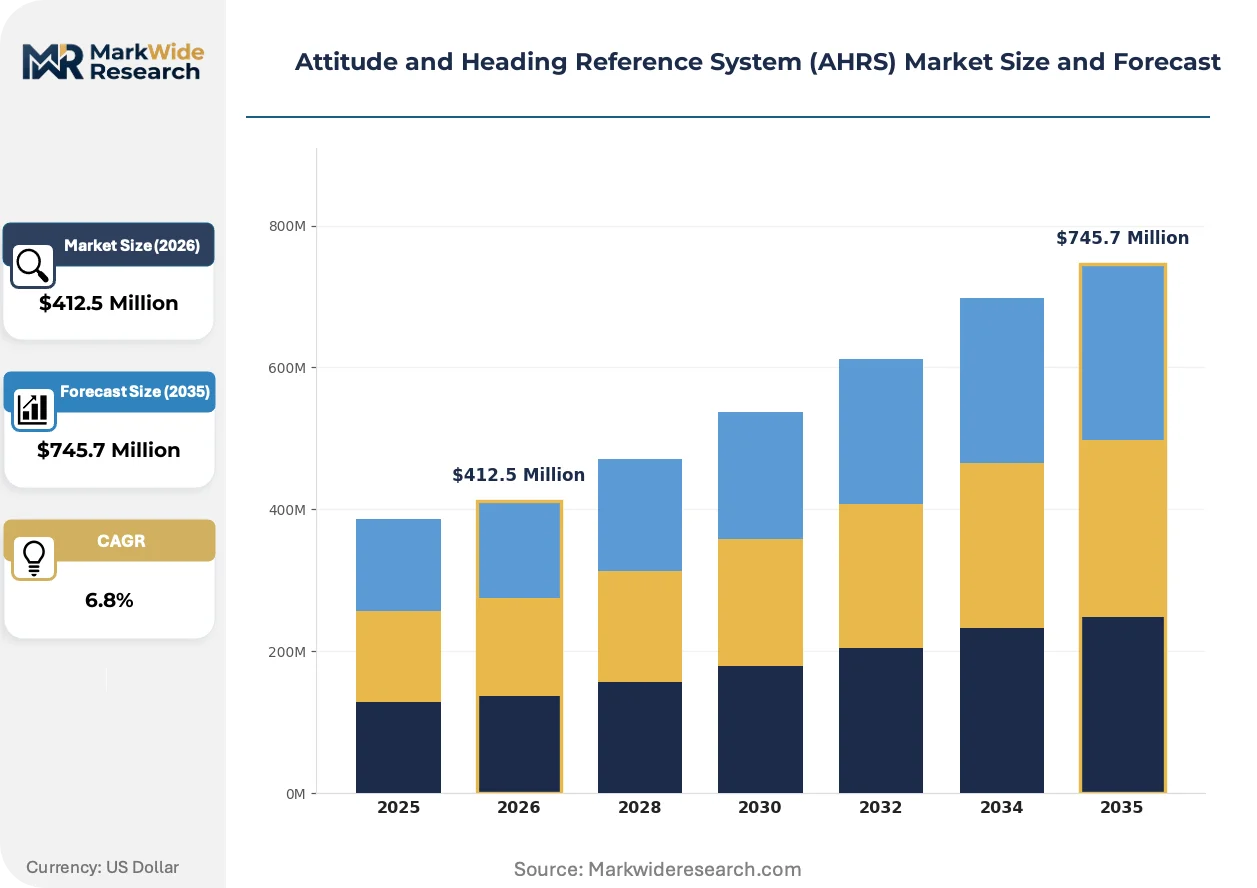
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gyroscopes, Accelerometers, Magnetometers, Integrated Modules Technology: Strapdown, Fiber Optic Gyroscope, Ring Laser Gyroscope, Microelectromechanical Systems Application: Aerospace, Marine Navigation, Unmanned Vehicles, Defense Systems, Robotics End User: Aircraft Manufacturers, Marine Operators, Drone Manufacturers, Military Organizations |
| Companies Covered | Garmin Ltd., L3Harris Technologies Inc., Honeywell International Inc., Moog Inc., Safran S.A., Northrop Grumman Corporation, Collins Aerospace, KVH Industries Inc., Thales S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Attitude and Heading Reference System (AHRS) Market Strategic Shifts & Innovations
Sensor miniaturization is intersecting with artificial intelligence at the edge, compressing the performance gap between tactical-grade MEMS and navigation-grade optical gyroscopes across emerging application categories.
Photonic integrated circuit technology is absorbing waveguide functions previously implemented in discrete fiber coils. Urban air mobility developers in the United States are piloting chip-scale fiber optic gyroscope prototypes for weight-critical eVTOL platforms. This convergence is absorbing the traditional size advantage of MEMS while preserving the jamming immunity of optical architectures.
EU MDR-equivalent aerospace directives are tightening traceability requirements for flight-critical sensor calibration records. Manufacturers must now maintain 25-year data retention for accelerometer and gyroscope bias stability measurements. European defense procurement channels are responding by consolidating supplier qualification audits under EASA oversight frameworks.
Defense primes are unbundling sensor hardware from integration services, shifting procurement toward catalog-specified units with standardized mechanical and electrical interfaces. This disintermediation is compressing traditional systems integrator margins while elevating component-level certification value. The United States Army's Future Vertical Lift program exemplifies this pattern through its modular open systems approach specifications.
Attitude and Heading Reference System (AHRS) Market Segmentation
AHRS procurement channels diverge sharply across certification tiers, with FAA Part 25 commercial aviation imposing validation timelines that stretch 18-24 months longer than tactical-grade military specifications. Segmentation reveals how sensor architectures, application environments, and end-user compliance burdens create distinct competitive arenas with incompatible cost structures and technical requirements.
Product Type:
FAA Part 25 certification requirements concentrate most heavily on integrated modules, while discrete component procurement dominates defense robotics programs with looser validation protocols.
- Integrated Modules:Compact units combine gyroscopic, accelerometric, and magnetic sensing in sealed packages with ARINC 429 or Ethernet outputs. Urban air mobility developers in the United States specify these for eVTOL platforms where weight and wiring minimization override discrete component flexibility.
- Gyroscopes:Single-axis and multi-axis rotational sensors provide the foundational angular rate data for attitude computation. Fiber optic and ring laser variants command premium positioning in defense aerospace applications where jamming resistance is non-negotiable.
- Accelerometers:MEMS-based linear acceleration sensors measure specific force along orthogonal axes to enable gravity-referenced pitch and roll determination. Drone manufacturers favor these for cost-sensitive platforms with limited thermal control budgets.
- Magnetometers:Three-axis magnetic field sensors deliver heading reference by detecting Earth field orientation, requiring careful installation远离 ferrous structures. Marine operators specify magnetometer-aided configurations for GPS-denied polar navigation.
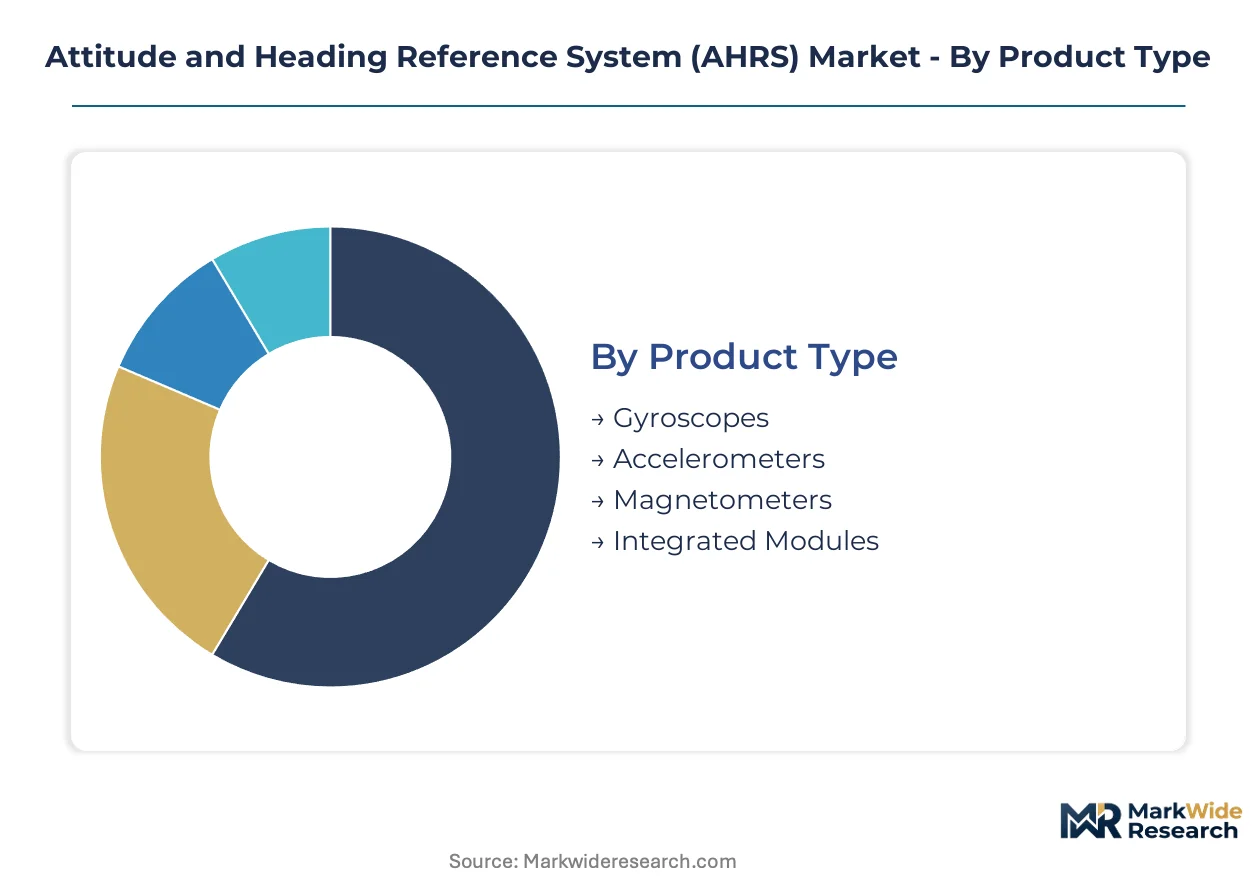
Integrated modules sit at the top of the volume ranking, with gyroscopes climbing the fastest as defense primes unbundle sensor hardware from integration services.
Technology:
Cost tier stratification separates navigation-grade optical platforms from tactical-grade silicon alternatives, with procurement budgets determining acceptable drift performance thresholds.
- Microelectromechanical Systems:Silicon-fabricated inertial sensors achieve sub-dollar unit costs at volume but exhibit heading error accumulation beyond acceptable limits for manned commercial aviation. Robotics and consumer drone applications absorb the majority of MEMS AHRS shipments.
- Fiber Optic Gyroscope:Light interference through coiled optical fiber detects rotation without moving parts, delivering navigation-grade stability with no warm-up time. Safran S.A. and Northrop Grumman compete through European and United States defense channels with ITAR-controlled variants.
- Strapdown:Computational architectures replace mechanical gimbals with fixed sensor mounting and real-time attitude propagation algorithms. Strapdown implementations now dominate all new installations across every technology tier due to reduced mechanical complexity.
- Ring Laser Gyroscope:Cavity laser interference measures rotation through frequency splitting between counter-propagating beams, achieving the highest precision for strategic-grade applications. Honeywell International Inc. sustains dominance through aerospace heritage and NIST-traceable calibration infrastructure.
MEMS technology commands the highest shipment volumes, with fiber optic gyroscope architectures gaining share fastest in urban air mobility and defense robotics segments.
Application:
Environmental severity determines packaging requirements, with marine and unmanned vehicle installations demanding hardened enclosures that aerospace cabins rarely require.
- Unmanned Vehicles:Autonomous aerial, ground, and maritime platforms specify compact AHRS units with minimal power draw and rapid initialization. NATO member state defense programs are expanding procurement for navigation-denied environment operations.
- Aerospace:Manned commercial and military aircraft impose the most stringent certification burdens, with FAA Part 25 and EASA CS-25 standards requiring extensive environmental qualification and failure mode analysis. Urban air mobility powered-lift aircraft are creating new certification categories.
- Defense Systems:Weapons platforms and tactical vehicles prioritize jamming immunity and radiation hardness over absolute precision, with ITAR restrictions concentrating supply within domestic vendor bases.
- Marine Navigation:Surface vessels and submersibles operate in high-humidity, salt-spray environments with magnetic interference from hull structures. Autonomous cargo ships in polar regions require ice-hardened packaging and magnetometer redundancy.
- Robotics:Industrial and field robotics applications tolerate higher drift rates in exchange for cost minimization and rapid replacement availability. Warehouse automation and agricultural robotics are emerging volume channels.
Aerospace generates the highest revenue per unit, with unmanned vehicles expanding most quickly across defense and commercial procurement channels.
End User:
Customer type dictates contract structures, with military organizations imposing multi-year qualification requirements that aircraft manufacturers compress through delegated production authority frameworks.
- Aircraft Manufacturers:Boeing, Airbus, and emerging eVTOL developers specify AHRS as line-fit equipment with supplier-managed certification packages. FAA Organization Designation Authorization streamlines approval for established vendor relationships.
- Military Organizations:United States Department of Defense and NATO procurement channels require NIST-traceable calibration, ITAR compliance, and 25-year data retention for flight-critical sensors. Defense primes are shifting toward modular open systems approach specifications.
- Drone Manufacturers:Commercial and defense unmanned aerial vehicle producers prioritize unit cost and supply security over navigation-grade performance. Chinese and Israeli drone OEMs dominate volume procurement with MEMS-based architectures.
- Marine Operators:Commercial shipping lines and naval fleets specify AHRS for integrated bridge systems with redundant heading sources. Autonomous vessel developers in Norway and Singapore are piloting magnetometer-aided configurations for uncrewed operations.
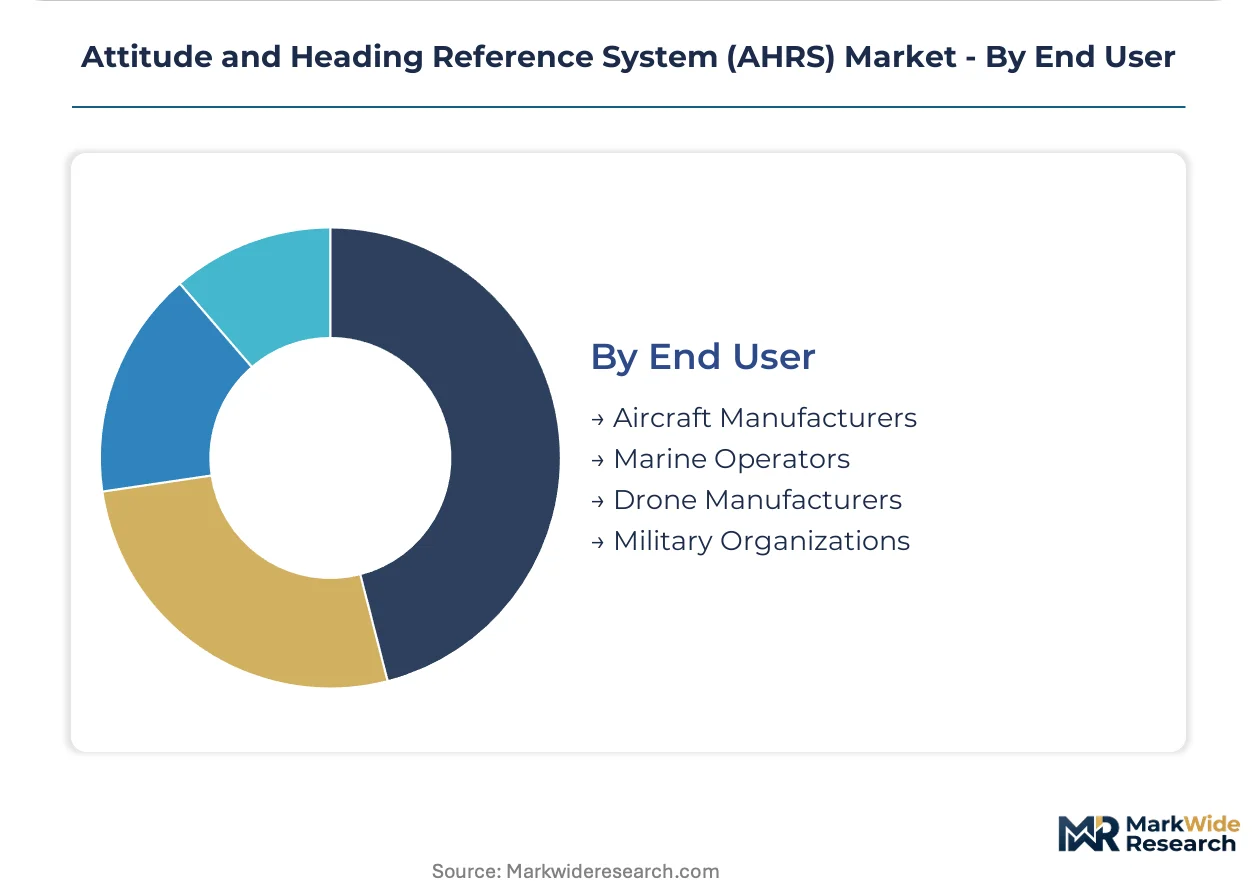
Aircraft manufacturers sit at the top of the volume ranking, with drone manufacturers climbing the fastest as urban air mobility and defense robotics programs accelerate sensor integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The AHRS industry traces its commercial origins to United States aerospace contractors that developed ring laser gyroscope platforms for military aircraft during the Cold War era. This heritage established American dominance in navigation-grade optical systems. Defense modernization programs and emerging urban air mobility frameworks now concentrate demand across specific national markets.
United States
The United States hosts the largest AHRS procurement channels through military modernization and FAA-certified urban air mobility initiatives. The FAA's Special Class Airworthiness Criteria for powered-lift aircraft creates dedicated sensor certification pathways for eVTOL developers. California and Texas aerospace clusters concentrate Honeywell and Northrop Grumman production facilities serving defense and commercial aviation.
France
France maintains strategic positioning in fiber optic gyroscope manufacturing through defense-aerospace integration. EASA oversight frameworks govern supplier qualification audits for flight-critical sensor calibration records. The Paris-Saclay and Toulouse aerospace corridors host Safran S.A. operations specializing in ITAR-controlled variants for NATO procurement.
Germany
Germany's industrial base supports dual-use component manufacturing aligned with EU MDR-equivalent aerospace directives. The country's national aviation regulator enforces 25-year data retention requirements for accelerometer and gyroscope bias stability measurements. Bavaria and Baden-Württemberg host precision optics suppliers serving European defense primes.
Japan
Japan supplies specialized fused silica boules essential for ring laser gyroscope manufacturing, creating geological-grade material dependencies. METI industrial policy supports domestic precision substrate production for strategic aerospace components. Nagoya and Tokyo metropolitan areas concentrate precision ceramics and optical fiber suppliers.
United Kingdom
The United Kingdom participates in NATO unmanned vehicle programs specifying hardened AHRS units for navigation-denied environments. The country's national defense procurement office imposes NIST-traceable calibration requirements on flight-critical sensors. Bristol and Cambridge technology clusters host sensor fusion and edge computing research for AI-assisted error correction.
Attitude and Heading Reference System (AHRS) Market Key Industry Players
The competitive structure tilts toward heritage aerospace conglomerates with NIST-traceable calibration infrastructure and ITAR compliance capabilities. Three strategic archetypes dominate: ring laser gyroscope specialists with decades-long aerospace heritage, fiber optic platform vendors competing through European defense channels, and compact MEMS suppliers anchoring general aviation and unmanned vehicle segments. M&A activity concentrates on acquiring calibration facility assets, while strategic partnerships target urban air mobility certification bundling.
Among heritage-tier vendors, Honeywell International Inc., Safran S.A., and Northrop Grumman Corporation exemplify the divergence between American and European defense-aerospace supply bases. Honeywell occupies a position representing ring laser gyroscope dominance through aerospace heritage. Safran S.A. exemplifies European fiber optic specialization through defense channel concentration. Northrop Grumman sits within the ITAR-controlled vendor archetype serving domestic military procurement. Garmin Ltd. represents the compact commercially certified segment anchoring general aviation volume.
| Leading Market Players |
|---|
| Garmin Ltd. |
| L3Harris Technologies Inc. |
| Honeywell International Inc. |
| Moog Inc. |
| Safran S.A. |
| Northrop Grumman Corporation |
| Collins Aerospace |
| KVH Industries Inc. |
| Thales S.A. |
| Others |
Cost & Logistics Intelligence
Fused silica boule pricing indices from Japanese and European suppliers cascade through ring laser gyroscope manufacturing into three distinct procurement tiers, compressing margins at the premium navigation-grade level while MEMS volume economics reshape economy-tier contracting.
Pricing Analysis
Certification-grade pricing stratification across FAA Part 25, ITAR-controlled military, and tactical-grade commercial tiers anchors contract structures, with NIST-traceable calibration and 25-year data retention driving premium-mid-economy pricing differentiation. Price differentiation rests on validation timeline length and ITAR compliance burden rather than raw sensor hardware costs. Cost compression in MEMS-based drone supply channels is intensifying because Chinese and Israeli OEMs are consolidating component purchasing power. Drone manufacturers exhibit the highest price sensitivity, while United States military procurement channels prioritize supply security over unit economics.
Supply Chain Analysis
Regional distribution centers in California, Texas, and Toulouse maintain hub-and-spoke patterns for flight-critical sensor fulfillment, with ITAR-controlled inventory segregated from dual-use commercial stock. Geographic supply concentration centers on the United States, France, and Japan for finished systems, with Germany and the United Kingdom contributing specialized calibration and edge-compute capabilities. Raw material dependencies draw from Japanese fused silica boules, European precision optical fiber, and domestic MEMS foundry capacity. Single-source vulnerability in precision quartz substrate supply exposes production schedules to geological-grade material scarcity. Distribution runs through defense prime direct procurement and commercial aviation delegated production authority frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AHRS market reads as a late-cycle quality story, with FAA Special Class Airworthiness Criteria for powered-lift aircraft shifting procurement specifications toward navigation-grade sensor fusion architectures.
For Market Incumbents: Lock in NIST-traceable calibration infrastructure and ITAR compliance capabilities as defensive moats against emerging photonic integrated circuit entrants. Prioritize backward integration into precision optical fiber coil manufacturing to insulate margins from Japanese fused silica supply constraints. Channel control through modular open systems approach specifications with the United States Army's Future Vertical Lift program sustains incumbent positioning. For New Entrants and Emerging Players: The mid-tier price-point gap between Honeywell-grade ring laser platforms and commodity MEMS units creates white-space opportunity for chip-scale fiber optic gyroscope developers. Urban air mobility eVTOL platforms in the United States represent the most penetrable segment, with weight-critical specifications favoring compact optical architectures over silicon alternatives. A certification-bundling go-to-market angle with FAA Organization Designation Authorization holders accelerates market access. For Investors and Strategic Acquirers: Asymmetric upside sits with calibration facility asset owners possessing NIST-traceable infrastructure and existing defense prime relationships. Long-term viability across the five-to-ten year window favors vendors with dual-use commercial-military certification capabilities rather than pure-play tactical-grade suppliers. The signal to monitor is urban air mobility platform design-lock announcements, which will determine which sensor architectures achieve embedded positions in next-generation eVTOL fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Manufacturing Scale-Up | Chip-scale fiber optic gyroscope production preserves jamming immunity while matching MEMS size constraints for eVTOL platforms. |
| Modular Open Systems Approach Certification | United States Army Future Vertical Lift specifications disintermediate traditional systems integrators and elevate component-level value. |
| NIST-Traceable Calibration Facility Acquisition | Specialized inertial test infrastructure with laser interferometry capability commands scarcity premiums in defense procurement channels. |
| Urban Air Mobility Sensor Fusion Partnership | FAA Special Class Airworthiness Criteria bundling with powered-lift developers accelerates design-lock positioning in emerging eVTOL platforms. |
| EU MDR-Aligned Aerospace Directive Compliance | Convergence between medical device and aviation quality standards opens cross-certified manufacturing for German and French suppliers. |
Research Approach
Direct dialogue with aerospace procurement officers, defense prime sensor integration leads, FAA certification specialists, and urban air mobility platform engineers grounded qualitative findings, cross-referenced with EASA regulatory filings, United States Department of Defense budget justification documents, FAA airworthiness criteria dockets, and SEC 10-K aerospace segment disclosures. Bottom-up shipment modeling and top-down defense procurement budget triangulation validated volume estimates.
Bottom-up analysis aggregated unit economics across MEMS, fiber optic gyroscope, and ring laser gyroscope technology tiers, while top-down assessment calibrated against military modernization appropriations and commercial aviation OEM sensor content per platform. Segmentation dimensions spanned certification grade, application environment severity, and end-user procurement channel structure. CAGRs were derived from installed base replacement cycles and emerging platform penetration curves, with urban air mobility certification timelines and unmanned traffic management integration requirements serving as key demand swing factors.
Caveats apply where FAA powered-lift airworthiness criteria revisions or ITAR classification changes could materially shift the outlook for dual-use sensor architectures. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Global Flight Inspection Market
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Aircraft Attitude Indicators Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Global Connected Aircraft Solutions Market
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
Air Data Testers Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Aviation Analytics Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Aircraft Control Software Market