
 OTC Analgesic Market | 2026-2036
OTC Analgesic Market Size, Share, and Industry Trends Forecast 2026-2036
OTC Analgesic Market Outlook
Digital therapeutics integration with mobile health platforms is reshaping how consumers select and track OTC pain relief regimens. Johnson & Johnson leverages its Neutrogena and Tylenol brand architecture to sustain pharmacy shelf dominance across North American retail networks. Bayer AG anchors its competitive position through aspirin heritage formulations and cardiovascular co-positioning strategies. Haleon PLC differentiates via specialist-led pharmacy detailing and gastrointestinal-protective ibuprofen variants.
OTC analgesics comprise non-prescription pharmacological agents—primarily acetaminophen, aspirin, ibuprofen, and naproxen—formulated as tablets, liquids, gels, or capsules for temporary pain and fever relief without clinician supervision. These compounds function through cyclooxygenase inhibition or central prostaglandin modulation, with standard adult dosing ranging from 200 mg to 1000 mg per administration depending on active ingredient and regulatory classification. Tablet formats dominate volume throughput in mature markets due to manufacturing economies and stability profiles, while liquid suspensions command premium positioning in pediatric and geriatric applications where swallowing compliance drives substitution. Online stores represent the fastest-expanding distribution channel as telehealth referrals and subscription replenishment models reduce pharmacy foot traffic dependency.
The FDA's ongoing monograph modernization initiative and the EPA's pharmaceutical discharge standards jointly elevate manufacturing compliance burdens and environmental liability exposure for domestic producers. The IRA's prescription drug pricing provisions indirectly compress OTC premium pricing headroom by resetting consumer reference points across the analgesic category. Stakeholders must monitor monograph finalization timelines and inventory channel migration patterns to calibrate portfolio allocation between pharmacy-centric and direct-to-consumer fulfillment models.
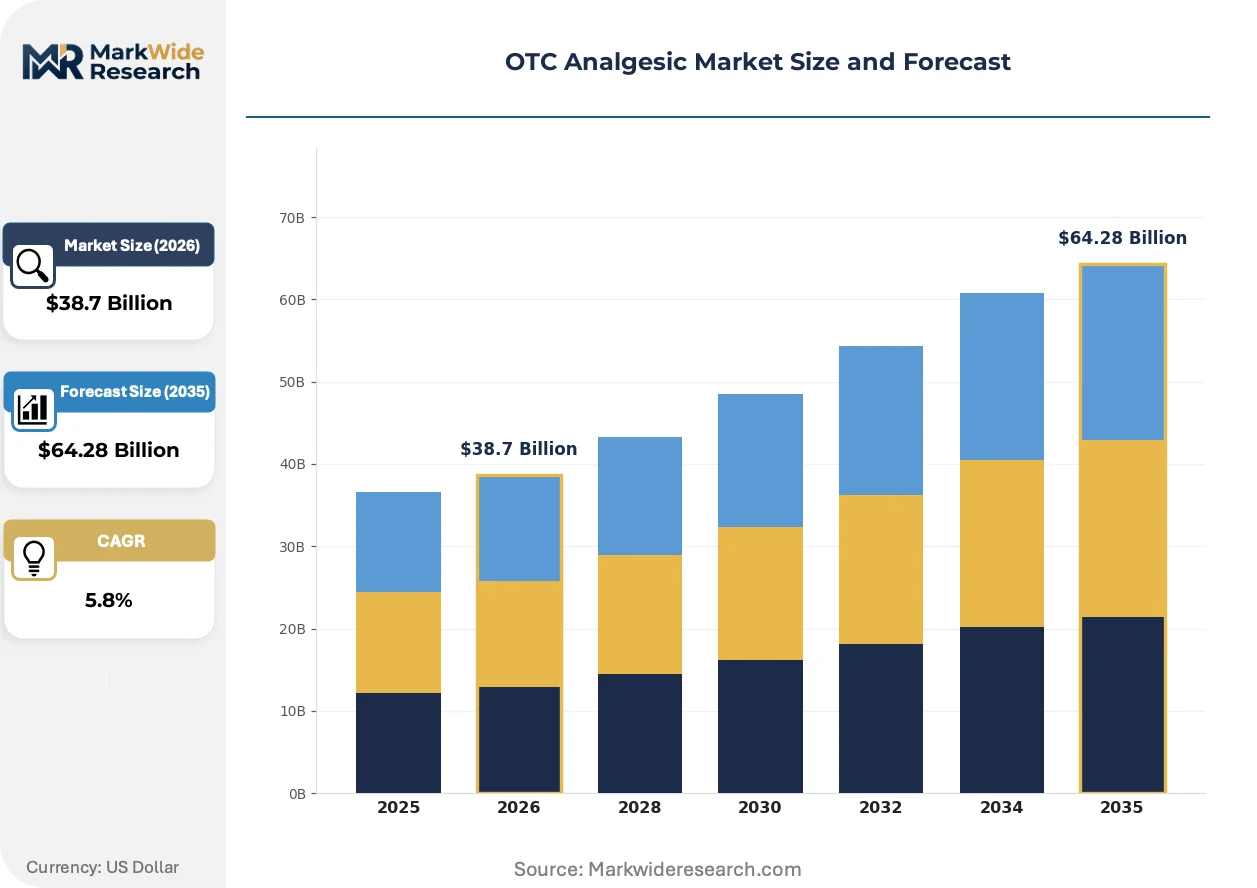
Market Dynamics
The FDA's monograph modernization initiative is compressing formulation timelines while telehealth platforms reroute demand toward direct-to-consumer channels, forcing incumbent manufacturers to reconfigure their pharmacy-centric distribution architectures.
Growth Catalysts
- Sports Medicine Protocol Expansion:Athletic trainers at NCAA Division I programs and professional sports franchises are implementing self-medication protocols for acute pain management, creating institutional demand pull for rapid-dissolve tablet formats.
- IRA Pricing Spillover:The Inflation Reduction Act's prescription drug pricing provisions reset consumer reference points across the analgesic category, expanding the addressable market for premium OTC substitutes previously priced out of consideration sets.
- EPA Discharge Standards:Stricter pharmaceutical manufacturing effluent rules are accelerating capital deployment toward continuous manufacturing processes that reduce solvent waste and environmental liability exposure.
Market Restraints
- API Supply Concentration:Ibuprofen and naproxen active pharmaceutical ingredients concentrate among Chinese and Indian contract manufacturers, exposing formulators to customs delays and geopolitical friction.
- Acetaminophen Hepatotoxicity Labeling:The FDA's liver damage warning requirements for combination products have constrained marketing claims and compressed margin structures for multi-symptom cold and flu formulations.
- Substitution by Digital Therapeutics:Mobile-based pain management applications and prescription digital therapeutics for chronic pain are capturing younger demographics who previously self-medicated with OTC analgesics.
Strategic Opportunities
- Pediatric Liquid Formulation Gap:Swallowing compliance challenges among children aged 2-6 years create unmet demand for palatable, dye-free suspensions with precise dosing instruments.
- Gastrointestinal-Protective Positioning:Ibuprofen variants formulated with proton pump inhibitor co-therapy or enteric coatings can capture patients discontinuing prescription NSAIDs due to ulcer risk.
- Subscription Replenishment Models:Telehealth platforms and pharmacy benefit managers are piloting algorithmic reorder systems for chronic pain patients, locking in recurring revenue streams outside traditional retail.
Industry Challenges
- Monograph Finalization Uncertainty:The FDA's ongoing reform of OTC drug review processes creates regulatory ambiguity around formulation changes, delaying pipeline investments and shelf-space negotiations.
- Channel Migration Complexity:Manufacturers must simultaneously maintain pharmacy relationships while building direct-to-consumer fulfillment capabilities, straining working capital and inventory forecasting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OTC Analgesic Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetaminophen, Aspirin, Ibuprofen, Naproxen Dosage Form: Tablet, Liquid, Gel, Capsules Distribution Channel: Pharmacies, Supermarkets, Online Stores, Hospitals Customer Type: Adults, Children, Seniors, Healthcare Professionals |
| Companies Covered | Bayer AG, Reckitt Benckiser Group PLC, Johnson & Johnson, Haleon PLC, Sanofi SA, Pfizer Inc., Viatris Inc., GlaxoSmithKline PLC, Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OTC Analgesic Market Strategic Shifts
Digital health integration and manufacturing process intensification are converging to redefine how consumers discover, purchase, and adhere to OTC pain management regimens outside traditional pharmacy environments.
Continuous manufacturing technology is migrating from batch pharmaceutical production toward real-time synthesis of analgesic APIs. Contract manufacturers in Ireland and Singapore are adopting flow chemistry platforms that reduce solvent volumes and accelerate quality release timelines. This migration from batch to continuous processing is compressing working capital requirements and enabling smaller production runs for niche formulations.
The FDA's updated acetaminophen safety labeling mandates are forcing reformulation of combination cold and flu products. Manufacturers must now display liver toxicity warnings prominently on primary packaging, which has reduced allowable marketing surface area and triggered package redesign cycles. Pediatric and geriatric segments are responding with single-ingredient positioning to simplify consumer decision-making.
Subscription-based replenishment through telehealth referrals is displacing episodic pharmacy purchases for chronic pain patients. Pharmacy benefit managers and digital health platforms are capturing patient relationships previously held by retail pharmacists, particularly in states with expanded Medicaid managed care contracts. This channel shift is most visible in California, Texas, and Florida where direct-to-consumer shipment volumes have accelerated.
OTC Analgesic Market Segmentation
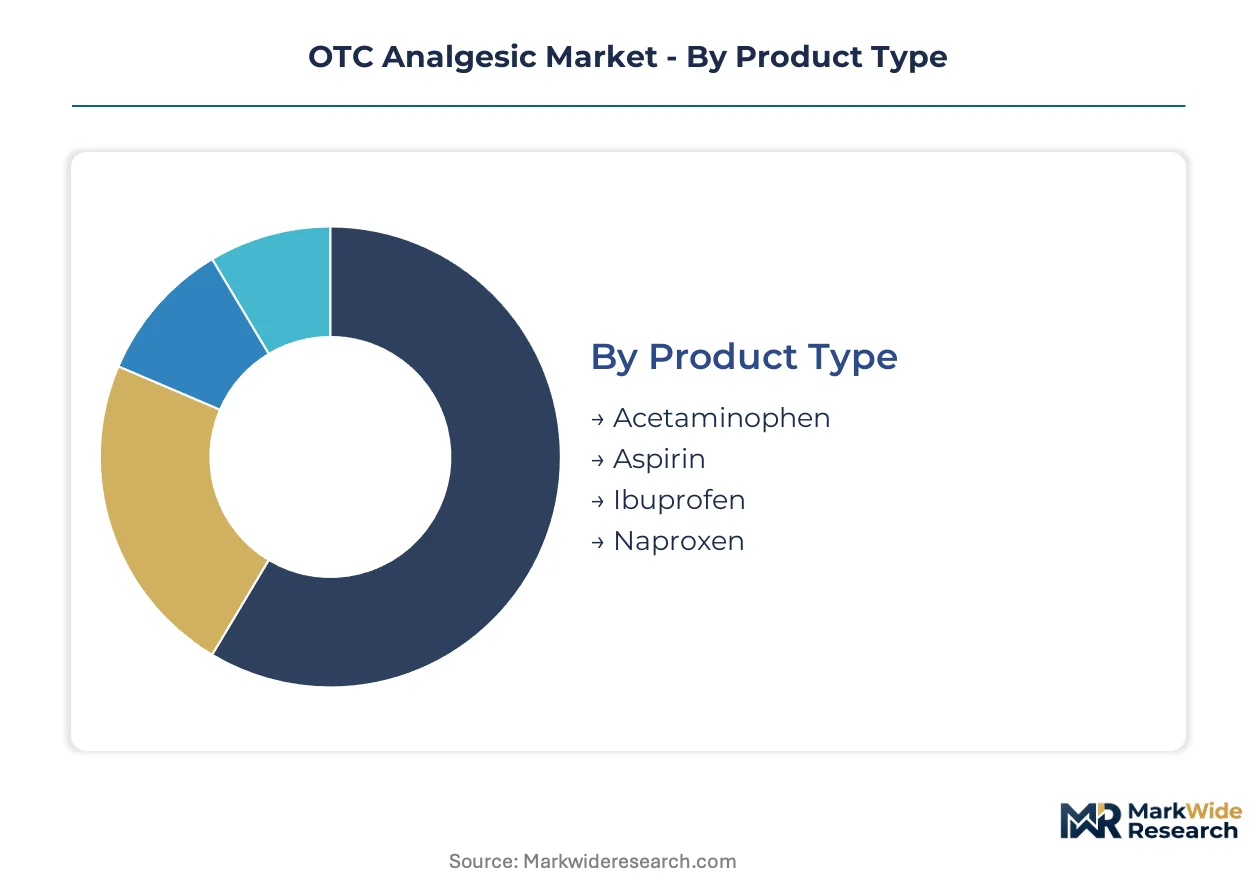
Segmentation in OTC analgesics determines formulation priorities, shelf-space negotiations, and channel investment intensity. Each dimension—chemical class, physical format, fulfillment pathway, and user demographic—carries distinct margin profiles and regulatory exposure that shape portfolio allocation.
Product Type:
Active ingredient selection dictates mechanism of action, safety labeling burden, and competitive differentiation against prescription alternatives.
- Acetaminophen:Central prostaglandin modulation provides analgesia without anti-inflammatory activity. Demand concentrates in pediatric and geriatric populations where gastrointestinal tolerability limits NSAID use, though FDA hepatotoxicity warnings constrain combination product development.
- Ibuprofen:Non-selective COX inhibition delivers anti-inflammatory and analgesic effects. Sports medicine protocols and athletic trainer formularies drive institutional procurement of rapid-dissolve variants, particularly in collegiate and professional franchise settings.
- Aspirin:Irreversible COX-1 inhibition anchors cardiovascular co-positioning strategies. Bayer AG leverages heritage formulations to maintain pharmacy shelf presence despite bleeding risk limitations in pain-only indications.
- Naproxen:Longer half-life enables less frequent dosing for chronic conditions. API supply concentration among Indian and Chinese contract manufacturers exposes formulators to customs friction and working capital volatility.
Established volume favors ibuprofen; emerging adoption favors acetaminophen single-ingredient positioning post-labeling reform.
Dosage Form:
Physical format governs manufacturing capital intensity, stability requirements, and swallowing compliance across age demographics.
- Tablet:Dominates volume throughput through manufacturing economies and extended shelf stability. Direct-to-consumer pharmacy chains allocate disproportionate shelf space to rapid-dissolve and film-coated variants.
- Liquid:Suspension formulations command premium positioning where swallowing compliance drives substitution. Palatability engineering and dye-free positioning target parental purchase criteria for children aged 2-6 years.
- Gel:Topical delivery bypasses first-pass hepatic metabolism for localized musculoskeletal pain. Athletic trainers incorporate topical NSAID gels into acute injury protocols to reduce systemic exposure.
- Capsules:Gelatin and vegetable-based shells enable taste masking and modified release. Subscription replenishment models favor capsule formats for chronic pain patients seeking portable dosing convenience.
Tablet formats capture institutional procurement scale; liquid suspensions gain share fastest in pediatric-directed telehealth channels.
Distribution Channel:
Fulfillment pathway determines customer acquisition cost, inventory velocity, and regulatory jurisdiction for labeling compliance.
- Pharmacies:Dominant shelf-space allocation through pharmacist recommendation influence. Private-label penetration concentrates in United States chain networks where vertical integration compresses branded margin headroom.
- Supermarkets:Impulse purchase visibility and promotional velocity drive seasonal cold-flu category attachment. Limited pharmacist consultation availability elevates importance of front-of-package dosing clarity.
- Online Stores:Algorithmic reorder systems and telehealth referrals reduce foot traffic dependency. California, Texas, and Florida shipment volumes accelerate through Medicaid managed care digital integration.
- Hospitals:Discharge prescription protocols and emergency department formularies create institutional demand pull. Unit-dose packaging requirements differ from retail formats, necessitating separate production lines.
Pharmacy relationships defend margin position through professional recommendation; online stores expand most quickly via subscription lock-in.
Customer Type:
End-user physiology and decision-making authority shape dosing instrument design, packaging communication, and channel selection.
- Adults:Self-directed purchase behavior with established brand loyalty patterns. Standard adult dosing of 200-1000 mg per administration accommodates workplace and home pain management without clinical supervision.
- Children:Caregiver-mediated purchase with precise weight-based dosing requirements. Swallowing compliance challenges generate unmet demand for palatable suspensions with calibrated delivery devices.
- Seniors:Polypharmacy risk and renal function decline elevate importance of drug-drug interaction labeling. Geriatric segments respond to single-ingredient positioning that simplifies decision-making against multi-symptom combinations.
- Healthcare Professionals:Athletic trainers, school nurses, and occupational health officers exercise institutional procurement authority. NCAA Division I programs and professional sports franchises implement self-medication protocols with documented rapid-dissolve tablet preferences.
Adult self-medication sustains volume base; healthcare professional protocol adoption drives fastest expansion in institutional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian and Chinese API manufacturers supply ibuprofen and naproxen to formulators across North America and Europe, with customs friction and working capital volatility reshaping procurement patterns for finished dose producers.
United States
Direct-to-consumer pharmacy chains dominate shelf-space allocation and private-label penetration, while the FDA's monograph modernization initiative accelerates safety labeling requirements for acetaminophen-containing products. The IRA's prescription drug pricing provisions indirectly compress OTC premium pricing headroom by resetting consumer reference points. California, Texas, and Florida shipment volumes accelerate through Medicaid managed care digital integration.
Germany
Bayer AG anchors competitive positioning through aspirin heritage formulations and cardiovascular co-positioning strategies in pharmacy networks. The EMA's ongoing OTC harmonization efforts intersect with Germany's stringent national pharmacy regulations. The Rhine-Ruhr industrial corridor hosts continuous manufacturing technology deployments that reduce solvent waste and environmental liability exposure.
China
API supply concentration for ibuprofen and naproxen exposes formulators to customs delays and geopolitical friction, though domestic consumption rises through e-commerce pharmacy platforms. The NMPA's pharmaceutical discharge standards elevate manufacturing compliance burdens for domestic producers. The Yangtze River Delta region concentrates contract manufacturing capacity with flow chemistry platform adoption.
United Kingdom
Haleon PLC differentiates via specialist-led pharmacy detailing and gastrointestinal-protective ibuprofen variants across community pharmacy networks. The MHRA's post-Brexit regulatory autonomy creates divergence from EU OTC monograph timelines. The Southeast England corridor around London maintains headquarters concentration for European pharmaceutical marketing operations.
India
Contract manufacturers supply ibuprofen and naproxen APIs to global formulators, with CDSCO oversight of active pharmaceutical ingredient quality standards intensifying. The country's pharmaceutical export machinery faces working capital volatility from customs friction in destination markets. The Hyderabad-Visakhapatnam corridor clusters API synthesis capacity with growing adoption of continuous processing technologies.
OTC Analgesic Market Competitive Environment
Channel-controlling players compete with product-specialist players for pharmacy shelf dominance and direct-to-consumer fulfillment relationships. The market structure concentrates around multinational consumer health divisions with legacy brand portfolios and established retail network access. Three archetypes define competitive positioning: heritage pharmaceutical conglomerates with cardiovascular co-positioning capabilities, consumer health spin-offs with pharmacy detailing infrastructure, and private-label specialists with vertical retail integration. M&A activity targets gastrointestinal-protective formulation capabilities, while strategic partnerships with telehealth platforms accelerate subscription replenishment model deployment.
Among heritage pharmaceutical conglomerates, Bayer AG exemplifies the cardiovascular-co-positioning archetype through aspirin legacy formulations. Johnson & Johnson occupies a position within the pharmacy shelf-dominance tier through its Neutrogena and Tylenol brand architecture across North American retail networks. Haleon PLC represents the consumer health spin-off model with specialist-led pharmacy detailing and gastrointestinal-protective ibuprofen variants.
| Leading Market Players |
|---|
| Bayer AG |
| Reckitt Benckiser Group PLC |
| Johnson & Johnson |
| Haleon PLC |
| Sanofi SA |
| Pfizer Inc. |
| Viatris Inc. |
| GlaxoSmithKline PLC |
| Boehringer Ingelheim International GmbH |
| Others |
Value Chain & Pricing Dynamics
Chinese and Indian API manufacturers for ibuprofen and naproxen concentrate upstream supply, feeding margin pools downstream to branded formulators and pharmacy chains that command shelf-space premiums in United States retail networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates gastrointestinal-protective ibuprofen variants from rapid-dissolve tablets and private-label commodity tablets. Price differentiation rests on brand heritage and FDA labeling compliance status, with premium tiers absorbing hepatotoxicity warning redesign costs. Cost compression in standard-tier acetaminophen is intensifying because IRA prescription pricing resets compress reference points. Healthcare professional procurement segments show least price sensitivity; Medicaid-managed-care subscribers exhibit highest.
Supply Chain Analysis
Contract manufacturing concentration sits with API synthesizers in China's Yangtze River Delta and India's Hyderabad-Visakhapatnam corridor, with flow chemistry adopters in Ireland and Singapore gaining share for finished dose production. Ibuprofen and naproxen APIs draw from Chinese and Indian chemical synthesis; excipients and packaging materials source from regional converters. Single-source vulnerability runs through customs friction at destination ports. Distribution runs through direct-to-consumer pharmacy chains and telehealth-platform subscriptions.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OTC analgesic markets operate as defensive-moat structures where regulatory entrenchment via FDA monograph compliance creates switching costs that lock in shelf-space allocation for incumbent formulators.
For Market Incumbents: Pre-empt digital therapeutic substitution by integrating subscription replenishment algorithms with telehealth platform partnerships. Lock in pediatric liquid formulation capacity before CDSCO quality standard intensification closes the window. Channel control through pharmacy benefit manager relationships remains the priority lever against direct-to-consumer disintermediation.
For New Entrants and Emerging Players: Gastrointestinal-protective ibuprofen white space in United States Medicaid managed care networks represents the most penetrable entry point. Palatable, dye-free suspensions for children aged 2-6 years offer second-mover advantage where swallowing compliance drives parental substitution. Go-to-market execution should anchor on telehealth referral partnerships rather than retail shelf-space contests.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed consumer health spin-offs lacking gastrointestinal-protective formulation pipelines. Long-term viability over the mid-decade horizon favors targets with continuous manufacturing technology deployment and EPA discharge compliance already capitalized. Watch FDA monograph finalization timelines as the inflection signal for portfolio reallocation between pharmacy-centric and direct-to-consumer fulfillment models.
| Strategic Initiative | Industry Significance |
|---|---|
| Gastrointestinal-Protective Formulation Development | Captures patients discontinuing prescription NSAIDs due to ulcer risk under EMA guidance. |
| Continuous Manufacturing Technology Deployment | Reduces solvent waste and accelerates quality release timelines under EPA discharge standards. |
| Telehealth Platform Partnership | Locks in subscription replenishment revenue outside traditional pharmacy foot traffic dependency. |
| Pediatric Liquid Formulation Launch | Addresses swallowing compliance gaps for children aged 2-6 years with precise dosing instruments. |
| Private-Label Vertical Integration | Defends margin position against United States chain pharmacy shelf-space compression. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with pharmacy benefit managers, athletic trainers at NCAA Division I programs, FDA regulatory affairs specialists, and contract manufacturing executives in India and China. Secondary validation drew from FDA monograph dockets, EPA pharmaceutical discharge filings, CMS Medicaid managed care enrollment data, and customs trade records for API shipments. Bottom-up patient population modeling and top-down retail audit triangulation anchored volume estimates.
Calibration against historical regulatory timeline slippage and channel migration patterns shaped the analytical framework across the analysis window. Segmentation dimensions included active ingredient class, dosage form, distribution channel, and customer type with regional regulatory cluster overlays. CAGRs derived from patent cliff impacts, monograph modernization schedules, and telehealth platform penetration curves. Forecast inputs incorporated IRA pricing spillover elasticity and continuous manufacturing adoption S-curves.
Stress conditions across FDA monograph finalization delays, API customs friction severity, and digital therapeutic substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding telehealth referral growth trajectories and EPA enforcement intensity. Quarterly review of Medicaid managed care digital integration metrics and monograph comment period volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Chloramphenicol Eye Drops Market
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
North America Biguanide Market
Pharmaceuticals
RAS-Acting Agents Market
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Global Two Piece Empty Hard Capsule Market
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Tissue Plasminogen Activator Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market