
 APAC Vibration Sensors Market | 2026-2036
APAC Vibration Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Vibration Sensors Market Outlook
Market Context
Modular sensor-to-gateway bundling is broadening buyer choice across the APAC Vibration Sensors landscape, letting facilities scale from single-point monitoring to full plant-wide systems without vendor switching. Bosch Sensortec GmbH leverages its MEMS fabrication depth to dominate compact accelerometer supply for automotive tier-1s. Honeywell International Inc anchors its position through integrated circuit designs that tolerate extreme temperatures in aerospace test cells. SKF AB competes by extending its bearing-installed sensor packages into predictive maintenance service contracts.
Technical Definition and Segment Structure
APAC vibration sensors are electromechanical or solid-state transducers that convert mechanical oscillation into electrical signals, typically operating across frequency ranges from sub-Hertz to tens of kiloHertz with sensitivity thresholds down to micro-g levels for precision machinery diagnostics. Their primary commercial purpose is enabling condition-based maintenance, structural health monitoring, and process control across capital-intensive industries. Accelerometers command the largest revenue pool due to universal deployment in rotating equipment monitoring, while wireless technology segments attract the fastest growth as battery-harvesting designs eliminate cabling costs in sprawling industrial sites. Fiber optic sensing occupies a premium niche where electromagnetic immunity matters, such as near high-voltage switchgear in power utilities.
Regulatory Framework and Outlook
Japan's METI enforces industrial energy conservation standards that mandate vibration monitoring on designated high-power machinery, while China's GB standards for machinery safety specify periodic vibration measurement protocols. Australia's TGA and South Korea's MFDS indirectly shape demand through medical device manufacturing quality rules that require cleanroom vibration isolation verified by calibrated sensors. Stakeholders must weigh cloud-based deployment models against data sovereignty requirements as ASEAN nations draft cross-border industrial data regulations.
Market Dynamics
China's dual carbon goals and Japan's METI energy-efficiency mandates are forcing manufacturing plants to install continuous vibration monitoring on high-power rotating equipment, compressing replacement cycles for legacy measurement systems.
Growth Catalysts
- Automotive electrification:Battery gigafactories across China's eastern coastal provinces require precision vibration isolation for electrode coating lines, driving demand for micro-g sensitivity sensors in cleanroom environments.
- Japan's METI mandates:Designated high-power machinery must deploy continuous condition monitoring, creating regulatory pull for wireless accelerometer networks in steel and chemical plants.
- Predictive maintenance service contracts:SKF and bearing manufacturers bundle installed sensors with multi-year performance guarantees, converting capital expenditure into operational budgets for mid-sized manufacturers.
Market Restraints
- MEMS foundry concentration:Taiwan and South Korean semiconductor fabrication facilities control 80% of compact accelerometer wafer supply, exposing buyers to geopolitical logistics disruption.
- Calibration infrastructure gaps:Vietnam, Indonesia, and Philippines lack ISO 17025-accredited vibration laboratories, forcing manufacturers to ship sensors to Japan or Australia for certification.
- Wireless spectrum fragmentation:China's MIIT, Japan's MIC, and South Korea's MSIT operate incompatible industrial IoT frequency allocations, complicating multi-country sensor deployments.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for semiconductor and automotive component factories will create greenfield demand for integrated sensor-to-gateway systems in Gujarat and Tamil Nadu.
- Energy harvesting convergence:Piezoelectric and thermoelectric power modules eliminate battery replacement in remote mining and pipeline monitoring applications across Australia's Pilbara region.
- Cloud-based vibration analytics:Alibaba Cloud and Tencent Cloud are building industrial data sovereignty-compliant platforms that lower analytics barriers for ASEAN small and medium manufacturers.
Industry Challenges
- Embedded systems firmware expertise:Sensor vendors struggle to hire engineers capable of optimizing edge computing algorithms for real-time frequency analysis on resource-constrained microcontroller platforms.
- Legacy DCS integration:Decades-old distributed control systems in Japanese and South Korean petrochemical plants lack native digital interfaces, requiring costly protocol gateway hardware for sensor data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Vibration Sensors Market |
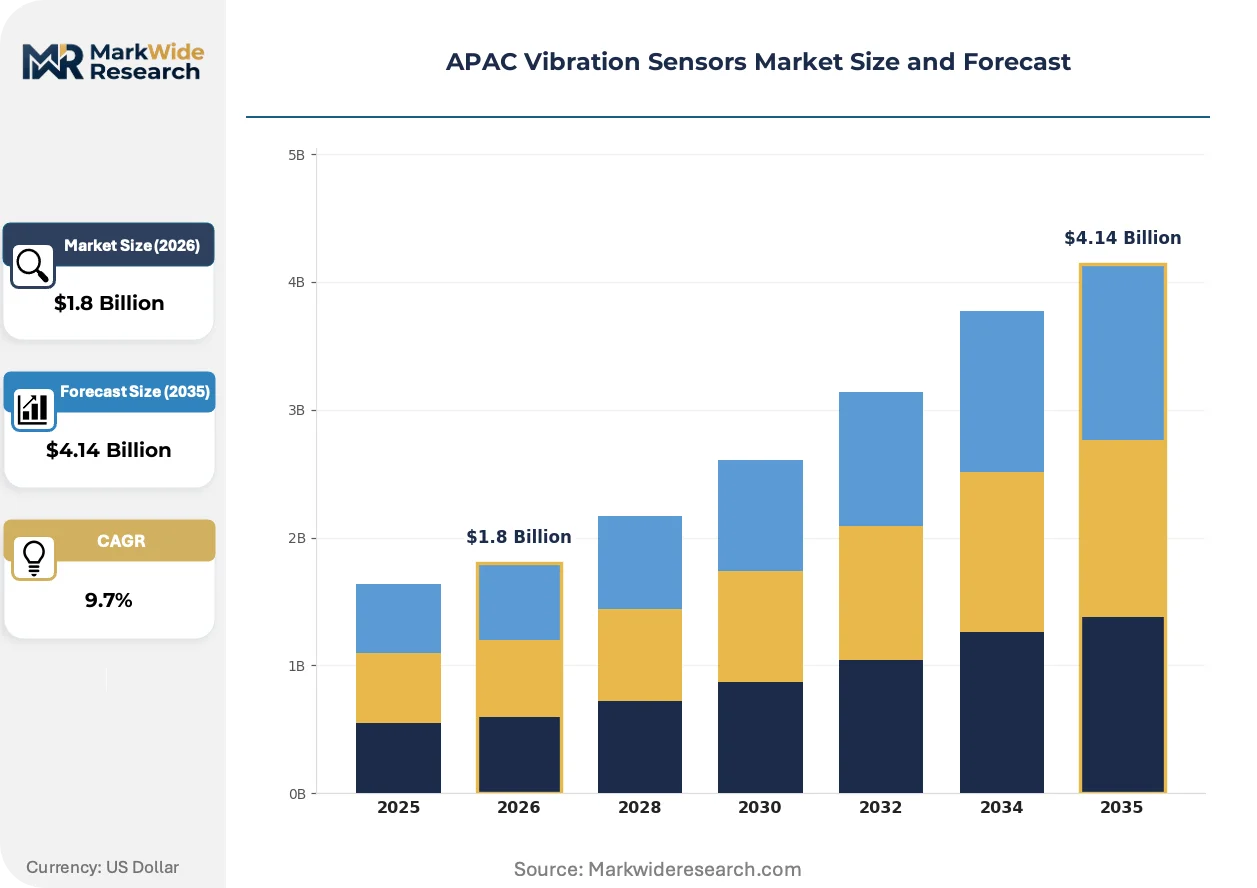
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Velocity Sensors, Displacement Sensors, Pressure Sensors End User: Manufacturing, Automotive, Aerospace, Electronics Deployment Model: On-premise, Cloud-based, Hybrid, Integrated Technology: Micromechanical, Fiber Optic, Wireless, Integrated Circuit |
| Companies Covered | National Instruments Corporation, Bosch Sensortec GmbH, Honeywell International Inc, Hansford Sensors Ltd, TE Connectivity Ltd, NXP Semiconductors N.V., Emerson Electric Co, Texas Instruments Incorporated, SKF AB, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Vibration Sensors Market Strategic Shifts
Edge computing architectures are redistributing vibration analytics from cloud servers to sensor nodes, reducing latency for critical machinery protection while complicating firmware update logistics across dispersed industrial sites.
Triaxial MEMS accelerometers with built-in temperature compensation are integrating machine-learning inference engines directly onto the sensing die. Automotive tier-1 suppliers in China's Yangtze River Delta are qualifying these devices for electric powertrain NVH validation. This convergence is integrating vibration and thermal diagnostics into single-chip modules that compress bill-of-materials costs for high-volume applications.
Japan's METI has revised its Energy Conservation Act to mandate real-time power consumption correlation with machinery health indicators, including vibration signatures. Steel mills in Chiba and Kobe must now retrofit continuous monitoring on blast furnace fans and compressor trains. Compliance deadlines are accelerating replacement of periodic manual measurement routines with permanent wireless sensor networks.
Asset owners in Australia's mining sector are unbundling predictive maintenance contracts from original equipment manufacturer service agreements. BHP and Rio Tinto procurement teams now directly specify sensor brands and data platform requirements in capital project tenders. This disintermediation is visible most acutely in Western Australia's iron ore operations, where independent vibration analytics vendors displace incumbent compressor and pump OEM service divisions.
APAC Vibration Sensors Market Segmentation
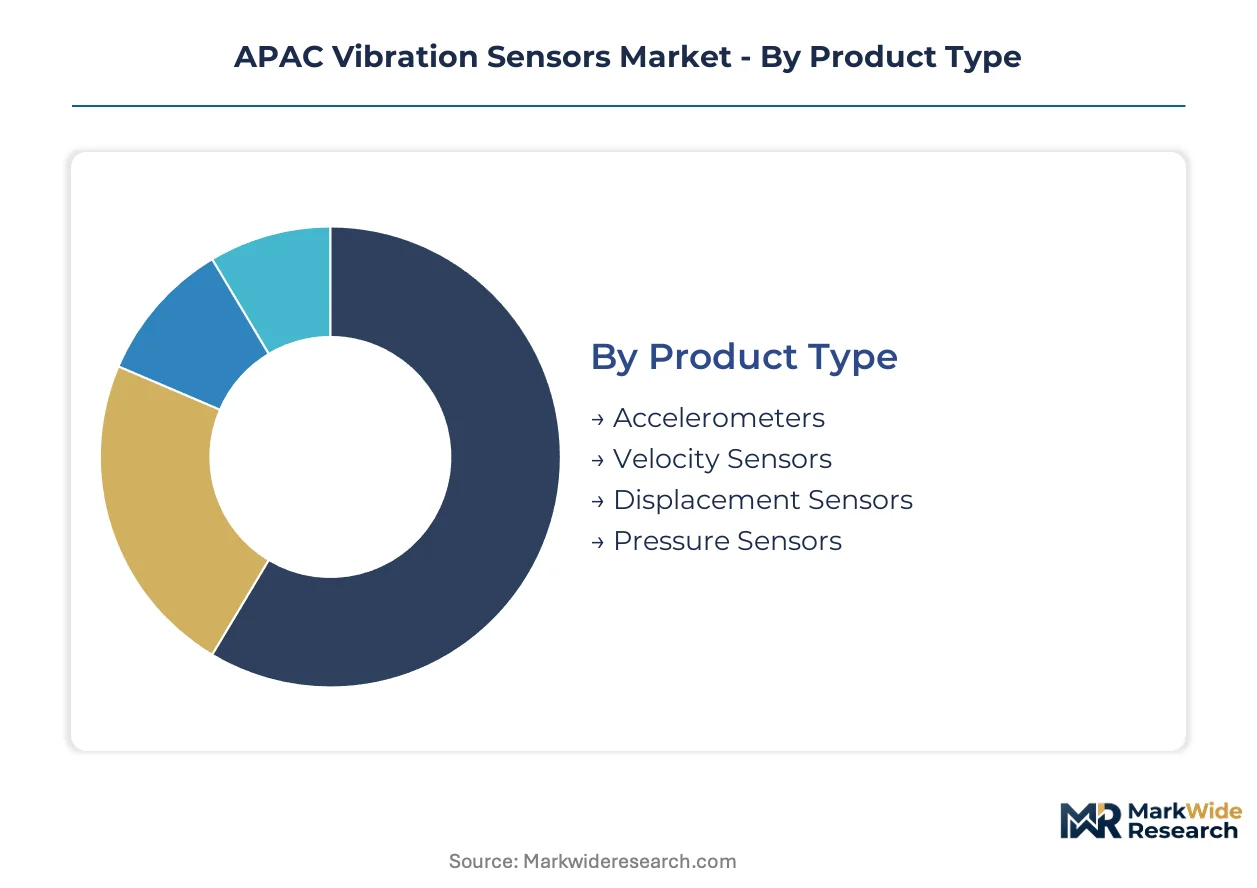
APAC vibration sensor procurement patterns diverge sharply between capital-intensive process industries seeking certified precision and distributed operations prioritizing wireless scalability. Segmentation reveals how technical specifications, deployment constraints, and regulatory exposure shape purchasing decisions across China's manufacturing belt, Japan's precision engineering clusters, and Australia's remote resource operations.
Product Type:
Standardization dominates high-volume automotive and consumer electronics applications, while custom-calibrated units serve aerospace test cells and nuclear power turbine monitoring where traceability requirements override cost considerations.
- Accelerometers:MEMS-based triaxial devices with micro-g sensitivity thresholds dominate rotating equipment monitoring in China's battery gigafactories and Japan's steel mills. Demand concentrates in China's eastern coastal provinces where automotive and electronics production clusters require precision vibration isolation for cleanroom electrode coating lines.
- Velocity Sensors:Electromagnetic coil-and-magnet architectures tolerate high temperatures in cement kiln and blast furnace fan applications. Japan's METI energy conservation mandates are forcing steel mills in Chiba and Kobe to retrofit continuous velocity monitoring on compressor trains, displacing periodic manual measurement routines.
- Displacement Sensors:Eddy current and laser triangulation variants measure shaft orbit and bearing clearance in hydroelectric turbines across Australia's Snowy Mountains schemes.
- Pressure Sensors:Piezoelectric and strain gauge configurations monitor cavitation-induced vibration in pipeline pumps across Indonesia's geothermal fields.
Most installed capacity flows through accelerometers. Expansion is steepest in velocity sensors.
End User:
Volume scales inversely with specification stringency — automotive plants purchase thousands of standardized units while aerospace qualification cycles stretch procurement timelines across years.
- Manufacturing:Predictive maintenance programs in China's expanding plants drive bulk sensor deployment. SKF and bearing manufacturers bundle installed sensors with multi-year performance guarantees, converting capital expenditure into operational budgets for mid-sized manufacturers across Vietnam and Thailand.
- Automotive:Battery gigafactories in China's Yangtze River Delta require micro-g sensitivity sensors for electric powertrain NVH validation. Tier-1 suppliers are qualifying triaxial MEMS accelerometers with built-in temperature compensation for production line integration.
- Aerospace:Honeywell's integrated circuit designs tolerate extreme temperatures in test cells across Japan's Nagoya aerospace cluster and Australia's defense research facilities.
- Electronics:Semiconductor fabrication in Taiwan and South Korea demands vibration isolation verification for lithography equipment, with cleanroom protocols specified under MFDS and TGA indirect quality rules.
Manufacturing absorbs the largest unit volumes. Electronics applications are climbing the fastest as wafer fabrication expands.
Deployment Model:
Cloud migration accelerates where data sovereignty frameworks mature, while on-premise retention persists in defense-linked and critical infrastructure applications.
- On-premise:Air-gapped installations dominate defense aerospace and nuclear power applications in Japan and Australia where foreign cloud access is restricted. Legacy DCS integration challenges in South Korean petrochemical plants require costly protocol gateway hardware.
- Cloud-based:Alibaba Cloud and Tencent Cloud are building industrial data sovereignty-compliant platforms lowering analytics barriers for ASEAN small and medium manufacturers. Australia's mining sector leads cloud adoption with BHP and Rio Tinto procurement teams directly specifying data platform requirements.
- Hybrid:Edge computing architectures redistribute vibration analytics from cloud servers to sensor nodes, reducing latency for critical machinery protection while complicating firmware update logistics across dispersed Indonesian and Philippine industrial sites.
- Integrated:Modular sensor-to-gateway bundling lets facilities scale from single-point monitoring to full plant-wide systems without vendor switching, particularly in India's Gujarat and Tamil Nadu greenfield semiconductor factories under PLI incentives.
Hybrid architectures capture the most new project specifications. Cloud-based deployment is gaining share fastest as ASEAN data sovereignty regulations crystallize.
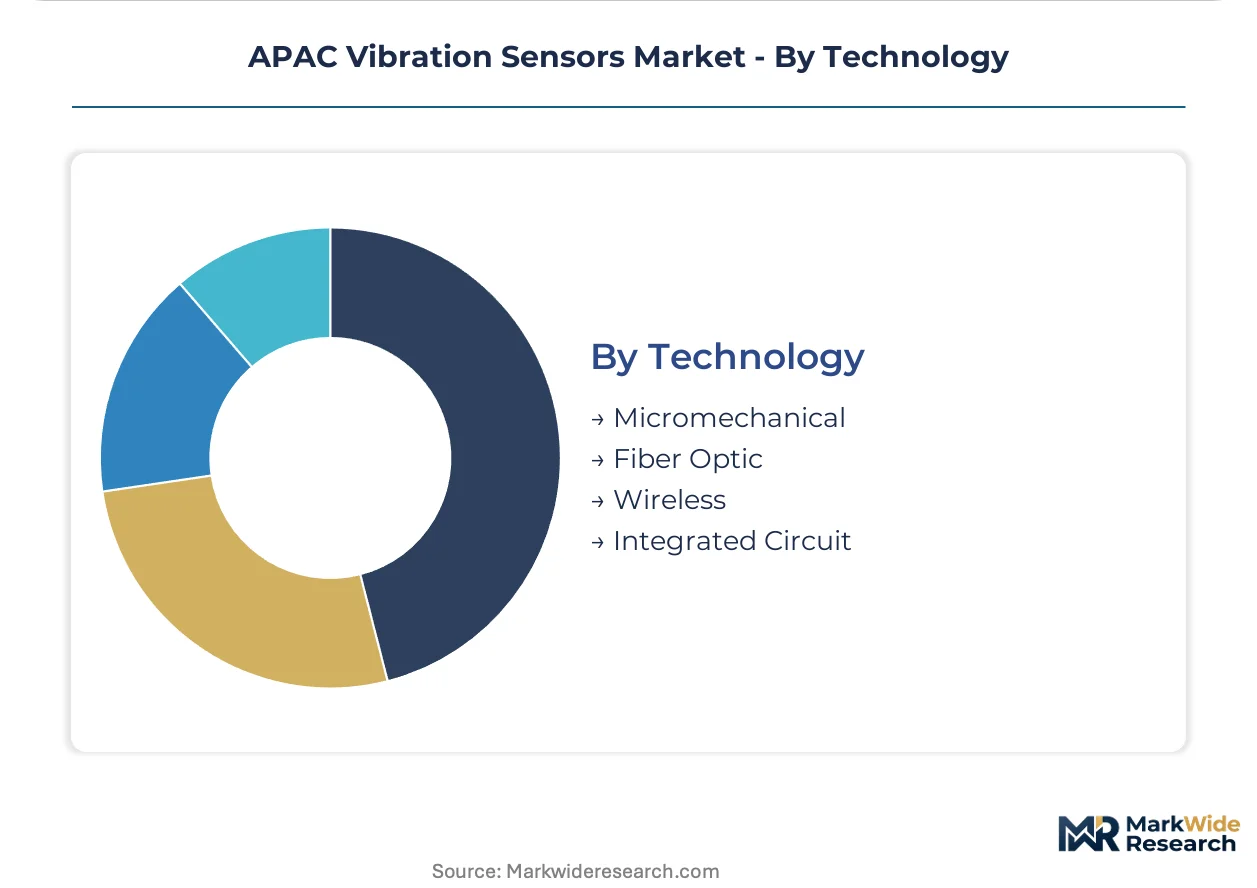
Technology:
Supply concentration in Taiwan and South Korean semiconductor fabrication creates technology-specific vulnerability exposure for buyers dependent on MEMS wafer supply.
- Micromechanical:MEMS foundry concentration in Taiwan and South Korea controls compact accelerometer wafer supply, exposing buyers to geopolitical logistics disruption. Bosch Sensortec leverages fabrication depth to dominate automotive tier-1 supply.
- Fiber Optic:Electromagnetic immunity near high-voltage switchgear in Chinese and Australian power utilities commands premium pricing. Intrinsic safety in explosive atmospheres drives adoption in Indonesia's coal gasification plants.
- Wireless:Battery-harvesting piezoelectric and thermoelectric designs eliminate cabling costs in sprawling Australian Pilbara mining operations and remote pipeline monitoring across Malaysia's peninsula. Spectrum fragmentation between China's MIIT, Japan's MIC, and South Korea's MSIT complicates multi-country deployments.
- Integrated Circuit:Machine-learning inference engines embedded directly onto sensing die compress bill-of-materials costs for high-volume automotive applications. Firmware expertise scarcity constrains edge algorithm optimization.
Micromechanical devices account for the greatest installed base. Wireless technology is expanding most quickly as energy harvesting matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vibration sensor manufacturing first achieved industrial scale in Japan's precision engineering clusters during the 1980s, with MEMS fabrication later concentrating in Taiwan and South Korea. This historical lineage shapes current procurement patterns across the Asia-Pacific region.
China
Battery gigafactories in the Yangtze River Delta and eastern coastal provinces drive micro-g sensitivity sensor demand for electrode coating lines. The country's dual carbon goals and GB machinery safety standards mandate continuous vibration monitoring on designated high-power equipment. Procurement concentrates in Jiangsu and Guangdong provinces where automotive and electronics production clusters dominate.
Japan
Steel mills in Chiba and Kobe retrofit continuous monitoring on blast furnace fans under METI's revised Energy Conservation Act. The mandate requires real-time power consumption correlation with machinery health indicators including vibration signatures. Nagoya's aerospace cluster maintains demand for extreme-temperature tolerant sensors in test cell applications.
South Korea
Semiconductor fabrication facilities in the Seoul Capital Area and Busan-Ulsan region require cleanroom vibration isolation verification for lithography equipment. MFDS medical device manufacturing quality rules indirectly shape sensor specifications. Legacy distributed control systems in petrochemical plants create integration challenges for new sensor deployments.
Australia
Iron ore operations in Western Australia's Pilbara region lead unbundling of predictive maintenance contracts from OEM service agreements. BHP and Rio Tinto procurement teams directly specify sensor brands and data platform requirements. The Snowy Mountains hydroelectric schemes deploy displacement sensors for turbine shaft orbit monitoring.
India
Production-linked incentives for semiconductor and automotive component factories create greenfield demand in Gujarat and Tamil Nadu. PLI scheme beneficiaries require integrated sensor-to-gateway systems for new manufacturing capacity. The country's national industrial regulator is drafting data sovereignty frameworks affecting cloud-based vibration analytics adoption.
APAC Vibration Sensors Market Competitive Environment
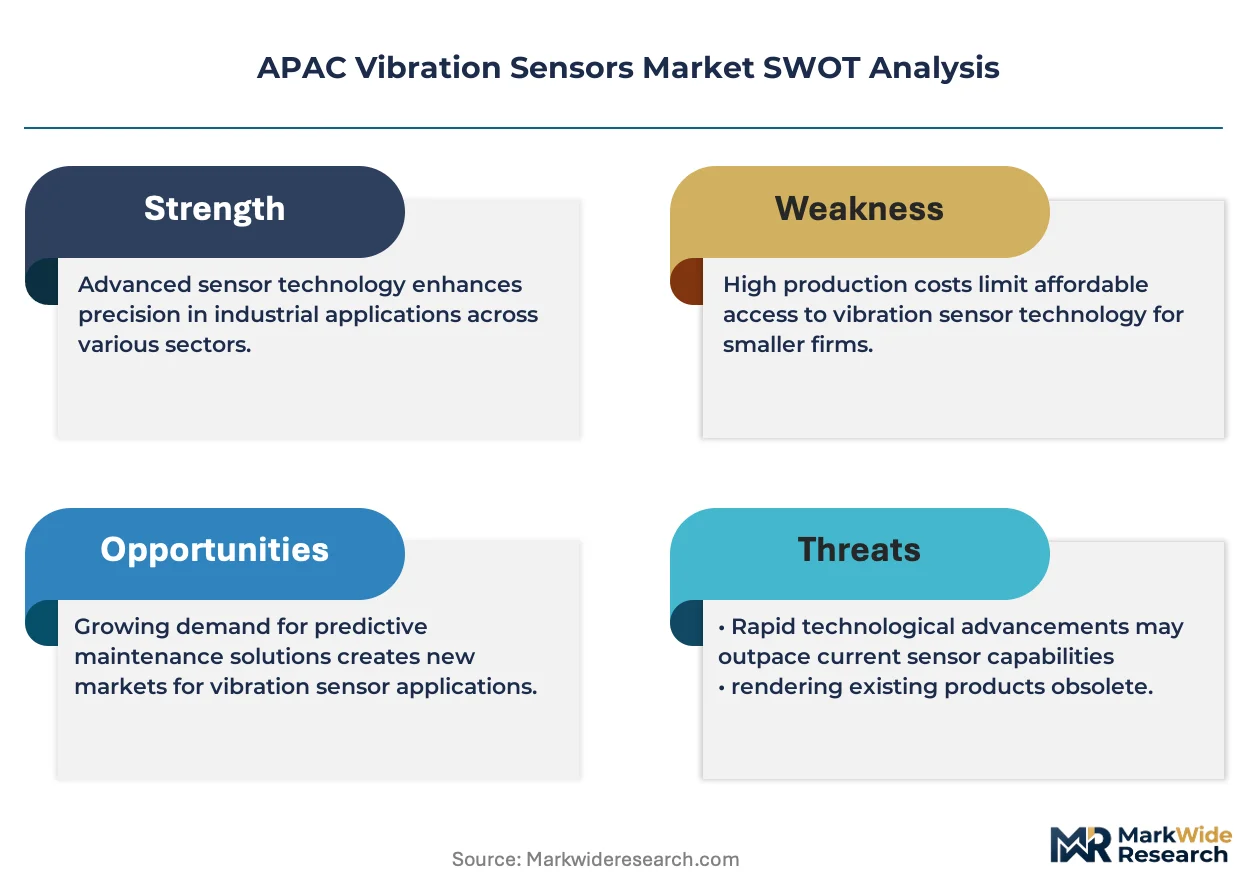
Premium-margin players sit above commodity-margin players across certification depth and MEMS fabrication capabilities. The vendor base organizes into three tiers: integrated industrial conglomerates with predictive maintenance service arms, semiconductor specialists leveraging wafer-scale manufacturing, and component suppliers focused on specific transducer architectures. Consolidation pressure operates through bearing manufacturers bundling sensors with multi-year performance guarantees, while technology licensing agreements proliferate around edge computing firmware.
Among European-anchored industrial specialists, SKF AB and Hansford Sensors Ltd exemplify the predictive maintenance service model, converting capital expenditure into operational budgets through bundled offerings. Bosch Sensortec GmbH represents the semiconductor fabrication archetype, leveraging MEMS process depth for high-volume supply. Honeywell International Inc occupies a position emphasizing integrated circuit architectures for extreme environment applications.
| Leading Market Players |
|---|
| National Instruments Corporation |
| Bosch Sensortec GmbH |
| Honeywell International Inc |
| Hansford Sensors Ltd |
| TE Connectivity Ltd |
| NXP Semiconductors N.V. |
| Emerson Electric Co |
| Texas Instruments Incorporated |
| SKF AB |
| Others |
Value Chain & Pricing Dynamics
Captive MEMS fabrication at Bosch Sensortec and Honeywell anchors both supply security and premium pricing power for extreme-environment sensor variants. This integration choice insulates tier-one suppliers from foundry volatility while compressing margins for fabless competitors dependent on Taiwan wafer allocation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-certified precision units from industrial-grade MEMS and uncalibrated commodity accelerometers. Price differentiation hinges on calibration traceability and after-sales service bundling. Cost compression in the economy tier intensifies because Chinese battery gigafactories negotiate volume offtakes exceeding ten thousand units. Automotive tier-1s exhibit lowest price sensitivity; mid-sized Vietnamese manufacturers show highest.
Supply Chain Analysis
China's MIIT local-content requirements for industrial IoT equipment are reshaping sourcing patterns toward domestic sensor packaging and calibration facilities. Wafer supply concentrates in Taiwan and South Korea; final assembly draws from China and Thailand. Quartz substrates and piezoelectric ceramics rest on Japanese and German material streams. Single-source vulnerability runs through Taiwan Semiconductor's MEMS foundry capacity. Distribution runs through SKF and bearing OEM service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APAC vibration sensors market compounds steadily as predictive maintenance contracts convert capital expenditure into recurring operational budgets across manufacturing plants.
For Market Incumbents: Lock in predictive maintenance service contracts with multi-year performance guarantees to defend against independent analytics vendors displacing OEM service divisions in Australian mining. Deepen backward integration into MEMS fabrication to secure wafer allocation against Taiwan logistics disruption. Prioritize firmware talent acquisition to maintain edge computing algorithm superiority. For New Entrants and Emerging Players: India's PLI scheme for semiconductor manufacturing opens a window for integrated sensor-to-gateway systems in Gujarat and Tamil Nadu greenfield factories. Target wireless velocity sensor retrofits in Japan's Chiba and Kobe steel mills where METI mandates force compliance spending. Lead with cloud-native analytics platforms compliant with emerging ASEAN data sovereignty frameworks. For Investors and Strategic Acquirers: Roll-up economics work for regional vibration analytics specialists because customer acquisition costs fall dramatically when bundled with existing maintenance contractor relationships. Five-to-ten year viability favors firms with captive calibration infrastructure. Watch for BHP and Rio Tinto procurement unbundling as the inflection signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Service Bundling | SKF converts capital expenditure into operational budgets across mid-sized Vietnamese manufacturers. |
| Edge Computing Firmware Development | Machine-learning inference engines embedded on sensing die compress automotive bill-of-materials costs. |
| Energy Harvesting Integration | Piezoelectric power modules eliminate battery replacement in Australia's Pilbara mining operations. |
| Cloud Platform Sovereignty Compliance | Alibaba Cloud and Tencent Cloud build industrial data platforms for ASEAN small manufacturers. |
| Wireless Spectrum Harmonization | Multi-country deployments complicate under fragmented MIIT, MIC, and MSIT frequency allocations. |
Study Parameters
Direct dialogue with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across China's Yangtze River Delta and Japan's Chiba steel corridor grounded qualitative findings. Secondary validation drew from METI energy conservation filings, China's GB machinery safety standards, customs trade data for accelerometer imports, and SEC 10-K disclosures from listed industrial conglomerates. Bottom-up unit demand estimates triangulated against top-down industry spend analysis.
Segment-level outputs across the analysis window reflect modeled deployment by product type, end-use industry, technology architecture, and regional regulatory cluster. CAGRs derived from curve-fitting historical procurement patterns against mandated compliance deadlines. Forecast inputs incorporated METI Energy Conservation Act retrofit timelines and India's PLI scheme capacity buildout schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Taiwan semiconductor logistics disruption or ASEAN data sovereignty regulation acceleration. Forecasts reflect assumptions on wireless technology adoption rates and foundry capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Thermography Condition Monitoring Equipment Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Piezoelectric Devices Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Battery Free Sensor Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
Digital Angle Gauge Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
Europe Nano Sensors Market