
 Global Cognitive Data Management Market | 2026-2036
Global Cognitive Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cognitive Data Management Market Intelligence
Enterprise buyer concentration is broadening as mid-market financial services and regional healthcare networks join tier-one banks and telecom operators in procuring cognitive data platforms. IBM sustains technology leadership through its Watson-powered governance stack, while SAP leverages deep ERP integration to anchor deployments in European manufacturing. Microsoft competes aggressively via Azure Purview and Fabric, embedding cognitive capabilities directly into cloud productivity workflows that enterprises already operate.
Cognitive data management fuses machine learning, natural language processing, and automated metadata tagging to organize, classify, and govern information assets without exhaustive human curation; systems typically process streaming data pipelines with sub-second latency to enforce policy rules in real time. Unstructured data solutions command premium pricing as enterprises confront exponential growth in video, image, and sensor feeds that resist traditional relational schema. Hybrid cloud deployment models attract the fastest-growing investment because they reconcile sovereign data residency requirements with elastic compute economics.
The EU AI Act, GDPR, and the US HIPAA framework collectively tighten accountability for automated decision-making and cross-border data transfers, forcing vendors to embed explainable classification and audit trails as standard features. ISO 27001 and SOC 2 certifications now function as baseline market-access credentials rather than differentiators. Stakeholders must monitor how national AI safety institutes and sector-specific regulators calibrate enforcement intensity, as compliance cost allocation between vendors and customers remains unresolved.
Market Dynamics
Automated metadata classification is compressing procurement cycles as enterprises replace manual data stewardship with machine-learning pipelines that enforce governance rules in real time.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making accountability requirements are forcing European enterprises to deploy explainable classification engines that generate auditable data lineage trails.
- Healthcare interoperability rules:US federal mandates for seamless patient data exchange are driving hospital networks to adopt cognitive platforms that normalize unstructured clinical records into standardized formats.
- Streaming data pipeline architectures:Sub-second latency processing capabilities are enabling financial services firms to apply policy enforcement at ingestion rather than in batch overnight cycles.
Market Restraints
- Specialized talent scarcity:Shortages of data engineers fluent in both governance frameworks and machine-learning operations are extending implementation timelines by twelve to eighteen months.
- Hybrid cloud integration costs:Sovereign data residency requirements across Germany, France, and Singapore are forcing redundant infrastructure deployments that inflate total cost of ownership.
- Relational database substitution:Mature data warehousing investments at incumbent enterprises resist full migration, creating technical debt that fragments governance coverage.
Strategic Opportunities
- Brazilian manufacturing digitization:ANVISA traceability requirements for pharmaceutical supply chains are creating first-mover advantages for vendors offering Portuguese-localized cognitive classification.
- Edge-to-cloud orchestration:Convergence of 5G network slicing with containerized data governance is opening real-time policy enforcement for autonomous vehicle fleets and industrial IoT deployments.
- US state-level privacy fragmentation:California CPRA, Virginia CDPA, and Colorado CPA are compelling multi-jurisdictional enterprises to purchase unified platforms rather than patchwork state-specific solutions.
Industry Challenges
- ISO 27001 certification bottlenecks:Audit backlogs at accredited bodies are delaying market entry for startups by six to nine months beyond product readiness.
- Mainframe integration complexity:COBOL-based core banking systems resist API-native connectivity, requiring expensive middleware layers that erode platform margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cognitive Data Management Market |
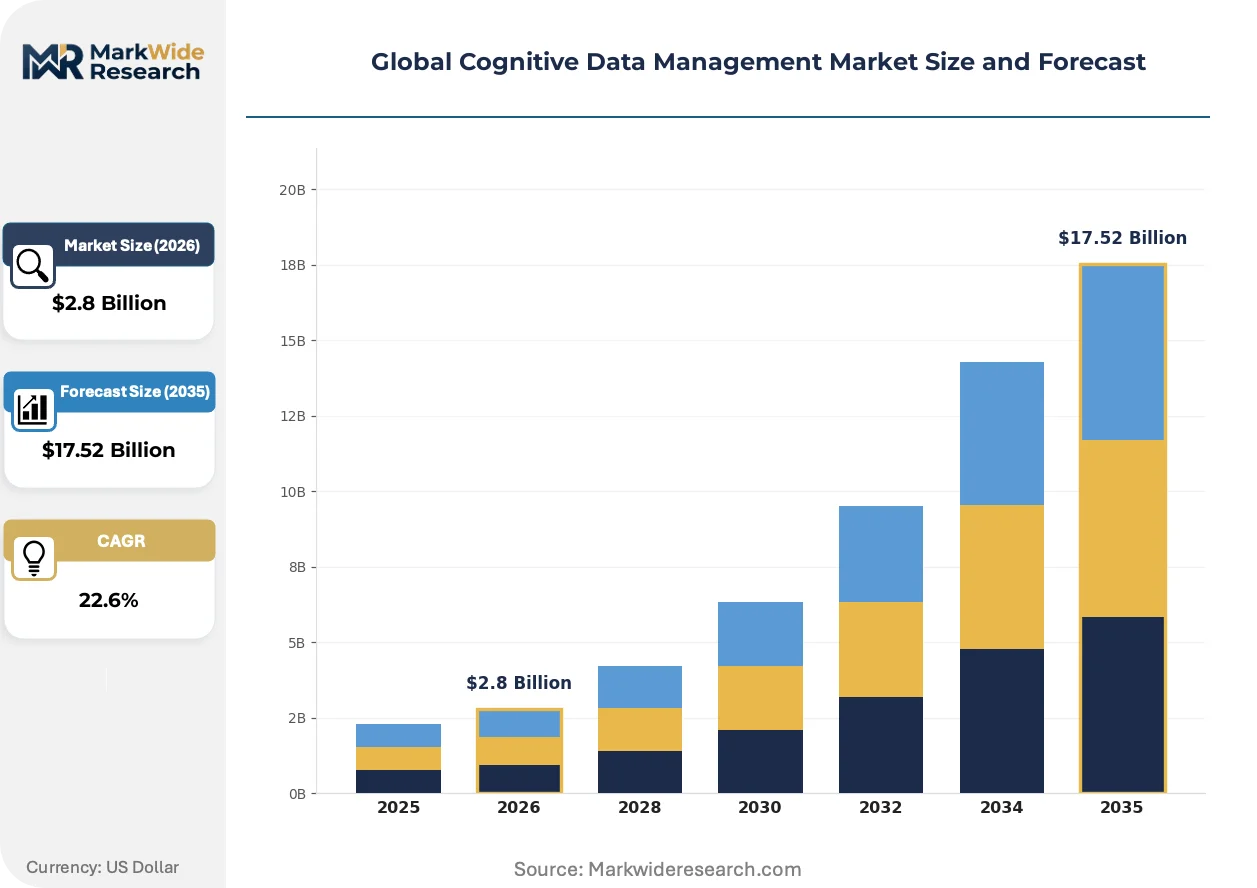
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $17.52 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Data Type: Structured Data, Unstructured Data, Semi-Structured Data, Metadata, Streaming Data Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User Industry: Banking, Telecommunications, Manufacturing, Media & Entertainment, Government Solution Offering: Data Integration, Data Governance, Data Security, AI & Analytics, Data Storage |
| Companies Covered | SAP, Informatica, IBM, Cognizant, SAS, Microsoft, Salesforce, HPE, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cognitive Data Management Market Strategic Shifts & Innovations
Natural language processing engines trained on domain-specific corpora are replacing generic classification models, compressing accuracy improvement cycles from quarters to weeks.
Foundation-model-powered metadata extraction is consolidating vendor positioning as platforms embed large language models directly into governance workflows rather than bolt-on integrations. Healthcare providers in the United States are deploying these systems to auto-classify decades of unstructured radiology reports. The structural consequence is collapsing the addressable market for standalone data cataloging tools into comprehensive platform bundles.
The EU AI Act's risk-based classification system is mandating algorithmic impact assessments for high-stakes automated decisions, forcing vendors to bake explainability modules into standard offerings. Financial institutions in Frankfurt and Paris face the strictest enforcement timelines. Deployment patterns show these buyers prioritizing European-hosted solutions to satisfy data localization requirements even at premium pricing.
Subscription pricing for cognitive data platforms is displacing perpetual licensing as procurement teams favor operational expenditure treatment and rapid scaling flexibility. Mid-market manufacturers in Japan and South Korea are driving this shift, negotiating consumption-based contracts tied to actual data volumes processed. Vendor response has focused on tiered service levels that align cost with governance maturity rather than one-size-fits-all enterprise agreements.
Global Cognitive Data Management Market Segmentation
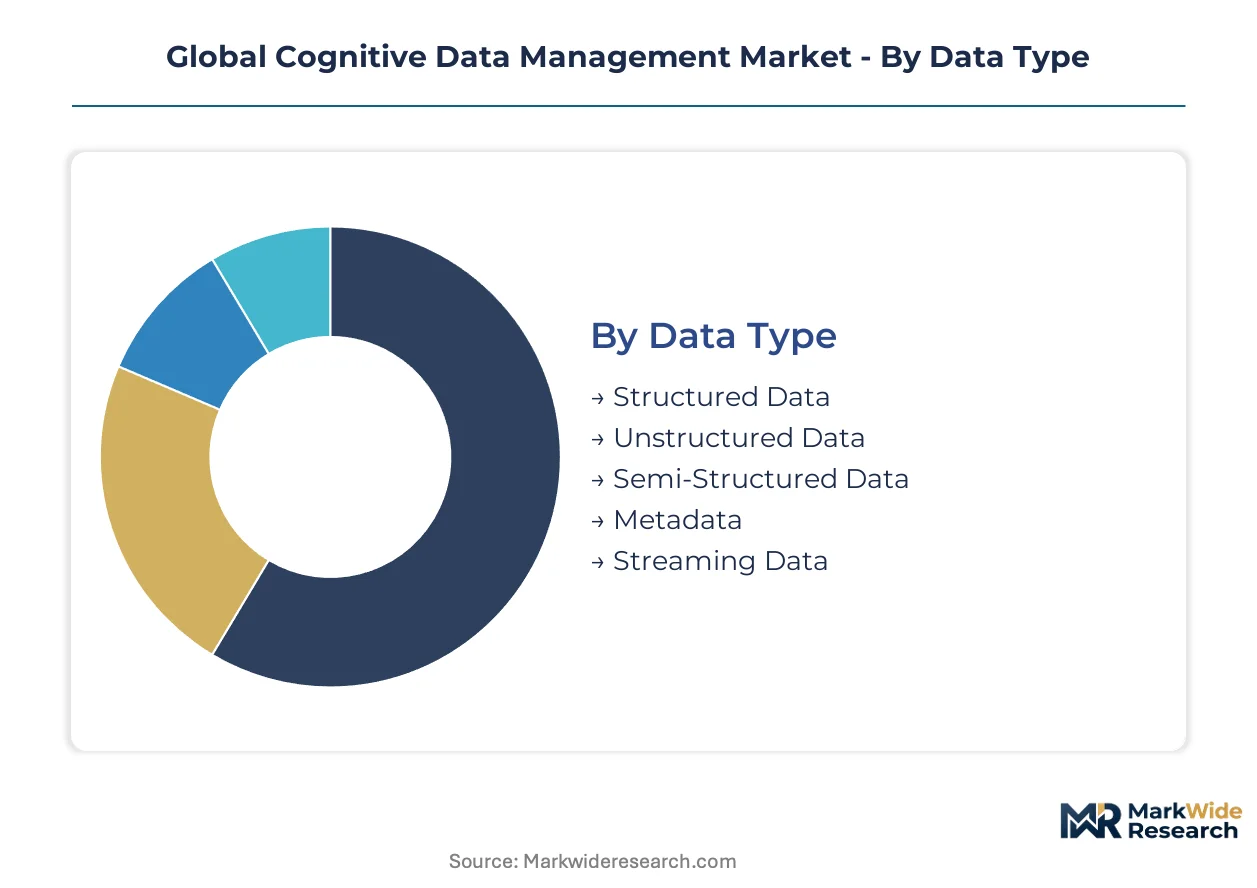
Cognitive data management platforms segment across four critical dimensions that determine architectural choices, pricing tiers, and deployment complexity. Each category reveals distinct buyer priorities: data type dictates processing infrastructure, deployment model governs compliance posture, end-user industry shapes workflow integration, and solution offering defines competitive positioning.
Data Type:
Volume concentrates in structured repositories, yet premium pricing attaches to streaming and unstructured formats where governance automation delivers measurable labor savings.
- Structured Data:Relational databases and transactional systems with predefined schemas dominate enterprise data estates. Demand concentrates among Frankfurt-based financial institutions automating regulatory reporting under ECB stress-testing mandates.
- Unstructured Data:Video, image, and free-text assets resist traditional schema mapping. Healthcare networks in the United States prioritize this segment to auto-classify decades of radiology reports and clinical notes for HIPAA-compliant retrieval.
- Semi-Structured Data:JSON, XML, and log files bridge rigid and free-form formats.
- Metadata:Data about data assets enables automated lineage tracking and policy enforcement.
- Streaming Data:Continuous ingestion pipelines demand sub-second latency classification.
Mature deployment sits with Structured Data. Newer deployment is concentrated in Streaming Data.
Deployment Model:
Cost tier stratification separates sovereign-hosted private infrastructure from elastic public consumption, with hybrid architectures commanding mid-market expansion.
- On-Premises:Dedicated hardware installations within enterprise data centers satisfy air-gapped security requirements. Defense contractors and classified research facilities in the United States maintain this model despite higher capital intensity.
- Public Cloud:Shared-tenant infrastructure delivers consumption-based scaling. Mid-market manufacturers in Japan and South Korea favor this tier for rapid pilot-to-production transitions without facility investments.
- Private Cloud:Single-tenant virtualized environments balance control with operational flexibility.
- Hybrid Cloud:Orchestrated workloads across on-premises and cloud substrates reconcile data residency with burst compute.
- Multi-Cloud:Distributed deployments across AWS, Azure, and GCP reduce vendor lock-in.
Procurement maturity clusters around On-Premises. Fastest procurement velocity is occurring in Hybrid Cloud.
End User Industry:
Application intensity varies sharply: banking and telecommunications drive platform complexity, while manufacturing and government prioritize compliance automation over analytical depth.
- Banking:Core banking modernization and real-time fraud detection demand millisecond-latency governance. Tier-one institutions in Singapore deploy cognitive platforms to satisfy MAS technology risk management guidelines while replacing COBOL-based lineage tracking.
- Telecommunications:Subscriber data management and 5G network slicing generate massive metadata volumes. European operators leverage these tools to automate GDPR-compliant data retention across distributed infrastructure.
- Manufacturing:Supply chain traceability and quality documentation drive adoption.
- Media & Entertainment:Content rights management and distribution optimization shape requirements.
- Government:Citizen data protection and inter-agency interoperability define procurement.
Established platform penetration is deepest in Banking. Emerging demand is expanding most quickly in Manufacturing.
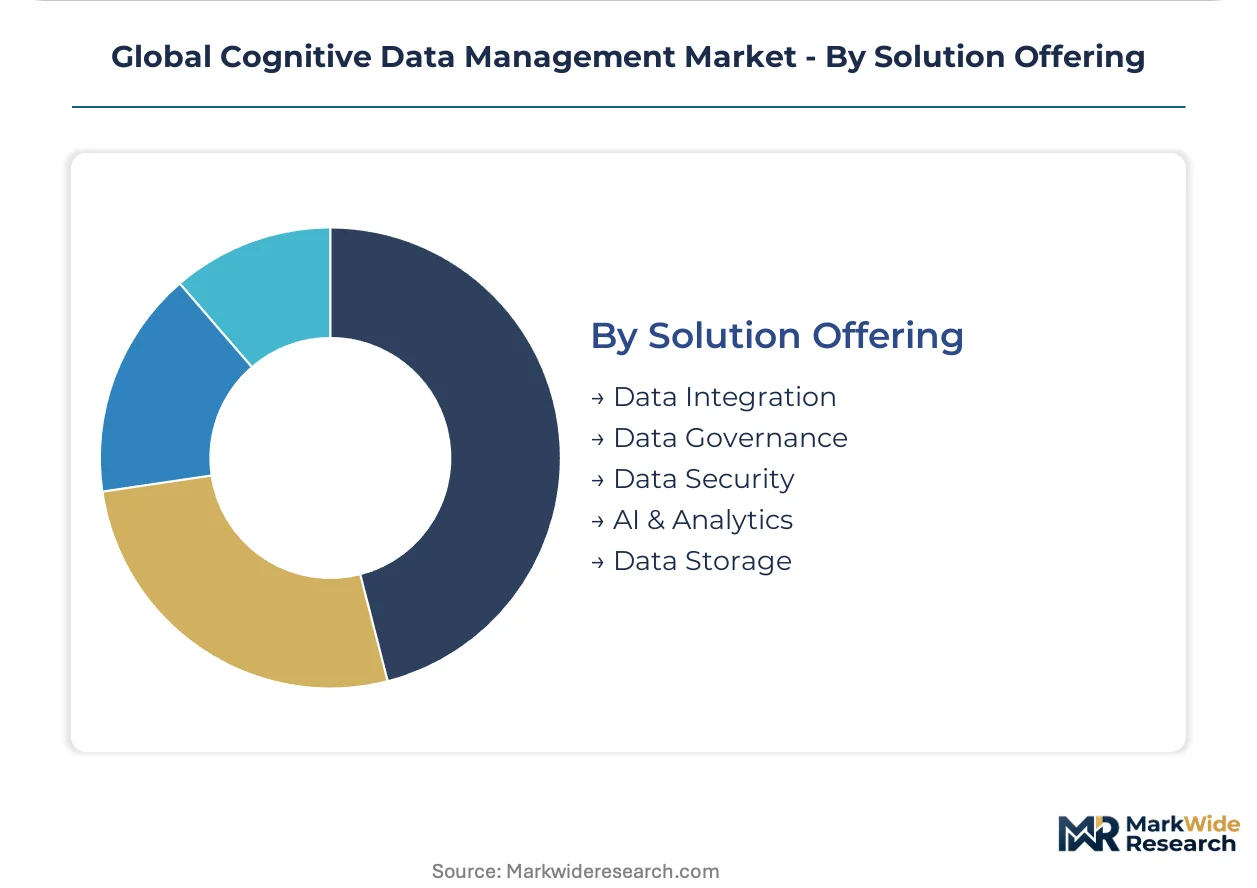
Solution Offering:
Margin concentration follows integration depth: standalone storage and security commoditize, while governance and AI analytics capture value from workflow embedding.
- Data Integration:Pipeline construction and schema normalization connect disparate sources. Brazilian pharmaceutical manufacturers prioritize this capability to satisfy ANVISA serialization mandates across distributed production facilities.
- Data Governance:Policy enforcement, lineage tracking, and cataloging constitute the platform core. EU AI Act compliance timelines are accelerating procurement among Paris and Frankfurt enterprises requiring explainable classification modules.
- Data Security:Encryption, access control, and threat detection protect information assets.
- AI & Analytics:Embedded machine learning and natural language processing automate insight generation.
- Data Storage:Tiered retention and retrieval infrastructure underlies all other functions.
Revenue maturity aligns with Data Governance. Steepest expansion trajectory is occurring in AI & Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement intensity clusters in the United States, Germany, and Japan, where federal cloud mandates, EU AI Act compliance timelines, and manufacturing digitization programs concentrate enterprise spending on cognitive governance platforms.
United States
Federal cloud modernization mandates and HIPAA interoperability rules drive hospital network procurement of automated classification engines. The Department of Veterans Affairs accelerates legacy system migration, creating demand for metadata lineage tools that bridge mainframe and cloud architectures. Healthcare clusters in Boston and the Research Triangle deploy these platforms to normalize decades of unstructured clinical records.
Germany
ECB stress-testing mandates and the EU AI Act's risk-based classification system force Frankfurt-based financial institutions to deploy explainable governance modules. Data localization requirements under GDPR and the proposed Data Act push enterprises toward sovereign-hosted private cloud deployments. Industrial manufacturers in Bavaria integrate cognitive platforms with ERP systems to automate supply chain documentation for CSRD reporting.
Japan
METI's Society 5.0 initiative and manufacturing digitization subsidies propel mid-market automotive suppliers toward consumption-based cognitive data contracts. Pharmaceutical traceability requirements under PMDA guidance drive deployment of automated metadata classification for batch record management. Industrial clusters in Nagoya and Osaka prioritize edge-to-cloud orchestration for real-time quality documentation.
Singapore
MAS technology risk management guidelines and cross-border data transfer protocols under the Personal Data Protection Act compel financial institutions to adopt sub-second latency governance pipelines. Sovereign cloud requirements for government contractors sustain demand for hybrid deployment models. The One-North technology district hosts regional headquarters vendors serving ASEAN banking modernization programs.
Brazil
ANVISA serialization mandates for pharmaceutical supply chains create first-mover opportunities for Portuguese-localized cognitive classification platforms. Central bank open finance regulations accelerate data governance investment among São Paulo-based tier-two banks. Manufacturing digitization in Minas Gerais and Rio Grande do Sul drives demand for automated quality documentation tied to export compliance.
Global Cognitive Data Management Market Key Industry Players
United States-based technology conglomerates anchor one tier through cloud-embedded governance stacks; European specialists hold differentiated positions in ERP-integrated compliance automation. Market structure tilts toward consolidation as foundation-model capabilities raise capital requirements for competitive metadata extraction. Three archetypes dominate: hyperscale cloud platforms, legacy enterprise software vendors with deep workflow integration, and vertical specialists in regulated industries. Competitive dynamics center on strategic partnerships with systems integrators and geographic expansion through localized compliance modules.
Within the cloud-native tier, Microsoft exemplifies platform bundling through Azure Purview and Fabric integration, while IBM occupies a position representing Watson-powered governance specialization. SAP anchors the ERP-integrated archetype, leveraging manufacturing workflow presence to embed cognitive capabilities directly into operational data flows. These three companies represent distinct competitive vectors: cloud productivity embedding, AI-native governance specialization, and enterprise resource planning extension.
| Leading Market Players |
|---|
| SAP |
| Informatica |
| IBM |
| Cognizant |
| SAS |
| Microsoft |
| Salesforce |
| HPE |
| Oracle |
| Others |
Cost & Logistics Intelligence
Federal cloud modernization mandates and HIPAA interoperability rules in the United States are compressing procurement timelines for cognitive data platforms, forcing vendors to absorb certification costs upfront while pricing subscription tiers to recover compliance investments over contract lifecycles.
Pricing Analysis
Volume concentrates in consumption-based SaaS tiers while margin capture sits with sovereign-hosted private deployments. Three-tier pricing structure across premium, standard, and economy levels separates fully managed EU AI Act-compliant instances from self-service public cloud tiers. Pricing pressure stems from mid-market manufacturers in Japan and South Korea negotiating usage-based contracts tied to actual data volumes processed. Healthcare networks in the United States exhibit highest price sensitivity due to constrained IT budgets, while Frankfurt-based financial institutions accept premium pricing for data localization guarantees.
Supply Chain Analysis
France's proposed Data Act and Germany's sovereign cloud requirements are reshaping vendor sourcing strategies toward EU-based infrastructure partners. Compute hardware concentrates in Taiwan, South Korea, and the United States; specialized AI accelerators draw from NVIDIA's foundry network and domestic Chinese alternatives. Single-source vulnerability in advanced GPU supply creates procurement risk for training-intensive classification engines. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
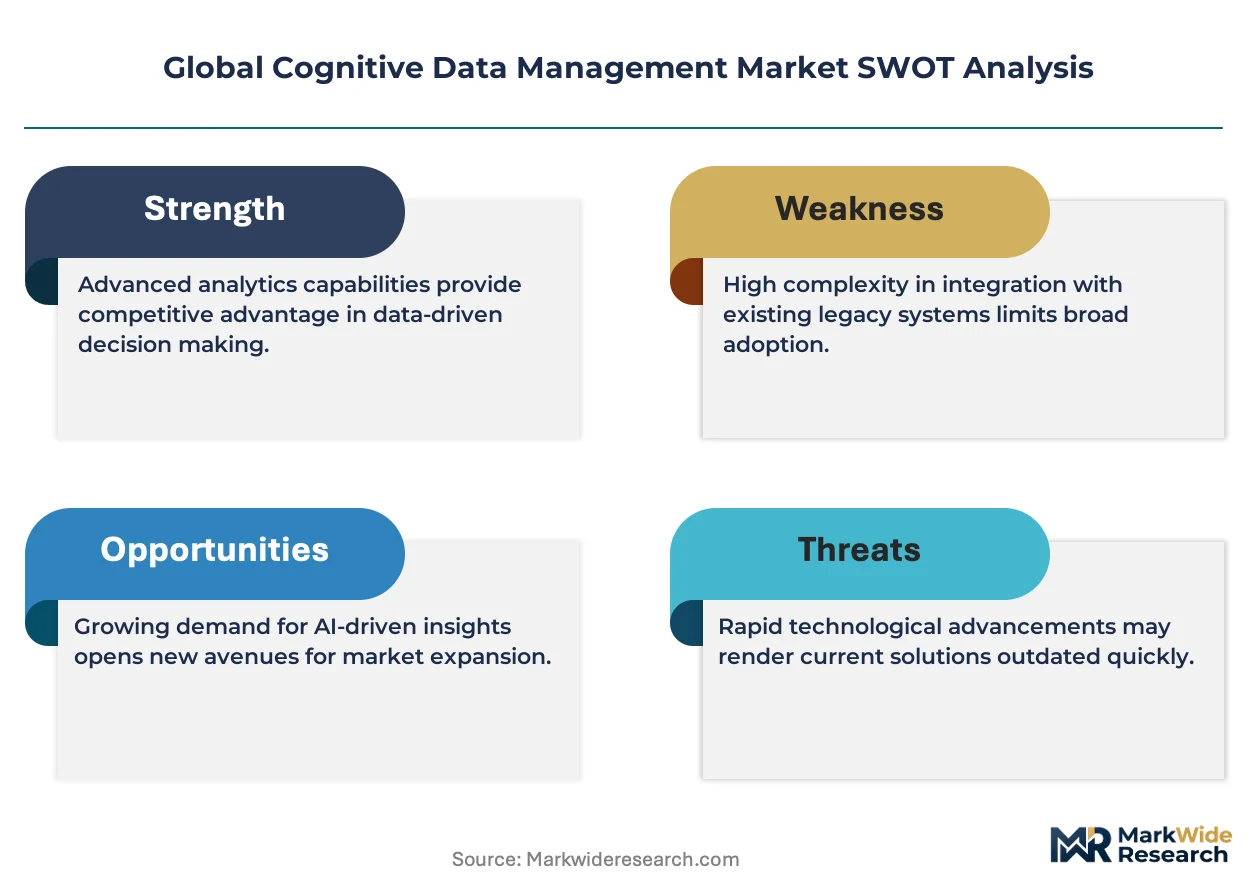
The EU AI Act's risk-based classification system creates a compliance moat where certification investment functions as barrier to entry, advantaging incumbents with established audit trails over capital-constrained challengers.
For Market Incumbents: Deploy embedded AI governance modules as the primary defensive lever. IBM and Microsoft should deepen integration between cognitive classification and existing productivity workflows to raise switching costs for hospital networks and financial institutions. SAP must accelerate Portuguese and Japanese localization to defend manufacturing ERP anchoring against cloud-native entrants. The threat of standalone data cataloging tools collapsing into platform bundles demands preemptive bundling of explainable lineage features. For New Entrants and Emerging Players: Enter via Brazilian pharmaceutical traceability and ASEAN banking modernization as whitespace targets. ANVISA serialization mandates create first-mover windows for Portuguese-localized cognitive classification platforms serving São Paulo-based manufacturers. Edge-to-cloud orchestration for autonomous vehicle fleets offers penetrable entry with 5G network slicing partnerships as the go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors vertical specialists with regulatory workflow depth over horizontal platform aspirants. Long-term viability hinges on embedded position in high-friction compliance environments rather than commodity data storage. Acquisition targets should demonstrate ISO 27001 certification completion and at least one named regulator relationship. The signal to watch is enforcement intensity calibration by national AI safety institutes, which will determine compliance cost allocation between vendors and customers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure Purview embedding into Microsoft 365 workflows captures healthcare procurement in Boston clusters. |
| Regulatory Localization | Portuguese-language classification modules unlock ANVISA pharmaceutical traceability contracts in Brazil. |
| Strategic Partnership | Systems integrator alliances accelerate Frankfurt bank deployments under ECB stress-testing timelines. |
| Acquisition of Specialist Firm | Vertical compliance expertise in HIPAA or GDPR enforcement commands premium positioning. |
| Geographic Expansion | Japanese METI subsidy alignment captures Society 5.0 manufacturing digitization budgets. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with chief data officers, healthcare IT procurement leads, regulatory compliance officers, and cloud platform engineers validated demand-side assumptions. FDA guidance documents, EMA submissions, EU AI Act implementation texts, and MAS technology risk circulars provided regulatory calibration. Bottom-up sizing of deployment volumes triangulated against top-down IT spending estimates from national statistical agencies.
Granularity-level modeling treated data type, deployment model, end-user industry, and solution offering as distinct forecast dimensions across the analysis window. Structured versus unstructured data splits, on-premises versus hybrid cloud trajectories, and banking versus manufacturing adoption curves received separate CAGR derivation. Hyperscaler capex disclosures and hospital network EHR modernization budgets informed infrastructure investment assumptions. Subscription pricing displacement trends and sovereign data residency requirements shaped revenue recognition modeling.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU AI Act enforcement acceleration or geopolitical fragmentation of cloud infrastructure standards. Forecasts reflect documented assumptions regarding regulatory timeline adherence and enterprise cloud migration velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
Europe Machine Learning As a Service Market
Machine Learning and Data Science
Global Machine Learning in Manufacturing Market
Machine Learning and Data Science
Cloud Machine Learning Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Global Computational Creativity Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Natural Language Processing Market
Machine Learning and Data Science
Global Image Recognition in CPG Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Asia-Pacific Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Europe Data Science Platform Market
Machine Learning and Data Science
Global Data Annotation Service Market
Machine Learning and Data Science
Machine Learning Operation Technology Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
Data Science Platform Market