
 Global Data Annotation Tools Market | 2026-2036
Global Data Annotation Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Annotation Tools Market Foresight
Enterprise AI labs and autonomous vehicle developers are bifurcating demand away from traditional academic and small-team buyers. Scale AI leverages its federal contracting relationships to anchor government and defense annotation workflows. Labelbox competes through vertical-specific workflow templates that reduce time-to-deployment for computer vision teams. Appen Limited sustains a distributed workforce model that controls cost structures across multilingual text and speech annotation pools.
Data annotation tools are software platforms that apply metadata labels, bounding boxes, semantic masks, transcription tags, or classification taxonomies to raw unstructured data, typically supporting formats from RGB imagery to LiDAR point clouds and waveform audio, with core functions including quality assurance pipelines, annotator workforce management, and export compatibility with TensorFlow, PyTorch, or ONNX training frameworks. Their primary commercial purpose is to transform unlabeled data into supervised learning inputs for machine learning model development. Image annotation solutions occupy the largest solution-type position due to persistent demand from autonomous driving and medical imaging pipelines. Cloud-based deployment leads in new contract value as hyperscaler integrations reduce infrastructure friction for technology providers. Sensor data labeling represents the fastest-expanding solution type as robotics and autonomous vehicle programs multiply LiDAR and radar annotation requirements.
The EU AI Act imposes documentation and traceability mandates on high-risk AI training datasets, compelling European buyers to prioritize annotation platforms with audit trails and provenance logging. The FDA's software-as-a-medical-device guidance in the United States shapes how health-tech firms validate image annotation workflows for diagnostic AI. China's SAMR algorithm recommendation provisions and GB standards for intelligent vehicle data processing create parallel compliance layers for suppliers operating across jurisdictions. Stakeholders must evaluate whether their annotation infrastructure can satisfy divergent regulatory evidence requirements without fragmenting operational architecture.
Market Dynamics
Autonomous vehicle programs are compressing annotation timelines from months to weeks, forcing infrastructure providers to re-architect quality assurance pipelines around real-time sensor fusion workflows rather than batch image processing.
Growth Catalysts
- EU AI Act documentation mandates:European high-risk AI deployers now require immutable audit trails for training data provenance, driving platform upgrades toward blockchain-anchored logging systems.
- LiDAR annotation automation:Robotics manufacturers are adopting neural-assisted point cloud labeling tools that reduce human-in-the-loop requirements for semantic segmentation tasks.
- California-Washington R&D clustering:Cloud hyperscaler proximity in these states concentrates demand for API-native annotation services with direct TensorFlow and PyTorch export compatibility.
Market Restraints
- Specialized annotator wage inflation:Rare expertise in 3D point cloud labeling and medical imaging ontologies commands premium compensation that erodes per-unit margins.
- Single-region workforce concentration:Distributed annotation labor pools cluster in specific emerging economies, exposing operations to geopolitical disruption and currency volatility.
- Regulatory fragmentation:Divergent evidence requirements between FDA software-as-a-medical-device guidance and China's GB standards for intelligent vehicles force redundant compliance architecture.
Strategic Opportunities
- Synthetic data generation convergence:Gaming engine-rendered training imagery paired with physics simulation is creating hybrid annotation workflows that reduce raw data collection costs.
- India's data localization incentives:The country's PLI scheme for AI infrastructure is attracting annotation platform operators to establish domestic compute and workforce nodes.
- Edge deployment models:On-premise annotation appliances for defense and healthcare buyers are opening channels previously dominated by SaaS-only vendors.
Industry Challenges
- Inter-annotator agreement variance:Subjective judgment in medical imaging and legal document classification creates quality control bottlenecks that automated consensus algorithms struggle to resolve.
- Legacy EHR integration friction:Hospital systems running decades-old DICOM archives face expensive middleware development to connect modern annotation APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Annotation Tools Market |
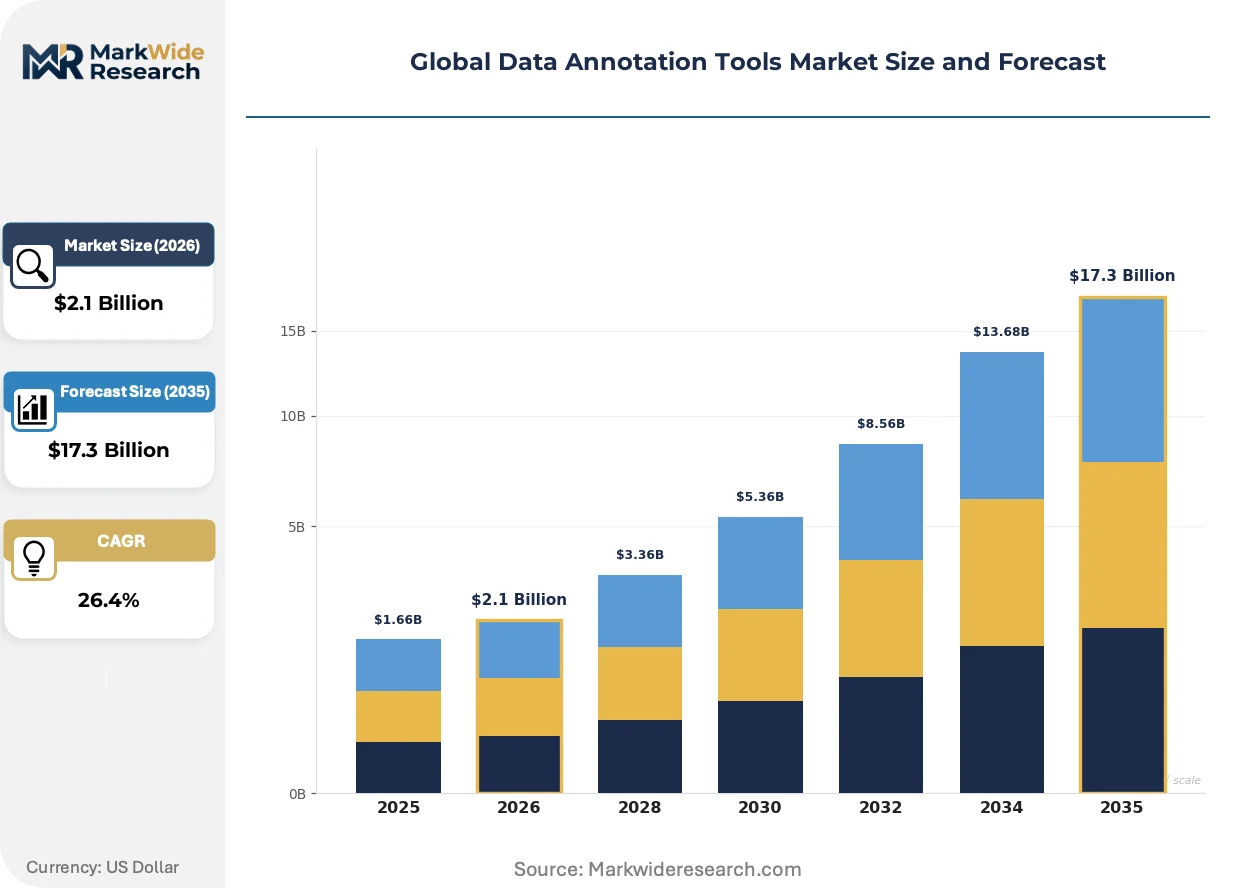
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $17.3 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Solution Type: Image Annotation, Text Annotation, Video Annotation, Audio Annotation, Sensor Data Labeling Use Case: Natural Language Processing, Computer Vision, Speech Recognition, Autonomous Vehicles, Robotics End User: Technology Providers, Research Institutions, Manufacturing Firms, Government Agencies |
| Companies Covered | Labelbox, iMerit, Scale AI, Amazon Web Services, SuperAnnotate, Appen Limited, CloudFactory, Alegion, TELUS International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Annotation Tools Market Shifts & Advancements
Foundation model architectures are compressing the annotation value chain by enabling zero-shot and few-shot learning that reduces labeled data requirements across multiple verticals simultaneously.
Active learning with uncertainty sampling is supplanting random batch annotation in computer vision pipelines. Autonomous vehicle developers at Waymo, Cruise, and Argo AI predecessors adopted this approach aggressively between 2021 and 2023. The technique enables model-in-the-loop selection of edge-case frames, cutting total annotation volume by half while preserving rare scenario coverage.
The FDA's software-as-a-medical-device guidance now requires algorithm change control plans that document training data drift. Diagnostic AI vendors must maintain versioned annotation histories for every model iteration. Radiology groups at Mayo Clinic and Mass General Brigham have responded by mandating DICOM-structured reporting with embedded provenance metadata.
Enterprise buyers are consolidating vendor relationships around platforms offering both workforce management and synthetic data generation. Computer vision teams at agricultural robotics firms and industrial inspection providers now reject point solutions lacking integrated 3D simulation capabilities. This preference shift is most visible in Germany's manufacturing belt, where KBA-regulated automotive suppliers demand unified annotation-simulation environments for homologation documentation.
Global Data Annotation Tools Market Segmentation
Regulatory divergence across the EU AI Act, FDA guidance, and China's GB standards fragments procurement requirements, forcing buyers to segment their annotation infrastructure by compliance jurisdiction rather than purely by technical function.
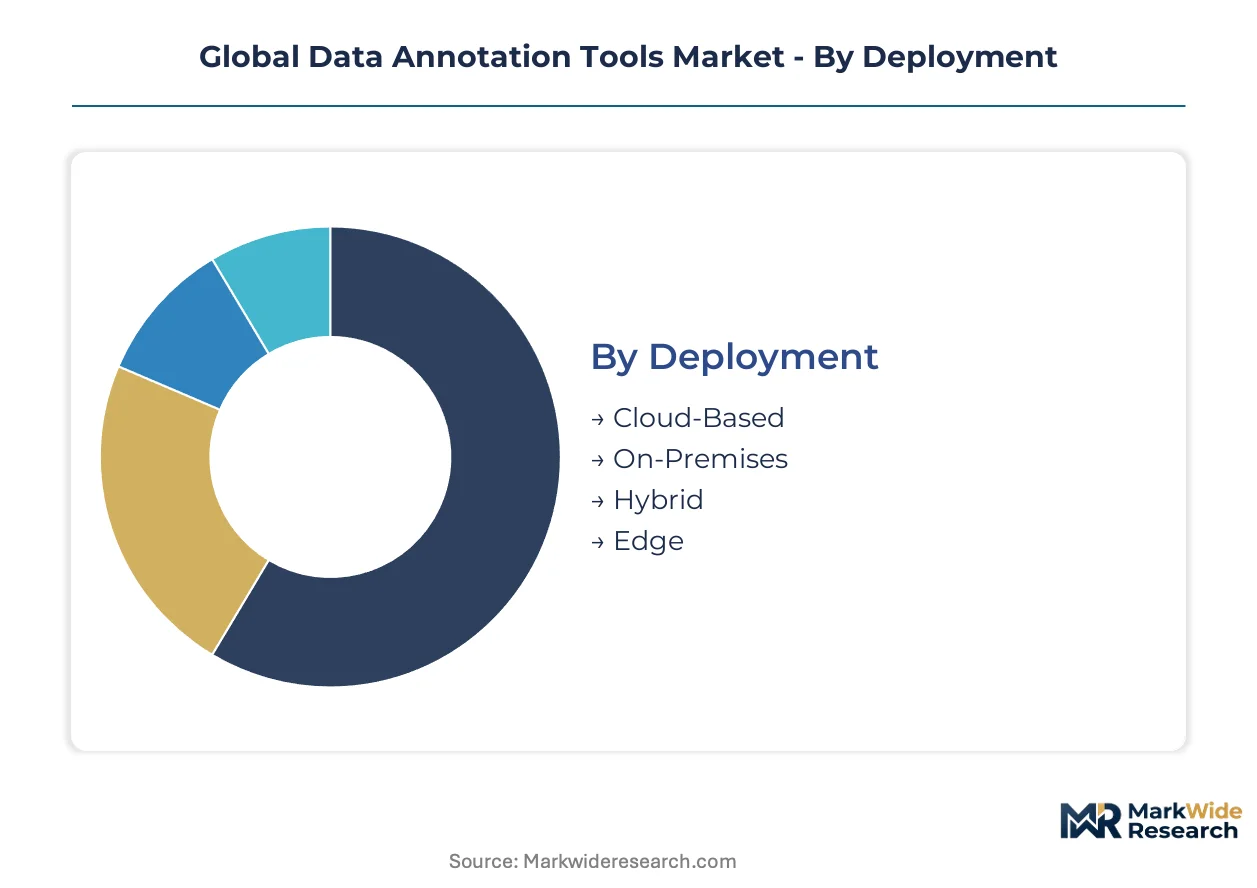
Deployment:
Regulatory differentiation separates cloud-native buyers seeking audit trails from defense and healthcare deployers requiring air-gapped infrastructure.
- Cloud-Based:Hyperscaler-integrated platforms dominate new contract value, with TensorFlow and PyTorch native exports reducing pipeline friction for California and Washington R&D clusters. European buyers prioritize blockchain-anchored logging to satisfy EU AI Act documentation mandates.
- On-Premises:Defense contractors and hospital systems mandate physical data sovereignty, with Mayo Clinic and Mass General Brigham requiring DICOM-structured reporting with embedded provenance metadata for FDA algorithm change control plans.
- Hybrid:Tiered workloads split sensitive pre-processing on-site from scalable labeling in cloud environments.
- Edge:On-premise annotation appliances serve robotics manufacturers with real-time sensor fusion requirements.
Established volume favors cloud-based deployment; emerging adoption favors edge appliances.
Solution Type:
Cost tier differentiation separates premium sensor fusion tooling from commoditized text annotation pools.
- Image Annotation:Bounding box and semantic mask tools occupy the largest revenue position, serving autonomous driving and medical imaging pipelines with DICOM-structured validation workflows. Waymo, Cruise, and Argo AI predecessors compressed timelines through active learning with uncertainty sampling.
- Sensor Data Labeling:LiDAR and radar point cloud annotation is expanding most quickly as robotics programs multiply 3D semantic segmentation requirements. Neural-assisted labeling reduces human-in-the-loop demands for KBA-regulated automotive suppliers.
- Text Annotation:Multilingual transcription and entity tagging serves NLP pipelines with distributed workforce cost structures.
- Video Annotation:Temporal frame labeling supports action recognition and surveillance AI with frame-interpolation automation.
- Audio Annotation:Waveform segmentation and speaker diarization powers speech recognition training with phonetic precision requirements.
Mature tooling dominates image annotation; synthetic data convergence favors sensor data labeling.
Use Case:
Application concentration tracks R&D clustering, with autonomous vehicle developers bifurcating demand from academic and small-team buyers.
- Autonomous Vehicles:Real-time sensor fusion workflows compress annotation timelines from months to weeks, forcing quality assurance re-architecture around LiDAR-camera-radar alignment. FDA and KBA documentation requirements shape tooling selection.
- Computer Vision:Agricultural robotics and industrial inspection providers reject point solutions lacking integrated 3D simulation, consolidating around unified annotation-simulation environments.
- Natural Language Processing:Foundation model architectures enable zero-shot learning that reduces labeled text requirements across multilingual corpora.
- Speech Recognition:Uncertainty sampling and active learning optimize phonetic edge-case coverage for conversational AI.
- Robotics:Manipulation and navigation training demands physics-simulated synthetic data paired with real-world annotation validation.
Computer vision anchors current procurement; autonomous vehicles drive infrastructure investment.
End User:
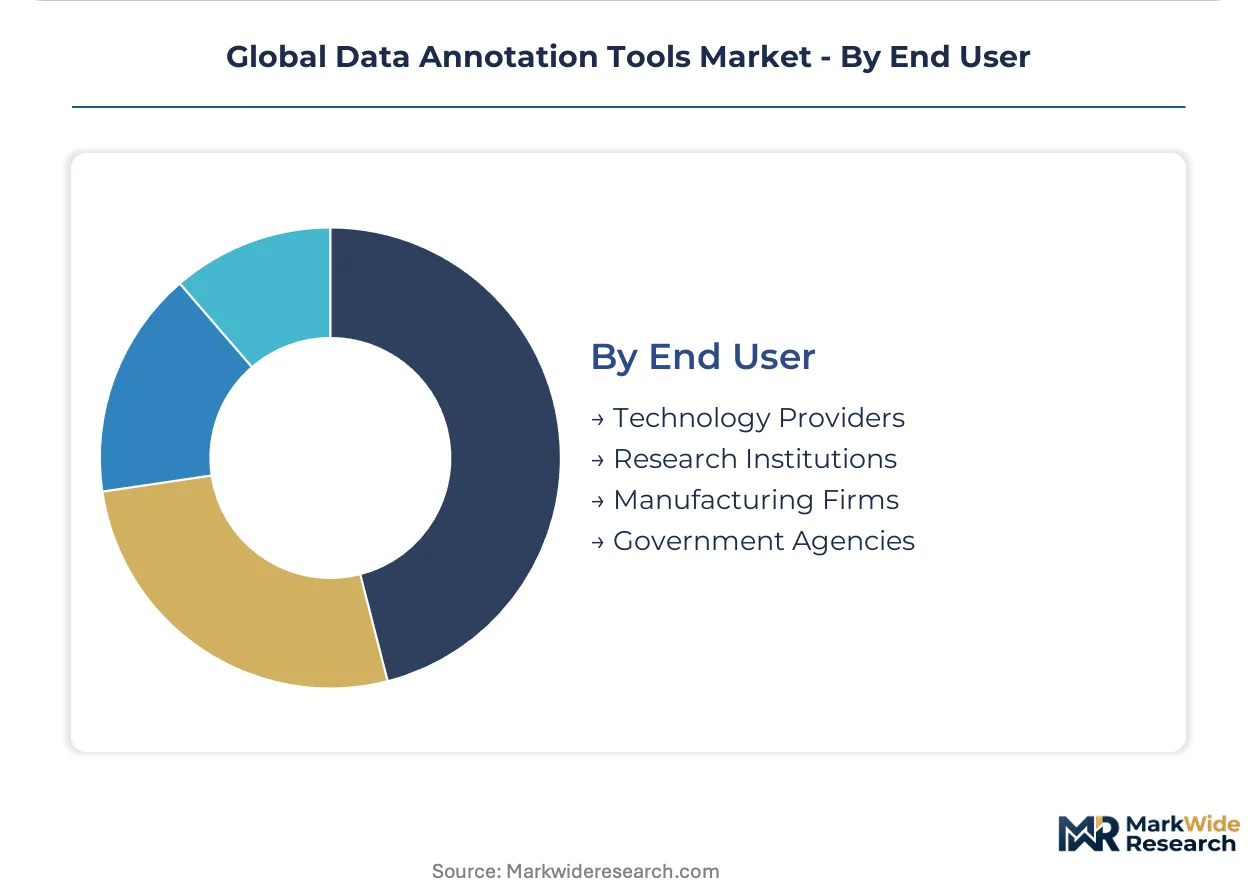
Customer type determines workforce model selection, with government buyers mandating federal contracting relationships and manufacturing firms prioritizing homologation-ready documentation.
- Technology Providers:API-native platforms with direct ML framework exports serve cloud-proximate R&D clusters in California and Washington.
- Government Agencies:Defense and intelligence buyers require air-gapped infrastructure with immutable audit trails and citizenship-verified annotator pools.
- Manufacturing Firms:Germany's automotive belt demands unified annotation-simulation environments satisfying KBA homologation standards.
- Research Institutions:Academic labs with constrained budgets prioritize open-source tooling and shared dataset repositories over enterprise platforms.
Technology providers concentrate contract value; government agencies impose the strictest compliance architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise AI labs and autonomous vehicle developers concentrate procurement in jurisdictions with dense cloud infrastructure and permissive data governance frameworks. Government buyers impose citizenship-verified workforce requirements that fragment vendor selection across national boundaries.
United States
California and Washington host the densest R&D clustering for API-native annotation services with direct TensorFlow and PyTorch export compatibility. The FDA's software-as-a-medical-device guidance mandates algorithm change control plans with versioned annotation histories. Mayo Clinic and Mass General Brigham radiology groups require DICOM-structured reporting with embedded provenance metadata for diagnostic AI validation.
Germany
KBA-regulated automotive suppliers in the manufacturing belt demand unified annotation-simulation environments for homologation documentation. The EU AI Act imposes immutable audit trail requirements for high-risk AI training data provenance. Stuttgart and Munich anchor procurement for neural-assisted point cloud labeling tools serving robotics and autonomous vehicle programs.
China
SAMR algorithm recommendation provisions and GB standards for intelligent vehicle data processing create parallel compliance layers for cross-jurisdictional suppliers. MIIT-backed AI infrastructure investments concentrate annotation platform development in Beijing and Shenzhen. Domestic technology providers prioritize air-gapped deployment models for defense and government buyers.
India
The PLI scheme for AI infrastructure attracts annotation platform operators to establish domestic compute and workforce nodes. CDSCO guidance on medical device software shapes validation requirements for health-tech annotation workflows. Bangalore and Hyderabad host distributed workforce pools for multilingual text and speech annotation with cost-controlled structures.
United Kingdom
London-based computer vision teams reject point solutions lacking integrated 3D simulation capabilities for agricultural robotics and industrial inspection. The Information Commissioner's Office guidelines on automated decision-making influence training data documentation standards. Cambridge and Oxford research clusters sustain open-source tooling adoption over enterprise platform procurement.
Global Data Annotation Tools Market Competitive Landscape
Player mix skews toward venture-backed workflow platforms and federal contracting specialists with divergent margin structures. Scale AI leverages citizenship-verified annotator pools and defense relationships to anchor government procurement. Labelbox competes through vertical-specific templates that compress deployment timelines for computer vision teams. Appen Limited sustains distributed workforce models across multilingual corpora. Consolidation pressure intensifies as enterprise buyers demand unified annotation-simulation environments rather than point solutions.
Among venture-scale workflow platforms, Labelbox, Scale AI, and SuperAnnotate occupy positions that exemplify the API-native archetype with direct ML framework integration. These companies anchor procurement for technology providers in California-Washington R&D clusters. Federal contracting relationships distinguish Scale AI within the government-agency segment. Appen Limited represents the distributed workforce archetype with cost structures spanning multilingual text, speech, and image annotation pools. CloudFactory and iMerit sit within mid-scale service tiers that compete on workforce management automation rather than platform technology differentiation. The vendor base fragments further across synthetic data generation specialists and edge-deployment appliance manufacturers serving defense and healthcare buyers with air-gapped requirements.
| Leading Market Players |
|---|
| Labelbox |
| iMerit |
| Scale AI |
| Amazon Web Services |
| SuperAnnotate |
| Appen Limited |
| CloudFactory |
| Alegion |
| TELUS International |
| Others |
Supply & Pricing Matrix
Capacity utilization at cloud hyperscaler data centers in California and Washington creates scale economies that compress per-unit annotation costs while simultaneously concentrating supply power among API-native platform providers. This concentration shapes price floors across deployment tiers and forces tier-two vendors toward workforce arbitrage strategies.
Pricing Analysis
Cost-plus contracts with annotator wage indexation dominate enterprise procurement, particularly for LiDAR and medical imaging workflows where specialized labor commands premium rates. Three-tier pricing structure across premium sensor fusion tooling, standard image annotation, and economy text transcription reflects certification-grade differentiation and vertical integration depth. Pricing pressure stems from synthetic data generation tools that reduce raw annotation volume requirements. Academic research institutions exhibit highest price sensitivity; defense contractors with air-gapped mandates show lowest sensitivity to unit costs.
Supply Chain Analysis
India and the Philippines anchor distributed workforce pools for multilingual text and speech annotation, while Germany and the United States concentrate sensor fusion tooling development. Raw material dependencies include GPU compute capacity from NVIDIA and AMD, cloud storage from AWS and Azure, and citizenship-verified labor pools for government contracts. Single-region workforce concentration exposes operations to geopolitical disruption and currency volatility. Distribution runs through direct enterprise sales for large contracts and self-serve API portals for developer teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-classification mandates represent a regulatory inflection that accelerates platform consolidation around audit-capable infrastructure, compressing timelines for compliance-ready deployment.
For Market Incumbents: Fortify defensive moats through backward integration into synthetic data generation engines and citizenship-verified workforce nodes in India. Scale AI's federal contracting relationships demonstrate how defense channel control creates switching-cost barriers. Prioritize blockchain-anchored logging investments to satisfy EU AI Act documentation mandates before competitors achieve certification parity. For New Entrants and Emerging Players: Differentiate on edge-deployment appliances for hospital systems and defense buyers requiring physical data sovereignty. White-space concentration sits with KBA-regulated automotive suppliers in Germany demanding unified annotation-simulation environments. Go-to-market leverage rests on pre-certified compliance templates that compress procurement cycles for European high-risk AI deployers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms combining workforce management with synthetic data generation capabilities. Long-term viability hinges on synthetic-real hybrid workflow adoption across robotics and autonomous vehicle pipelines. Acquisition target archetype: venture-scale annotation platforms with established hyperscaler integrations and dormant defense channel relationships. Signal to watch: FDA algorithm change control plan submission volumes from diagnostic AI vendors as leading indicator of provenance-logging infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies annotation workflows with TensorFlow and PyTorch exports for California-Washington R&D clusters. |
| Acquisition of Specialist Firm | Captures synthetic data generation capabilities that reduce raw collection costs for robotics manufacturers. |
| Geographic Expansion | Establishes domestic compute nodes in India under PLI scheme incentives for cost-controlled workforce scaling. |
| Strategic Partnership | Links annotation platforms to KBA homologation documentation requirements for German automotive suppliers. |
| Product Launch | Introduces blockchain-anchored logging systems satisfying EU AI Act immutable audit trail mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings from annotation platform operators, hyperscaler capex disclosures, and EU regulatory guidance documents. Data collection encompassed CTOs at autonomous vehicle developers, AI lab directors at enterprise technology providers, procurement officers at hospital systems, and regulatory affairs leads at diagnostic AI vendors. Bottom-up segment sizing triangulated against top-down market envelope validation from trade association publications and venture capital investment databases.
Segmentation dimensions modeled include deployment architecture, solution type, end-user category, and regional regulatory cluster across the projection horizon. CAGRs derived from growth driver elasticity analysis and technology adoption curve positioning. Industry-specific forecast inputs incorporated FDA software-as-a-medical-device guidance trajectory and EU AI Act implementation timelines for high-risk AI system documentation requirements.
Material uncertainties — synthetic data substitution rates, annotator wage inflation in specialized categories, and regulatory enforcement variance across jurisdictions — sit outside the modeled envelope. Forecasts reflect assumptions about continued cloud infrastructure investment concentration and foundation model architecture maturation. Recalibration cycles align with material shifts in EU AI Act guidance interpretation and FDA diagnostic AI validation precedent.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Data Science Platform Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Europe Data Science Platform Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Global Machine Learning in Manufacturing Market
Machine Learning and Data Science
Europe Machine Learning As a Service Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Global Image Recognition in CPG Market
Machine Learning and Data Science
Natural Language Processing Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Cloud Machine Learning Market
Machine Learning and Data Science
Semantic Knowledge Graphing Market
Machine Learning and Data Science
Asia-Pacific Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Speech-To-Text API Market
Machine Learning and Data Science
Machine Learning (ML) Market