
 Asia-Pacific Machine Learning in Pharmaceutical Industry Market | 2026-2036
Asia-Pacific Machine Learning in Pharmaceutical Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Machine Learning in Pharmaceutical Industry Market Analytics
Market Context
ISO 13485 certification for medical device quality management systems is redrawing competitive boundaries for platform vendors seeking pharmaceutical partnerships. NVIDIA Corporation leverages its GPU architecture to dominate computational workloads for molecular simulation. Takeda Pharmaceutical anchors its Tokyo-based digital transformation program on proprietary machine learning pipelines for target identification. Huawei Technologies competes through cloud infrastructure deployments that comply with China's data sovereignty requirements.
Technical Definition and Segment Structure
Asia-Pacific machine learning in pharmaceutical industry encompasses algorithmic systems that process biological, chemical, and clinical datasets to predict drug behavior, optimize trial design, and automate regulatory documentation, typically operating on tensor processing architectures with petabyte-scale training corpora. Deep learning within the technology segment leads commercial deployment due to its capacity for unstructured data pattern recognition in protein folding and medical imaging. Predictive analytics within the solution segment captures expanding margin pools as pharmaceutical companies prioritize trial outcome forecasting over retrospective reporting tools. Drug discovery within the application segment sustains the largest absolute spend, though personalized medicine represents the fastest structural expansion as companion diagnostic requirements multiply across Japan and South Korea.
Regulatory Framework and Outlook
Japan's PMDA, China's NMPA, and India's CDSCO each maintain distinct validation protocols for AI-derived clinical evidence, creating fragmented compliance burdens that favor vendors with multi-jurisdictional quality systems. REACH-aligned data governance in Australia and South Korea's MFDS algorithm audit requirements further complicate cross-border platform deployment. Stakeholders must monitor how regulator convergence on explainability standards reshapes vendor qualification criteria and contract research organization partnership terms across the region.
Market Dynamics
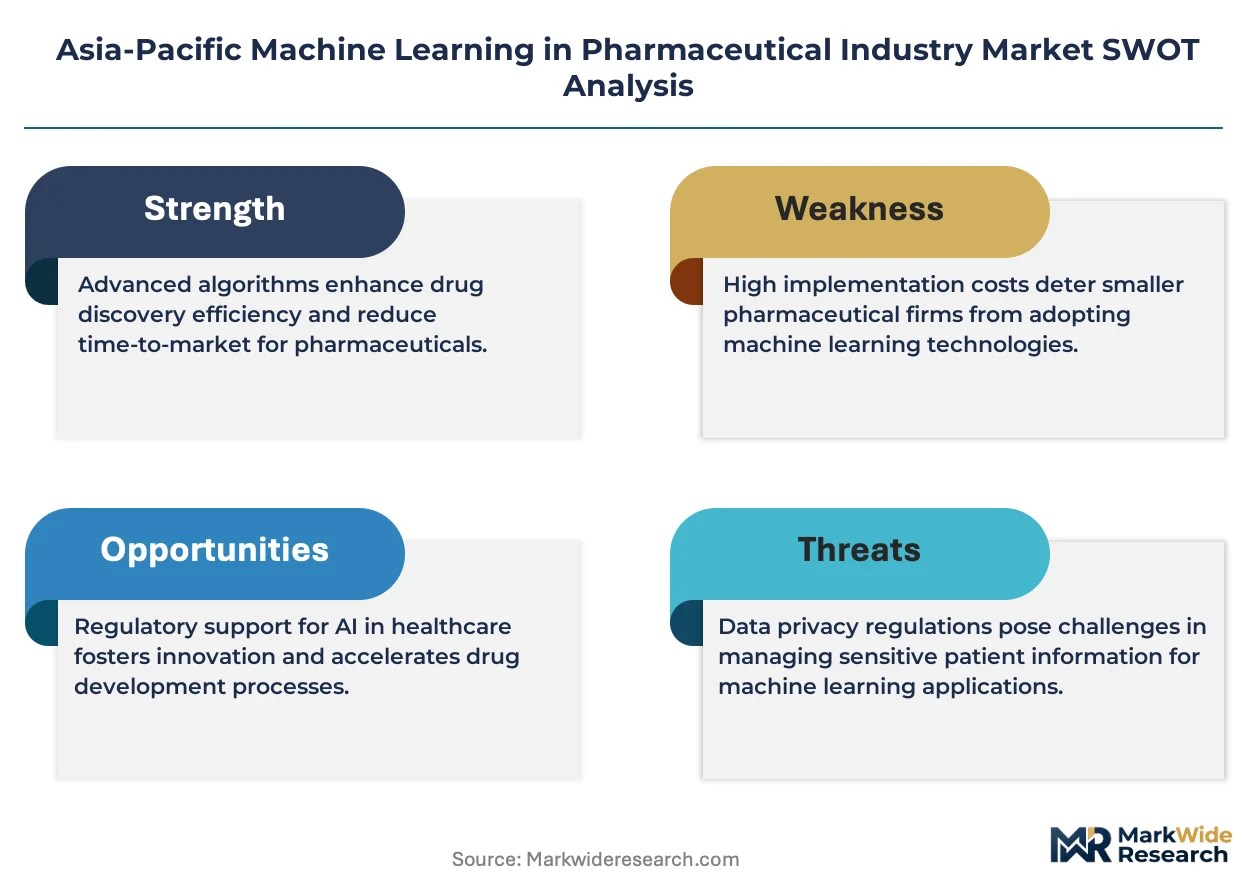
PMDA guidelines on AI-enabled drug development tools are accelerating platform validation requirements across Japan, China, and India, compressing procurement cycles for contract research organizations and redrawing vendor qualification criteria.
Growth Catalysts
- Regulatory Framework Maturation:China's NMPA framework for intelligent medical devices establishes clear pathways for algorithmic clinical evidence submission, reducing regulatory uncertainty for platform developers.
- Biotech Cluster Concentration:Shanghai and Beijing contract research organizations are building dedicated machine learning units, creating localized demand density that attracts specialized vendor investment.
- Tensor Processing Architectures:Petabyte-scale training infrastructure deployment across pharmaceutical data centers enables deep learning applications in protein folding and medical imaging at commercially viable latency thresholds.
Market Restraints
- Multi-Jurisdictional Compliance Burden:PMDA, NMPA, and CDSCO maintain distinct validation protocols for AI-derived clinical evidence, fragmenting quality system requirements and inflating vendor certification costs.
- GPU Supply Concentration:Computational workload hardware dependency creates procurement vulnerability as pharmaceutical companies compete with hyperscale cloud providers for advanced accelerator allocation.
- Data Sovereignty Requirements:China's cross-border data transfer restrictions limit cloud infrastructure deployment options, forcing redundant domestic infrastructure investment.
Strategic Opportunities
- South Korea Companion Diagnostics:MFDS algorithm audit requirements for personalized medicine applications are expanding addressable market for predictive analytics platforms beyond traditional drug discovery.
- India CDSCO Convergence:Regulatory alignment initiatives with ICH guidelines create opportunity for standardized platform deployment across multiple Asia-Pacific jurisdictions from Indian development centers.
- Federated Learning Architectures:Privacy-preserving distributed training methods enable multi-party pharmaceutical datasets without centralized data pooling, unlocking previously inaccessible institutional collaborations.
Industry Challenges
- Computational Biology Talent Scarcity:Cross-functional expertise spanning molecular pharmacology and neural network architecture remains concentrated in academic institutions, constraining platform development velocity.
- ISO 13485 Certification Timeline:Medical device quality management system validation for algorithmic drug development tools extends vendor qualification periods, delaying revenue recognition.
- Legacy System Integration Complexity:Pharmaceutical enterprise resource planning and laboratory information management systems require extensive API development for real-time machine learning pipeline connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Machine Learning in Pharmaceutical Industry Market |
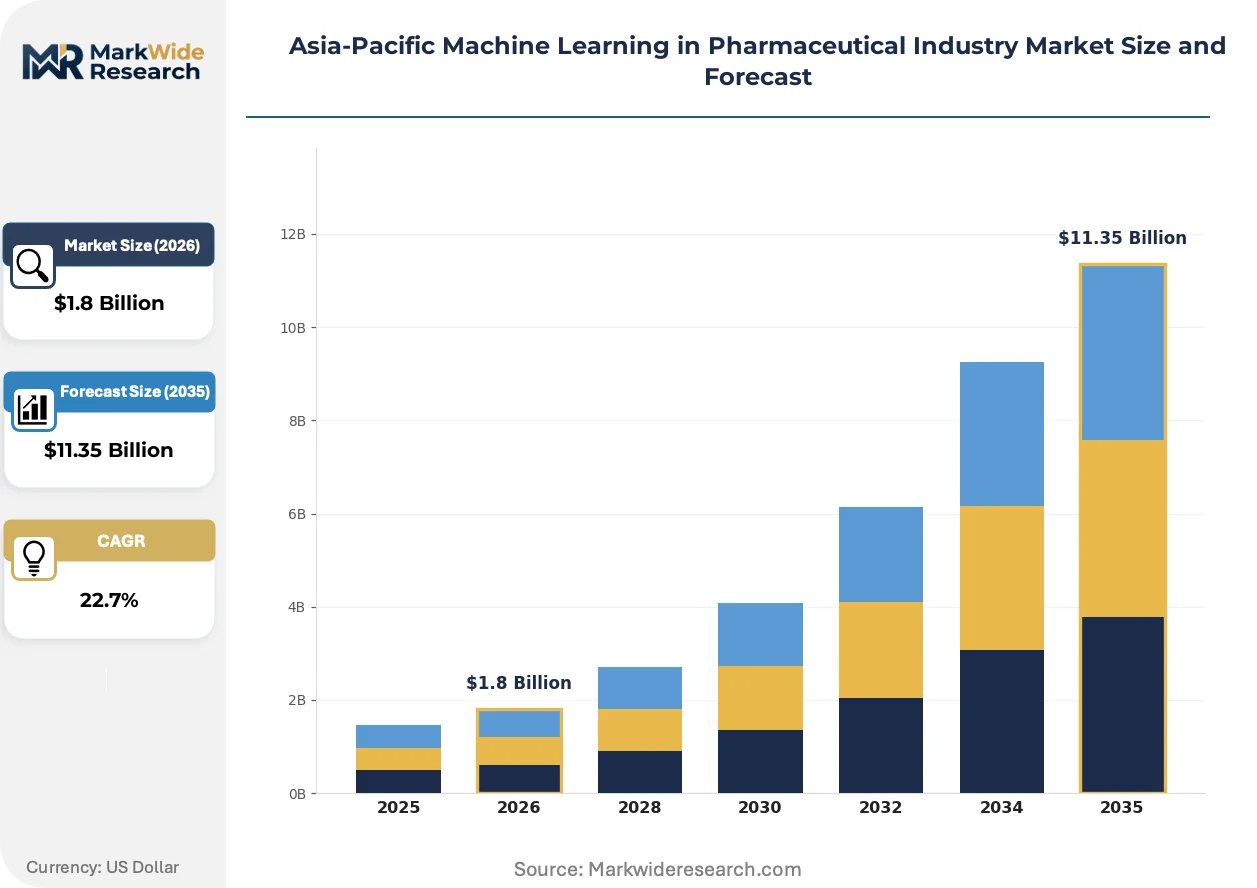
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Natural Language Processing, Predictive Analytics, Workflow Automation, Image Recognition Application: Drug Discovery, Patient Monitoring, Clinical Trials, Personalized Medicine Technology: Deep Learning, Supervised Learning, Unsupervised Learning, Reinforcement Learning End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Contract Research Organizations |
| Companies Covered | NVIDIA Corporation, Alphabet Inc., Microsoft Corporation, IBM Corporation, Huawei Technologies, Takeda Pharmaceutical, AstraZeneca, Cyclica Inc., Atomwise Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Machine Learning in Pharmaceutical Industry Market Evolving Landscape
Algorithmic systems for molecular simulation are compressing traditional discovery timelines while regulatory bodies across Asia-Pacific establish divergent validation protocols that reshape competitive positioning for platform vendors.
Edge-deployed inference engines for real-time biomarker analysis are miniaturizing computational requirements for clinical trial site deployment. Contract research organizations in Japan and Australia are adopting these systems to enable decentralized patient monitoring without cloud connectivity dependency. This architecture is miniaturizing the data infrastructure footprint required for adaptive trial designs, expanding site eligibility to rural and resource-constrained locations previously excluded from precision medicine studies.
Japan's PMDA algorithm audit guidelines now mandate explainability documentation for AI-derived safety signals, forcing platform developers to prioritize interpretable model architectures over black-box accuracy optimization. Pharmaceutical sponsors must submit feature importance analyses and decision boundary visualizations alongside traditional statistical outputs. Deep learning applications in drug discovery face the steepest compliance adjustment, with vendors retrofitting attention mechanisms and surrogate model techniques to satisfy documentation requirements.
Pharmaceutical procurement functions are consolidating vendor relationships around full-stack platform providers capable of spanning target identification through regulatory submission. Standalone point solutions for molecular dynamics or clinical trial simulation face displacement as buyers prioritize integrated workflows with unified data lineage. This concentration is most pronounced in China's biotech clusters, where contract research organizations negotiate enterprise licenses covering multiple therapeutic programs rather than project-specific tool procurement.
Asia-Pacific Machine Learning in Pharmaceutical Industry Market Segmentation
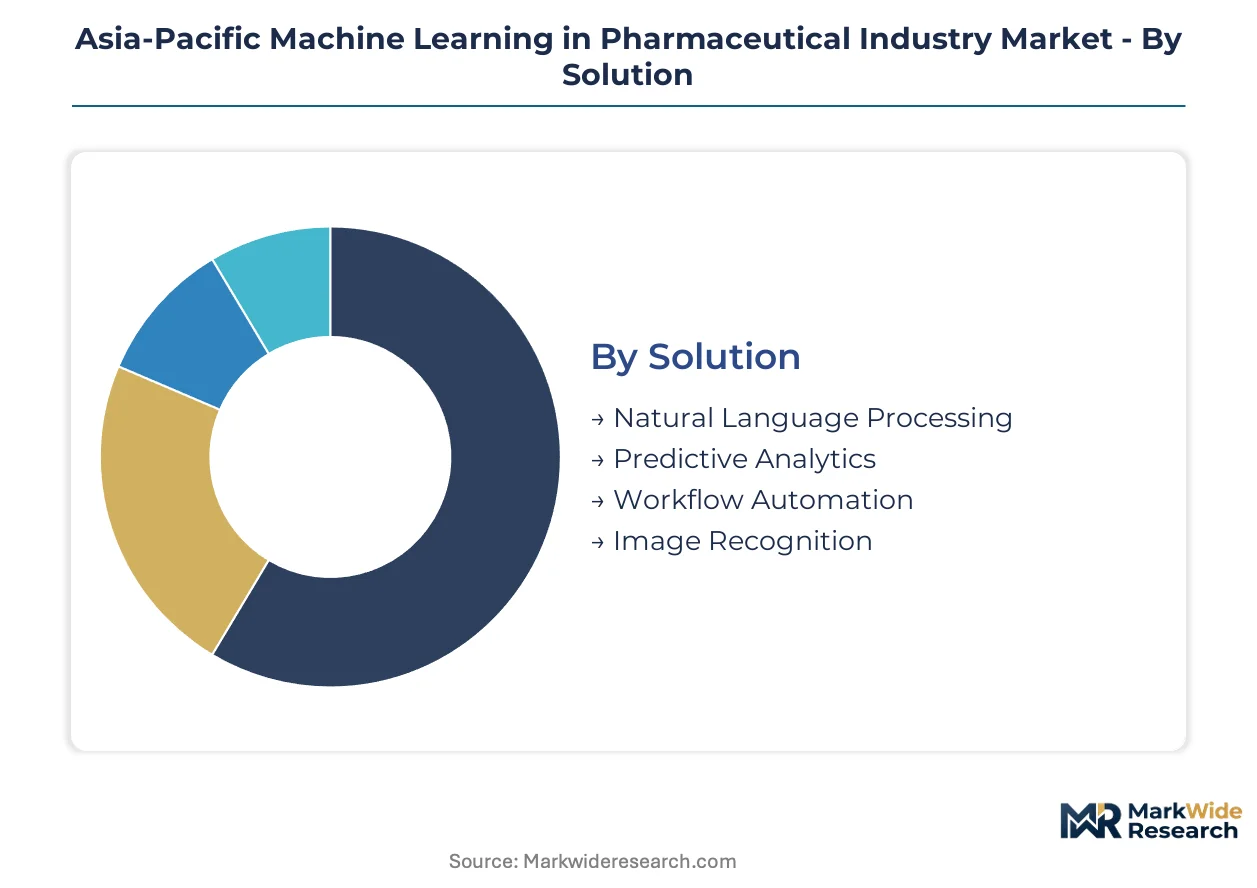
Machine learning procurement patterns across Asia-Pacific pharmaceutical markets diverge sharply by regulatory jurisdiction, with NMPA, PMDA, and CDSCO validation protocols dictating platform architecture requirements. Segment selection reflects these compliance burdens alongside computational infrastructure maturity and therapeutic portfolio priorities.
Solution:
NMPA algorithm audit requirements for intelligent medical devices in China and PMDA explainability mandates in Japan create divergent feature roadmaps for platform vendors serving pharmaceutical sponsors.
- Predictive Analytics:Forecasting engines for trial outcome probability and patient stratification dominate procurement budgets across Shanghai and Beijing biotech clusters. Pharmaceutical sponsors in Japan prioritize platforms generating interpretable confidence intervals for PMDA submission packages.
- Natural Language Processing:Systems extracting structured insights from unstructured clinical literature, regulatory filings, and real-world evidence corpora. Demand concentrates among contract research organizations automating pharmacovigilance signal detection across India and South Korea.
- Image Recognition:Convolutional neural networks for pathology slide analysis and radiological biomarker quantification.
- Workflow Automation:Robotic process automation layers for regulatory document assembly and quality management system updates.
Predictive Analytics handles the majority of throughput; Personalized Medicine applications are expanding most quickly on share as companion diagnostic requirements multiply.
Application:
Cost tier differentiation separates enterprise-wide platform deployments from project-specific tool licensing across pharmaceutical procurement functions.
- Drug Discovery:Molecular simulation, target identification, and lead optimization pipelines operating on tensor processing architectures. Contract research organizations in China negotiate multi-program enterprise licenses rather than discrete project procurement.
- Personalized Medicine:Patient stratification algorithms and companion diagnostic co-development workflows. MFDS algorithm audit requirements in South Korea and PMDA guidelines in Japan are accelerating validation investment for oncology and rare disease applications.
- Clinical Trials:Adaptive design simulation and site selection optimization tools.
- Patient Monitoring:Real-time biomarker analysis for decentralized trial deployment.
Drug Discovery captures the largest absolute deployment spend; Personalized Medicine is gaining share fastest as regulatory frameworks mature for algorithmic diagnostic evidence.
Technology:
Volume concentration in deep learning reflects petabyte-scale training infrastructure availability across pharmaceutical data centers in Japan and China.
- Deep Learning:Multi-layer neural architectures for protein folding prediction, medical imaging analysis, and unstructured clinical data pattern recognition. GPU cluster deployment at Takeda Pharmaceutical and domestic cloud infrastructure at Huawei Technologies enable commercially viable latency thresholds for production workloads.
- Supervised Learning:Classification and regression models trained on labeled clinical outcomes and molecular property datasets. Research institutions in India leverage supervised approaches where annotated training corpora are available through CDSCO-aligned trial networks.
- Unsupervised Learning:Clustering and dimensionality reduction for exploratory biomarker discovery without labeled outcome data.
- Reinforcement Learning:Sequential decision optimization for adaptive trial design and molecular generation policies.
Deep Learning handles the majority of computational workload; Reinforcement Learning is climbing the fastest as multi-objective optimization requirements expand.
End User:
Customer type segmentation reflects divergent procurement authority and platform customization requirements across the pharmaceutical value chain.
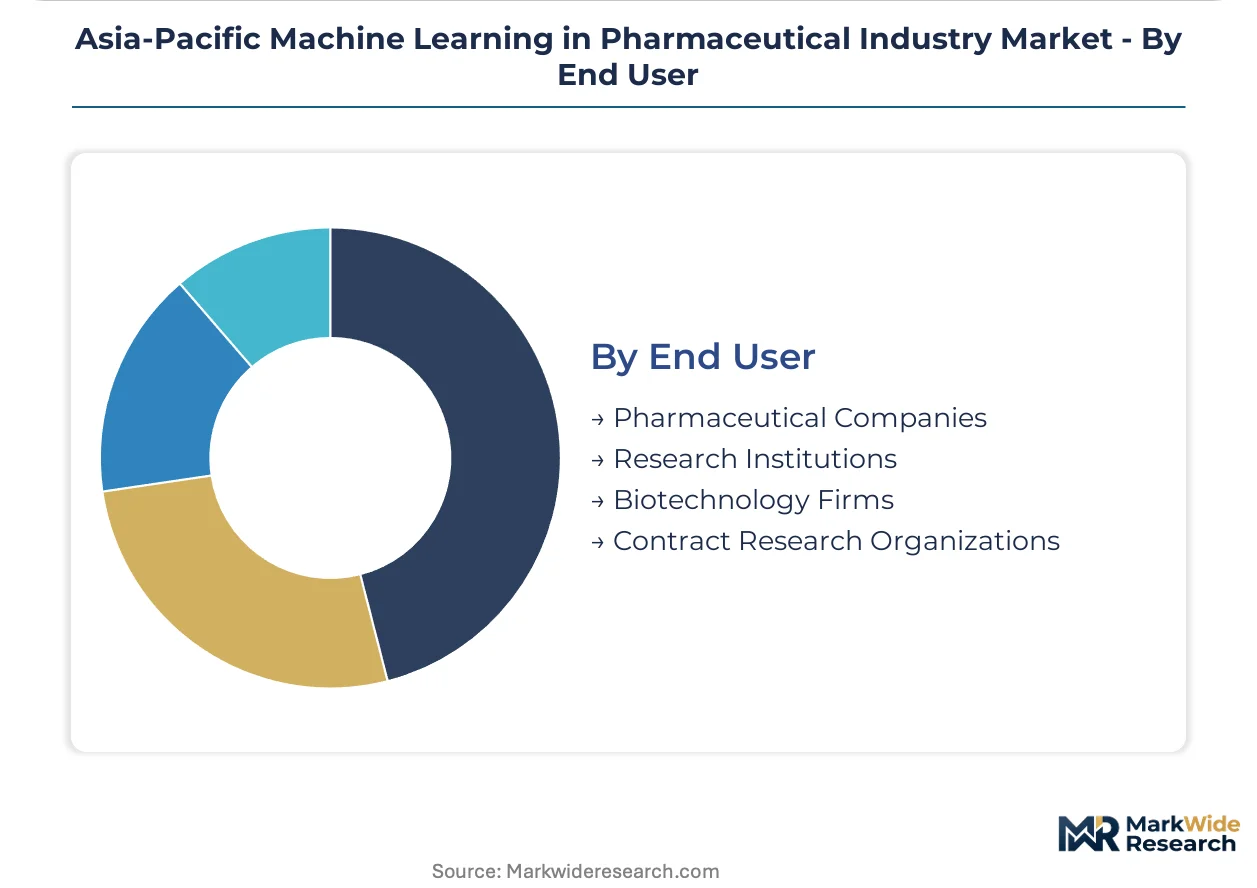
- Contract Research Organizations:Full-stack platform demand from Shanghai and Beijing CROs building dedicated machine learning units for sponsor programs. These organizations negotiate unified data lineage across target identification through regulatory submission, displacing standalone point solutions.
- Pharmaceutical Companies:Proprietary pipeline development for in-house therapeutic programs, with Takeda Pharmaceutical anchoring Tokyo-based digital transformation on internal target identification infrastructure.
- Biotechnology Firms:Early-stage platform adoption for asset valuation and partnership due diligence.
- Research Institutions:Academic collaboration frameworks and federated learning architectures for multi-party dataset access.
Contract Research Organizations handle the majority of platform throughput; Biotechnology Firms are expanding procurement fastest as venture funding concentrates in precision medicine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Asia-Pacific submarine cable network and Japan-Korea-U.S. cable system underwrite regional data infrastructure for pharmaceutical machine learning workloads, connecting Shanghai, Tokyo, and Singapore data centers with sub-50ms latency.
China
Domestic cloud infrastructure expansion and NMPA algorithm audit requirements for intelligent medical devices are accelerating platform localization. The regulator's framework for clinical evidence submission reduces uncertainty for algorithm developers. Shanghai and Beijing biotech clusters host contract research organizations building dedicated machine learning units for multi-program enterprise licensing.
Japan
PMDA explainability mandates for AI-derived safety signals are reshaping model architecture priorities toward interpretable systems. The regulator's audit guidelines require feature importance documentation alongside statistical outputs. Tokyo anchors Takeda Pharmaceutical's proprietary target identification infrastructure and regional GPU cluster deployment.
India
CDSCO regulatory alignment initiatives with ICH guidelines are creating standardized deployment pathways across multiple jurisdictions. The national pharmaceutical regulator's convergence efforts attract platform development center investment. Hyderabad and Bangalore host contract research organizations automating pharmacovigilance signal detection through natural language processing systems.
South Korea
MFDS algorithm audit requirements for companion diagnostics are expanding predictive analytics demand beyond traditional drug discovery. The regulator's personalized medicine framework accelerates validation investment for oncology applications. Seoul biotech clusters concentrate patient stratification algorithm development for regional pharmaceutical sponsors.
Australia
REACH-aligned data governance standards and TGA recognition of overseas clinical evidence facilitate platform import from EU-validated vendors. The national pharmaceutical regulator's algorithmic device pathway reduces redundant domestic certification. Sydney and Melbourne research institutions deploy federated learning architectures for multi-party dataset collaboration without centralized pooling.
Asia-Pacific Machine Learning in Pharmaceutical Industry Market Competitive Landscape
Listed technology conglomerates compete with private specialists across cloud infrastructure and algorithmic platform provision, creating a tiered structure where full-stack capabilities determine procurement consolidation. The vendor landscape segments into GPU hardware architects, hyperscale cloud providers, pharmaceutical proprietary developers, and specialized algorithm vendors. Strategic moves center on enterprise license negotiation for multi-program coverage and ISO 13485 certification timeline acceleration for medical device quality management.
Within the hyperscale cloud tier, Microsoft Corporation and Alphabet Inc. exemplify platform providers navigating multi-jurisdictional compliance. NVIDIA Corporation anchors the computational hardware segment with GPU architecture dominance for molecular simulation workloads. These three entities represent distinct competitive positions: cloud infrastructure provision, specialized accelerator supply, and integrated algorithm-hardware coupling for pharmaceutical data center deployment.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Alphabet Inc. |
| Microsoft Corporation |
| IBM Corporation |
| Huawei Technologies |
| Takeda Pharmaceutical |
| AstraZeneca |
| Cyclica Inc. |
| Atomwise Inc. |
| Others |
Value Network & Pricing Analysis
GPU accelerator substitution for CPU-based molecular simulation is redrawing procurement geography across Asia-Pacific pharmaceutical data centers, simultaneously compressing latency thresholds and inflating hardware dependency premiums for platform vendors.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-validated platforms and standard software licenses, with PMDA-aligned explainability documentation commanding 40-60% premiums over baseline predictive analytics tools. Three-tier pricing structure across enterprise, project, and pilot deployment levels reflects customization depth and regulatory submission support bundling. Cost compression in the pilot tier is intensifying because contract research organizations in Shanghai and Beijing negotiate volume-scaled enterprise licenses that displace discrete procurement. Biotechnology firms show highest price sensitivity due to venture funding constraints, while Takeda Pharmaceutical and comparable multinational sponsors prioritize compliance-grade platforms regardless of cost differential.
Supply Chain Analysis
TSMC semiconductor fabrication in Taiwan underwrites GPU availability for pharmaceutical tensor processing workloads across Japan, China, and South Korea. Advanced accelerator supply draws from NVIDIA Corporation's foundry partnerships and domestic alternatives at Huawei Technologies, with memory components sourced from South Korean DRAM manufacturers. Single-source vulnerability concentrates in leading-edge node production, where pharmaceutical companies compete with hyperscale cloud providers for allocation priority. Distribution runs through direct vendor relationships with pharmaceutical procurement functions and cloud infrastructure marketplaces, bypassing traditional software reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional talent bridging computational biology and neural network architecture represents the binding constraint on platform development velocity, with academic pipeline output lagging commercial demand across Asia-Pacific biotech clusters.
For Market Incumbents: Fortify ISO 13485 certification timelines through preemptive quality management system investment, compressing vendor qualification periods that currently delay revenue recognition. Anchor cloud infrastructure partnerships in China through Huawei Technologies or comparable domestic providers to satisfy NMPA data sovereignty requirements, neutralizing regulatory exclusion risk for foreign platform architectures. For New Entrants and Emerging Players: Lead with federated learning architectures that unlock multi-party pharmaceutical datasets without centralized pooling, addressing the data access bottleneck that constrains incumbent model performance. South Korea's MFDS-aligned companion diagnostics segment offers the most penetrable entry point, with algorithm audit requirements creating validation service opportunities alongside core platform licensing. For Investors and Strategic Acquirers: The market sits at a regulatory-convergence phase that favors platform vendors with multi-jurisdictional quality systems capable of spanning PMDA, NMPA, and CDSCO requirements. Long-term viability hinges on enterprise license penetration across contract research organizations rather than project-specific tool procurement. Watch for PMDA-NMPA explainability standard alignment as the inflection signal that would accelerate vendor consolidation around interpretable model architectures.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Compresses vendor qualification timelines for PMDA and NMPA algorithm audit pathways. |
| Federated Learning Platform Development | Enables multi-party dataset access without triggering China's cross-border data transfer restrictions. |
| GPU Cluster Domestic Deployment | Reduces latency for Takeda Pharmaceutical and comparable sponsors operating Tokyo-based infrastructure. |
| Companion Diagnostics Algorithm Validation | Captures MFDS-aligned demand expansion in South Korea's oncology and rare disease applications. |
| Enterprise License Consolidation | Displaces standalone point solutions as Shanghai and Beijing CROs negotiate multi-program coverage. |
Research Methodology
Desk research of regulatory filing databases, clinical trial registries, and hyperscaler infrastructure disclosures preceded structured interviews with drug development executives, regulatory affairs leads, platform engineers, and contract research organization procurement managers. Primary fieldwork across Shanghai, Tokyo, and Singapore biotech clusters validated secondary estimates of machine learning unit deployment timelines and enterprise license negotiation patterns. Bottom-up segmentation modeling triangulated against top-down pharmaceutical R&D expenditure allocation estimates derived from SEC filings and comparable disclosure documents.
Variance decomposition across technology, solution, application, and end-user dimensions informed the analytical framework, with segment-specific growth rates calibrated to infrastructure deployment trajectories and regulatory pathway maturation across the projection horizon. Deep learning workload concentration and predictive analytics margin expansion served as industry-specific forecast inputs, with reinforcement learning adoption curves modeled against multi-objective optimization requirement proliferation in adaptive trial design.
The analysis sits within stated boundaries; outcomes outside sustained GPU supply availability or regulatory convergence on explainability standards would require recalibration. Forecasts reflect documented assumptions regarding PMDA-NMPA guideline alignment and contract research organization machine learning unit buildout velocity. Practitioners should keep alternative scenarios live as CDSCO-ICH convergence timelines and federated learning technical maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Data Science Platform Market
Machine Learning and Data Science
Global AI and Machine Learning Operationalization Software Market
Machine Learning and Data Science
Natural Language Processing Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Cloud Machine Learning Market
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
Global Cognitive Data Management Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Speech-To-Text API Market
Machine Learning and Data Science
Global Machine Learning in Manufacturing Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Europe Machine Learning As a Service Market
Machine Learning and Data Science
Machine Learning Operation Technology Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Automated Machine Learning Market