
 Europe Data Science Platform Market | 2026-2036
Europe Data Science Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Science Platform Market Analytics
Data engineering talent scarcity across the European Union is unwinding project timelines and pushing enterprises toward managed-service platforms. Microsoft Corporation leverages its Azure ecosystem to anchor public-sector contracts in France and Germany. IBM Corporation sustains competitive positioning through vertical specialization in regulated industries. Databricks Inc. differentiates via unified lakehouse architecture that appeals to mid-market firms seeking simplified infrastructure.
A data science platform integrates data ingestion pipelines, distributed computing frameworks, and model lifecycle management tools to transform raw enterprise data into predictive and prescriptive intelligence. Cloud-based deployment leads segment expansion as organizations migrate from legacy on-premises clusters to elastic compute environments. Predictive analytics commands premium pricing in financial services, while machine learning solutions attract manufacturing clients automating quality control. Hybrid deployments retain relevance among energy and telecommunications operators managing sensitive operational data across sovereign boundaries.
GDPR enforcement by national data protection authorities shapes platform procurement requirements around data residency and algorithmic transparency. The EU AI Act establishes conformity obligations for high-risk automated decision systems that vendors must embed into product roadmaps. EMA guidelines on real-world evidence generation drive healthcare-specific demand for validated analytics workflows. Stakeholders must monitor evolving national implementations of the AI Act to anticipate procurement specification shifts.
Market Dynamics
The EU AI Act is forcing platform vendors to re-architect product roadmaps around algorithmic transparency requirements. Financial services firms in Germany and France now mandate explainable analytics pipelines for credit scoring and fraud detection workflows.
Growth Catalysts
- EU AI Act Conformity Mandates:High-risk automated decision systems must embed audit trails and human oversight mechanisms. Procurement specifications now prioritize platforms with built-in explainability dashboards.
- Cloud Migration Acceleration:Enterprises across the United Kingdom, Germany, and France are retiring on-premises Hadoop clusters. Elastic compute environments reduce infrastructure overhead for variable workloads.
- Real-World Evidence Generation:EMA guidelines drive pharmaceutical demand for validated analytics workflows. Healthcare providers require platforms supporting clinical data integration and regulatory submission pipelines.
Market Restraints
- Data Residency Compliance Costs:GDPR enforcement by national data protection authorities requires sovereign cloud deployments. Multi-region infrastructure duplication raises total cost of ownership for cross-border operators.
- Engineering Talent Scarcity:Pipeline development and MLOps expertise shortages extend implementation timelines. Enterprises face six-to-nine month hiring cycles for specialized platform administrators.
- Legacy System Integration Friction:Mainframe data sources and proprietary formats resist standard API connectivity. Custom extraction layers consume disproportionate project resources.
Strategic Opportunities
- Mid-Market Lakehouse Adoption:Unified storage-compute architectures appeal to firms lacking dedicated infrastructure teams. Simplified deployment models reduce operational complexity for resource-constrained organizations.
- Energy Sector Hybrid Deployments:Grid operators manage sensitive operational data across sovereign boundaries. Edge-to-cloud orchestration tools address latency requirements for real-time asset monitoring.
- CSRD Reporting Automation:Corporate Sustainability Reporting Directive mandates granular emissions disclosure. Platforms integrating ESG data pipelines capture compliance-driven procurement budgets.
Industry Challenges
- Cross-Border Data Governance Complexity:Divergent national implementations of AI Act conformity procedures create specification fragmentation. Vendors must maintain multiple certification tracks across member states.
- Model Drift Monitoring at Scale:Production machine learning systems require continuous performance validation. Automated retraining pipelines demand specialized observability tooling most platforms lack natively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Science Platform Market |
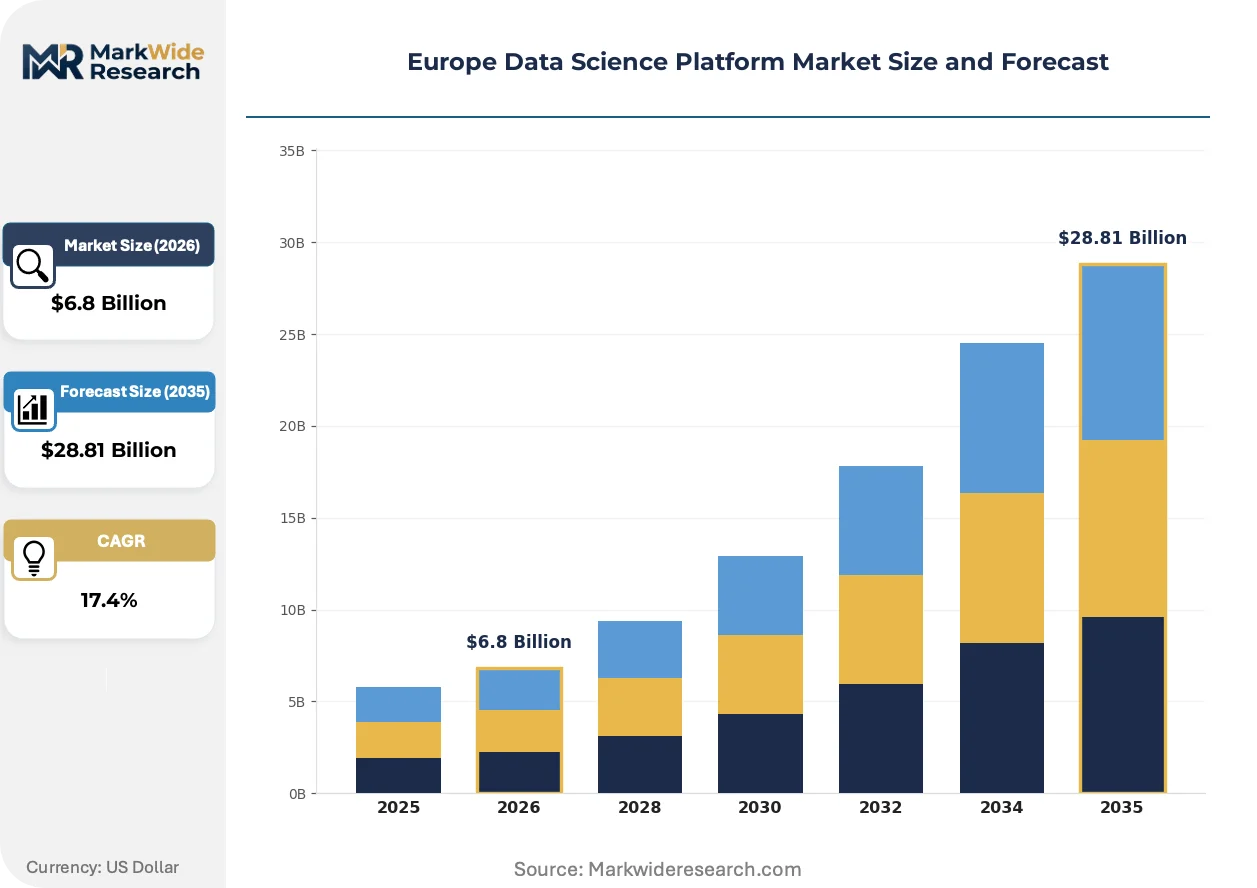
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service End User: Healthcare, Retail, Financial Services, Education Solution: Data Integration, Data Visualization, Predictive Analytics, Machine Learning Industry Vertical: Manufacturing, Telecommunications, Energy, Transportation |
| Companies Covered | Microsoft Corporation, IBM Corporation, Google LLC (Alphabet Inc.), SAS Institute Inc., SAP SE, Oracle Corporation, Alteryx Inc., Databricks Inc., Snowflake Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Science Platform Market Evolving Landscape
Platform architectures are converging around lakehouse designs that unify batch and streaming workloads. This structural shift is compressing vendor differentiation and forcing specialization around vertical compliance capabilities.
Unified lakehouse architectures combining data warehouse performance with data lake flexibility are displacing traditional separate-storage paradigms. Manufacturing quality-control teams in Germany adopt these platforms for real-time defect detection alongside historical batch analytics. The consolidation is compressing infrastructure vendor margins and elevating analytics-layer competition.
The EU AI Act establishes mandatory conformity assessments for high-risk automated decision systems. Platform vendors must embed technical documentation, risk management systems, and human oversight capabilities into product designs. Financial services procurement teams in France now require pre-certified analytics tools to accelerate deployment timelines.
Consumption-based pricing models are replacing perpetual license structures for mid-market buyers. Managed service providers capture deployment and optimization responsibilities previously retained in-house. This shift is most pronounced in the United Kingdom, where platform-as-a-service offerings dominate new procurement decisions among firms with limited data engineering headcount.
Europe Data Science Platform Market Segmentation
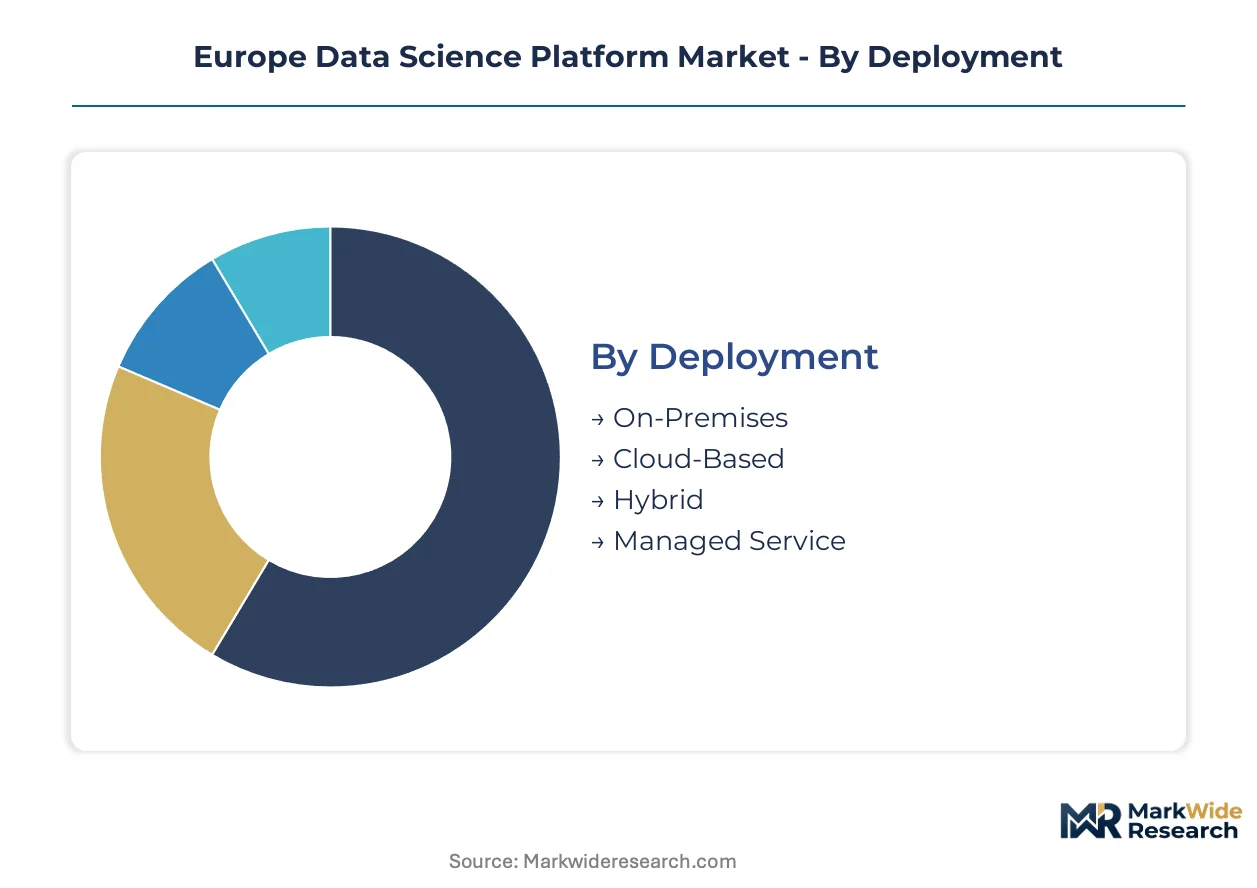
Platform procurement patterns across Europe diverge sharply by infrastructure maturity and regulatory exposure. Deployment choices determine total cost structures, while end-user concentration shapes vendor specialization strategies.
Deployment:
Cloud-based configurations face intensifying substitution pressure from hybrid architectures as GDPR enforcement hardens data residency requirements.
- Cloud-Based:Elastic compute environments provision distributed storage and serverless processing without capital infrastructure commitment. Financial services procurement teams in France and Germany prioritize these deployments for variable fraud detection workloads, though sovereignty concerns are prompting multi-region redundancy investments.
- Hybrid:Split architectures retain sensitive operational data on sovereign infrastructure while bursting analytics workloads to public cloud. Grid operators across Germany and France deploy these configurations for real-time asset monitoring that crosses national boundaries.
- On-Premises:Dedicated hardware clusters serve defense contractors and classified research facilities with air-gapped security requirements.
- Managed Service:Outsourced platform administration appeals to mid-market firms lacking MLOps expertise, particularly in the United Kingdom where engineering talent scarcity is most acute.
Cloud-based deployments retain volume leadership; hybrid configurations hold the steepest expansion curve as cross-border operators navigate divergent national AI Act implementations.
End User:
Cost tier segmentation reveals premium pricing capture in regulated verticals versus commoditized tooling for general enterprise analytics.
- Financial Services:Risk modeling and compliance reporting workflows demand explainable analytics pipelines with embedded audit trails. German and French banks mandate pre-certified platforms for credit scoring automation under EU AI Act high-risk system requirements.
- Healthcare:Clinical data integration platforms support EMA real-world evidence generation guidelines. Pharmaceutical procurement in Switzerland and Germany prioritizes validated workflows for regulatory submission pipelines.
- Retail:Customer segmentation and demand forecasting tools attract omnichannel operators seeking unified behavioral analytics.
- Education:Research computing environments serve university consortia with federated learning requirements and open-source tooling preferences.
Financial services commands premium pricing; healthcare is expanding most quickly as EMA guidelines harden evidence standards.
Solution:
Application maturity varies widely, with foundational tooling commoditizing while advanced analytics layers retain differentiation.
- Predictive Analytics:Statistical modeling engines for forecasting and classification deploy across credit risk, demand planning, and clinical trial design. French banking supervisors now require algorithmic transparency documentation for all production scoring models.
- Machine Learning:Automated model development pipelines with MLOps lifecycle management attract manufacturing quality control teams in Germany automating defect detection.
- Data Integration:ETL and streaming ingestion frameworks consolidate fragmented enterprise sources into unified lakehouse architectures.
- Data Visualization:Self-service dashboarding layers face margin compression from open-source alternatives and embedded analytics in business applications.
Predictive analytics retains volume leadership; machine learning is gaining share fastest as manufacturing automation accelerates.
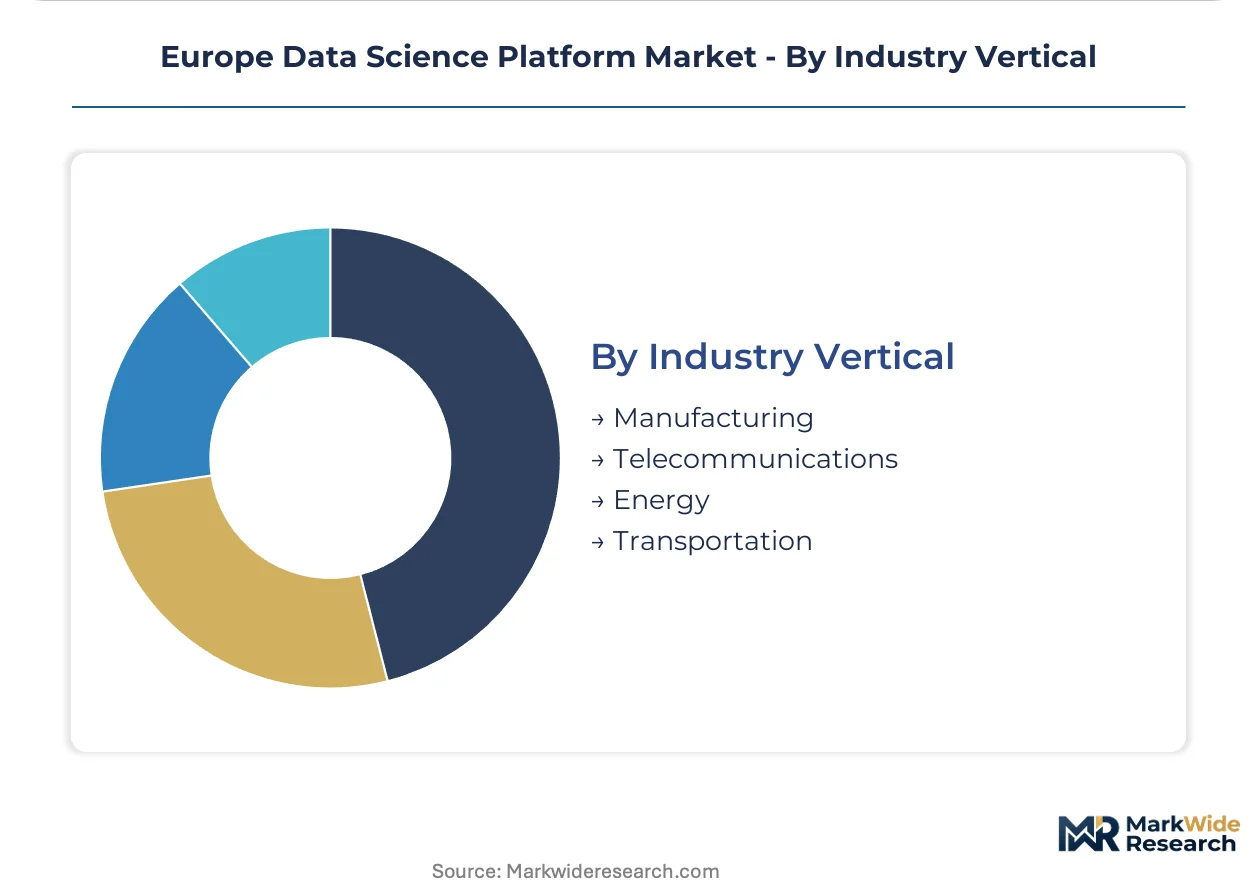
Industry Vertical:
Customer type concentration shows public infrastructure operators outspending private manufacturers on per-seat platform investment.
- Energy:Grid modernization and renewable integration drive demand for edge-to-cloud orchestration. German transmission operators manage cross-border load balancing with latency-sensitive telemetry pipelines.
- Telecommunications:Network optimization and customer churn prediction attract major carriers in the United Kingdom and France with substantial subscriber data volumes.
- Manufacturing:Quality control automation and predictive maintenance workflows deploy across automotive and industrial equipment producers.
- Transportation:Fleet optimization and autonomous system validation serve logistics operators and rail infrastructure managers with safety-critical algorithm requirements.
Energy retains volume leadership; telecommunications holds the steepest expansion trajectory as 5G network data volumes compound.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Europe diverge sharply between financial services hubs prioritizing explainable analytics and industrial clusters favoring lakehouse architectures for manufacturing automation.
Germany
BaFin supervision drives demand for audit-ready risk modeling pipelines among Frankfurt-based banking groups. The EU AI Act high-risk system requirements accelerate procurement of platforms with embedded documentation tools. Automotive manufacturers in Baden-Württemberg deploy lakehouse architectures for real-time quality control alongside predictive maintenance workflows.
United Kingdom
Platform-as-a-service consumption dominates as London financial firms retire legacy Hadoop clusters for elastic fraud detection workloads. FCA guidelines on algorithmic trading transparency shape vendor selection criteria. The Edinburgh-Glasgow corridor attracts managed service providers targeting mid-market firms with scarce MLOps talent.
France
ACPR enforcement mandates explainable credit scoring pipelines that accelerate deployment of pre-certified analytics tools. CNIL guidance on automated decision-making reinforces data residency requirements for Parisian banking headquarters. Lyon-based pharmaceutical clusters adopt validated workflows for EMA real-world evidence submission under tightened regulatory timelines.
Switzerland
Swissmedic validation requirements drive pharmaceutical procurement of platforms supporting clinical data integration for regulatory submissions. FINMA oversight of algorithmic trading systems extends transparency mandates to private banking analytics. Basel's life sciences corridor concentrates demand for GxP-compliant machine learning pipelines in drug development.
Netherlands
AFM supervision of automated investment advice creates procurement specifications for explainable model documentation among Amsterdam asset managers. The Dutch Data Protection Authority's strict GDPR interpretation reinforces sovereign cloud requirements for cross-border operators. Eindhoven's high-tech systems sector adopts edge-to-cloud orchestration for semiconductor manufacturing telemetry.
Europe Data Science Platform Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hyperscale cloud providers anchoring public-sector contracts through ecosystem lock-in while vertical specialists capture regulated industry premiums. The market structure rewards bundled infrastructure-analytics offerings over point solutions. Three archetypes dominate: hyperscale platform bundlers, vertical compliance specialists, and lakehouse architecture pure-plays. Competitive moves concentrate on strategic partnerships with systems integrators and geographic expansion through localized data residency certifications.
Within the hyperscale tier, Microsoft Corporation and Google LLC exemplify ecosystem-driven positioning through public-sector anchoring in France and Germany. Databricks Inc. occupies a distinct position as the lakehouse architecture reference point for mid-market firms seeking simplified infrastructure without dedicated platform teams. These three entities collectively represent the competitive vectors shaping procurement specifications across European financial services and industrial automation segments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Google LLC (Alphabet Inc.) |
| SAS Institute Inc. |
| SAP SE |
| Oracle Corporation |
| Alteryx Inc. |
| Databricks Inc. |
| Snowflake Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day implementation timelines for enterprise platform deployments concentrate pricing power with hyperscale cloud providers anchoring multi-year subscription contracts. Procurement teams at Frankfurt banking groups and London financial firms face compressed negotiation leverage when sovereign cloud requirements extend delivery schedules.
Pricing Analysis
Long-term subscription offtakes dominate enterprise procurement, with three-year SaaS contracts anchoring relationships between hyperscale providers and financial services buyers. Price differentiation separates GDPR-certified sovereign cloud tiers from standard multi-tenant deployments, with German and French buyers absorbing premiums for data residency guarantees. Cost compression in mid-market lakehouse offerings intensifies as Databricks and Snowflake compete for firms lacking dedicated infrastructure teams. Manufacturing quality-control teams show highest price sensitivity, while pharmaceutical procurement under EMA guidelines tolerates premium validated-workflow pricing.
Supply Chain Analysis
Just-in-time provisioning preferences dominate cloud infrastructure delivery, with hyperscale providers maintaining spare compute capacity across Ireland, Netherlands, and Germany to burst variable analytics workloads. Platform software draws from concentrated engineering talent pools in the United Kingdom, Germany, and Switzerland, with MLOps expertise shortages extending hiring cycles. Single-source vulnerability concentrates in NVIDIA GPU supply for model training clusters, with lead times extending when semiconductor fabrication faces disruption. Distribution runs through direct enterprise sales teams and systems integrator partnerships, particularly for public-sector deployments requiring localized certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
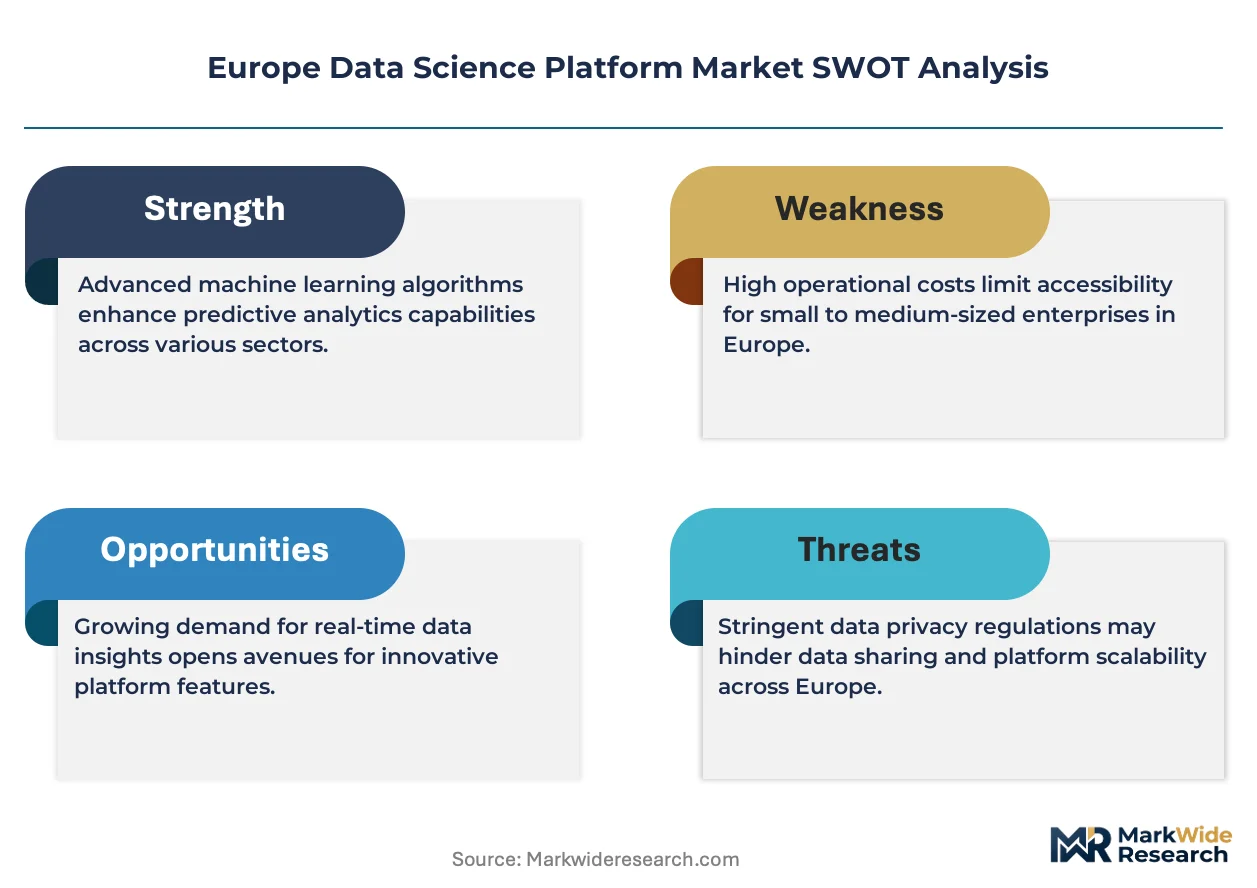
Platform economics in this market hinge on ecosystem lock-in dynamics, with Microsoft Azure's vertical integration of compute, storage, and analytics layers reshaping procurement specifications across European financial services.
For Market Incumbents: Compound defensive positioning through vertical specialization in EU AI Act high-risk system certification, embedding audit-trail capabilities that emerging lakehouse pure-placks lack. Deepen backward integration into sovereign cloud infrastructure to capture data residency premiums that GDPR enforcement amplifies. Secure exclusive partnerships with systems integrators serving French and German public-sector buyers where procurement cycles favor incumbent relationships. For New Entrants and Emerging Players: Mid-market MLOps service gaps expose white-space opportunities where resource-constrained firms abandon self-managed deployments. Target United Kingdom healthcare providers and Netherlands high-tech manufacturers with consumption-based pricing that eliminates upfront infrastructure commitment. Pursue geographic expansion through localized data residency certifications in Switzerland and Nordics, where regulatory divergence from EU AI Act implementation creates specification fragmentation incumbents under-serve. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-technology play because regulatory obligation depth—EU AI Act conformity assessments, GDPR sovereign cloud mandates, EMA validated workflows—creates durable competitive moats around certified platform architectures. Prioritize acquisition targets with pre-certified analytics tools for financial services and pharmaceutical verticals. Watch for inflection when national AI Act implementation divergences force vendors to maintain multiple certification tracks, elevating compliance-layer specialists above undifferentiated infrastructure providers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure ecosystem bundling captures French and German public-sector contracts through sovereign cloud anchoring. |
| Acquisition of Specialist Firm | Vertical compliance capabilities in pharmaceutical validated workflows attract premium pricing from EMA-regulated buyers. |
| Strategic Partnership | Systems integrator alliances accelerate deployment timelines for EU AI Act high-risk system implementations. |
| Geographic Expansion | Localized data residency certifications in Switzerland and Nordics address GDPR enforcement divergence. |
| Product Launch | Explainable analytics dashboards meet ACPR and BaFin mandates for credit scoring transparency documentation. |
Research Methodology
The analysis maps cloud-based, hybrid, on-premises, and managed service deployment configurations, each validated through primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners across financial services, healthcare, and manufacturing verticals. Secondary validation draws from SEC filings of hyperscale cloud providers, EMA real-world evidence guidelines, EU AI Act conformity assessment documentation, and national data protection authority enforcement records. Bottom-up segment sizing triangulates against top-down market aggregation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs derive from segment-level growth trajectory analysis incorporating EU AI Act implementation timelines, cloud migration velocity in United Kingdom and Germany, and pharmaceutical EMA guideline adoption curves.
Forecasts assume regulatory continuity in EU AI Act, GDPR, and EMA regimes; material policy shifts would require re-modeling. Revision becomes warranted when national AI Act conformity procedure divergences cross thresholds that fragment procurement specifications beyond vendor adaptation capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Machine Learning in Communication Market
Machine Learning and Data Science
Global Image Recognition in CPG Market
Machine Learning and Data Science
Europe Machine Learning As a Service Market
Machine Learning and Data Science
Data Science Platform Market
Machine Learning and Data Science
Global Cognitive Data Management Market
Machine Learning and Data Science
Semantic Knowledge Graphing Market
Machine Learning and Data Science
Global Computational Creativity Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Europe Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Cloud Machine Learning Market
Machine Learning and Data Science
Asia-Pacific Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Natural Language Processing Market