
 Global Image Recognition in CPG Market | 2026-2036
Global Image Recognition in CPG Market Size, Share, and Industry Trends Forecast 2026-2036
Global Image Recognition in CPG Market Foresight
Buyer concentration across multinational retailers is rebalancing as regional grocery chains and direct-to-consumer brands fragment procurement across specialized vendors. Google leverages its TensorFlow ecosystem to anchor cloud-based visual inference pipelines for packaged goods verification. Microsoft competes through Azure AI services that sustain enterprise-grade shelf monitoring contracts with North American retailers.
Image recognition in CPG denotes automated visual analysis systems that process product imagery through convolutional neural networks with sub-second inference latency to detect SKUs, assess shelf placement, and flag quality deviations in manufacturing lines. These systems primarily serve commercial purposes by converting unstructured visual data into actionable inventory and merchandising signals. Deep neural networks occupy the highest-margin tier of technology deployment, while edge computing architectures represent the fastest-growing delivery mode as latency requirements tighten in warehouse settings. Product identification and shelf analytics concentrate the bulk of current application spending, though quality inspection is widening its share among manufacturers seeking defect reduction.
The EU AI Act imposes risk-classification obligations on automated visual systems processing consumer-facing imagery, while the FDA maintains algorithmic transparency standards for quality inspection tools deployed in food and beverage packaging facilities. China's SAMR enforces national AI standards that govern facial and object recognition accuracy benchmarks in retail deployments. Stakeholders must weigh compliance architecture investments against the operational flexibility of multi-region model deployment strategies.
Market Dynamics
Edge computing architectures are compressing inference latency requirements in warehouse and retail floor deployments, forcing a fundamental reconfiguration of how visual recognition pipelines distribute processing loads between cloud and local nodes.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification obligations for automated visual systems processing consumer-facing imagery are compelling retailers to upgrade legacy shelf monitoring infrastructure with auditable algorithmic stacks.
- Shelf analytics penetration:Large-format grocery retailers are deploying convolutional neural networks with sub-second latency to automate planogram compliance and out-of-stock detection across high-SKU categories.
- China's retail automation buildout:SAMR-enforced national AI standards for object recognition accuracy are accelerating procurement of certified visual inspection systems among domestic beverage and packaged food manufacturers.
Market Restraints
- GPU supply concentration:Inference hardware dependency on Taiwan-based semiconductor fabrication creates vulnerability in edge device procurement timelines for North American and European deployers.
- Algorithmic transparency requirements:FDA documentation standards for quality inspection tools in food packaging facilities extend validation cycles and inflate compliance architecture costs.
- Label noise in training data:Inconsistent SKU photography standards across CPG manufacturers degrade model accuracy in multi-brand retail environments, necessitating costly dataset curation.
Strategic Opportunities
- Quality inspection expansion:Defect reduction mandates in food and beverage packaging lines are widening application share beyond shelf analytics into manufacturing line monitoring.
- Direct-to-consumer brand procurement:Fragmenting buyer concentration among specialized vendors creates entry points for edge-native solution providers outside incumbent cloud ecosystems.
- Germany's retail automation infrastructure:Federal investment in smart logistics corridors is generating demand for warehouse-bound visual recognition systems with millisecond-latency requirements.
Industry Challenges
- Computer vision engineering scarcity:Shortage of practitioners capable of optimizing neural network architectures for constrained edge hardware extends deployment timelines.
- Multi-region model deployment complexity:Reconciling EU AI Act risk classifications with SAMR accuracy benchmarks and FDA transparency standards fragments model governance architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Image Recognition in CPG Market |
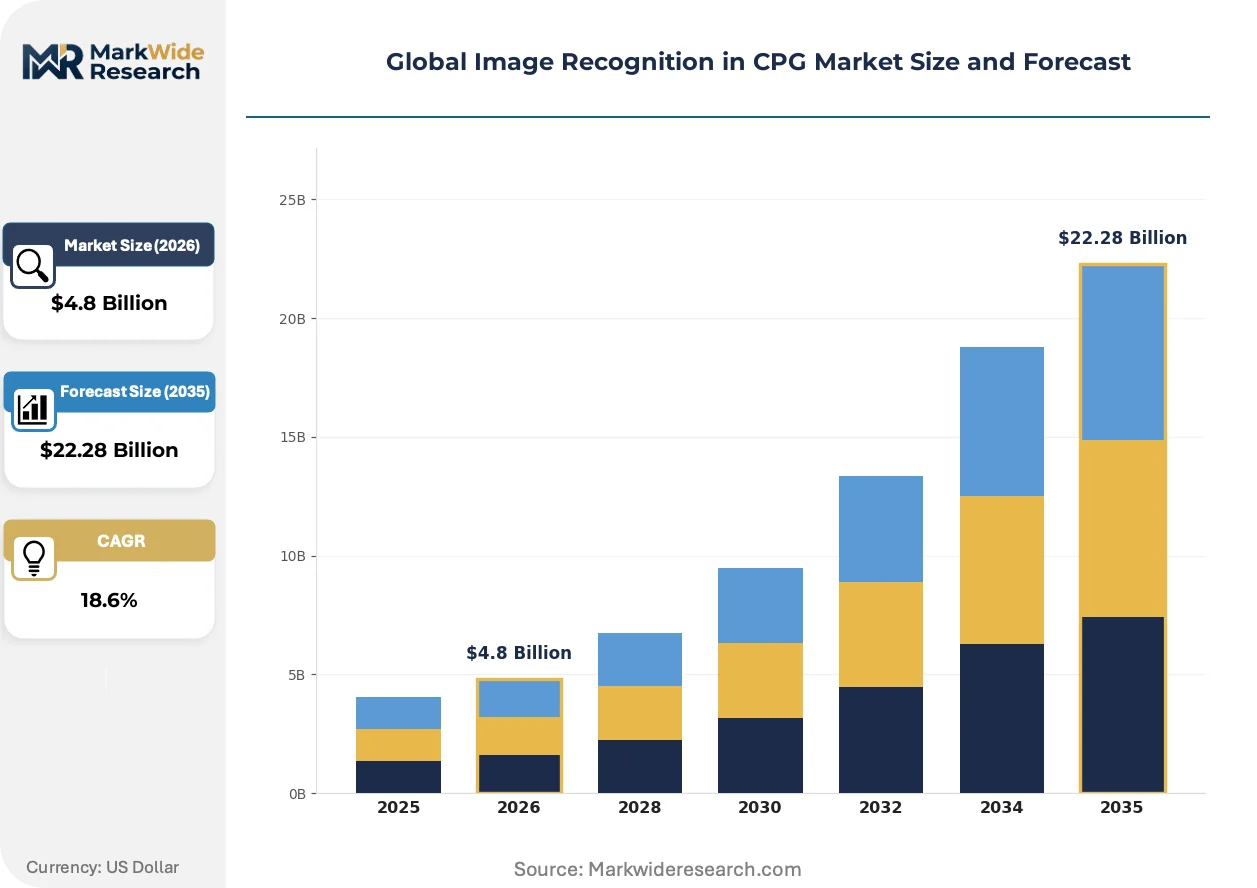
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Deep Neural Networks, Convolutional Neural Networks, Computer Vision, Pattern Recognition, Feature Extraction Application: Product Identification, Shelf Analytics, Quality Inspection, Inventory Management, Consumer Insights, Marketing Optimization End User: Retailers, Brand Owners, Manufacturers, Logistics Providers, Advertising Agencies, Packaging Firms Deployment: Cloud-Based, On-Premises, Edge Computing, Hybrid Solutions, SaaS Platforms, Mobile Integration |
| Companies Covered | Google, IBM, Microsoft, Amazon Web Services, Trax, Clarifai, Qualcomm, Honeywell International, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Image Recognition in CPG Market Shifts & Advancements
Visual inference pipelines are fragmenting into composable microservices that decouple model training, deployment, and monitoring functions, enabling retailers to swap algorithmic components without wholesale system replacement.
Containerized vision models are modularizing how CPG manufacturers and retailers assemble shelf analytics and quality inspection workflows. Mid-market grocery chains are adopting these architectures faster than enterprise peers, driven by capital constraints that favor incremental capability expansion over monolithic platform commitments. This modularity is compressing vendor lock-in duration and expanding the addressable market for specialized inference providers.
The EU AI Act's risk-tier framework for biometric and object recognition systems is imposing documentation and human-oversight requirements on deployed visual analytics. Food retailers operating across European markets must maintain algorithmic impact assessments and audit trails for shelf monitoring applications processing shopper imagery. German and French deployments face the steepest compliance architecture investments due to national implementations exceeding baseline EU requirements.
Outcome-based contracting is displacing perpetual license models in enterprise shelf analytics procurement. North American retailers are negotiating performance-linked agreements where vendors absorb inference accuracy risk in exchange for revenue-share arrangements tied to inventory optimization outcomes. This shift concentrates vendor selection criteria on demonstrated SKU-level detection precision rather than feature breadth or platform ecosystem breadth.
Global Image Recognition in CPG Market Segmentation
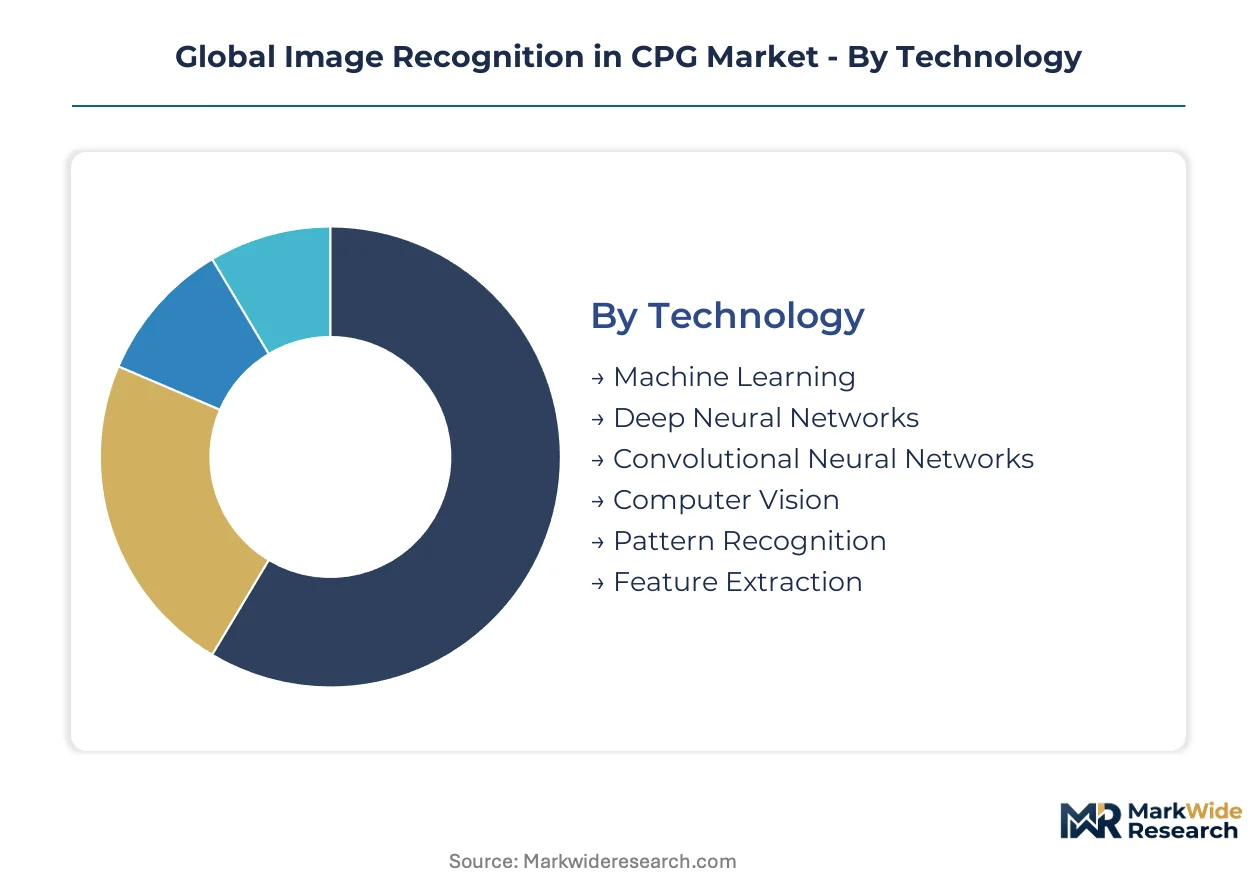
Segmentation in image recognition for CPG reveals how technology integration depth varies by deployment architecture and end-user sophistication. Standalone systems dominate legacy retail infrastructure, while embedded visual modules penetrate manufacturing lines and logistics networks.
Technology:
Integration depth separates standalone inference engines from embedded vision stacks co-located with operational technology.
- Deep Neural Networks:Multi-layer architectures process complex visual hierarchies with automated feature learning, eliminating manual engineering. Demand concentrates in quality inspection lines at food and beverage packaging facilities where FDA algorithmic transparency standards mandate auditable decision pathways.
- Convolutional Neural Networks:Specialized architectures for spatial feature extraction deliver sub-second SKU detection latency. Large-format grocery retailers in the United States deploy these for planogram compliance automation across high-density shelf configurations.
- Machine Learning:Traditional statistical methods persist in legacy retail environments with constrained computational budgets.
- Computer Vision:Broad discipline encompassing hardware-software co-design for industrial camera integration.
- Pattern Recognition:Rule-based approaches retain niche applications in controlled manufacturing settings with limited SKU variability.
- Feature Extraction:Manual engineering pipelines survive in edge-constrained deployments where neural network inference exceeds thermal or power envelopes.
Volume placements concentrate in Convolutional Neural Networks; the faster expansion belongs to Deep Neural Networks.
Application:
Cost tier stratification separates high-frequency operational deployments from episodic analytical use cases.
- Shelf Analytics:Real-time shelf monitoring systems detect out-of-stock conditions and planogram deviations through continuous camera feeds. German retailers face elevated compliance architecture costs under EU AI Act risk-tier frameworks that mandate human oversight for consumer-facing visual processing.
- Quality Inspection:Manufacturing line systems identify packaging defects and label misalignments at production speeds. China's SAMR-enforced accuracy benchmarks accelerate procurement among domestic beverage manufacturers seeking defect reduction mandates.
- Product Identification:SKU-level recognition underpins inventory tracking across warehouse and retail floor environments.
- Inventory Management:Cycle-count automation through visual verification reduces manual stock-taking labor.
- Consumer Insights:Shopper behavior analysis via in-store camera networks faces regulatory headwinds in European markets.
- Marketing Optimization:Shelf placement effectiveness measurement supports trade spend allocation decisions.
Commercial deployment concentrates in Shelf Analytics; Quality Inspection is climbing the fastest as manufacturing automation deepens.
End User:
Customer type determines procurement sophistication, from enterprise platform contracts to specialized vendor fragmentation.
- Retailers:Grocery chains and big-box operators deploy shelf analytics at scale with outcome-based contracting replacing perpetual licenses. North American retailers negotiate performance-linked agreements where vendors absorb inference accuracy risk.
- Manufacturers:Food and beverage packaging lines integrate quality inspection for defect reduction with FDA documentation requirements extending validation cycles.
- Brand Owners:Direct-to-consumer CPG brands fragment procurement across specialized edge-native providers outside incumbent cloud ecosystems.
- Logistics Providers:Warehouse automation drives demand for millisecond-latency visual recognition in Germany's smart logistics corridors.
- Advertising Agencies:Marketing effectiveness measurement through shelf placement verification supports retail media networks.
- Packaging Firms:Contract manufacturers adopt quality inspection to meet brand owner specifications.
Procurement volume concentrates in Retailers; Brand Owners are expanding most quickly as direct-to-consumer channels proliferate.
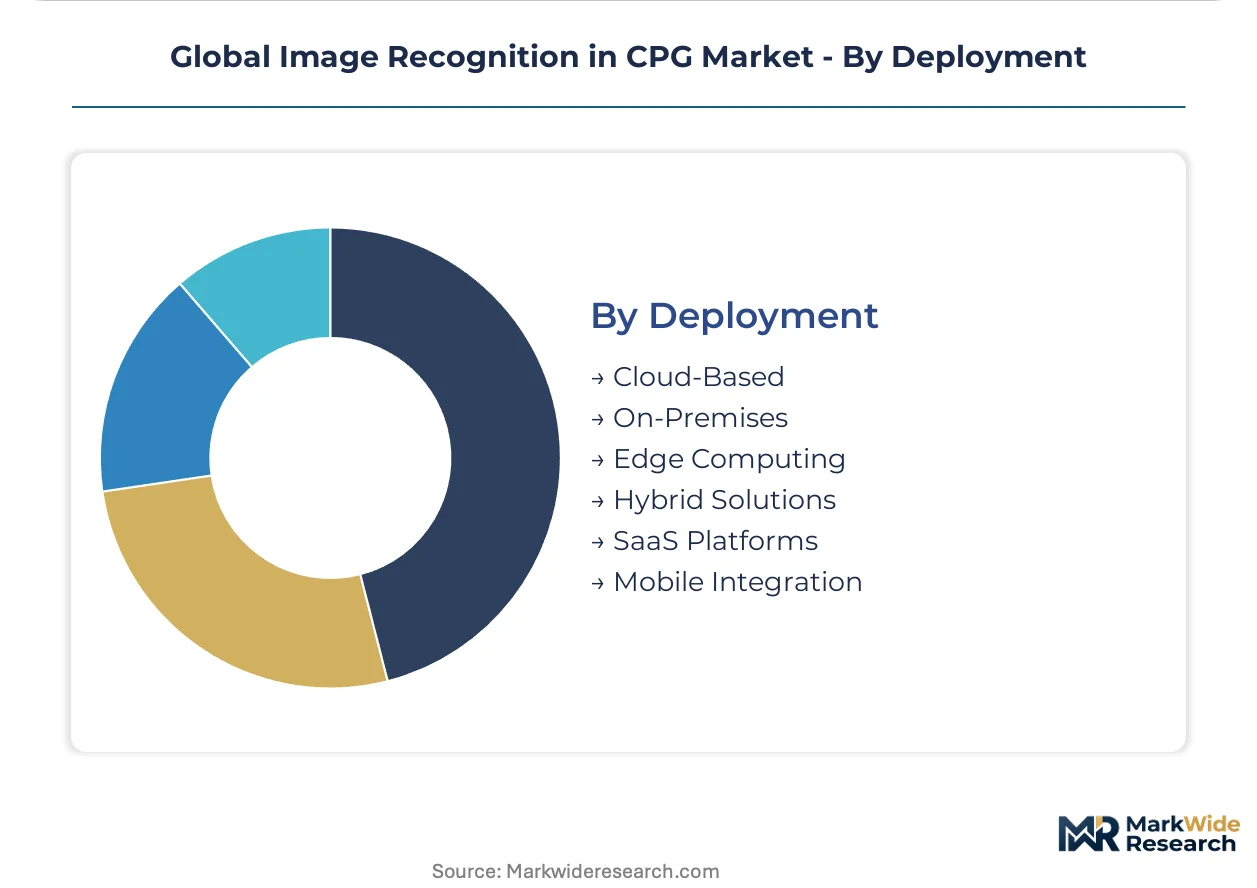
Deployment:
Supply concentration in GPU fabrication shapes delivery mode feasibility across geographies.
- Edge Computing:Local inference processing eliminates cloud latency for warehouse robotics and real-time shelf monitoring. Taiwan-based semiconductor fabrication concentration creates procurement vulnerability for North American and European deployers seeking constrained hardware.
- Cloud-Based:Centralized model training and batch inference serve analytical applications with relaxed latency requirements. Google and Microsoft anchor enterprise-grade shelf monitoring contracts through TensorFlow and Azure AI service ecosystems.
- On-Premises:Dedicated infrastructure persists in facilities with data sovereignty requirements or air-gapped security mandates.
- Hybrid Solutions:Tiered processing distributes training to cloud and inference to edge for latency-sensitive applications.
- SaaS Platforms:Subscription delivery lowers capital barriers for mid-market grocery chains with constrained IT budgets.
- Mobile Integration:Smartphone-based visual search and inventory applications extend recognition to field sales and delivery workflows.
Current infrastructure concentrates in Cloud-Based deployments; Edge Computing is gaining share fastest as latency requirements tighten in warehouse settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for image recognition in CPG concentrates in the United States, China, and Germany as these markets scale retail automation infrastructure and enforce divergent regulatory frameworks on algorithmic systems.
United States
Large-format grocery retailers deploy convolutional neural networks for planogram compliance and out-of-stock detection across high-SKU categories. FDA algorithmic transparency standards extend validation cycles for quality inspection tools in food and beverage packaging facilities. Chicago and Dallas-Fort Worth anchor enterprise-grade shelf monitoring deployments with outcome-based contracting replacing perpetual licenses.
Germany
Federal investment in smart logistics corridors generates demand for warehouse-bound visual recognition systems with millisecond-latency requirements. EU AI Act risk-tier frameworks mandate elevated compliance architecture investments, particularly for consumer-facing shelf analytics in Berlin and Hamburg. Munich's industrial automation cluster concentrates edge-native solution development for manufacturing line monitoring.
China
Domestic beverage and packaged food manufacturers accelerate procurement of certified visual inspection systems under SAMR-enforced national AI standards for object recognition accuracy. Shenzhen and Shanghai anchor retail automation buildouts with edge computing architectures compressing inference latency in warehouse robotics deployments. Yangtze River Delta manufacturers integrate defect reduction mandates into packaging line upgrades.
United Kingdom
London-based retail media networks drive shelf placement effectiveness measurement through visual verification systems. GDPR compliance requirements impose documentation burdens on in-store camera networks processing shopper behavior data. Midlands logistics hubs adopt hybrid cloud-edge architectures for inventory cycle-count automation.
Japan
Tokyo-Osaka corridor retailers deploy sub-second latency recognition for high-density convenience store shelf configurations. METI guidelines on AI system reliability shape procurement criteria for manufacturing quality inspection. Nagoya's automotive supply chain expertise transfers into packaging line visual systems for precision defect detection.
Global Image Recognition in CPG Market Competitive Landscape
United States technology conglomerates anchor the cloud-based tier; European and Israeli specialists hold positions in edge-native and compliance-focused segments. Market structure splits between consolidated hyperscaler ecosystems and fragmented specialized vendors serving mid-market grocery chains. Three archetypes dominate: hyperscale cloud AI platforms, edge hardware-software integrators, and vertical-specific shelf analytics pure-plays. Competitive moves concentrate on strategic partnerships with retail automation integrators and geographic expansion into Germany's smart logistics corridors.
Within the hyperscale tier, Google and Microsoft exemplify divergent ecosystem strategies—TensorFlow anchoring open-source visual inference pipelines versus Azure AI sustaining enterprise-grade shelf monitoring contracts. Amazon Web Services occupies a position bridging cloud infrastructure and retail operational technology. Trax represents the vertical-specialist archetype, its name signaling dedicated shelf analytics positioning outside incumbent cloud ecosystems.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Amazon Web Services |
| Trax |
| Clarifai |
| Qualcomm |
| Honeywell International |
| Apple |
| Others |
Supply & Pricing Matrix
GPU spot pricing indices on Taiwan Semiconductor Manufacturing's advanced node wafers cascade through edge device bill-of-materials, stratifying solution costs across cloud-native hyperscaler tiers and latency-constrained warehouse deployments.
Pricing Analysis
High-volume SaaS subscriptions for shelf analytics compress margins against lower-volume but premium-priced edge hardware-software bundles for manufacturing quality inspection. Price differentiation rests on inference latency guarantees and FDA algorithmic transparency certification tiers. Pricing pressure stems from GPU supply concentration extending procurement timelines for North American deployers. Mid-market grocery chains exhibit highest price sensitivity, while multinational retailers with outcome-based contracts absorb accuracy risk for inventory optimization gains.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale retailer demand for cloud-based inference pipelines, while specialized systems integrators distribute edge-native solutions to fragmented brand owner procurement. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States. Supply chains draw from CMOS image sensors, AI accelerators, and precision optics. Single-source vulnerability in Taiwan-based GPU foundries threatens deployment timelines. Distribution runs through retail automation integrators and manufacturing line OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies a technology-transition phase where edge computing architectures displace cloud-centric inference pipelines for latency-sensitive warehouse and retail floor applications.
For Market Incumbents: Deploy outcome-based contracting mechanisms to lock in multinational retailer relationships against specialized vendor fragmentation. Anchor enterprise shelf monitoring contracts through TensorFlow and Azure AI service ecosystems to defend against edge-native entrants. Invest in EU AI Act compliance architecture to maintain German and French market access as national implementations exceed baseline requirements. For New Entrants and Emerging Players: Retail automation integrators represent the most accessible channel for penetrating Germany's smart logistics corridor demand. Target quality inspection applications among direct-to-consumer brand owners seeking defect reduction outside incumbent cloud ecosystems. White-space exists in millisecond-latency warehouse robotics for mid-market logistics providers with constrained IT budgets. For Investors and Strategic Acquirers: Distressed-cycle entries favor edge hardware-software integrators with SAMR-certified deployments in China's Yangtze River Delta manufacturing cluster. Long-term viability hinges on reconciling multi-region model governance across EU AI Act, FDA, and SAMR requirements. Monitor GPU supply chain diversification announcements as inflection indicators for edge device procurement normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Platform Launch | Millisecond-latency inference captures warehouse automation contracts in Germany's federal logistics corridors. |
| Regulatory Certification Investment | FDA algorithmic transparency documentation opens food packaging quality inspection procurement pipelines. |
| Strategic Partnership with Retail Integrators | Systems integrator alliances accelerate shelf analytics deployment across fragmented mid-market grocery chains. |
| Acquisition of Computer Vision Specialist | Neural network optimization talent scarcity extends deployment timelines for constrained edge hardware. |
| Geographic Expansion into China | SAMR-enforced accuracy benchmarks accelerate certified visual inspection procurement among domestic beverage manufacturers. |
Research Methodology
Independent corroboration across CTOs at North American grocery chains, computer vision engineering leads at edge device manufacturers, regulatory affairs directors navigating EU AI Act compliance, and procurement officers at German logistics providers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings for quality inspection tools, SAMR AI standard certifications, hyperscaler capex disclosures for cloud AI infrastructure, and EU AI Act implementation guidance documents. Bottom-up segment sizing triangulates against top-down market envelope estimates.
Comparable-period anchoring to historical GPU supply chain disruptions and retail automation capex cycles shapes projection assumptions across the analysis window. Segmentation dimensions include deployment architecture, application type, end-user sophistication tier, and regional regulatory cluster. CAGRs derive from fitted growth curves against technology adoption S-cycles. Forecast inputs incorporate edge device shipment trajectories and shelf analytics contract value disclosures.
Caveats apply where GPU supply chain normalization, EU AI Act enforcement intensity, or FDA algorithmic transparency rulemaking could materially shift the outlook. Practitioners should monitor Taiwan semiconductor capacity expansion announcements and German federal smart logistics procurement awards for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Machine Learning Operation Technology Market
Machine Learning and Data Science
Europe Data Science Platform Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Natural Language Processing Market
Machine Learning and Data Science
Europe Machine Learning As a Service Market
Machine Learning and Data Science
Cloud Machine Learning Market
Machine Learning and Data Science
Europe Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Global AI and Machine Learning Operationalization Software Market
Machine Learning and Data Science
Semantic Knowledge Graphing Market
Machine Learning and Data Science
Speech-To-Text API Market
Machine Learning and Data Science
Data Science Platform Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market