
 Grinding Machines Market | 2026-2036
Grinding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Grinding Machines Market Intelligence
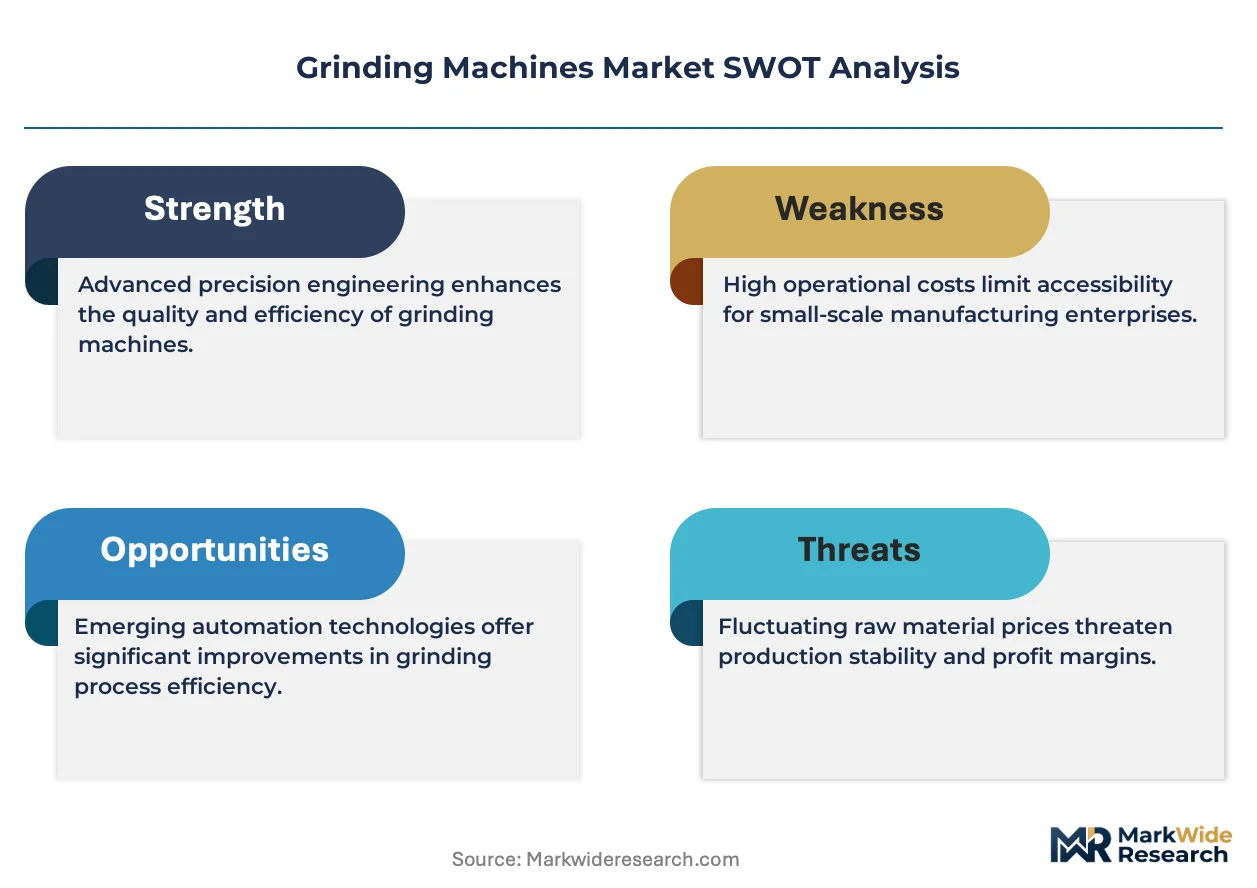
The substitution of traditional steel with advanced composites and nickel-based superalloys in aerospace components is realigning product economics for grinding machine manufacturers. United Grinding North America leverages its portfolio of surface and cylindrical grinding solutions to address these material challenges. JTEKT Toyoda Americas Corporation competes on the strength of its high-speed CNC grinders for automotive production. Falcon Machine Tools specializes in surface grinders for the tool and die sector.
Grinding machines are industrial tools that employ a rotating abrasive wheel to remove material from a workpiece, achieving high surface quality and precise dimensional tolerances. Their primary function is the finishing of hardened metal parts that require exceptional accuracy, often to within a few micrometers. Among product types, cylindrical grinders hold a significant share for producing rotational components like shafts and bearings. Automated and CNC technology variants are displacing manual machines in precision engineering firms due to superior repeatability.
Compliance with standards like ISO 9001 for quality management and CE marking for European market access are fundamental for machine builders. In the United States, OSHA regulations dictate machine guarding and operator safety protocols, influencing equipment design. Regulations in China, such as specific GB standards, also govern machine tool safety and performance. Stakeholders must decide whether to invest in integrated automation and in-process metrology to meet tightening tolerance requirements.
Market Dynamics
The market's central dynamic is the escalating demand for ultra-precision finishes on difficult-to-machine materials like superalloys. This pressure from aerospace and medical device sectors forces a fundamental shift in machine tool capabilities and integrated automation strategies.
Growth Catalysts
- Aerospace Component Manufacturing:The transition to advanced composites and nickel-based superalloys for jet engine turbines and structural components requires grinding machines capable of achieving sub-micron tolerances and complex geometries.
- CNC and Automation Integration:The adoption of multi-axis CNC systems and robotic loading automates production, enhancing repeatability and throughput for high-volume automotive and electronics manufacturing.
- China's Advanced Manufacturing Push:National industrial policies in China are accelerating investment in high-end machine tools for its expanding electric vehicle and semiconductor fabrication equipment sectors.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for ultra-precision CNC grinding machines creates a substantial barrier to entry for small and medium-sized enterprises in the tool and die sector.
- Material Machinability Issues:The inherent hardness and abrasive nature of materials like ceramic matrix composites leads to rapid abrasive wheel wear and thermal damage, limiting process efficiency.
- Competition from Alternative Processes:Advances in non-traditional machining, such as electrical discharge machining and laser polishing, present a substitution threat for specific applications requiring intricate features without mechanical stress.
Strategic Opportunities
- Medical Device Miniaturization:The growing market for miniaturized surgical instruments and orthopedic implants, often made from titanium or cobalt-chrome, opens new avenues for specialized micro-grinding equipment.
- Integrated In-Process Metrology:Combining grinding with real-time measurement systems using optical or tactile probes allows for closed-loop process control, reducing scrap rates and eliminating separate inspection steps.
- Sustainable Machining Mandates:European Union regulations like the EU Green Deal encourage the adoption of machines with improved energy efficiency and reduced coolant usage, creating an opportunity for eco-friendly grinding solutions.
Industry Challenges
- Skilled Operator Shortage:A persistent lack of technicians proficient in programming and operating complex multi-axis CNC grinding machines hampers productivity and limits the adoption of advanced automation in precision engineering firms.
- Navigating Global Standards:Manufacturers face complexity in designing machines that simultaneously comply with diverse safety and performance standards, such as OSHA in the United States, CE marking in Europe, and GB standards in China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grinding Machines Market |
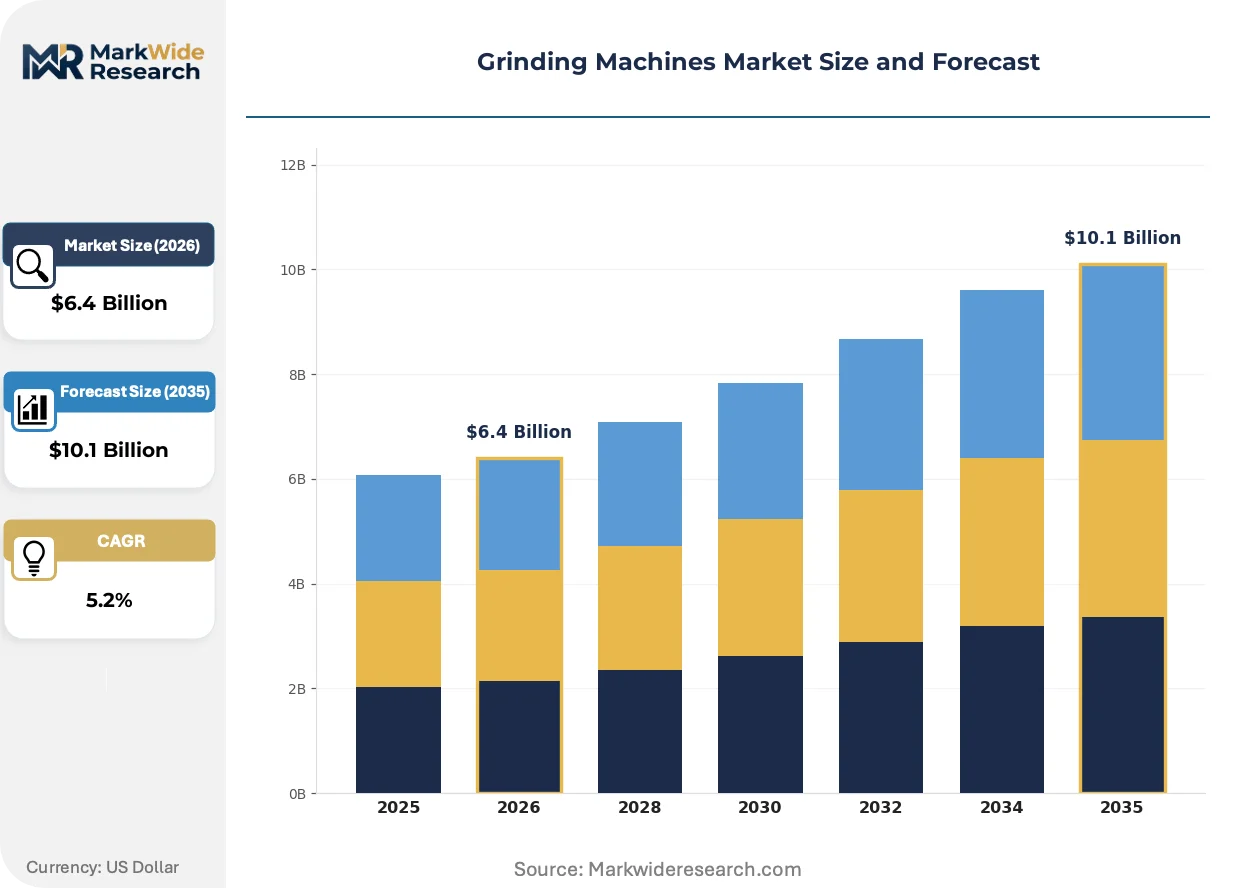
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.1 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Grinders, Cylindrical Grinders, Centerless Grinders, Tool & Cutter Grinders, Internal Grinders Technology: Conventional, CNC, Ultra-Precision, Manual, Automated Application: Metalworking, Aerospace Parts, Automotive Components, Optical Components, Mold Making End User Industry: Manufacturing Plants, Machine Shops, Tool & Die Makers, Precision Engineering Firms, Defense Contractors |
| Companies Covered | STUDER, BLOHM, JTEKT Toyoda Americas Corporation, KREBS & RIEDEL, MÄGERLE, Falcon Machine Tools, WALTER, Rome Grinding Solutions, United Grinding North America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grinding Machines Market Strategic Shifts & Innovations
The evolution of grinding technology is defined by the integration of digital intelligence and advanced sensor technology. This shift turns machines from standalone tools into connected nodes within a data-driven ecosystem, prioritizing process optimization over raw speed.
Artificial intelligence and machine learning algorithms are being integrated into CNC controllers to enable adaptive process control. High-volume sectors like automotive and aerospace are adopting these systems to dynamically adjust grinding parameters based on real-time sensor feedback. This digital overlay absorbs process variability previously managed by operator skill, improving part consistency and reducing setup times.
Heightened machine safety regulations, such as updated OSHA machine guarding standards in the United States, mandate more sophisticated interlocking systems and failsafe controls. This directly impacts equipment design, increasing the cost and complexity of new machines to ensure operator protection. Machine builders for the North American market must now engineer these safety features as standard, not optional add-ons.
A move toward service-based consumption models is altering how large manufacturers acquire machine tool capabilities. The traditional one-time capital purchase is being challenged by long-term service agreements that bundle machine access, maintenance, and software updates into a predictable operational expense. This trend is most prominent in European automotive and aerospace supply chains, where uptime and performance guarantees are critical.
Grinding Machines Market Segmentation
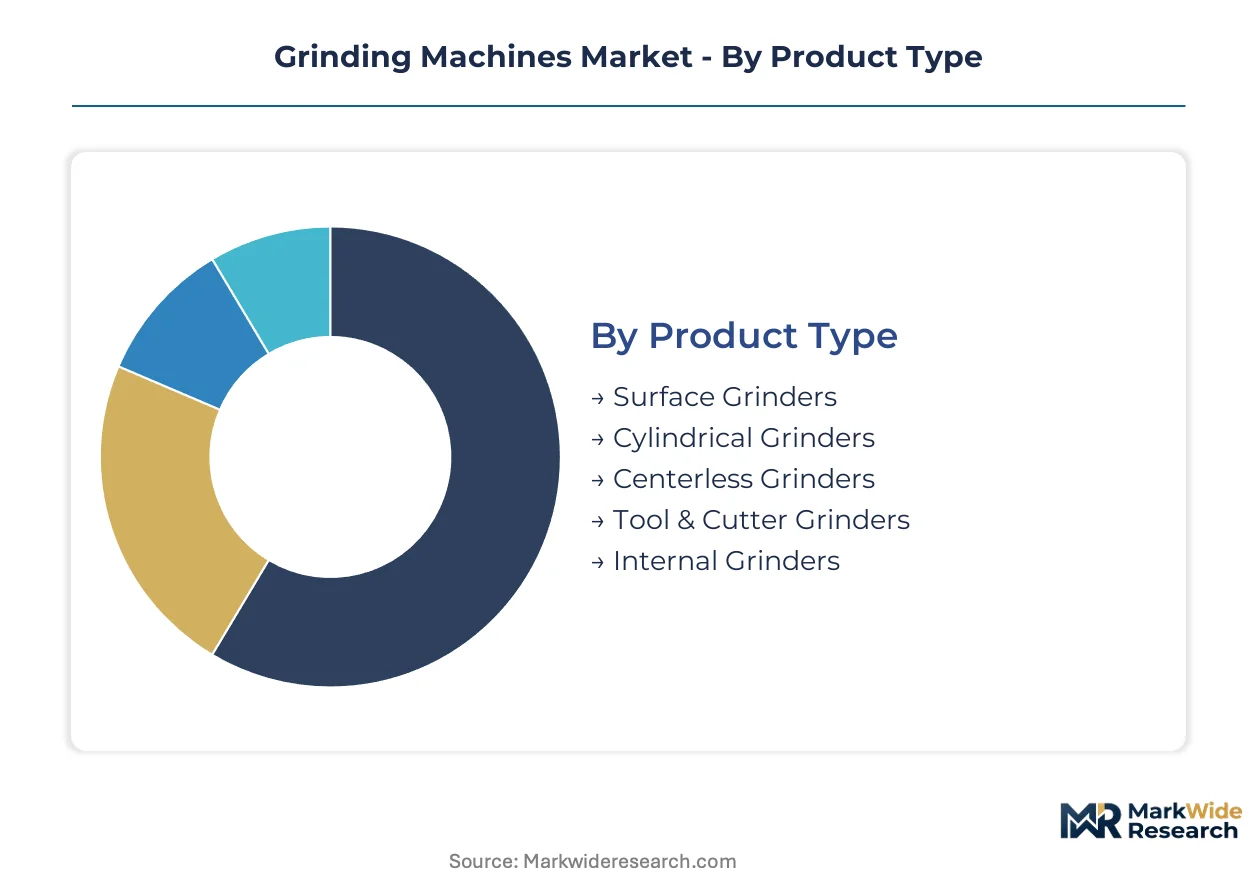
Market segmentation provides a detailed understanding of how diverse product types, technologies, applications, and end-user industries shape demand within the grinding machines market. This granular analysis helps manufacturers align product development and market strategies with specific industry requirements and emerging technological shifts.
Product Type:
Buyers in the grinding machines market make product type decisions based on the required workpiece geometry and the specific surface finish needed for their components.
- Cylindrical Grinders:These machines process external and internal cylindrical surfaces, often for rotating parts requiring high concentricity. Demand concentrates in Germany's automotive industry for precision shafts due to high volume production and strict quality controls.
- Surface Grinders:Surface grinders create flat, smooth surfaces on workpieces using a rotating abrasive wheel, achieving high flatness and parallelism. Demand focuses on tool and die manufacturing in Japan for achieving intricate mold geometries with superior surface integrity.
- Centerless Grinders:These machines grind external cylindrical surfaces without requiring center holes for support, ideal for high-volume production of small parts.
- Tool & Cutter Grinders:These specialized machines sharpen and recondition various cutting tools, extending their lifespan and maintaining cutting performance.
- Internal Grinders:Internal grinders finish the inner diameter of workpieces, crucial for bearing races and bushings where precise fits are essential.
Volume sits with Cylindrical Grinders; growth tilts toward Internal Grinders.
Technology:
Technology selection dictates the level of automation and precision achievable in grinding operations for various industrial applications.
- CNC:Computer Numerical Control (CNC) technology enables automated, multi-axis control of grinding parameters for complex geometries and repeatability. Demand concentrates in China's electronics manufacturing for high-volume, repeatable component production in consumer devices.
- Ultra-Precision:Ultra-precision grinding achieves sub-micron tolerances and mirror-like surface finishes, often using advanced machine designs and environmental controls. Demand focuses on medical device manufacturing in Switzerland for miniaturized orthopedic implants requiring extreme accuracy.
- Conventional:These machines rely on manual operator control for setup and operation, offering versatility for small batches and specialized tasks.
- Manual:Manual grinding machines require continuous operator intervention, suitable for basic finishing tasks and prototyping.
- Automated:Automated systems integrate robotic loading and unloading with grinding processes, enhancing throughput and reducing labor costs in mass production.
Advanced technologies like CNC and Ultra-Precision are gaining market share.
Application:
The specific application determines the required material removal rates and surface integrity standards for grinding machines across different industries.
- Aerospace Parts:Grinding machines finish critical aerospace components like turbine blades and structural elements made from superalloys, demanding sub-micron tolerances. Demand concentrates in the United States for high-tolerance jet engine components due to stringent safety standards and performance requirements.
- Automotive Components:Grinding is essential for precision components such as crankshafts, camshafts, and gears in vehicle powertrains and chassis systems. Demand focuses on Germany's automotive industry for electric vehicle motor components requiring high efficiency and durability.
- Metalworking:This broad category includes general machining tasks for various metal parts, requiring versatile grinding solutions for surface finishing and dimensioning.
- Optical Components:Grinding achieves precise geometries and surface quality for lenses, mirrors, and prisms in optical systems, minimizing light distortion.
- Mold Making:Grinding machines create highly accurate and smooth surfaces for molds used in plastic injection or die casting, influencing final product quality.
Automotive Components and Aerospace Parts applications drive significant investment in advanced grinding capabilities.
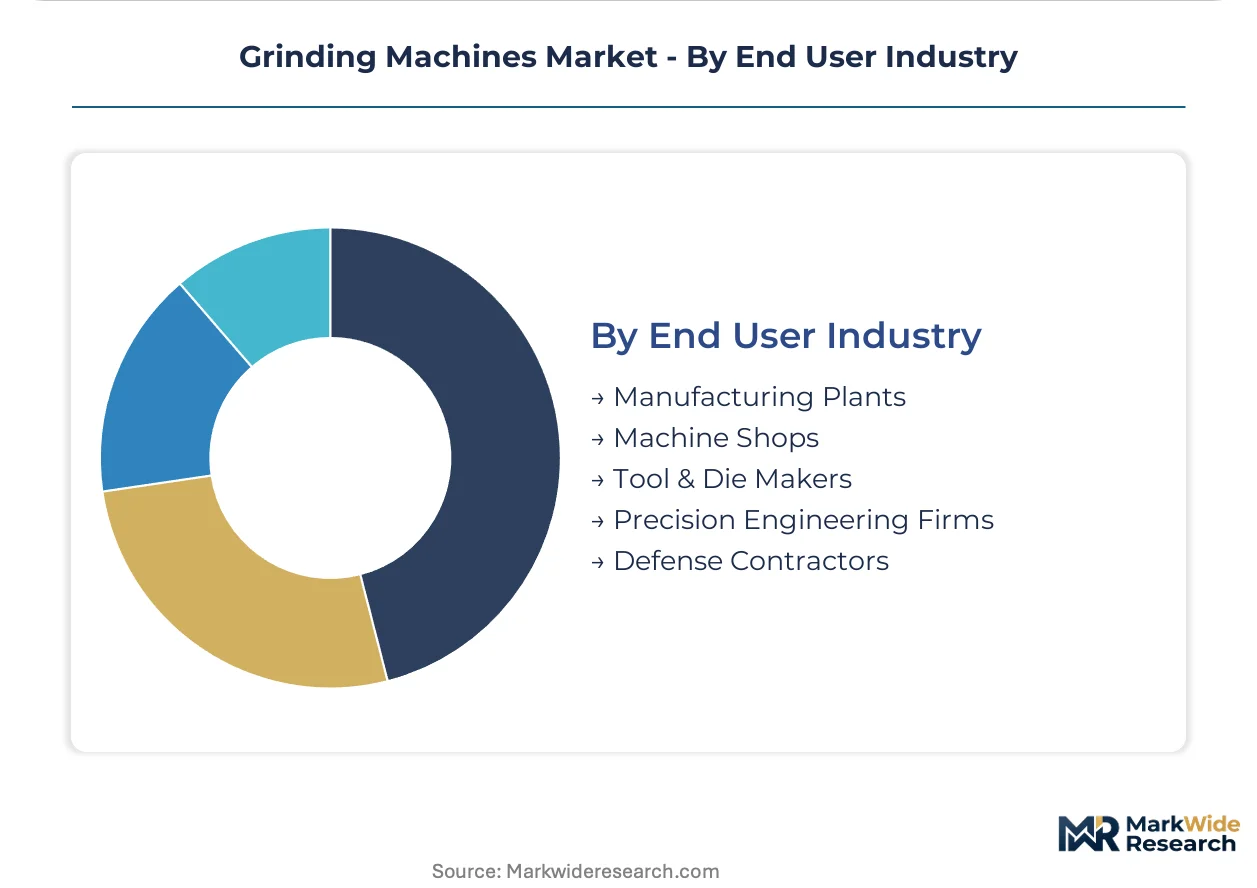
End User Industry:
End-user industry characteristics influence the scale of production, required machine flexibility, and investment capacity for grinding equipment.
- Precision Engineering Firms:These firms specialize in producing components with extremely tight tolerances and complex designs for various high-tech sectors. Demand concentrates in Switzerland for micro-machining applications in luxury watchmaking and medical devices.
- Manufacturing Plants:Large-scale manufacturing plants utilize grinding machines for high-volume production of standardized parts in sectors like automotive and electronics. Demand focuses on China's industrial clusters for mass production of consumer electronics components.
- Machine Shops:General machine shops use grinding for diverse job-shop work, often requiring flexible and adaptable machines for varied client needs.
- Tool & Die Makers:These specialists rely on grinding for producing high-precision tools, dies, and molds with exacting specifications for manufacturing processes.
- Defense Contractors:Defense contractors use grinding machines for critical components in armaments and aerospace, demanding extreme reliability and performance.
Precision Engineering Firms and Manufacturing Plants represent the fastest-growing end-user segments for grinding machine procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration within China's advanced manufacturing clusters drives significant investment in grinding machines, particularly for its expanding automotive and electronics sectors. This regional focus reflects broader industrial policies prioritizing high-end machine tools. Other key regions also exhibit distinct demand profiles shaped by their industrial specializations and regulatory environments.
China
China's robust electronics manufacturing and electric vehicle production propel demand for advanced grinding machines. National industrial policies, such as specific GB standards for machine tool safety and performance, influence equipment design. Chinese industrial clusters, particularly in the Yangtze River Delta, are aggressively adopting CNC technology for mass production of consumer electronics components.
Germany
Germany's automotive industry drives substantial demand for precision grinding solutions, especially for high-volume production of precision shafts and EV motor components. Compliance with CE marking for European market access and the EU Green Deal's sustainability mandates shape machine development. Bavaria and Baden-Württemberg remain key centers for automotive manufacturing and advanced machine tool innovation.
United States
The United States aerospace parts manufacturing sector requires grinding machines capable of achieving sub-micron tolerances for jet engine components. OSHA regulations regarding machine guarding and operator safety protocols are fundamental design considerations for equipment sold in this market. Clusters around Seattle and Wichita concentrate on high-tolerance jet engine components due to stringent safety standards.
Japan
Japan's tool and die manufacturing sector requires surface grinders for achieving intricate mold geometries with superior surface integrity. Adherence to JIS standards ensures high quality and precision in machine tool construction and operation. The Chubu region, including Nagoya, remains a critical hub for automotive component manufacturing and high-precision tooling.
Switzerland
Switzerland's specialized medical device manufacturing and luxury watchmaking sectors demand ultra-precision grinding equipment for miniaturized orthopedic implants. Swissmedic regulations ensure stringent quality and safety standards for medical device production. Precision engineering firms in the Jura Arc region focus on micro-machining applications, requiring extreme accuracy.
Grinding Machines Market Key Industry Players
Technology integration dominates the current landscape as manufacturers seek to enhance precision and automation capabilities. The market structure exhibits a tiered consolidation, with a few global players offering comprehensive portfolios alongside numerous specialized manufacturers. Key strategic archetypes include diversified solution providers, high-speed specialists, and niche application experts. Competitive moves primarily involve portfolio diversification and strategic partnerships to integrate advanced metrology.
Specialists in specific grinding applications include Falcon Machine Tools, which focuses on surface grinders for the tool and die sector. United Grinding North America represents a diversified portfolio player, leveraging its extensive range of surface and cylindrical grinding solutions to address complex material challenges. JTEKT Toyoda Americas Corporation occupies a position as a high-speed specialist, competing on the strength of its advanced CNC grinders tailored for automotive production lines.
| Leading Market Players |
|---|
| STUDER |
| BLOHM |
| JTEKT Toyoda Americas Corporation |
| KREBS & RIEDEL |
| MÄGERLE |
| Falcon Machine Tools |
| WALTER |
| Rome Grinding Solutions |
| United Grinding North America |
| Others |
Cost & Logistics Intelligence
Specialized abrasive materials for grinding wheels impact production costs for ultra-precision machines, influencing their premium pricing in aerospace and medical sectors downstream.
Pricing Analysis
Volume-driven segments like automotive manufacturing emphasize cost-efficiency, while aerospace and medical device applications prioritize specialized performance and higher margins. Tiered pricing structures are common, differentiating between conventional, CNC, and ultra-precision machines. Quality grade, CE marking compliance, and customization for complex geometries drive premium pricing. Pricing softness reflects competition from alternative machining processes like electrical discharge machining for intricate features. Small and medium-sized enterprises in tool and die manufacturing are highly price-sensitive, whereas precision engineering firms prioritize accuracy over cost.
Supply Chain Analysis
Dual-sourcing requirements for critical components are becoming prevalent among large-scale manufacturers to mitigate supply chain disruptions. Manufacturing of grinding machine components concentrates in Germany for precision mechanics, Japan for advanced robotics, and China for high-volume standard parts. The industry relies heavily on specialized abrasive materials, high-precision bearings, and advanced CNC controllers. Single-source vulnerability for ultra-precision metrology sensors presents a structural risk. Distribution runs through direct sales channels for major industrial buyers and specialized distributors for smaller workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The persistent lack of technicians proficient in programming complex multi-axis CNC grinding machines creates a supply-side constraint. This human capital bottleneck props up pricing for advanced automation solutions that mitigate labor dependency.
For Market Incumbents: Lock in long-term service agreements with aerospace and medical device clients to secure recurring revenue streams against competitive threats from alternative machining processes. Invest in research and development for integrated in-process metrology to achieve sub-micron tolerances, and pursue strategic partnerships for artificial intelligence and machine learning integration into CNC controllers. Deepen certification investments in ISO 9001 and CE marking to reinforce market access and quality perception.
For New Entrants and Emerging Players: Specialized systems integrators offer a viable entry point for new players targeting niche applications requiring complex automation. Focus on developing micro-grinding equipment for medical device miniaturization, or eco-friendly grinding solutions addressing EU Green Deal mandates. Precision engineering firms in Switzerland represent a highly receptive segment for ultra-precision equipment. Emphasize integrated automation and in-process metrology capabilities to address skilled operator shortages.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists in Germany's automotive supply chain, presenting opportunities for long-term value. The long-term viability of grinding machine investments remains strong due to persistent demand for high-tolerance components in aerospace and medical sectors. Target specialized technology providers with expertise in ultra-precision grinding or advanced metrology systems. Monitor the adoption rates of artificial intelligence and machine learning algorithms in CNC controllers as an inflection indicator for future growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-driven Adaptive Control | AI algorithms in CNC controllers reduce process variability, improving part consistency for automotive production. |
| Develop Micro-Grinding Solutions | Specialized micro-grinding equipment addresses miniaturization trends in Switzerland's medical device manufacturing. |
| Expand Integrated Metrology Offerings | In-process metrology reduces scrap rates and inspection steps for aerospace parts manufacturing in the United States. |
| Pursue Eco-Friendly Machine Design | Energy-efficient designs and reduced coolant usage align with EU Green Deal regulations in European markets. |
| Enhance Operator Training Programs | Addressing the skilled operator shortage supports adoption of complex multi-axis CNC machines in precision engineering firms. |
Research Approach
Industry association reports, government industrial policy documents, and company annual reports formed the secondary backbone for this analysis. Primary interviews with production managers, R&D engineers, procurement specialists, and machine tool distributors provided qualitative insights. This data was triangulated using both bottom-up market sizing and top-down validation approaches.
Historical trendline analysis combined with econometric modeling established the foundational forecast framework across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived from projected shifts in manufacturing capital expenditure cycles and technological advancements in difficult-to-machine materials.
Caveats apply where geopolitical trade policies or significant raw material price volatility could materially shift the outlook. Forecasts reflect documented assumptions regarding technological adoption and manufacturing investment. Deviation in skilled labor availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Vertical Milling Machine Market
Tools
Mold Racks Market
Tools
Cordless Wood Planer Market
Tools
Industrial Cleaning Equipment Market
Tools
Taps and Dies Market
Tools
Floor Scraper Market
Tools
Nail Gun Market
Tools
Painting Tools Market
Tools
Machine Bench Vices Market
Tools
Broaching Tools Market
Tools
Brazing Torch Market
Tools
Coil Thread Insert Market
Tools
Vinyl Bending Machine Market
Tools
Digital Levels Market
Tools
Fine Blanking Tools Market
Tools
Drill Bit Market