
 Community Cloud Market | 2026-2036
Community Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Community Cloud Market Analysis
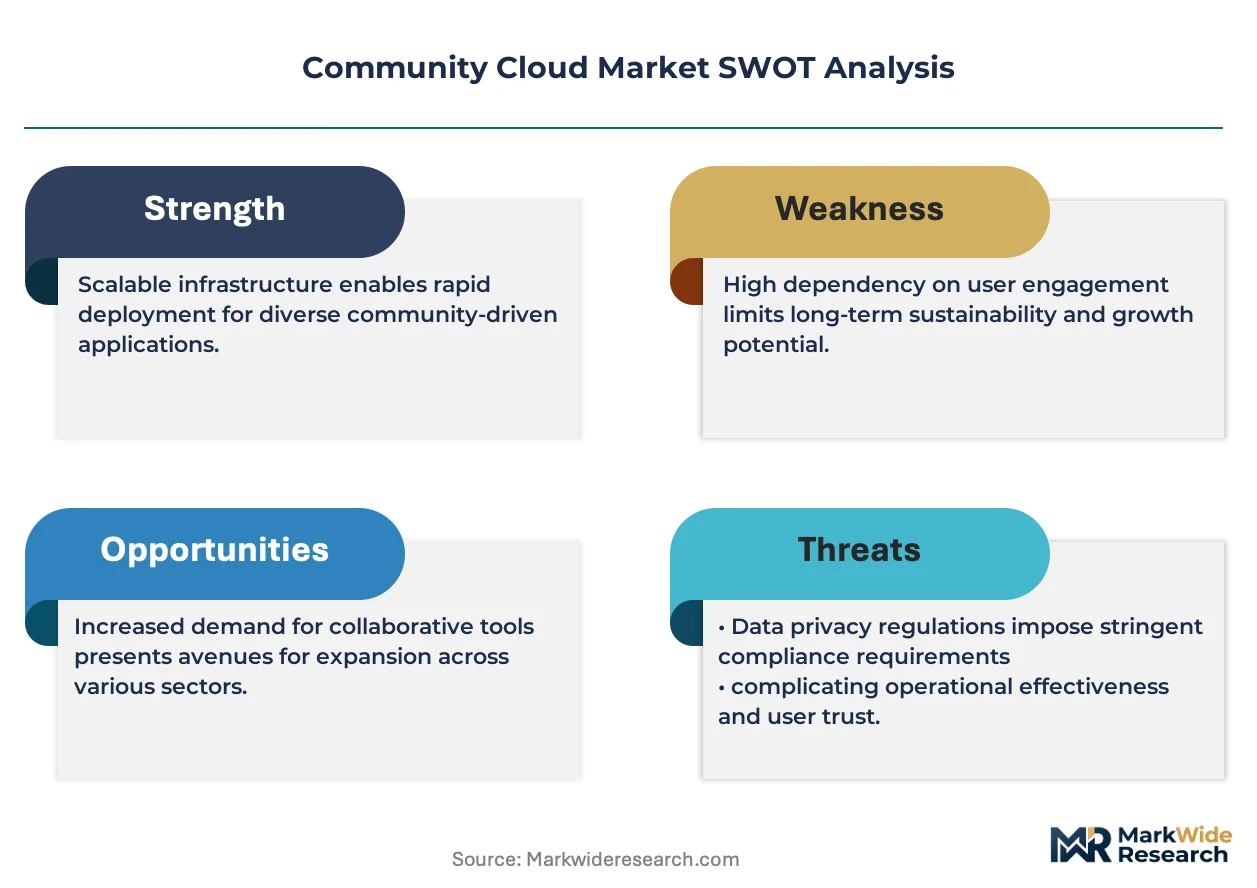
Healthcare provider demand is consolidating as the dominant end-use vertical within community cloud deployments, displacing earlier education-sector concentration. Microsoft Corporation leverages its Azure Government stack to anchor sovereign cloud instances across European public-sector consortia. Amazon Web Services, Inc. competes through dedicated local zones purpose-built for regulated health data workloads. IBM Corporation specializes in hybrid fabric architectures that bridge on-premise hospital systems with shared community infrastructure.
Community cloud denotes a multi-tenant infrastructure model where computing resources serve a defined cohort of organizations bound by common compliance, operational, or sectoral requirements, typically deployed with tenant isolation at the virtualization layer and encryption both in transit and at rest. Its primary commercial purpose centers on delivering economies of scale without sacrificing the jurisdictional control and audit transparency that single-tenant private clouds provide at premium cost. Hybrid cloud deployments now lead structural investment as agencies sequence workload migration while retaining sensitive processing on premise. SaaS delivery within community frameworks shows the fastest expansion trajectory, though IaaS retains the deepest margin pools due to long-term capacity commitments and custom networking configurations.
FDA guidance on cloud-based medical device data systems, HIPAA Security Rule provisions for business associate agreements, and GDPR Article 28 processor requirements collectively shape product architecture and market access conditions for community cloud vendors. EU AI Act risk-classification obligations are extending compliance burdens into machine-learning inference layers hosted on shared infrastructure. Stakeholders must monitor evolving cross-border data localization statutes to determine whether federated community models or country-captive instances represent the more durable configuration.
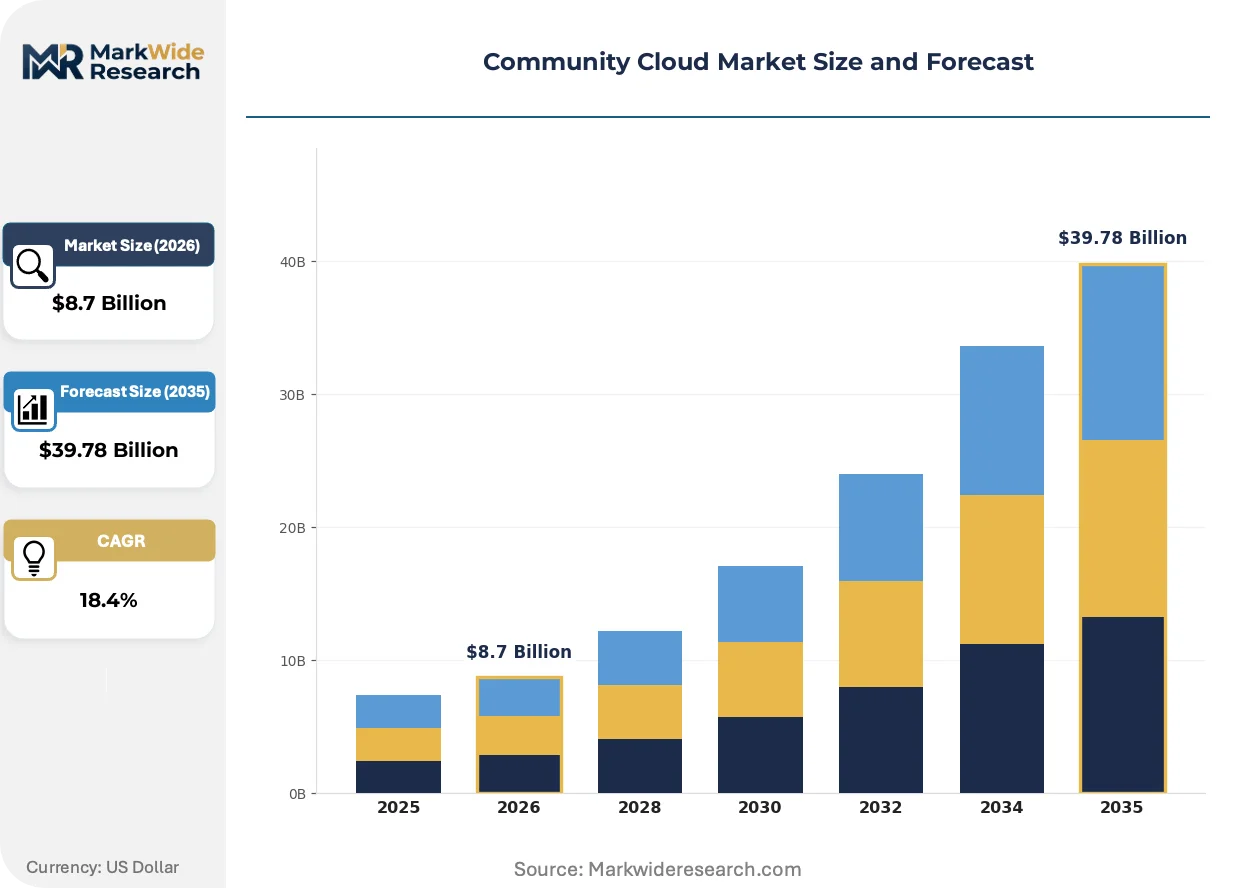
Market Dynamics
Multi-jurisdictional data sovereignty mandates are forcing infrastructure redesigns across healthcare consortia, compelling providers to abandon centralized hyperscale models in favor of federated community architectures with jurisdictional isolation at the virtualization layer.
Growth Catalysts
- GDPR Article 28 Processor Mandates:Data localization requirements under European privacy law are accelerating procurement of sovereign cloud instances by German public-sector consortia.
- Healthcare Interoperability:Patient data exchange imperatives are consolidating demand among hospital networks seeking shared infrastructure with HIPAA-compliant encryption controls.
- EU AI Act Risk Classification:Machine-learning inference obligations on shared infrastructure are creating regulated demand for compliant community hosting environments.
Market Restraints
- Cross-Border Data Localization Statutes:Conflicting national requirements fragment infrastructure economics and complicate federated deployment models.
- Custom Networking Configurations:Long-tail IaaS commitments with specialized routing requirements extend payback periods and depress margin velocity.
- Hybrid Integration Complexity:Bridging on-premise hospital systems with shared community fabrics demands scarce specialized engineering talent.
Strategic Opportunities
- SaaS Delivery Expansion:Application-layer services within community frameworks show accelerating trajectory as providers seek operational expenditure models.
- Edge-Cloud Convergence:Distributed inference nodes combined with centralized community storage are opening new workload categories for latency-sensitive diagnostics.
- German Public-Sector Consortia:Localized cloud clusters serving municipal and regional government entities represent underpenetrated procurement channels.
Industry Challenges
- Business Associate Agreement Negotiations:HIPAA Security Rule compliance timelines for cloud vendors extend sales cycles and strain legal resources.
- Virtualization Layer Isolation Expertise:Shortage of engineers capable of implementing tenant-segregated architectures at scale constrains deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Community Cloud Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Hybrid Cloud, Private Cloud, Public Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, Managed Services End User: Education Institutions, Government Agencies, Non-Profit Organizations, Healthcare Providers Security Features: Data Encryption, Identity Management, Access Control, Compliance Auditing |
| Companies Covered | Amazon Web Services, Inc., Microsoft Corporation, Google LLC, IBM Corporation, Cisco Systems, Inc., Salesforce, Inc., Oracle Corporation, Broadcom Inc., Atos SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Community Cloud Market Emerging Trajectories
Architectural evolution in community cloud deployments centers on unifying previously siloed compliance frameworks with operational scalability, compressing the traditional trade-off between jurisdictional control and cost efficiency that has structured procurement decisions.
Confidential computing hardware is unifying encryption-in-use capabilities with existing at-rest and in-transit protections, enabling healthcare providers to process sensitive patient records on shared infrastructure without exposing raw data to cloud operators. German hospital networks are piloting these trusted execution environments for multi-party analytics across institutional boundaries. This technology is unifying previously incompatible security requirements from GDPR, HIPAA, and FDA guidance into single-stack deployments.
FDA guidance on cloud-based medical device data systems is tightening validation requirements for infrastructure hosting connected diagnostic equipment, forcing vendors to document continuous compliance monitoring rather than point-in-time certification. Medical device manufacturers are restructuring supplier agreements to include real-time audit rights. The regulated health data segment is responding by demanding dedicated local zones with pre-validated control frameworks.
Consortium-based procurement is displacing single-institution cloud contracts as hospital systems seek volume leverage and shared compliance costs. Purchasing coalitions in Germany and the Netherlands are aggregating demand for sovereign cloud capacity, shifting vendor relationships from bilateral negotiations to multi-party frameworks. This behavioral shift is most visible in European public-sector health networks where budget constraints intersect with strict data localization requirements.
Community Cloud Market Segmentation
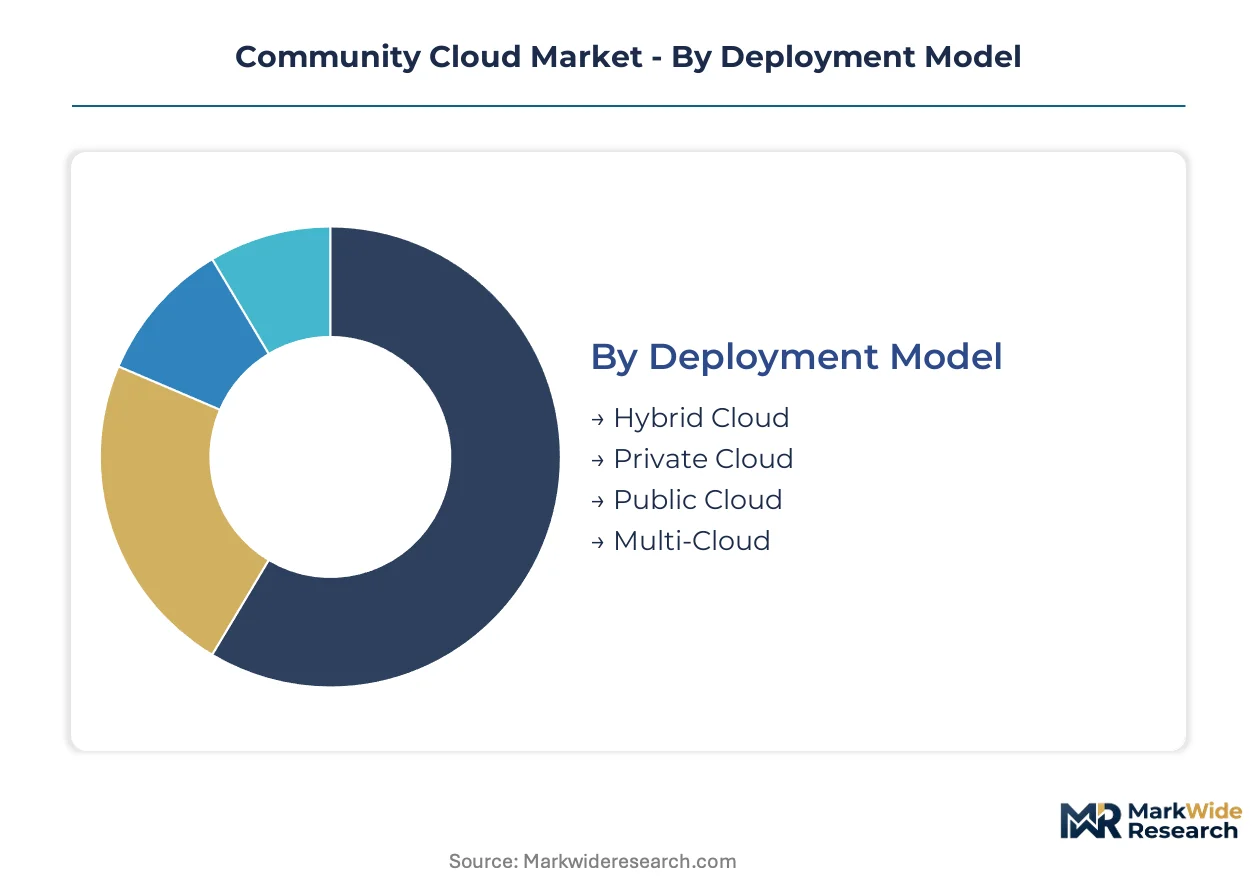
Community cloud procurement decisions pivot on deployment architecture, service layering, and sector-specific compliance requirements. Segmentation reveals how healthcare consortia prioritize hybrid fabrics while German public-sector buyers concentrate demand in sovereign IaaS configurations.
Deployment Model:
Upgrade cycles from legacy on-premise infrastructure to shared community architectures vary dramatically by control requirements and data sensitivity classifications.
- Hybrid Cloud:Combines on-premise hospital systems with shared community capacity through encrypted interconnect fabrics. German public-sector health networks are consolidating procurement around hybrid stacks to satisfy GDPR data localization while retaining legacy system integration.
- Private Cloud:Delivers dedicated single-tenant infrastructure with full jurisdictional isolation at the virtualization layer. FDA-regulated medical device manufacturers demand private community instances for continuous compliance monitoring obligations.
- Public Cloud:Multi-tenant shared infrastructure with standardized encryption controls and automated compliance tooling. Education institutions displaced from earlier market concentration now represent residual demand for cost-sensitive public community deployments.
- Multi-Cloud:Orchestrated workload distribution across disparate cloud operators to mitigate vendor lock-in and geographic risk. Dutch hospital purchasing coalitions are piloting multi-cloud frameworks to balance sovereignty requirements against supplier diversity.
Volume placements concentrate in Hybrid Cloud; the faster expansion belongs to Multi-Cloud.
Service Type:
Margin structures diverge sharply between capital-intensive infrastructure commitments and operational expenditure application layers.
- IaaS:Raw compute, storage, and networking capacity with custom routing configurations and long-term capacity reservations. Deep margin pools attract sustained vendor investment despite extended payback periods from specialized networking requirements.
- SaaS:Pre-configured healthcare applications delivered through shared community frameworks with HIPAA-compliant encryption controls. Hospital networks seeking operational expenditure models are accelerating procurement of clinical workflow SaaS within sovereign cloud instances.
- PaaS:Development and deployment environments with pre-validated compliance frameworks for regulated health data workloads. Medical device manufacturers leverage PaaS layers to compress FDA validation timelines for cloud-connected diagnostics.
- Managed Services:Outsourced operational responsibility including security monitoring, patch management, and audit documentation. Scarce virtualization-layer isolation expertise is driving demand for managed service wrappers around community infrastructure.
Revenue concentration remains deepest in IaaS; SaaS is climbing the fastest as procurement shifts toward operational expenditure models.
End User:
Compliance maturity and budget authority shape adoption velocity across institutional categories.
- Healthcare Providers:Hospital networks and integrated delivery systems requiring HIPAA-compliant encryption with GDPR Article 28 processor agreements. German hospital consortia are aggregating demand through purchasing coalitions to secure volume pricing on sovereign cloud capacity.
- Government Agencies:Municipal, regional, and national public-sector entities with strict data localization mandates. Localized cloud clusters in Germany serve this segment through dedicated sovereign instances with pre-validated control frameworks.
- Education Institutions:Universities and research consortia with moderate compliance requirements and cost-sensitive procurement. Earlier market concentration in this segment has yielded to healthcare provider dominance as interoperability imperatives reshape priorities.
- Non-Profit Organizations:Charitable health systems and research foundations with constrained capital budgets and shared mission alignment. Consortium-based procurement models enable this segment to access enterprise-grade infrastructure through pooled demand aggregation.
Contract value concentrates among Healthcare Providers; Government Agencies show the steepest expansion trajectory under sovereign cloud mandates.
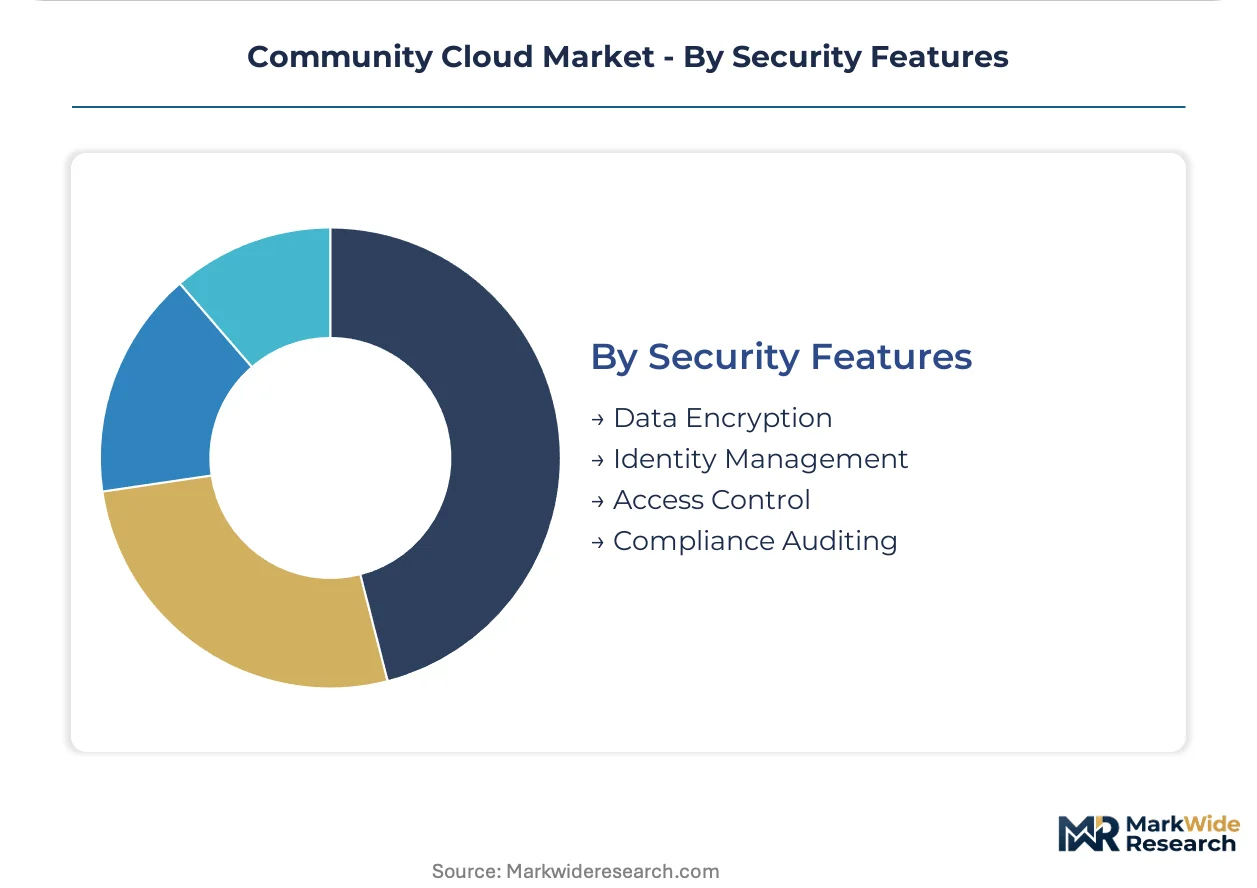
Security Features:
Architectural investment prioritizes capabilities that unify previously incompatible regulatory requirements into single-stack deployments.
- Data Encryption:At-rest, in-transit, and in-use protections including confidential computing hardware for raw data isolation. German hospital networks pilot trusted execution environments to enable multi-party analytics without exposing patient records to operators.
- Identity Management:Federated authentication and privileged access controls spanning institutional boundaries. HIPAA Security Rule business associate agreement negotiations are extending sales cycles for vendors lacking mature identity federation architectures.
- Access Control:Role-based and attribute-based permissions with real-time audit logging for regulatory inspection. EU AI Act risk-classification obligations are embedding access control requirements into machine-learning inference layers on shared infrastructure.
- Compliance Auditing:Continuous monitoring, automated evidence collection, and real-time audit rights for regulatory inspectors. FDA guidance on cloud-based medical device data systems is tightening validation requirements from point-in-time certification to continuous compliance documentation.
Procurement weight concentrates in Data Encryption; Compliance Auditing is gaining share fastest as regulatory frameworks shift toward continuous validation models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt Rhine-Main's financial hub status and proximity to European Central Bank data centers concentrate sovereign cloud investment in Germany. Tax incentives for greenfield data center construction in Luxembourg and Ireland accelerate hyperscaler facility deployment. Dutch digital infrastructure subsidies position Amsterdam as a secondary node for health data federation.
United States
FDA validation requirements for cloud-hosted medical devices drive hospital procurement of compliant community instances. HIPAA Security Rule enforcement through OCR audits compels business associate agreement standardization. The Research Triangle Park cluster in North Carolina hosts multi-institutional health data consortia piloting federated analytics.
Germany
GDPR Article 28 processor mandates accelerate sovereign cloud procurement by municipal health networks. The Gaia-X initiative structures technical standards for federated European data infrastructure. Berlin-Brandenburg's public-sector consortia aggregate demand through centralized procurement frameworks serving regional hospital systems.
Netherlands
Healthcare purchasing coalitions in Utrecht and Rotterdam consolidate cloud capacity tenders for interoperability mandates. The Dutch Authority for Personal Data enforces strict data localization for patient records. Eindhoven's health technology cluster experiments with edge-cloud convergence for diagnostic imaging workloads.
United Kingdom
NHS Digital's cloud-first policies redirect hospital infrastructure spending toward community architectures with IGToolkit compliance. The UK Information Commissioner's Office enforces data protection impact assessments for shared health platforms. London's academic medical centers operate procurement consortia spanning teaching hospital networks.
France
ANSM guidance on cloud-hosted medical device data tightens infrastructure validation for connected diagnostics. The French Data Protection Authority enforces GDPR localization requirements for health data processing. Paris-Saclay's research cluster deploys community cloud instances for multi-party clinical trial data sharing.
Community Cloud Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale platforms dominating IaaS capacity while vertical specialists capture managed services margins. The vendor base concentrates around three tiers: full-stack cloud operators, healthcare-focused compliance wrappers, and regional sovereign infrastructure providers. Consolidation pressures intensify as procurement shifts toward consortium-based tendering. Dominant competitive moves include strategic partnerships with hospital purchasing coalitions and geographic expansion through dedicated local zone deployment.
Within the full-stack operator tier, Amazon Web Services, Inc., Microsoft Corporation, and IBM Corporation exemplify divergent architectural bets. AWS anchors its position through dedicated local zones purpose-built for regulated health data workloads. Microsoft leverages Azure Government stack penetration to secure European public-sector consortia contracts. IBM occupies a hybrid fabric specialization bridging on-premise hospital systems with shared community infrastructure. These three represent distinct responses to multi-jurisdictional sovereignty requirements.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Cisco Systems, Inc. |
| Salesforce, Inc. |
| Oracle Corporation |
| Broadcom Inc. |
| Atos SE |
| Others |
Supply Flow & Price Mechanics
Confidential computing hardware adoption is compressing infrastructure cost curves while concentrating supplier qualification authority among three dominant chip vendors. German hospital consortia now demand trusted execution environments as standard, forcing cloud operators to absorb premium silicon costs or cede sovereign cloud tenders to qualified rivals.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent deployments from planned capacity reservations across community cloud procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and data sovereignty tier, with HIPAA-validated instances commanding substantial premiums over baseline encryption offerings. Cost compression in standard-tier IaaS is intensifying because hyperscalers are absorbing networking customization overhead to secure long-term hospital network commitments. Non-profit health systems exhibit highest price sensitivity, while FDA-regulated medical device manufacturers prioritize compliance-grade instances regardless of cost premium.
Supply Chain Analysis
Certification and qualification gating restricts trusted execution environment silicon supply to Intel, AMD, and ARM Holdings licensees with healthcare-validated firmware stacks. Raw material dependencies center on advanced semiconductor lithography equipment, rare earth elements for processor manufacturing, and specialized cooling infrastructure for edge-cloud convergence nodes. Single-source vulnerability concentrates in confidential computing attestation services, where proprietary verification protocols tether hospital networks to specific vendor ecosystems. Distribution runs through direct hyperscaler procurement channels and regional sovereign infrastructure providers serving German public-sector consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Community cloud capacity is supply-constrained by scarce engineers capable of implementing tenant-segregated virtualization architectures at scale, propping pricing power for qualified vendors.
For Market Incumbents: Hedge against margin erosion by acquiring managed service wrappers with HIPAA Security Rule expertise and by expanding dedicated local zone footprints in Berlin-Brandenburg municipal networks. Vertical integration into confidential computing hardware partnerships secures silicon allocation priority as German hospital consortia consolidate procurement. For New Entrants and Emerging Players: Launch via consortium-based tender participation targeting Dutch healthcare purchasing coalitions in Utrecht and Rotterdam, where interoperability mandates have outpaced incumbent response capacity. White-space concentrates in edge-cloud convergence for diagnostic imaging workloads, with Eindhoven's health technology cluster representing the most penetrable entry node. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hyperscalers seeking sovereign cloud credentials and managed services capabilities. Acquisition targets with pre-validated FDA control frameworks and established German public-sector contracting relationships offer strongest long-term viability. Watch for EU AI Act enforcement actions against non-compliant inference hosting as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | GDPR Article 28 processor mandates in Germany require jurisdictional isolation at virtualization layer. |
| Confidential Computing Partnership | Trusted execution environments enable multi-party analytics without exposing raw patient records to operators. |
| Hospital Consortium Integration | Berlin-Brandenburg public-sector frameworks aggregate demand through centralized procurement channels. |
| Managed Services Acquisition | Scarce virtualization-layer isolation expertise drives premium valuations for qualified engineering teams. |
| Edge-Cloud Convergence Deployment | Eindhoven diagnostic imaging pilots demonstrate latency-sensitive workload viability for distributed infrastructure. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cloud infrastructure architects, hospital procurement committee members, biomedical informatics officers, and GPO contracts managers combined with secondary validation from FDA 510(k) databases, EMA medical device guidance documents, Gaia-X technical specifications, and hyperscaler capex disclosures. Bottom-up deployment tracking across German municipal health networks and top-down market sizing from sovereign cloud procurement tenders were triangulated to derive volume estimates.
Data-stream reconciliation across deployment model, service type, end-user vertical, and security feature tier informed the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate assumptions applied to baseline capacity installation data, with confidential computing hardware penetration curves and EU AI Act compliance timelines serving as industry-specific forecast inputs.
Regulatory enforcement variance, confidential computing silicon allocation disruptions, and hospital purchasing coalition negotiation outcomes are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in EU AI Act risk-classification implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Cloud Office Services Market
Cloud Computing
Global Cloud Computing in Healthcare Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Global Cloud High-Performance Computing Market
Cloud Computing
Government Cloud Computing Market
Cloud Computing
High-Performance Computing (HPC) As a Service Market
Cloud Computing
Global Cloud Computing Iaas in Life Science Market
Cloud Computing
Cloud Data Warehouse Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Multi-Cloud Optimization Tools Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
Cloud CDN Market
Cloud Computing
India Cloud Computing Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
Web Service Cloud Market