
 Cloud Identity Management Market | 2026-2036
Cloud Identity Management Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Identity Management Market Outlook
GDPR enforcement is rebalancing the cost-of-entry calculus for cloud identity vendors serving European enterprises. Microsoft Corporation leverages its Azure Active Directory ecosystem to anchor enterprise hybrid deployments across regulated industries. Okta Inc. competes through API-first architectures that simplify SaaS application onboarding for mid-market buyers. SailPoint Technologies specializes in identity governance administration, sustaining premium positioning through compliance automation workflows.
Cloud identity management governs the lifecycle of digital identities across distributed computing environments through protocols such as SAML, OAuth, and SCIM for secure authentication and authorization. Its primary commercial purpose is to unify access controls across heterogeneous application portfolios while maintaining audit trails for security and compliance. Multi-factor authentication occupies the fastest-expanding solution tier as phishing-resistant standards like FIDO2 displace password-centric models. Hybrid cloud deployment attracts the largest enterprise spend as organizations retain sensitive directory services on-premises while extending identity federation to public cloud workloads.
FDA oversight of cloud systems handling pharmaceutical research data shapes identity verification requirements for life sciences adopters. The EU AI Act imposes conformity assessments on automated identity decisions, forcing vendors to document algorithmic transparency. NIST SP 800-63 digital identity guidelines influence federal procurement criteria for government agency deployments. Stakeholders must monitor evolving zero-trust mandates from regulators and decide whether to build adaptive risk engines internally or embed third-party behavioral analytics.
Market Dynamics
Zero-trust architecture mandates from NIST and the EU AI Act are forcing identity vendors to rebuild authentication stacks around continuous verification rather than perimeter-based access models. This structural pivot favors platforms with native behavioral analytics over legacy directory services.
Growth Catalysts
- EU AI Act Conformity Assessments:Automated identity verification systems face mandatory algorithmic transparency documentation, creating pull for governance platforms that embed audit trails by design.
- FIDO2 Standards:Phishing-resistant authentication protocols are displacing password-centric models across financial services and healthcare verticals, accelerating hardware security key deployments.
- German Industrial Consolidation:Multi-cloud identity architectures are centralizing procurement decisions at conglomerate headquarters in Munich and Stuttgart, concentrating vendor selection authority.
Market Restraints
- Skilled Identity Architect Scarcity:Zero-trust implementation expertise commands premium compensation in Frankfurt, London, and Singapore, inflating deployment costs for mid-market buyers.
- Legacy Directory Lock-in:Active Directory dominance in enterprise on-premises infrastructure creates switching friction that extends hybrid cloud migration timelines by 18-36 months.
- Cross-Border Data Localization:China's PIPL and Russia's data sovereignty laws fragment identity federation architectures, forcing redundant infrastructure investments.
Strategic Opportunities
- India's Digital Public Infrastructure:The Aadhaar-linked identity stack creates a greenfield market for cloud-native verification vendors serving fintech and e-government applications.
- Convergence of IAM and Data Security:Identity platforms that integrate attribute-based access control with data loss prevention are capturing budget from separate security tool categories.
- CSRD Reporting Mandates:European sustainability disclosure requirements position identity governance data as a source of workforce analytics for ESG compliance automation.
Industry Challenges
- SCIM Protocol Fragmentation:Inconsistent vendor implementations of automated provisioning standards force costly custom integration work for enterprise IT teams.
- Post-Quantum Cryptography Migration:Certificate infrastructure re-architecture demands capital allocation before NIST finalizes algorithm standards, creating planning uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Identity Management Market |
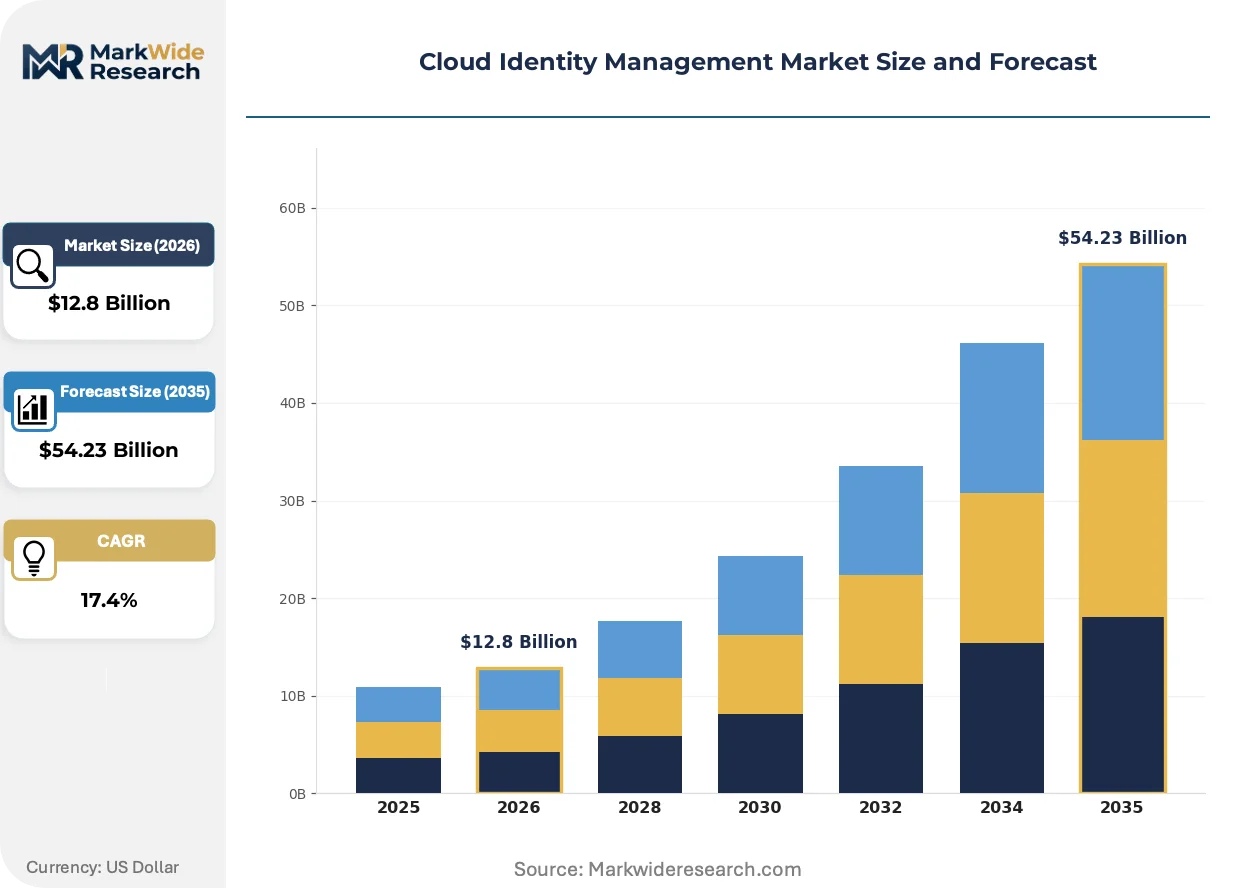
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $54.23 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Single Sign-On, Multi-Factor Authentication, Identity as a Service, Privileged Access Management Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Managed Cloud End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Integration Type: API Integration, Custom Integration, Standard Integration, Legacy System Integration |
| Companies Covered | Okta Inc., Microsoft Corporation, IBM Corporation, Ping Identity, Oracle Corporation, Amazon Web Services Inc., SailPoint Technologies, Saviynt, Google Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Identity Management Market Strategic Shifts
Passwordless authentication is converging with decentralized identity standards to reshape how enterprises provision workforce access. Three developments are compressing competitive timelines and reallocating R&D budgets.
Behavioral biometrics is converging with continuous authentication protocols to eliminate session hijacking risks. Financial institutions in Singapore and London are deploying keystroke dynamics and mouse-movement analysis at scale. This convergence is compressing the authentication vendor landscape by bundling risk signals directly into identity platforms rather than standalone fraud tools.
The EU AI Act's conformity assessment framework for automated decision-making systems imposes documentation burdens on identity verification vendors serving European enterprises. Algorithmic transparency requirements force engineering teams to build explainability layers into machine learning models. Life sciences and banking sectors in Germany and France are demanding pre-certified identity platforms to accelerate their own compliance timelines.
Buyers are unbundling identity professional services from software subscriptions, preferring fixed-scope implementation contracts over perpetual managed service arrangements. System integrators in the United States and United Kingdom are capturing this spend through specialized zero-trust transformation practices. Healthcare and federal government verticals show the strongest preference for outcome-based engagement models tied to specific migration milestones.
Cloud Identity Management Market Segmentation
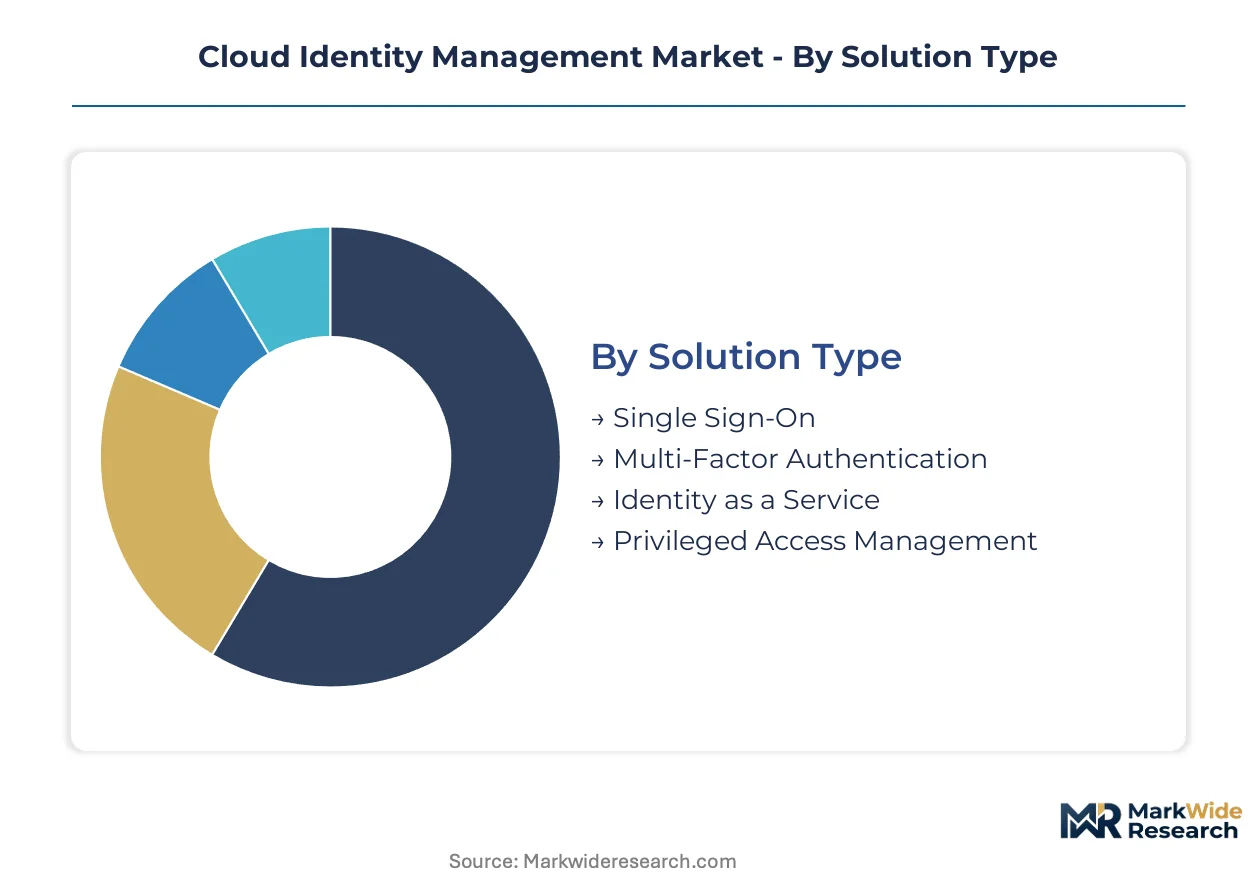
Cloud identity management solutions fragment across deployment architectures, user scale, and integration complexity. Vendors configure pricing and capability tiers around these axes to capture divergent buyer readiness and compliance postures.
Solution Type:
Volume deployments cluster around commoditized authentication layers, while premium pricing attaches to governance and privileged access controls.
- Single Sign-On:Federated authentication protocol enabling one credential set across multiple SaaS applications. Demand concentrates in mid-market financial services firms in Germany and the Netherlands consolidating SaaS portfolios under GDPR-compliant access controls.
- Multi-Factor Authentication:Layered verification combining passwords with biometrics, hardware tokens, or push notifications. Healthcare providers in Singapore and life sciences firms in Switzerland are deploying FIDO2-compliant hardware keys to satisfy FDA and EMA data integrity requirements.
- Identity as a Service:Cloud-native directory and provisioning delivered via subscription.
- Privileged Access Management:Granulated controls for administrative credentials and high-risk system access.
Mature deployment sits with Single Sign-On. Newer deployment is concentrated in Privileged Access Management.
Deployment Model:
Cost tiering separates hyperscale public offerings from sovereign and air-gapped alternatives.
- Public Cloud:Shared infrastructure with tenant isolation via policy enforcement. Fintech startups in India and Brazil are adopting public cloud identity stacks to accelerate Aadhaar-linked and PIX-integrated verification workflows.
- Private Cloud:Dedicated identity infrastructure within enterprise-controlled data centers.
- Hybrid Cloud:Split architecture retaining sensitive directory services on-premises while extending federation to public workloads. German industrial conglomerates in Munich and Stuttgart are centralizing procurement around hybrid configurations to satisfy EU AI Act algorithmic transparency mandates.
- Managed Cloud:Third-party operated identity infrastructure with outsourced operational responsibility.
Established procurement favors Hybrid Cloud. Fastest capability adoption is occurring in Managed Cloud.
End User:
Customer type determines contract structure and support intensity.
- SMEs:Subscription-based identity services with standardized configuration templates.
- Large Enterprises:Custom-negotiated platforms with professional services attachment. Banking groups in London and Frankfurt are demanding outcome-based engagement models tied to zero-trust migration milestones.
- Government Agencies:FedRAMP or equivalent certified deployments with audit trail mandates. Federal buyers in the United States align procurement with NIST SP 800-63 digital identity guidelines.
- Educational Institutions:Volume-discounted identity provisioning for distributed student and faculty populations.
Complex integration requirements define Large Enterprises. Simplified procurement patterns characterize Educational Institutions.
Integration Type:
Technical architecture choices map to internal engineering capacity and legacy system burden.
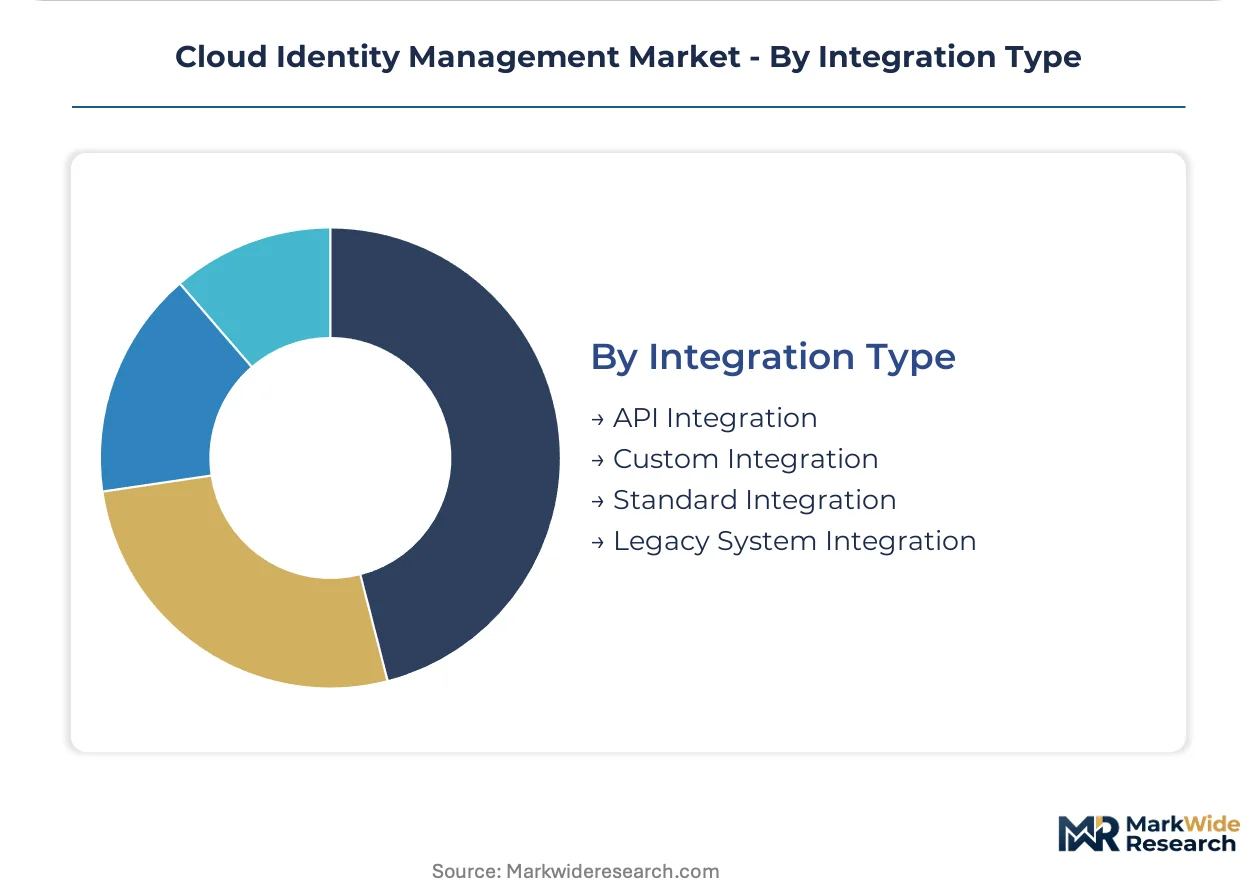
- API Integration:RESTful or GraphQL connectivity for cloud-native application onboarding. Mid-market SaaS vendors in the United Kingdom prioritize API-first identity platforms to accelerate customer provisioning.
- Custom Integration:Bespoke connector development for proprietary or niche systems.
- Standard Integration:Pre-built connectors for common enterprise applications.
- Legacy System Integration:Bridge architectures linking modern cloud identity to on-premises directories. Active Directory dominance in enterprise infrastructure creates switching friction that extends migration timelines for organizations in North America and Western Europe.
Standard Integration captures baseline demand. Engineering-intensive deployment is shifting toward Custom Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial conglomerates concentrate multi-cloud identity procurement authority in Munich and Stuttgart headquarters, while Singapore and London financial centers drive behavioral biometrics adoption at scale.
United States
Federal agencies align identity procurement with NIST SP 800-63 digital identity guidelines, mandating FedRAMP-certified deployments with comprehensive audit trail capabilities. FDA oversight of pharmaceutical research data systems shapes verification requirements for life sciences organizations. Healthcare clusters in Greater Boston and federal contracting corridors around Washington D.C. prioritize outcome-based engagement models tied to zero-trust migration milestones.
Germany
Industrial conglomerates centralize multi-cloud identity architecture decisions at headquarters in Munich and Stuttgart, consolidating vendor selection authority under procurement functions. EU AI Act conformity assessments impose algorithmic transparency documentation burdens on automated verification systems. Banking and automotive sectors in Frankfurt and Wolfsburg demand pre-certified identity platforms to accelerate internal compliance timelines.
United Kingdom
Mid-market SaaS vendors prioritize API-first identity platforms to accelerate customer provisioning workflows across cloud-native application portfolios. System integrators capture unbundled professional services spend through specialized zero-trust transformation practices. Financial services clusters in London deploy behavioral biometrics at scale, integrating keystroke dynamics and mouse-movement analysis into continuous authentication protocols.
Singapore
Financial institutions deploy behavioral biometrics and continuous authentication protocols to eliminate session hijacking risks across digital banking infrastructure. Healthcare providers adopt FIDO2-compliant hardware keys to satisfy data integrity requirements for pharmaceutical research handling. The city-state's fintech regulatory sandbox creates accelerated pathways for cloud-native verification vendors serving cross-border payment applications.
India
Fintech startups adopt public cloud identity stacks to accelerate Aadhaar-linked verification workflows for digital payment and lending applications. The national digital public infrastructure creates greenfield demand for cloud-native verification vendors serving e-government and financial inclusion initiatives. Technology clusters in Bangalore and Mumbai concentrate engineering talent for API-first identity platform development.
Cloud Identity Management Market Competitive Environment
United States-based technology conglomerates anchor one tier with directory services and hyperscale cloud infrastructure; European specialists hold differentiated positions in governance automation and compliance-centric workflows. The vendor landscape stratifies across three archetypes: hyperscale cloud providers bundling identity with infrastructure services, pure-play SaaS vendors with API-first architectures, and governance specialists commanding premium positioning through compliance automation. Consolidation pressure intensifies as zero-trust mandates force authentication stack rebuilds around continuous verification. Strategic moves concentrate on portfolio diversification into behavioral analytics and geographic expansion into India's Aadhaar-linked identity infrastructure.
Within the pure-play SaaS tier, Okta Inc. and SailPoint Technologies exemplify divergent positioning strategies. Okta occupies a position representing API-first architectures that simplify SaaS application onboarding for mid-market buyers. SailPoint anchors the governance automation archetype, sustaining premium positioning through compliance workflow specialization. Microsoft Corporation sits within the hyperscale tier, leveraging Azure Active Directory ecosystem integration to anchor enterprise hybrid deployments across regulated industries. These three patterns illustrate how competitive positioning fragments across technical architecture choices rather than geographic markets alone.
| Leading Market Players |
|---|
| Okta Inc. |
| Microsoft Corporation |
| IBM Corporation |
| Ping Identity |
| Oracle Corporation |
| Amazon Web Services Inc. |
| SailPoint Technologies |
| Saviynt |
| Google Inc. |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration into managed security service provider networks anchors pricing power for mid-market identity platforms while compressing margins for standalone SaaS vendors. EU AI Act compliance certification costs feed directly into subscription pricing tiers, creating a bifurcation between governance-heavy premium offerings and commoditized authentication layers.
Pricing Analysis
Volume deployments concentrate in standardized SSO and MFA tiers where per-seat pricing faces compression from hyperscaler bundling, while governance and PAM solutions sustain premium positioning through compliance automation value. Price differentiation rests on FedRAMP certification grade and algorithmic transparency documentation depth for EU AI Act conformity. Pricing pressure intensifies in the mid-market as Microsoft and Google embed identity capabilities into productivity suites at no incremental cost. SME buyers exhibit highest price sensitivity, while German industrial conglomerates and US federal agencies accept substantial premiums for pre-certified, audit-ready deployments.
Supply Chain Analysis
China's PIPL and Russia's data sovereignty laws are fragmenting identity federation architectures and forcing redundant infrastructure investments across regional deployments. Engineering talent concentrates in India, the United States, and Germany, with Bangalore and San Francisco anchoring platform development and Munich hosting specialized zero-trust implementation expertise. Hardware security key manufacturing draws from Taiwan and South Korea for FIDO2-compliant components. Single-source vulnerability sits with hyperscale cloud infrastructure dependencies. Distribution runs through direct enterprise sales teams for large accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cloud identity management market operates as a cost-of-compliance story where EU AI Act algorithmic transparency mandates erect barrier-to-entry moats favoring vendors with pre-certified governance platforms.
For Market Incumbents: Extend behavioral analytics capabilities through acquisition or in-house development to defend against fraud-tool vendors bundling risk signals into identity platforms. Fortify FedRAMP and EU AI Act certification portfolios to capture US federal and German industrial procurement concentrated in Washington D.C. and Munich headquarters. Prioritize API-first architecture investments to maintain mid-market positioning against hyperscaler bundling. For New Entrants and Emerging Players: Mid-market healthcare providers in the United States represent an underserved buyer archetype seeking outcome-based zero-trust migration contracts with fixed-scope implementation pricing. India's Aadhaar-linked fintech ecosystem offers the most penetrable geography for cloud-native verification vendors with localized engineering presence in Bangalore or Mumbai. Pursue platform integration partnerships with established system integrators rather than direct enterprise sales buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of governance-specialist firms to fill compliance automation gaps. Long-term viability favors vendors with durable certification moats and recurring revenue concentration above eighty percent. Watch NIST post-quantum cryptography standard finalization as an inflection signal triggering certificate infrastructure replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Behavioral analytics bundling into identity stacks displaces standalone fraud vendors in Singapore and London financial centers. |
| Acquisition of Specialist Firm | Governance automation capabilities fill EU AI Act conformity assessment gaps for mid-market European expansion. |
| Geographic Expansion | Aadhaar-linked verification infrastructure in India creates greenfield demand for cloud-native provisioning vendors. |
| Product Launch | FIDO2-compliant hardware key deployments satisfy FDA data integrity requirements for US life sciences organizations. |
| Strategic Partnership | System integrator alliances capture unbundled professional services spend from healthcare and federal government verticals. |
Study Parameters
Multi-period observation of hyperscaler identity capex disclosures, FedRAMP certification timelines, and EU AI Act implementation guidance anchored the trend analysis, supplemented by interviews with CISOs, identity architects, system integrator practice leads, and procurement officers at German industrial conglomerates. Secondary validation drew from NIST SP 800-63 documentation, SEC 10-K filings, EMA regulatory guidance, and hyperscaler earnings call transcripts. Bottom-up deployment estimates triangulated against top-down market sizing across solution type, deployment model, and end-user segmentation.
Input-output matrix modeling connected identity workload growth to infrastructure spending patterns, enterprise SaaS adoption curves, and regulatory compliance timelines across the projection horizon. Segmentation dimensions included solution type, deployment architecture, organization scale, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derived from trend extrapolation of historical deployment velocities adjusted for policy inflection points. Forecast inputs incorporated zero-trust mandate adoption curves and post-quantum cryptography migration planning horizons.
Revisions become necessary when NIST finalizes post-quantum standards, when EU AI Act enforcement actions clarify conformity assessment scope, or when major economies impose additional data localization requirements. Forecasts reflect documented assumptions about regulatory timeline adherence and enterprise migration velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Multi-Cloud Architecture Market
Cloud Computing
Nigeria Cloud Computing Market
Cloud Computing
Cloud-Managed LAN Market
Cloud Computing
Cloud Based-Batch Processing Market
Cloud Computing
Cloud Services Market
Cloud Computing
Cloud Management Market
Cloud Computing
AI and Blockchain Cloud Services Market
Cloud Computing
India Cloud Computing Market
Cloud Computing
Saudi Arabia Cloud Services Market
Cloud Computing
Canada Cloud Computing Market
Cloud Computing
Cloud Based Information Governance Market
Cloud Computing
Global Cloud Office Services Market
Cloud Computing
Hyperscale Cloud Market
Cloud Computing
Europe Mobile Cloud Market
Cloud Computing
Cognitive Cloud Market
Cloud Computing
Japan Cloud Computing Market