
 Cloud Computing Market | 2026-2036
Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Computing Market Intelligence
Serverless computing architectures are reconfiguring how enterprises deploy applications without managing underlying infrastructure. Amazon Web Services dominates serverless with AWS Lambda, which anchors its broader platform ecosystem. Microsoft Azure competes through Azure Functions integrated tightly with its enterprise productivity stack. Google Cloud differentiates via Cloud Run and its Kubernetes-native serverless approach.
Cloud computing encompasses the on-demand delivery of IT resources—compute power, storage, databases, networking, and software—over the internet with pay-as-you-go pricing, typically measured in virtual CPU cores, gigabytes of RAM, and terabytes of storage with latency thresholds under 100 milliseconds for standard workloads. Its primary purpose is to replace capital-intensive on-premises infrastructure with scalable operational expenditure models. Public cloud deployment leads in absolute revenue scale while hybrid cloud architectures capture the fastest growth as enterprises maintain sensitive workloads on-premises. SaaS within the service model dimension commands the deepest margin pools due to high customer lifetime value and low incremental delivery costs.
FDA guidelines for cloud-hosted medical device data, EU GDPR cross-border transfer rules, and China's MEE data localization requirements each reshape where providers build infrastructure and how customers architect compliance. The SEC's cybersecurity disclosure rules for publicly traded companies further accelerate demand for audited cloud environments with transparent incident reporting. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of infrastructure placement and partnership strategy.
Market Dynamics
Serverless computing architectures are compressing deployment cycles and reconfiguring capital allocation patterns across enterprise IT. The shift from provisioned infrastructure to event-driven execution models is redistributing margin pools toward platform orchestration layers and away from raw compute commoditization.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making systems require auditable cloud infrastructure, forcing financial services and healthcare providers to upgrade hosting environments.
- Real-time transaction processing:Payment networks and capital markets infrastructure demand sub-100 millisecond latency thresholds that only hyperscale edge deployments can satisfy.
- Federal procurement concentration:United States government cloud contracts are consolidating demand among cleared facilities, accelerating investment in accredited data center construction.
Market Restraints
- Cross-border data transfer friction:EU GDPR adequacy decisions and China's MEE localization rules fragment infrastructure placement, raising compliance architecture costs.
- Specialized silicon supply concentration:AI training workloads depend on advanced GPU availability concentrated among single-source foundry capacity in Taiwan.
- Energy input cost volatility:Data center power purchase agreements face repricing pressure from grid instability and renewable intermittency in key markets.
Strategic Opportunities
- India's digital public infrastructure:UIDAI and UPI stack expansion creates demand for sovereign cloud capacity among domestic and foreign providers.
- Healthcare data interoperability:FDA 21 CFR Part 11 and HIPAA aligned cloud environments open regulated hosting for medical device telemetry and clinical trial platforms.
- Carbon-aware compute scheduling:EU Green Deal emissions reporting requirements reward workload migration to renewable-powered facilities with transparent metering.
Industry Challenges
- Multi-cloud orchestration expertise scarcity:Kubernetes and Terraform proficiency gaps constrain enterprise migration velocity and operational reliability.
- Legacy mainframe integration complexity:Financial services core banking systems require specialized middleware to connect with modern API-native cloud services.
- Incident response certification timelines:SOC 2 Type II and ISO 27001 audit cycles extend sales cycles for regulated industry deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Computing Market |
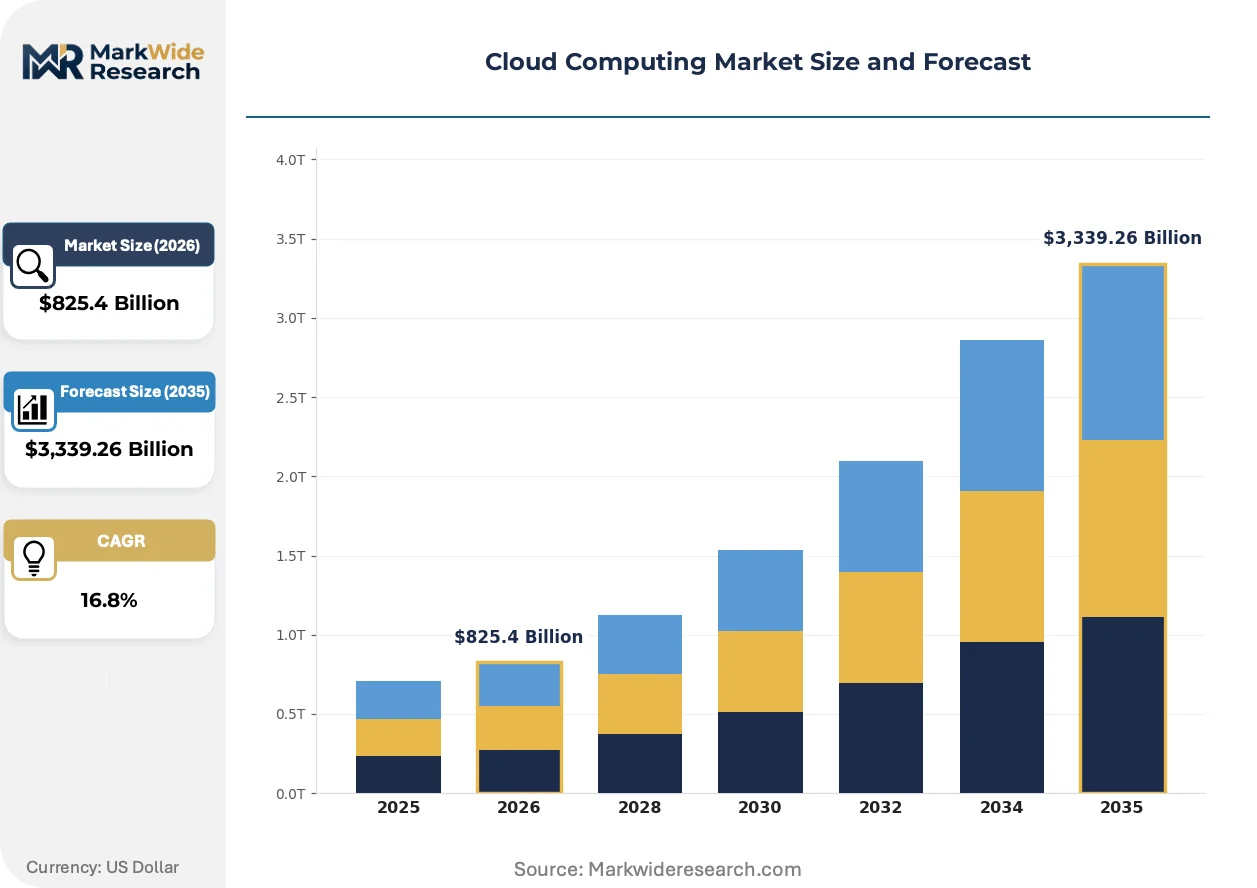
| Market Size in 2026 | $825.4 Billion |
| Market Size in 2035 | $3,339.26 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Model: IaaS, PaaS, SaaS, FaaS End User: Enterprise, SMEs, Government, Education Application: Data Backup, Disaster Recovery, Software Development, Big Data Analytics |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Oracle Cloud, Alibaba Cloud, IBM Cloud, Salesforce, DigitalOcean, Rackspace Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Computing Market Strategic Shifts & Innovations
Compute deployment models are fragmenting across edge, regional, and centralized tiers as latency requirements diverge by workload type. This spatial redistribution is forcing architectural decisions that prioritize proximity over pure economies of scale.
Container orchestration is hybridizing virtual machine and bare-metal execution environments into unified control planes. Manufacturing and logistics enterprises are adopting these converged stacks to run predictive maintenance and inventory optimization workloads on factory floors. The technology is hybridizing previously separate operational technology and information technology infrastructure domains, collapsing procurement silos and vendor consolidation timelines.
The SEC's cybersecurity disclosure rules for publicly traded companies mandate material incident reporting within four business days. This regulatory compression is forcing cloud providers to build transparent logging and automated breach detection into standard service agreements. Healthcare and financial services verticals are responding fastest, baking audit rights and forensic cooperation clauses into enterprise contracts.
Consumption-based billing granularity is reshaping how enterprises commit to capacity. Reserved instance purchasing is giving way to automated savings plan optimization and spot market arbitrage. Software vendors and managed service providers are the primary adopters, using programmatic commitment management to reduce effective compute costs by double-digit percentages. This pattern is most visible in North American and European markets where FinOps tooling maturity exceeds Asia-Pacific adoption curves.
Cloud Computing Market Segmentation
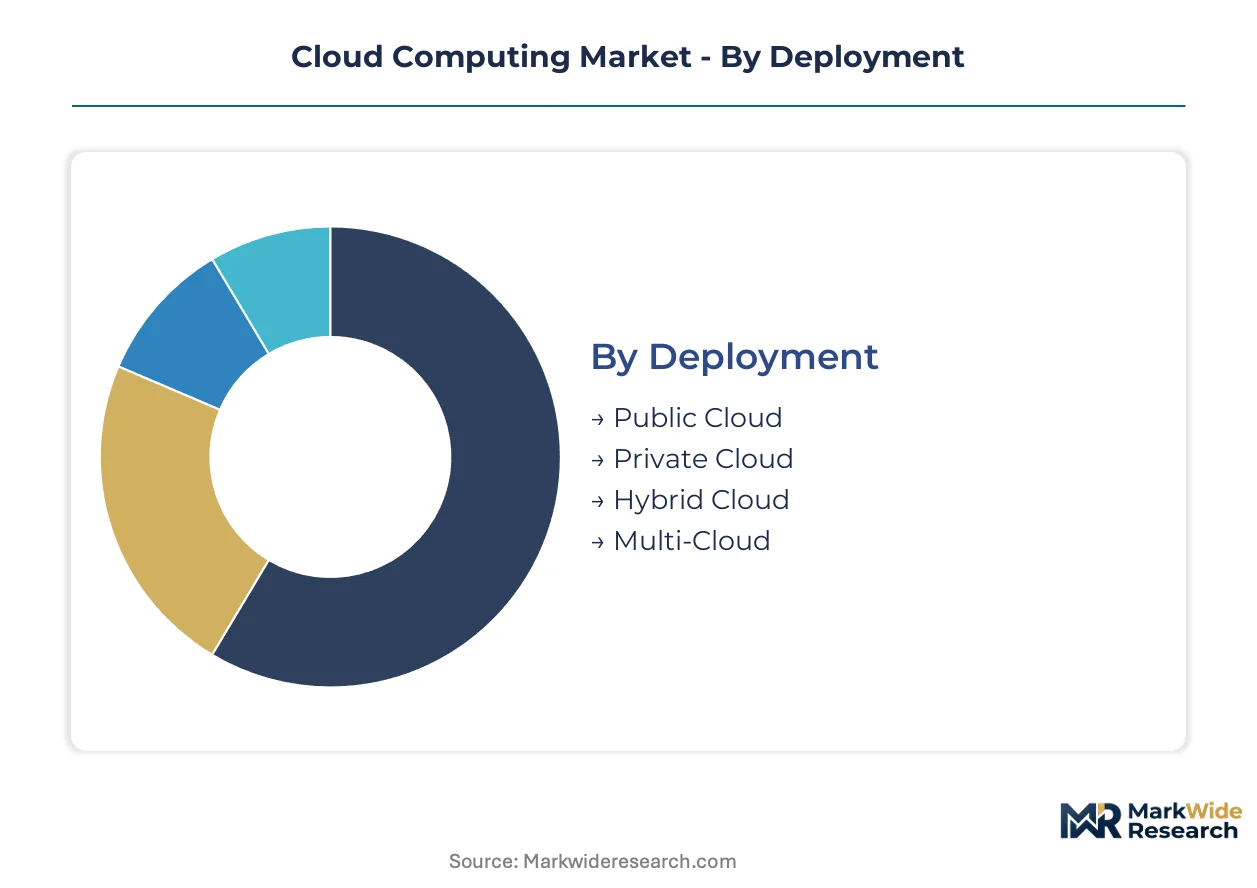
Cloud computing segmentation reveals how procurement patterns diverge across technical architectures, commercial models, and organizational sophistication. Understanding these fault lines exposes where margin pools concentrate and which deployment trajectories warrant strategic investment.
Deployment:
Mature provisioning models coexist with emerging orchestration approaches across enterprise infrastructure strategies.
- Public Cloud:Third-party providers deliver compute, storage, and networking resources over the internet through shared infrastructure. Financial services institutions in the United States concentrate demand here for elastic capacity during trading volatility, though EU GDPR adequacy decisions constrain cross-border workload placement.
- Private Cloud:Dedicated infrastructure serves single-tenant environments with enhanced control over security configurations and compliance boundaries. Healthcare providers deploying FDA 21 CFR Part 11 aligned systems favor this model for patient data sovereignty.
- Hybrid Cloud:Unified management planes orchestrate workloads across on-premises and off-premises environments. Manufacturing enterprises adopt this architecture to keep predictive maintenance data local while bursting analytics to regional facilities.
- Multi-Cloud:Deliberate distribution of applications across two or more public providers reduces vendor lock-in and optimizes service-specific capabilities. Enterprises with sophisticated FinOps tooling leverage this approach for spot market arbitrage.
Public Cloud retains volume leadership; Multi-Cloud holds the steepest expansion curve.
Service Model:
Abstraction layers determine how deeply providers embed into customer value chains and procurement budgets.
- IaaS:Fundamental compute, storage, and networking resources delivered as virtualized infrastructure. Hyperscale operators serving United States federal contracts dominate this tier through accredited facility construction.
- PaaS:Development and deployment environments abstracting underlying infrastructure management. Software vendors building containerized applications drive demand for Kubernetes-native orchestration capabilities.
- SaaS:Fully managed applications accessible via subscription without local installation or maintenance. This layer commands the deepest margin pools due to high customer lifetime value and minimal incremental delivery costs.
- FaaS:Event-driven execution models where code runs in response to triggers without persistent server management. Real-time transaction processing workloads in capital markets infrastructure exploit this for sub-100 millisecond latency.
SaaS captures the widest margin expansion; FaaS is climbing the fastest as serverless architectures mature.
End User:
Organizational scale and regulatory exposure shape procurement sophistication and contract complexity.
- Enterprise:Large organizations with dedicated IT procurement functions and multi-year cloud transformation programs. These buyers negotiate enterprise discount programs and demand SOC 2 Type II attestation.
- SMEs:Mid-sized businesses prioritizing rapid deployment over customization, typically consuming standardized SaaS offerings through self-service portals.
- Government:Public sector entities requiring cleared facilities, FedRAMP authorization, or equivalent national accreditation. United States federal procurement concentration accelerates investment in compliant data center construction.
- Education:Academic institutions leveraging cloud for research computing and administrative systems, often through consortium purchasing arrangements.
Enterprise dominates absolute spend; Government is gaining share fastest through digital modernization mandates.
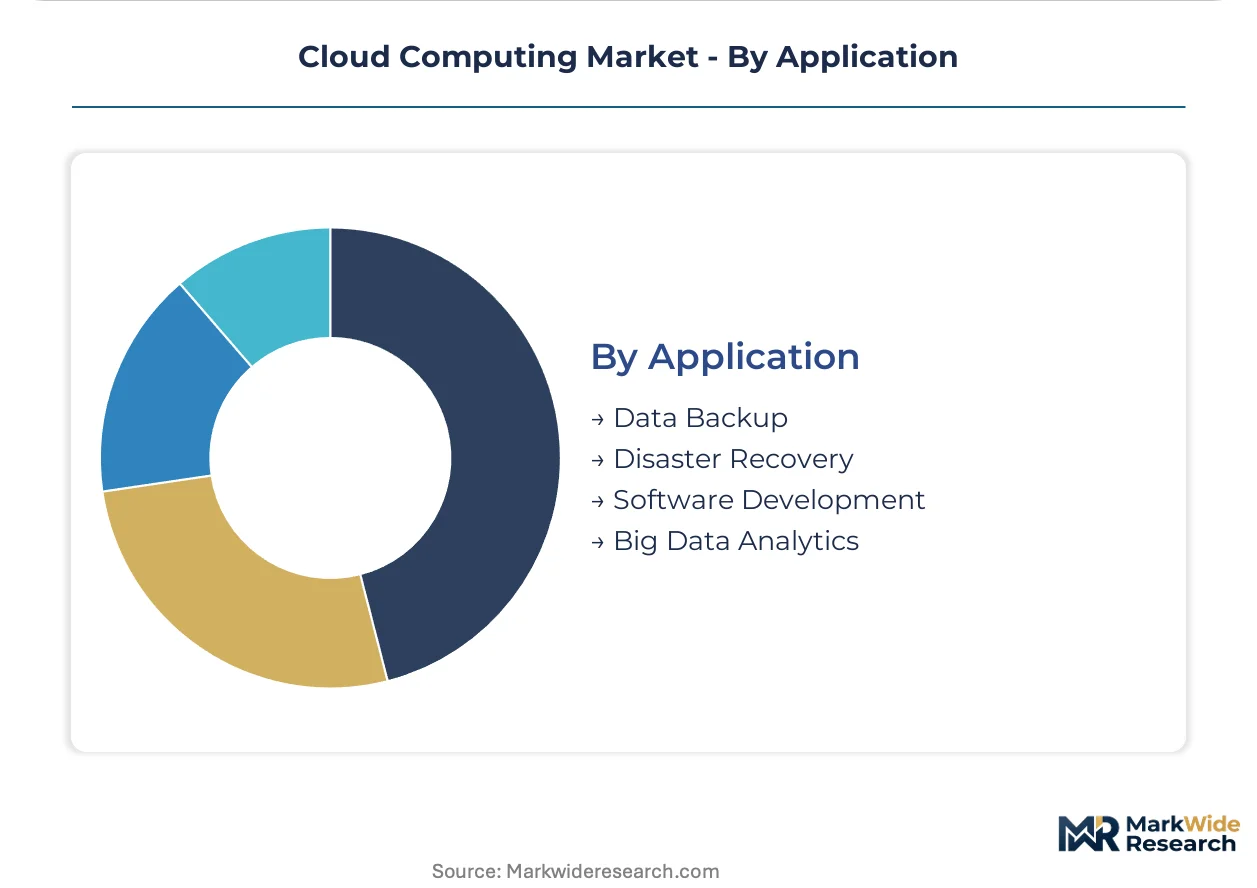
Application:
Workload characteristics dictate latency thresholds, compliance boundaries, and architectural requirements.
- Data Backup:Scheduled replication of critical information to geographically distributed storage tiers. Ransomware resilience requirements drive demand for immutable backup configurations.
- Disaster Recovery:Automated failover systems maintaining business continuity during infrastructure outages. Financial institutions subject to SEC cybersecurity disclosure rules prioritize four-day recovery objectives.
- Software Development:Continuous integration and delivery pipelines enabling rapid application iteration. Container orchestration platforms support dev-test-prod environment parity.
- Big Data Analytics:Distributed processing frameworks extracting insights from petabyte-scale datasets. Carbon-aware compute scheduling migrates these workloads to renewable-powered facilities for EU Green Deal compliance.
Data Backup sustains the largest installed base; Big Data Analytics shows the steepest growth trajectory as AI training workloads expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial surplus in cloud services trade, exporting infrastructure-as-a-service to European and Asian enterprises while importing specialized compliance consulting from London and Singapore. This asymmetry shapes where hyperscale operators concentrate capital deployment.
United States
Federal procurement concentration drives hyperscale data center construction across Virginia, Texas, and Oregon. FedRAMP authorization requirements filter which providers compete for Department of Defense and civilian agency contracts. Northern Virginia's Data Center Alley hosts the densest concentration of accredited facilities worldwide, with operators expanding into secondary markets like Columbus and Phoenix.
Germany
Industrial manufacturing demand for predictive maintenance workloads anchors private cloud investment in Bavaria and Baden-Württemberg. The EU AI Act's automated decision-making mandates force financial services firms in Frankfurt to upgrade hosting environments for auditability. Berlin's startup ecosystem consumes substantial SaaS capacity, though GDPR adequacy decisions constrain cross-border data flows with US providers.
China
Domestic cloud adoption accelerates for e-commerce and fintech applications, though MEE data localization rules require foreign providers to partner with local licensees. The Yangtze River Delta around Shanghai concentrates demand from semiconductor and automotive manufacturers deploying edge computing for quality control. Beijing's regulatory tightening on algorithmic recommendation systems adds compliance layers for hosted AI services.
India
UIDAI and UPI stack expansion generates sovereign cloud demand from domestic banks and payment processors. RBI guidelines on data localization for financial services push foreign providers to build Mumbai and Hyderabad facilities. Karnataka's Bangalore cluster attracts engineering talent for cloud-native application development, with operators competing for enterprise contracts in the IT services sector.
United Kingdom
London's financial services sector demands sub-50 millisecond latency for high-frequency trading infrastructure. FCA operational resilience rules mandate multi-region failover capabilities for critical banking systems. The Thames Valley corridor hosts secondary data center development as operators seek alternatives to primary London capacity constraints and energy costs.
Cloud Computing Market Key Industry Players
On the supply side, the industry is consolidated among three hyperscale operators controlling infrastructure economics, with a long tail of specialized providers occupying niche positions. Tier-one players compete through integrated platform ecosystems spanning compute, storage, and machine learning services. Tier-two regional specialists differentiate through data sovereignty guarantees and industry-specific compliance certifications. Dominant competitive moves include vertical integration into custom silicon design and strategic partnerships with enterprise software vendors to embed cloud consumption into existing procurement relationships.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and Google Cloud occupy positions defined by ecosystem breadth and enterprise sales reach. Amazon Web Services exemplifies the platform-orchestration archetype through Lambda serverless and adjacent service density. Microsoft Azure represents the enterprise-integration archetype, leveraging existing productivity software relationships to anchor cloud commitments. Google Cloud sits within the data-analytics-specialist archetype, differentiating through Kubernetes-native infrastructure and AI research translation. These three entities collectively set pricing benchmarks and capacity investment cycles that regional competitors must navigate.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Oracle Cloud |
| Alibaba Cloud |
| IBM Cloud |
| Salesforce |
| DigitalOcean |
| Rackspace Technology |
| Others |
Cost & Logistics Intelligence
Trans-Pacific fiber-optic cable routes carry the majority of cross-border data traffic between Asia and North America, with per-bit transport costs shaping how hyperscale operators price compute capacity across regional zones. This logistics corridor's cost dynamics concentrate pricing power among operators with owned submarine infrastructure while forcing tier-two providers into spot-market bandwidth arbitrage that compresses margins on standard compute tiers.
Pricing Analysis
Current-generation GPU instances command substantial premiums over prior-generation CPU-only workloads, while next-generation quantum-ready infrastructure remains pre-commercial with placeholder pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by latency SLA and compliance certification tier, with FedRAMP-authorized environments capturing the widest spreads. Cost compression in standard compute is intensifying because hyperscale operators are absorbing energy price volatility into flat-rate commitments. SMEs exhibit the highest price sensitivity and gravitate toward automated savings plan optimization, while government buyers prioritize audit-ready environments with minimal incremental cost scrutiny.
Supply Chain Analysis
US Commerce Department export controls on advanced AI accelerators limit foundry-to-cloud flow of restricted silicon into Chinese facilities, fragmenting procurement channels. Taiwan, South Korea, and the United States concentrate advanced semiconductor fabrication capacity that feeds cloud infrastructure deployment. Supply chains draw from specialized silicon wafers, high-bandwidth memory modules, and precision cooling systems as critical inputs. Single-source vulnerability around Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through direct hyperscale procurement relationships with tier-one foundries, bypassing traditional component distributors for AI training clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from sovereign cloud deployments and edge-native application architectures that bypass centralized hyperscale consumption. Defense requires pre-emptive moves before these alternatives capture regulated workload share.
For Market Incumbents: Pre-empt sovereign cloud substitution by securing national data localization certifications ahead of regulatory mandates in India and Southeast Asia. Build cleared facility capacity for United States federal contracts before procurement consolidation hardens vendor lists. Accelerate in-house production of custom inference chips to reduce dependency on external foundry allocation cycles. For New Entrants and Emerging Players: Mid-market manufacturing enterprises in Germany's industrial corridor represent the most penetrable entry point for private cloud specialists with predictive maintenance expertise. India's UIDAI-integrated sovereign cloud segment offers second-mover opportunity as foreign providers build Mumbai facilities for RBI compliance. Lead with FinOps tooling and automated commitment management as the primary go-to-market wedge against hyperscale direct sales. For Investors and Strategic Acquirers: Container orchestration specialists with Kubernetes-native security certifications offer the strongest acquisition target archetype for platform consolidation plays. Long-term viability hinges on whether edge computing fragmentation or hyperscale concentration wins the architectural debate for latency-sensitive workloads. Monitor hyperscale capital expenditure guidance revisions as the primary inflection signal for infrastructure demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Development | In-house AI accelerator production reduces foundry dependency and secures allocation priority during supply crunches. |
| Sovereign Cloud Certification | National data localization accreditation opens procurement channels for government and regulated financial services workloads. |
| FinOps Platform Integration | Automated commitment management tools capture SME demand for cost optimization without direct hyperscale negotiation. |
| Edge Computing Partnership | Factory-floor orchestration alliances with manufacturing OEMs collapse operational technology procurement silos. |
| FedRAMP Authorization Acceleration | Cleared facility status qualifies providers for United States federal consolidation contracts with multi-year visibility. |
Research Approach
A standing panel of cloud infrastructure procurement officers, platform engineering directors, regulatory compliance leads, and FinOps tooling specialists provided ongoing calibration throughout the study. Primary interview data combined with secondary validation from SEC hyperscaler capex disclosures, EU regulatory filings, and national data localization guidance documents. Bottom-up deployment forecasts triangulated against top-down IT spending surveys across enterprise, government, and education verticals.
Scenario-bracketing framed the analytical approach across the analysis window, with high-growth and conservative tracks reflecting divergent AI adoption curves and regulatory enforcement intensity. Segmentation dimensions modeled include deployment architecture, service model abstraction layer, organization scale tier, and regional compliance cluster. CAGRs derived from fitted growth curves incorporating capital expenditure trajectories, energy cost projections, and workload migration velocity indicators from container orchestration telemetry.
Practitioners should monitor export control expansion, sovereign cloud procurement mandate announcements, and hyperscale facility construction permitting delays for early signals of forecast deviation. Forecasts reflect assumptions about sustained AI training demand growth and stable cross-border data transfer adequacy frameworks. Material shifts in foundry capacity allocation rules or national data localization enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Web Service Cloud Market
Cloud Computing
Global Cloud Business Email Market
Cloud Computing
Global Cloud Computing Iaas in Life Science Market
Cloud Computing
Global Personal Cloud Market
Cloud Computing
Brazil Cloud Computing Market
Cloud Computing
UK Cloud Computing Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market
Cloud Computing
Hyperscale Cloud Market
Cloud Computing
China Cloud Computing Market
Cloud Computing
Japan Cloud Computing Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Public Cloud Application Infrastructure Services Market
Cloud Computing
North America Mobile Cloud Market
Cloud Computing
Cloud and Data Center Transformation Market
Cloud Computing
Cloud CDN Market
Cloud Computing
France Cloud Computing Market