
 Germany Cloud Computing Market | 2026-2036
Germany Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Cloud Computing Market Insights
The EU Green Deal is recalibrating energy efficiency mandates for data center operators across Germany, pushing workload migration toward carbon-neutral cloud zones. Microsoft Azure leverages its Frankfurt and Berlin region expansions to sustain leadership in enterprise SaaS workloads. SAP SE anchors its competitive position through deep integration between SAP HANA Cloud and on-premise ERP estates. Deutsche Telekom (T-Systems) differentiates via sovereign cloud offerings that satisfy domestic data residency requirements for public sector buyers.
Cloud computing encompasses the on-demand delivery of IT resources—compute, storage, databases, networking, and software—over the internet with metered, pay-as-you-go pricing and elastic scalability. In Germany, this model serves industrial automation, financial services, and healthcare by enabling real-time analytics, remote collaboration, and disaster recovery without capital-intensive infrastructure ownership. Infrastructure as a Service dominates spending as manufacturers provision virtualized environments for shop-floor IoT data processing. Hybrid Cloud deployments expand fastest among large enterprises seeking to balance legacy system retention with public cloud agility. Software as a Service captures concentrated margin pools in vertical applications for compliance, HR, and supply chain management.
The German Federal Office for Information Security (BSI) enforces baseline protection standards that shape procurement criteria across federal and state agencies. GDPR and the EU AI Act together constrain cross-border data flows and mandate algorithmic accountability for machine learning workloads deployed on German infrastructure. Stakeholders must monitor evolving BSI cloud certification requirements and assess whether multi-cloud architectures preserve operational flexibility without fragmenting compliance posture.
Market Dynamics
The EU AI Act and BSI cloud certification requirements are recalibrating procurement criteria across German federal agencies and industrial buyers, forcing infrastructure decisions toward sovereign and hybrid architectures that satisfy algorithmic transparency mandates.
Growth Catalysts
- GDPR data residency enforcement:Cross-border data flow restrictions push financial services and healthcare providers toward domestic cloud zones with certified local infrastructure.
- Baden-Württemberg industrial corridor:Automotive and machinery clusters generate concentrated demand for private cloud deployments supporting shop-floor IoT analytics.
- Edge computing integration:Latency-sensitive manufacturing applications require distributed processing nodes that hybrid cloud architectures uniquely deliver.
Market Restraints
- Energy cost volatility:German electricity prices strain data center operator margins and constrain expansion of carbon-intensive server capacity.
- Hyperscaler supply concentration:Three US-based providers control over 60 percent of public cloud infrastructure, creating dependency risk for critical workloads.
- BSI certification timeline friction:Extended audit cycles delay go-live dates for public sector cloud migrations by 12-18 months.
Strategic Opportunities
- Saxony-Anhalt greenfield zones:Renewable energy surplus regions offer carbon-neutral hosting capacity for sustainability-conscious enterprise buyers.
- AI workload sovereignty:The EU AI Act creates certified infrastructure demand for machine learning training and inference within German jurisdiction.
- Cloud-native SAP S/4HANA migration:Mid-market manufacturers seek managed services to transition legacy ERP estates without internal platform expertise.
Industry Challenges
- Cloud architect talent scarcity:German enterprises compete for limited DevOps and platform engineering specialists capable of multi-cloud orchestration.
- Hybrid integration complexity:Legacy mainframe and on-premise ERP systems require custom middleware development for seamless public cloud connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Cloud Computing Market |
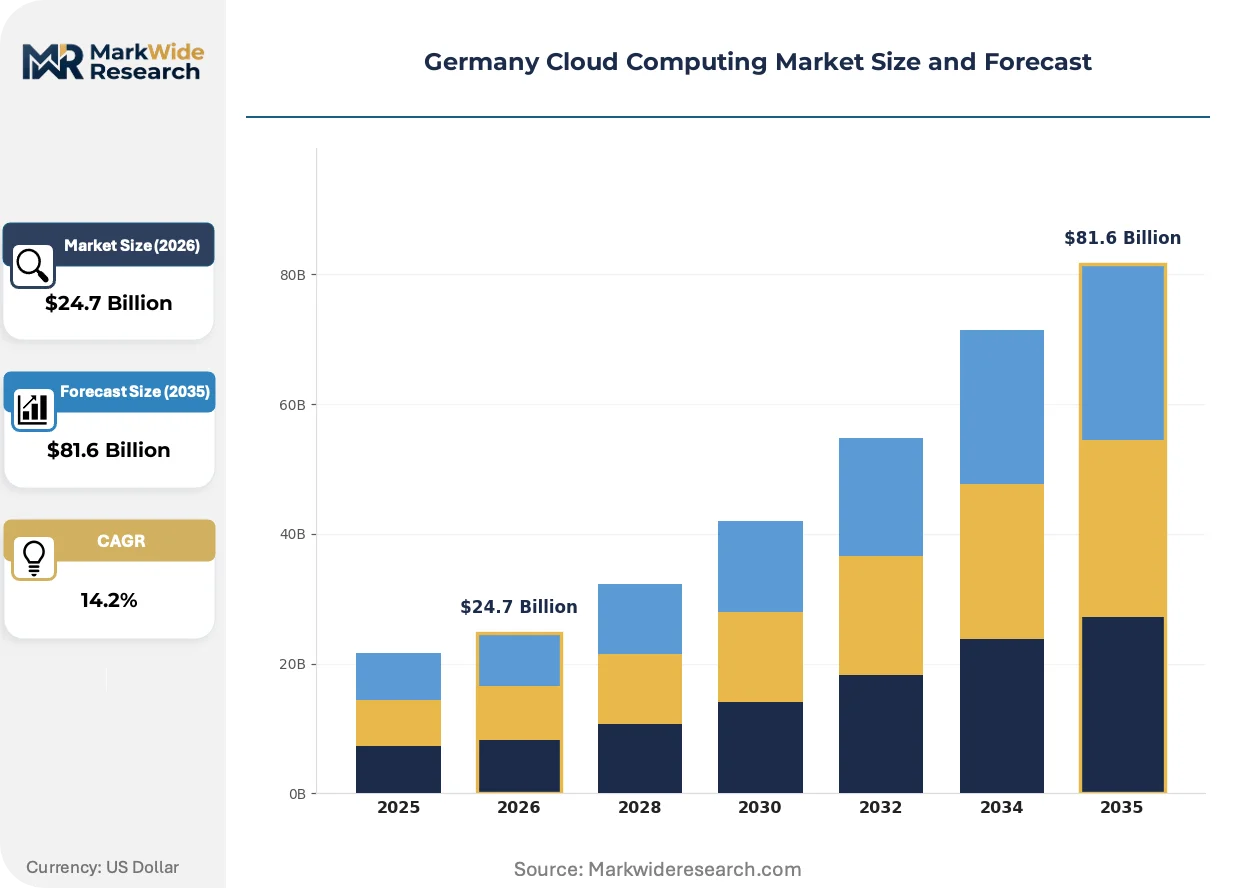
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $81.6 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Function as a Service End User: SMEs, Large Enterprises, Public Sector, Startups Solution: Backup & Disaster Recovery, Cloud Storage, Cloud Security, Cloud Monitoring |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, SAP SE, Deutsche Telekom (T-Systems), IBM Corporation, Oracle Corporation, 1&1 IONOS, Atos SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Cloud Computing Market Trends and Innovations
Generative AI deployment patterns and carbon accounting mandates are restructuring how German enterprises evaluate cloud provider selection, with sovereignty and sustainability metrics displacing pure cost-per-compute comparisons.
Confidential computing using hardware-based trusted execution environments is converging with regulated industry demand for data-in-use protection. Pharmaceutical and automotive manufacturers in Bavaria and Baden-Württemberg are piloting these enclaves for multi-party AI training on sensitive proprietary datasets. This convergence is compressing the acceptable security perimeter from network boundaries down to individual processor memory spaces.
The EU Green Deal's delegated act on data center energy efficiency entered force in 2024, mandating power usage effectiveness reporting and waste heat recovery planning for facilities above 500kW capacity. German operators in Frankfurt and Berlin regions now face binding carbon intensity ceilings that disqualify conventional diesel backup systems. Hyperscale providers are responding with liquid cooling deployments and power purchase agreements tied to hourly renewable matching.
Consumption-based pricing models are displacing reserved instance commitments among mid-market manufacturing buyers. Procurement teams in North Rhine-Westphalia's industrial belt now evaluate cloud spend against actual production throughput rather than capacity headroom, with FinOps tooling adoption accelerating to attribute infrastructure costs to specific product lines. This behavioral shift is most visible among automotive suppliers managing volatile OEM order cycles.
Germany Cloud Computing Market Segmentation
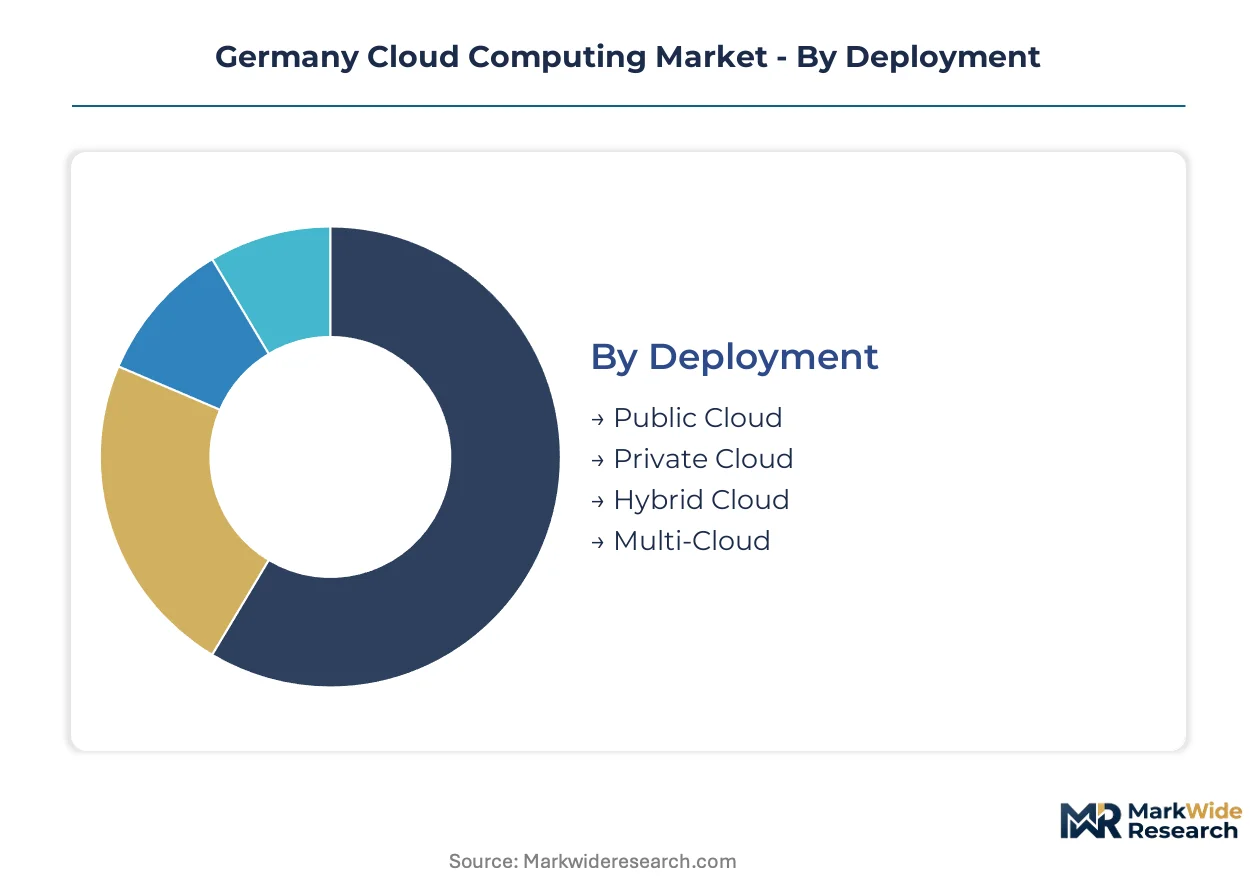
German cloud procurement decisions hinge on data sovereignty mandates, legacy system constraints, and sector-specific compliance loads. Deployment architecture and service tier selection vary sharply across industrial automation, financial services, and public sector buyers with divergent risk tolerances.
Deployment:
Cost tier determines infrastructure ownership depth for German buyers balancing capital efficiency against control requirements.
- Public Cloud:Third-party operated infrastructure delivers elastic compute and storage via shared tenancy. Demand concentrates among North Rhine-Westphalia's mid-market manufacturers seeking variable cost structures for volatile OEM order cycles without facility ownership.
- Private Cloud:Dedicated single-tenant environments provisioned on-premise or via hosted facilities. Baden-Württemberg's automotive and machinery clusters drive spending here, with GDPR data residency enforcement and shop-floor IoT latency requirements mandating localized processing nodes.
- Hybrid Cloud:Orchestrated workload distribution across private and public domains. Bavarian pharmaceutical manufacturers pilot these architectures for confidential computing enclaves protecting proprietary AI training datasets.
- Multi-Cloud:Deliberate distribution across competing provider platforms to mitigate vendor lock-in. Large enterprises in Hesse's financial corridor deploy this strategy to preserve negotiation leverage and satisfy BSI certification diversification requirements.
Public Cloud leads on scale; Hybrid Cloud leads on momentum.
Service Type:
Application criticality shapes service tier selection, with core systems anchoring on managed infrastructure and peripheral functions migrating to higher abstraction layers.
- Infrastructure as a Service:Virtualized compute, storage, and networking resources delivered via API-driven provisioning. Manufacturing buyers across Saxony's industrial belt favor IaaS for shop-floor IoT data lakes requiring customizable kernel-level configurations.
- Platform as a Service:Managed runtime environments abstracting infrastructure management from application deployment. Berlin's startup ecosystem leverages PaaS for rapid prototyping without platform engineering headcount.
- Software as a Service:Fully managed application delivery eliminating operational burden. HR and compliance software demand concentrates among Mittelstand enterprises seeking predictable per-seat pricing without upgrade cycles.
- Function as a Service:Event-driven compute executing discrete code units without persistent server management. Automotive suppliers pilot FaaS for connected vehicle telemetry processing during traffic spike events.
IaaS dominates current spending; FaaS exhibits steepest expansion trajectory among latency-sensitive workloads.
End User:
Customer type dictates procurement process complexity, with public sector buyers facing extended BSI certification timelines absent in commercial segments.
- SMEs:Mid-sized enterprises with constrained IT staffing and capital budgets. Consumption-based pricing adoption is accelerating here as FinOps tooling enables cost attribution to specific product lines.
- Large Enterprises:Complex organizations with heterogeneous legacy estates. SAP S/4HANA migration demand concentrates among this cohort, with managed service providers capturing margin from skills-scarce internal teams.
- Public Sector:Federal and state agencies bound by BSI baseline protection standards. Extended audit cycles delay cloud migrations by 12-18 months, compressing addressable near-term revenue.
- Startups:Venture-backed and bootstrapped entities prioritizing speed over customization. Cloud-native architecture adoption is near-universal, with minimal on-premise baggage enabling direct serverless deployment.
Large Enterprises anchor revenue concentration; Startups gain share fastest in AI-native application development.
Solution:
Maturity curves diverge across solution categories, with storage commoditization compressing margins while security specialization sustains pricing power.
- Backup & Disaster Recovery:Automated replication and restoration services ensuring business continuity. Financial services buyers in Frankfurt's banking cluster mandate geographically distributed recovery sites satisfying regulatory resilience requirements.
- Cloud Storage:Object, block, and file storage services with tiered durability guarantees. Archive and cold storage demand is climbing among healthcare providers managing multi-decade imaging retention obligations.
- Cloud Security:Identity management, encryption, and threat detection delivered as managed services. EU AI Act algorithmic transparency mandates are expanding this category's scope to include ML pipeline governance tooling.
- Cloud Monitoring:Observability platforms tracking performance, cost, and compliance posture. FinOps integration is the primary selection criterion as manufacturing procurement teams attribute infrastructure spend to production throughput.
Cloud Storage leads on scale; Cloud Security leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cloud infrastructure traces its industrial lineage to Baden-Württemberg's automotive manufacturing heartland, where shop-floor digitization demands first drove private data center investment in the early 2010s.
Baden-Württemberg
Automotive and machinery clusters generate concentrated demand for private cloud deployments supporting shop-floor IoT analytics. The BSI enforces baseline protection standards that shape procurement criteria for industrial buyers. Stuttgart's manufacturing corridor hosts confidential computing pilots protecting proprietary AI training datasets for multi-party collaborations.
North Rhine-Westphalia
Mid-market manufacturers seek consumption-based pricing structures for volatile OEM order cycles. GDPR data residency enforcement pushes financial services providers toward domestic cloud zones with certified local infrastructure. The Ruhr industrial belt's procurement teams evaluate cloud spend against actual production throughput using FinOps tooling.
Bavaria
Pharmaceutical manufacturers pilot hybrid architectures for latency-sensitive quality control applications. The EU AI Act mandates algorithmic accountability for machine learning workloads deployed on Bavarian infrastructure. Munich's life sciences cluster drives demand for hardware-based trusted execution environments securing multi-party data collaborations.
Hesse
Frankfurt's banking corridor anchors financial services cloud adoption with geographically distributed recovery sites satisfying regulatory resilience requirements. BSI certification diversification requirements push large enterprises toward multi-cloud strategies preserving negotiation leverage. The region's hyperscale facility expansions target carbon-neutral hosting capacity through renewable power purchase agreements.
Berlin-Brandenburg
Startup ecosystems leverage platform-as-a-service for rapid prototyping without platform engineering headcount. Extended BSI audit cycles delay public sector cloud migrations by 12-18 months, compressing near-term addressable revenue. The capital's AI-native application developers represent the fastest-growing customer segment for serverless deployment models.
Germany Cloud Computing Market Competitive Landscape
Capital-heavy infrastructure operators compete with asset-light platform orchestrators across deployment architecture decisions. The market structure concentrates around three US-based hyperscalers controlling public cloud infrastructure, with domestic providers carving defensive positions in sovereign and hybrid segments. Strategic archetypes separate into hyperscale platform operators, telecommunications-anchored sovereign specialists, and enterprise software-integrated managed service providers. Competitive moves center on renewable energy procurement for carbon-neutral zone expansion and confidential computing hardware deployment for regulated industry capture.
Among telecommunications-anchored providers, Deutsche Telekom (T-Systems) and 1&1 IONOS occupy positions exemplifying sovereign cloud differentiation through domestic data residency guarantees. SAP SE represents the enterprise software-integrated archetype, anchoring competitive positioning through deep connectivity between cloud-native platforms and legacy ERP estates. These three companies illustrate how German market participants defend share against hyperscale encroachment via compliance specialization and incumbent relationship leverage.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| SAP SE |
| Deutsche Telekom (T-Systems) |
| IBM Corporation |
| Oracle Corporation |
| 1&1 IONOS |
| Atos SE |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's carbon intensity ceilings gate access to premium-tier cloud capacity in Frankfurt and Berlin hyperscale zones, forcing workload migration toward renewable-powered facilities that command per-compute premiums over conventional diesel-backed alternatives.
Pricing Analysis
Consumption-based metered pricing dominates German cloud procurement, with three-tier pricing structure across premium, standard, and economy levels differentiated by carbon certification status and BSI compliance tier. Price differentiation stems from renewable energy matching granularity and confidential computing hardware availability. Cost compression in economy tiers is intensifying because mid-market manufacturers demand throughput-linked billing without reserved commitments. Mittelstand enterprises exhibit highest price sensitivity, while pharmaceutical manufacturers in Bavaria accept premium rates for sovereign data enclaves.
Supply Chain Analysis
Freight cost exposure concentrates in semiconductor and server hardware inbound flows from Taiwan, South Korea, and the USA, with liquid cooling component shortages amplifying lead time volatility for Frankfurt data center expansions. German cloud infrastructure draws from specialized chip fabrication, precision cooling systems, and renewable energy certificates as critical inputs. Single-source vulnerability in AI accelerator supply chains threatens confidential computing deployment timelines. Distribution runs through direct hyperscaler enterprise sales teams and telecommunications-anchored managed service partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German cloud computing represents a late-cycle quality story as EU AI Act compliance mandates shift procurement criteria toward certified sovereign infrastructure with embedded algorithmic transparency tooling.
For Market Incumbents: Anchor defensive positioning through backward integration into renewable energy procurement for carbon-neutral zone expansion. Invest in confidential computing hardware deployment to capture regulated industry demand from Baden-Württemberg automotive clusters. BSI certification timeline friction threatens revenue recognition delays.
For New Entrants and Emerging Players: Begin with white-space targeting of Saxony-Anhalt greenfield zones where renewable energy surplus enables cost-competitive carbon-neutral hosting. Mid-market SAP S/4HANA migration services offer the most penetrable segment given skills scarcity among incumbent systems integrators. Pursue FinOps tooling partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for sovereign cloud specialists because BSI certification barriers create defensive moats against hyperscale encroachment. Long-term viability favors providers with dual capabilities in domestic data residency guarantees and legacy ERP integration expertise. Monitor EU AI Act delegated act implementation as the signal to watch for certified infrastructure demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Deployment | Hardware-based enclaves satisfy Bavarian pharmaceutical multi-party AI training compliance requirements. |
| Renewable Energy Procurement | Hourly-matched power purchase agreements enable Frankfurt carbon-neutral zone premium pricing. |
| BSI Certification Investment | Extended audit cycle navigation compresses public sector cloud migration timelines for T-Systems. |
| FinOps Platform Integration | Cost attribution tooling captures North Rhine-Westphalia manufacturing procurement decision influence. |
| Sovereign Cloud Partnership | Domestic data residency guarantees differentiate against AWS Azure Google public cloud dominance. |
Research Methodology
Direct dialogue with cloud platform engineers, federal procurement officers, IT directors at automotive manufacturers, and hyperscaler enterprise sales leaders grounded qualitative insights. Secondary validation incorporated BSI certification documentation, EU AI Act regulatory filings, hyperscaler capex disclosures, and German federal IT procurement databases. Bottom-up service tier demand modeling and top-down infrastructure capacity analysis were triangulated against regional energy grid data.
Market size and growth trajectory outputs across the projection horizon reflect segmentation by deployment architecture, service abstraction layer, end-user organization scale, and vertical compliance intensity. CAGRs were derived from workload migration velocity assumptions tied to SAP S/4HANA transition timelines and EU AI Act implementation phases. Carbon accounting mandate stringency and confidential computing adoption curves served as industry-specific forecast inputs.
Caveats apply where energy cost volatility, BSI audit timeline extensions, or AI accelerator supply constraints could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Cloud Banking Solutions Market
Cloud Computing
GPU As a Service (Gpuaas) Market
Cloud Computing
ASEAN Cloud Computing Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
Cloud VPN Market
Cloud Computing
Cloud-Based Workload Scheduling Software Market
Cloud Computing
Public Cloud in BFSI Market
Cloud Computing
Global Grid Computing Market
Cloud Computing
Cloud Enterprise Content Management Market
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market
Cloud Computing
Cloud Integration Software Market
Cloud Computing
Cloud Computing Stack Layers Market
Cloud Computing
Global Cloud Computing in Healthcare Market
Cloud Computing
Japan Cloud Computing Market