
 United States Cloud Computing Market | 2026-2036
United States Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
United States Cloud Computing Market Insights
Market Context
Subscription-based software-defined networking is hardening into the primary revenue architecture for US cloud providers. Amazon Web Services leverages its hyperscale data center footprint to dominate federal and enterprise contracts. Microsoft Azure sustains deep integration with existing enterprise software stacks. Google Cloud specializes in AI-optimized compute instances for machine learning workloads.
Technical Definition and Segment Structure
United States cloud computing denotes the on-demand delivery of IT resources over networked infrastructure, encompassing virtualized compute, storage, and networking services with measured service provisioning and rapid elasticity. Its primary commercial purpose centers on replacing capital-intensive on-premises infrastructure with operational expenditure models that scale dynamically with workload demands. Public cloud deployment captures the dominant share of enterprise workloads, while hybrid cloud configurations are expanding fastest among regulated industries requiring data sovereignty controls. SaaS retains the largest revenue pool across service types, though IaaS generates superior margins for providers operating at hyperscale efficiency.
Regulatory Framework and Outlook
FedRAMP authorization requirements, HIPAA privacy safeguards, and SEC cybersecurity disclosure rules collectively shape procurement standards and vendor qualification pathways across federal, healthcare, and financial sectors. The FTC exercises expanding oversight of cloud provider market practices and data handling commitments. Stakeholders must monitor evolving state-level data privacy legislation and federal AI governance frameworks that will redefine compliance obligations for multi-tenant infrastructure operators.
Market Dynamics
FedRAMP authorization mandates are compressing vendor qualification timelines while redirecting federal procurement toward pre-certified hyperscale operators, consolidating contract awards among authorized providers.
Growth Catalysts
- GPU-Enabled Infrastructure Demand:Artificial intelligence integration into enterprise workflows is redirecting procurement toward specialized compute instances. Financial services clusters in Texas and North Carolina are expanding machine learning operations.
- FedRAMP Authorization Requirements:Federal agencies face procurement mandates favoring pre-certified cloud environments. This regulatory pressure accelerates migration timelines and disqualifies non-compliant vendors.
- Healthcare System Consolidation:Northeast hospital networks are unifying electronic health record systems on SaaS platforms. HIPAA privacy safeguards drive preference for compliant multi-tenant architectures.
Market Restraints
- Hyperscale Supply Concentration:Three operators control dominant shares of federal-eligible infrastructure. This geographic and vendor concentration creates single-source vulnerability for mission-critical workloads.
- Energy Input Cost Volatility:Data center power consumption exposes operators to regional electricity price fluctuations. Virginia and Texas grid constraints amplify operational expenditure uncertainty.
- Technical Talent Scarcity:Cloud security architecture and FedRAMP compliance expertise remains concentrated among limited specialist pools. Certification requirements extend hiring timelines.
Strategic Opportunities
- State-Level Privacy Legislation Divergence:California, Virginia, and Colorado have enacted distinct data protection frameworks. Multi-tenant operators can capture compliance-as-a-service revenue from enterprises navigating fragmented obligations.
- Edge Computing Convergence:5G network deployment and container orchestration are enabling distributed processing architectures. Manufacturing facilities in the Midwest are piloting low-latency industrial IoT applications.
- SEC Cybersecurity Disclosure Rules:Public companies must report material cloud security incidents. This mandate creates advisory and monitoring service opportunities for compliance-focused providers.
Industry Challenges
- Legacy System Integration Complexity:Mainframe-dependent financial institutions face multi-year migration timelines. Technical debt and interdependency mapping consume disproportionate implementation resources.
- FedRAMP Certification Timeline Compression:Authorization pathways require 12-18 month cycles. Smaller vendors lack capital reserves to sustain pre-revenue compliance investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Cloud Computing Market |
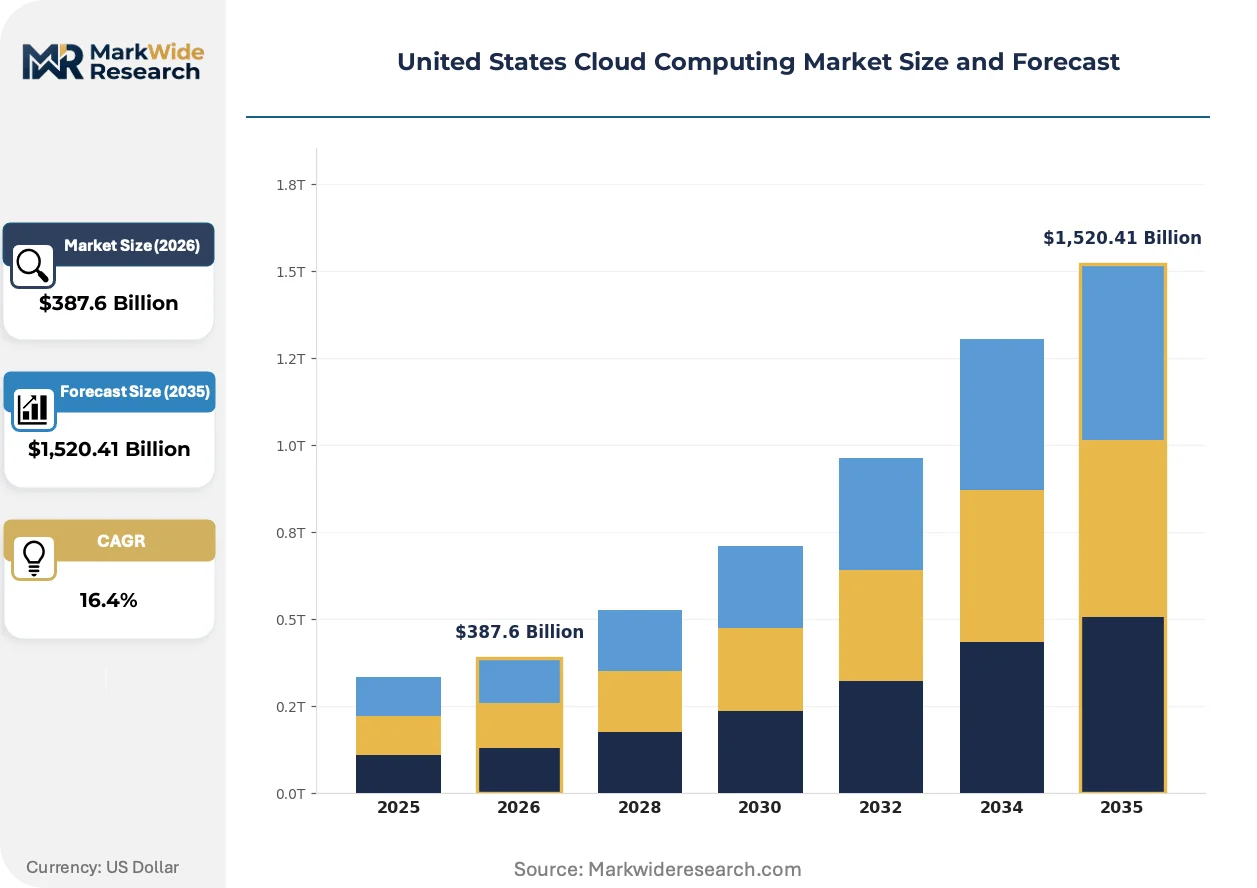
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,520.41 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, Backup & Recovery End User: Enterprise, SME, Government, Non-Profit Application: Data Storage, Disaster Recovery, Application Development, Testing |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM Corporation, Oracle Corporation, Salesforce, Adobe Inc., Rackspace Technology, DigitalOcean, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Cloud Computing Market Trends and Innovations
Generative AI deployment is forcing infrastructure architecture redesigns, with enterprise buyers prioritizing inference-optimized compute over general-purpose instances. This technical pivot is compressing hardware refresh cycles and redrawing competitive positioning among service tiers.
Inference-optimized silicon is automating workload placement decisions across distributed infrastructure. Healthcare systems in the Northeast are adopting these platforms to reduce latency for diagnostic imaging pipelines. The technology is compressing the gap between training and deployment environments, enabling real-time model updates without infrastructure reconfiguration.
FTC oversight of cloud provider market practices is expanding disclosure requirements for data handling commitments. This regulatory development is forcing contract renegotiations across financial services procurement. Institutions in North Carolina and Texas are demanding granular audit rights and breach notification clauses.
Consumption-based billing models are displacing reserved instance commitments among mid-market enterprises. Software vendors are unbundling storage from compute pricing to capture variable workload revenue. This pattern is most visible among SaaS providers serving professional services clusters in metropolitan Northeast corridors.
United States Cloud Computing Market Segmentation
Cloud computing procurement patterns diverge sharply across deployment architectures and organizational scale. Service type selection correlates directly with in-house technical capacity and compliance burden severity.
Deployment:
Upgrade cycles in enterprise infrastructure now pivot on container orchestration maturity and data sovereignty requirements rather than hardware depreciation schedules alone.
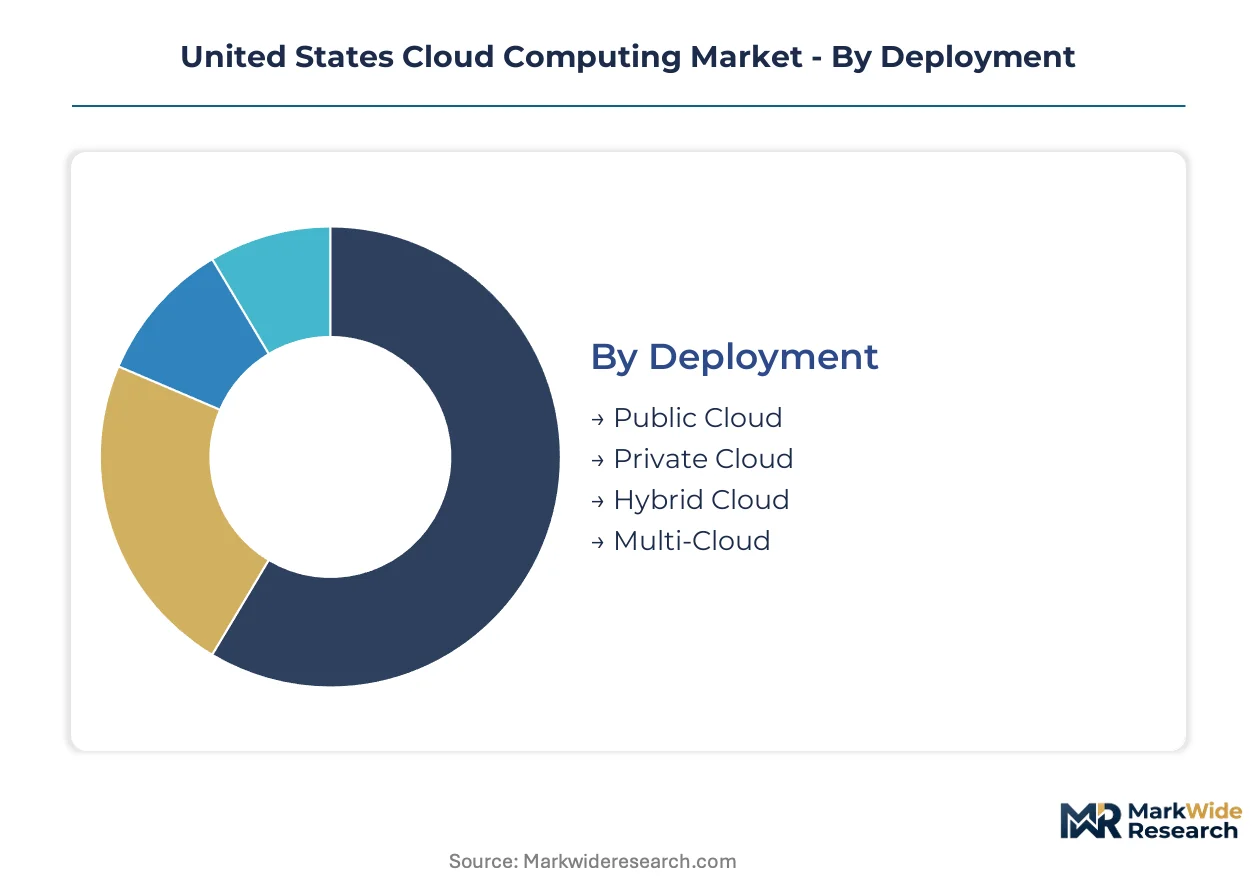
- Public Cloud:Shared infrastructure pools deliver compute, storage, and networking through multi-tenant architectures with metered consumption. Financial services clusters in Texas and North Carolina favor this model for machine learning workloads requiring elastic GPU access. FedRAMP authorization mandates compress vendor qualification timelines toward pre-certified hyperscale operators.
- Hybrid Cloud:Orchestrated workload placement spans on-premises infrastructure and public cloud resources through unified management planes. Healthcare systems in the Northeast deploy this architecture to maintain HIPAA-compliant data residency for electronic health records while bursting analytics to cloud. Technical debt in legacy integration constrains migration velocity.
- Private Cloud:Dedicated single-tenant infrastructure operates behind organizational firewalls with customized security controls. Federal agencies with classified workloads mandate this deployment for sensitive operational data.
- Multi-Cloud:Distributed workload placement across two or more independent cloud providers reduces single-source dependency. Mid-market enterprises adopt this pattern to negotiate favorable contract terms and avoid vendor lock-in.
Public Cloud sits at the top of the volume ranking, with Hybrid Cloud climbing the fastest.
Service Type:
Margin structures vary dramatically across service tiers, with infrastructure operations capturing superior economics at hyperscale efficiency while software layers face commoditization pressure.
- SaaS:Application software delivered through subscription models eliminates local installation and maintenance overhead. Professional services clusters in metropolitan Northeast corridors drive concentrated demand for productivity and collaboration platforms. Consumption-based billing models are displacing reserved instance commitments among mid-market buyers.
- IaaS:Virtualized compute, storage, and networking resources provisioned through APIs enable workload portability across hardware generations. GPU-enabled instances command premium pricing from financial services machine learning operations in Texas and North Carolina.
- PaaS:Managed runtime environments abstract infrastructure management from application deployment. Development teams in technology hubs leverage these platforms to accelerate release cycles without operational overhead.
- Backup & Recovery:Automated data protection services with geographic replication satisfy SEC cybersecurity disclosure requirements for incident recovery capabilities. Public companies in regulated sectors mandate these services for material system resilience.
SaaS commands the largest revenue pool, though IaaS gains share fastest among AI-optimized procurement.
End User:
Customer type determines contract structure complexity, with government procurement requiring specialized compliance pathways that disqualify non-certified vendors.
- Enterprise:Large organizations with dedicated cloud centers of excellence negotiate customized service level agreements and dedicated support tiers. These buyers drive demand for hybrid architectures bridging legacy mainframe dependencies.
- Government:Federal, state, and local agencies operate under FedRAMP authorization mandates that restrict procurement to pre-certified environments. Authorization pathways require sustained capital reserves that smaller vendors cannot sustain.
- SME:Mid-market organizations prioritize consumption-based billing and rapid deployment without specialized technical staff. These buyers favor SaaS platforms with minimal configuration requirements.
- Non-Profit:Mission-driven organizations with constrained IT budgets leverage cloud grant programs and discounted pricing tiers from major providers.
Enterprise accounts dominate contract value, with Government expanding most quickly under accelerated federal migration mandates.
Application:
Workload purpose shapes infrastructure specifications, with latency-sensitive applications demanding edge-adjacent deployment and archival storage tolerating higher latency for cost optimization.
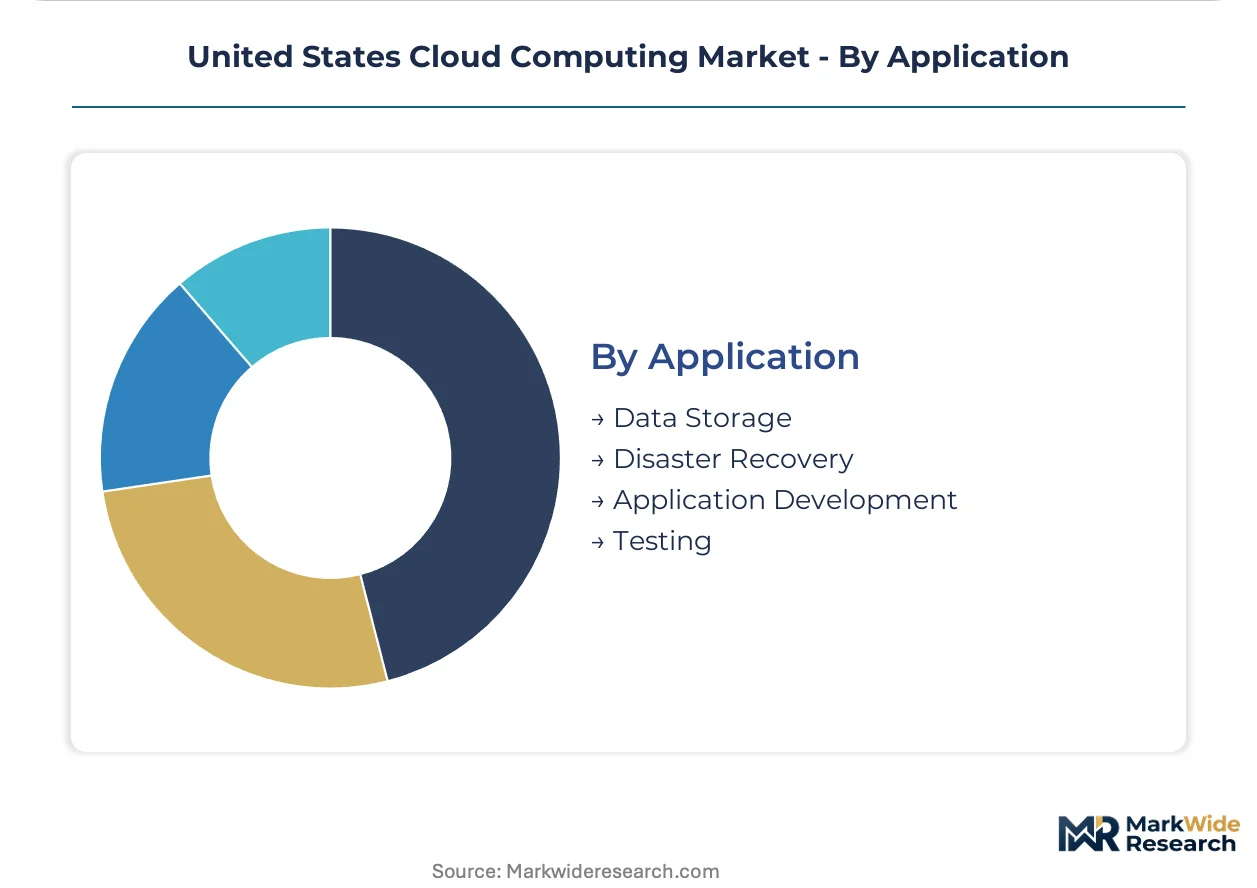
- Data Storage:Object, block, and file storage services with tiered durability guarantees replace capital-intensive on-premises storage area networks. Healthcare imaging archives in the Northeast drive petabyte-scale consumption.
- Application Development:Integrated development environments, CI/CD pipelines, and container registries accelerate software release velocity. Manufacturing facilities in the Midwest pilot low-latency industrial IoT applications through 5G-enabled edge convergence.
- Disaster Recovery:Automated failover and geographic replication services satisfy business continuity requirements with recovery time objectives measured in minutes. SEC disclosure rules mandate these capabilities for public companies.
- Testing:Ephemeral infrastructure provisioning enables parallel test execution without permanent capacity commitment. Development teams leverage spot pricing for cost-efficient quality assurance.
Data Storage leads by provisioned capacity, with Application Development showing steepest expansion trajectory as generative AI deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's cloud procurement lags the United States by approximately three years in federal authorization maturity, while Mexico's enterprise adoption concentrates in manufacturing corridor cities near the US border.
California
Silicon Valley hyperscale campuses anchor GPU-enabled infrastructure deployment for generative AI training workloads. The California Consumer Privacy Act (CCPA) imposes data handling obligations that exceed federal baselines, forcing contract renegotiations with multi-tenant providers. Los Angeles media and entertainment clusters drive petabyte-scale object storage consumption for content distribution pipelines.
Virginia
Northern Virginia's data center alley processes the highest concentration of federal cloud workloads outside direct government facilities. State-level tax incentives for renewable energy procurement shape operator site selection decisions. Loudoun County and Prince William County jurisdictions host the majority of East Coast hyperscale capacity expansion.
Texas
Dallas-Fort Worth and Austin metropolitan areas attract financial services machine learning operations requiring low-latency GPU access. ERCOT grid volatility exposes operators to electricity price fluctuations that compress margin structures. Houston energy sector enterprises deploy hybrid architectures to maintain operational data residency while bursting analytics to cloud.
New York
Manhattan financial services procurement mandates granular audit rights and breach notification clauses under state Department of Financial Services cybersecurity regulations. Healthcare systems across the Hudson Valley and Long Island consolidate electronic health records on HIPAA-compliant SaaS platforms. Buffalo and Syracuse manufacturing facilities pilot edge computing for industrial IoT quality control.
Washington
Seattle-area cloud engineering talent pools concentrate FedRAMP compliance expertise that extends hiring timelines for authorization pathway completion. State renewable portfolio standards accelerate data center clean energy procurement commitments. Spokane and eastern Washington jurisdictions attract secondary site deployment for geographic redundancy requirements.
United States Cloud Computing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale operators commanding federal-eligible infrastructure awards while regional hosting providers capture price-sensitive mid-market workloads. The vendor base concentrates among three dominant operators controlling authorized federal procurement pathways. Strategic archetypes include hyperscale platform operators, compliance-specialized managed services providers, and developer-focused infrastructure-as-a-service boutiques. Competitive dynamics center on authorization timeline acceleration and GPU-enabled instance portfolio expansion.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and Google Cloud occupy positions that exemplify divergent specialization vectors: AWS anchors federal and enterprise contract dominance through data center footprint scale, Azure represents enterprise software stack integration depth, and Google Cloud sits within the AI-optimized compute positioning for machine learning workloads.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM Corporation |
| Oracle Corporation |
| Salesforce |
| Adobe Inc. |
| Rackspace Technology |
| DigitalOcean |
| Others |
Pricing and Supply Chain Analysis
GPU-enabled infrastructure deployment is simultaneously compressing hardware refresh cycles and consolidating procurement power among hyperscale operators with captive silicon allocation agreements. This technical pivot reshapes cost economics for enterprise buyers while amplifying supplier concentration among three dominant cloud platforms.
Pricing Analysis
Capacity additions in Virginia and Texas are reshaping price floors for compute-intensive workloads. Three-tier pricing structure across premium GPU-enabled, standard general-purpose, and economy spot-instance levels stratifies buyer segments. Cost compression in standard compute tiers is intensifying because hyperscale efficiency gains outpace infrastructure depreciation. Mid-market enterprises exhibit highest price sensitivity, while federal agencies demonstrate lowest elasticity due to FedRAMP compliance requirements.
Supply Chain Analysis
Domestic-content mandates under federal procurement guidelines are reshaping data center equipment sourcing toward US-based server assembly and domestic renewable energy certificates. Taiwan, South Korea, and the United States anchor semiconductor supply for cloud infrastructure. Raw material dependencies center on advanced lithography equipment, high-bandwidth memory modules, and specialized cooling systems. Single-source vulnerability concentrates in GPU accelerator supply chains controlled by one dominant silicon designer. Distribution runs through direct enterprise sales teams and authorized federal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States cloud computing market functions as a stable compounder anchored by structural federal migration mandates that institutionalize procurement volume regardless of macroeconomic cycles.
For Market Incumbents: Anticipate margin compression in general-purpose compute tiers as hyperscale efficiency gains diffuse through competitive pricing. Defensive positioning requires accelerated FedRAMP authorization timeline compression to capture federal contract awards before smaller vendors achieve compliance. GPU-enabled instance portfolio expansion represents the critical lever for sustaining pricing power against commodity infrastructure erosion. For New Entrants and Emerging Players: The price-point gap between premium FedRAMP-authorized hyperscale offerings and economy-tier regional hosting creates white-space opportunity for compliance-specialized managed services providers. Healthcare systems in the Northeast present the most penetrable segment due to HIPAA complexity that disqualifies pure commodity operators. A vertical-specific compliance-as-a-service go-to-market angle enables differentiation without direct hyperscale infrastructure competition. For Investors and Strategic Acquirers: Valuations sit cheapest among regional hosting providers with established data center footprints but incomplete federal authorization pathways. Long-term viability across the analysis window hinges on successful navigation of AI infrastructure transition and regulatory compliance complexity. Acquisition targets should demonstrate existing healthcare or financial services vertical penetration with compliant architectures. The signal to watch is hyperscaler capex allocation shifts between general-purpose and AI-optimized infrastructure buildouts.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Pre-certified providers capture federal contract awards under accelerated migration mandates. |
| GPU-Enabled Infrastructure Expansion | AI-optimized compute instances command premium pricing from financial services machine learning operations. |
| Vertical-Specific Compliance Packaging | HIPAA and SEC-aligned service bundles capture healthcare and financial sector procurement. |
| Edge Computing Partnership Development | 5G-enabled distributed processing addresses manufacturing IoT latency requirements in Midwest corridors. |
| Consumption-Based Billing Migration | Variable workload pricing displaces reserved commitments among mid-market professional services clusters. |
Research Methodology
Bottom-up enterprise workload modeling reconciled against top-down hyperscale capex tracking forms the analytical core of this study. Primary interviews with federal procurement officers, healthcare IT directors, financial services cloud architects, and hyperscale platform engineers combined with secondary validation from SEC filings, hyperscaler infrastructure expenditure disclosures, and FedRAMP authorization databases. Triangulation across supply-side capacity announcements and demand-side contract awards ensures convergence between modeled and observed market dynamics.
Historical trendline analysis of infrastructure deployment patterns and service revenue trajectories established baseline growth parameters. Segmentation modeling spans deployment architecture, service type, organization scale, and vertical industry across the projection horizon. CAGRs derived from regression analysis of historical hyperscale revenue growth adjusted for AI infrastructure transition effects and federal procurement acceleration. Forecast inputs incorporate GPU supply constraints, electricity price volatility in key data center markets, and FedRAMP authorization pipeline velocity.
Caveats apply where semiconductor supply disruptions, state-level data privacy legislation divergence, or federal AI governance framework implementation could materially shift the outlook. Forecasts reflect assumptions regarding sustained federal migration mandates and hyperscale efficiency gains. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
Public Cloud Application Services Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
Cloud Services Market
Cloud Computing
Cloud CDN Market
Cloud Computing
Global Cloud Migration Market
Cloud Computing
Japan Cloud Computing Market
Cloud Computing
Cloud Management Platform Market
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
Hybrid Cloud in BFSI Market
Cloud Computing
Hyperscale Cloud Market
Cloud Computing
GPU Virtualization Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Public Cloud Application Infrastructure Services Market
Cloud Computing
Global Grid Computing Market
Cloud Computing
Global Cloud Collaboration Market