
 Virtual Private Cloud (VPC) Market | 2026-2036
Virtual Private Cloud (VPC) Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Private Cloud (VPC) Market Intelligence
Cloud platform engineering talent scarcity is redrawing competitive boundaries across the VPC landscape. Amazon Web Services sustains its market presence through backward integration into custom silicon and fiber infrastructure. Microsoft Azure differentiates via deep enterprise channel control and hybrid cloud interoperability. Google Cloud Platform navigates regulatory complexity by expanding sovereign cloud regions and local staffing.
A Virtual Private Cloud provisions logically isolated network segments within shared cloud infrastructure, typically defined by software-defined perimeters, dedicated IP addressing, and customizable routing tables that enforce tenant-level segregation. Its primary commercial purpose is to deliver public cloud elasticity while satisfying security, compliance, and governance requirements that prohibit multi-tenant exposure. Hybrid VPC deployments now lead enterprise uptake as organizations retain on-premises systems for latency-sensitive workloads while bursting to cloud capacity. Managed VPC services represent the fastest-expanding service type segment, capturing margin pools from enterprises lacking internal platform engineering depth. SMB adoption of VPN connectivity options is maturing as direct connection and transit gateway configurations gain favor among large enterprises requiring deterministic performance.
FCC data sovereignty guidelines, EU GDPR cross-border transfer mechanisms, and India's Digital Personal Data Protection Act collectively shape product architecture and market access requirements for VPC providers. The EU AI Act's risk classification framework is forcing providers to document infrastructure provenance and audit trails for AI training environments. Stakeholders must monitor evolving certification regimes across multiple jurisdictions to anticipate where compliance investments will concentrate.
Market Dynamics
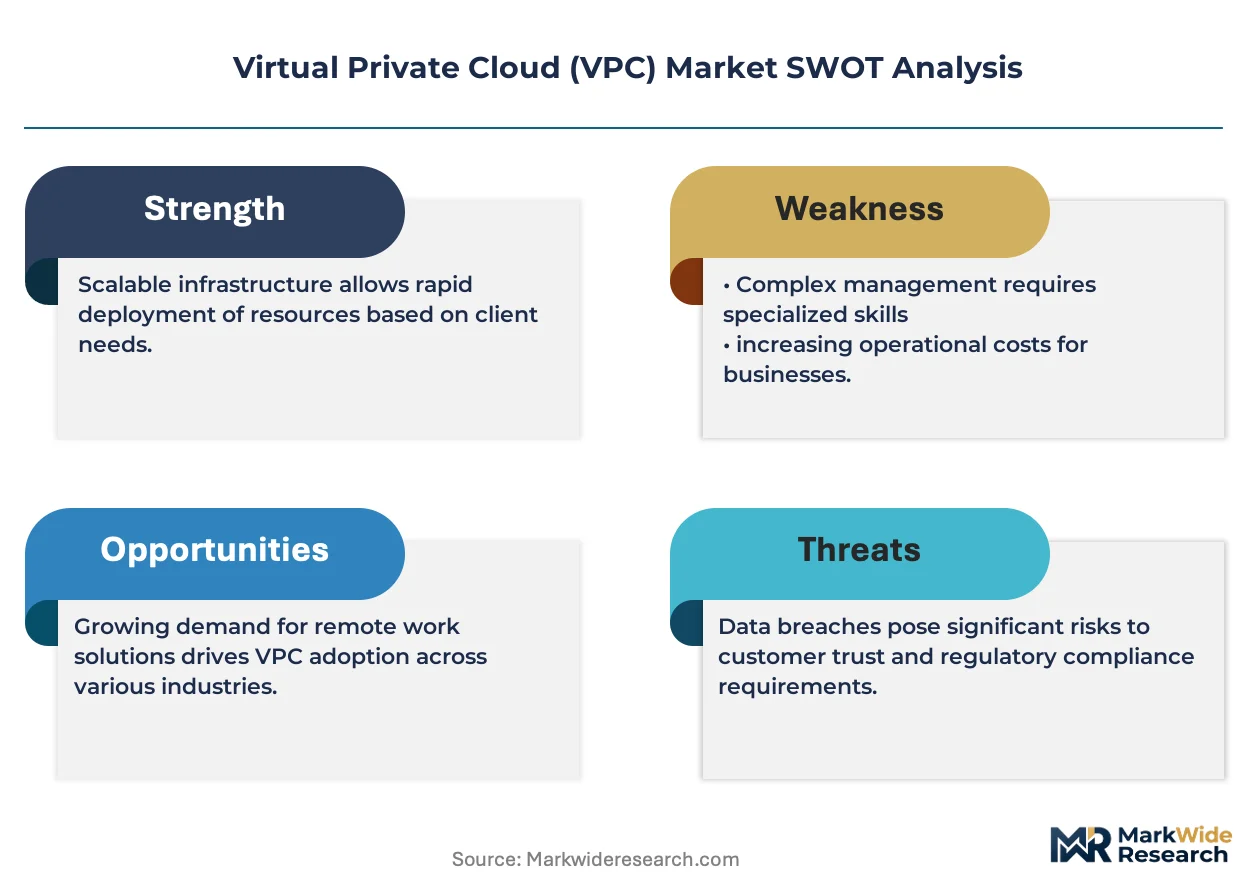
Platform engineering talent scarcity is compressing enterprise build-versus-buy decisions, forcing organizations toward managed VPC services while hyperscalers capture margin pools through vertical integration into custom silicon and sovereign cloud infrastructure.
Growth Catalysts
- GDPR cross-border transfer mechanisms:European financial services firms require logically isolated environments for AI training data, accelerating sovereign VPC deployments in Germany and France.
- Operational technology convergence:Industrial conglomerates in manufacturing and energy sectors demand VPC architectures that bridge IT/OT networks with deterministic latency guarantees.
- India's Digital Personal Data Protection Act:Data localization mandates are compelling multinational enterprises to establish in-country VPC regions with dedicated compute and storage infrastructure.
Market Restraints
- Custom silicon supply concentration:Hyperscaler dependence on Taiwan Semiconductor Manufacturing for AI-optimized networking chips creates infrastructure provisioning bottlenecks.
- Fiber backbone cost volatility:Submarine cable deployment costs and terrestrial dark fiber leasing rates fluctuate with raw copper and optical component pricing.
- EU AI Act documentation requirements:Infrastructure provenance audit trails for high-risk AI systems impose compliance overhead that slows procurement cycles.
Strategic Opportunities
- Sovereign cloud regions in the Nordics:Sweden and Finland offer renewable energy-powered data centers with favorable tax treatment for carbon-neutral VPC workloads.
- Edge-to-cloud orchestration convergence:Integration of 5G network slicing with VPC transit gateways enables ultra-low latency industrial automation applications.
- Japan's METI data free flow with trust initiative:Certified cloud frameworks create preferential market access for compliant VPC providers serving cross-border enterprises.
Industry Challenges
- Cloud networking specialist scarcity:Enterprises struggle to hire engineers proficient in software-defined perimeters, BGP routing, and multi-cloud transit architectures.
- Hybrid integration complexity:Legacy on-premises identity systems and mainframe connectivity require custom engineering that extends deployment timelines.
- Multi-jurisdiction certification timelines:Concurrent ISO 27001, SOC 2 Type II, and national cloud security certification processes delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Private Cloud (VPC) Market |
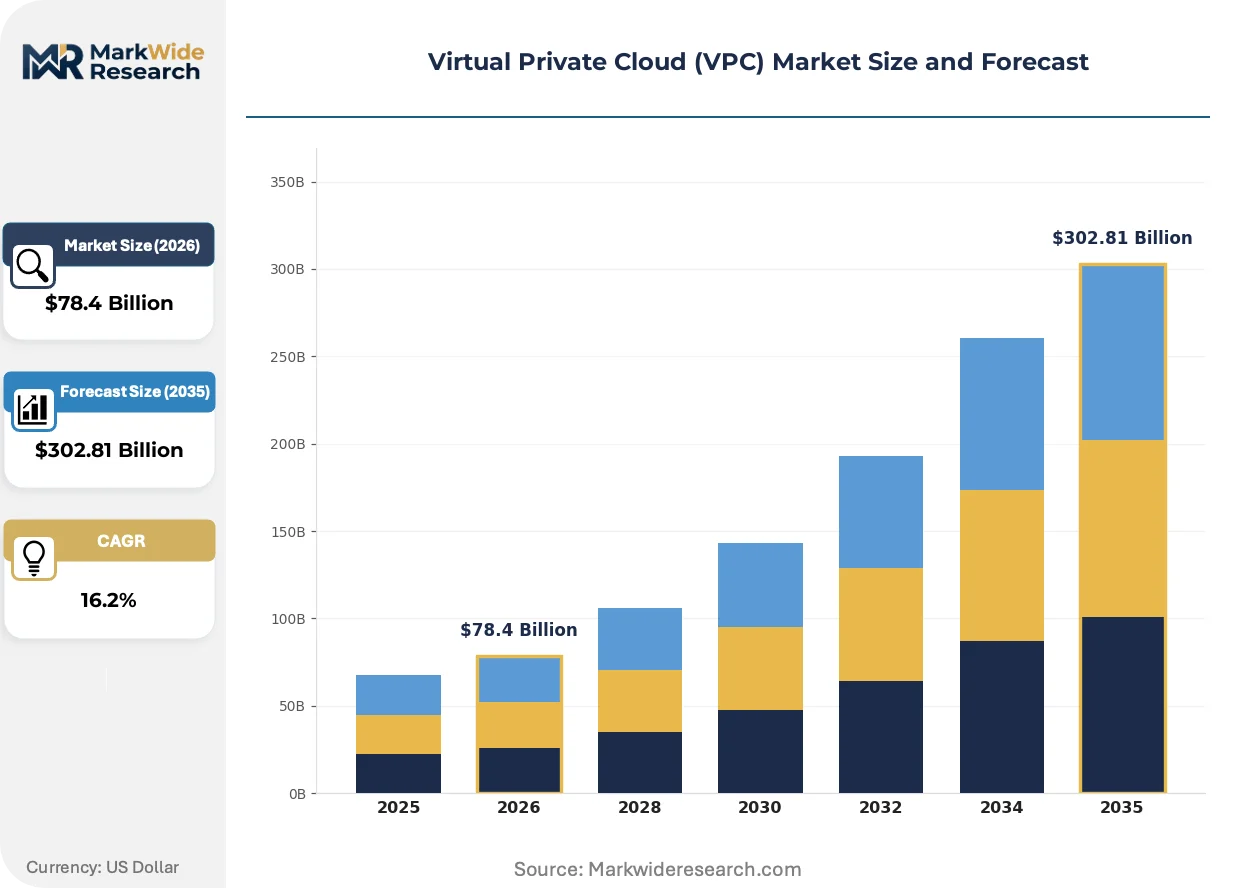
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $302.81 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public VPC, Private VPC, Hybrid VPC, Multi-Cloud VPC Service Type: IaaS, PaaS, SaaS, Managed VPC User Type: SMBs, Large Enterprises, Government, Educational Institutions Connectivity Option: VPN, Direct Connection, Internet Gateway, Transit Gateway |
| Companies Covered | VMware (Broadcom), IBM Cloud, Amazon Web Services (AWS), Dell Technologies APEX, HPE GreenLake, Microsoft Azure, Oracle Cloud Infrastructure (OCI), Cisco, Google Cloud Platform (GCP), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Private Cloud (VPC) Market Strategic Shifts & Innovations
Software-defined networking architectures are fundamentally restructuring how enterprises provision isolation, with programmable infrastructure replacing hardware-defined boundaries and enabling dynamic policy enforcement across distributed workloads.
Zero-trust network access architectures are supplanting traditional VPN concentrators and perimeter-based security models. Financial services institutions and healthcare providers are adopting these frameworks fastest, driven by breach disclosure mandates and ransomware exposure. This transition is compressing demand for legacy IPsec appliances while expanding managed secure access service edge consumption.
The EU AI Act's risk classification framework is mandating infrastructure provenance documentation for high-risk AI training environments. Providers must now maintain immutable audit trails for compute, storage, and network resources touching sensitive models. European healthcare and public sector deployments are most affected, with procurement specifications now requiring explicit compliance attestations.
Consumption-based network provisioning is displacing committed-use connectivity contracts among mid-market enterprises. Direct cloud exchange and software-defined WAN platforms are capturing share from traditional MPLS and leased-line arrangements. This pattern is most visible in Germany's Mittelstand manufacturing sector, where seasonal production cycles favor elastic bandwidth scaling over fixed infrastructure commitments.
Virtual Private Cloud (VPC) Market Segmentation
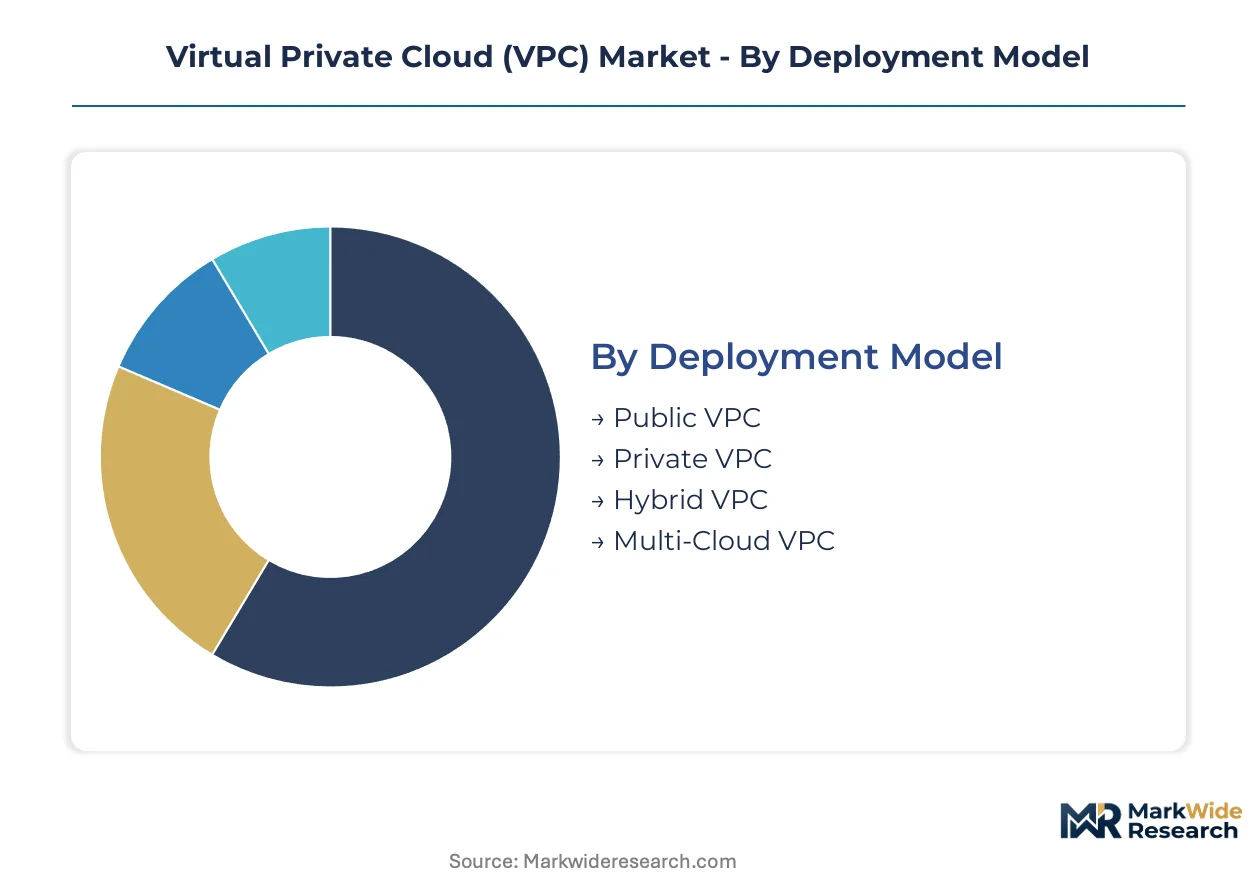
VPC segmentation reveals how deployment architecture, service abstraction layers, and connectivity mechanisms align with distinct risk tolerances and engineering capabilities across buyer organizations. Each category maps directly to procurement authority centers and budget allocation patterns within enterprise IT.
Deployment Model:
Substitution pressure runs strongest against single-tenant private VPC configurations as hybrid architectures absorb workloads from both public and fully isolated alternatives.
- Public VPC:Shared infrastructure with logical isolation via software-defined perimeters and tenant-specific routing tables. Demand concentrates among digital-native enterprises in Germany's Mittelstand manufacturing sector seeking burst capacity without capital expenditure.
- Private VPC:Dedicated physical infrastructure with no multi-tenant compute or storage. Financial services institutions in France deploy these environments for AI training data under EU AI Act high-risk system requirements.
- Hybrid VPC:Orchestrated workload placement across on-premises systems and cloud capacity with unified policy enforcement. Industrial conglomerates favor this architecture for operational technology integration requiring deterministic latency guarantees.
- Multi-Cloud VPC:Consistent networking abstraction spanning two or more hyperscaler environments. Procurement is accelerating among European enterprises seeking vendor diversification and regulatory arbitrage flexibility.
Hybrid VPC retains volume leadership; multi-cloud VPC holds the steepest expansion curve.
Service Type:
Margin capture varies sharply by abstraction layer, with higher-level services extracting premium pricing from organizations lacking internal platform engineering depth.
- IaaS:Raw compute, storage, and networking resources with customer-managed orchestration. Technology-intensive enterprises in Sweden's renewable energy sector favor this model for maximum configuration control.
- PaaS:Managed runtime environments with automated infrastructure provisioning. Application development teams in Finland deploy these services to compress release cycles for carbon-neutral workload deployments.
- SaaS:Fully managed applications delivered over isolated network segments. Procurement is concentrating among educational institutions seeking turnkey collaboration tools with data residency guarantees.
- Managed VPC:Outsourced network architecture, security policy enforcement, and operational monitoring. Large enterprises facing cloud networking specialist scarcity are shifting procurement toward these comprehensive engagements.
IaaS dominates current spending; managed VPC is climbing the fastest as talent constraints bite.
User Type:
Contract structure and sales cycle duration diverge significantly across organizational scale and sectoral procurement regulations.
- SMBs:Organizations with limited IT headcount favor consumption-based provisioning and standardized security templates. India's data localization mandates are compelling this segment toward in-country VPC regions with simplified compliance tooling.
- Large Enterprises:Complex procurement processes with dedicated cloud centers of excellence. Industrial automation and energy sector deployments in Germany require deterministic latency bridging IT and operational technology networks.
- Government:Sovereign cloud requirements with national security certification and domestic staffing mandates. European public sector procurement now requires explicit EU AI Act infrastructure provenance attestations.
- Educational Institutions:Budget-constrained environments with seasonal usage patterns and research data sensitivity. Nordic universities leverage renewable-powered data centers for cost and carbon positioning.
Large enterprises anchor revenue concentration; government verticals are gaining share fastest through sovereign cloud mandates.
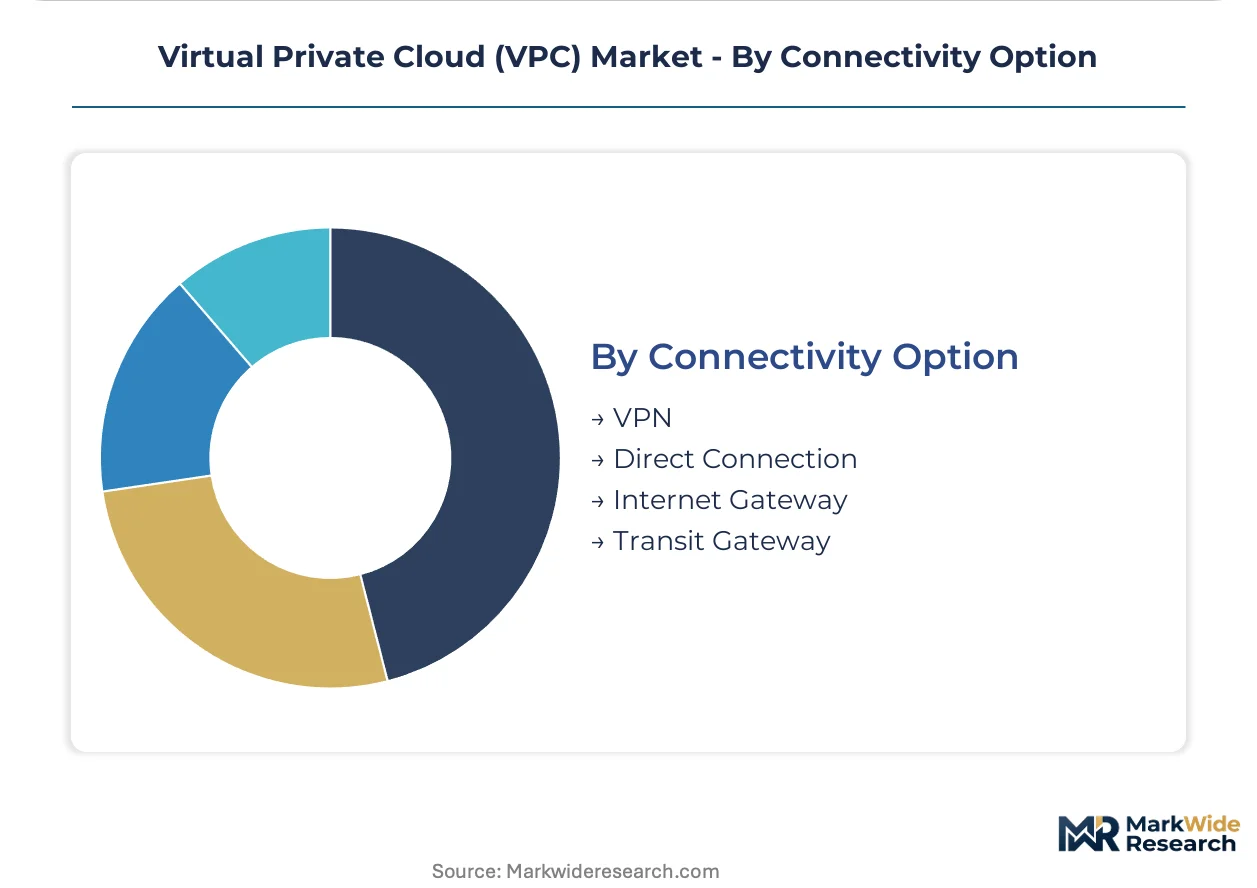
Connectivity Option:
Performance guarantees and cost structures differentiate access mechanisms, with direct physical infrastructure displacing encrypted tunneling for latency-sensitive workloads.
- VPN:Encrypted tunneling over public internet with software-based endpoint management. SMB adoption is maturing as larger enterprises migrate toward deterministic alternatives.
- Direct Connection:Dedicated physical fiber links between customer premises and cloud points of presence. Financial services institutions in Frankfurt and Paris require these configurations for high-frequency trading and real-time risk systems.
- Internet Gateway:Standard public internet access with stateful firewall inspection. Development and test environments deploy this option for cost minimization where data sensitivity permits.
- Transit Gateway:Centralized hub-and-spoke routing for multi-VPC and hybrid network topologies. Manufacturing enterprises with distributed production facilities favor this architecture for simplified operational technology integration.
Direct connection commands premium pricing; transit gateway adoption is expanding most quickly among distributed industrial operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR enforcement by European data protection authorities anchors demand concentration for logically isolated cloud infrastructure. Sovereign data residency mandates in Germany and France are accelerating dedicated VPC deployments for financial and industrial workloads. Cross-border transfer restrictions reshape procurement patterns across continental Europe.
Germany
Industrial conglomerates in manufacturing and energy sectors require VPC architectures bridging IT and operational technology networks. The EU AI Act mandates infrastructure provenance documentation for high-risk AI training environments in Frankfurt and Munich. Automotive suppliers in Baden-Württemberg deploy hybrid configurations to maintain deterministic latency for production line automation.
United States
Financial services institutions demand direct fiber connectivity for high-frequency trading infrastructure in New York and Chicago. FCC data sovereignty guidelines influence cloud architecture decisions for healthcare providers handling HIPAA-protected information. Technology enterprises in Northern Virginia and Silicon Valley favor multi-cloud VPC abstractions for vendor diversification.
France
Healthcare providers and public sector agencies require sovereign cloud certifications under national security frameworks. ANSM and CNIL oversight extends to AI training data governance, compelling dedicated infrastructure for pharmaceutical research. Paris-based financial institutions deploy private VPC configurations for real-time risk calculation systems.
India
Multinational enterprises establish in-country VPC regions to satisfy data localization mandates under the Digital Personal Data Protection Act. Mumbai and Bangalore technology corridors concentrate demand for managed network services among enterprises lacking internal platform engineering depth. Domestic conglomerates in Gujarat and Maharashtra prefer hybrid architectures connecting legacy manufacturing systems to cloud capacity.
Japan
Cross-border enterprises leverage METI-certified cloud frameworks for regional data free flow with trust initiatives. Tokyo and Osaka financial centers require deterministic network performance for quantitative trading operations. Manufacturing enterprises in Aichi Prefecture integrate VPC transit gateways with 5G network slicing for factory automation.
Virtual Private Cloud (VPC) Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with hyperscalers commanding infrastructure provisioning while systems vendors capture hybrid integration contracts. The upper tier consolidates around backward integration into custom silicon and sovereign cloud regions. Three archetypes dominate: hyperscale platform operators, enterprise systems integrators, and networking infrastructure specialists. Competitive moves concentrate on geographic expansion into certified sovereign zones and strategic partnerships for operational technology connectivity.
Among hyperscale platform operators, Amazon Web Services, Microsoft Azure, and Google Cloud Platform exemplify the integrated infrastructure archetype. AWS represents backward integration into custom networking silicon and fiber backbone ownership. Microsoft Azure occupies a position emphasizing enterprise channel depth and hybrid interoperability frameworks. Google Cloud Platform anchors the regulatory navigation archetype through sovereign cloud region expansion and localized staffing commitments.
| Leading Market Players |
|---|
| VMware (Broadcom) |
| IBM Cloud |
| Amazon Web Services (AWS) |
| Dell Technologies APEX |
| HPE GreenLake |
| Microsoft Azure |
| Oracle Cloud Infrastructure (OCI) |
| Cisco |
| Google Cloud Platform (GCP) |
| Others |
Cost & Logistics Intelligence
Managed VPC services displacing in-house platform engineering are redrawing procurement geography and compressing margin structures across service tiers. Enterprises lacking internal cloud networking specialists now source comprehensive network management from hyperscalers, while those retaining engineering capabilities negotiate raw infrastructure at lower unit economics.
Pricing Analysis
Frankfurt commands a 15-25% premium over Mumbai for equivalent dedicated connectivity configurations, reflecting fiber density and certification density. Three-tier pricing structure across premium sovereign-certified, standard enterprise-grade, and economy developer-tier levels dominates procurement. Price differentiation hinges on data residency certification tier and committed-use volume scale. Pricing pressure stems from hyperscaler backward integration into custom networking silicon compressing third-party hardware margins. SMBs exhibit highest price sensitivity, while financial institutions in Paris and Frankfurt absorb premium sovereign-certified rates without elasticity.
Supply Chain Analysis
Lead times for AI-optimized networking chips from Taiwan Semiconductor Manufacturing now stretch 6-9 months, constraining infrastructure provisioning velocity. Supply concentrates in Taiwan for advanced silicon, Japan for optical components, and the United States for software-defined networking controllers. Raw material dependencies span rare earth substrates for chip fabrication, high-purity copper for submarine cabling, and specialized optical glass for transceivers. Single-source vulnerability around Taiwan-based advanced node production represents the dominant structural risk. Distribution runs through hyperscaler direct sales organizations and certified systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive advantage. Sovereign cloud certification requirements and data residency mandates generate switching costs that protect incumbent positioning.
For Market Incumbents: Consolidate sovereign cloud region presence in Germany and France ahead of EU AI Act enforcement deadlines. Acquire specialized operational technology networking firms to bridge IT/OT integration capabilities. Threat from emerging sovereign cloud specialists in the Nordics demands preemptive capacity commitments. Channel control through systems integrators remains the priority defensive lever. For New Entrants and Emerging Players: Fast-track ISO 27001 and national cloud security certification in Sweden and Finland to capture carbon-neutral workload demand. White-space exists in managed VPC services for India's Mittelstand manufacturing segment under data localization mandates. Target educational institutions in Nordic markets with research-data-sensitive procurement. Go-to-market through hyperscaler marketplace listings accelerates trust establishment. For Investors and Strategic Acquirers: EU AI Act infrastructure provenance documentation requirements reshape the acquisition landscape toward compliance-ready platforms. Long-term viability favors providers with captive sovereign region footprints and established audit trail capabilities. Acquisition target archetype: regional managed services specialists with existing national security certifications. Signal to watch: hyperscaler capex allocation shifts toward custom silicon fabrication capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Region Expansion | EU AI Act compliance in Frankfurt and Paris secures financial services procurement. |
| Custom Silicon Backward Integration | In-house AI networking chip production reduces Taiwan Semiconductor Manufacturing dependency. |
| Operational Technology Partnership | Integration with Siemens and ABB systems captures German industrial automation demand. |
| Managed VPC Service Launch | Platform engineering talent scarcity drives enterprise outsourcing toward comprehensive engagements. |
| Carbon-Neutral Certification Program | Swedish and Finnish renewable energy positioning attracts sustainability-mandated workloads. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud platform engineers, enterprise IT procurement officers, hyperscaler solution architects, and sovereign cloud compliance specialists. Secondary validation drew from SEC 10-K infrastructure capex disclosures, EU regulatory filings documenting AI Act implementation timelines, and national data protection authority enforcement patterns. Bottom-up spending estimates triangulated against top-down infrastructure provisioning forecasts.
Across the analysis window, projections incorporate deployment model substitution curves, service type margin evolution, and connectivity option migration patterns. Segmentation dimensions span deployment architecture, abstraction layer, organizational scale, and access mechanism. CAGR derivation incorporated sovereign cloud certification pipeline velocity, platform engineering labor market tightness, and cross-border data transfer mechanism adoption rates.
Decision-makers should treat outputs as directional under sustained GDPR enforcement intensity and stable Taiwan-based semiconductor supply; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Migration Services Market
Cloud Computing
Brazil Cloud Computing Market
Cloud Computing
Healthcare Cloud Computing Software Market
Cloud Computing
Community Cloud Market
Cloud Computing
Telecom Cloud Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
Canada Cloud Computing Market
Cloud Computing
Cloud Based Backup Services Market
Cloud Computing
Cloud Directory Services Market
Cloud Computing
Philippines ICT Market
Cloud Computing
Cloud IDE Market
Cloud Computing
Cloud ECS Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
North America Mobile Cloud Market
Cloud Computing
Hybrid Cloud in BFSI Market
Cloud Computing
UK Cloud Backup Market