
 Cloud Computing Services Market | 2026-2036
Cloud Computing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Computing Services Market Analysis
Usage-based leasing and asset-light infrastructure financing is fragmenting capital barriers to entry in cloud services. Amazon Web Services leverages its data center scale and enterprise channel depth to dominate enterprise migrations. Microsoft Azure anchors hybrid cloud demand through native integration with existing productivity stacks. Google Cloud Platform specializes in analytics and AI workloads, competing on compute price-performance for machine learning pipelines.
Cloud computing services deliver on-demand access to pooled configurable computing resources—servers, storage, databases, networking, software—via internet protocols with metered service parameters including latency SLAs below 20ms and 99.99% uptime guarantees. The primary commercial purpose is replacing capital-intensive on-premises infrastructure with elastic operational expenditure models. Public cloud deployment captures the largest revenue pool due to hyperscaler economies of scale, while hybrid architectures represent the fastest-expanding segment as regulated industries balance agility with data sovereignty requirements. SaaS within service type commands the deepest margin pools through recurring subscription structures and low incremental delivery costs.
FDA 21 CFR Part 11 and HIPAA shape healthcare cloud adoption through audit trail and encryption mandates, while EU GDPR and the EU AI Act restrict cross-border data flows and automated decision-making workloads. ISO 27001 and SOC 2 Type II certifications function as de facto market access requirements for enterprise procurement. Stakeholders must monitor evolving sovereign cloud regulations in Germany, France, and India as fragmentation of compliance frameworks threatens unified service architectures.
Market Dynamics
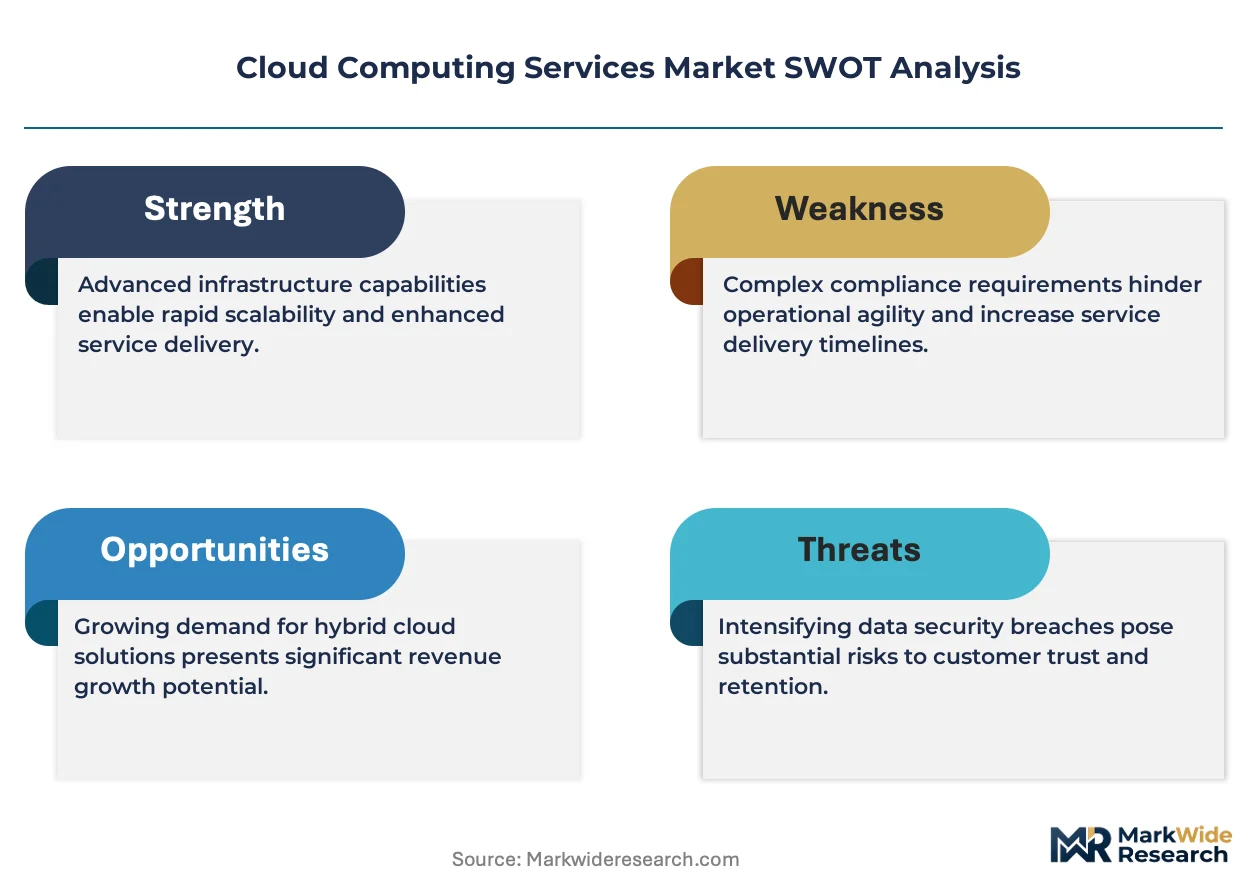
Hyperscaler concentration in infrastructure supply is forcing mid-tier enterprises into multi-cloud architectures to avoid vendor lock-in, while sovereign data residency mandates fragment service delivery models across national boundaries.
Growth Catalysts
- EU AI Act compliance deadlines:European enterprises are accelerating migration to certified cloud environments to meet automated decision-making audit requirements, expanding demand for GDPR-aligned infrastructure.
- Federal cloud-first procurement:United States government agencies mandate cloud-native solutions for new IT deployments, creating sustained demand for FedRAMP-authorized service tiers.
- Diagnostic imaging workloads:Healthcare systems are shifting PET and MRI analytics to GPU-accelerated cloud instances, requiring specialized HIPAA-compliant environments with sub-10ms latency guarantees.
Market Restraints
- Electricity cost volatility:Data center power purchase agreements in Germany and Ireland face renewal pressure from grid instability, compressing hyperscaler margin structures in European facilities.
- Cross-border data friction:India's data localization directives under the Digital Personal Data Protection Act restrict workload portability, forcing redundant infrastructure deployment.
- Optical interconnect shortages:Co-packaged optics supply concentrates among Taiwanese and Korean component vendors, constraining AI training cluster expansion timelines.
Strategic Opportunities
- Edge-native manufacturing:Industrial IoT convergence with 5G private networks creates demand for micro-data centers at production facilities, bypassing core cloud latency constraints.
- Carbon-aware compute scheduling:EU Green Deal reporting requirements position renewable-powered cloud regions as premium service tiers, attracting ESG-mandated procurement from financial services.
- Brazilian healthcare digitization:ANVISA's electronic medical record mandates drive first-wave cloud adoption among regional hospital networks underserved by local infrastructure.
Industry Challenges
- FinOps talent scarcity:Enterprise cloud cost optimization requires specialized engineers capable of rightsizing Kubernetes workloads across multi-vendor environments, with skill gaps most acute in mid-market organizations.
- Legacy mainframe integration:Financial institutions maintaining COBOL-based core banking systems face protracted API abstraction projects to enable hybrid cloud connectivity.
- Sovereign certification timelines:Germany's C5 baseline and France's SecNumCloud qualifications demand 18-24 month audit cycles, delaying service launches for non-European providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Computing Services Market |
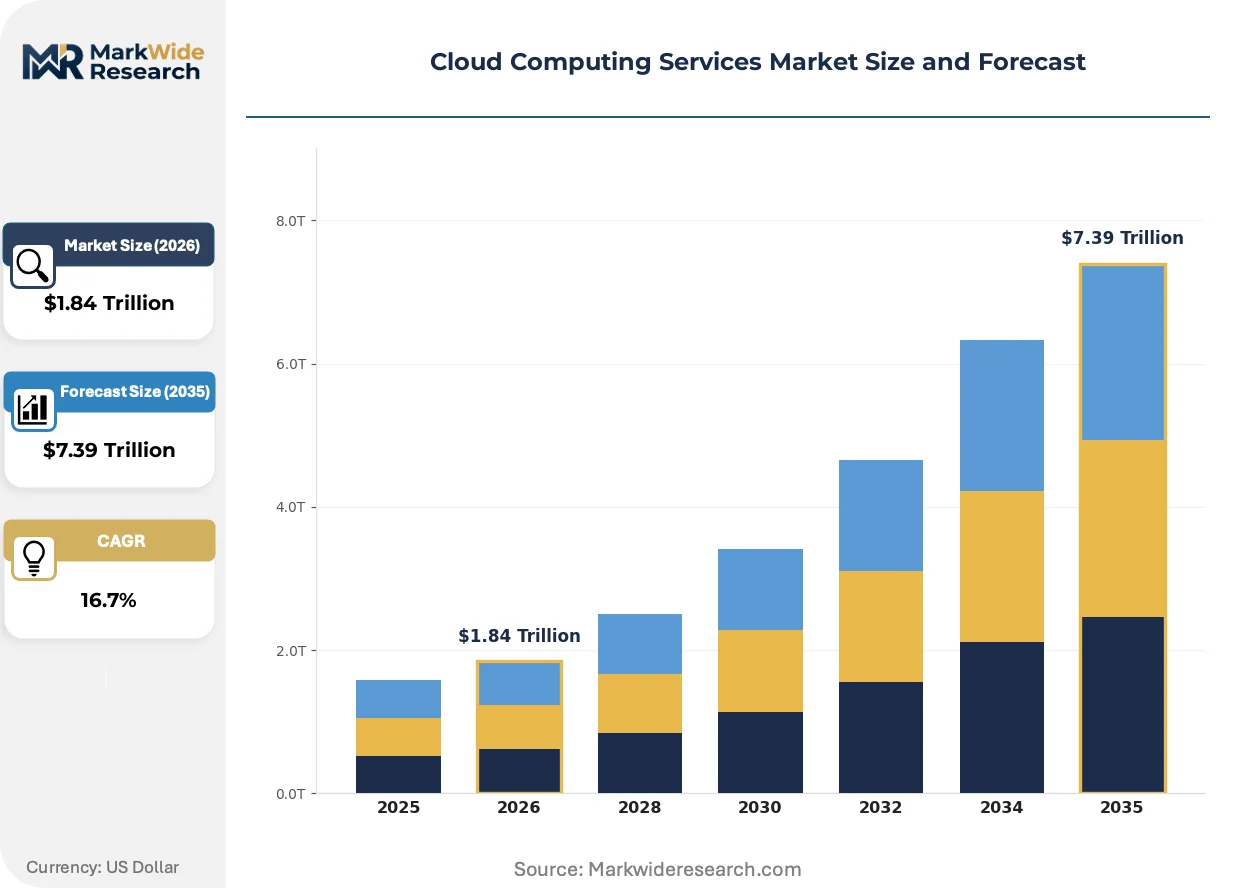
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $7.39 Trillion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, FaaS End User: SMEs, Large Enterprises, Government, Educational Institutions Feature: Data Storage, Disaster Recovery, High Availability, Security |
| Companies Covered | IBM Cloud, Alibaba Cloud, Amazon Web Services, Cloudflare, DigitalOcean, Microsoft Azure, Oracle Cloud Infrastructure, UpCloud, Google Cloud Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Computing Services Market Emerging Trajectories
Serverless computing architectures are compressing the abstraction layer between application code and infrastructure management, enabling developers to deploy without provisioning visibility. This shift is redistributing value capture toward platform engineering tooling.
Containerization is collapsing the distinction between development and production environments through immutable infrastructure patterns. DevOps teams at SaaS vendors and fintech startups are adopting GitOps workflows at scale, compressing release cycles from weeks to hours and eliminating configuration drift as a failure mode.
GDPR's Article 44 restrictions on international data transfers are forcing architectural fragmentation. European enterprises now maintain distinct data residency zones for customer records, while cloud providers invest in EU-exclusive sovereign cloud offerings that isolate operations from non-European legal jurisdictions.
Consumption-based pricing is displacing committed-use discounts as the dominant procurement calculus. Mid-market buyers in retail and logistics verticals are prioritizing granular billing transparency over volume commitments, pressuring providers to expose real-time cost attribution dashboards and automated anomaly detection.
Cloud Computing Services Market Segmentation
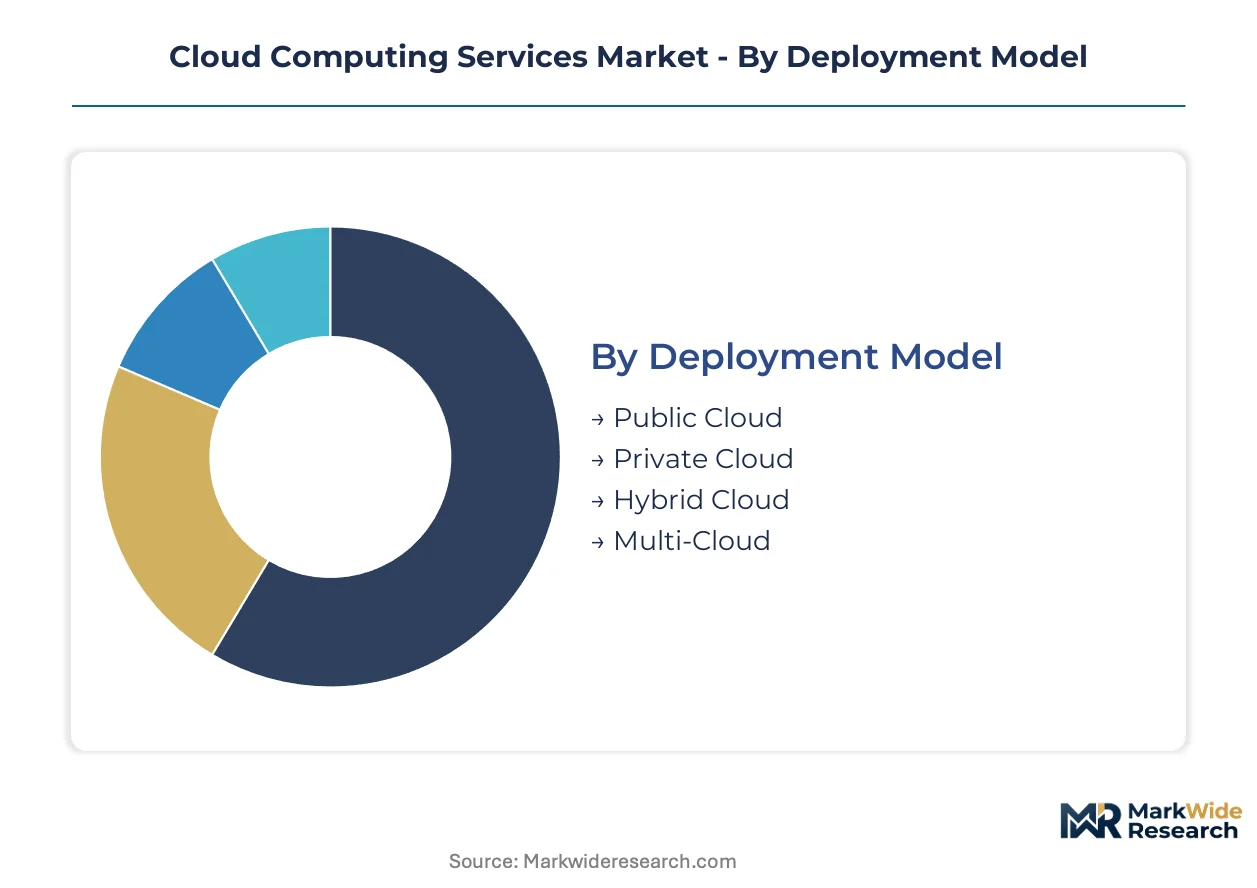
Cloud computing services fragment across deployment architectures, service abstraction layers, and procurement sophistication levels. Each segmentation dimension carries distinct margin profiles and compliance obligations that reshape vendor positioning and customer switching costs.
Deployment Model:
Cost tier stratification across deployment models determines capital intensity, operational control depth, and regulatory exposure for workload owners.
- Public Cloud:Shared infrastructure pools deliver metered compute, storage, and networking through hyperscaler-operated facilities. Demand concentrates among retail, media, and SaaS startups in the United States seeking burst capacity without facility ownership. AWS, Azure, and GCP price competition compresses margins at scale.
- Private Cloud:Dedicated single-tenant environments deploy on-premises or at colocation facilities with full hardware isolation. Financial services and defense contractors in Germany and France mandate private deployments to satisfy SecNumCloud and C5 baseline certifications. Capital expenditure requirements limit adoption to regulated enterprises with compliance-driven procurement.
- Hybrid Cloud:Orchestrated workload portability between private infrastructure and public cloud pools enables tiered data placement by sensitivity. Manufacturing and healthcare systems across India and Brazil adopt hybrid architectures to retain patient records locally while bursting analytics to public GPU clusters.
- Multi-Cloud:Deliberate distribution across two or more hyperscalers mitigates vendor lock-in and negotiates pricing leverage. Mid-market technology firms in the United Kingdom and Netherlands deploy multi-cloud Kubernetes fabrics to arbitrage spot instance pricing and service-specific strengths.
Public Cloud holds installed capacity. Hybrid Cloud is rotating up the share rankings.
Service Type:
Application abstraction depth determines vendor value capture, customer technical requirements, and switching friction across the stack.
- IaaS:Raw compute, storage, and network virtualization exposes infrastructure APIs for direct resource orchestration. High-performance computing and genomics pipelines at research institutions in Switzerland and South Korea demand bare-metal GPU clusters with InfiniBand interconnects. Procurement emphasizes price-performance per FLOP and storage IOPS.
- PaaS:Managed runtime environments abstract operating systems, middleware, and database administration from application developers. Fintech startups in Singapore and UAE accelerate release velocity through managed Kubernetes, serverless functions, and CI/CD pipelines. Vendor stickiness derives from integrated developer tooling and database migration friction.
- SaaS:Fully managed application delivery eliminates infrastructure visibility for end-users through browser or mobile client access. Enterprise productivity, CRM, and ERP deployments at Canadian healthcare networks and Australian government agencies prioritize FedRAMP and ISO 27001 certifications over customization depth. Recurring subscription models generate the deepest margin pools.
- FaaS:Event-driven compute execution charges per invocation duration and memory allocation without persistent server management. IoT data processing and real-time stream analytics at Japanese automotive suppliers and German industrial OEMs leverage FaaS for intermittent, latency-sensitive workloads. Cold start latency remains the primary architectural constraint.
SaaS captures the margin concentration. FaaS is climbing the fastest in developer adoption metrics.
End User:
Customer type segmentation maps procurement sophistication, contract scale, and compliance complexity against vendor sales motion requirements.
- SMEs:Organizations below 500 employees prioritize consumption-based pricing, self-service onboarding, and pre-configured industry templates. Regional logistics providers and professional services firms in Spain and Italy adopt SaaS-first strategies with limited internal cloud engineering capacity. Procurement cycles compress to days through marketplace transactions.
- Large Enterprises:Global organizations above 10,000 employees negotiate enterprise license agreements with committed spend thresholds and dedicated support tiers. Pharmaceutical manufacturers and energy conglomerates in the United States and United Kingdom require custom security attestations and private connectivity options. Sales cycles extend 12-18 months with multi-stakeholder governance.
- Government:National, state, and municipal agencies mandate FedRAMP, IRAP, or equivalent sovereign certifications with data residency guarantees. Defense and civilian departments across Australia, Canada, and Saudi Arabia segment workloads across classified and unclassified tiers. Procurement follows formal RFP processes with incumbent preference biases.
- Educational Institutions:Universities and K-12 districts leverage academic pricing programs and research grant funding for compute-intensive workloads. Genomics, climate modeling, and particle physics collaborations across CERN member states and US National Science Foundation grantees consume petascale allocations. Budget cyclicality drives spot instance and preemptible VM adoption.
Large Enterprises anchor vendor revenue concentration. SMEs are gaining share fastest in net new customer acquisition.
Feature:
Functional capability bundles reshape architectural decisions, pricing premiums, and competitive differentiation in procurement evaluations.
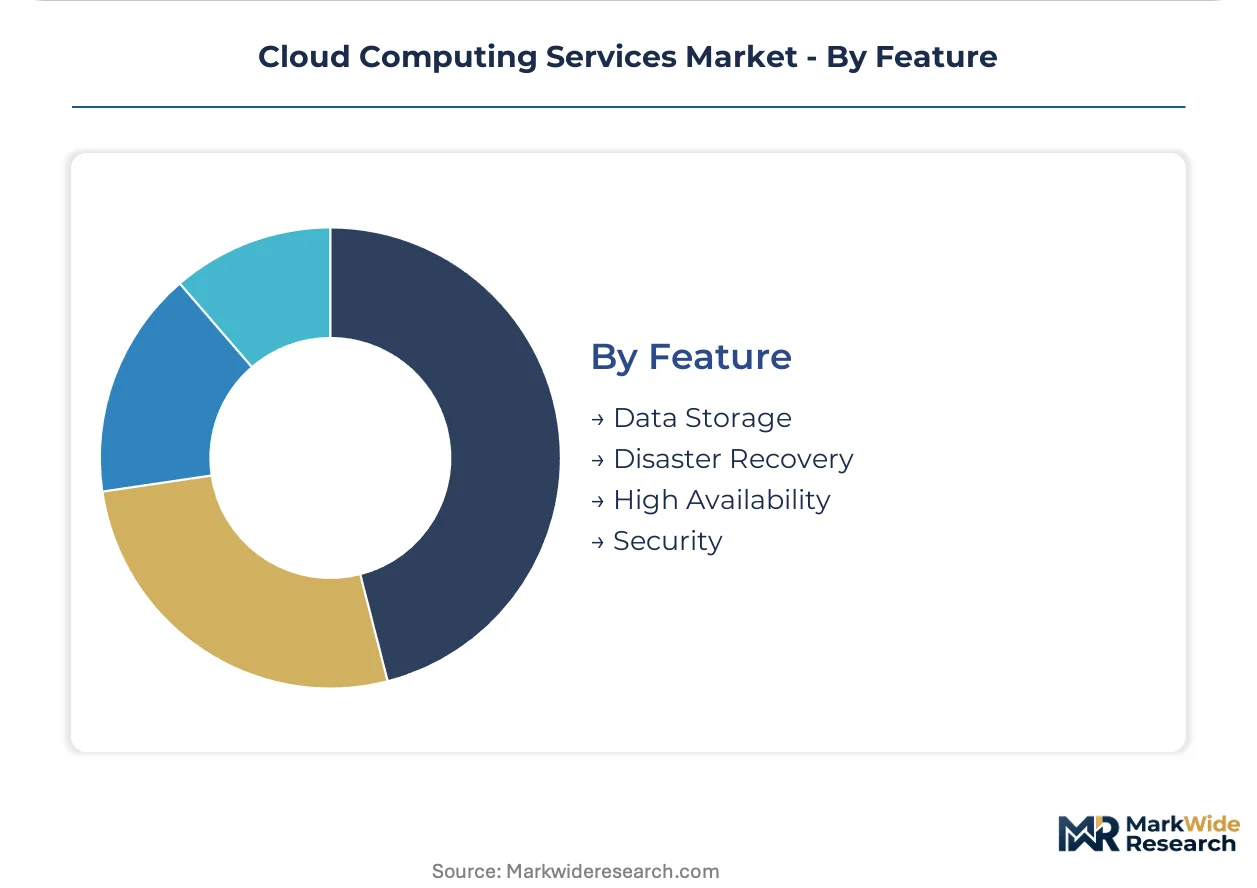
- Data Storage:Object, block, and file abstractions with tiered durability, retrieval latency, and geographic replication options. Media archives and surveillance systems in Brazil and Mexico optimize across hot, warm, and cold storage economics. Egress bandwidth pricing dominates total cost of ownership calculations.
- Disaster Recovery:Automated failover, backup orchestration, and point-in-time recovery capabilities with defined recovery point and time objectives. Banking and insurance regulators in Japan and South Korea mandate DR testing frequency and documentation. Synchronous replication within 100km radii satisfies sub-15 minute RTO requirements.
- High Availability:Multi-zone and multi-region redundancy with automatic health checking and traffic routing. E-commerce platforms and payment processors in the United States and United Kingdom architect for 99.999% uptime with financial penalty clauses. Load balancing and database clustering consume the architectural complexity budget.
- Security:Identity and access management, encryption at rest and in transit, threat detection, and compliance monitoring integrations. Healthcare providers under HIPAA and EU GDPR deploy customer-managed keys and private endpoint connectivity. Shared responsibility model clarity determines procurement risk acceptance.
Data Storage holds installed capacity. Security is rotating up the share rankings as sovereign compliance tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud computing services flow disproportionately toward net-importing economies where domestic infrastructure lags demand growth. Export dynamics concentrate in the United States, where hyperscaler headquarters and data center buildouts generate service revenues absorbed globally.
United States
Federal cloud-first procurement mandates and hyperscaler data center expansion drive infrastructure investment. FedRAMP authorization requirements shape vendor qualification pathways for government contracts. Northern Virginia's data center corridor sustains the densest concentration of cloud capacity worldwide.
Germany
Industrial IoT workloads and automotive digitalization propel enterprise cloud consumption. The C5 baseline certification and GDPR compliance frameworks enforce sovereign data residency standards. Frankfurt's financial hub anchors demand for low-latency trading infrastructure with sub-10ms connectivity guarantees.
India
Digital public infrastructure scale-out and startup ecosystem growth accelerate service adoption. The Digital Personal Data Protection Act mandates data localization, restricting cross-border workload portability. Bangalore's technology corridor concentrates engineering talent for cloud-native application development.
United Kingdom
Financial services modernization and regulatory technology deployment sustain enterprise demand. FCA operational resilience rules mandate multi-region redundancy for critical banking systems. London's fintech cluster consumes specialized compliance-aligned cloud tiers for payment processing infrastructure.
Japan
Manufacturing edge computing integration and aging workforce automation drive hybrid cloud architectures. METI data governance guidelines encourage domestic facility preference for sensitive industrial data. Tokyo-Osaka corridor hosts submarine cable terminations linking Asia-Pacific traffic flows.
Cloud Computing Services Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying optical interconnects, cooling systems, and power infrastructure. The market exhibits oligopolistic concentration at the infrastructure layer, with three hyperscalers capturing the majority of public cloud revenue pools. Strategic archetypes span hyperscale platform operators, sovereign cloud specialists, and vertical-specific managed service providers. Competitive dynamics center on multi-year enterprise contract capture and sovereign certification acquisition timelines.
Among hyperscale platform operators, Amazon Web Services, Microsoft Azure, and Google Cloud Platform exemplify the infrastructure-dominant archetype through global facility networks and enterprise channel depth. These entities occupy positions where scale economies in power procurement and custom silicon development create defensive moats. Sovereign cloud specialists and regional operators sit in adjacent tiers, serving compliance-constrained workloads where data residency mandates override price-performance optimization.
| Leading Market Players |
|---|
| IBM Cloud |
| Alibaba Cloud |
| Amazon Web Services |
| Cloudflare |
| DigitalOcean |
| Microsoft Azure |
| Oracle Cloud Infrastructure |
| UpCloud |
| Google Cloud Platform |
| Others |
Supply Flow & Price Mechanics
Northern Virginia's data center corridor concentrates hyperscaler capacity, translating facility scale into procurement leverage that compresses mid-tier provider margins. Electricity purchase agreements and optical interconnect sourcing costs flow through to enterprise contract pricing, with sovereign certification premiums layering atop base compute rates.
Pricing Analysis
Industrial OEM buyers anchor consumption-based metering as the dominant pricing structure, with compute instances billed per hour and storage tiered across hot, warm, and cold retrieval latency bands. Price differentiation rests on FedRAMP authorization grade and reserved capacity commitments, with hyperscaler spot instances undercutting on-demand rates by substantial margins. Pricing pressure stems from GPU cluster scarcity for AI training workloads, tightening margins on accelerated compute tiers. Mid-market SaaS vendors exhibit highest price sensitivity, while defense contractors accept premium sovereign-cloud rates for air-gapped environments.
Supply Chain Analysis
Foundry capacity at TSMC and Samsung Electronics anchors custom silicon production for hyperscaler AI accelerators, while Foxconn and Quanta Computer concentrate server assembly. Taiwan, South Korea, and the United States dominate advanced node fabrication and co-packaged optics supply. Raw material dependencies center on high-purity silicon wafers, rare earth elements for magnetics, and specialized cooling fluids. Single-source vulnerability concentrates in Taiwanese optical component vendors, exposing expansion timelines to geopolitical friction. Distribution runs through direct hyperscaler procurement channels and tier-one systems integrators for enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud computing services sit in early-cycle expansion as sovereign data residency mandates force workload fragmentation across national boundaries, creating greenfield infrastructure demand.
For Market Incumbents: Harden multi-cloud interoperability layers to prevent customer defection to specialized sovereign providers. Accelerate C5 and SecNumCloud certification timelines in Frankfurt and Paris facilities to preempt European competitor entry. Vertical integration into custom AI silicon preserves margin on GPU-accelerated workloads threatened by NVIDIA supply constraints. For New Entrants and Emerging Players: Pursue edge-native manufacturing deployments in São Paulo and Mexico City industrial corridors, where 5G private network convergence outpaces hyperscaler buildout. Brazilian healthcare digitization under ANVISA mandates presents the most penetrable vertical, with regional hospital networks lacking local infrastructure expertise. Lead with managed compliance wrappers that abstract GDPR and LGPD complexity for mid-market buyers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical-specific managed service providers with embedded regulatory expertise, offering 5-10 year contract visibility. Target acquisition archetypes include FinOps tooling vendors and sovereign cloud specialists holding national security clearances. Monitor hyperscaler capex guidance revisions as the primary signal for AI infrastructure demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EU AI Act deadlines in Germany and France accelerate C5 and SecNumCloud qualification timelines for market access. |
| Custom Silicon Development | In-house AI accelerator programs at AWS and Google Cloud reduce dependency on NVIDIA supply allocations. |
| Edge Infrastructure Partnership | Industrial IoT convergence with 5G private networks in Japan and Brazil creates micro-data center demand. |
| FinOps Platform Acquisition | Cloud cost optimization tooling addresses enterprise talent scarcity in Kubernetes rightsizing across multi-vendor environments. |
| Healthcare Compliance Specialization | HIPAA and FDA 21 CFR Part 11 expertise captures diagnostic imaging workload migration to GPU-accelerated instances. |
Methodological Framework
The analysis maps IaaS, PaaS, SaaS and FaaS service layers, each validated through cloud architects, enterprise procurement officers, and DevOps platform engineers. Primary interviews with hyperscaler solutions architects and channel partners combined with secondary validation against SEC capex disclosures, hyperscaler earnings reports, and sovereign certification registries. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against aggregate infrastructure investment flows anchored value estimates.
Assumption sets held federal cloud-first procurement mandates and EU AI Act compliance deadlines as fixed demand drivers, while varying electricity cost trajectories and optical interconnect supply scenarios. Segmentation dimensions modeled include deployment architecture, service abstraction layer, organization size tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves and infrastructure capacity expansion pipelines, with AI training workload growth and sovereign data residency requirements as primary forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting infrastructure financing costs or escalation in Taiwan Strait tensions disrupting component supply would shift the trajectory. Forecasts reflect these documented assumptions with acknowledged sensitivity to hyperscaler pricing discipline and sovereign certification timeline delays. Quarterly review of hyperscaler capital expenditure guidance and EU member state data localization enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
Cloud Based Backup Services Market
Cloud Computing
UAE Cloud Computing Market
Cloud Computing
Cloud Identity Management Market
Cloud Computing
Nigeria Cloud Computing Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market
Cloud Computing
Global Cloud Office Services Market
Cloud Computing
AI and Blockchain Cloud Services Market
Cloud Computing
Cloud Applications Market
Cloud Computing
Web Service Cloud Market
Cloud Computing
Global Cloud Computing Iaas in Life Science Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Cloud Managed Networking Market
Cloud Computing
Europe AI Cloud Computing in Automotive Market
Cloud Computing
Global Distributed Cloud Market