
 Cloud Enterprise Content Management Market | 2026-2036
Cloud Enterprise Content Management Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Enterprise Content Management Market Analysis
The gap between premium AI-infused content services and commodity file storage is broadening into a structural market divide. Microsoft Corporation leverages its Copilot integration to anchor the premium tier with generative document intelligence. OpenText Corporation sustains dominance in regulated verticals through deep compliance tooling and long-term records governance. Box, Inc. competes on API-first architecture, specializing in developer-centric embedding for SaaS workflows.
Cloud Enterprise Content Management denotes a software architecture for capturing, storing, managing, and delivering unstructured business content through distributed cloud infrastructure, typically employing metadata-driven retrieval, version control, and role-based access protocols to ensure audit trails across document lifecycles. Its primary commercial purpose centers on eliminating information silos while enforcing retention policies and security boundaries across decentralized workforces. The deployment model dimension shows hybrid cloud configurations capturing the fastest expansion as enterprises balance latency-sensitive operations against burst scalability needs. Within applications, workflow automation commands disproportionate margin pools because it embeds directly into operational expenditure reduction narratives. Document management remains the volume anchor but faces commoditization pressure from native platform offerings.
GDPR and the EU AI Act impose algorithmic transparency and data residency obligations that reshape vendor qualification criteria across European procurement. The SEC's cybersecurity disclosure rules and HIPAA breach notification standards in the United States similarly elevate auditability to a non-negotiable specification. ISO 27001 certification and SOC 2 Type II attestation now function as table stakes rather than differentiators for enterprise RFP shortlisting. Stakeholders must weigh sovereign cloud requirements against interoperability costs when architecting multi-tenant versus dedicated instance strategies.
Market Dynamics
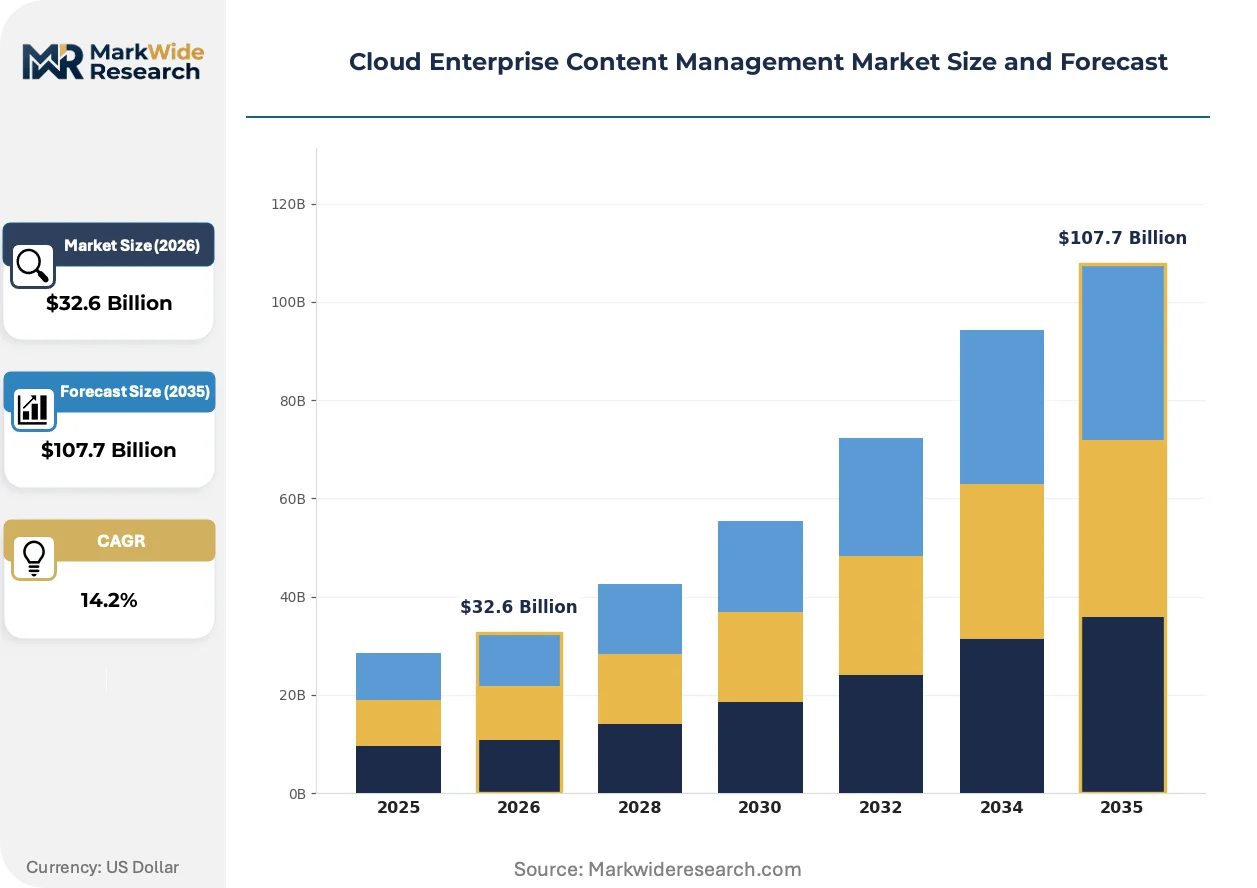
The Cloud Enterprise Content Management market is experiencing structural compression as generative AI capabilities force vendors to differentiate through embedded intelligence rather than storage scale, while GDPR and the EU AI Act impose algorithmic auditability requirements that disqualify legacy architectures from European procurement shortlists.
Growth Catalysts
- EU AI Act compliance mandates:Enterprises across Germany, France, and Italy must replace opaque on-premises archives with auditable cloud repositories that expose decision logic for automated content classification systems.
- Healthcare digitization:Hospital systems and pharmaceutical manufacturers are deploying cloud-native document management to unify patient records, clinical trial documentation, and regulatory submissions under HIPAA and EMA retention frameworks.
- Automotive supplier networks:Mittelstand manufacturers in Stuttgart, Wolfsburg, and Munich are digitizing quality records and supplier documentation to meet ISO/TS 16949 traceability requirements for electric vehicle supply chains.
Market Restraints
- Data residency enforcement:Germany's Federal Data Protection Authority and France's CNIL impose strict localization requirements that fragment cloud architectures and inflate operational complexity for multi-national deployments.
- Hybrid integration costs:Enterprises maintaining latency-sensitive manufacturing execution systems on-premises face substantial capital expenditure to synchronize with burst-scalable cloud content tiers.
- Skills concentration:DevOps and compliance engineering talent clusters in Berlin, Paris, and London, creating recruitment bottlenecks for secondary European markets attempting equivalent transformations.
Strategic Opportunities
- Small-mid enterprise underpenetration:Professional services firms and specialty manufacturers in Spain, Poland, and the Netherlands remain dependent on file shares and email attachments, presenting greenfield deployment potential.
- Workflow automation convergence:Integration of low-code process orchestration with content repositories enables vendors to capture operational expenditure reduction budgets previously allocated to separate business process management suites.
- CSRD sustainability reporting:The Corporate Sustainability Reporting Directive mandates structured disclosure of environmental data, creating demand for content systems that version-control audit trails across distributed ESG data collection workflows.
Industry Challenges
- Algorithmic transparency engineering:Vendors must reconstruct machine learning pipelines to generate explainable confidence scores for automated document classification, extending product development cycles by 12-18 months.
- Multi-tenant security isolation:Financial services and defense contractors demand dedicated instance architectures that sacrifice economies of scale, compressing margins for providers serving regulated verticals.
- Interoperability standardization gaps:Absence of unified APIs between competing content platforms forces enterprises into costly custom integration projects or vendor lock-in acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Enterprise Content Management Market |
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $107.7 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Small Enterprises, Medium Enterprises, Large Enterprises, Government Agencies Application: Document Management, Workflow Automation, Digital Asset Management, Records Management Service Type: Consulting, Implementation, Training, Support |
| Companies Covered | Microsoft Corporation, OpenText Corporation, IBM Corporation, Oracle Corporation, Hyland Software, Inc., Box, Inc., Alfresco Software, Inc., Adobe Inc., Laserfiche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Enterprise Content Management Market Emerging Trajectories
Generative document intelligence is restructuring competitive boundaries as vendors race to embed contextual understanding directly into content workflows, while regulatory pressure accelerates the obsolescence of architectures that cannot demonstrate algorithmic accountability.
Retrieval-augmented generation is expanding into enterprise content repositories to synthesize answers across dispersed document corpora. Automotive quality engineers and pharmaceutical regulatory affairs teams in Germany and Switzerland are piloting these systems to accelerate root-cause analysis and submission preparation. The technology is compressing research timelines from days to hours, forcing traditional search vendors to reposition or exit.
The EU AI Act's risk-based classification framework imposes documentation and human oversight obligations on high-risk AI applications including automated content processing. Financial institutions in Frankfurt and Paris must now maintain model cards and training data provenance for document classification systems previously deployed without governance infrastructure. Compliance tooling has become a procurement gate, with vendors lacking audit trails excluded from RFP shortlists regardless of functional capability.
Subscription fatigue among mid-market enterprises is fragmenting purchasing authority away from centralized IT procurement toward line-of-business buyers. Manufacturing operations managers in Bavaria and Rhineland-Palatinate now directly evaluate content platforms against production system integration rather than deferring to CIO-led standardization. This shift favors vendors with API-first architectures and pre-built connectors to Siemens, SAP, and Dassault Systèmes environments over monolithic suite providers.
Cloud Enterprise Content Management Market Segmentation
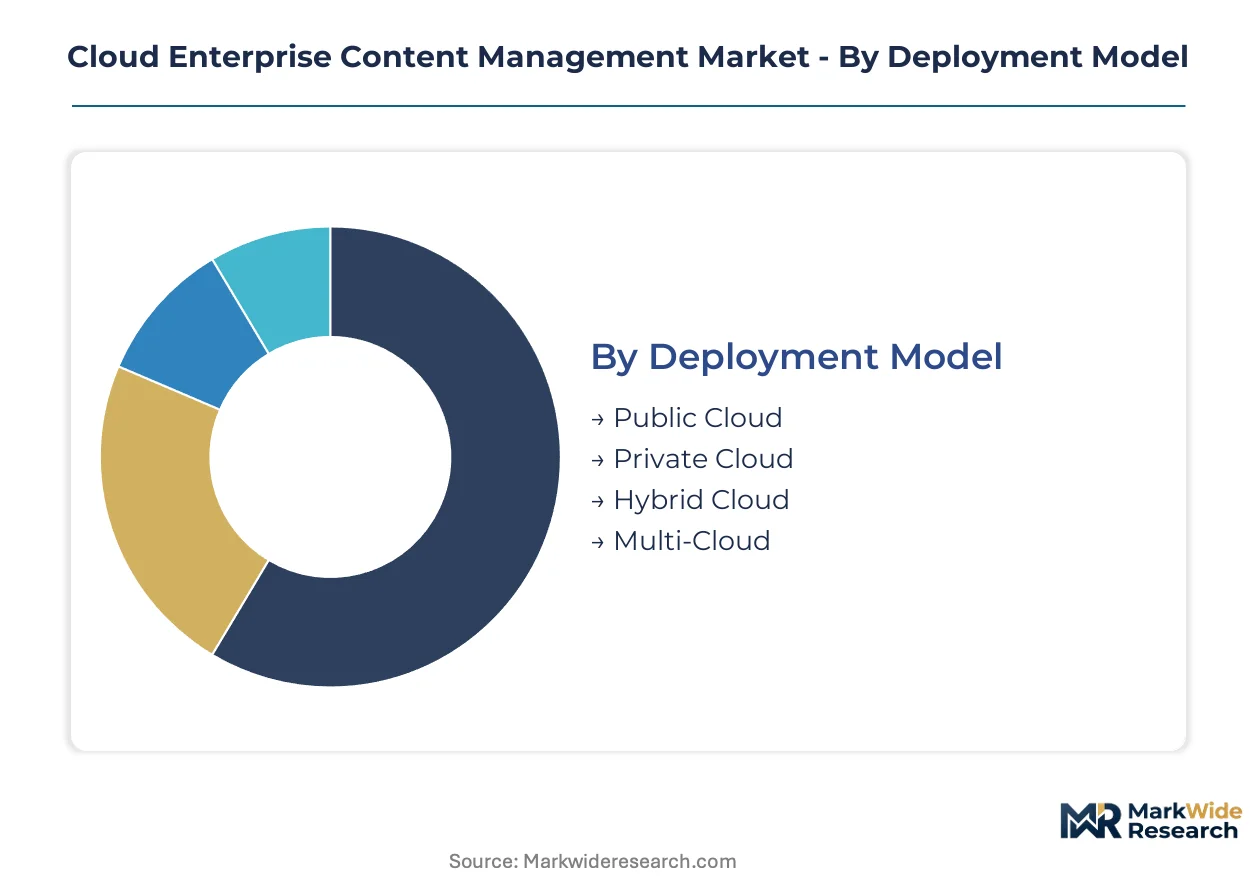
Cloud ECM segmentation reveals divergent vendor strategies across deployment complexity and customer scale. Procurement patterns split between enterprises demanding sovereign infrastructure and mid-market buyers prioritizing speed-to-deployment over customization depth.
Deployment Model:
Customization intensity decreases from dedicated infrastructure to shared services, creating distinct margin profiles and sales cycle durations across the spectrum.
- Public Cloud:Shared-tenant architectures deliver burst scalability through hyperscaler infrastructure. German automotive suppliers and pharmaceutical manufacturers in Basel deploy public tiers for non-sensitive collaboration workloads, constrained by GDPR data residency requirements for customer records.
- Private Cloud:Single-tenant dedicated environments enforce security boundaries through isolated compute and storage. Frankfurt-based financial institutions and defense contractors in Stuttgart mandate private deployments to satisfy BaFin and NATO procurement specifications for classified documentation.
- Hybrid Cloud:Synchronized on-premises and cloud tiers balance latency-sensitive operations against elastic capacity. Mittelstand manufacturers in Bavaria synchronize shop-floor document capture with cloud-based supplier portals, though integration engineering inflates total cost of ownership.
- Multi-Cloud:Orchestrated workloads across competing hyperscalers mitigate vendor lock-in and optimize regional latency. Pan-European logistics operators distribute content repositories across AWS, Azure, and Google Cloud to satisfy divergent national data localization mandates.
Leading the category by volume: Public Cloud. Growing fastest: Hybrid Cloud.
End User:
Buyer sophistication and procurement authority concentrate at the enterprise tier, while mid-market segments exhibit fragmented purchasing patterns across IT and line-of-business stakeholders.
- Small Enterprises:Subscription fatigue and limited IT staffing drive preference for pre-configured templates over custom development. Spanish professional services firms and Dutch specialty manufacturers rely on email-to-folder automation and mobile capture applications.
- Medium Enterprises:Manufacturing operations managers in Poland and the Czech Republic now directly evaluate platforms against SAP and Siemens integration rather than deferring to centralized IT procurement.
- Large Enterprises:Complex governance requirements and multi-jurisdictional operations necessitate dedicated compliance engineering. French pharmaceutical manufacturers and Swiss banking conglomerates maintain internal centers of excellence for content platform administration.
- Government Agencies:Sovereign cloud mandates and classified information handling impose dedicated instance requirements. German federal ministries and Italian regional health authorities specify NATO RESTRICTED certification and domestic data center presence.
Dominating procurement value: Large Enterprises. Expanding most quickly: Medium Enterprises.
Application:
Functional depth determines margin capture, with workflow automation embedding into operational expenditure reduction narratives while document management faces commoditization pressure.
- Document Management:Version control, metadata indexing, and role-based access form the foundational content layer. Healthcare providers in Munich and Hamburg deploy cloud-native repositories to unify patient records under HIPAA and BfArM retention frameworks.
- Workflow Automation:Low-code process orchestration embedded within content platforms captures budgets previously allocated to separate business process management suites. Automotive quality engineers in Wolfsburg automate supplier documentation approval chains to accelerate electric vehicle certification timelines.
- Digital Asset Management:Structured repositories for rich media with automated transcoding and rights management. Marketing organizations in Paris and Milan centralize campaign assets across distributed agency networks.
- Records Management:Long-term retention with legal hold and disposition scheduling for regulatory compliance. Insurance carriers in Zurich and Luxembourg maintain immutable audit trails for Solvency II and DORA documentation requirements.
Commanding premium margins: Workflow Automation. Gaining share fastest: Records Management.
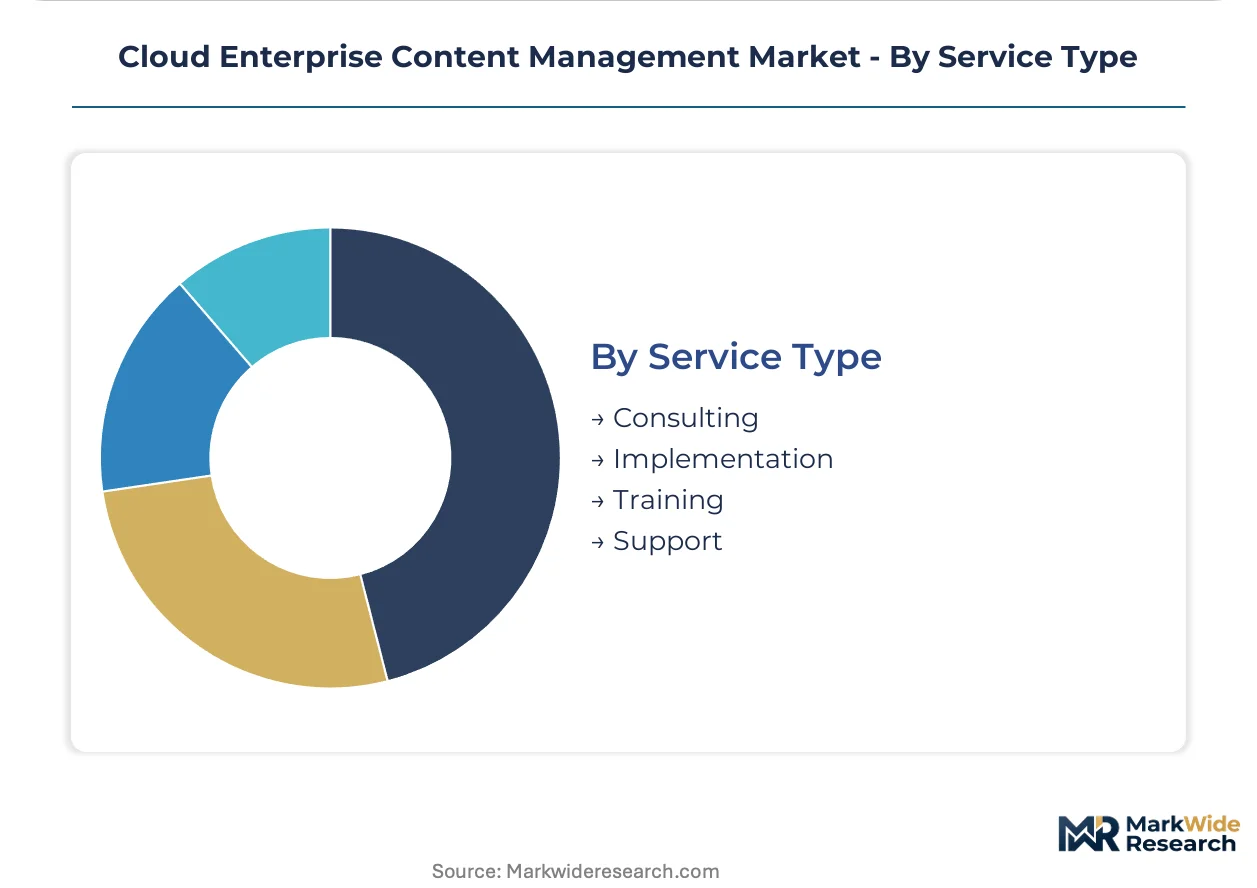
Service Type:
Revenue recurrence and margin stability vary sharply across project-based implementation and recurring support engagements.
- Consulting:Migration assessment and governance framework design for complex enterprise transformations. Boutique practices in Berlin and Paris specialize in EU AI Act readiness evaluations for automated content classification systems.
- Implementation:System integration, data migration, and custom connector development. Systems integrators in London and Amsterdam compete on pre-built adapters to SAP, Salesforce, and Dassault Systèmes environments.
- Training:Change management and user adoption programs for decentralized workforces. Vendors deliver localized curricula in German, French, and Italian to satisfy works council consultation requirements.
- Support:Tiered response commitments with dedicated technical account management. Financial services clients in Frankfurt negotiate 15-minute severity-one response SLAs for trading floor document access.
Generating highest recurring revenue: Support. Steepest expansion trajectory: Consulting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European Cloud ECM procurement intensity, with Mittelstand automotive suppliers digitizing quality documentation under EU AI Act mandates. German Federal Data Protection Authority enforcement drives replacement of legacy archives across Baden-Württemberg manufacturing corridors.
United States
Healthcare systems in Boston and Minneapolis deploy cloud-native repositories for HIPAA-compliant patient record unification. SEC cybersecurity disclosure rules elevate auditability specifications for financial services procurement in New York and Chicago. Pharmaceutical manufacturers in Research Triangle Park digitize clinical trial documentation under FDA 21 CFR Part 11 frameworks.
Germany
BaFin supervision drives private cloud mandates for Frankfurt banking conglomerates handling classified documentation. Stuttgart automotive suppliers automate supplier quality records under ISO/TS 16949 traceability requirements for electric vehicle supply chains. Bavarian manufacturing operations synchronize shop-floor document capture with cloud-based supplier portals despite hybrid integration cost inflation.
France
CNIL data localization requirements fragment cloud architectures for Paris-based pharmaceutical manufacturers preparing EMA regulatory submissions. Healthcare providers in Lyon and Marseille unify patient records under HIPAA-equivalent HDS certification standards. Insurance carriers in La Défense district maintain immutable audit trails for Solvency II documentation under DORA operational resilience mandates.
Switzerland
Swissmedic regulatory requirements drive records management specialization for Basel pharmaceutical manufacturers. Zurich banking conglomerates demand dedicated instance architectures with NATO RESTRICTED certification for classified information handling. Geneva private wealth managers deploy multi-cloud orchestration across AWS, Azure, and Google Cloud to optimize regional latency.
United Kingdom
London financial services firms navigate post-Brexit divergence between UK GDPR and EU AI Act compliance obligations. NHS trusts in Manchester and Birmingham accelerate cloud-native document management for patient record digitization. Cambridge biotechnology clusters pilot retrieval-augmented generation systems for regulatory submission preparation under MHRA frameworks.
Cloud Enterprise Content Management Market Vendor Landscape
Premium-margin players sit above commodity-margin players across algorithmic transparency and compliance engineering depth. The vendor base stratifies between hyperscaler-integrated suites, vertical specialists in regulated industries, and API-first developers embedding into SaaS workflows. Three archetypes dominate: compliance-heavy incumbents defending financial services accounts, cloud-native challengers capturing mid-market manufacturing, and platform extenders leveraging existing productivity suite relationships. Competitive intensity concentrates on M&A absorption of workflow automation capabilities and strategic partnerships with industrial software vendors.
Within the compliance-heavy tier, OpenText Corporation and Hyland Software, Inc. exemplify vendors sustaining dominance through deep records governance tooling. Microsoft Corporation anchors the premium-integration vector, leveraging productivity suite relationships to embed generative document intelligence. Box, Inc. occupies the API-first position, specializing in developer-centric architectures for line-of-business procurement outside centralized IT control.
| Leading Market Players |
|---|
| Microsoft Corporation |
| OpenText Corporation |
| IBM Corporation |
| Oracle Corporation |
| Hyland Software, Inc. |
| Box, Inc. |
| Alfresco Software, Inc. |
| Adobe Inc. |
| Laserfiche |
| Others |
Supply Flow & Price Mechanics
Large enterprise procurement committees in Frankfurt and Paris concentrate purchasing authority for cloud ECM platforms, anchoring market-wide pricing to value-based outcomes rather than per-seat metrics. This buyer concentration compresses margins for mid-tier vendors while rewarding compliance-heavy incumbents with pricing power tied to audit trail guarantees.
Pricing Analysis
Value-based pricing tied to workflow automation outcomes dominates enterprise procurement, with German automotive suppliers and French pharmaceutical manufacturers paying premiums for guaranteed uptime SLAs and EU AI Act auditability. Price differentiation separates ISO 27001-certified sovereign cloud tiers from commodity public cloud storage, with customization depth and dedicated instance requirements driving tier separation. Pricing pressure stems from hyperscaler-native offerings bundling basic document management at marginal cost, eroding standalone repository margins. Mid-market manufacturing operations managers in Bavaria and Rhineland-Palatinate exhibit highest price sensitivity, while Frankfurt financial institutions under BaFin supervision show lowest elasticity for compliance-guaranteed deployments.
Supply Chain Analysis
Hyperscaler infrastructure supply rests on concentrated data center capacity in Germany, Ireland, and the Netherlands, with AWS, Azure, and Google Cloud anchoring European cloud compute availability. Software development draws from engineering talent clusters in Berlin, Paris, and London, while compliance engineering and EU AI Act documentation expertise concentrates in Frankfurt and Brussels. Supply chain risk centers on single-source vulnerability for specialized sovereign cloud hardware certified to NATO RESTRICTED standards. Distribution runs through direct enterprise sales teams for large accounts and hyperscaler marketplaces for mid-market self-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
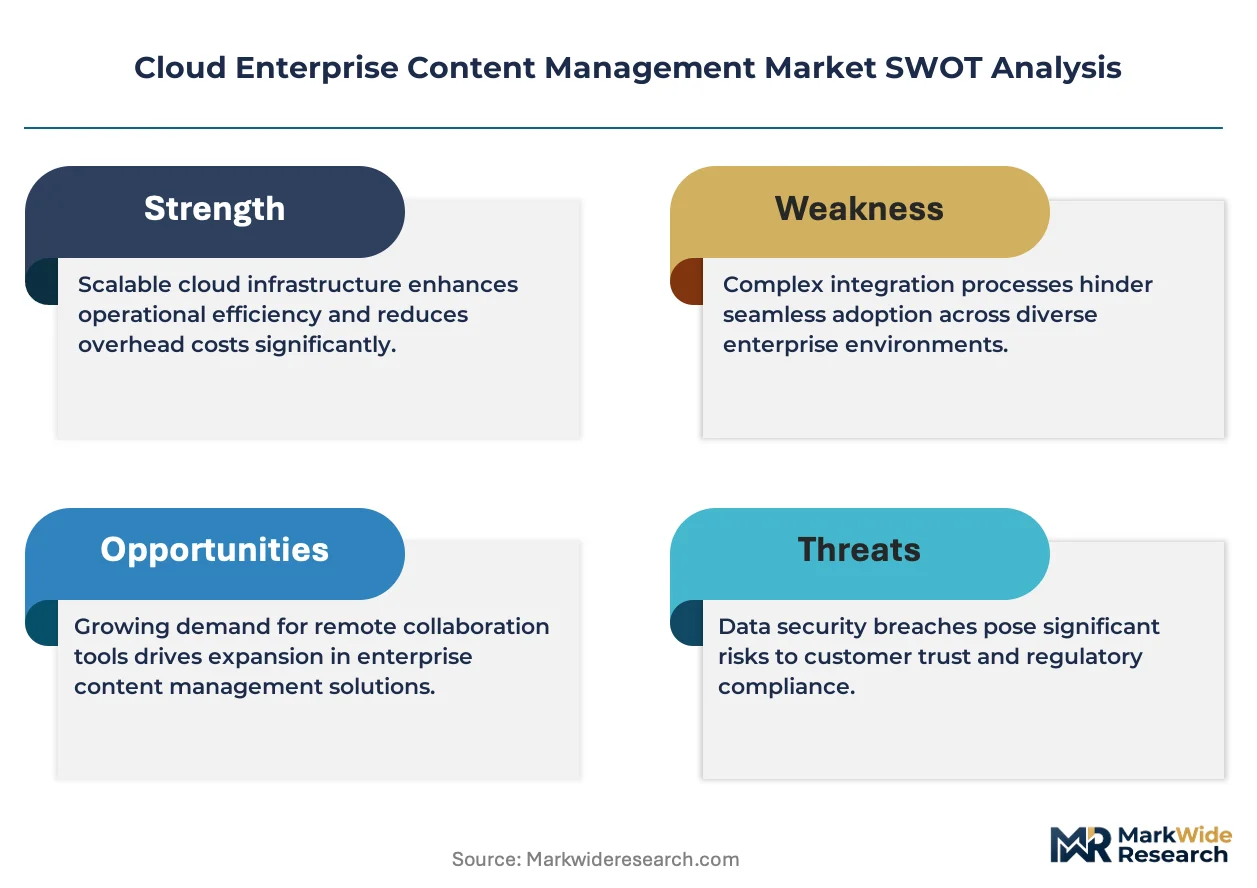
Cloud ECM vendor capacity to deliver EU AI Act-compliant audit trails operates as the binding constraint propping pricing premiums, with algorithmic transparency engineering timelines extending 12-18 months and limiting near-term competitive entry.
For Market Incumbents: Cement dominance in regulated verticals by acquiring workflow automation specialists to deepen operational expenditure capture, while investing in dedicated instance architectures for defense and financial services accounts threatened by sovereign cloud mandates. Prioritize backward integration into compliance documentation tooling to defend margin position against hyperscaler bundle erosion. For New Entrants and Emerging Players: Begin with API-first architectures targeting line-of-business procurement outside centralized IT control, focusing on manufacturing operations managers in Poland and the Czech Republic seeking SAP and Siemens integration without enterprise sales cycle overhead. Pursue greenfield deployment in Spanish professional services firms and Dutch specialty manufacturers still dependent on file shares. For Investors and Strategic Acquirers: The window for entry favors workflow automation specialists with pre-built industrial connectors and EU AI Act readiness tooling, as compliance engineering scarcity extends competitive moats. Watch retrieval-augmented generation pilot adoption rates in German automotive quality engineering and Swiss pharmaceutical regulatory affairs as inflection indicators for generative document intelligence demand.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | BaFin and CNIL procurement gates now mandate algorithmic auditability for automated classification systems. |
| Workflow Automation Acquisition | Low-code process orchestration embedded in content platforms captures business process management budgets. |
| Sovereign Cloud Infrastructure Buildout | Dedicated instance architectures satisfy NATO RESTRICTED requirements for Stuttgart defense contractors. |
| Industrial Software Partnership | Pre-built connectors to Siemens, SAP, and Dassault Systèmes accelerate Mittelstand manufacturing adoption. |
| Retrieval-Augmented Generation Deployment | Contextual synthesis across document corpora compresses root-cause analysis timelines for automotive engineers. |
Methodological Framework
Independent corroboration across CTOs at German automotive suppliers, compliance officers at Frankfurt financial institutions, IT procurement leads at French pharmaceutical manufacturers, and platform engineers at cloud-native challengers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from SEC filings, hyperscaler capex disclosures, EU regulatory documentation, and hospital procurement databases established demand-side parameters. Bottom-up deployment estimates triangulated against top-down market sizing across deployment model, organization scale, vertical application, and regional adoption pattern dimensions.
Comparable-period anchoring to historical ECM migration cycles and cloud infrastructure adoption curves structured the projection horizon. The analytical framework modeled segmentation across public, private, hybrid, and multi-cloud deployment architectures; small, medium, large, and government end-user tiers; and document management, workflow automation, digital asset management, and records management applications. CAGRs derived from elasticity-adjusted penetration curves incorporating EU AI Act compliance deadline effects and healthcare digitization funding trajectories.
Regulatory enforcement variance, hyperscaler pricing aggression, and generative AI capability maturation are the dominant revision risks to modeled outcomes. Forecasts embed assumptions about sovereign cloud mandate expansion and workflow automation convergence timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Computing Stack Layers Market
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
Canada Cloud Computing Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Hybrid Cloud in BFSI Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
AI Platform Cloud Service Market
Cloud Computing
Cloud-Based Repository Services Market
Cloud Computing
Japan Cloud Computing Market
Cloud Computing
Cloud-Managed LAN Market
Cloud Computing
Global Distributed Cloud Market
Cloud Computing
Cloud Based Backup Services Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
SME Cloud Market
Cloud Computing
Cloud Enablement Market
Cloud Computing
Multi-Cloud Optimization Tools Market