
 Cloud Directory Services Market | 2026-2036
Cloud Directory Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Directory Services Market Outlook
North American hyperscaler infrastructure is expanding to accommodate enterprise directory workloads at scale. Microsoft Corporation leverages its Entra ID platform to anchor hybrid identity deployments across Fortune 500 environments. Amazon Web Services (AWS) competes through deep integration with its broader cloud ecosystem, while Okta specializes in vendor-neutral SSO and lifecycle automation for multi-vendor stacks.
Cloud directory services constitute centralized identity repositories that authenticate users, devices, and applications through protocols including LDAP, SAML, and SCIM, with replication latencies typically under 100 milliseconds for distributed architectures. Public cloud deployments dominate volume due to lower capital barriers and faster provisioning cycles, though hybrid cloud configurations capture disproportionate margin pools from regulated enterprises maintaining on-premises legacy bindings. Identity Management leads service type revenue by addressing privileged access and compliance auditing requirements.
The US Federal Risk and Authorization Management Program (FedRAMP) and the EU Cybersecurity Act shape product certification requirements, with FedRAMP authorization gating federal agency procurement and the Cybersecurity Act mandating CE marking for critical infrastructure operators. ISO/IEC 27001 and NIST SP 800-63 provide baseline identity assurance frameworks that vendors must map against to satisfy enterprise security reviews. Stakeholders must weigh vendor lock-in risks against interoperability demands as multi-cloud strategies proliferate.
Market Dynamics
Healthcare provider networks are accelerating migration to cloud-native identity infrastructure, driven by the EU AI Act and NIS2 Directive tightening access-control mandates for critical service operators. This regulatory pressure is forcing consolidation of fragmented identity systems into unified cloud directories.
Growth Catalysts
- EU AI Act mandates:Critical infrastructure operators must deploy centralized identity governance, creating immediate procurement pull for cloud directory platforms with automated compliance auditing.
- Industrial conglomerates in Germany:Manufacturing giants are unifying disparate legacy identity silos into single cloud-native repositories to reduce operational overhead.
- Zero Trust architecture adoption:Enterprise security teams are replacing perimeter-based models with continuous verification frameworks requiring real-time directory synchronization.
Market Restraints
- FedRAMP authorization timelines:Federal contractors face 12-18 month certification cycles that delay revenue recognition and strain working capital.
- Legacy LDAP binding dependencies:Regulated enterprises maintain on-premises authentication hooks that resist full cloud migration.
- Skilled identity architect shortage:Implementation of SCIM provisioning and SAML federation protocols requires specialized expertise concentrated in coastal technology hubs.
Strategic Opportunities
- Machine-to-machine authentication expansion:IoT device fleets in automotive and energy sectors require non-human identity lifecycle management.
- India's digitization push:The country's PLI scheme for cloud infrastructure is attracting hyperscaler investment in local directory service nodes.
- Convergence of identity and data governance:Unified platforms combining access control with data residency compliance are displacing point solutions.
Industry Challenges
- Multi-cloud interoperability gaps:Directory synchronization across AWS, Azure, and Google Cloud environments introduces latency and conflict resolution complexity.
- ISO/IEC 27001 audit preparation:Certification timelines compress delivery schedules and require dedicated compliance engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Directory Services Market |
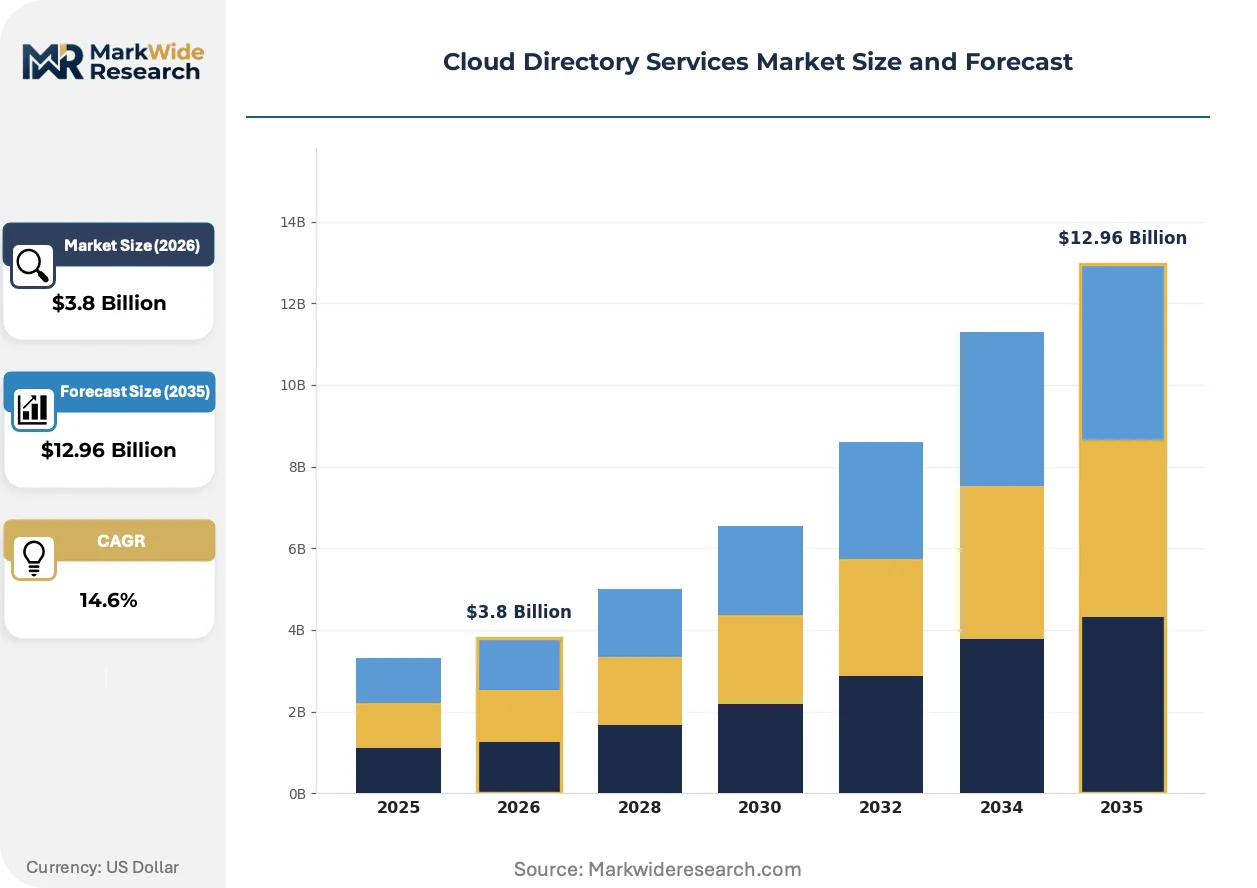
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Identity Management, Access Management, Directory Synchronization, User Provisioning End User: Small Enterprises, Medium Enterprises, Large Enterprises, Government Agencies Integration Type: API Integration, On-Premises Integration, Cloud Sync, Third-Party Integration |
| Companies Covered | International Business Machines (IBM), Ping Identity, Amazon Web Services (AWS), Deloitte, JumpCloud, Microsoft Corporation, Okta, Accenture, Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Directory Services Market Strategic Shifts
Identity infrastructure is undergoing fundamental architectural transformation as distributed workforces and automated service meshes demand real-time authentication at scale. Three forces are reshaping how organizations deploy and consume directory services.
Passwordless authentication using FIDO2 standards is converging with hardware security key deployments. Financial services institutions in Singapore and Switzerland are piloting biometric-backed FIDO2 implementations for privileged access scenarios. This convergence is compressing time-to-authentication while eliminating credential theft vectors.
The EU Cybersecurity Act now mandates CE marking for identity management systems serving critical infrastructure operators. Product manufacturers must demonstrate conformity with EN 303 645 baseline security requirements before market entry. German energy utilities and French healthcare networks are prioritizing pre-certified directory platforms to accelerate procurement cycles.
Consumption-based pricing for directory services is displacing traditional per-seat licensing in enterprise procurement. Mid-market technology firms in the Netherlands and Denmark are negotiating usage-tiered contracts tied to monthly active authentication events. This shift is most visible among SaaS-native companies with seasonal workforce fluctuations.
Cloud Directory Services Market Segmentation
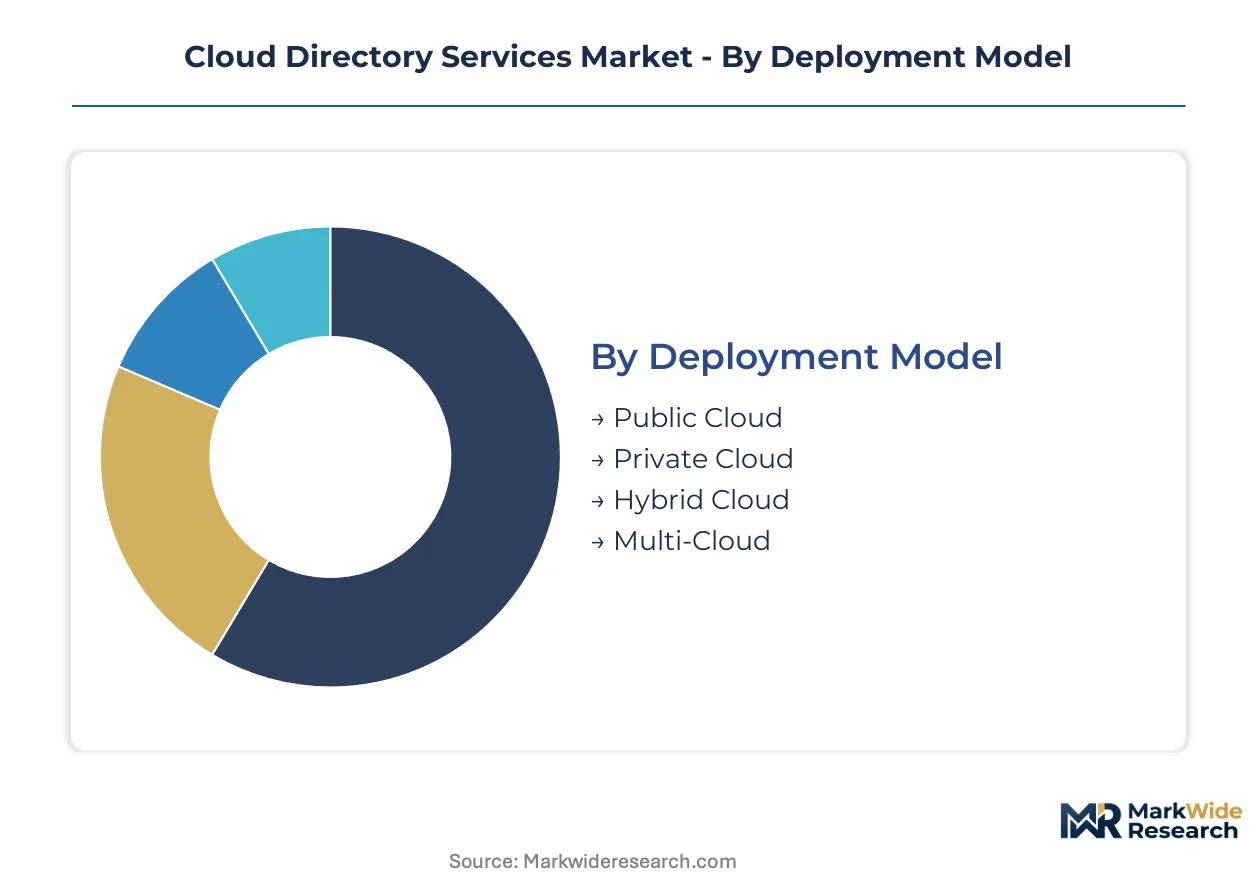
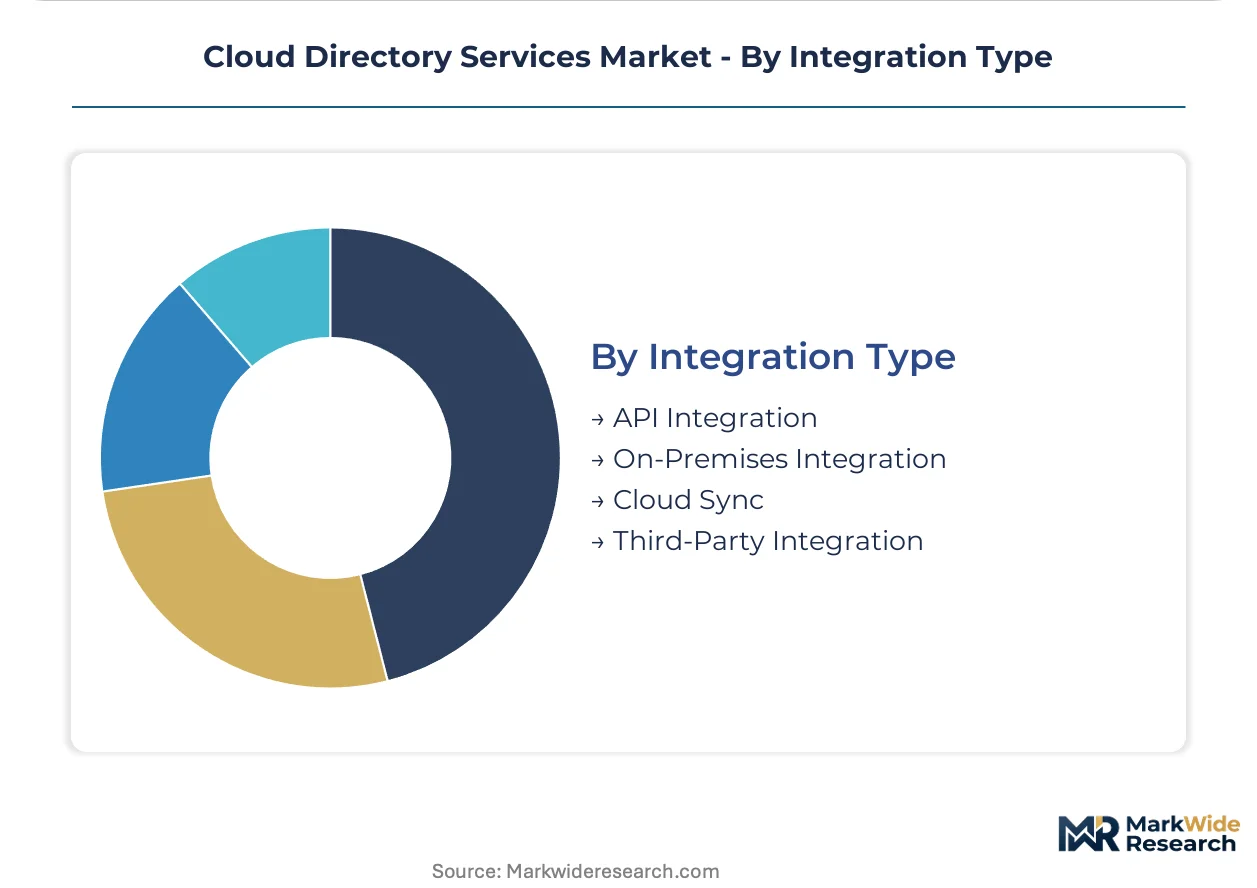
Cloud directory architectures fragment across four distinct segmentation axes that determine procurement priorities, integration complexity, and compliance burden. Deployment topology dictates latency profiles and data residency constraints. Service type selection reveals whether buyers prioritize governance automation or authentication throughput. End-user scale shapes licensing models and support tier requirements. Integration architecture determines migration path feasibility for legacy-bound enterprises.
Deployment Model:
Deployment topology defines the fundamental infrastructure boundary between vendor-managed control planes and customer-retained sovereignty over credential stores.
- Public Cloud:Fully managed directory instances hosted on hyperscaler infrastructure eliminate capital expenditure for hardware provisioning. German automotive suppliers and Dutch SaaS startups favor this model for sub-hour provisioning of global user bases under EU GDPR data processing agreements.
- Private Cloud:Dedicated single-tenant directory deployments on customer-controlled infrastructure preserve complete isolation of authentication logs. French defense contractors and Swiss private banks mandate this architecture to satisfy national security clearance requirements for classified project access.
- Hybrid Cloud:Synchronized identity repositories spanning on-premises Active Directory and cloud-native Entra ID instances. US healthcare networks deploy this configuration to maintain HIPAA-compliant local authentication for clinical workstations while enabling cloud SSO for administrative staff.
- Multi-Cloud:Federated directory services operating across AWS, Azure, and Google Cloud environments without single-vendor dependency. Japanese manufacturing conglomerates adopt this pattern to avoid concentration risk in vendor-specific identity stacks.
Public Cloud leads on scale; Multi-Cloud leads on momentum.
Service Type:
Functional specialization within directory platforms separates governance-heavy deployments from throughput-optimized authentication pipelines.
- Identity Management:Lifecycle automation for user onboarding, role transitions, and termination workflows with embedded compliance auditing. Critical infrastructure operators under EU NIS2 Directive procurement mandates prioritize these capabilities for privileged access certification.
- Access Management:Real-time policy enforcement for application and resource authorization decisions. Singaporean financial institutions deploy these services to satisfy MAS Technology Risk Management Guidelines for customer-facing digital channels.
- Directory Synchronization:Bidirectional replication engines maintaining consistency across heterogeneous identity stores. Energy utilities in Texas and Alberta rely on these tools to unify operational technology and IT directory silos.
- User Provisioning:Automated account creation and attribute mapping via SCIM protocol implementations. Mid-market technology firms in Denmark and the Netherlands negotiate usage-based contracts tied to monthly provisioning event volumes.
Identity Management commands the largest contract values; User Provisioning is climbing the fastest as SaaS-native companies scale headcount variably.
End User:
Organizational scale determines support model expectations, compliance granularity, and pricing negotiation leverage.
- Small Enterprises:Directory deployments under 500 seats typically consume managed identity services through bundled Microsoft 365 or Google Workspace subscriptions. Limited internal security expertise drives preference for vendor-operated control planes.
- Medium Enterprises:Organizations between 500 and 5,000 employees represent the fastest-expanding segment for standalone cloud directory procurement. India's PLI scheme beneficiaries in cloud infrastructure are building local service nodes to capture this demand tier.
- Large Enterprises:Global conglomerates with 50,000-plus users require dedicated identity architect resources and custom SLA negotiations. Industrial manufacturers in Germany consolidate fragmented legacy silos into unified repositories to reduce operational overhead.
- Government Agencies:Federal and state entities impose FedRAMP authorization or national equivalent certification requirements. US contractors face 12-18 month approval timelines that strain working capital during procurement cycles.
Large Enterprises dominate absolute spending; Medium Enterprises show the steepest expansion trajectory.
Integration Type:
Connectivity architecture determines migration feasibility for organizations with decades of legacy authentication binding investments.
- API Integration:RESTful directory service endpoints enabling custom application authentication without protocol translation layers. Developer-centric firms in Israel and Estonia favor this model for microservices mesh identity injection.
- On-Premises Integration:LDAP proxy and Active Directory Federation Services bridging to cloud identity providers. Regulated US healthcare and financial services maintain these bindings for legacy clinical and core banking systems resistant to full cloud migration.
- Cloud Sync:Native replication protocols between cloud-native directory instances and SaaS application identity stores. This pattern dominates among organizations born in the cloud without legacy binding dependencies.
- Third-Party Integration:Pre-built connectors to HR systems, SIEM platforms, and IT service management tools. Enterprise buyers prioritize vendor marketplaces with 500-plus certified integrations to reduce custom development burden.
On-Premises Integration retains the largest installed base; API Integration is gaining share fastest among cloud-native development teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping procurement patterns as enterprises migrate identity workloads toward jurisdictions with streamlined compliance pathways. Cost-of-compliance gaps between FedRAMP-authorized US environments and CE-marking regimes in Europe are accelerating cross-border vendor selection.
United States
Federal contractors dominate enterprise procurement through FedRAMP-authorized platforms. HIPAA binds healthcare networks to maintain hybrid architectures for clinical authentication. Texas energy utilities and California technology clusters are consolidating fragmented LDAP silos into unified cloud repositories.
Germany
Industrial conglomerates in automotive and machinery sectors are unifying legacy identity systems. The EU AI Act and NIS2 Directive mandate centralized access governance for critical infrastructure operators. Bavarian manufacturing hubs and North Rhine-Westphalian chemical clusters are prioritizing pre-certified directory platforms.
United Kingdom
Financial services institutions in London are piloting FIDO2 passwordless implementations for privileged access. The UK National Cyber Security Centre guidelines align with ISO/IEC 27001 assurance frameworks. Fintech clusters in Manchester and Edinburgh are negotiating usage-based directory contracts.
India
PLI scheme beneficiaries in cloud infrastructure are building local directory service nodes for mid-market demand. The country's digitization push requires scalable identity provisioning for government service portals. Bengaluru and Hyderabad technology corridors are absorbing hyperscaler investment in regional identity nodes.
Japan
Manufacturing conglomerates are deploying multi-cloud directory configurations to avoid vendor concentration risk. METI guidelines on critical infrastructure cybersecurity shape procurement specifications. Tokyo and Osaka industrial clusters are federating identity systems across operational technology and IT environments.
Cloud Directory Services Market Competitive Environment
US-based hyperscalers anchor one tier; European and Israeli specialists hold differentiated positions in compliance-heavy segments. Market structure tilts toward consolidation as platform breadth determines procurement outcomes. Three archetypes dominate: infrastructure-anchored suites, identity-native specialists, and systems integrators with implementation depth. Competitive moves center on FedRAMP certification acceleration and API ecosystem expansion.
Among infrastructure-anchored providers, Microsoft Corporation and Amazon Web Services exemplify platform bundling strategies that embed directory services within broader cloud consumption. Okta occupies a position as the vendor-neutral specialist for multi-cloud SSO and lifecycle automation. IBM represents the systems integrator archetype, combining implementation services with proprietary directory technology for regulated enterprise deployments.
| Leading Market Players |
|---|
| International Business Machines (IBM) |
| Ping Identity |
| Amazon Web Services (AWS) |
| Deloitte |
| JumpCloud |
| Microsoft Corporation |
| Okta |
| Accenture |
| Google LLC |
| Others |
Value Chain & Pricing Dynamics
Consumption-based pricing models for directory services are displacing legacy per-seat licensing, compressing vendor margins while hyperscaler infrastructure investments concentrate supply capacity in Germany, the United States, and India. This shift simultaneously reshapes cost economics for SaaS-native buyers and consolidates provisioning leverage among cloud-native platform operators.
Pricing Analysis
Distributor margins in enterprise software procurement typically capture 15-25 percent of contract value before reseller discounts apply. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance certification tier—FedRAMP-authorized deployments command substantial premiums over baseline ISO/IEC 27001 configurations. Cost compression in mid-market segments intensifies as India's PLI scheme beneficiaries expand local service nodes. Small enterprises exhibit highest price sensitivity, while government agencies prioritize certification assurance over unit cost.
Supply Chain Analysis
FedRAMP authorization and CE marking under the EU Cybersecurity Act gate market entry for directory platform vendors, creating qualification bottlenecks that concentrate certified supply among incumbent hyperscalers. Infrastructure provisioning draws from data center investments in the United States, Germany, and India, with identity synchronization protocols resting on open standards development anchored in IEEE and IETF working groups. Single-source vulnerability emerges from hyperscaler concentration in authentication API delivery. Distribution runs through direct enterprise sales organizations and systems integrator partnerships for regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between FedRAMP-authorized US environments and CE-marking regimes in Europe creates procurement cost differentials exceeding 30 percent for equivalent compliance tiers, rewarding vendors with dual-certification capabilities.
For Market Incumbents: Hedge against hyperscaler bundling by accelerating API ecosystem expansion and securing FedRAMP High authorization ahead of federal procurement cycles. Invest in vertical-specific compliance engineering for EU NIS2 Directive implementations to defend margin position against platform commoditization. For New Entrants and Emerging Players: Launch via usage-based pricing models targeting mid-market technology firms in the Netherlands and Denmark with seasonal workforce volatility. Prioritize SCIM provisioning automation and HR system connectors as the most penetrable functional wedge against incumbent suite bundling. For Investors and Strategic Acquirers: Valuations sit cheapest among private-cloud directory specialists with national security clearances and limited hyperscaler exposure. Long-term viability hinges on convergence of identity governance with data residency compliance platforms. Monitor FedRAMP authorization backlog clearance rates as inflection signal for federal procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP High Authorization | Unlocks federal agency procurement pipelines under 12-18 month certification cycles. |
| CE Marking Pathway | Accelerates EU critical infrastructure operator sales under Cybersecurity Act mandates. |
| API Ecosystem Expansion | Reduces customer switching costs through 500-plus certified third-party connectors. |
| Machine-to-Machine Identity Launch | Captures IoT device fleet authentication demand from automotive and energy sectors. |
| Strategic Partnership with Systems Integrators | Penetrates regulated healthcare and financial services through implementation depth. |
Study Parameters
Direct dialogue with identity architects, CISOs at industrial conglomerates, federal procurement officers, cloud infrastructure engineers, and compliance auditors grounded qualitative findings in operational reality. Secondary validation drew from FedRAMP authorization databases, EU NIS2 implementation guidance, hyperscaler capex disclosures, and ISO/IEC 27001 certification registries. Bottom-up deployment model sizing triangulated against top-down enterprise IT spending allocations across the analysis window.
Bottom-up modeling segmented the market by deployment topology, service type functional specialization, organizational scale tier, and integration architecture complexity. Top-down validation cross-referenced regulatory mandate timelines against procurement cycle data from critical infrastructure operators. CAGR derivation incorporated technology substitution curves for passwordless authentication and machine-to-machine identity lifecycle expansion throughout the forecast period.
Several conditions sit outside the modeled scope, including quantum-resistant cryptographic migration timelines and sovereign cloud mandate variations by EU member state. Forecasts reflect assumptions regarding FedRAMP authorization velocity and CE marking harmonization across European national implementations. Deviation in EU AI Act enforcement intensity or NIS2 Directive transposition delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
Public Cloud Application Infrastructure Services Market
Cloud Computing
Global Mobile Cloud Market
Cloud Computing
North America Healthcare Cloud Computing Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Global Cloud Collaboration Market
Cloud Computing
Cloud Integration Software Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Cloud Enterprise Content Management Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Japan Cloud Computing Market
Cloud Computing
North America Mobile Cloud Market
Cloud Computing
Europe Cloud Managed Networking Market
Cloud Computing
AI and Blockchain Cloud Services Market
Cloud Computing
South Korea Cloud Computing Market