
 Europe Data Center Storage Market | 2026-2036
Europe Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Center Storage Market Insights
QLC NAND is decoupling enterprise storage economics from traditional HDD cost curves by delivering denser bit-per-cell architectures at lower cost-per-terabyte points. Dell Inc. leverages its PowerMax and PowerStore portfolios to dominate high-performance transactional workloads across European financial hubs. Pure Storage differentiates through its Evergreen subscription model, which sustains recurring revenue streams while minimizing hardware refresh cycles for continental enterprise customers. Hewlett Packard Enterprise anchors its position through GreenLake as-a-service deployments, competing directly with capex-light consumption models favored by mid-market adopters.
Europe data center storage encompasses electromechanical and solid-state systems engineered for persistent data retention, typically specified by IOPS density, latency thresholds below 5 milliseconds, and endurance ratings measured in drive writes per day. These systems serve as the foundational tier for enterprise applications ranging from real-time analytics to regulatory archive compliance. All-flash arrays now command the premium performance tier as NAND flash costs decline, while hybrid storage configurations retain structural importance for tiered workloads balancing hot and cold data access patterns. Object storage architectures are gaining share in unstructured data environments, displacing traditional NAS approaches for media archives and backup repositories across the region.
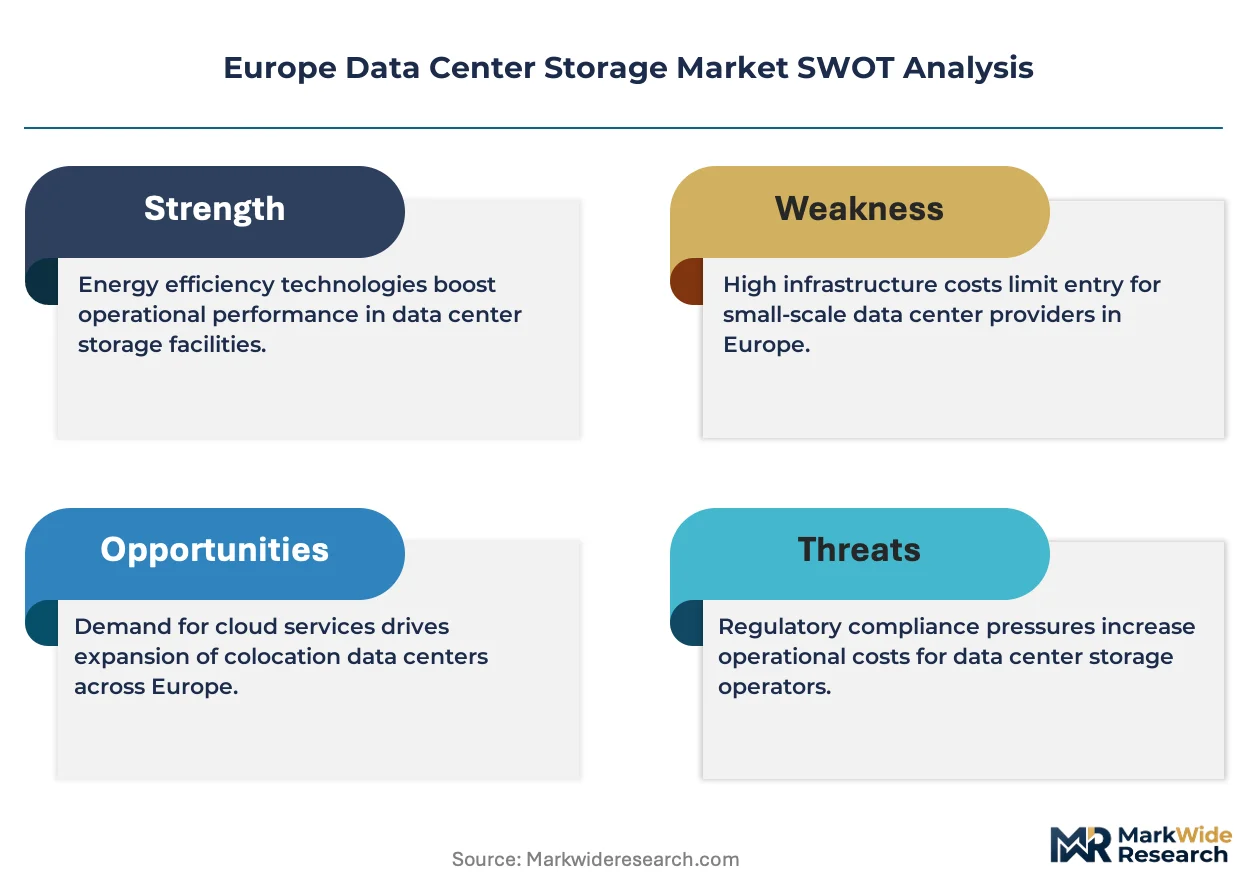
The EU AI Act imposes data governance requirements that directly shape storage procurement criteria, mandating traceability and auditability for training datasets that influence algorithmic decision systems. Ecodesign for Sustainable Products Regulation pressures vendors to disclose embodied carbon metrics, altering competitive positioning for equipment with extended operational lifespans. GDPR retention and erasure mandates continue to dictate encryption standards and geographic data placement decisions. Stakeholders must weigh sovereignty-compliant deployment models against cloud-native scalability as regulatory fragmentation between member states intensifies.
Market Dynamics
QLC NAND bit-density improvements are compressing all-flash array cost curves below hybrid storage parity points, forcing infrastructure planners across European financial and AI training facilities to recalculate tiered storage economics.
Growth Catalysts
- EU AI Act traceability mandates:Training dataset auditability requirements are compelling hyperscalers and enterprises to deploy compliant, locally governed storage infrastructure with embedded metadata tagging and lineage tracking capabilities.
- Frankfurt and Amsterdam facility concentration:Hyperscaler investments in FLAP markets are generating concentrated demand for high-density electromechanical and solid-state systems with sub-5 millisecond latency specifications.
- Ecodesign for Sustainable Products Regulation:Embodied carbon disclosure obligations are favoring storage equipment with extended operational lifespans, redirecting procurement toward vendors with circular service models.
Market Restraints
- NAND flash supply concentration:Wafer fabrication capacity in East Asian foundries creates exposure to geopolitical disruption and input cost volatility for European array assemblers.
- GDPR geographic placement friction:Cross-border data transfer restrictions complicate centralized storage architectures for multinational enterprises operating across divergent national implementations.
- QLC endurance limitations:Reduced drive writes per day ratings constrain deployment in high-rewrite transactional environments, preserving structural demand for costlier TLC configurations.
Strategic Opportunities
- Poland and Nordic expansion:Underpenetrated secondary markets offer whitespace for sovereign-compliant deployments as German and Dutch facility costs escalate and power availability tightens.
- AI inference edge nodes:Distributed model serving architectures are creating demand for compact, high-IOPS storage at metro edge locations outside traditional hyperscale campuses.
- CSRD-aligned circular service models:Extended producer responsibility frameworks are creating competitive openings for vendors offering hardware refresh minimization through subscription-based maintenance and component upgrade paths.
Industry Challenges
- Legacy SAN integration complexity:Financial services incumbents face friction migrating from Fibre Channel architectures to NVMe-oF fabrics without disrupting millisecond-sensitive trading applications.
- Specialized firmware engineering scarcity:Talent gaps in flash translation layer optimization and endurance management constrain vendor development timelines for differentiated enterprise offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Center Storage Market |
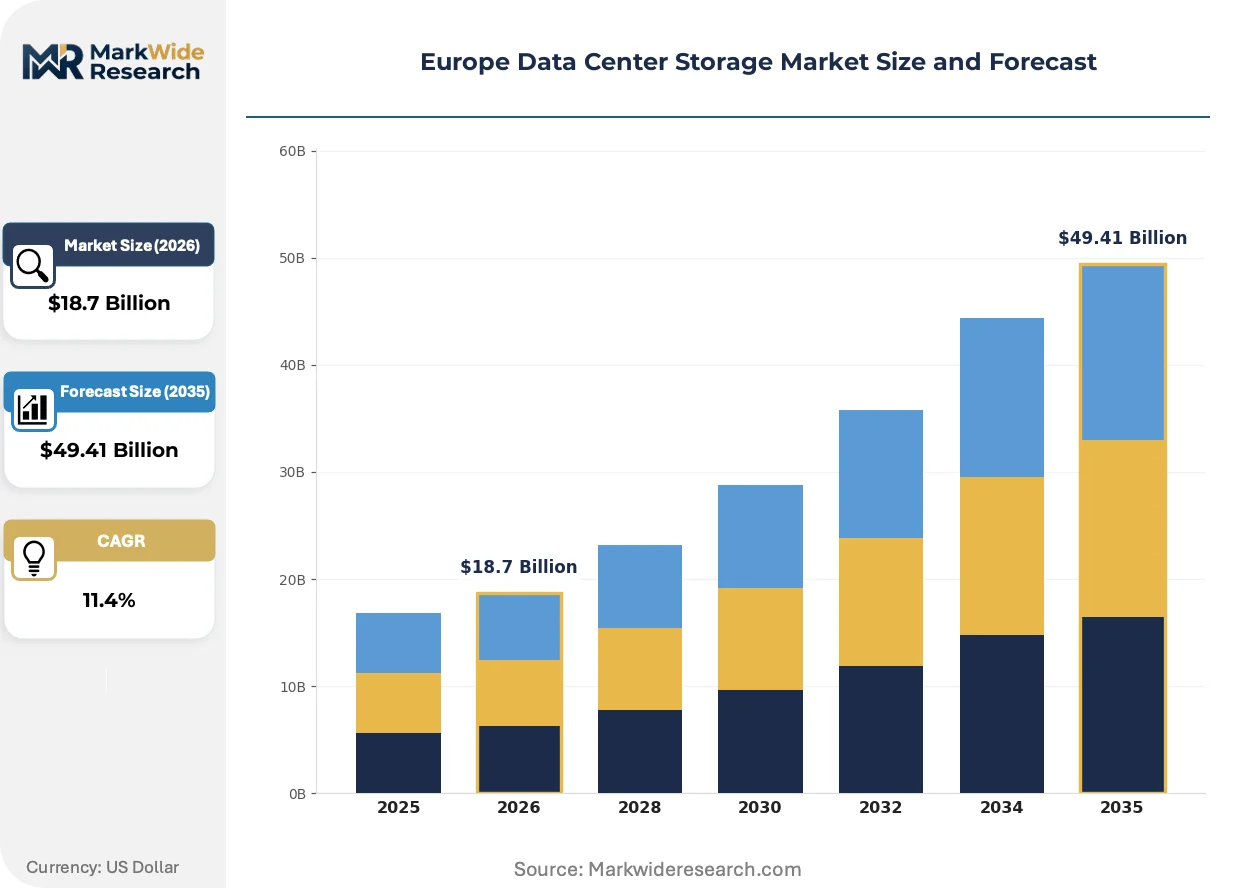
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disk Storage, Tape Storage, All-Flash Storage, Hybrid Storage Technology: SAN, NAS, Object Storage, Cloud Storage End User: Telecommunications, BFSI, Healthcare, Retail Deployment: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud |
| Companies Covered | Dell Inc., Hewlett Packard Enterprise, NetApp Inc., Huawei Technologies Co. Ltd., Hitachi Vantara LLC, Pure Storage, IBM, Western Digital, Nutanix, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Center Storage Market Trends and Innovations
Storage class memory architectures and computational storage processing are converging to reshape how European enterprises handle AI training and real-time analytics workloads, compressing the boundary between memory and persistent tiers.
QLC NAND is expanding into secondary storage tiers previously dominated by nearline hard disk drives, delivering 30-50% cost-per-terabyte advantages at equivalent rack densities. German automotive manufacturers and French pharmaceutical groups are adopting these arrays for warm data lakes and model checkpoint repositories. The technology is expanding into backup and disaster recovery infrastructure, compressing recovery time objectives that HDD-based systems cannot satisfy under EU operational resilience directives.
CSRD sustainability reporting obligations are mandating granular carbon footprint disclosure across storage equipment lifecycles, from wafer fabrication through operational energy consumption to end-of-life processing. Vendors must now provide embodied carbon metrics and power usage effectiveness calculations as standard procurement documentation. Financial services and cloud service providers in the Netherlands and Ireland are prioritizing equipment with verified circular material content and extended depreciation schedules.
Consumption-based pricing models are displacing traditional capital expenditure procurement for mid-market enterprises and public sector bodies across Spain and Italy. Storage-as-a-service contracts with committed capacity tiers and burst provisions are replacing outright hardware purchases, transferring operational risk to vendors while aligning costs to actual utilization patterns. Municipal data centers and regional healthcare networks are the most visible adopters, driven by constrained IT budgets and preference for predictable operational expenditure profiles.
Europe Data Center Storage Market Segmentation
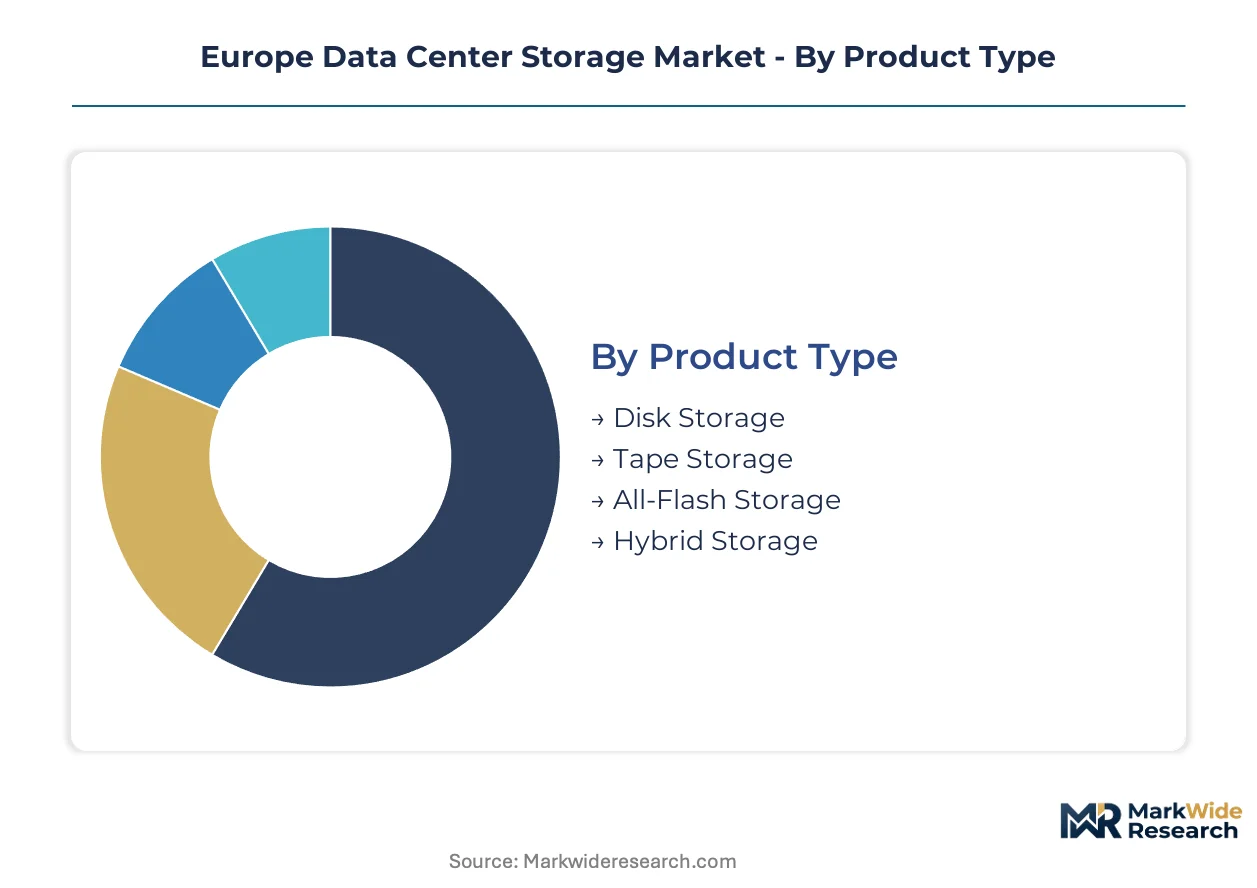
Storage procurement patterns across Europe diverge sharply by workload intensity, regulatory exposure, and infrastructure legacy. Understanding how these dimensions fragment demand enables vendors to align product roadmaps with buyer priorities rather than forcing uniform solutions across incompatible use cases.
Product Type:
Buyers in this category separate by performance tolerance versus cost sensitivity, with latency requirements dictating media selection more than capacity scale.
- All-Flash Storage:NAND-based arrays with NVMe-oF connectivity deliver sub-millisecond response times for algorithmic trading and real-time fraud detection. Frankfurt and Amsterdam financial exchanges are standardizing on these systems as EU AI Act traceability mandates intensify data pipeline velocity requirements.
- Hybrid Storage:Tiered architectures combining flash caching with electromechanical capacity balance hot data access against cold archive economics. German automotive manufacturers deploy these configurations for engineering simulation datasets where 80% of stored bytes remain dormant beyond 90 days.
- Disk Storage:Nearline HDD arrays retain dominance for backup repositories and regulatory archives where retrieval frequency falls below monthly thresholds.
- Tape Storage:LTO-9 libraries persist for long-term compliance archives and air-gapped ransomware recovery across French healthcare networks and Dutch pension funds.
Hybrid configurations lead volumes today; all-flash arrays are gaining share fastest.
Technology:
Architectural choices here reflect data structure complexity and access pattern predictability, with unstructured growth pushing buyers toward scale-out designs.
- Object Storage:Flat-namespace architectures with erasure coding distribute petabyte-scale unstructured datasets across failure domains without hierarchical metadata bottlenecks. French media conglomerates and Scandinavian video streaming platforms are migrating content libraries from NAS to object systems as 4K/8K production volumes explode.
- SAN:Fibre Channel and NVMe-oF fabrics maintain structural importance for transactional databases where block-level consistency and deterministic latency remain non-negotiable. Italian banking cores and Spanish insurance policy systems continue refreshing these investments despite cloud migration pressures.
- NAS:File-level access protocols serve legacy enterprise applications and departmental shares, though growth stalls as object alternatives capture net-new unstructured workloads.
- Cloud Storage:API-managed capacity pools from hyperscalers absorb variable-growth workloads, particularly among mid-market enterprises lacking capital for owned infrastructure expansion.
SAN retains the largest installed base; object storage shows the steepest expansion trajectory.
End User:
Sector-specific regulatory regimes and data gravity requirements create divergent procurement calendars and technical specifications across verticals.
- BFSI:Banks, insurers, and capital markets operators combine millisecond-latency trading infrastructure with multi-decade audit trails. GDPR Article 17 erasure mandates and ECB operational resilience directives force simultaneous investment in high-performance primary systems and immutable archive tiers.
- Healthcare:Hospital networks and pharmaceutical research organizations manage imaging archives and clinical trial datasets with strict ANSM and BfArM data localization requirements. French and German health systems are consolidating radiology PACS onto compliant domestic cloud storage to satisfy patient data sovereignty rules.
- Telecommunications:5G network function virtualization and subscriber data management drive distributed edge storage deployments across national mobile operator footprints.
- Retail:E-commerce platforms and loyalty analytics programs generate seasonal demand spikes that favor consumption-priced cloud capacity over owned infrastructure.
BFSI commands the largest absolute spend; healthcare is expanding most quickly.
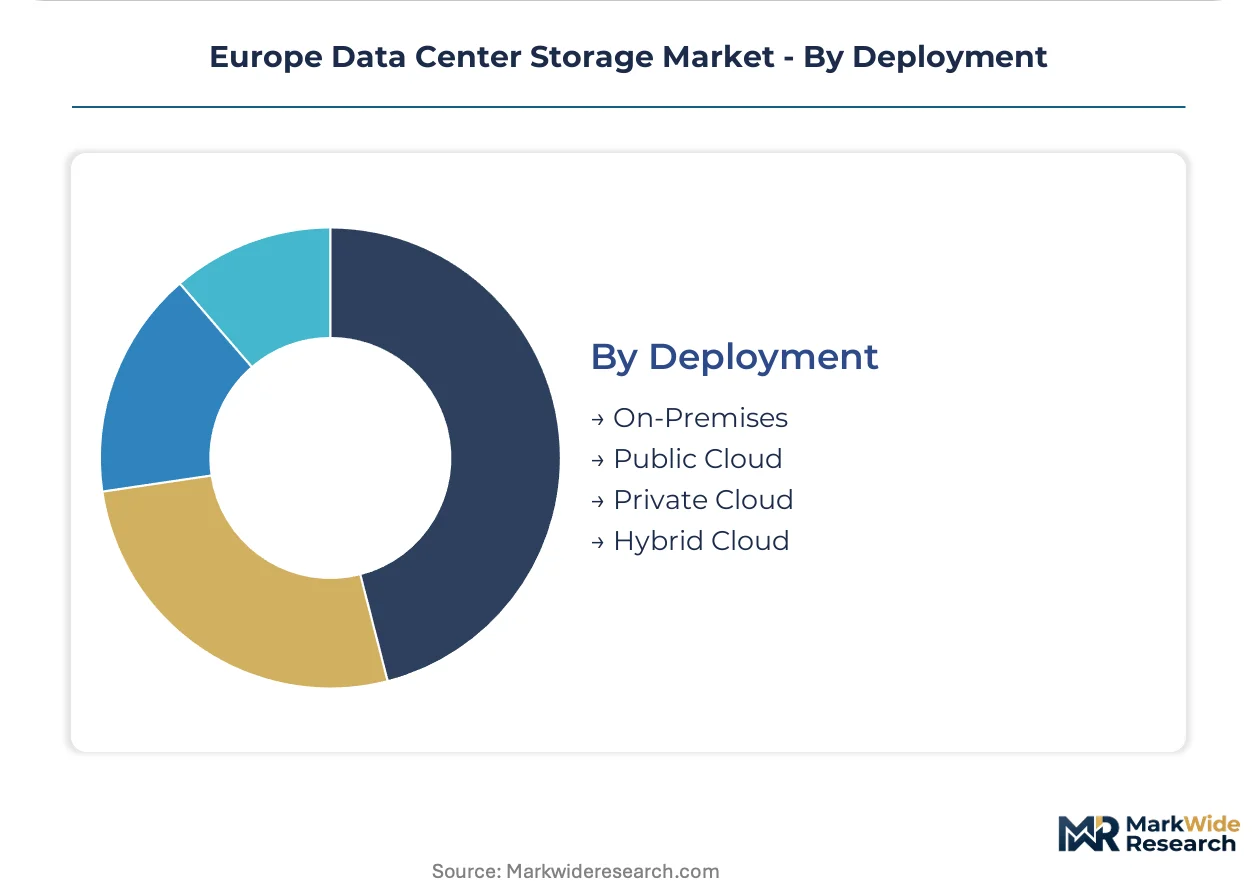
Deployment:
Infrastructure location decisions hinge on data sovereignty risk tolerance, workload predictability, and balance sheet constraints rather than technical capability gaps.
- Private Cloud:Dedicated storage resources within single-tenant facilities address classified government workloads and critical national infrastructure operators. Polish energy utilities and Czech defense contractors are expanding sovereign-compliant private deployments as EU strategic autonomy frameworks harden.
- Public Cloud:Shared hyperscale capacity pools attract variable-growth SaaS providers and mid-market enterprises prioritizing operational expenditure flexibility over capital deployment control.
- On-Premises:Owned data center storage persists for latency-sensitive manufacturing execution systems and regulatory-mandated air-gapped archives.
- Hybrid Cloud:Orchestrated data placement across owned and rented infrastructure enables tiered workload strategies, with hot data on-premises and cold archives in lower-cost cloud tiers.
Private cloud dominates regulated sectors; hybrid cloud is climbing the fastest among enterprises reconciling sovereignty with scalability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors continental demand as hyperscaler facility investments concentrate in the FLAP corridor, with Amsterdam, Paris, and London completing the primary storage deployment cluster.
Germany
Automotive manufacturers and pharmaceutical groups drive demand for QLC NAND arrays and warm data lake infrastructure. BfArM data localization requirements compel domestic cloud storage deployments for clinical trial datasets. Frankfurt's hyperscale campuses absorb the majority of high-density flash and electromechanical system deployments.
Netherlands
Financial services and cloud service providers prioritize equipment with verified circular material content under CSRD sustainability reporting obligations. The national pension regulator mandates granular carbon footprint disclosure across storage lifecycles. Amsterdam's data center corridor ranks second only to Frankfurt in hyperscaler facility concentration.
France
ANSM patient data sovereignty rules accelerate consolidation of radiology PACS onto compliant domestic storage infrastructure. Media conglomerates migrate content libraries to object systems as 4K/8K production volumes explode. Île-de-France hosts the primary concentration of AI training workload deployments.
United Kingdom
Financial exchanges standardize on all-flash arrays with NVMe-oF connectivity as FCA operational resilience directives intensify data pipeline velocity requirements. GDPR Article 17 erasure mandates force simultaneous investment in high-performance primary systems and immutable archive tiers. London's trading infrastructure sustains millisecond-latency storage procurement.
Poland
Energy utilities and defense contractors expand sovereign-compliant private cloud deployments as EU strategic autonomy frameworks harden. Underpenetrated secondary markets offer whitespace for compliant storage infrastructure as German facility costs escalate. Warsaw emerges as a cost-competitive alternative for mid-market enterprises seeking continental presence.
Europe Data Center Storage Market Competitive Landscape
Global majors compete with regional champions across portfolio breadth and service model differentiation. The vendor base separates into three distinct tiers: integrated infrastructure conglomerates with full-stack offerings, pure-play storage specialists with subscription-centric business models, and Asian technology groups with cost-optimized hardware platforms. Consolidation pressures favor vendors with extended service lifecycles and circular economy credentials. Strategic moves center on consumption-based pricing expansion and sustainability certification alignment.
Within the integrated infrastructure tier, Dell Inc. and Hewlett Packard Enterprise occupy positions defined by hybrid cloud orchestration capabilities and as-a-service deployment frameworks. Pure Storage exemplifies the pure-play specialist archetype through its Evergreen subscription model. Huawei Technologies Co. Ltd. anchors the Asia-origin technology group segment with hardware-integrated platform offerings. These three company structures represent the dominant competitive archetypes shaping procurement criteria across European financial, healthcare, and industrial verticals.
| Leading Market Players |
|---|
| Dell Inc. |
| Hewlett Packard Enterprise |
| NetApp Inc. |
| Huawei Technologies Co. Ltd. |
| Hitachi Vantara LLC |
| Pure Storage |
| IBM |
| Western Digital |
| Nutanix |
| Others |
Pricing and Supply Chain Analysis
Hyperscaler procurement concentration across Frankfurt and Amsterdam data center corridors anchors enterprise storage pricing to consumption-based subscription tiers with committed capacity floors. Cost pass-through from NAND flash wafer fabrication tightens margin structures for array assemblers serving mid-market European buyers.
Pricing Analysis
Input-cost pass-through from East Asian foundry capacity constraints compresses gross margins for European system integrators assembling all-flash arrays. Pricing stratifies across premium NVMe-oF configurations for financial trading floors, standard hybrid tiers for automotive simulation workloads, and economy QLC arrays for warm data lakes. Price differentiation hinges on latency certification thresholds and CSRD-aligned circular service bundling. Cost compression in mid-market hybrid segments intensifies as Dell and HPE expand GreenLake-style consumption models. Municipal data centers and regional healthcare networks exhibit highest price sensitivity; Frankfurt-based hyperscalers demonstrate lowest sensitivity due to workload-critical latency requirements.
Supply Chain Analysis
Dual-sourcing requirements from EU strategic autonomy frameworks compel storage vendors to qualify secondary NAND suppliers beyond dominant South Korean and Taiwanese foundries. European array assembly draws from Japanese silicon wafer suppliers, German precision electromechanical component manufacturers, and Chinese rare earth magnet providers for HDD spindle motors. Single-source vulnerability concentrates in advanced NAND lithography equipment where Dutch ASML systems face export license uncertainty. Distribution runs through authorized channel partners serving national VAR networks, with direct OEM relationships dominating hyperscale procurement in FLAP markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe data center storage market functions as a regulatory compounder where EU AI Act traceability mandates and CSRD carbon disclosure obligations continuously expand compliant infrastructure demand.
For Market Incumbents: Lock in circular service model differentiation through extended hardware lifecycles and component upgrade paths that satisfy Ecodesign for Sustainable Products Regulation requirements. Defend against Pure Storage's Evergreen subscription traction by embedding firmware-level metadata tagging for AI Act compliance. Prioritize certification investment in ANSM and BfArM data localization standards to maintain position in French and German healthcare verticals. For New Entrants and Emerging Players: Regional systems integrators in Poland and the Nordics represent the most penetrable channel partner type for sovereign-compliant storage deployments outside saturated FLAP corridors. Target Polish energy utilities and Czech defense contractors with private cloud configurations addressing EU strategic autonomy frameworks. Pursue edge AI inference node opportunities in secondary metros where latency requirements favor compact high-IOPS arrays over hyperscale campus economics. For Investors and Strategic Acquirers: Cloud service providers expanding European footprints are the most active acquirer in this space, seeking storage software stacks and metadata lineage capabilities for AI Act compliance. Five-to-ten year viability favors vendors with vertically integrated firmware engineering and flash translation layer optimization talent. Watch hyperscaler capex allocation shifts toward European facility expansion as the primary inflection indicator for storage equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Consumption Model Expansion | HPE GreenLake and Dell APEX frameworks capture mid-market buyers preferring operational expenditure profiles under constrained IT budgets. |
| Sustainability Certification Alignment | CSRD-compliant carbon disclosure and circular material verification secure procurement preference from Dutch pension funds and Irish cloud providers. |
| Edge AI Storage Development | Compact NVMe arrays for metro edge inference nodes address latency requirements outside traditional hyperscale campuses in secondary European markets. |
| Regulatory Compliance Integration | Firmware-embedded metadata tagging and lineage tracking satisfy EU AI Act traceability mandates for training dataset auditability. |
| Secondary Market Geographic Expansion | Polish and Nordic deployments exploit whitespace as Frankfurt facility costs escalate and German power availability tightens. |
Research Methodology
Bottom-up enterprise workload modeling reconciled against top-down hyperscaler facility investment tracking forms the analytical core of this study. Primary interviews with data center infrastructure planners, storage procurement officers at financial institutions, cloud provider capacity engineers, and systems integrators across Germany, France, Netherlands, and Poland combined with secondary validation from SEC filings, hyperscaler capex disclosures, EU regulatory registers, and industry association deployment surveys. Triangulation across supply-side NAND fabrication capacity announcements and demand-side storage array shipment patterns ensures convergence in volume estimates.
Historical trendline analysis of storage media cost curves and hyperscaler facility construction pipelines informed projection framework construction across the analysis window. Segmentation dimensions modeled include storage architecture type, deployment model, end-use vertical, and geographic regulatory cluster. CAGRs derived from fitted growth curves applied to base-year estimates incorporate technology substitution rates for QLC NAND displacement of nearline HDD and AI workload intensity scaling assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NAND supply concentration disruptions and divergent national implementations of GDPR geographic placement rules. Deviation in EU AI Act enforcement intensity or hyperscaler facility permitting timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Consumer Network Attached Storage Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Global Cloud Storage Software Market
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
Hong Kong Data Center Storage Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
5D Data Storage Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
Hard Disk Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Media and Entertainment Storage Market
Storage Solutions
Global Storage As a Service Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Asia Pacific Automated Storage and Retrieval System Market
Storage Solutions
Global Personal Cloud Storage Market