
 UK Data Center Storage Market | 2026-2036
UK Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
UK Data Center Storage Market Insights
Market Context
London's hyperscale facility pipeline is recalibrating capacity planning across the UK colocation sector. Equinix leverages its Slough campus to anchor interconnection density west of the capital. Digital Realty Trust sustains development momentum through pre-committed power allocations at its Docklands sites. Kao Data specializes in high-performance computing environments, positioning its Harlow campus for AI training workloads.
Technical Definition and Segment Structure
UK data center storage encompasses electromechanical and solid-state media systems engineered for enterprise-grade data retention, with SSD arrays achieving sub-millisecond latency and HDD platforms delivering cost-optimized capacity tiers above 20TB per drive. The primary commercial purpose centers on enabling continuous data availability for cloud services, enterprise applications, and mission-critical backup operations. SSD deployments command premium margins in financial services and healthcare verticals where transaction speed determines operational viability. Cloud storage expansion within the deployment model category is displacing on-premises capital expenditure patterns among mid-market enterprises. Colocation remains the structural default for organizations requiring physical asset control without facility ownership burdens.
Regulatory Framework
Ofcom's infrastructure competition rules intersect with the UK government's net-zero data centre policy to reshape power procurement and cooling technology mandates. BSI standards for data center resilience, alongside FCA operational resilience requirements for BFSI operators, establish compliance thresholds that filter market participation. Stakeholders must monitor grid interconnection queues and renewable power purchase agreement availability as determinants of site viability.
Market Dynamics
Net-zero carbon mandates are compressing deployment timelines for liquid cooling infrastructure across UK colocation facilities, forcing operators to reconfigure power density specifications before grid interconnection agreements expire.
Growth Catalysts
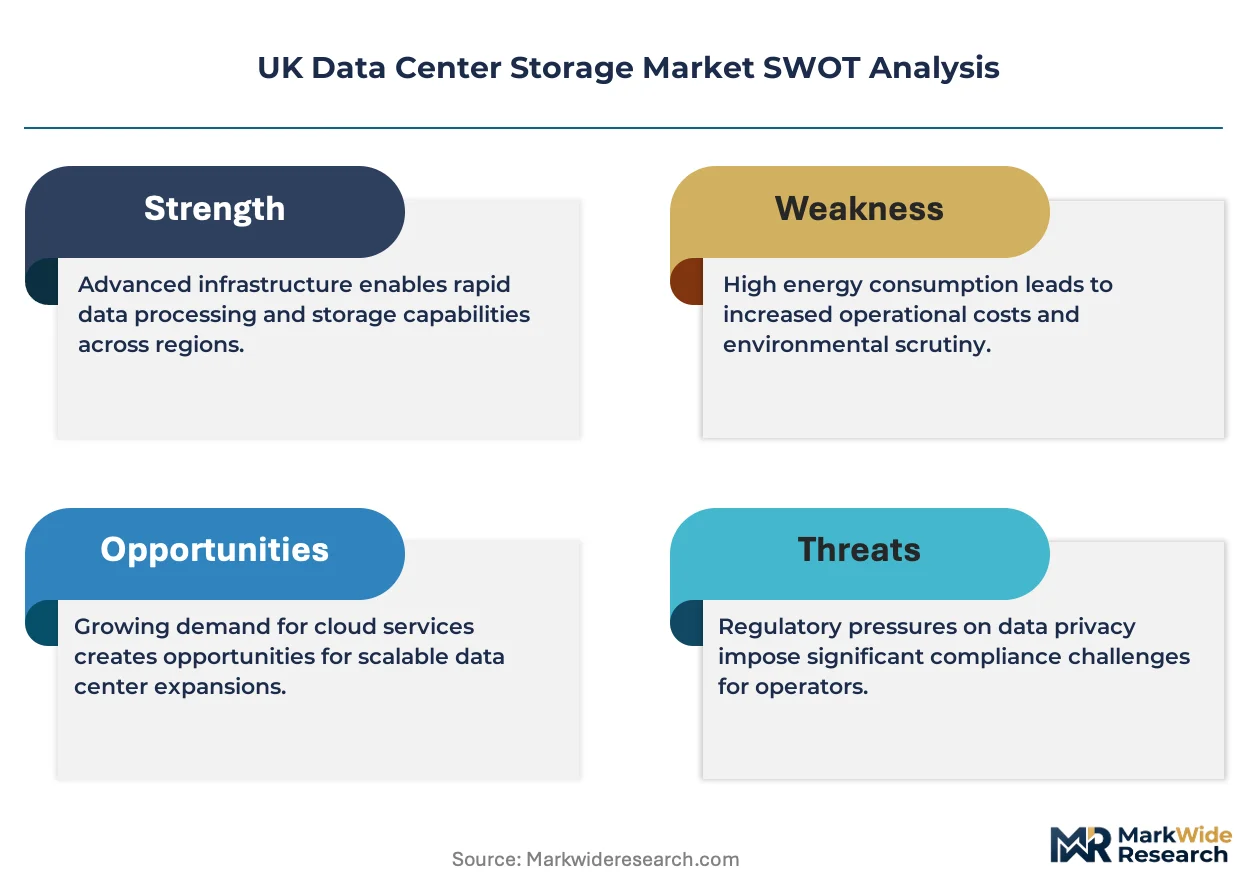
- FCA operational resilience requirements:Financial services firms must maintain continuous data availability with sub-four-hour recovery windows, mandating redundant storage architectures and secondary site replication.
- AI training workload concentration:High-performance computing clusters in the London-Frankfurt corridor demand NVMe-over-Fabrics storage with microsecond latency tolerances for neural network checkpoint operations.
- Ofcom infrastructure competition rules:Wholesale bandwidth pricing transparency accelerates multi-cloud connectivity deployments, expanding addressable storage capacity for mid-market enterprises migrating from on-premises estates.
Market Restraints
- Grid interconnection queue congestion:National Grid capacity allocation delays extend facility commissioning timelines by 18-36 months, freezing capital deployment returns for speculative storage builds.
- Liquid cooling capex premiums:Immersion and direct-to-chip systems require 40-60% higher initial infrastructure investment versus traditional air-cooled arrays, compressing IRRs for brownfield retrofits.
- Flash memory supply concentration:NAND fabrication capacity clusters in South Korea and Taiwan, exposing UK operators to geopolitical disruption risks and volatile component pricing cycles.
Strategic Opportunities
- Scotland renewable power corridors:Abundant offshore wind and hydroelectric generation in the Central Belt enables carbon-negative storage operations with PPA structures below grid parity.
- BSI resilience certification premium:Tier IV-equivalent facilities command 15-25% colocation pricing premiums from BFSI and healthcare tenants with zero-downtime mandates.
- Computational storage convergence:Processing-in-memory architectures from Samsung and Intel reduce data movement overhead for real-time analytics workloads in quantitative trading environments.
Industry Challenges
- Liquid cooling technician scarcity:Dielectric fluid handling, corrosion monitoring, and immersion tank maintenance require specialized certifications absent from standard HVAC training pipelines.
- Legacy SAN integration complexity:Fibre Channel fabrics and block-based storage estates resist seamless migration to software-defined architectures without application-level refactoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Data Center Storage Market |
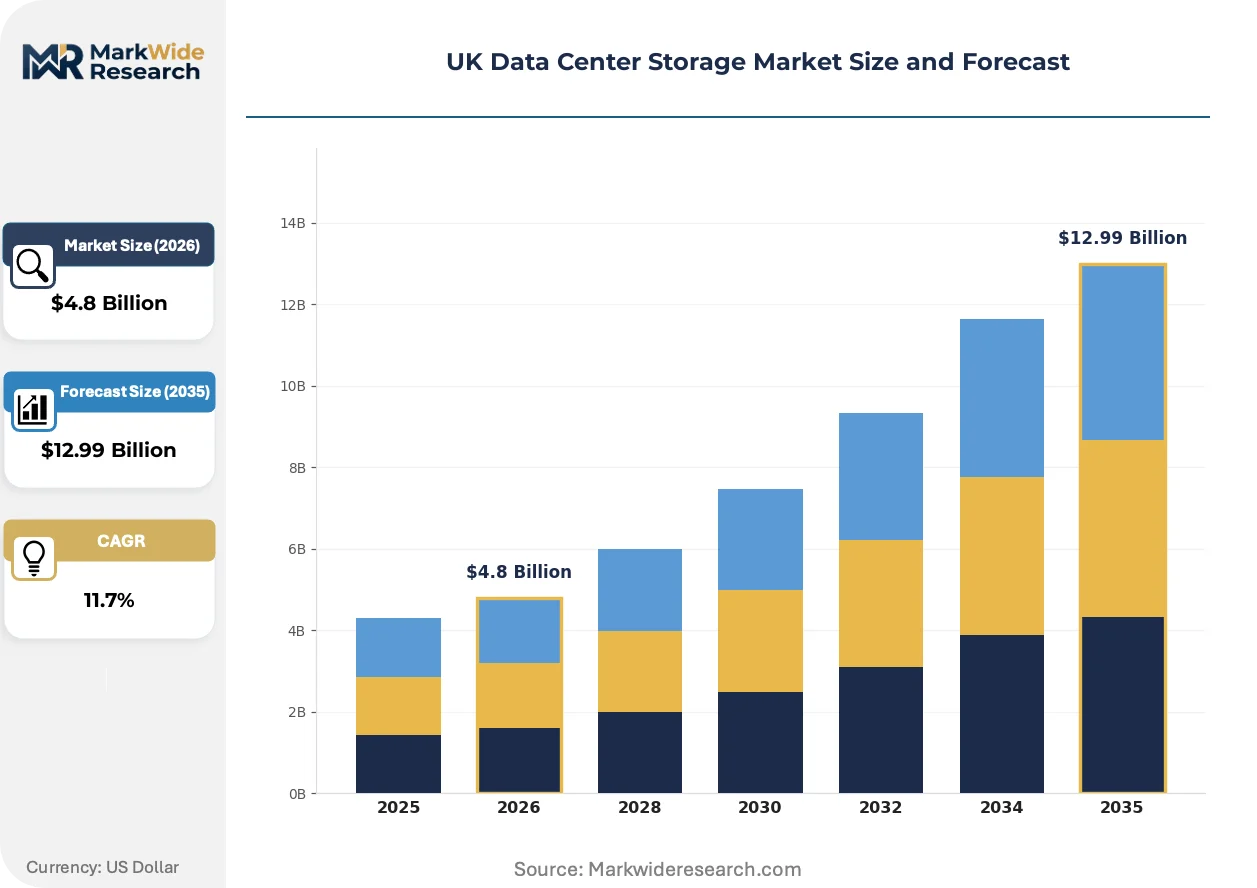
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: HDD, SSD, Hybrid, Tape Deployment Model: On-Premises, Colocation, Managed Services, Cloud Storage Application: Big Data Analytics, Backup Solutions, Disaster Recovery, Virtualization End User: Telecommunications, BFSI, Government, Healthcare |
| Companies Covered | Rackspace Technology Inc, Global Switch Holdings Limited, Equinix Inc, Telehouse (KDDI Corporation), NTT Ltd, Digital Realty Trust Inc, Colt Technology Services, Kao Data Ltd, Vantage Data Centers LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Data Center Storage Market Trends and Innovations
Storage-class memory hierarchies and software-defined disaggregation are collapsing traditional three-tier architectures, enabling compute and capacity scaling at independent cadences for cloud-native workloads.
Computational storage drives integrating ARM processing cores directly on NVMe devices are decentralizing analytics execution from server CPUs to the storage layer itself. Quantitative hedge funds and genomics laboratories deploy these arrays for pattern-matching operations that would saturate host memory buses. The architecture compresses rack space requirements while reducing east-west traffic across spine-leaf fabrics.
Ofcom's 2023 wholesale fixed telecoms market review mandates physical infrastructure access for alternative network operators, accelerating dark fiber deployment between Slough, Docklands, and Manchester MediaCity. Storage operators leverage these regulated interconnection rights to offer latency-guaranteed replication services without building captive fiber plant. The policy shift most benefits mid-market colocation providers previously locked out of premium connectivity corridors.
Consumption-based storage procurement with committed use discounts displaces capital-intensive ownership models among UK mid-market enterprises. Finance directors prefer operational expenditure treatment for unpredictable data growth trajectories, particularly in professional services and legal verticals with document retention mandates. Channel partners respond with managed service wrappers bundling hardware, software, and operational support into single monthly metrics.
UK Data Center Storage Market Segmentation
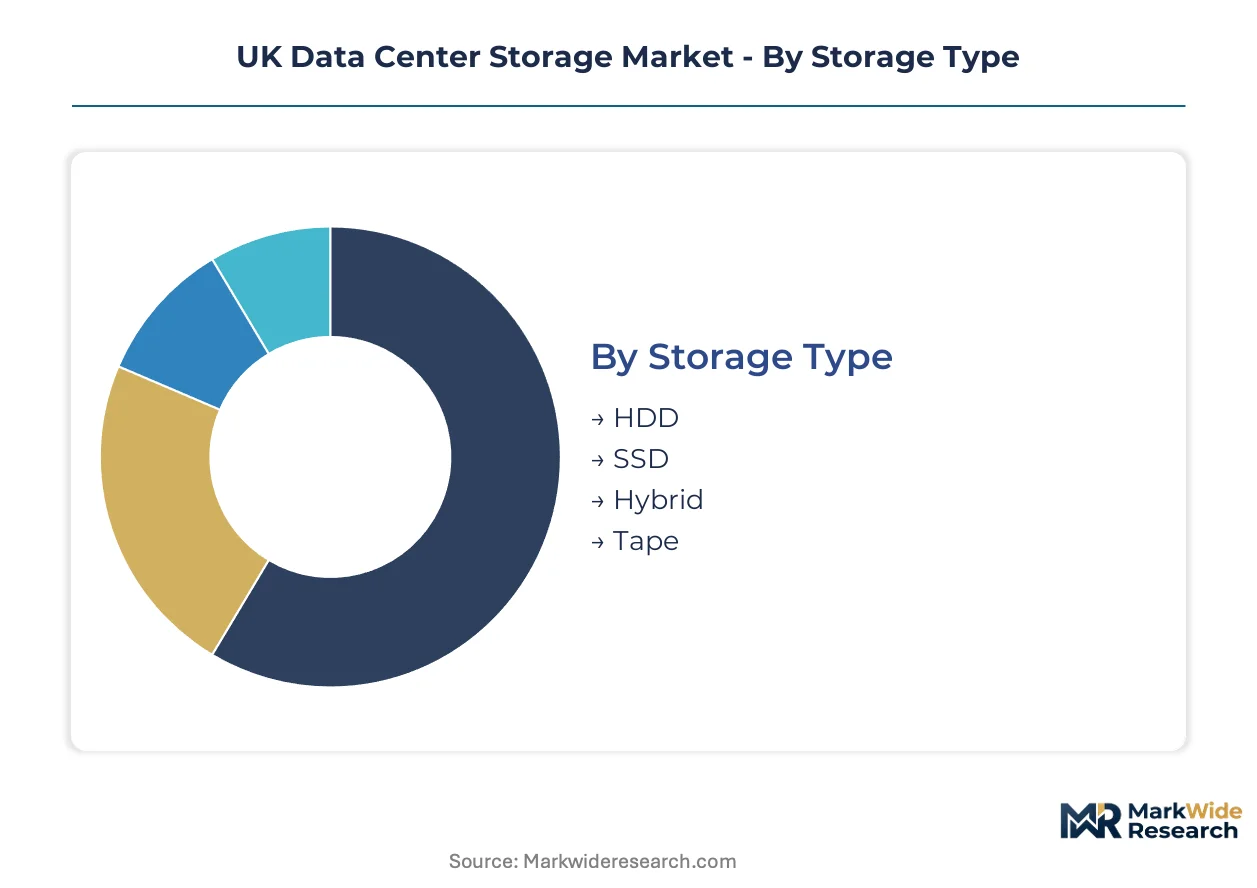
Segmentation reveals how UK data center storage procurement diverges between latency-sensitive financial workloads and capacity-optimized archival tiers. Understanding these fault lines enables vendors to align product roadmaps with distinct power density, compliance, and connectivity requirements across deployment models.
Storage Type:
Integration depth varies sharply—HDD and tape function as standalone capacity tiers, while SSD and hybrid arrays embed directly into compute nodes for AI training clusters.
- HDD:Electromechanical platters delivering 20TB+ per drive with sequential throughput optimized for warm archival tiers. Demand concentrates in Slough and Docklands colocation facilities where financial services firms maintain regulatory-mandated seven-year retention vaults constrained by FCA operational resilience requirements.
- SSD:NAND-based arrays achieving sub-millisecond latency through NVMe-over-Fabrics protocols. AI training workloads in the London-Frankfurt corridor absorb premium flash deployments for neural network checkpoint operations requiring microsecond recovery windows.
- Hybrid:Tiered architectures combining flash caching with HDD capacity pools for mid-market enterprises migrating from legacy SAN estates.
- Tape:Linear Tape-Open libraries providing air-gapped immutability for ransomware recovery and long-term compliance archives in government and healthcare verticals.
HDD leads volumes today; SSD is gaining share fastest.
Deployment Model:
Cost tier stratification separates capital-intensive ownership from operational expenditure models favored by unpredictable growth trajectories.
- On-Premises:Enterprise-owned infrastructure with dedicated power and cooling footprints. BFSI operators in the City of London maintain captive storage estates to satisfy FCA operational resilience mandates for physical asset control and sub-four-hour recovery guarantees.
- Colocation:Leased cabinet or cage space with shared facility infrastructure. Kao Data's Harlow campus and Equinix's Slough sites attract HPC deployments requiring 50kW+ rack densities with liquid cooling readiness.
- Managed Services:Third-party operational responsibility bundling hardware, software, and support into single monthly metrics. Professional services and legal verticals prefer this structure for document retention mandates with unpredictable discovery volumes.
- Cloud Storage:Consumption-based object and block services with committed use discounts. Mid-market enterprises displaced by Ofcom's wholesale bandwidth pricing transparency accelerate multi-cloud connectivity deployments.
Colocation leads volumes today; cloud storage is climbing the fastest.
Application:
Volume throughput requirements distinguish streaming analytics from sporadic recovery operations.
- Big Data Analytics:Computational storage arrays with processing-in-memory architectures decentralizing pattern-matching execution from host CPUs. Quantitative hedge funds deploy these for real-time trading signal generation.
- Backup Solutions:Immutable snapshot repositories with ransomware-resistant air-gapping. Healthcare trusts in England leverage these for patient record protection under NHS digital resilience standards.
- Disaster Recovery:Synchronous replication between geographically separated sites with latency-guaranteed dark fiber connectivity.
- Virtualization:Software-defined storage pools enabling independent compute and capacity scaling for cloud-native container workloads.
Backup solutions lead volumes today; big data analytics shows the steepest expansion trajectory.
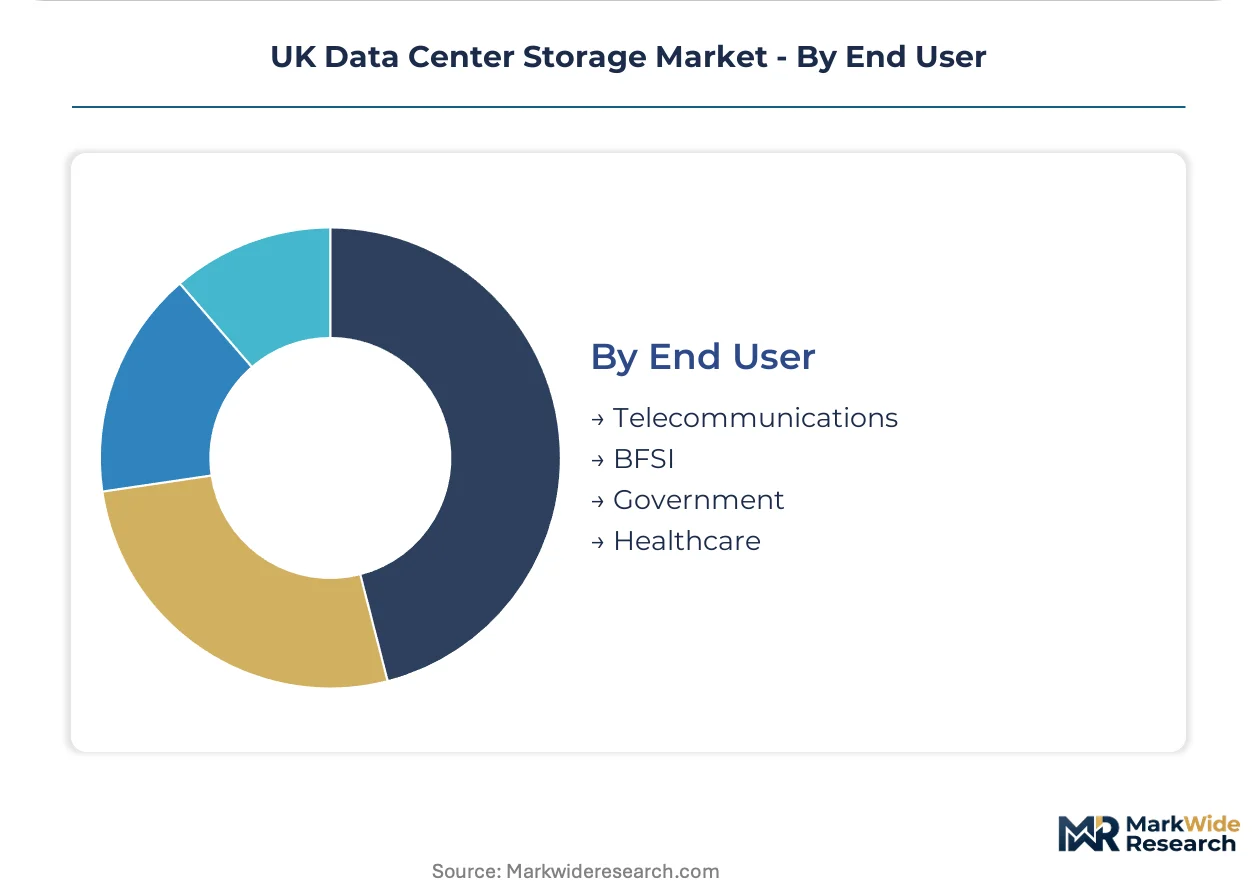
End User:
Customer type determines certification requirements and pricing tolerance for Tier IV-equivalent resilience premiums.
- BFSI:Banks, insurers, and asset managers with zero-downtime mandates and FCA-mandated operational resilience thresholds. These operators absorb 15-25% colocation pricing premiums for BSI-certified Tier IV facilities with redundant storage architectures.
- Healthcare:NHS trusts and private providers with patient data sovereignty requirements and clinical system continuity mandates. Scotland's Central Belt renewable power corridors attract carbon-negative storage operations from this vertical.
- Telecommunications:Mobile and fixed-line operators with subscriber data retention obligations and network function virtualization storage demands.
- Government:Central and local authorities with classified information handling protocols and long-term digital preservation mandates.
BFSI leads volumes today; healthcare is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping UK data center storage deployment patterns, with operators migrating capacity toward sub-regions offering streamlined grid interconnection and renewable power purchase agreements below grid parity.
London and the Southeast
Hyperscale demand concentrates in Slough and Docklands corridors where Equinix and Digital Realty Trust maintain pre-committed power allocations. Ofcom's wholesale bandwidth pricing transparency accelerates multi-cloud connectivity deployments across these sites. The London-Frankfurt corridor anchors low-latency NVMe-over-Fabrics storage for AI training workloads requiring microsecond checkpoint recovery.
The Midlands
Mid-market colocation operators exploit land cost differentials against the capital while maintaining sub-10ms latency to London financial exchanges. BSI resilience certification requirements filter market participation toward Tier III-equivalent facilities. Birmingham and Leicester industrial zones attract disaster recovery replication sites from BFSI operators seeking geographic separation from primary London estates.
North England
Manchester MediaCity emerges as a secondary connectivity hub benefiting from Ofcom-mandated dark fiber access between Slough and northern corridors. Renewable power purchase agreements from offshore wind clusters in the Irish Sea enable carbon-negative storage operations. Healthcare trusts in Leeds and Sheffield deploy immutable tape archives for NHS digital resilience compliance.
Scotland
Central Belt hydroelectric and offshore wind generation delivers power purchase agreement structures substantially below UK grid averages. Kao Data's Edinburgh-adjacent positioning exemplifies high-performance computing migration toward carbon-negative jurisdictions. Scottish government net-zero data centre policy accelerates liquid cooling adoption for AI training clusters.
Wales
Cardiff and Newport industrial zones leverage Severn Estuary offshore wind development for renewable-powered colocation expansion. Grid interconnection queue congestion in England pushes speculative storage builds toward Welsh substations with available capacity. BFSI operators establish secondary replication sites here to satisfy FCA operational resilience geographic separation mandates.
UK Data Center Storage Market Competitive Landscape
US-based hyperscale operators anchor one tier of UK data center storage; domestic specialists and European operators hold differentiated positions in colocation and connectivity segments. Market structure concentrates around vertically integrated platforms with captive power procurement capabilities and independent operators relying on wholesale grid access. Three archetypes dominate: hyperscale developers with sovereign wealth backing, telecom-captive colocation divisions, and pure-play HPC specialists. Competitive intensity centers on pre-committed power allocation securing and liquid cooling infrastructure retrofitting.
Within the hyperscale developer tier, Digital Realty Trust and Equinix occupy positions exemplifying transatlantic platform scale with UK-specific interconnection density. Kao Data represents the domestic HPC specialist archetype, anchoring high-performance computing positioning in the London-Frankfurt corridor. Among connectivity-integrated operators, Colt Technology Services and Telehouse exemplify telecom-derived colocation models leveraging captive fiber assets for latency-guaranteed storage replication services.
| Leading Market Players |
|---|
| Rackspace Technology Inc |
| Global Switch Holdings Limited |
| Equinix Inc |
| Telehouse (KDDI Corporation) |
| NTT Ltd |
| Digital Realty Trust Inc |
| Colt Technology Services |
| Kao Data Ltd |
| Vantage Data Centers LLC |
| Others |
Pricing and Supply Chain Analysis
NAND flash spot price indices cascading from South Korean and Taiwanese fabrication facilities transmit directly into UK storage array pricing tiers, compressing margins for distributors while amplifying premiums on NVMe-over-Fabrics configurations for AI training clusters.
Pricing Analysis
Distributor margin compression of 8-12 percentage points is reshaping procurement economics for UK colocation operators sourcing SSD arrays. Three-tier pricing structure across enterprise NVMe, mid-market hybrid, and archival HDD levels separates FCA-mandated financial services deployments from capacity-optimized healthcare archives. Cost compression in liquid cooling-ready rack configurations is intensifying because grid interconnection queue delays freeze speculative capital deployment. Mid-market enterprises migrating from on-premises estates exhibit highest price sensitivity; BFSI operators with zero-downtime mandates absorb Tier IV resilience premiums with minimal elasticity.
Supply Chain Analysis
Specialized dielectric fluid technicians in Germany and the Netherlands constrain UK liquid cooling deployment velocity, forcing operators to import certified maintenance crews at 40% labor cost premiums. NAND fabrication concentrates in South Korea and Taiwan; HDD assembly clusters in Thailand and Malaysia. UK operators source controller silicon from US fabless designers and power management components from Japanese suppliers. Single-source vulnerability in advanced node NAND exposes operators to geopolitical disruption risks. Distribution runs through value-added resellers with FCA compliance expertise serving London financial services verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK data center storage has transitioned into a late-cycle quality phase where FCA operational resilience mandates filter procurement toward BSI-certified Tier IV facilities with redundant architectures.
For Market Incumbents: Deploy captive renewable power purchase agreements in Scotland's Central Belt to defend margin position against carbon-negative entrants. Liquid cooling infrastructure retrofitting at existing Slough and Docklands campuses locks in AI training workload retention before grid interconnection queues extend further. Certification investment in BSI Tier IV equivalence commands 15-25% pricing premiums from BFSI tenants. For New Entrants and Emerging Players: Enter via Wales and Scotland sub-regions where grid interconnection capacity remains available below English queue congestion. Secondary disaster recovery replication sites for London financial services operators represent the most penetrable white-space target. Managed service wrappers bundling hardware, software, and operational support into single monthly metrics capture professional services verticals with unpredictable discovery volumes. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic HPC specialists controlling pre-committed power allocations in the London-Frankfurt corridor. Five-to-ten year viability hinges on liquid cooling readiness and renewable PPA structures below grid parity. Acquisition target archetype: mid-scale operators with BSI Tier III-equivalent certifications and available grid capacity in non-London sub-regions. Signal to watch: National Grid interconnection queue clearance rates as inflection indicator for speculative build viability.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Retrofit | Enables 50kW+ rack densities required for AI training workloads in Slough and Harlow corridors. |
| Scotland Renewable PPA Procurement | Secures carbon-negative power structures below UK grid averages for Central Belt facilities. |
| BSI Tier IV Certification Investment | Commands resilience premiums from FCA-mandated financial services operators with zero-downtime requirements. |
| Multi-Cloud Connectivity Expansion | Leverages Ofcom-mandated dark fiber access for latency-guaranteed replication services. |
| Computational Storage Array Deployment | Reduces east-west traffic for quantitative trading and genomics pattern-matching workloads. |
Research Methodology
Direct dialogue with data center operators, FCA compliance officers, National Grid interconnection planners, and liquid cooling engineering specialists grounded qualitative assessment, validated against secondary sources including Ofgem capacity auction results, National Grid transmission network data, BSI certification registries, and colocation provider tariff disclosures. Bottom-up and top-down triangulation cross-referenced facility-level power commitments with aggregate storage capacity deployment patterns.
Bottom-up modeling aggregated individual facility power allocations and storage technology mix assumptions across the projection horizon, while top-down analysis benchmarked UK deployment against European capacity trends. Segmentation dimensions included storage type, deployment model, application workload, and end-user vertical. CAGRs derived from fitted growth curves incorporating grid interconnection queue clearance assumptions and renewable PPA availability trajectories. Forecast inputs encompassed NAND supply elasticity and FCA operational resilience enforcement intensity.
Inputs from National Grid interconnection databases and Ofgem regulatory filings were available through the study window; gaps in speculative facility commissioning timelines introduce uncertainty bands around capacity expansion trajectories. Forecasts reflect documented assumptions regarding power procurement velocity and cooling technology adoption curves. Material deviation in grid queue clearance rates or NAND supply disruption severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Global Ethernet Storage Fabric Market
Storage Solutions
Global Cloud Storage Software Market
Storage Solutions
Brazil Data Center Storage Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
Software Defined Storage Market
Storage Solutions
Global Personal Cloud Storage Market
Storage Solutions
Cloud Storage Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Mexico Data Center Storage Market
Storage Solutions
India Data Center Storage Market
Storage Solutions
Singapore Data Center Storage Market