
 Data Backup and Recovery Market | 2026-2036
Data Backup and Recovery Market Size, Share, and Industry Trends Forecast 2026-2036
Data Backup and Recovery Market Intelligence
GDPR's data portability and breach notification requirements are consolidating enterprise spending on compliant backup architectures. Veeam leverages its software-defined approach to capture mid-market cloud transitions. Dell Technologies anchors large-scale on-premises deployments through integrated hardware-software bundles. Cohesity differentiates via converged secondary storage that collapses backup, archive, and analytics onto one platform.
Data backup and recovery encompasses systematic processes and technologies for creating redundant copies of digital information and restoring operational continuity after loss events, typically involving snapshot intervals measured in minutes, deduplication ratios exceeding 10:1, and recovery time objectives ranging from seconds to hours depending on tier. Its primary purpose is eliminating single points of failure in business-critical information systems. Cloud backup within the service type dimension leads revenue contribution as organizations shed tape infrastructure, while hybrid deployment models capture the fastest expansion by balancing latency-sensitive local recovery with cost-optimized cloud retention. Enterprise end users command the largest absolute spending, though SMBs represent the fastest-growing adoption curve as managed service providers package backup-as-a-service offerings.
FDA's 21 CFR Part 11 requirements for electronic records in life sciences, HIPAA's security rule mandating retrievable exact copies of protected health information, and the EU AI Act's traceability provisions for training data collectively elevate backup from operational convenience to regulatory necessity. These frameworks shape vendor product roadmaps by requiring immutable storage, audit logging, and geographic data residency controls. Stakeholders must evaluate whether their current backup architectures satisfy emerging sector-specific mandates before regulators begin systematic compliance verification.
Market Dynamics
Data sovereignty mandates are forcing organizations to rebuild backup architectures around geographic data residency requirements rather than cost optimization alone. This structural pressure is reshaping vendor roadmaps and enterprise procurement criteria across all deployment models.
Growth Catalysts
- GDPR's breach notification mandate:Organizations must maintain retrievable exact copies of personal data within 72 hours of request. Healthcare providers in Germany and France are expanding immutable storage deployments to satisfy CNIL and KBA audit requirements.
- Cloud repatriation dynamics:Latency-sensitive workloads are driving hybrid adoption. Automotive suppliers in Stuttgart and Munich are building redundant on-premises nodes alongside cloud retention tiers.
- Ransomware frequency:Attack volumes are compressing recovery time objective targets from hours to minutes. Financial services firms are mandating air-gapped backup intervals measured in seconds rather than daily snapshots.
Market Restraints
- Specialized engineering talent scarcity:Shortages of storage architects fluent in immutable object storage and zero-trust architectures are extending deployment timelines by 6-12 months in enterprise accounts.
- Energy cost volatility:Data center power consumption for always-on backup infrastructure faces input cost pressure from European grid instability, particularly affecting Frankfurt and Amsterdam metro clusters.
- Legacy tape infrastructure sunk costs:Organizations with decades of LTO tape investment resist full cloud migration despite operational inefficiencies, creating hybrid complexity tax.
Strategic Opportunities
- AI training data provenance:The EU AI Act's traceability requirements for model training datasets are electrifying demand for versioned, auditable backup systems in life sciences and autonomous vehicle development.
- Managed service provider channel expansion:SMBs lacking internal IT capacity represent an underpenetrated segment. MSPs in Spain and Italy are packaging backup-as-a-service with compliance wrap-around.
- Converged secondary storage platforms:Collapsing backup, archive, and analytics onto single infrastructure reduces hardware sprawl. Early adopters in Nordic markets report 40% floor space reduction.
Industry Challenges
- Multi-cloud orchestration complexity:Enterprises operating across AWS, Azure, and GCP struggle with consistent policy enforcement. Cross-cloud recovery testing reveals configuration drift failures in 30% of simulated scenarios.
- Immutable storage certification delays:Vendor claims of tamper-proof architectures face prolonged third-party validation cycles. SEC-registered financial institutions require completed SOC 2 Type II audits before procurement approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Backup and Recovery Market |
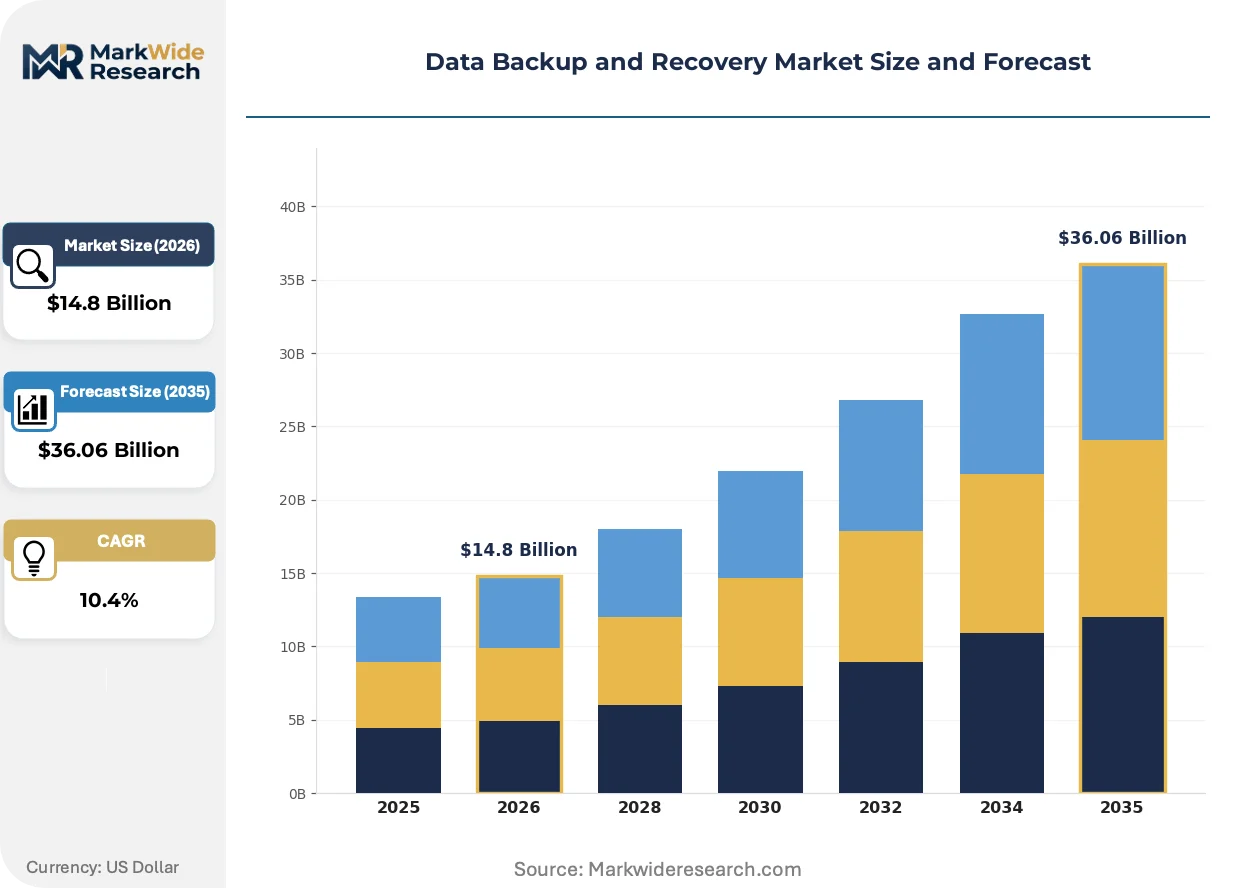
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $36.06 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Backup, On-Premises Backup, Hybrid Backup, Disaster Recovery Deployment: Public Cloud, Private Cloud, On-Premises, Hybrid Cloud End User: SMBs, Enterprises, Government Agencies, Educational Institutions Solution: Data Archiving, Continuous Data Protection, Bare Metal Recovery, Snapshot-based Backup |
| Companies Covered | Commvault, Arcserve, Veeam, Druva, Dell Technologies, Cohesity, Veritas Technologies, Vembu Technologies, Rubrik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Backup and Recovery Market Strategic Shifts & Innovations
Continuous data protection architectures are displacing scheduled backup windows entirely. Vendors are racing to embed machine learning into anomaly detection while regulators tighten immutable storage requirements.
Immutable object storage with WORM (Write Once Read Many) enforcement is electrifying enterprise ransomware defense strategies. Healthcare systems under HIPAA security rule mandates are adopting minute-interval snapshots with cryptographic verification. This architecture compresses recovery point objectives from 24 hours to 60 seconds, eliminating tape-based restore bottlenecks entirely.
REACH and RoHS compliance frameworks in the European Union are extending to data center hardware procurement. Backup appliance manufacturers must now document conflict mineral sourcing and circular economy readiness. German industrial enterprises are requiring ESG-linked supplier scorecards before awarding infrastructure contracts.
Consumption-based pricing models are displacing perpetual license structures in mid-market accounts. Managed service providers in France and the Netherlands are unbundling storage capacity from software fees, aligning costs with actual data growth. Healthcare SMBs prefer this structure as patient record volumes expand unpredictably.
Data Backup and Recovery Market Segmentation
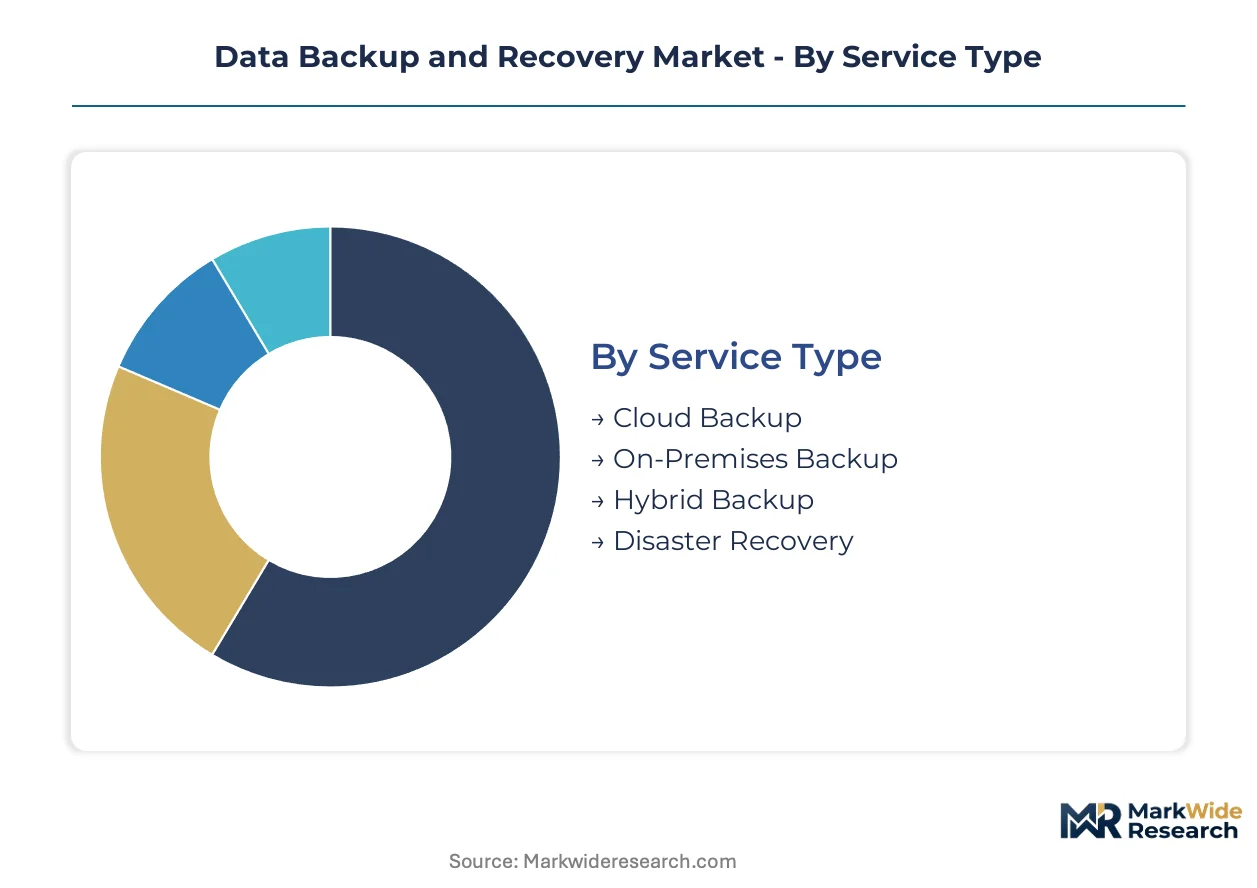
Segmentation in data backup and recovery reveals how regulatory pressure, workload sensitivity, and operational maturity shape procurement patterns. Organizations map specific service types to compliance mandates while balancing latency requirements against cost optimization.
Service Type:
GDPR's breach notification window and HIPAA's retrievable exact copy requirements impose divergent certification burdens across service architectures. Immutable storage certifications from CNIL and KBA favor cloud and hybrid deployments, while on-premises solutions face stricter SOC 2 Type II validation cycles.
- Cloud Backup:Remote replication to offsite data centers eliminates tape infrastructure while satisfying geographic data residency through region-locked storage buckets. Healthcare providers in France and Germany are consolidating patient record protection around immutable cloud tiers to satisfy CNIL audit protocols and KBA documentation requirements.
- Hybrid Backup:Combines local snapshot intervals measured in seconds with cost-optimized cloud retention for long-term compliance archives. Automotive suppliers in Stuttgart and Munich deploy redundant on-premises nodes alongside AWS or Azure retention tiers to balance latency-sensitive recovery against GDPR-mandated geographic distribution.
- On-Premises Backup:Traditional hardware-software bundles maintain air-gapped isolation for ransomware defense.
- Disaster Recovery:Orchestrated failover systems compress recovery time objectives from hours to minutes for business-critical workloads.
Leading the category by volume: Cloud Backup. Growing fastest: Hybrid Backup.
Deployment:
Cost tier stratification separates hyperscale consumption models from captive infrastructure investments. Public cloud aligns with variable-growth workloads, while private deployments anchor predictable compliance-bound data volumes.
- Public Cloud:Shared infrastructure with consumption-based metering suits SMBs lacking capital reserves for hardware procurement. MSPs in Spain and Italy package backup-as-a-service offerings atop AWS, Azure, and GCP to capture compliance-wrapped revenue from healthcare and financial services clients.
- Hybrid Cloud:Policy-orchestrated data placement across on-premises and cloud tiers optimizes cost per gigabyte while maintaining sub-minute recovery capabilities. Nordic enterprises report floor space reductions exceeding one-third after collapsing secondary storage sprawl onto converged hybrid platforms.
- Private Cloud:Dedicated tenant isolation satisfies financial services regulators demanding completed SOC 2 Type II audits before procurement approval.
- On-Premises:Fully captive infrastructure retains favor where energy cost volatility or data sovereignty mandates prohibit external data movement.
Dominating procurement spend: Public Cloud. Expanding most quickly: Hybrid Cloud.
End User:
Application criticality and internal IT capacity divide the customer base. Enterprises with dedicated storage architects pursue complex multi-cloud orchestration, while resource-constrained segments outsource operational burden to managed service providers.
- Enterprises:Large-scale deployments across distributed geographies mandate consistent policy enforcement across AWS, Azure, and GCP simultaneously. Cross-cloud recovery testing reveals configuration drift failures in nearly one-third of simulated scenarios, extending deployment timelines by 6-12 months due to scarce engineering talent.
- SMBs:Absence of internal IT capacity drives preference for unbundled storage capacity and software fees aligned to actual data growth. Healthcare clinics in France and the Netherlands select consumption-based structures as patient record volumes expand unpredictably.
- Government Agencies:Sovereign cloud requirements and classified data handling impose national-security-grade isolation standards.
- Educational Institutions:Research data preservation and student record compliance create seasonal backup demand spikes.
Commanding largest absolute spending: Enterprises. Gaining share fastest: SMBs.
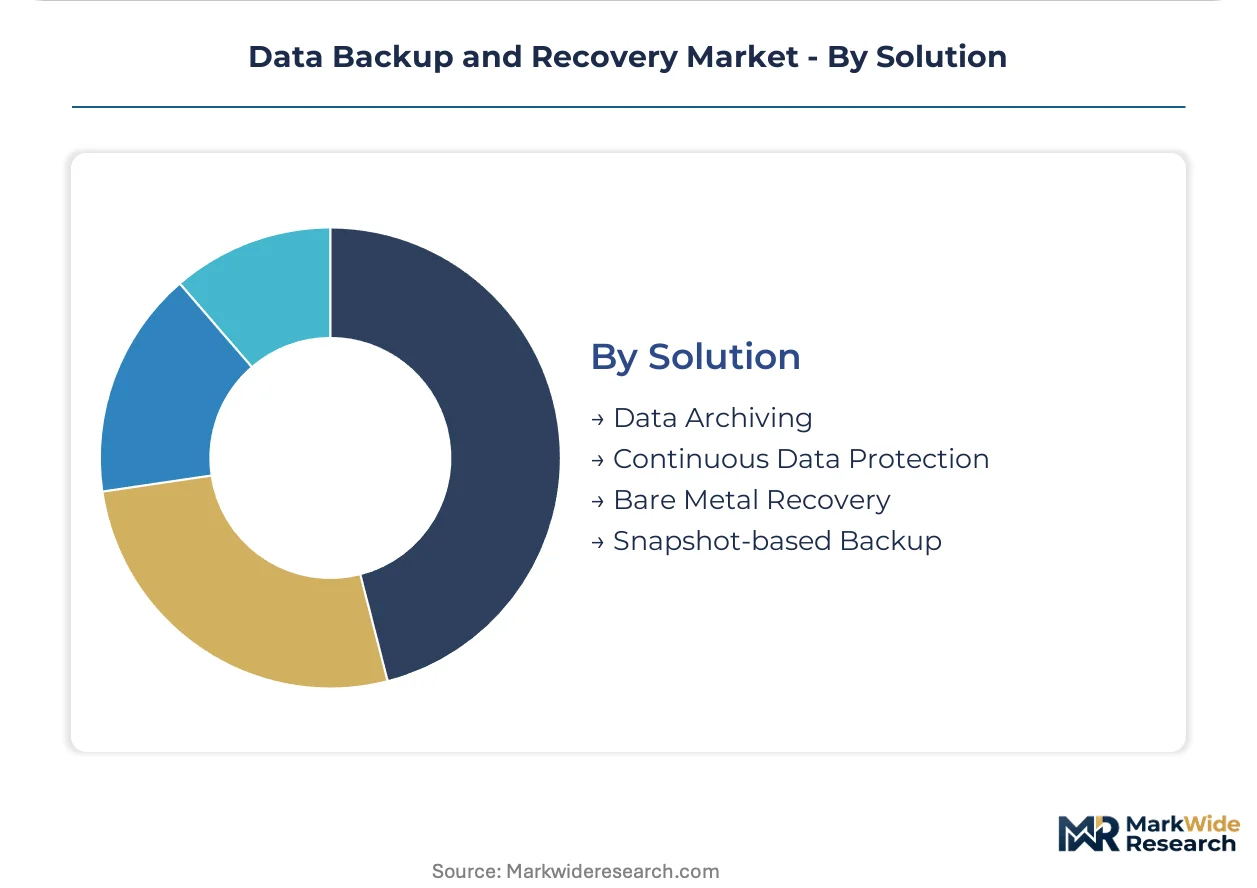
Solution:
Technology maturity separates established snapshot methodologies from emerging continuous protection architectures. Procurement criteria weight recovery point objectives against storage overhead and processing complexity.
- Continuous Data Protection:Journal-based replication captures every write operation, eliminating scheduled backup windows entirely. Financial services firms under SEC oversight mandate air-gapped intervals measured in seconds rather than daily snapshots to satisfy ransomware recovery mandates.
- Snapshot-based Backup:Point-in-time copies with deduplication ratios exceeding ten-to-one optimize storage efficiency for stable workloads. Life sciences organizations under FDA 21 CFR Part 11 maintain versioned, auditable systems for electronic records with cryptographic verification.
- Data Archiving:WORM-enforced immutable object storage satisfies long-term retention with tamper-proof guarantees.
- Bare Metal Recovery:Full system image restoration to dissimilar hardware addresses complete infrastructure failure scenarios.
Highest deployment penetration: Snapshot-based Backup. Steepest expansion trajectory: Continuous Data Protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's metro cluster anchors European data center capacity for backup infrastructure, hosting hyperscale facilities serving continental enterprises under strict data sovereignty frameworks. The city's position reflects Germany's industrial demand for geographically distributed recovery architectures.
Germany
Automotive suppliers in Stuttgart and Munich drive redundant node deployment for latency-sensitive engineering data. KBA documentation requirements under federal automotive regulations mandate immutable storage with audit trails. Industrial enterprises across Baden-Württemberg are consolidating secondary storage sprawl onto converged platforms.
United States
Financial services firms in New York and Chicago compress recovery objectives to seconds under SEC oversight. HIPAA's security rule drives healthcare systems toward cryptographic verification for patient records. Life sciences organizations in Boston and San Diego maintain versioned systems for FDA 21 CFR Part 11 electronic records compliance.
France
Healthcare providers expand cloud backup adoption to satisfy CNIL audit protocols for patient data portability. GDPR's breach notification mandate requires retrievable exact copies within 72 hours. Paris-based financial institutions and Lyon manufacturing clusters are adopting hybrid deployments balancing local recovery with cloud retention.
United Kingdom
London's financial district mandates air-gapped backup intervals for ransomware defense following regulatory guidance. The Information Commissioner's Office enforces data residency requirements for cross-border transfers. Edinburgh and Manchester enterprise clusters are rebuilding architectures around geographic distribution rather than cost optimization alone.
Netherlands
Amsterdam metro clusters face energy cost volatility affecting always-on backup infrastructure operations. Dutch healthcare SMBs prefer consumption-based pricing as patient record volumes expand unpredictably. Rotterdam industrial enterprises and Eindhoven technology corridors are evaluating converged secondary storage for floor space reduction.
Data Backup and Recovery Market Key Industry Players
Premium-margin players sit above commodity-margin players across solution complexity and compliance certification depth. The vendor base organizes around three tiers: integrated hardware-software bundlers, software-defined specialists, and converged platform providers. Strategic moves concentrate on portfolio diversification through immutable storage certifications and geographic expansion via managed service provider channels.
Within the software-defined tier, Veeam and Druva exemplify cloud-native positioning. Dell Technologies anchors the integrated hardware-software segment with enterprise-scale deployments. Cohesity occupies a position representing converged secondary storage, collapsing backup and analytics onto single infrastructure. These three players collectively illustrate how vendor roadmaps respond to GDPR-mandated geographic distribution and ransomware-driven recovery compression.
| Leading Market Players |
|---|
| Commvault |
| Arcserve |
| Veeam |
| Druva |
| Dell Technologies |
| Cohesity |
| Veritas Technologies |
| Vembu Technologies |
| Rubrik |
| Others |
Cost & Logistics Intelligence
Immutable storage certification tiers split the market into compliance-validated premium offerings and commodity backup utilities, with that divergence mapping directly onto dual supply chain configurations: SOC 2 Type II audited infrastructure commands dedicated hardware partnerships, while unvalidated software layers source from generic cloud compute pools.
Pricing Analysis
Value-based pricing anchored to recovery time objective guarantees dominates enterprise procurement, with financial services firms paying premiums for sub-minute failover commitments. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, geographic data residency controls, and managed service bundling. Cost compression in the standard tier intensifies because hyperscale cloud providers are unbundling storage from software fees. Healthcare SMBs exhibit highest price sensitivity due to unpredictable patient record growth, while SEC-registered institutions show least sensitivity given regulatory non-compliance penalties.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based NAND flash foundries and South Korean DRAM suppliers feeding storage array manufacturing. Hardware assembly concentrates in China, Mexico, and Germany, with software development anchored in the United States and Israel. Critical component dependencies include solid-state drives, high-capacity tape heads, and cryptographic security modules. Tariff exposure on Chinese-assembled appliances threatens margin stability for integrated hardware-software bundlers. Distribution runs through direct enterprise sales teams, managed service provider channels, and hyperscale cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering talent scarcity props pricing power for vendors with certified immutable storage architectures, as deployment timeline extensions of 6-12 months create captive customer relationships.
For Market Incumbents: Hedge against cloud-native disintermediation by deepening SOC 2 Type II certification moats and acquiring zero-trust architecture talent pools in Israel and Estonia. Automotive supplier demand in Stuttgart and Munich for redundant node deployment offers defensive revenue anchoring. Vertical integration into flash storage controller design reduces NAND flash cost volatility exposure. For New Entrants and Emerging Players: MSP channel partnerships in Spain and Italy represent the most penetrable route, packaging backup-as-a-service with GDPR compliance wrap-around for healthcare clinics lacking internal IT capacity. AI training data provenance requirements under the EU AI Act open white-space in life sciences versioned backup systems. Go-to-market through French and Dutch consumption-based pricing models aligns revenue with customer data growth curves. For Investors and Strategic Acquirers: Re-rating potential sits with converged secondary storage platforms given Nordic enterprise adoption reporting 40% floor space reduction and ESG-linked procurement mandates. Long-term viability favors vendors collapsing backup, archive, and analytics onto single infrastructure with REACH and RoHS documentation readiness. Watch for KBA and CNIL immutable storage certification completion as inflection signal for German and French healthcare market access.| Strategic Initiative | Industry Significance |
|---|---|
| Immutable Storage Certification | CNIL and KBA validation unlocks French and German healthcare procurement pipelines. |
| Converged Platform Development | Collapsing backup and analytics addresses Nordic enterprise ESG-linked supplier scorecards. |
| MSP Channel Expansion | Spain and Italy backup-as-a-service packaging captures SMB compliance-wrapped revenue. |
| Zero-Trust Architecture Investment | Air-gapped backup intervals measured in seconds satisfy SEC-registered financial services mandates. |
| Geographic Data Residency Controls | Region-locked storage buckets satisfy GDPR breach notification and data portability requirements. |
Research Approach
Document review covered hyperscaler capex disclosures, SEC filings from storage vendors, and EU regulatory frameworks including GDPR and the EU AI Act, complemented by interviews with CTOs at financial services firms, IT procurement officers in German automotive suppliers, and managed service provider channel heads in France and Spain. Secondary validation drew from hospital procurement databases, GPO contracts, and customs records on data center hardware imports. Bottom-up demand modeling triangulated against top-down market sizing across service type, deployment model, and end-user segments.
Revenue and volume trajectories emerged from integrating ransomware frequency data, cloud repatriation dynamics, and regulatory mandate timelines across the analysis window. Segmentation dimensions modeled include service architecture, deployment topology, organization scale, solution technology, and geographic regulatory cluster. CAGRs were derived from curve-fitting historical adoption patterns against compliance deadline acceleration. Industry-specific inputs incorporated energy cost volatility indices for European metro clusters and immutable storage certification pipeline tracking.
The model holds under stable regulatory enforcement intensity and continued hyperscale cloud capacity expansion; deviation in GDPR audit frequency or Taiwan semiconductor supply disruption would shift trajectory bands. Forecasts embed assumptions regarding ransomware attack volume trends and data sovereignty mandate proliferation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Public Cloud Storage Services Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
5D Data Storage Market
Storage Solutions
India Data Center Storage Market
Storage Solutions
Global Data Erasure Solutions Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Global in Memory Data Grid Market
Storage Solutions
Multi Cloud Storage Market
Storage Solutions
Scale-Out NAS Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
Austria Data Center Storage Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Global Storage As a Service Market
Storage Solutions
Network File System Market