
 Global Climate Control System for Commercial Vehicle Market | 2026-2036
Global Climate Control System for Commercial Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Climate Control System for Commercial Vehicle Market Analysis
Fleet operators is collapsing as the dominant buyer archetype as logistics companies and construction firms accelerate direct procurement of climate control packages. Valeo SA leverages its European manufacturing base to sustain leadership in electric compressor technology for heavy-duty applications. MAHLE GmbH anchors its position through R&D intensity in thermal management systems optimized for battery-electric commercial vehicles. DENSO Corporation dominates Asian supply relationships with OEMs through integrated HVAC modules designed for high-cabinity truck platforms.
A climate control system for commercial vehicle integrates compressors, condensers, evaporators, and refrigerant circuits to regulate cabin temperature and cargo zone conditions across operating ranges from minus thirty to fifty degrees Celsius. These systems employ aluminum microchannel heat exchangers and R-1234yf or CO2 refrigerant circuits to achieve thermal efficiency targets while maintaining driver safety and perishable cargo integrity. Air conditioning and refrigeration command the largest share of product type revenue due to mandatory cold-chain compliance in pharmaceutical and food distribution, while electric technology is displacing hydronic architectures fastest as commercial vehicle electrification advances. Installation through OEM channels captures premium margin pools because factory-integrated systems reduce warranty exposure and enable CAN-bus connectivity for predictive maintenance.
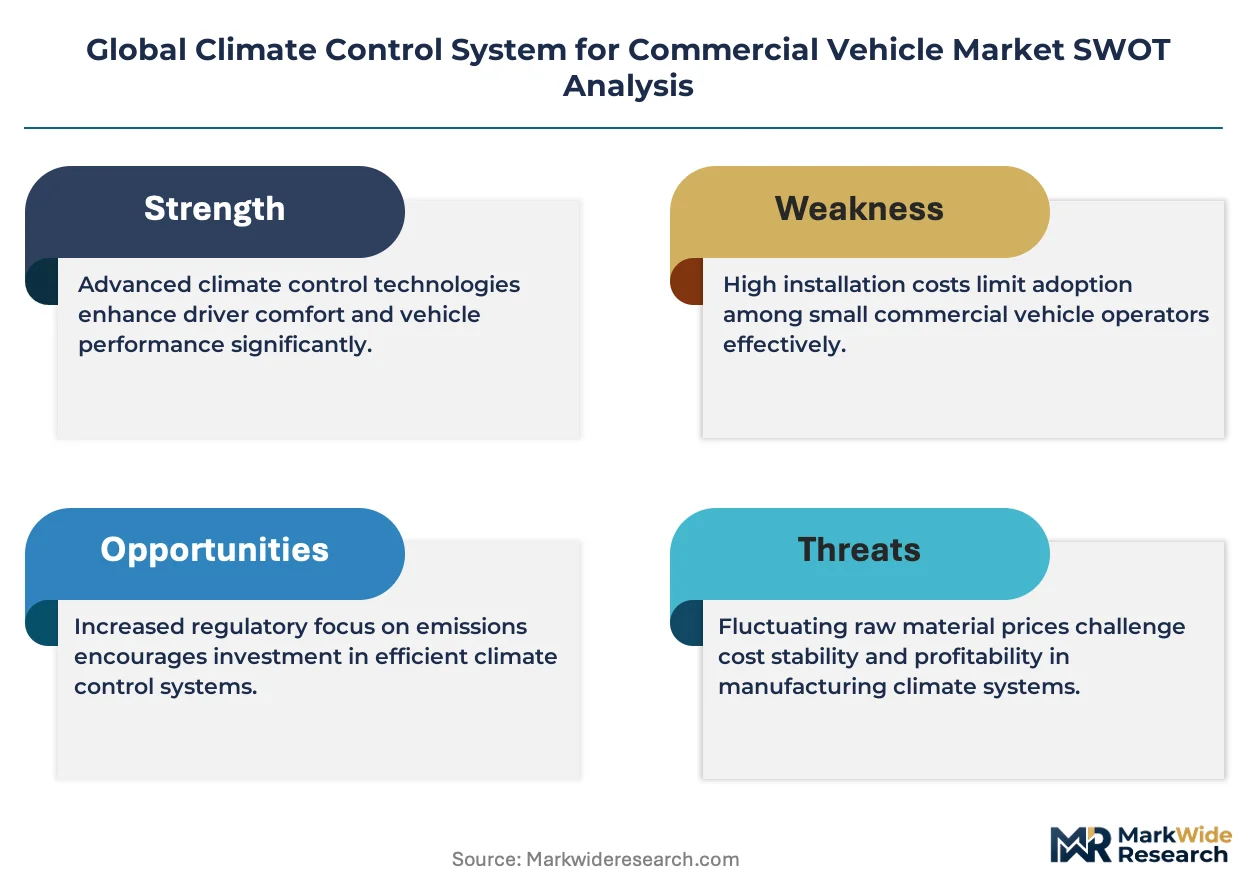
The EPA, CARB, and EU Green Deal collectively mandate refrigerant phase-downs and CO2 emission thresholds that force redesign of compressor efficiency and thermal insulation specifications. NHTSA cabin safety standards and ECE R122 regulations further dictate airflow minimums and defrost performance, creating compliance barriers for aftermarket suppliers lacking certification depth. Stakeholders must monitor how refrigerant transition timelines and electric vehicle thermal load requirements reshape supplier qualification criteria and procurement specifications across OEM and retrofit channels.
Market Dynamics
Electric compressor architectures are forcing a wholesale redesign of thermal management supply chains as commercial vehicle electrification accelerates beyond passenger car adoption curves. Battery thermal loads now dominate system sizing decisions, compressing legacy hydronic supplier margins while rewarding integrated HVAC-electric powertrain specialists.
Growth Catalysts
- EPA Phase 3 Standards:Greenhouse gas thresholds for heavy-duty trucks mandate improved cabin and cargo thermal efficiency, pulling demand toward factory-integrated climate systems with predictive load management.
- Refrigerated Pharmaceutical Logistics:Cold-chain integrity requirements for biologics and vaccines are expanding trailer refrigeration unit deployment across third-party logistics fleets in Germany, the United States, and Japan.
- CO2 Heat Pump Adoption:Transcritical CO2 refrigerant circuits are penetrating Nordic and Central European markets where R-1234yf phase-down timelines are most aggressive.
Market Restraints
- Aluminum Microchannel Supply Concentration:Heat exchanger core manufacturing clusters in China and South Korea create input vulnerability for European and North American system assemblers.
- Refrigerant Price Volatility:R-1234yf supply constraints and quota allocations under the EU F-Gas Regulation are inflating service costs for aftermarket retrofit channels.
- Battery Thermal Load Complexity:Electric commercial vehicles require simultaneous cabin cooling and battery conditioning, stretching compressor duty cycles beyond legacy duty ratings.
Strategic Opportunities
- Indian Cold-Chain Infrastructure:Food processing corridor investments and FSSAI-mandated temperature monitoring are creating first-mover advantage for integrated telematics-enabled refrigeration units.
- Predictive Maintenance Contracts:CAN-bus connected climate systems enable outcome-based service models that unbundle hardware from uptime guarantees.
- Brazilian Biofuel Corridor Expansion:ANVISA pharmaceutical distribution rules and agricultural export growth are converging to expand refrigerated truck fleet specifications.
Industry Challenges
- Refrigerant Handling Certification:Technician qualification gaps for CO2 transcritical systems and flammable refrigerant recovery are extending service network buildout timelines.
- Legacy Fleet Integration:Retrofit electric compressor packages require cab structural modifications and high-voltage electrical architecture upgrades that compress installer margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Climate Control System for Commercial Vehicle Market |
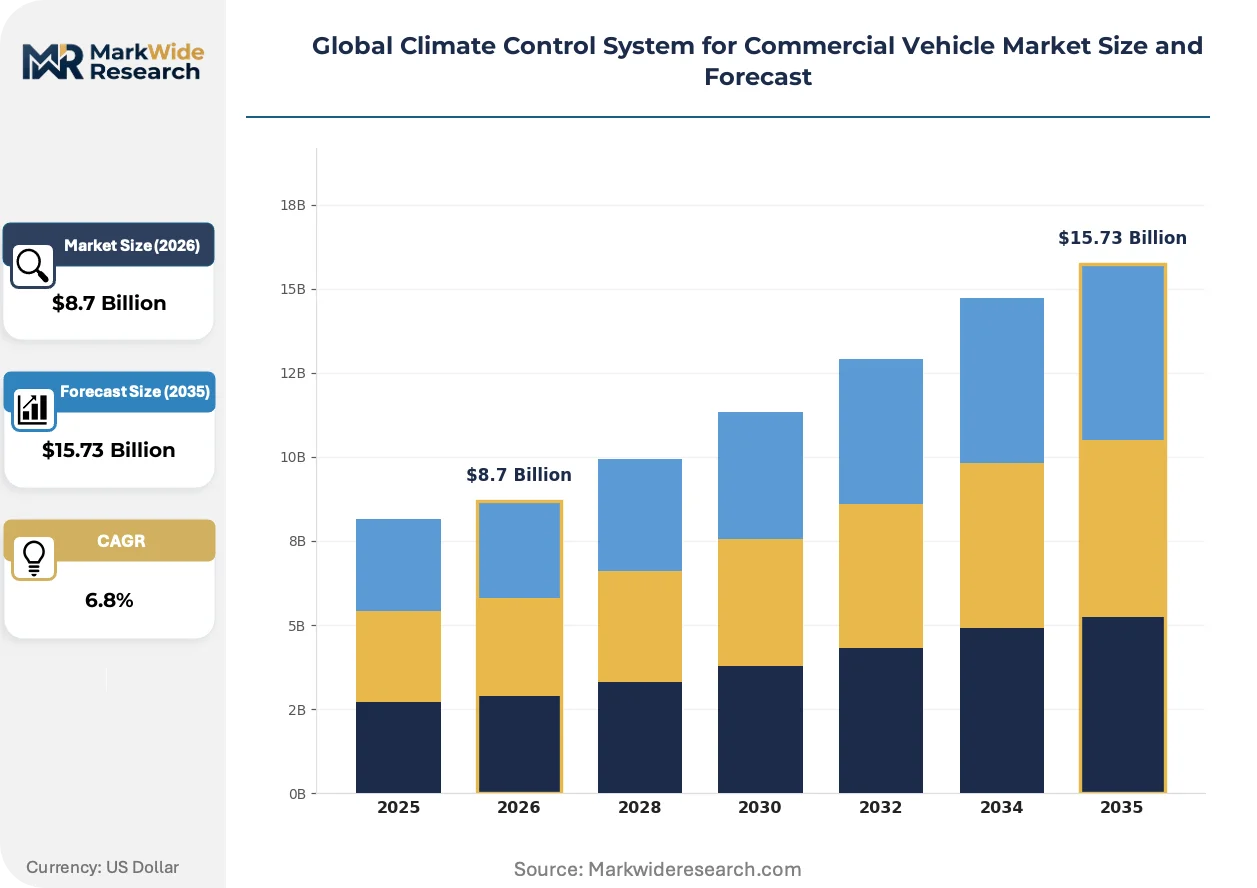
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Conditioning, Heating, Ventilation, Refrigeration End User: Fleet Operators, Logistics Companies, Construction Firms, Public Transport Technology: Hydronic, Electric, Variable Refrigerant Flow, Evaporative Installation Type: OEM, Aftermarket, Retrofit, Integrated |
| Companies Covered | Valeo SA, Eberspächer Group, MAHLE GmbH, Webasto SE, Sanden Holdings Corporation, Hanon Systems, Bergstrom Inc., Mobile Climate Control, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Climate Control System for Commercial Vehicle Market Emerging Trajectories
Thermal management intelligence is migrating from standalone climate controllers into unified vehicle energy management systems. This convergence is compressing supplier tiers and rewarding software-integrated hardware platforms.
Electric compressor technology is bifurcating between high-voltage integrated units for battery-electric trucks and belt-driven electrified compressors for hybrid platforms. Long-haul fleet operators in California and the Netherlands are adopting the former at accelerated replacement cycles. The technology split is compressing single-architecture supplier volumes while expanding systems integration contract values.
The EU F-Gas Regulation and its delegated acts are accelerating refrigerant phase-downs with binding quota reductions through 2030. Compressor manufacturers must redesign displacement and efficiency maps for lower-GWP alternatives. Heavy-duty OEMs in Germany and France are responding with factory-filled CO2 systems for premium cab configurations.
Fleet procurement departments are consolidating climate system specifications across tractor and trailer assets to compress parts proliferation and service training costs. This standardization is displacing fragmented aftermarket retrofit channels with direct OEM supply agreements. The shift is most visible among North American refrigerated carriers operating above five thousand power units.
Global Climate Control System for Commercial Vehicle Market Segmentation
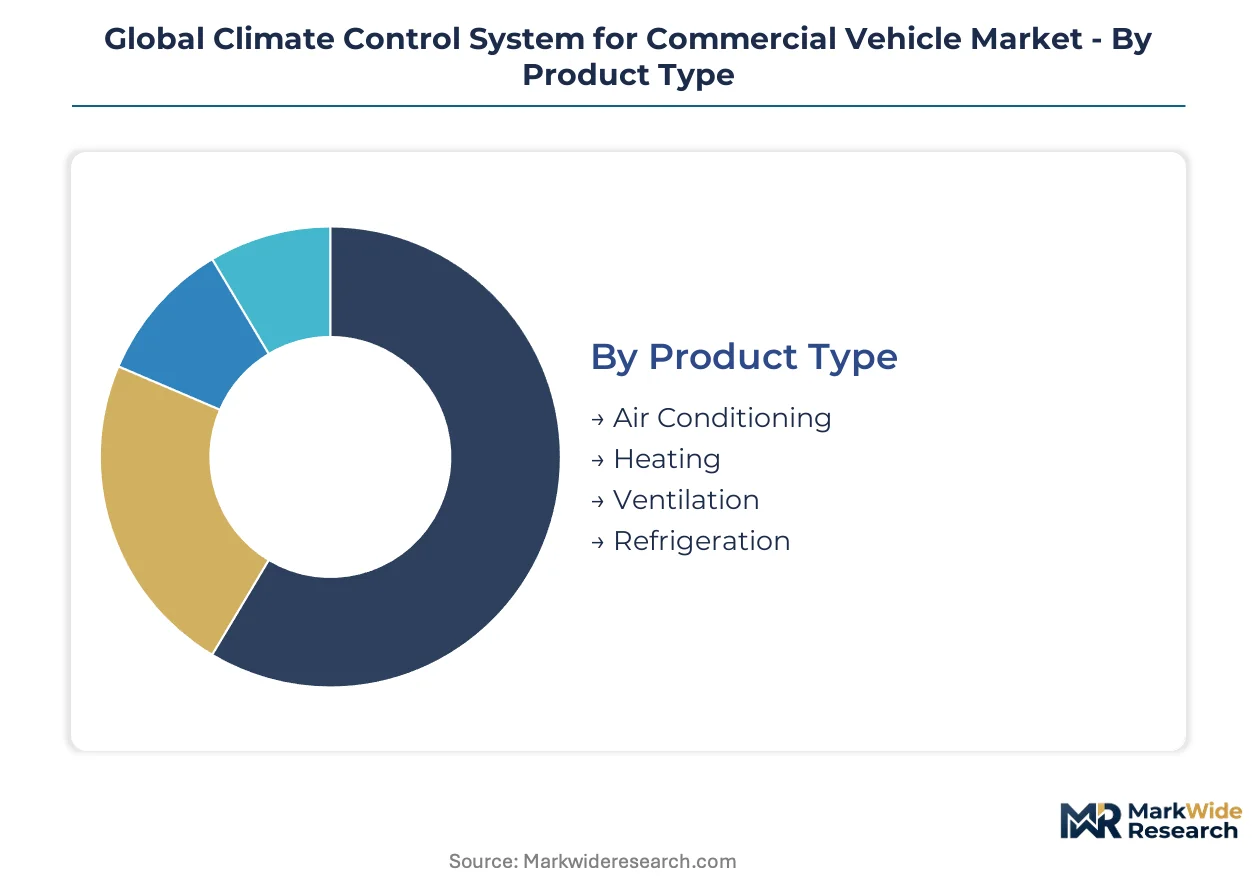
Climate control system procurement patterns diverge sharply across product architectures and installation channels, with electrification pressures and regulatory compliance timelines fragmenting traditional supplier relationships. Fleet operators now segment their specifications by thermal load profile rather than vehicle class alone, compressing legacy category boundaries.
Product Type:
Refrigeration faces the most acute substitution pressure from integrated thermal management platforms that bundle cargo and cabin conditioning into unified electric architectures.
- Air Conditioning:Compressor-condenser-evaporator circuits regulate cabin temperature across minus thirty to fifty degrees Celsius operating ranges. Demand concentrates in long-haul tractor platforms serving pharmaceutical corridors between Germany and the Netherlands, where driver retention regulations mandate precise climate control.
- Refrigeration:Trailer-mounted units maintain cargo zone integrity for perishable goods through aluminum microchannel heat exchangers and R-1234yf or CO2 refrigerant circuits. Cold-chain compliance requirements for biologics distribution across the United States and Japan are expanding unit deployment in third-party logistics fleets.
- Heating:Hydronic and electric core systems deliver defrost and cabin warmth compliant with ECE R122 airflow minimums.
- Ventilation:Fresh air intake modules with filtration manage cabin air quality per NHTSA safety standards.
Air conditioning retains volume leadership; refrigeration holds the steepest expansion curve.
End User:
Cost tier stratification separates premium factory-integrated procurement from fragmented aftermarket retrofit channels, with direct OEM relationships commanding margin premiums.
- Fleet Operators:Multi-thousand-unit carriers standardize climate specifications across tractor and trailer assets to compress parts proliferation and service training costs. North American refrigerated carriers above five thousand power units are displacing aftermarket channels with direct supply agreements.
- Logistics Companies:Third-party cold-chain specialists deploy telematics-enabled refrigeration units with predictive maintenance contracts. Indian food processing corridor investments and FSSAI-mandated temperature monitoring are creating first-mover advantage for integrated system suppliers.
- Construction Firms:Heavy-duty vocational truck operators prioritize durability-rated HVAC modules for high-cabinity platforms in extreme ambient conditions.
- Public Transport:Municipal bus fleets specify low-floor-compatible climate systems with rapid door-recovery capacity.
Fleet operators dominate procurement volume; logistics companies are expanding most quickly through cold-chain infrastructure buildout.
Technology:
Application-specific thermal loads dictate architecture selection, with battery-electric commercial vehicles forcing convergence between cabin cooling and powertrain conditioning systems.
- Electric:High-voltage integrated compressors for battery-electric trucks and belt-driven electrified units for hybrid platforms serve distinct replacement cycles. California and Netherlands long-haul operators are accelerating adoption of integrated electric architectures.
- Hydronic:Engine-coolant-based heating circuits face compression from electric alternatives as commercial vehicle electrification advances beyond passenger car curves.
- Variable Refrigerant Flow:Modulated capacity systems optimize energy consumption across variable cabin occupancy loads.
- Evaporative:Desert-climate cooling solutions serve vocational applications in high-temperature low-humidity operating environments.
Hydronic retains installed base dominance; electric gains share fastest through OEM platform integration mandates.
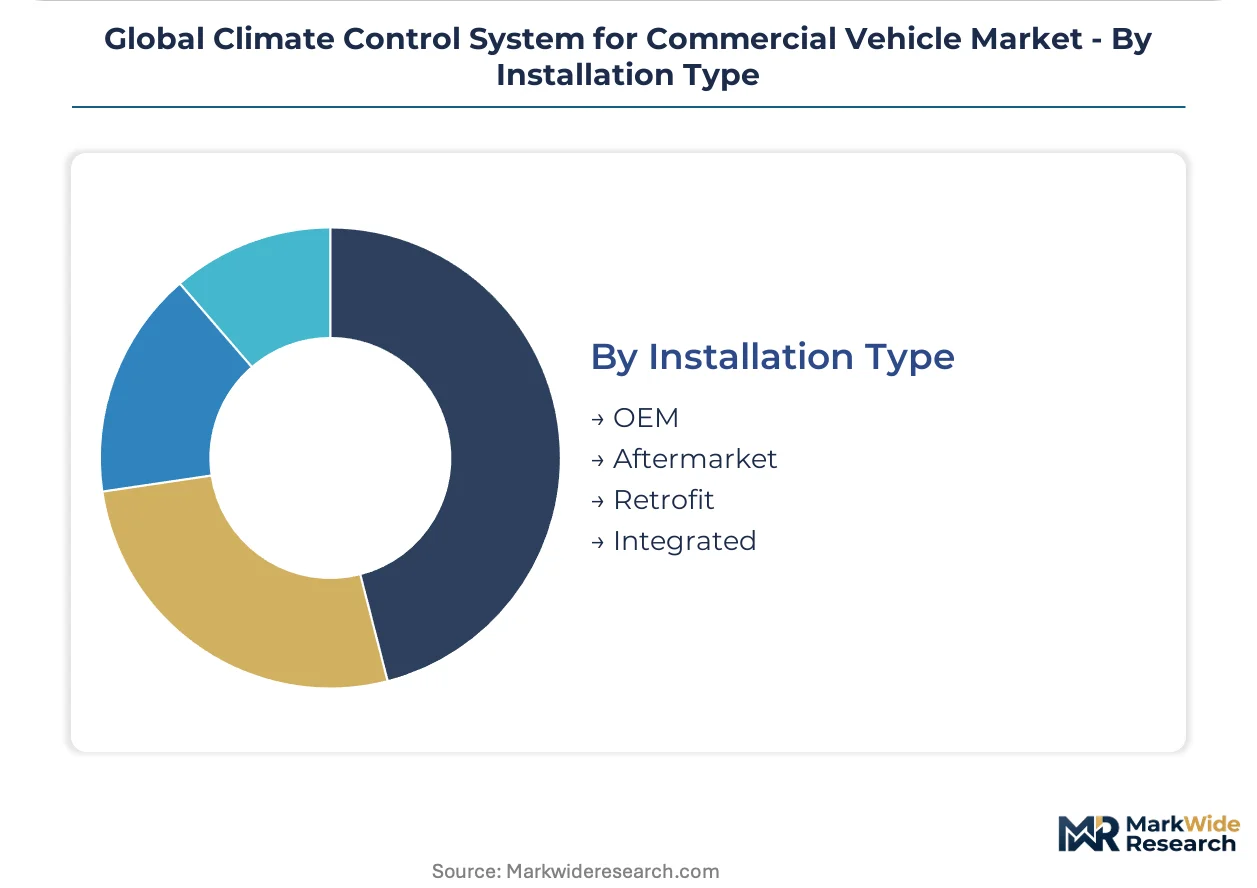
Installation Type:
Customer type stratification separates factory-integrated premium channels from price-sensitive retrofit markets, with warranty exposure and CAN-bus connectivity driving consolidation toward OEM supply relationships.
- OEM:Factory-integrated systems reduce warranty exposure and enable predictive maintenance through CAN-bus connectivity. Premium margin pools concentrate here due to design-in relationships and qualification depth requirements.
- Integrated:Unified vehicle energy management systems merge climate control with battery thermal management, compressing supplier tiers and rewarding software-integrated hardware platforms.
- Aftermarket:Service channel replacement units face refrigerant handling certification barriers and technician qualification gaps for CO2 transcritical systems.
- Retrofit:Electric compressor packages require cab structural modifications and high-voltage electrical architecture upgrades that compress installer margins.
OEM captures value concentration; integrated climbs fastest as thermal management intelligence migrates into unified vehicle energy systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor freight rail network underwrites Germany's centrality in European cold-chain logistics, while China's Belt and Road trunk lines distribute refrigerated container capacity across Eurasian trade routes.
United States
Pharmaceutical distribution corridors between New Jersey and Illinois drive refrigerated trailer deployment at accelerated replacement cycles. EPA Phase 3 greenhouse gas standards and CARB Advanced Clean Trucks regulation tighten thermal management specifications for heavy-duty OEMs. Detroit-Warren manufacturing clusters concentrate electric compressor assembly for battery-electric long-haul platforms.
Germany
Biologics cold-chain compliance between Frankfurt and Rotterdam expands trailer refrigeration unit procurement among third-party logistics fleets. EU F-Gas Regulation mandates binding refrigerant quota reductions through 2030, forcing compressor displacement redesigns. Stuttgart engineering centers prototype transcritical CO2 circuits for premium cab configurations serving Nordic export markets.
China
Domestic truck production scaling and cold-chain logistics investment concentrate demand in Yangtze River Delta food processing corridors. MIIT dual carbon goals and GB standards accelerate battery-electric commercial vehicle thermal management integration. Qingdao and Tianjin port clusters assemble aluminum microchannel heat exchangers for regional OEM supply contracts.
India
Food processing corridor investments between Maharashtra and Gujarat create first-mover advantage for telematics-enabled refrigeration units. FSSAI-mandated temperature monitoring and CDSCO pharmaceutical distribution rules expand integrated climate system specifications. Pune automotive clusters manufacture electric compressor packages for domestic electric truck platforms.
Japan
Third-party logistics fleets serving Tokyo-Osaka pharmaceutical corridors deploy predictive maintenance contracts for CAN-bus connected refrigeration systems. METI energy efficiency standards and JIS certification requirements filter aftermarket supplier participation. Nagoya manufacturing bases export integrated HVAC modules optimized for high-cabinity truck platforms across Southeast Asian markets.
Global Climate Control System for Commercial Vehicle Market Vendor Landscape
Listed leaders compete with private specialists across thermal management technology depth, with public companies commanding premium valuation multiples for electrification-ready portfolios. The vendor base stratifies into three tiers: integrated system architects owning factory-install relationships, component specialists capturing retrofit replacement cycles, and electric powertrain-thermal convergence players. Consolidation pressure concentrates among hydronic heating incumbents facing displacement by high-voltage electric architectures. Dominant competitive moves include backward integration into aluminum microchannel heat exchanger production and strategic partnerships with battery-electric truck OEMs for unified energy management system co-development.
Within the integrated system architect tier, Valeo SA and MAHLE GmbH exemplify European engineering-intensive positioning, while DENSO Corporation anchors Asian supply relationships through OEM-embedded module design. These three entities occupy positions that compress supplier tiers as thermal management intelligence migrates into unified vehicle energy systems, representing archetypes of geographic manufacturing base leverage versus R&D intensity specialization versus continental supply relationship depth.
| Leading Market Players |
|---|
| Valeo SA |
| Eberspächer Group |
| MAHLE GmbH |
| Webasto SE |
| Sanden Holdings Corporation |
| Hanon Systems |
| Bergstrom Inc. |
| Mobile Climate Control |
| DENSO Corporation |
| Others |
Supply Flow & Price Mechanics
CO2 refrigerant displacement of R-1234yf circuits is redrawing procurement geography and compressing margin structures across European and North American assembler networks. This substitution simultaneously concentrates sourcing leverage among transcritical system specialists in Germany and France while inflating technician certification costs that feed back into service pricing tiers.
Pricing Analysis
Volume-discount tiering separates fleet operators above five thousand power units from fragmented aftermarket retrofit channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and CAN-bus integration density. Pricing pressure stems from aluminum microchannel supply concentration in China and South Korea. Fleet operators exhibit lowest price sensitivity due to warranty consolidation benefits, while independent repair shops face acute cost compression from refrigerant quota volatility.
Supply Chain Analysis
Strait of Malacca transit vulnerability underwrites just-in-time aluminum microchannel delivery schedules for European system assemblers. Manufacturing gravity centers on China, South Korea, and Germany for heat exchanger cores, compressor assemblies, and refrigerant circuits respectively. Input dependencies rest on bauxite processing capacity, rare-earth magnet supply for electric compressor motors, and fluorspar derivatives for refrigerant synthesis. Tariff exposure on Chinese aluminum extrusions threatens margin stability. Distribution runs through OEM direct contracts for factory-integrated systems and authorized dealer networks for replacement units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Climate control intelligence is migrating from standalone controllers into unified vehicle energy management platforms, creating winner-take-most dynamics for software-integrated hardware suppliers. This platform-economics inflection favors ecosystem orchestrators over component specialists as battery-electric commercial vehicle architectures standardize.
For Market Incumbents: Consolidate backward integration into aluminum microchannel production to secure heat exchanger supply against Chinese export quota volatility. Deepen R&D intensity in transcritical CO2 compressor efficiency maps to defend factory-install relationships against emerging electric powertrain-thermal convergence players as EU F-Gas Regulation quotas tighten.
For New Entrants and Emerging Players: Lead with telematics-enabled predictive maintenance contracts for Indian cold-chain logistics corridors, where FSSAI-mandated temperature monitoring creates first-mover advantage for integrated system suppliers. Target third-party pharmaceutical distribution fleets in Brazil's biofuel corridor expansion zones through ANVISA-compliant refrigeration unit specifications.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hydronic heating specialists facing displacement by high-voltage electric architectures. Long-term viability hinges on acquisition targets with embedded OEM platform engineering relationships and software-defined thermal management capabilities. Monitor battery-electric truck OEM thermal load specification releases as inflection indicators for compressor architecture standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Production | Captive aluminum microchannel supply secures margin stability against Chinese export concentration. |
| CO2 Transcritical System Certification Investment | EU F-Gas Regulation quota reductions force refrigerant circuit redesign for premium cab configurations. |
| Predictive Maintenance Platform Development | CAN-bus connectivity enables outcome-based service contracts unbundled from hardware sales. |
| Battery-Electric OEM Platform Partnership | Unified energy management system co-development compresses supplier tiers toward integrated architects. |
| Indian Cold-Chain Infrastructure Deployment | FSSAI-mandated temperature monitoring creates first-mover advantage for telematics-enabled refrigeration units. |
Methodological Framework
The analysis maps electric compressor architectures, transcritical CO2 circuits, and hydronic heating systems, each validated through procurement directors at fleet operators, OEM platform engineers, aftermarket service network managers, and refrigerant handling certification bodies. Primary interview findings triangulate against customs trade data, EPA regulatory filings, EU F-Gas Regulation quota allocations, and vehicle production databases. Bottom-up unit economics and top-down market sizing converge through iterative stakeholder feedback loops.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions include product architecture, installation channel, thermal load profile, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to OEM platform launch timelines and fleet replacement cycle patterns. Forecast inputs incorporate battery-electric commercial vehicle adoption curves and cold-chain logistics infrastructure investment pipelines.
The analysis sits within stated boundaries; outcomes outside EPA Phase 3 compliance timelines or EU refrigerant phase-down schedules would require recalibration. Forecasts reflect documented assumptions on aluminum input cost trajectories and technician certification network buildout rates. Practitioners should keep alternative scenarios live as battery thermal load specifications and transcritical CO2 service infrastructure evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Brazil Automotive Hydraulic Actuators Market
Automotive Parts
France Passenger Vehicles Lubricants Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Air Filter for Automotive Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
RV Gear Reducer Market
Automotive Parts
Powerglide Shifter Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Fastener Market