
 France Passenger Vehicles Lubricants Market | 2026-2036
France Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
France Passenger Vehicles Lubricants Market Foresight
France is reshaping lubricant demand patterns through its accelerating electric vehicle transition and stringent emissions protocols. TotalEnergies leverages its domestic refining network and renewable base oil investments to anchor supply security for French OEMs. ExxonMobil Corporation competes through advanced synthetic formulations engineered for downsized turbocharged engines prevalent in the French fleet. Motul specializes in high-performance lubricants, occupying a defensible niche among premium vehicle owners and motorsport channels.
France passenger vehicles lubricants encompass formulated fluids engineered to reduce friction, dissipate heat, and protect powertrain components across internal combustion, hybrid, and electrified drivetrains, with viscosity grades typically spanning SAE 0W-16 through 5W-40 and additive packages containing detergents, dispersants, anti-wear agents, and friction modifiers. Engine oil dominates volume flows given mandatory drain intervals and widespread petrol-diesel fleet penetration, though transmission fluid and coolants are gaining structural importance as hybrid architectures proliferate and thermal management complexity rises. The aftermarket service center channel leads value capture due to bundled labor-and-fluid service models, while electric vehicle lubricants represent the fastest-growing application subset as French EV registrations climb and specialized dielectric fluids enter maintenance schedules.
France's lubricant standards align with ACEA sequences and EU REACH chemical registration requirements, while ANSM and the national environmental agency enforce waste oil collection and recycling quotas that elevate re-refining economics. The EU F-Gas Regulation and France's own climate plan are forcing reformulation toward lower-carbon base stocks and extended-drain synthetics. Stakeholders must monitor how the EU AI Act and impending battery passport requirements reshape predictive maintenance platforms and fluid subscription models.
Market Dynamics
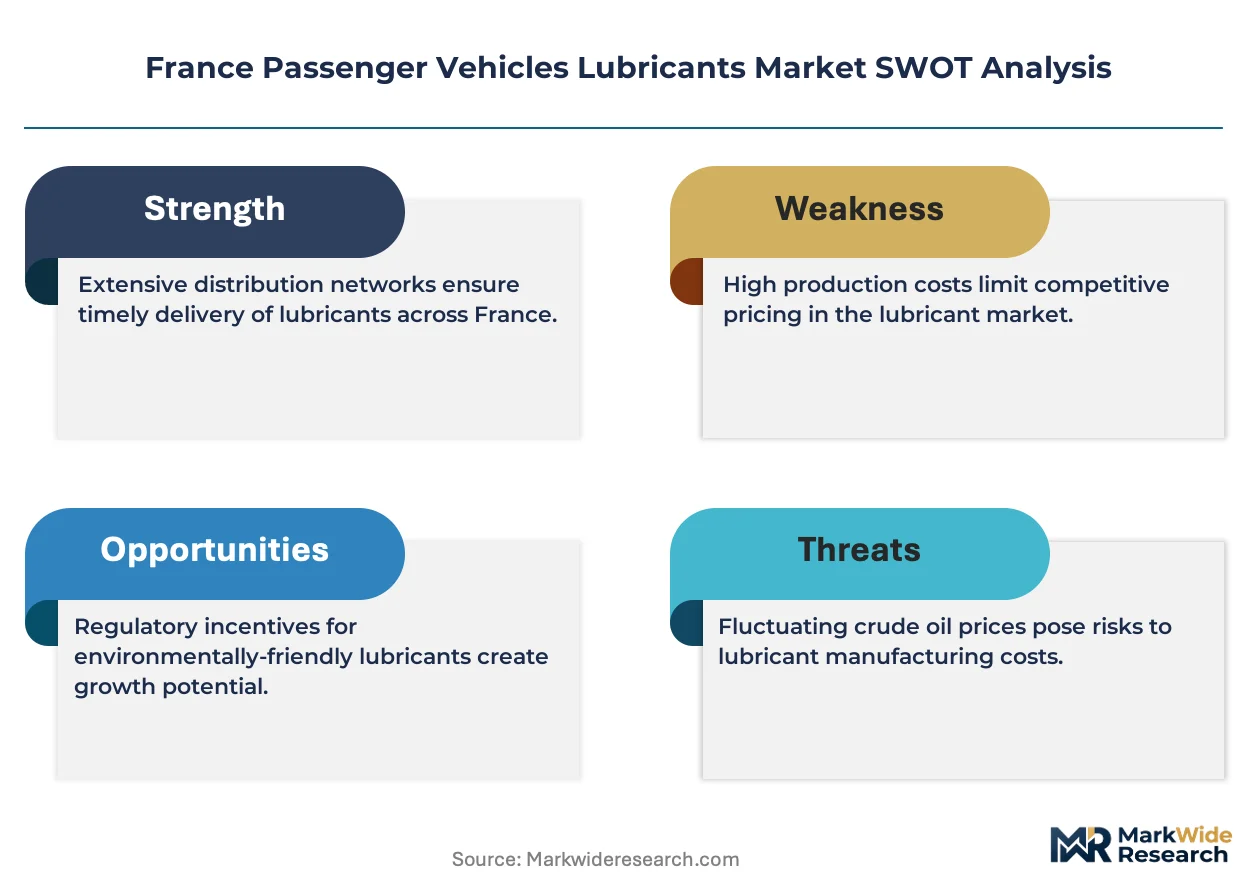
The French passenger vehicle lubricants sector faces structural compression from the national electric vehicle transition, as Paris mandates phase-out timelines for internal combustion engines while fleet operators simultaneously extend drain intervals through synthetic formulations.
Growth Catalysts
- EU Green Deal specifications:France's national low-carbon strategy tightens biodegradability requirements, pulling demand toward reformulated base stocks and extended-drain synthetics that command premium positioning.
- Fleet renewal cycles:Commercial vehicle operators across the Paris-Ile-de-France corridor are replacing aging diesel pools, creating synchronized procurement waves for high-performance engine oils.
- Hybrid drivetrain proliferation:Thermal management complexity in PHEV architectures expands the addressable market for specialized transmission fluids and dielectric coolants beyond conventional engine oils.
Market Restraints
- Base oil supply concentration:European Group III and Group IV base stock production clusters in Rotterdam and Antwerp, exposing French blenders to logistics bottlenecks and input cost volatility.
- REACH registration friction:ECHA chemical compliance timelines for novel additive packages delay product launches by 18-24 months, compressing effective patent windows.
- EV lubricant substitution:Battery electric vehicles eliminate engine oil demand entirely, with French BEV registrations accelerating faster than lubricant manufacturers can pivot portfolio mix.
Strategic Opportunities
- Predictive maintenance platforms:The EU AI Act creates regulatory clarity for algorithmic fluid monitoring systems, enabling subscription-based lubricant delivery models tied to real-time vehicle diagnostics.
- Dielectric fluid specialization:Battery thermal management requirements in French EVs open white space for immersion cooling formulations with electrical insulating properties absent from legacy products.
- Re-refining infrastructure:ANSM waste oil collection quotas elevate circular economy economics, positioning domestic re-refiners to capture margin from mandated recycling flows.
Industry Challenges
- Formulation talent scarcity:Tribology and additive chemistry expertise concentrates at retiring generations, with French technical universities producing insufficient replacement pipeline for specialized lubricant engineering.
- Dual certification complexity:Simultaneous ACEA sequence updates and OEM factory-fill approvals require parallel testing tracks, straining R&D laboratory capacity and extending time-to-market.
- Legacy distribution integration:Independent service centers resist digital inventory management platforms, fragmenting demand visibility for predictive production planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Passenger Vehicles Lubricants Market |
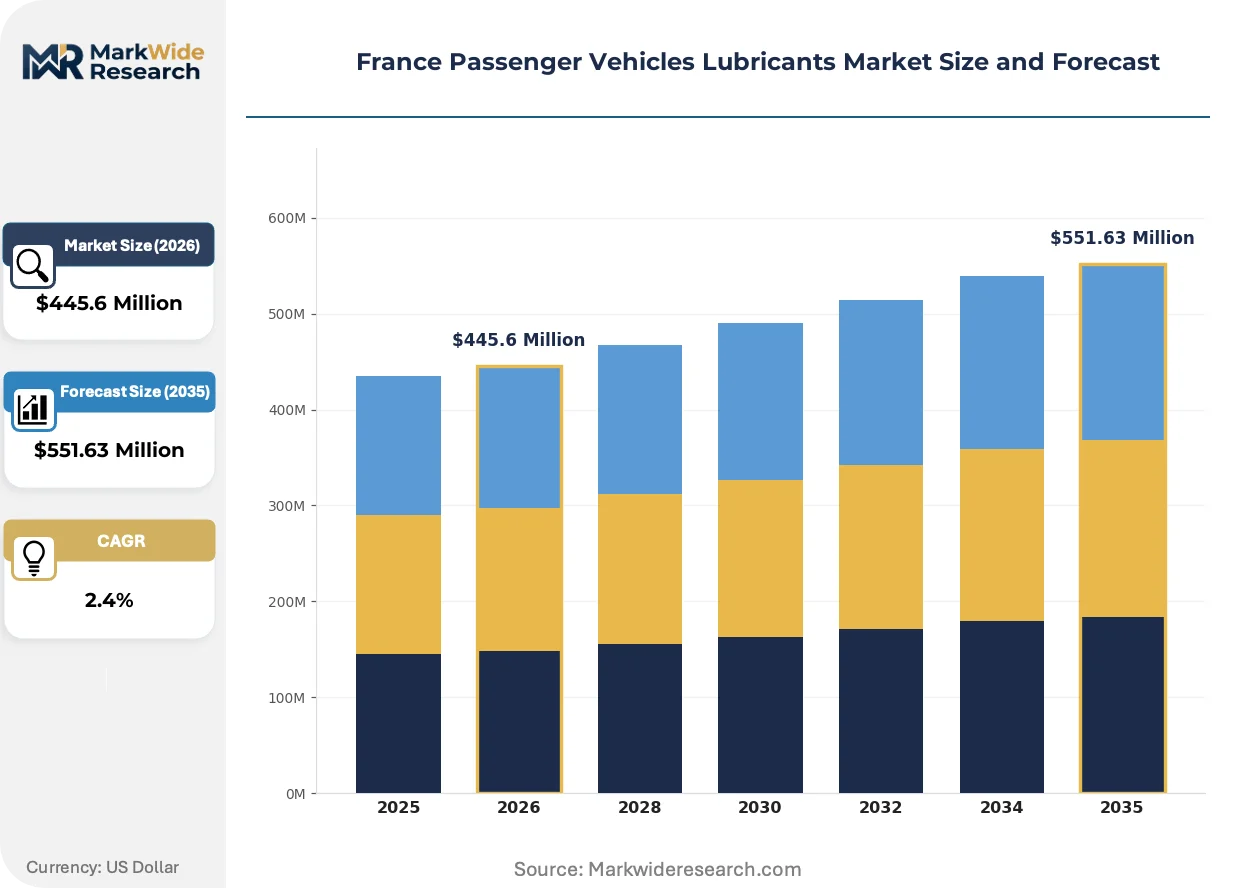
| Market Size in 2026 | $445.6 Million |
| Market Size in 2035 | $551.63 Million |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Brake Fluid, Coolants Application: Petrol Vehicles, Diesel Vehicles, Hybrid Vehicles, Electric Vehicles, Alternative Fuel Vehicles Packaging Type: Can, Drum, Pouch, Bulk, Bottle End User: OEMs, Aftermarket Service Centers, Fleet Operators, Independent Garages, Retail Consumers |
| Companies Covered | TotalEnergies, ExxonMobil Corporation, BP PLC (Castrol), Royal Dutch Shell Plc, Motul, Chevron Corporation, Fuchs Petrolub SE, Eni SpA, Liqui Moly, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Passenger Vehicles Lubricants Market Shifts & Advancements
Synthetic formulation chemistry and electrification-compatible fluids are restructuring competitive advantage in French lubricant supply, with regulatory pressure on carbon intensity accelerating technical differentiation beyond traditional viscosity positioning.
Lower-viscosity SAE 0W-16 and 0W-20 grades reduce parasitic friction losses in downsized turbocharged gasoline engines prevalent across French OEM lineups. PSA Stellantis and Renault Group factory-fill specifications now exclude conventional mineral oils from new vehicle warranties. This viscosity compression is rendering obsolete high-volume 5W-30 formulations that dominated the French aftermarket for two decades.
France's climate plan implements carbon intensity scoring for industrial products, including lubricant lifecycle assessments from base oil extraction through end-of-life recycling. The national environmental agency enforces disclosure requirements that disadvantage imported formulations with higher upstream emissions. Domestic blenders with renewable base oil investments capture preferential positioning in public fleet tenders.
Service bundling unravels as fleet operators separate fluid procurement from maintenance labor, negotiating direct supply agreements with lubricant manufacturers. Independent quick-lube chains in Lyon and Marseille disintermediate traditional distributor networks, capturing volume through price transparency and consolidated national contracts. This channel compression concentrates purchasing power among fewer buyers, pressuring margin structures for mid-tier brands dependent on fragmented garage networks.
France Passenger Vehicles Lubricants Market Segmentation
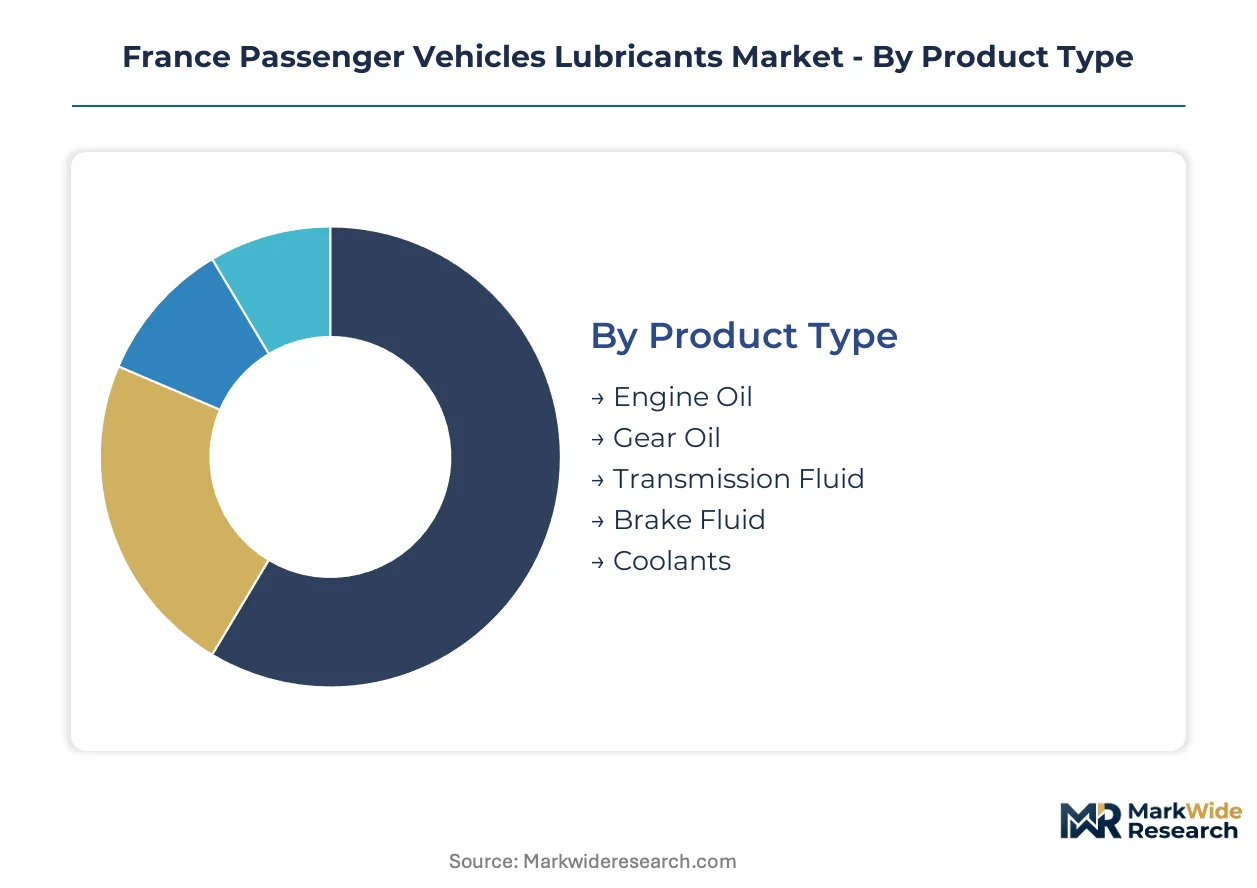
Segmentation in France's passenger vehicle lubricants market reveals how product specifications, drivetrain architectures, and procurement channels are diverging under regulatory pressure. Understanding these splits exposes where margin pools are concentrating and which customer relationships offer defensible positioning.
Product Type:
Use-case spectrum spans combustion-era fluids through electrification-compatible formulations, with viscosity grades and additive packages calibrated to thermal stress profiles.
- Engine Oil:Formulations span SAE 0W-16 through 5W-40 grades with detergent-dispersant packages engineered for PSA Stellantis and Renault Group factory-fill specifications. Demand concentrates in the Paris-Ile-de-France corridor where vehicle density sustains high-frequency drain intervals, though synthetic extended-drain formulations are compressing volume-per-vehicle.
- Transmission Fluid:Specialized ATF and DCT formulations serve dual-clutch and torque-converter architectures proliferating across French OEM lineups. Hybrid drivetrain adoption in Lyon and Marseille metropolitan areas is pulling demand toward low-viscosity, high-oxidation-stability grades absent from legacy product portfolios.
- Gear Oil:Hypoid gear lubricants with extreme-pressure additives protect differential and final-drive components.
- Brake Fluid:Glycol-ether and silicone-based formulations meeting DOT 4 and DOT 5.1 specifications for hydraulic brake systems.
- Coolants:Ethylene glycol and propylene glycol formulations with corrosion inhibitors for thermal management.
Established volume favors Engine Oil; emerging adoption favors Transmission Fluid.
Application:
Powertrain architecture segmentation tracks France's national low-carbon strategy and the EU Green Deal's phase-out timelines for internal combustion engines.
- Petrol Vehicles:Downsized turbocharged gasoline engines dominate French OEM production, requiring low-viscosity 0W-20 and 0W-30 synthetics with turbocharger deposit control additives. The Paris-Ile-de-France corridor retains concentrated petrol fleet penetration among private vehicle owners.
- Hybrid Vehicles:PHEV architectures combine thermal management complexity with intermittent engine operation, demanding fluids resistant to fuel dilution and electrical conductivity. French hybrid registrations are climbing fastest in Lyon, creating procurement pull for specialized transmission fluids and dielectric coolants.
- Diesel Vehicles:Compression-ignition engines with DPF and SCR aftertreatment systems requiring low-SAPS formulations.
- Electric Vehicles:Battery electric drivetrains eliminate engine oil demand while introducing dielectric fluid requirements for battery thermal management.
- Alternative Fuel Vehicles:CNG and hydrogen combustion engines with modified lubricant compatibility requirements.
Current revenue concentration sits with Petrol Vehicles; steepest expansion trajectory belongs to Hybrid Vehicles.
Packaging Type:
Packaging segmentation reflects procurement scale economics and regulatory pressure on waste generation across French distribution channels.
- Bulk:Tanker and intermediate bulk container deliveries serve fleet operators and quick-lube chains negotiating direct supply agreements, minimizing per-unit packaging cost and waste oil generation. ANSM collection quotas favor bulk systems that simplify re-refining logistics.
- Drum:200-liter steel drums dominate independent garage procurement in secondary French cities where volume does not justify bulk infrastructure.
- Bottle:Retail-sized containers for DIY maintenance and emergency top-up purchases.
- Can:Metal and composite cans for mid-volume professional and retail channels.
- Pouch:Flexible film packaging for single-use and sample applications.
Cost efficiency favors Bulk; channel flexibility favors Bottle.
End User:
Customer-type segmentation exposes how procurement authority is shifting from fragmented service networks toward consolidated fleet and direct OEM relationships.
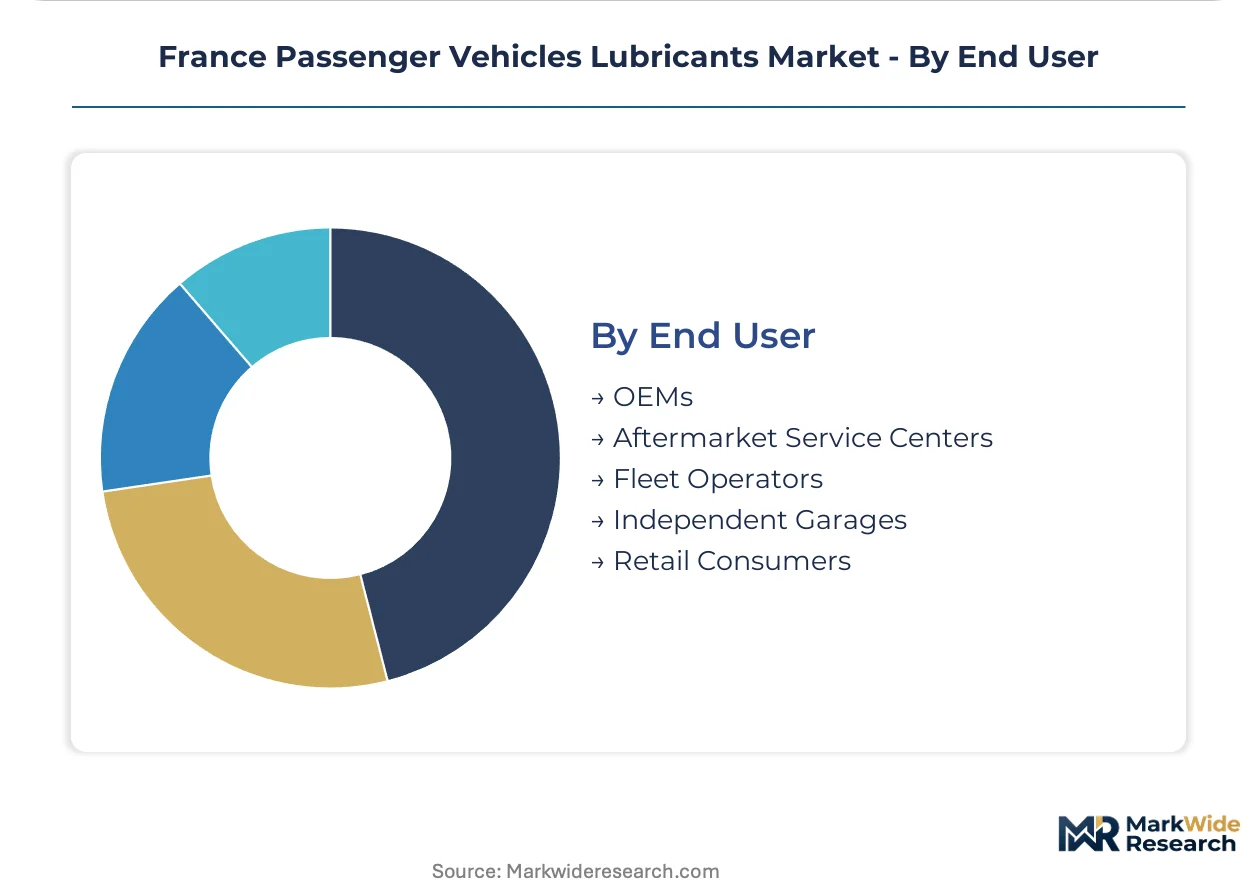
- Aftermarket Service Centers:Bundled labor-and-fluid service models capture value through mandated drain intervals and warranty compliance requirements. The Paris-Ile-de-France corridor hosts the densest concentration of authorized service centers, though independent quick-lube chains in Lyon and Marseille are disintermediating traditional distributor networks.
- Fleet Operators:Commercial vehicle pools across the Paris-Ile-de-France corridor are synchronizing lubricant procurement with vehicle renewal cycles, negotiating national contracts that bypass regional distributors. ANSM waste oil quotas and carbon intensity scoring favor suppliers with domestic re-refining capabilities.
- OEMs:Factory-fill specifications from PSA Stellantis and Renault Group exclude conventional mineral oils from new vehicle warranties.
- Independent Garages:Fragmented repair shops resisting digital inventory management platforms.
- Retail Consumers:DIY purchasers through automotive retail chains and e-commerce platforms.
Purchasing power concentrates with Fleet Operators; relationship fragmentation persists with Independent Garages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Group III and Group IV base stock production clusters in Rotterdam and Antwerp expose French blenders to logistics bottlenecks. Domestic re-refining capacity concentrates around Lyon and the Paris periphery where ANSM collection quotas elevate circular economics.
Île-de-France
Fleet operators across the Paris-Ile-de-France corridor synchronize lubricant procurement with vehicle renewal cycles. ANSM waste oil quotas and carbon intensity scoring favor suppliers with domestic re-refining capabilities. The metropolitan concentration hosts the densest authorized service center network, though quick-lube chains are disintermediating traditional distributors.
Auvergne-Rhône-Alpes
Hybrid vehicle registrations climb fastest in Lyon, pulling procurement toward specialized transmission fluids and dielectric coolants. The EU Green Deal tightens biodegradability requirements for formulations used in this manufacturing-heavy region. Re-refining infrastructure investments cluster around Saint-Étienne and Grenoble to capture mandated recycling flows.
Provence-Alpes-Côte d'Azur
Marseille quick-lube chains consolidate purchasing power through national contracts that bypass regional distributors. France's national low-carbon strategy implements carbon intensity scoring that disadvantages imported formulations with higher upstream emissions. The port infrastructure supports bulk lubricant deliveries serving fleet operators along the Mediterranean corridor.
Hauts-de-France
Industrial vehicle pools in Lille and the broader northern manufacturing belt maintain diesel-heavy fleets requiring low-SAPS formulations. ECHA REACH compliance timelines for novel additive packages delay product launches, compressing effective patent windows. The region's logistics hubs sustain drum-based procurement for independent garages below bulk-scale thresholds.
Nouvelle-Aquitaine
Bordeaux and the southwestern corridor exhibit fragmented independent garage networks resisting digital inventory management platforms. The EU F-Gas Regulation forces reformulation toward lower-carbon base stocks for climate-controlled vehicle applications. Agricultural vehicle fleets in the rural periphery sustain demand for conventional mineral oil grades excluded from new vehicle warranties.
France Passenger Vehicles Lubricants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation chemistry and additive packages. The French passenger vehicle lubricants sector exhibits consolidated upstream supply with tiered downstream distribution. Three archetypes dominate: integrated energy majors with domestic refining networks, global lubricant specialists with advanced synthetic portfolios, and regional formulators serving niche motorsport and premium channels. Competitive moves center on backward integration into renewable base oil production and direct fleet supply agreements that disintermediate traditional distributors.
Among integrated energy majors, TotalEnergies anchors supply security through its domestic refining network and renewable base oil investments. ExxonMobil Corporation exemplifies the global lubricant specialist archetype with advanced synthetic formulations. Motul occupies a defensible position among premium vehicle owners and motorsport channels, representing the regional formulator tier. These three players illustrate how technical differentiation, geographic proximity to demand clusters, and compliance with ANSM recycling quotas structure competitive positioning in the French market.
| Leading Market Players |
|---|
| TotalEnergies |
| ExxonMobil Corporation |
| BP PLC (Castrol) |
| Royal Dutch Shell Plc |
| Motul |
| Chevron Corporation |
| Fuchs Petrolub SE |
| Eni SpA |
| Liqui Moly |
| Others |
Supply & Pricing Matrix
Rotterdam and Antwerp base stock concentration funnels pricing power toward integrated energy majors while compressing margin capture for independent French blenders dependent on spot procurement. ACEA sequence compliance costs and ANSM recycling quota investments propagate downstream through tiered pricing structures that separate factory-fill synthetics from aftermarket mineral formulations.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across the French lubricant sector. Three-tier pricing separates extended-drain synthetics from conventional mineral grades from economy re-refined products. Price differentiation centers on carbon intensity scoring and biodegradability certification under France's national climate plan. Cost compression in the mid-tier is intensifying because quick-lube chains consolidate purchasing power through national contracts. Fleet operators exhibit lowest price sensitivity due to bundled service models, while independent garages face acute margin pressure from transparent pricing platforms.
Supply Chain Analysis
European toll blenders and contract manufacturers in the Netherlands, Belgium, and Germany hold capacity for finished lubricant production. French supply chains draw from Group III base stocks sourced from Rotterdam-Antwerp clusters, additive packages from specialty chemical producers, and renewable base oils from domestic biorefinery investments. Single-source vulnerability concentrates in European Group IV PAO production. Distribution runs through authorized service centers in the Paris-Ile-de-France corridor, quick-lube chains in Lyon and Marseille, and fragmented independent garage networks in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across the Paris-Ile-de-France corridor is shifting procurement authority away from fragmented distributor networks toward direct manufacturer relationships.
For Market Incumbents: Harden supply security through backward integration into renewable base oil production at domestic biorefinery sites. Deepen channel control by capturing quick-lube chain national contracts before independent distributors consolidate. Battery electric vehicle substitution threatens engine oil volume; pivot portfolio mix toward dielectric fluids and thermal management formulations for hybrid architectures. For New Entrants and Emerging Players: The Auvergne-Rhône-Alpes region outside Lyon presents underpenetrated white space for specialized transmission fluids serving climbing hybrid registrations. Dielectric coolant formulations for battery thermal management offer the most penetrable application segment given incumbent product portfolio gaps. A technical partnership with domestic re-refiners satisfies ANSM collection quotas while bypassing capital-intensive base stock production. For Investors and Strategic Acquirers: Capital is best deployed toward regional formulators with motorsport certification and premium channel access that incumbent energy majors cannot replicate. Long-term viability hinges on electrification-compatible fluid portfolios and circular economy infrastructure. Monitor French BEV registration trajectories as the inflection signal for engine oil demand compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Base Oils | Captures margin from EU Green Deal carbon intensity scoring for domestic biorefinery output. |
| Dielectric Fluid Specialization | Addresses battery thermal management white space as French EV registrations accelerate maintenance demand. |
| Quick-Lube Chain National Contracts | Concentrates purchasing power among fewer buyers, disintermediating traditional regional distributors. |
| Re-Refining Infrastructure Investment | Positions domestic operators to capture margin from ANSM-mandated waste oil collection quotas. |
| Predictive Maintenance Platform Development | Enables subscription lubricant delivery models under EU AI Act regulatory clarity for algorithmic monitoring. |
Research Methodology
Initial hypotheses were tested against primary input from lubricant procurement managers at fleet operators, technical directors at OEM factory-fill operations, aftermarket service center owners, and re-refining facility operators, then refined through secondary validation against ACEA technical documentation, ANSM regulatory filings, EU ECHA REACH registration databases, and French vehicle registration statistics. Bottom-up volume estimates from segment-level procurement patterns were triangulated with top-down market sizing from base stock production and trade flow analysis.
Demand-supply balance modeling across the projection horizon incorporated powertrain architecture transitions, drain interval extensions from synthetic formulations, and regulatory phase-out timelines for internal combustion engines. Segmentation dimensions included product viscosity grade, vehicle propulsion type, packaging format, and procurement channel structure. CAGRs were derived from regression analysis of historical volume patterns against fleet renewal cycles and electrification adoption curves, with specific inputs from hybrid drivetrain thermal management complexity and carbon intensity scoring implementation.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated energy majors or disruptive pricing by quick-lube consolidators would shift outcomes beyond modeled ranges. Quarterly review of French BEV registration data, ACEA sequence update timelines, and ANSM enforcement patterns for waste oil quotas is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Lubricants Market
Automotive Parts
Automotive Brake Fluid Market
Automotive Parts
Air Suspension Systems Market
Automotive Parts
Engine Oil Market
Automotive Parts
Qatar Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Weatherstrips Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
Automotive Canister Market
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market