
 Global Cigarette Packaging Market | 2026-2036
Global Cigarette Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cigarette Packaging Market Analysis
Chinese paperboard producers is shifting capacity toward specialty cigarette-grade substrates to serve export markets. Amcor plc leverages its integrated film-to-carton capabilities across multiple continents. WestRock Company anchors North American supply through high-volume folding carton operations. Mondi Group differentiates via sustainable fiber sourcing for regulated European markets.
Cigarette packaging denotes engineered paperboard, plastic, metal, or composite enclosures designed to protect tobacco sticks from moisture, preserve aroma, and display mandated health warnings across primary, secondary, and tertiary containment levels. Manufacturing employs gravure or offset printing on clay-coated recycled board, followed by die-cutting, embossing, and foil stamping to achieve dimensional tolerances of 0.5 millimeters for high-speed packing lines. Flip-top boxes dominate volume due to structural familiarity and machine compatibility, while rigid boxes command margin pools in the premium segment. Eco-friendly design types are gaining share as brand owners face ESG disclosure requirements.
FDA authority over modified risk tobacco product claims and the EU Tobacco Products Directive's standardized packaging rules jointly constrain graphic design freedom and mandate specific material opacity levels. China's SAMR enforces GB standards for packaging recyclability that affect export-bound production. Stakeholders must monitor evolving plain packaging scope expansions and pre-position compliant substrate inventories ahead of enforcement timelines.
Market Dynamics
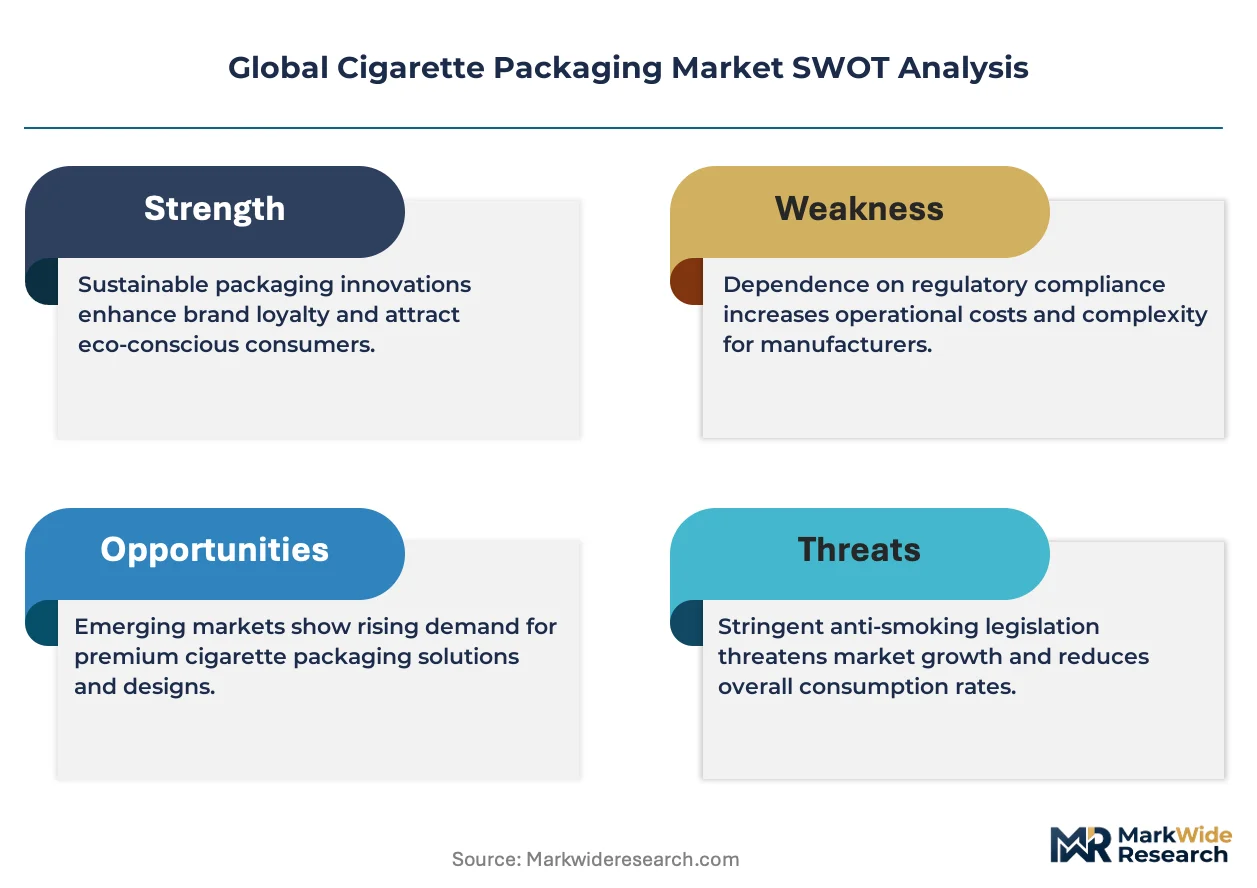
Plain packaging mandates across multiple jurisdictions are forcing substrate substitutions and pressuring brand differentiation, while premium segment demand in emerging economies creates countervailing pull toward high-margin rigid formats.
Growth Catalysts
- EU Tobacco Products Directive:Standardized packaging rules accelerate compliant paperboard adoption as manufacturers pre-position inventory ahead of enforcement timelines.
- Premium tobacco brands:Emerging economy consumers in Indonesia and Vietnam drive rigid box and magnetic closure adoption for margin expansion.
- High-speed packing lines:Die-cutting and foil stamping precision tolerances of 0.5 millimeters enable automation upgrades across Southeast Asian manufacturing hubs.
Market Restraints
- Graphic design constraints:FDA modified risk claim restrictions and EU opacity mandates compress creative differentiation and limit premium positioning tools.
- Recycled fiber volatility:Clay-coated recycled board supply concentrates among integrated paperboard producers, exposing converters to input cost swings.
- Substitution pressure:Heated tobacco and nicotine pouch formats reduce cigarette stick volumes in regulated European markets.
Strategic Opportunities
- Vietnam manufacturing expansion:Underdeveloped domestic packaging capacity creates first-mover advantage for substrate suppliers establishing localized production.
- ESG disclosure requirements:Sustainable fiber sourcing mandates from the EU Green Deal favor converters with certified chain-of-custody documentation.
- Smart packaging convergence:Near-field communication chips and authentication holograms merge with traditional carton structures for anti-counterfeiting and consumer engagement.
Industry Challenges
- Gravure-to-offset transition:Skilled press operators capable of managing substrate-specific ink adhesion properties remain scarce in expanding Southeast Asian hubs.
- Multi-jurisdiction compliance:Simultaneous adherence to China's GB recyclability standards, EU opacity rules, and FDA labeling requirements strains quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cigarette Packaging Market |
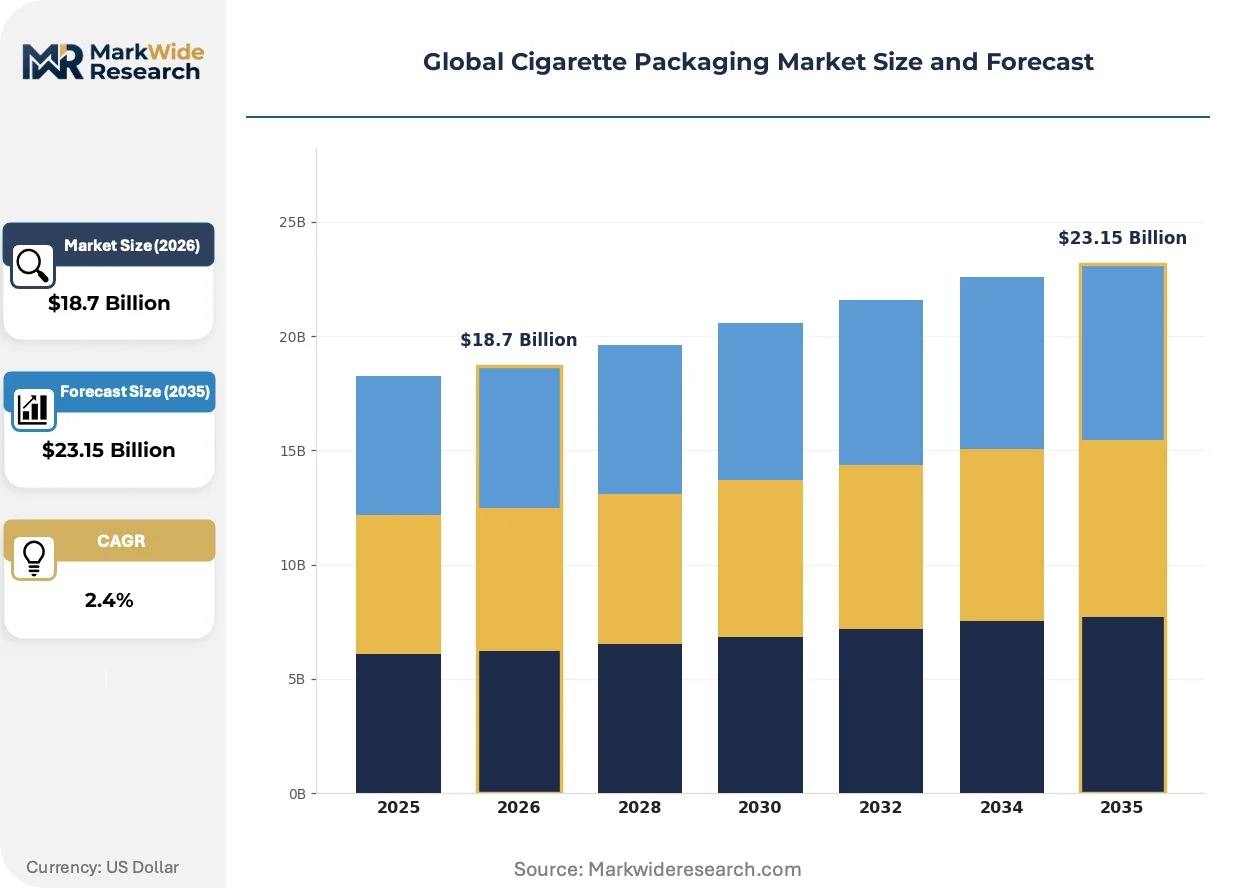
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $23.15 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flip-top Boxes, Rigid Boxes, Soft Packs, Cartons Material: Paperboard, Plastic, Metal, Composite Design Type: Custom Print, Standard Design, Eco-friendly, Premium Closure Type: Standard Seal, Die-cut, Tuck End, Magnetic Closure |
| Companies Covered | Amcor plc, WestRock Company, Mondi Group, Delfort Group, TANN Group, Jinjia Group, International Paper Company, Smurfit Kappa Group, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cigarette Packaging Market Emerging Trajectories
Material science advances and authentication technologies are redefining functional requirements, while regulatory harmonization efforts create both compliance burdens and standardization opportunities across production networks.
Biodegradable barrier coatings are electrifying moisture protection performance in paperboard primary packs. Premium brands in Indonesia and Vietnam are piloting these substrates for export-bound production. The technology is electrifying competitive positioning by enabling compliance with EU single-use plastics directives while preserving shelf-life performance.
REACH substance restrictions on certain ink chemistries are forcing reformulation across European supply chains. Gravure and offset houses must validate new pigment systems against established color-matching protocols. Specialty cigarette-grade substrate producers in China are accelerating compliant coating development to maintain export access.
Brand owners now specify chain-of-custody certification as a non-negotiable procurement criterion. European tobacco multinationals are consolidating supplier panels to favor integrated fiber-to-carton operators with FSC or PEFC documentation. This preference shift is most visible in regulated markets where ESG disclosure requirements intersect with consumer-facing sustainability claims.
Global Cigarette Packaging Market Segmentation
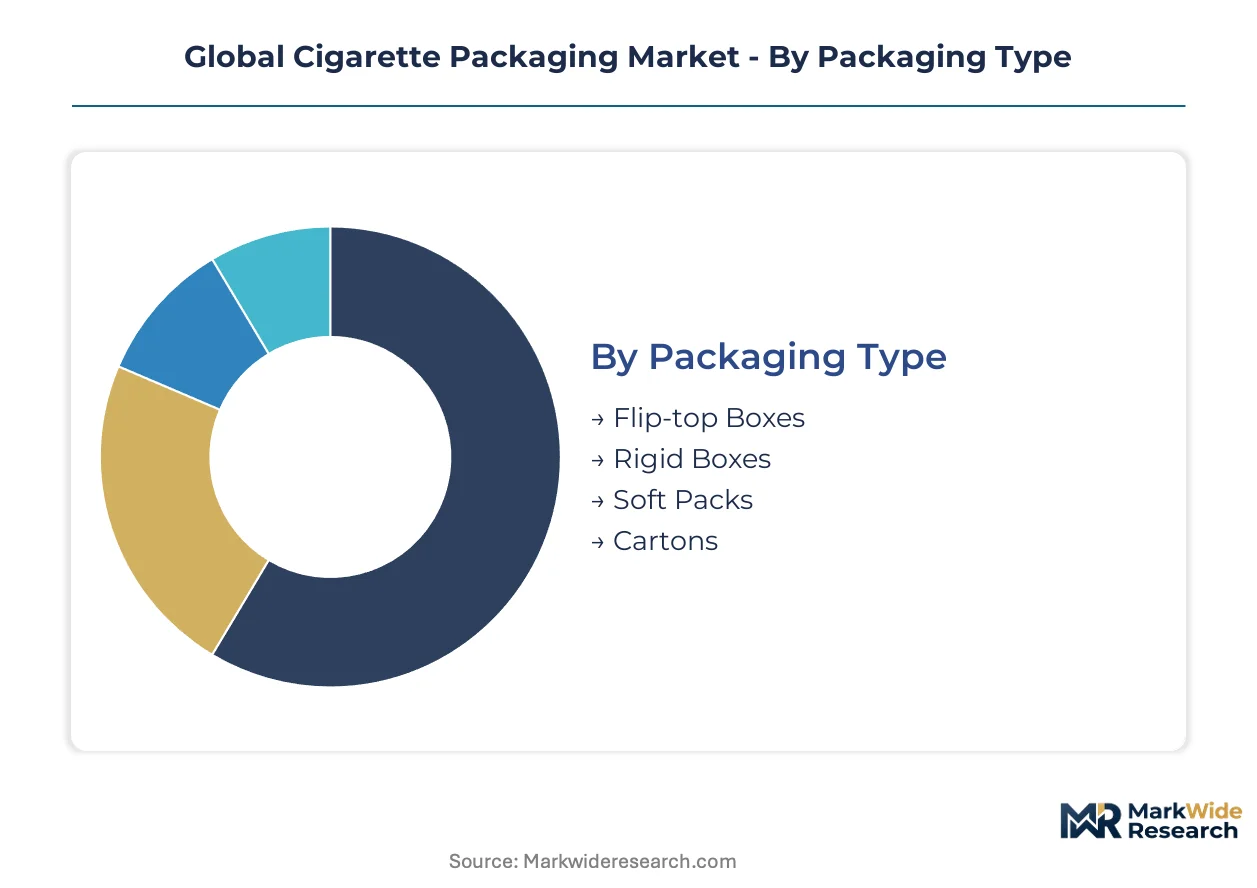
Cigarette packaging segmentation reflects divergent upgrade cycles across premiumization trends and regulatory compliance waves. Material and design choices increasingly bifurcate between cost-optimized mass-market formats and value-engineered premium structures.
Packaging Type:
Replacement cycles vary sharply between machine-compatible flip-top formats and artisanal rigid constructions targeting emerging-market premiumization.
- Flip-top Boxes:Engineered paperboard shells with hinged lids deliver dimensional stability within 0.5 millimeter tolerances for high-speed packing automation. Demand concentrates in Southeast Asian manufacturing hubs where Indonesia and Vietnam anchor volume production for both domestic consumption and export processing.
- Rigid Boxes:Thick-walled paperboard or composite structures with reinforced corners provide tactile premium positioning through substantial hand-feel. Emerging economy consumers in Vietnam and Indonesia drive adoption as tobacco multinationals seek margin expansion through luxury-tier portfolio extensions.
- Soft Packs:Flexible paper or film laminates without structural rigidity serve price-sensitive segments and traditionalist smoker preferences.
- Cartons:Multi-pack aggregation containers protect ten-pack configurations through distribution and retail display.
Flip-top boxes sit at the top of the volume ranking, with rigid boxes climbing the fastest.
Material:
Cost tiering separates commodity substrates from certified specialty grades commanding procurement premiums.
- Paperboard:Clay-coated recycled board dominates through gravure and offset print compatibility combined with EU Tobacco Products Directive compliance for opacity and health warning display. Chinese producers are shifting capacity toward cigarette-grade specialty substrates to capture export demand from regulated European markets.
- Plastic:Polypropylene and oriented films provide moisture barriers and tamper-evident sealing for tropical climate distribution. Southeast Asian brand owners specify these substrates for domestic supply chains where humidity degradation risks exceed regulatory substitution pressures.
- Metal:Tinplate and aluminum enclosures serve collectible and ultra-premium limited editions with extended shelf-life requirements.
- Composite:Multi-layer paperboard-film laminates balance structural integrity with barrier performance for mid-tier positioning.
Paperboard commands the widest procurement footprint, while composite laminates gain share fastest among converters seeking regulatory pre-positioning flexibility.
Design Type:
Application context determines whether brand differentiation or compliance minimalism drives specification.
- Custom Print:Gravure or offset reproduction of proprietary brand assets with foil stamping and embossing enables trademark recognition where regulatory frameworks permit graphic freedom. Premium tobacco brands in emerging economies deploy these designs for competitive differentiation ahead of potential plain packaging expansion.
- Eco-friendly:Biodegradable barrier coatings and certified fiber sourcing address EU Green Deal disclosure requirements and single-use plastics directives. European tobacco multinationals now mandate chain-of-custody documentation as non-negotiable procurement criteria.
- Standard Design:Template-based artwork with minimal customization serves contract manufacturing and private-label production.
- Premium:Holographic authentication features and specialty substrates support anti-counterfeiting and luxury positioning.
Custom print retains the largest specification base, with eco-friendly designs expanding most quickly under ESG disclosure acceleration.
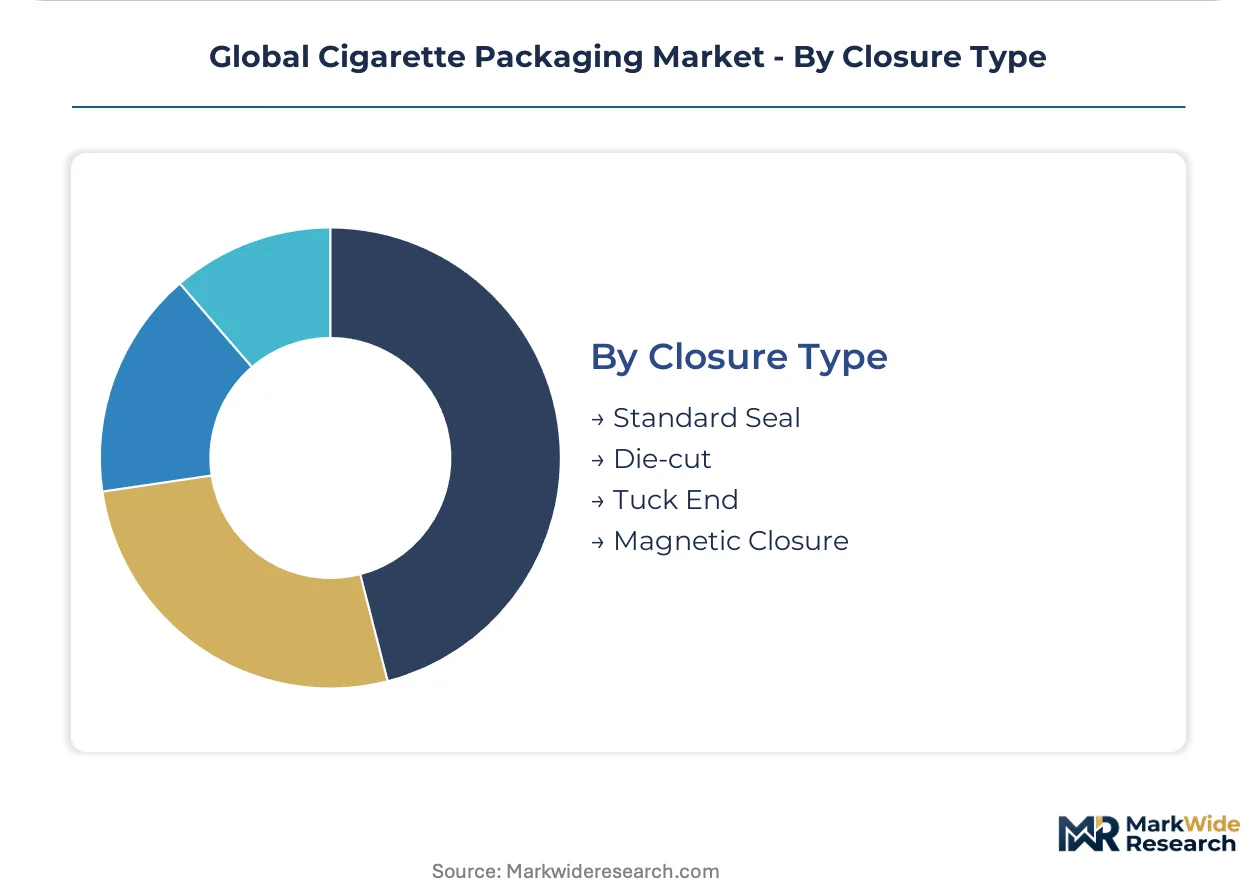
Closure Type:
Volume scale separates high-automation seal formats from low-throughput premium mechanisms.
- Standard Seal:Heat-activated adhesives and pressure-sensitive tapes enable fastest line speeds with minimal operator intervention. Mass-market production across Indonesian and Vietnamese manufacturing hubs relies on these mechanisms for throughput maximization.
- Magnetic Closure:Embedded ferrite or neodymium elements deliver satisfying tactile feedback and reseal functionality for premium user experience. Emerging-market luxury segments in Vietnam and Indonesia specify these closures for rigid box formats targeting affluent smoker demographics.
- Die-cut:Precision-cut paperboard tabs interlock without additional fasteners for cost-optimized structural integrity.
- Tuck End:Folded paperboard flaps insert into receiving slots for simple manual or semi-automated assembly.
Standard seal mechanisms dominate throughput metrics, with magnetic closure specifications gaining share fastest among premium portfolio expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting production toward jurisdictions where compliance costs remain manageable. Chinese substrate specialists now supply European converters facing REACH reformulation deadlines. Southeast Asian manufacturing hubs capture volume migration from regulated markets.
China
Specialty cigarette-grade paperboard capacity is expanding in Shandong and Guangdong provinces to serve export demand. SAMR enforces GB standards for packaging recyclability that affect production bound for regulated markets. Zhejiang-based converters are pre-positioning compliant coating inventories ahead of EU enforcement timelines.
Indonesia
Domestic tobacco consumption and regional export processing drive demand for both flip-top and rigid box formats. The national standards body regulates packaging material safety for food-contact applications. Jakarta-Bandung manufacturing corridors host expanding die-cutting and foil stamping operations serving premium brand portfolios.
Vietnam
Underdeveloped domestic packaging capacity creates first-mover opportunities for substrate suppliers establishing localized production. The Ministry of Science and Technology oversees product quality and labeling standards for imported materials. Ho Chi Minh City industrial zones are attracting gravure press installations to serve regional cigarette manufacturing.
Germany
REACH substance restrictions on certain ink chemistries are forcing reformulation across European supply chains. The ECHA maintains the central registry of restricted substances affecting packaging materials. Baden-Württemberg printing houses are validating new pigment systems against established color-matching protocols.
United States
FDA authority over modified risk tobacco product claims constrains graphic design freedom for domestic packaging. The agency mandates specific material opacity levels and health warning display requirements. Virginia and North Carolina tobacco manufacturing clusters drive demand for high-speed packing line compatibility.
Global Cigarette Packaging Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty substrate and sustainable certification niches. The market structure reflects moderate consolidation among integrated paperboard-to-carton operators alongside fragmentation in regional converting. Three archetypes dominate: multinational integrated packaging groups with film-to-carton capabilities, specialty paperboard producers focused on cigarette-grade substrates, and regional converters serving single-market brand owners. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing fiber supply agreements and authentication technology licenses.
Within the integrated multinational tier, Amcor plc and Mondi Group occupy positions exemplifying cross-continental film and fiber capabilities. WestRock Company anchors North American supply through high-volume folding carton operations. Among Asia-Pacific specialists, Jinjia Group represents the regional converter archetype serving domestic and export demand from Chinese manufacturing bases.
| Leading Market Players |
|---|
| Amcor plc |
| WestRock Company |
| Mondi Group |
| Delfort Group |
| TANN Group |
| Jinjia Group |
| International Paper Company |
| Smurfit Kappa Group |
| Sonoco Products Company |
| Others |
Supply Flow & Price Mechanics
Recycled pulp price indices cascading through clay-coated board converters are compressing margin pools at the gravure-printing tier while amplifying procurement premiums for FSC-certified specialty substrates serving European brand owners.
Pricing Analysis
Distributor markups on cigarette-grade paperboard vary with certification tier and volume commitment, with mass-market converters absorbing cost compression from integrated Chinese suppliers while premium rigid-box specialists pass through magnetic closure premiums to emerging-market brand owners in Indonesia and Vietnam. Price differentiation hinges on chain-of-custody documentation and die-cutting precision tolerances, with ESG-mandated buyers least sensitive to per-unit premiums. Pricing pressure intensifies in standard flip-top formats as Southeast Asian capacity expansion outpaces regional demand growth.
Supply Chain Analysis
Return flows of obsolete printing cylinders and decommissioned gravure presses from European converters to Chinese refurbishment specialists illustrate circular resource recovery patterns in this capital-equipment-intensive sector. Raw material sourcing concentrates in Chinese specialty paperboard producers, Indonesian fiber plantations, and German ink formulation houses, with clay-coated recycled board and REACH-compliant pigment systems as critical dependencies. Single-source vulnerability sits with integrated paperboard-to-carton operators controlling cigarette-grade substrate supply. Distribution runs through regional converting hubs in Ho Chi Minh City industrial zones and Jakarta-Bandung corridors serving tobacco multinationals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cigarette packaging market represents a late-cycle quality story where emerging-market premiumization toward rigid boxes and magnetic closures sustains margin expansion despite regulatory compression on graphic differentiation.
For Market Incumbents: Cement backward integration into certified fiber sourcing to lock in FSC and PEFC documentation ahead of EU Green Deal procurement mandates, while consolidating gravure press capacity in Vietnam and Indonesia to capture regional volume migration from regulated European markets. Heated tobacco substitution in Western Europe and plain packaging scope expansion constitute the primary demand threats. For New Entrants and Emerging Players: Begin with biodegradable barrier coating development for paperboard primary packs, targeting Vietnamese domestic supply gaps where underdeveloped converting infrastructure creates first-mover advantage. The most penetrable entry point sits with specialty substrate supply to European export-bound production, leveraging technical partnerships with Chinese coating developers to accelerate compliance validation. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional converters lack chain-of-custody certification and high-speed packing line compatibility. Long-term viability favors integrated fiber-to-carton operators with authenticated sustainable sourcing and Southeast Asian manufacturing footprints. Monitor EU Tobacco Products Directive enforcement timeline expansions and plain packaging adoption waves in emerging markets as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Fiber Supply | FSC and PEFC documentation secures procurement eligibility under EU Green Deal mandates. |
| Biodegradable Barrier Coating Development | REACH-compliant moisture protection enables paperboard substitution for plastic films in tropical distribution. |
| Magnetic Closure Specification Expansion | Premium tactile differentiation captures margin pools in Vietnamese and Indonesian luxury segments. |
| Gravure Press Installation in Vietnam | Localized high-precision printing reduces lead times for regional tobacco multinational supply contracts. |
| Smart Packaging Authentication Integration | Near-field communication chips merge with carton structures for anti-counterfeiting compliance. |
Methodological Framework
Multiple input streams — primary interviews with packaging procurement directors, gravure press operators, and regulatory affairs specialists at tobacco multinationals; secondary validation through EU Tobacco Products Directive filings, SAMR GB standard documentation, and FSC chain-of-custody registries; plus customs trade data on cigarette-grade paperboard flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across volume and value dimensions employed segmentation modeling by packaging type, material grade, closure mechanism, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of substrate adoption rates and premium format penetration, incorporating enforcement timeline assumptions for plain packaging mandates and ESG disclosure acceleration.
Several conditions sit outside the modeled scope, including sudden regulatory reversals on heated tobacco classification and unanticipated raw material trade restrictions. Forecasts reflect assumptions about compliance timeline adherence and brand owner procurement behavior. Practitioners should monitor EU opacity rule enforcement expansions and Chinese dual carbon policy implementation for early signals of substrate substitution acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Radar Systems Market
Others
Canada Laser Hair Removal Market
Others
North America Medical Simulation Market
Others
Asia-Pacific Agricultural Enzymes Market
Others
Disposable Non Woven Sponge Market
Others
Europe Travel Retail Market
Others
Asia-Pacific Adtech Market
Others
Foldable Smartphone Market
Others
Air Separation Module Kit Market
Others
DIY Smart Home Market
Others
India 3D Printing Construction Market
Others
Allogeneic T Cell Therapies Market
Others
Hopper Dryers Market
Others
Cellular-Connected Laptops Market
Others
Baking Paper Market
Others
Defense Optronics Market