
 Asia-Pacific Adtech Market | 2026-2036
Asia-Pacific Adtech Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Adtech Market Analytics
ISO/IEC 27001 certification for information security management is reorganizing competitive access across the Asia-Pacific Adtech Market, as enterprise advertisers in Japan and Australia now mandate audited data handling protocols before platform onboarding. Google leverages its DoubleClick infrastructure and search data moats to sustain pricing power across programmatic auctions in Australia and India. ByteDance anchors demand through TikTok's algorithmic content graph, which dominates short-form video ad allocation in Southeast Asia. AnyMind Group competes by extending influencer marketing technology into programmatic media buying, giving it differentiated access to mid-market brands across Japan, Thailand, and Taiwan.
Asia-Pacific adtech encompasses the software infrastructure, data platforms, and algorithmic trading systems that automate media buying, audience targeting, and campaign measurement across digital channels, typically operating through real-time bidding protocols that resolve ad placements within 100 milliseconds. Its primary commercial purpose is to replace manual insertion orders with data-driven efficiency, reducing cost-per-acquisition for advertisers while maximizing yield for publishers. Programmatic advertising leads transaction volume but generates thinner margins as commoditization spreads across demand-side platforms, whereas mobile ad tech captures disproportionate value growth given smartphone-dominant media consumption in India, Indonesia, and the Philippines. Cloud-based deployment now dominates new implementations as hyperscale infrastructure from Alibaba and Tencent lowers entry barriers for regional agencies.
TRAI in India enforces transparency mandates on telecom-linked data usage for ad targeting, while China's SAMR scrutinizes algorithmic recommendation systems under anti-monopoly guidelines, and Australia's ACCC applies competition scrutiny to platform self-preferencing in ad tech auctions. These frameworks collectively raise compliance costs for cross-border data flows and algorithmic transparency, pushing platforms toward localized infrastructure and audited data governance. Stakeholders must monitor how fragmentation between India's data localization requirements, China's algorithmic filing rules, and Australia's media bargaining code reshapes the economics of operating unified regional platforms.
Market Dynamics
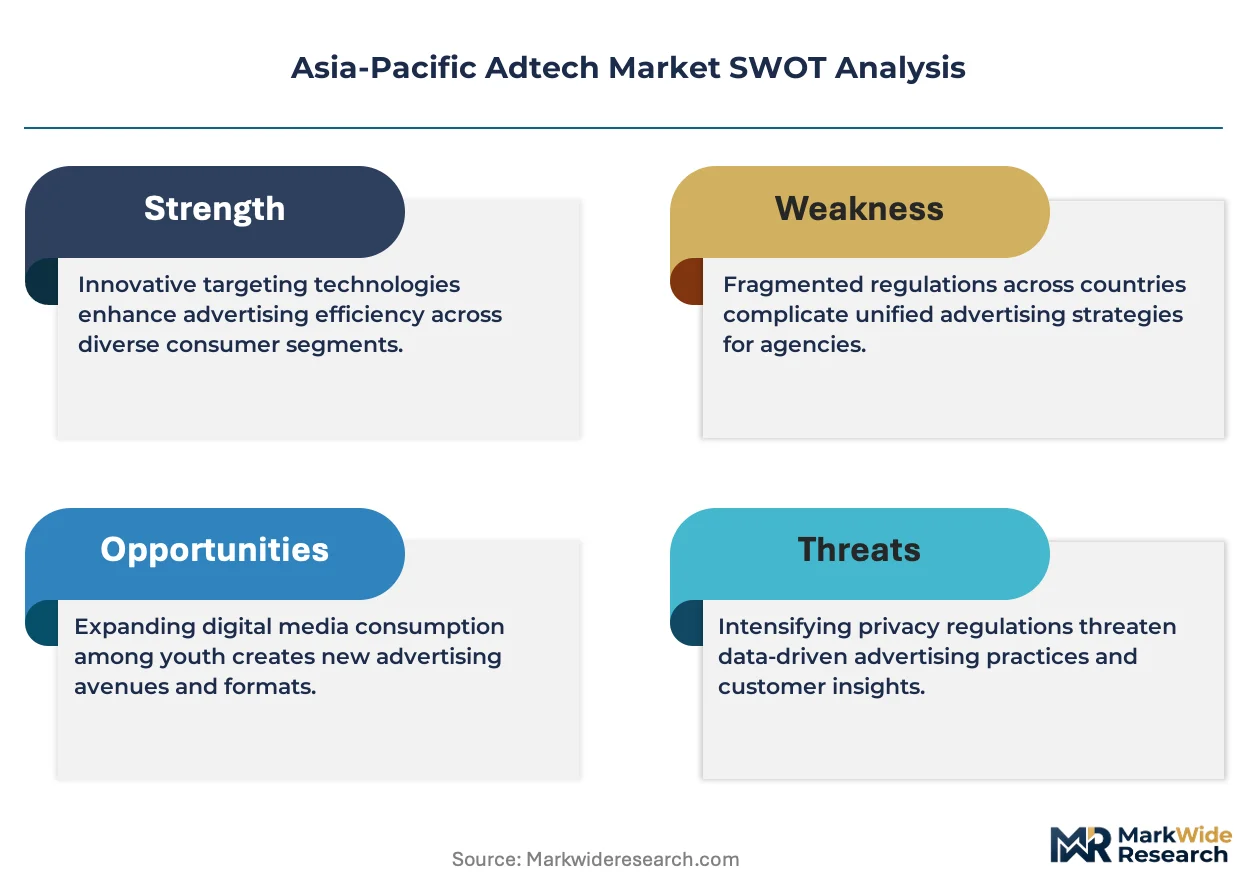
ISO/IEC 27001 certification requirements from enterprise advertisers in Japan and Australia are reorganizing platform access across the Asia-Pacific Adtech Market, forcing infrastructure investments that smaller regional players cannot absorb.
Growth Catalysts
- India's Digital Personal Data Protection Act:The framework mandates consent-based data collection, creating audited first-party data assets that premium advertisers will pay to access through compliant platforms.
- Mobile-first consumption in Indonesia:Smartphone-dominant media consumption concentrates programmatic demand on mobile-optimized inventory, rewarding platforms with native in-app bidding infrastructure.
- Cloud deployment via Alibaba and Tencent:Hyperscale infrastructure lowers capital barriers for regional agencies, expanding the addressable platform market beyond multinational buyers.
Market Restraints
- Cross-border data friction:India's localization requirements, China's algorithmic filing rules, and Australia's media bargaining code fragment unified regional operations, raising compliance overhead.
- Commoditization of demand-side platforms:Standardized real-time bidding protocols compress margins on programmatic transactions, squeezing undifferentiated intermediaries.
- Self-preferencing scrutiny:Australia's ACCC examines platform auction mechanics, creating regulatory risk for vertically integrated inventory owners.
Strategic Opportunities
- Influencer-to-programmatic convergence:Mid-market brands in Thailand and Taiwan seek unified workflow tools that bridge creator content with automated media buying.
- E-commerce platform demand:Southeast Asian marketplace operators represent an underpenetrated buyer segment for retail media networks and closed-loop attribution.
- Algorithmic transparency mandates:China's SAMR scrutiny of recommendation systems creates first-mover advantage for platforms with auditable machine-learning infrastructure.
Industry Challenges
- Certification timeline compression:Japan and Australia enterprise mandates require ISO/IEC 27001 completion within procurement windows that strain regional platform resources.
- Legacy system integration:Established agencies maintain manual insertion order workflows that resist API-based automation, slowing platform onboarding velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Adtech Market |
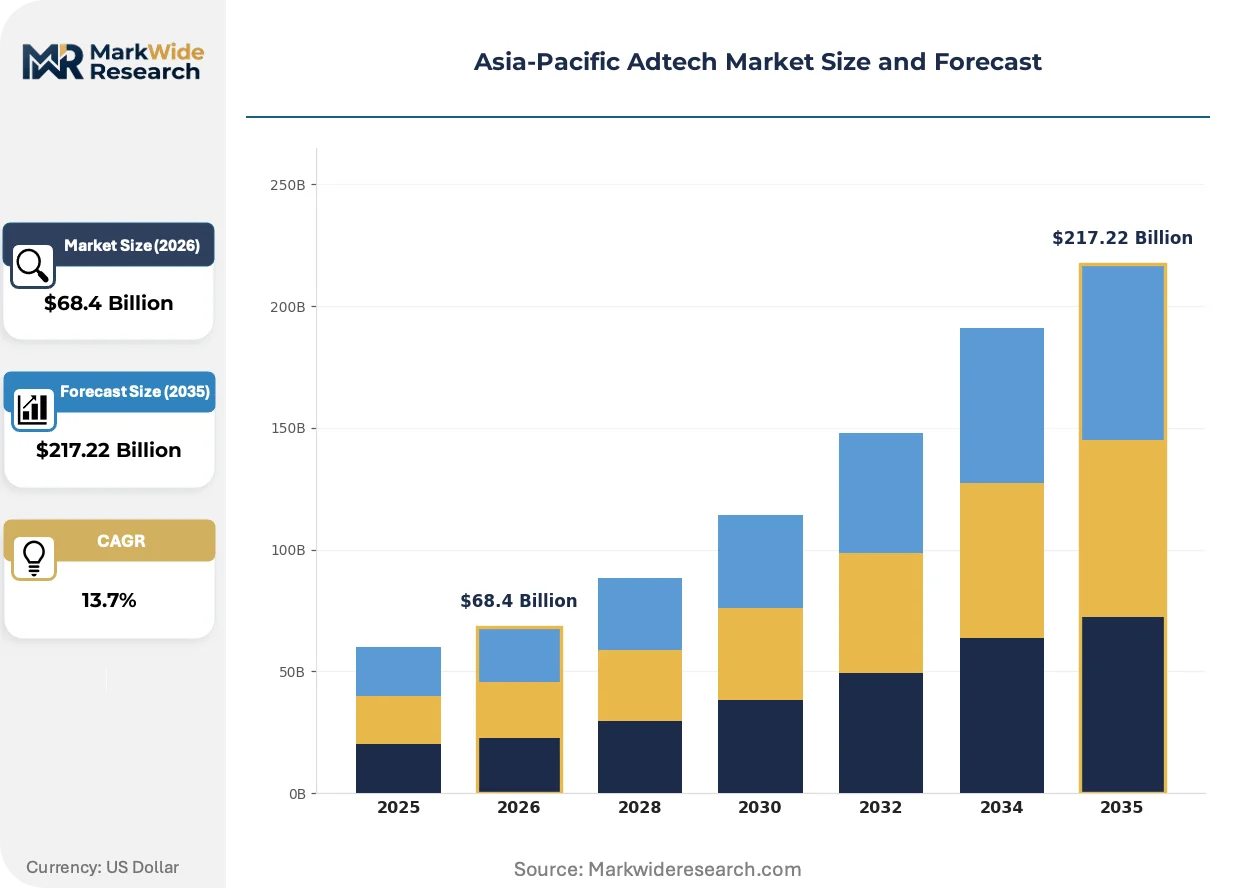
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $217.22 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Programmatic Advertising, Mobile Ad Tech, Data Management Platforms, Marketing Automation Client Type: Advertisers, Agencies, Publishers, Brands Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Advertising Format: Video Ads, Display Ads, Native Ads, Social Media Ads |
| Companies Covered | Google, Meta, Alibaba Group, Baidu, Tencent, ByteDance, Adobe, Dentsu, AnyMind Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Adtech Market Evolving Landscape
Real-time bidding infrastructure is fragmenting as specialized modules replace monolithic platforms, while regulatory pressure on algorithmic systems forces architectural redesigns.
Server-side ad insertion technology is decomposing the traditional client-side ad serving stack. Premium publishers in Australia and Japan are adopting SSAI to bypass ad blockers and reduce latency. The technology is decomposing legacy waterfall mediation into parallel auction architectures that compress decision time below 50 milliseconds.
TRAI transparency mandates on telecom-linked data usage are reshaping identity resolution in India. The regulation restricts carrier-grade targeting signals, forcing platforms to rebuild audience graphs on authenticated first-party data. Mobile operators and adtech intermediaries are responding by investing in consent management infrastructure ahead of enforcement.
Retail media networks are capturing brand budgets that previously flowed to open-web programmatic. E-commerce platforms in Indonesia and the Philippines now operate self-serve demand interfaces that displace agency-managed campaigns. This shift concentrates measurement within closed environments, reducing reliance on third-party attribution vendors.
Asia-Pacific Adtech Market Segmentation
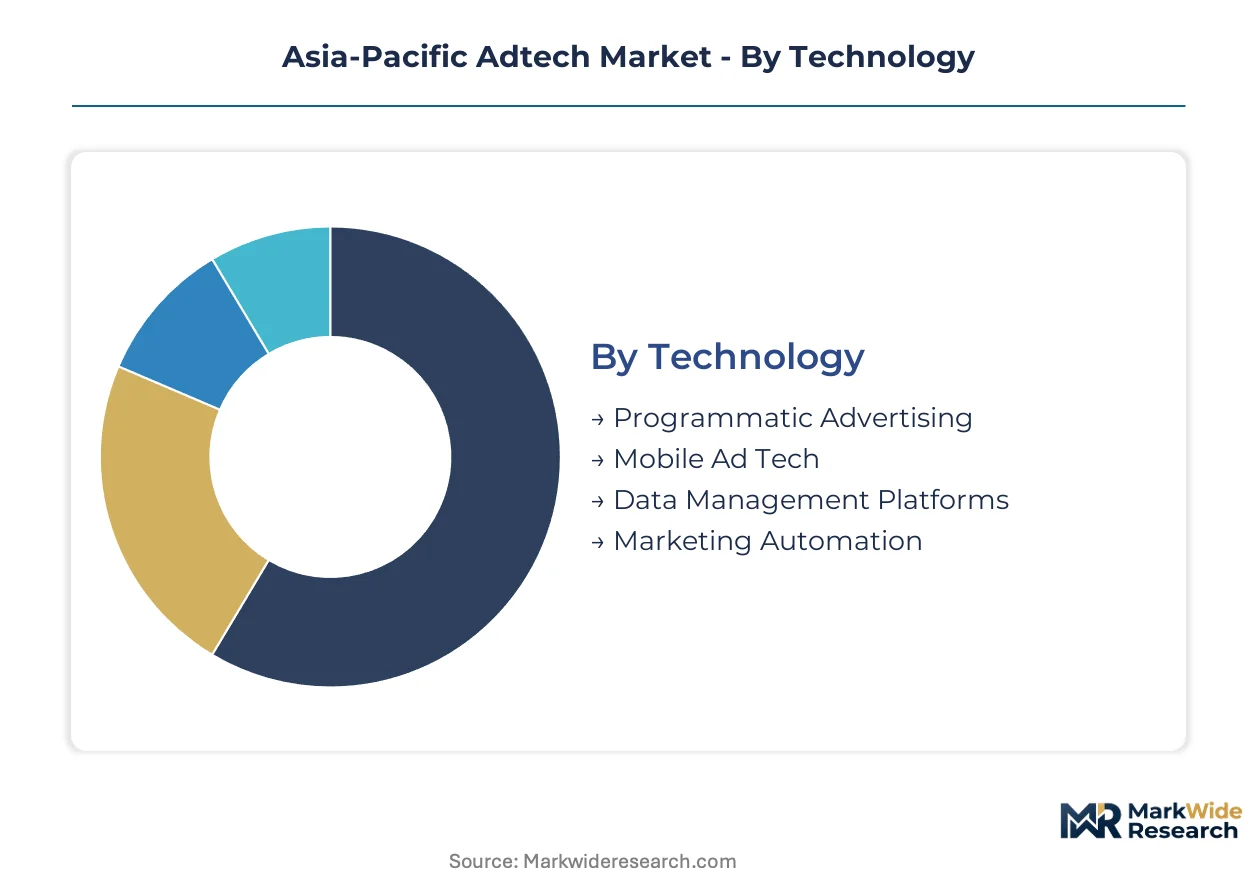
Adtech segmentation in the Asia-Pacific region reveals where platform investments concentrate and which buyer configurations command premium pricing. Technology deployment choices and client procurement patterns determine competitive positioning across this fragmented market.
Technology:
Margin pools concentrate in infrastructure that captures recurring platform fees rather than transactional commissions, rewarding vertical integration into data and measurement layers.
- Programmatic Advertising:Real-time bidding protocols automate media transactions through demand-side and supply-side platforms, resolving placements within milliseconds. Transaction volumes dominate in Australia and India, though standardized protocols compress margins and force differentiation through proprietary data assets.
- Mobile Ad Tech:In-app bidding infrastructure and SDK-based mediation serve smartphone-dominant consumption patterns across Indonesia, the Philippines, and India. Native mobile optimization captures disproportionate value growth as advertisers prioritize app inventory over mobile web.
- Data Management Platforms:First-party data unification and audience segmentation tools.
- Marketing Automation:Cross-channel campaign orchestration and customer journey management systems.
Programmatic Advertising holds installed capacity. Mobile Ad Tech is rotating up the share rankings.
Client Type:
Procurement authority determines contract structures, with direct advertiser relationships yielding higher lifetime value than intermediary-managed bookings.
- Advertisers:Direct brand spenders negotiating platform contracts and demanding transparent auction mechanics. Enterprise mandates in Japan and Australia require ISO/IEC 27001 certification, filtering accessible vendor pools and extending sales cycles.
- Agencies:Intermediary buyers managing cross-client media allocation through trading desks. Trading desk consolidation in Southeast Asia pressures commission structures while expanding volume commitments.
- Publishers:Inventory owners monetizing impressions through header bidding and private marketplace arrangements.
- Brands:Product manufacturers with in-house programmatic capabilities bypassing traditional agency relationships.
Agencies hold installed capacity. Advertisers are climbing the fastest in direct platform relationships.
Deployment:
Infrastructure cost structures separate hyperscale-backed regional entrants from capital-constrained competitors.
- Cloud-Based:Alibaba Cloud and Tencent infrastructure lower capital barriers for regional agencies and mid-market platforms. Deployment velocity accelerates in Thailand and Vietnam where legacy on-premise investments remain shallow.
- On-Premise:Self-managed server infrastructure requiring dedicated security and compliance personnel. Financial services advertisers in Singapore and Hong Kong maintain on-premise preferences for sensitive data processing.
- Hybrid:Mixed architectures balancing latency-sensitive auction engines with cloud analytics.
- SaaS:Subscription-based platform access with standardized feature sets and rapid onboarding.
Cloud-Based holds installed capacity. SaaS is rotating up the share rankings.
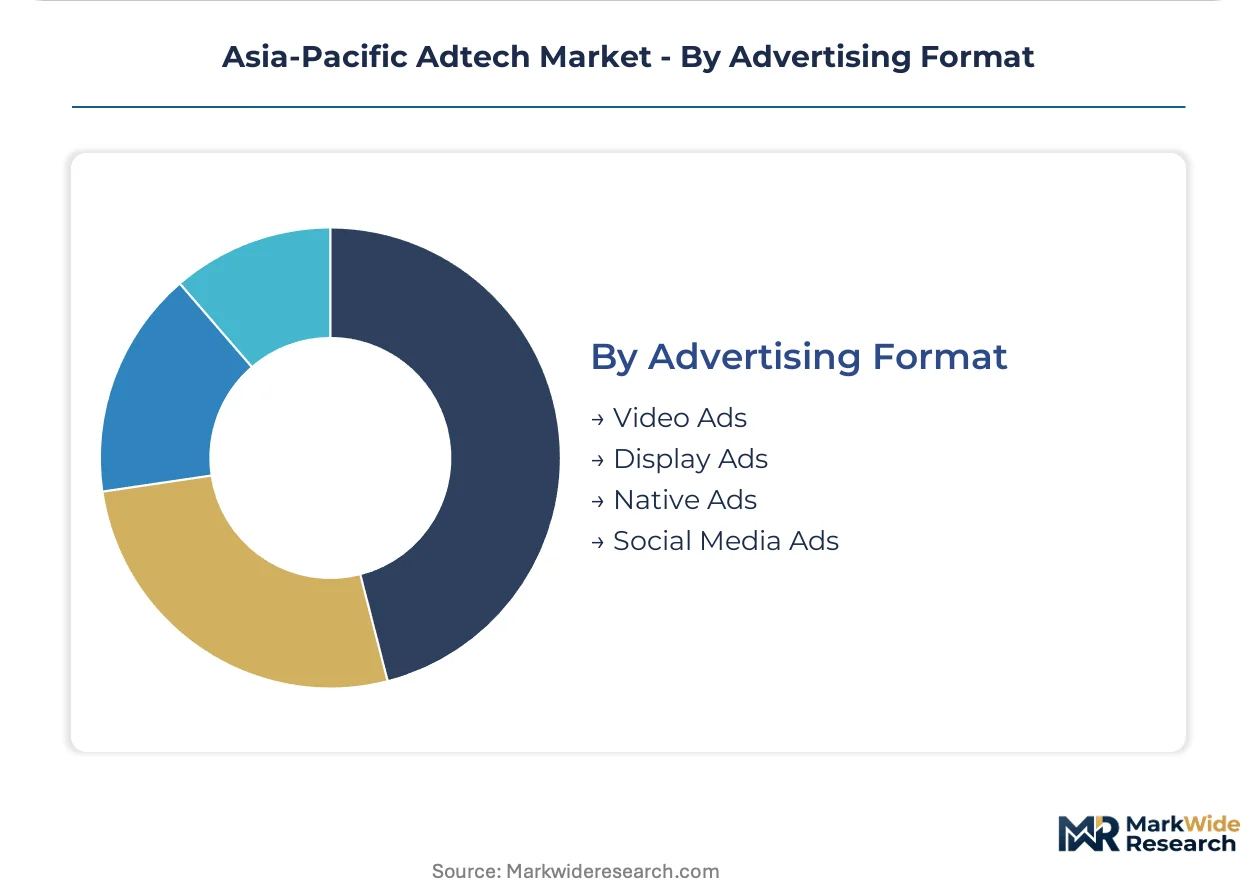
Advertising Format:
Creative production costs and measurement granularity differentiate format economics, with video commanding CPM premiums that offset higher serving infrastructure requirements.
- Video Ads:Streaming and in-stream placements across connected TV, mobile, and desktop environments. Short-form vertical video concentrates demand in Indonesia and Vietnam through TikTok and local platform inventory.
- Display Ads:Banner and rich media units served through traditional ad servers and programmatic pipes. Standardized IAB formats face downward CPM pressure as viewability concerns redirect budgets toward video and native alternatives.
- Native Ads:Format-matched placements integrating with publisher content feeds.
- Social Media Ads:Platform-native inventory across Meta, ByteDance, and regional networks with closed-loop attribution.
Display Ads hold installed capacity. Video Ads are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Digital Personal Data Protection Act and China's algorithmic filing rules are redrawing operational boundaries for cross-border platforms. Japan and Australia now mandate ISO/IEC 27001 certification for enterprise procurement, filtering vendor access. Indonesia's mobile-first consumption patterns concentrate investment in in-app bidding infrastructure.
India
Mobile-dominant media consumption and e-commerce expansion drive programmatic demand across Mumbai and Bangalore. TRAI enforces transparency mandates on telecom-linked data usage for ad targeting, forcing platforms to rebuild audience graphs on authenticated first-party data. The Delhi-NCR corridor hosts compliance-focused platform engineering centers responding to localization requirements.
China
Short-form video consumption and retail media network growth anchor adtech investment in tier-one cities. SAMR scrutinizes algorithmic recommendation systems under anti-monopoly guidelines, requiring auditable machine-learning infrastructure. The Yangtze River Delta cluster concentrates platform R&D responding to filing obligations for recommendation algorithms.
Japan
Enterprise advertiser procurement and connected TV adoption sustain premium pricing for compliant platforms. METI-aligned industrial standards intersect with ISO/IEC 27001 mandates from enterprise buyers, extending vendor sales cycles. The Tokyo-Osaka corridor hosts trading desks consolidating volume commitments while demanding audited data governance.
Australia
Programmatic maturity and platform self-preferencing scrutiny shape competitive access for demand-side platforms. The ACCC applies competition scrutiny to auction mechanics, creating regulatory risk for vertically integrated inventory owners. Sydney and Melbourne concentrate agency trading desks negotiating transparent auction protocols with certified vendors.
Indonesia
Smartphone-dominant media consumption and marketplace operator expansion drive mobile-optimized inventory demand. Rising digital ad budgets from e-commerce platforms draw platform investment in Jakarta and Surabaya. Local in-app bidding infrastructure captures disproportionate value growth as advertisers prioritize app inventory over mobile web.
Asia-Pacific Adtech Market Competitive Landscape
Player mix skews toward hyperscale technology conglomerates with captive data assets and cloud infrastructure. Market structure concentrates around vertically integrated platforms controlling inventory, data, and measurement layers. Two strategic archetypes dominate: algorithmic content platforms leveraging proprietary engagement graphs, and enterprise software vendors bundling adtech with marketing clouds. Competitive moves center on certification-driven vendor consolidation and localized infrastructure deployment responding to data residency mandates.
Within the hyperscale tier, Google and Meta exemplify data-integrated platform archetypes with search and social engagement moats. ByteDance occupies a position representing algorithmic content platforms dominating short-form video allocation. AnyMind Group sits within the regional specialist tier, extending influencer marketing technology into programmatic workflows. These anchors illustrate how competitive positioning diverges between global data conglomerates and mid-market platforms pursuing differentiated access through creator economy integration.
| Leading Market Players |
|---|
| Meta |
| Alibaba Group |
| Baidu |
| Tencent |
| ByteDance |
| Adobe |
| Dentsu |
| AnyMind Group |
| Others |
Value Network & Pricing Analysis
Capacity reservation contracts with Alibaba Cloud and Tencent lock in both infrastructure access and predictable unit economics for regional adtech platforms across Thailand and Vietnam. These arrangements insulate buyers from spot-price volatility in compute resources while binding suppliers to data residency commitments demanded by India's TRAI and China's SAMR.
Pricing Analysis
Certification level creates the primary spread between vendor tiers, with ISO/IEC 27001-audited platforms commanding premium positioning against uncertified competitors in Japan and Australia. SaaS-tiered subscription models dominate new deployments, though transactional commissions persist in programmatic auctions. Price differentiation rests on data governance maturity and latency performance, with enterprise advertisers in Tokyo and Sydney showing lowest sensitivity while regional agencies in Southeast Asia face acute margin compression. Pricing pressure stems from commoditized real-time bidding protocols that compress intermediary margins.
Supply Chain Analysis
China and India anchor cloud infrastructure deployment, with hyperscale data centers in the Yangtze River Delta and Mumbai-NCR corridor feeding regional platform expansion. Taiwan and South Korea supply advanced semiconductor components for ad-serving hardware. Supply chain risk centers on single-source vulnerability in specialized AI accelerators used for algorithmic bidding. Distribution runs through direct platform relationships with enterprise advertisers and consolidated agency trading desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific adtech market sits in a cyclical recovery phase as regulatory clarity from India's Digital Personal Data Protection Act and China's algorithmic filing rules stabilizes compliance investment cycles. Enterprise procurement resumption in Japan and Australia signals the upswing.
For Market Incumbents: Fortify certification moats by accelerating ISO/IEC 27001 audits ahead of procurement windows in Tokyo and Sydney. Deepen backward integration into first-party data infrastructure to offset signal loss from TRAI's telecom-data restrictions. Lock in long-term capacity reservations with Alibaba and Tencent before regional demand spikes inflate compute pricing.
For New Entrants and Emerging Players: Lead with influencer-to-programmatic workflow tools targeting mid-market brands in Thailand and Taiwan where AnyMind Group has validated demand but not saturated access. Capture e-commerce platform operators in Indonesia and the Philippines as an underpenetrated buyer segment for retail media networks. Position through self-serve interfaces that bypass agency intermediation.
For Investors and Strategic Acquirers: Regional specialists with auditable machine-learning infrastructure and localized data governance represent the most defensible acquisition profile as SAMR filing requirements and TRAI transparency mandates raise technical barriers. Long-term viability hinges on platforms' ability to operate compliant multi-country stacks without fragmenting unit economics. Watch for inflection in direct advertiser procurement ratios as the signal separating premium platforms from commodity intermediaries.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 27001 Certification Acceleration | Unlocks enterprise procurement pipelines in Japan and Australia where audited data governance is now mandatory. |
| First-Party Data Infrastructure Buildout | Rebuilds audience graphs independent of restricted telecom signals under India's TRAI transparency mandates. |
| Server-Side Ad Insertion Deployment | Bypasses ad blockers for premium publishers in Australia and Japan while compressing auction latency below 50 milliseconds. |
| Retail Media Network Integration | Captures brand budgets shifting from open-web programmatic into closed-loop e-commerce environments in Indonesia. |
| Algorithmic Audit Filing Preparation | Creates first-mover positioning ahead of SAMR enforcement on recommendation system transparency in China. |
Research Methodology
A spread of perspectives from platform engineers, agency trading desk heads, enterprise procurement officers, and regulatory compliance leads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from listed adtech vendors, hyperscaler capex disclosures from Alibaba and Tencent, and TRAI regulatory circulars. Bottom-up sizing of platform deployments and top-down cross-checks against aggregate digital ad spend estimates provided triangulation.
Segmentation dimensions modeled include technology deployment mode, client procurement authority, infrastructure delivery format, and creative format type across the projection horizon. CAGRs derived from regression analysis of historical transaction volumes and forward-looking platform investment announcements. Industry-specific forecast inputs incorporated mobile ad spend ratios by country and certification penetration rates among enterprise advertisers.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or cloud infrastructure cost trajectories would require recalibration. Forecasts reflect documented assumptions on data localization compliance timelines and algorithmic transparency implementation. Recalibration cycles align with material shifts in SAMR filing deadlines and TRAI enforcement actions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Personal Care Packaging Market
Others
Gym Wipes Market
Others
Aerospace Tester Market
Others
Electrical Calibration Equipment Market
Others
Global Smart Home Installation Service Market
Others
North America Ultraviolet Disinfection Equipment Market
Others
Asia Pacific Video Conferencing Hardware Market
Others
India Home Automation Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Programmatic Display Market
Others
Africa Lime Market
Others
Global Thermally Conductive Grease Market
Others
Molecular Spectroscopy Market
Others
Gem Faceting Machine Market
Others
Europe Indoor Air Purification Market
Others
Video-As-A-Service (Vaas) Market