
 Europe Cigarette Market | 2026-2036
Europe Cigarette Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cigarette Market Intelligence
Adult smoker demand in Eastern Europe is expanding as price-sensitive consumers shift toward value-tier traditional cigarettes and away from premium alternatives. Imperial Brands leverages its geographic dominance across multiple EU member states to sustain volume leadership. Philip Morris International competes through heated-tobacco diversification while maintaining conventional cigarette scale. British American Tobacco anchors its position via channel control in convenience retail and tobacco specialty stores.
A cigarette is a cylindrical roll of cured and cut tobacco leaf encased in paper, typically containing approximately 10 milligrams of tar and 0.5 to 1.0 milligram of nicotine per unit, designed for combustion and inhalation of smoke for recreational nicotine delivery. The manufacturing process involves blending, conditioning, cutting, and machine-rolling before packaging into soft pack, hard pack, or carton formats for retail distribution. Traditional cigarettes occupy the mature volume core where margin pools have compressed under excise pressure, while light cigarettes capture health-conscious switchers seeking reduced-tar positioning. Menthol cigarettes face structural decline where ECHA-aligned flavor prohibitions have taken effect, redirecting portfolio investment toward unflavored and reduced-risk alternatives.
The EU Tobacco Products Directive, ECHA flavor restrictions, and national regulations enforced by Germany's Federal Institute for Risk Assessment shape product standards, packaging mandates, and market access across member states. These frameworks elevate compliance costs while accelerating consolidation among manufacturers with regulatory affairs scale. Stakeholders must monitor the divergence between member-state enforcement intensity and the pace of next-generation product substitution to calibrate portfolio and geographic priorities.
Market Dynamics
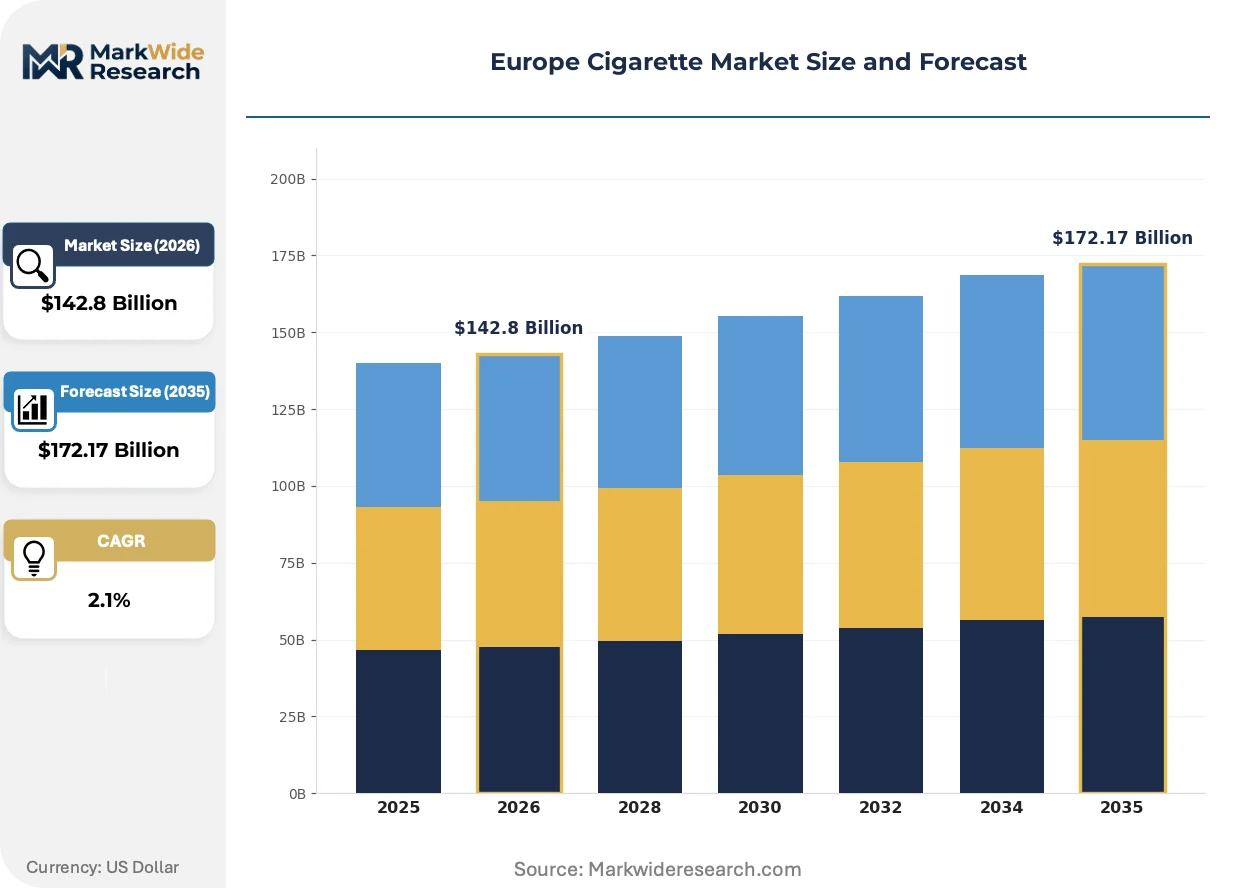
Excise tax compression and flavor prohibition under the EU Tobacco Products Directive are forcing portfolio restructuring toward reduced-risk alternatives and value-tier traditional formats. Manufacturers must simultaneously defend volume in Eastern European price-sensitive markets while absorbing compliance cost escalation in Western member states.
Growth Catalysts
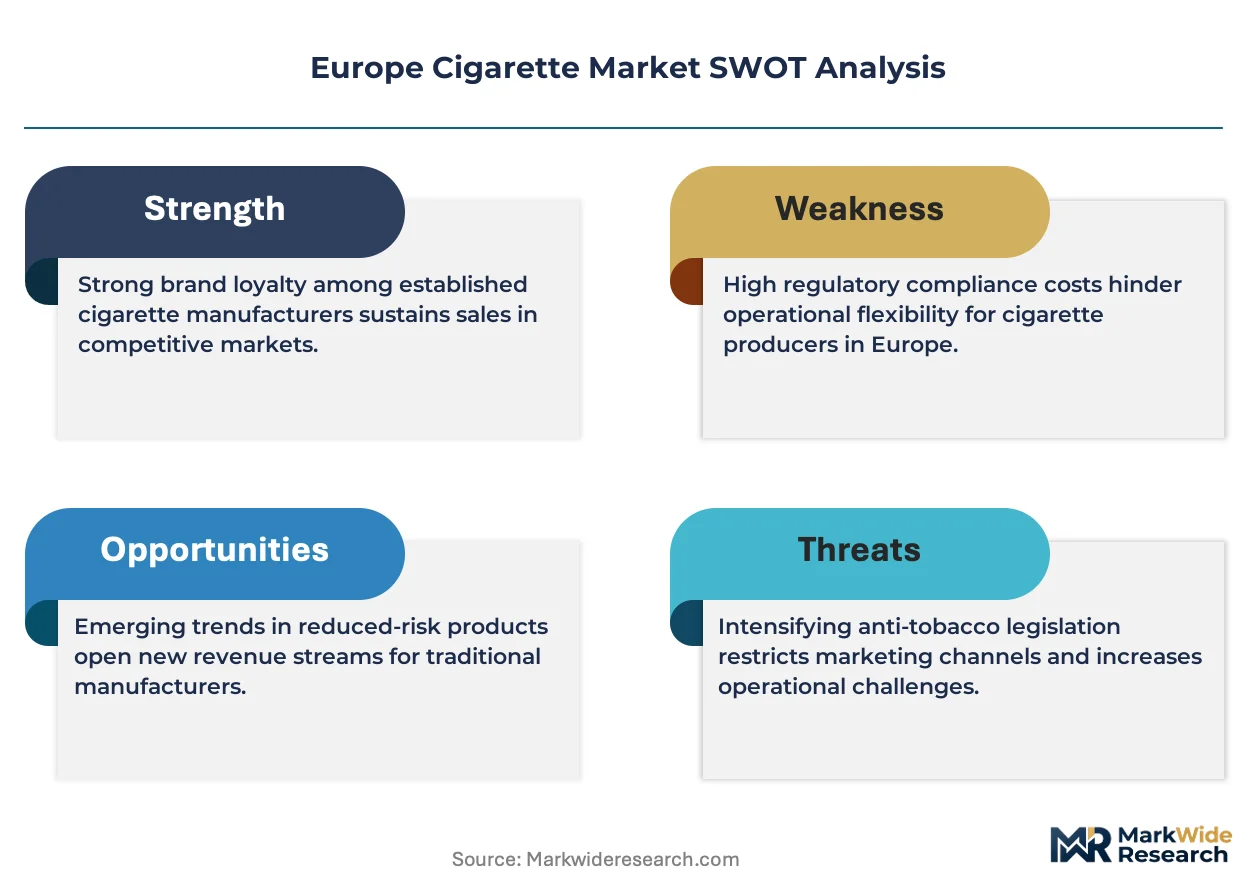
- Heated-tobacco technology:Device-based nicotine delivery systems are capturing adult smokers seeking combustion alternatives, expanding addressable demand beyond conventional cigarette formats.
- Poland manufacturing concentration:Export-oriented production hubs leverage labor cost advantages and EU single-market access to supply cross-border wholesale channels.
- ECHA flavor restrictions:Prohibitions on menthol and characterizing flavors redirect R&D investment toward unflavored reduced-risk products, accelerating portfolio transformation.
Market Restraints
- Tobacco leaf input volatility:Weather-dependent crop yields in Brazil and Zimbabwe create raw material cost instability that squeezes margin pools under fixed retail price ceilings.
- Western Europe demand compression:Germany and the Netherlands exhibit accelerating volume decline as smoking prevalence drops and next-generation product substitution intensifies.
- REACH compliance burden:Chemical substance registration requirements elevate testing and documentation costs for additive formulations and packaging materials.
Strategic Opportunities
- Romania production expansion:Greenfield manufacturing investments target duty-free and adjacent non-EU export markets with lower regulatory stringency.
- Convenience retail channel control:Exclusive distribution agreements with petrol station networks and tobacco specialists secure shelf space and consumer access points.
- CSRD sustainability reporting:Early compliance with corporate sustainability disclosure requirements positions manufacturers for ESG-linked institutional capital access.
Industry Challenges
- Regulatory affairs talent scarcity:Specialized expertise in EU Tobacco Products Directive interpretation and member-state enforcement variation commands premium compensation.
- Legacy IT integration friction:Track-and-trace serialization mandates require expensive ERP upgrades to achieve real-time supply chain visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cigarette Market |
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $172.17 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Cigarettes, Menthol Cigarettes, Light Cigarettes, Flavored Cigarettes, Clove Cigarettes Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, Online Retail, Tobacco Specialty Stores, Vending Machines Consumer Demographic: Young Adults, Middle-aged Consumers, Seniors, Male Smokers, Female Smokers Packaging Type: Soft Pack, Hard Pack, Box, Carton, Single Stick Packaging |
| Companies Covered | Imperial Brands, Korea Tobacco & Ginseng Corporation, Philip Morris International, Continental Tobacco Group, Karelia Tobacco Company, British American Tobacco, Bulgartabac Holding, European Tobacco, Japan Tobacco International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cigarette Market Strategic Shifts & Innovations
Product format diversification and combustion-alternative technologies are fragmenting what was historically a homogeneous cigarette market. Three developments merit particular attention.
Heated-tobacco devices are rewriting competitive boundaries between conventional cigarettes and vaping products. Adult smokers in Italy and Greece are adopting these systems at accelerating rates. The technology is compressing menthol and light cigarette segments by delivering flavor satisfaction without combustion byproducts.
The EU Tobacco Products Directive's flavor prohibition provisions are eliminating menthol and characterizing additive categories from legal commerce. Manufacturers are reallocating marketing expenditure toward unflavored reduced-risk portfolios. Germany's Federal Institute for Risk Assessment enforces these bans most stringently, redirecting cross-border smuggling flows toward neighboring jurisdictions.
Smoker purchasing patterns are consolidating around value-tier traditional formats as Eastern European consumers trade down from premium price points. Petrol station and convenience store channels are displacing traditional tobacco specialists for routine replenishment. Romania and Bulgaria exhibit the most pronounced channel shift, where price transparency via mobile comparison tools accelerates brand switching.
Europe Cigarette Market Segmentation
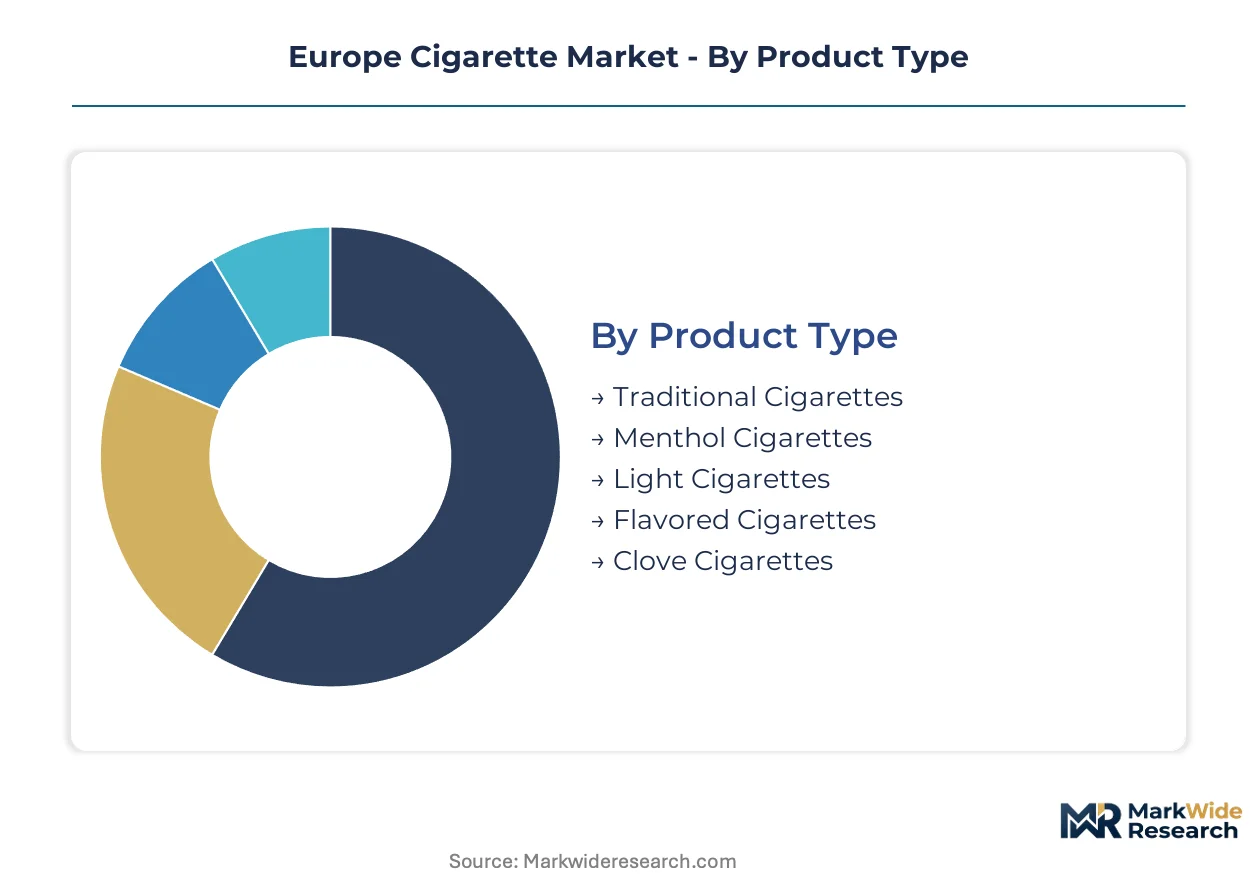
Segmentation in the Europe Cigarette Market reflects divergent regulatory pressures and smoker preferences across Eastern and Western member states. Manufacturers calibrate portfolio composition and channel strategy against excise tier structures and flavor prohibition enforcement intensity.
Product Type:
Smoker choices in this category differentiate primarily by tar content tolerance and flavor preference sensitivity to ECHA restrictions.
- Traditional Cigarettes:Full-flavor cured tobacco blends with standard tar delivery of 10 milligrams per unit. Demand concentrates in Poland and Romania where price-sensitive adult smokers prioritize nicotine satisfaction over reduced-risk positioning. Volume retention depends on value-tier pricing under escalating excise pressure.
- Light Cigarettes:Reduced-tar formulations targeting health-conscious switchers seeking lower combustion byproduct exposure. Germany and the Netherlands exhibit accelerating demand compression as smokers migrate to heated-tobacco alternatives or abandon combustion entirely.
- Menthol Cigarettes:Characterizing flavor additives face structural decline under EU Tobacco Products Directive prohibitions. Cross-border smuggling flows redirect toward jurisdictions with weaker enforcement.
- Flavored Cigarettes:Non-menthol characterizing additives including fruit and spice variants. ECHA-aligned national bans eliminate legal commerce in Germany and the Netherlands.
- Clove Cigarettes:Kretek-style products with eugenol content. Niche positioning in specialist retail channels serves diaspora communities and experimental smokers.
Traditional cigarettes lead volumes today; light cigarettes are gaining share fastest among health-conscious segments before heated-tobacco substitution accelerates.
Distribution Channel:
Channel selection in this category tracks smoker replenishment frequency and price transparency exposure.
- Convenience Stores:Petrol station networks and urban corner shops dominate routine single-pack purchases. Imperial Brands and British American Tobacco leverage exclusive agreements to secure shelf space in Romania and Bulgaria where mobile price comparison accelerates brand switching.
- Supermarkets & Hypermarkets:High-volume carton sales capture planned stock-up behavior. Germany's retail concentration laws limit tobacco visibility while preserving access for established brands.
- Tobacco Specialty Stores:Traditional tobacconists retain premium and imported variant distribution. Channel share erodes as convenience retail displaces routine replenishment.
- Online Retail:Cross-border e-commerce faces strict member-state enforcement under EU Tobacco Products Directive age verification mandates.
- Vending Machines:Automated sales require identity verification technology upgrades under national youth access regulations.
Convenience stores anchor volume today; supermarkets are expanding share fastest through private-label and promotional bundling.
Consumer Demographic:
Age-based segments in this category separate by smoking initiation timing and cessation intention.
- Middle-aged Consumers:Established smokers aged 35-54 with stable consumption patterns and brand loyalty. Eastern Europe concentrates this cohort where smoking prevalence remains elevated and next-generation product adoption lags Western member states.
- Young Adults:Smokers aged 18-34 exhibit highest switching propensity toward heated-tobacco and vaping alternatives. Italy and Greece show accelerating device adoption rates.
- Seniors:Smokers aged 55+ with ingrained combustion habits and lower technology receptivity. Volume retention depends on traditional format availability in familiar retail channels.
- Male Smokers:Gender-skewed segment with higher per-capita consumption intensity. Eastern European markets exhibit pronounced male smoking prevalence.
- Female Smokers:Preference concentration in light and slim variants. Social stigma dynamics vary across member-state cultural contexts.
Middle-aged consumers dominate volume today; young adults are shifting preferences fastest toward combustion alternatives.
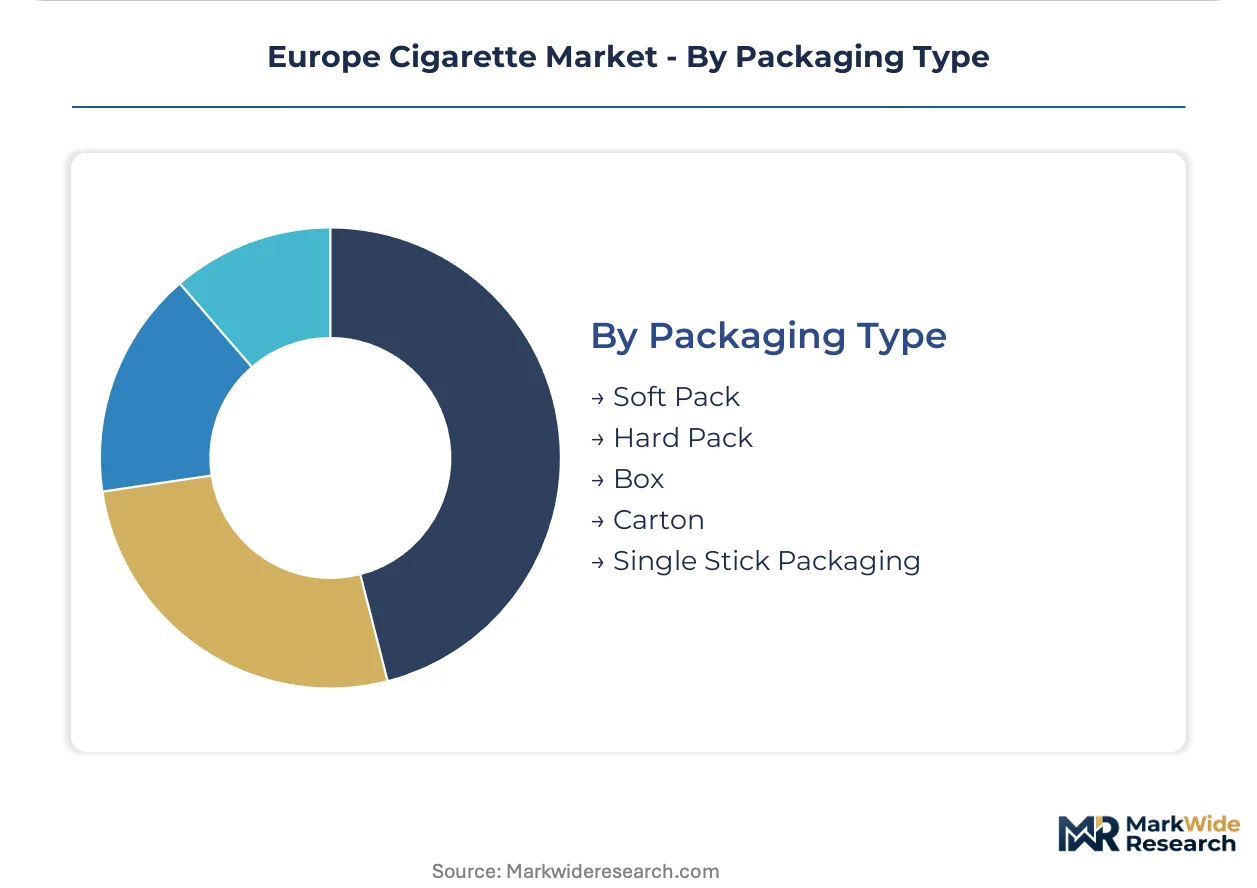
Packaging Type:
Format selection in this category balances portability, price per unit, and plain packaging compliance cost absorption.
- Hard Pack:Rigid cardboard construction protects product integrity and supports premium positioning. Germany and France mandate standardized plain packaging that eliminates brand differentiation through exterior design.
- Soft Pack:Flexible paper wrapping reduces material cost and supports value-tier pricing. Poland and Romania favor this format for price-sensitive traditional cigarette segments.
- Carton:Ten-pack aggregation captures bulk purchase discounts and reduces per-unit packaging cost. Supermarket channel concentration drives carton format growth.
- Box:Rigid hinged-lid construction common in premium and export-oriented variants. Manufacturing concentrates in Polish export hubs.
- Single Stick Packaging:Individual unit wrapping for vending machine and hospitality channel compliance. Regulatory scrutiny intensifies under youth access prevention frameworks.
Hard pack leads volumes today; carton formats are climbing fastest through supermarket channel expansion and bulk purchasing behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's manufacturing corridor anchors European cigarette production through export-oriented facilities serving duty-free and adjacent markets. Excise tier divergence between Eastern and Western member states creates arbitrage opportunities that reshape wholesale distribution patterns. The EU Tobacco Products Directive harmonizes baseline standards while national enforcement variation preserves regulatory fragmentation.
Germany
Adult smoker volume compression accelerates as heated-tobacco substitution penetrates metropolitan centers. The Federal Institute for Risk Assessment enforces ECHA-aligned flavor prohibitions with particular stringency, eliminating menthol variants from legal commerce. Manufacturing presence concentrates in North Rhine-Westphalia, where distribution hubs coordinate cross-border logistics into neighboring jurisdictions with weaker enforcement.
Poland
Value-tier traditional cigarettes dominate domestic consumption as price-sensitive smokers resist premium migration. EU Tobacco Products Directive compliance costs elevate entry barriers for smaller manufacturers while favoring scaled regulatory affairs capabilities. The Warsaw-Łódź corridor hosts the continent's largest export-oriented production facilities, supplying wholesale channels across the single market and adjacent non-EU territories.
Romania
Greenfield manufacturing investments target duty-free export markets and regional wholesale distribution with lower regulatory stringency. National excise structures remain below Western European thresholds, preserving margin pools for value-tier formats. Production clusters around Bucharest-Ploiești leverage labor cost advantages and Danube corridor logistics access for Black Sea and Middle Eastern market reach.
Italy
Heated-tobacco device adoption rates exceed regional averages among young adult smokers in northern metropolitan areas. ECHA flavor restrictions compress menthol segment viability while redirecting portfolio investment toward unflavored reduced-risk alternatives. The Veneto and Lombardy regions retain traditional cigarette manufacturing for domestic value-tier demand and Mediterranean export channels.
Netherlands
Accelerating smoking prevalence decline and next-generation product substitution compress conventional cigarette volume faster than regional peers. National flavor bans under EU Tobacco Products Directive implementation eliminate characterizing additive categories entirely. The Rotterdam-Antwerp logistics corridor facilitates transit distribution rather than domestic production, serving as a consolidation node for Benelux and German market supply.
Europe Cigarette Market Key Industry Players
Portfolio diversification dominates the current landscape as manufacturers reallocate investment between conventional cigarettes and reduced-risk alternatives. Market structure consolidates around four multinational groups with regulatory affairs scale and three regional specialists serving price-sensitive Eastern European demand. Strategic archetypes separate into combustion-defenders prioritizing volume retention, transition-leaders accelerating heated-tobacco substitution, and value-tier specialists exploiting excise arbitrage. Capacity expansion in Romanian and Polish production hubs and exclusive convenience retail distribution agreements constitute the dominant competitive moves reshaping market access.
Within the multinational defender archetype, Imperial Brands and British American Tobacco exemplify geographic diversification strategies spanning multiple EU member states. Philip Morris International occupies a position as the transition-leader archetype, representing portfolio reorientation toward device-based nicotine delivery systems. Korea Tobacco & Ginseng Corporation anchors the specialist tier as an Asia-Pacific-origin manufacturer with limited but targeted European market presence. These three entities collectively illustrate the competitive spectrum from combustion volume defense through reduced-risk substitution toward regional niche positioning.
| Leading Market Players |
|---|
| Imperial Brands |
| Korea Tobacco & Ginseng Corporation |
| Philip Morris International |
| Continental Tobacco Group |
| Karelia Tobacco Company |
| British American Tobacco |
| Bulgartabac Holding |
| European Tobacco |
| Japan Tobacco International |
| Others |
Cost & Logistics Intelligence
Family-owned tobacco specialists in Eastern Europe anchor supply-side discipline through multi-generational leaf procurement relationships and patient capital allocation that resists short-term margin compression. Their ownership structure preserves pricing power across excise tier arbitrage corridors while sustaining cross-border distribution networks that larger multinationals struggle to replicate at comparable unit economics.
Pricing Analysis
Distributor margin layers absorb the steepest compression as excise escalations outpace retail price elasticity in Germany and the Netherlands. Three-tier pricing structure across premium, standard, and economy levels stratifies by tar content and packaging format, with value-tier soft packs commanding highest volume share in Poland and Romania. Pricing pressure stems from REACH compliance cost pass-through requirements that squeeze mid-tier brand profitability. Price-sensitive Eastern European smokers exhibit highest elasticity, while Italian and Greek heated-tobacco adopters show lowest sensitivity to conventional cigarette pricing.
Supply Chain Analysis
Rising freight costs along Danube corridor routes and Rotterdam-Antwerp transit lanes elevate landed cost differentials between Polish manufacturing hubs and Southern European markets. Supply concentrates in Poland, Romania, and Italy as primary production geographies, with leaf sourcing drawing from Brazil, Zimbabwe, and select EU cultivation zones. Single-source vulnerability in Brazilian tobacco crop yields threatens raw material stability during El Niño cycles. Distribution runs through petrol station networks and tobacco specialty wholesalers that Imperial Brands and British American Tobacco control via exclusive agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Cigarette Market functions as a regulatory compounder where EU Tobacco Products Directive flavor prohibitions and ECHA restrictions continuously reshape portfolio viability and channel economics.
For Market Incumbents: Cement channel control in Romanian and Bulgarian convenience retail through exclusive petrol station agreements that lock out competitor shelf access. Secure backward integration into Polish leaf processing to defend margin position against Brazilian crop volatility. Heated-tobacco substitution in Italy and Greece represents the priority threat requiring accelerated device portfolio investment.
For New Entrants and Emerging Players: Direct-to-specialist online platforms targeting diaspora communities offer the most penetrable route for clove and niche variant distribution where regulatory enforcement gaps persist. Romania's duty-free export corridor presents white-space manufacturing opportunity with lower compliance thresholds than Western member states. White-label supply to Polish export hubs enables volume build without brand marketing expenditure.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Eastern European manufacturers with underutilized production capacity and weak next-generation product pipelines. Long-term viability hinges on heated-tobacco transition execution rather than combustion volume defense. Watch Italian and Greek device adoption velocity as the inflection signal for portfolio reallocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Heated-Tobacco Portfolio Expansion | Philip Morris International's device ecosystem captures Italian smokers migrating from menthol variants under ECHA bans. |
| Romania Greenfield Manufacturing | Duty-free export capacity leverages Danube logistics for Middle Eastern market access with reduced REACH burden. |
| Convenience Retail Exclusive Agreements | Imperial Brands locks petrol station shelf space in Bulgaria where mobile price comparison accelerates brand switching. |
| CSRD Sustainability Compliance | Early ESG disclosure positioning unlocks institutional capital for manufacturers with Polish production footprint. |
| Track-and-Trace ERP Integration | Serialization mandates force smaller competitors into expensive compliance upgrades that favor scaled regulatory affairs teams. |
Research Approach
Direct dialogue with tobacco manufacturing executives, regulatory affairs directors at EU member state level, convenience retail category buyers, and leaf procurement specialists grounded qualitative insights across the value chain. Secondary validation drew from EU Tobacco Products Directive implementation reports, ECHA restriction assessments, national customs trade data, and SEC filings of listed manufacturers. Bottom-up volume modeling triangulated against top-down excise revenue projections.
Top-down macroeconomic framing anchored demand elasticity assumptions while bottom-up segment modeling tracked product type, distribution channel, and consumer demographic splits across the projection horizon. CAGRs derived from weighted average of historical volume trajectories and regulatory scenario stress-testing. Forecast inputs incorporated heated-tobacco substitution rates and flavor prohibition enforcement intensity variation by member state.
Regulatory enforcement divergence, raw material crop yield volatility, and next-generation product adoption velocity are the dominant revision risks that could reshape trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Homemade Cigars Market
Tobacco Products
E-Cigarette and Vape Market
Tobacco Products
Cigarettes Filter Market
Tobacco Products
Africa Tobacco Products Market
Tobacco Products
Nicotine Pouches Market
Tobacco Products
Flavored Cigar Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
Philippines E-Cigarette and Vape Market
Tobacco Products
Europe E-Cigarettes Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
US E-Cigarette and Vape Market
Tobacco Products
E-Cigarette and Vaping Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
Middle East and Africa E-Cigarettes Market