
 Natural Berry Flavor Market | 2026-2036
Natural Berry Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Berry Flavor Market Outlook
Functional beverage startups are collapsing the traditional buyer hierarchy that long favored legacy confectionery houses. Givaudan leverages captive botanical sourcing networks across multiple continents to secure rare berry cultivars. Firmenich SA anchors its position through deep R&D partnerships with artisanal extract producers in France and Switzerland. Kerry Group PLC competes by integrating spray-dried flavor systems directly into dairy processor co-manufacturing lines.
Natural berry flavor denotes volatile and non-volatile aromatic compounds extracted from Rubus, Vaccinium, and Ribes species through cold-press, solvent-free, or fermentation-assisted methods, typically standardized to specific anthocyanin content and Brix levels for batch consistency in industrial food production. Extracts dominate current volume flows due to their clean-label compatibility and solubility in aqueous beverage matrices, while microencapsulated forms capture expanding margin pools in heat-stable bakery and snack applications where thermal degradation of volatile esters demands protective wall-system technologies. Nutraceutical end users represent the fastest-growing demand arc as polyphenol-standardized concentrates migrate from flavoring into dual-function positioning for immune and cognitive health products.
EFSA novel food assessments and ECHA REACH compliance obligations for botanical extracts shape formulation choices and supplier qualification protocols throughout the European value chain. FDA GRAS self-affirmation pathways in the United States create divergent market access timelines that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving maximum residue limits for pesticide metabolites in wild-harvested berries and calibrate sourcing strategies accordingly.
Market Dynamics
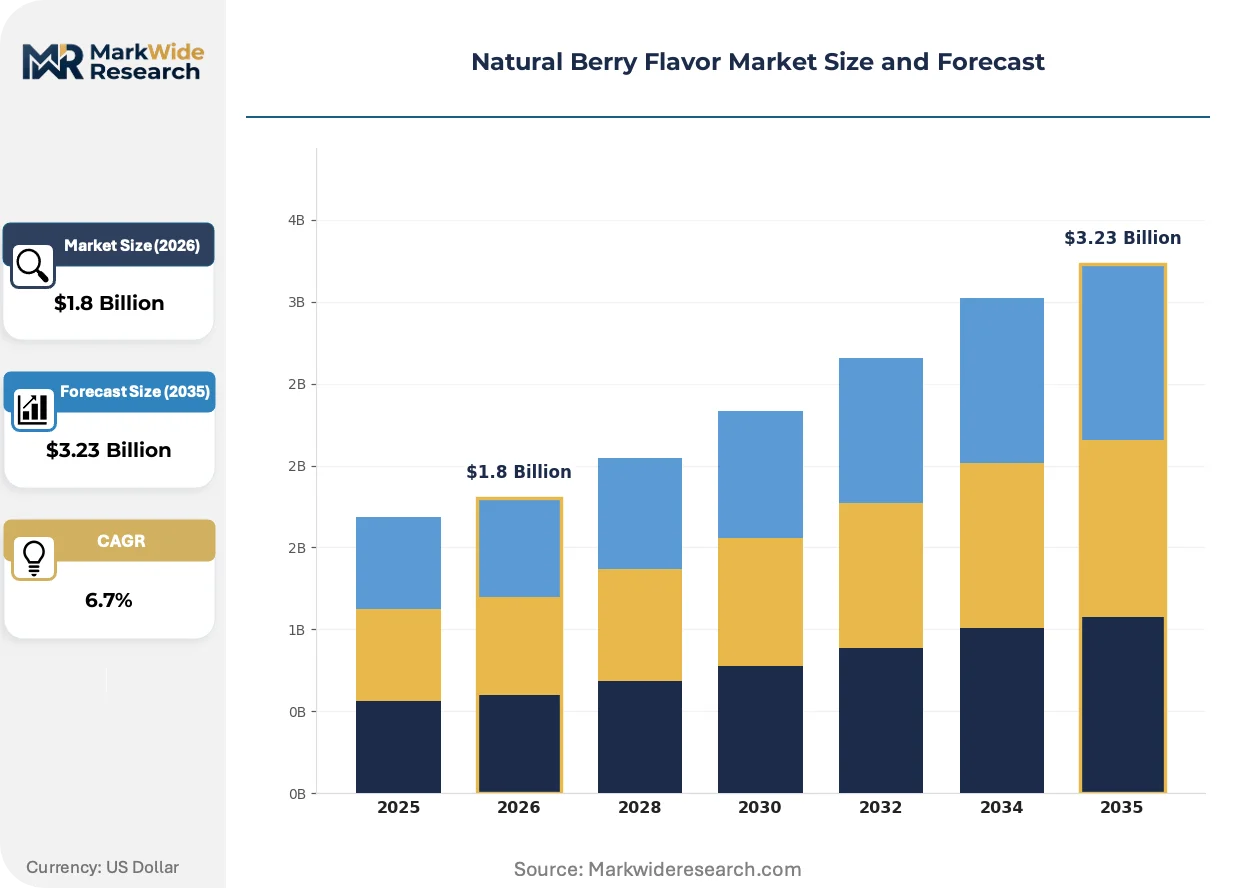
Clean-label mandates from EFSA and ECHA are compressing synthetic flavor inventories while concentrating procurement power among beverage formulators with verified botanical supply chains. This regulatory compression is restructuring supplier qualification protocols and accelerating capital flows into extraction infrastructure.
Growth Catalysts
- EFSA synthetic additive bans:Prohibitions on azo dyes and artificial flavorants under EFSA safety assessments are forcing confectionery and beverage manufacturers toward anthocyanin-based alternatives, expanding addressable demand for standardized berry extracts.
- Fermentation-assisted extraction:Enzymatic bioprocessing methods are reducing solvent residues and improving volatile compound recovery rates, enabling cleaner label claims for heat-sensitive applications.
- Functional beverage vertical:Immune-positioned drink startups are sourcing polyphenol-standardized concentrates at volumes that rival legacy confectionery procurement, collapsing traditional buyer hierarchies.
Market Restraints
- Wild-harvest supply concentration:Vaccinium and Ribes raw material dependence on Nordic and Baltic foraging cooperatives creates weather-driven volume volatility and pesticide metabolite compliance risks.
- Anthocyanin thermal degradation:Natural berry flavonoids lose bioactivity above 60°C, limiting direct incorporation into baked goods without microencapsulation wall-system investments.
- REACH registration costs:ECHA compliance obligations for novel botanical extracts impose six-figure toxicology study requirements that exclude smaller artisanal producers from EU commercialization.
Strategic Opportunities
- India nutraceutical expansion:FSSAI functional food regulations are clarifying health claim pathways for polyphenol concentrates, opening dual-positioning opportunities in ayurvedic supplement formulations.
- Spray-dried dairy integration:Direct injection of flavor systems at processor co-manufacturing lines eliminates intermediate handling and reduces oxidation exposure for extended shelf-life yogurt applications.
- EU Green Deal bioeconomy incentives:Circular extraction funding and regional development grants for solvent-free processing infrastructure are lowering capital barriers for sustainable production scale-up.
Industry Challenges
- Analytical chemistry talent scarcity:Batch-to-batch anthocyanin standardization requires specialized HPLC-MS expertise that competes with pharmaceutical sector compensation.
- Novel food authorization timelines:EFSA safety opinion delays of 18-24 months for non-traditional berry cultivars freeze product development cycles for innovation-driven formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Berry Flavor Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Concentrates, Powders, Infusions End User: Food & Beverage, Bakery, Confectionery, Nutraceuticals Application: Beverages, Dairy Products, Sauces, Snacks Form: Liquid, Solid, Spray-dried, Microencapsulated |
| Companies Covered | Givaudan, Firmenich SA, Symrise AG, Kerry Group PLC, Sensient Technologies Corporation, International Flavors & Fragrances (IFF), Takasago International Corporation, Archer Daniels Midland (ADM), Robertet SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Berry Flavor Market Strategic Shifts
Fermentation and enzyme-assisted extraction methods are displacing conventional solvent-based processes while regulatory pressure on synthetic additives intensifies formulation chemistry requirements. These forces are compressing traditional supply relationships and elevating technical service capabilities as competitive differentiators.
Cell-free enzymatic bioprocessing is displacing ethanol and hexane extraction in premium flavor production. Functional beverage formulators in Germany and Switzerland are adopting these systems at pilot scale to secure clean-label positioning. This technology is displacing legacy solvent infrastructure and compressing margin structures for conventional extract houses dependent on volume throughput.
EFSA's updated guidance on botanical safety assessments is tightening novel food evidentiary standards for wild-harvested berry concentrates. Industrial consequence includes mandatory pesticide metabolite testing and supply chain traceability documentation to batch level. Nutraceutical end-users in France and Italy are responding by qualifying captive sourcing partnerships with Nordic foraging cooperatives.
Direct procurement relationships between beverage brands and extraction specialists are collapsing traditional flavor house intermediation. Dairy and plant-based drink manufacturers are building technical integration teams that bypass conventional distributor networks. This channel compression is most visible in German-speaking markets where co-manufacturing agreements embed flavor specification into processor contracts.
Natural Berry Flavor Market Segmentation
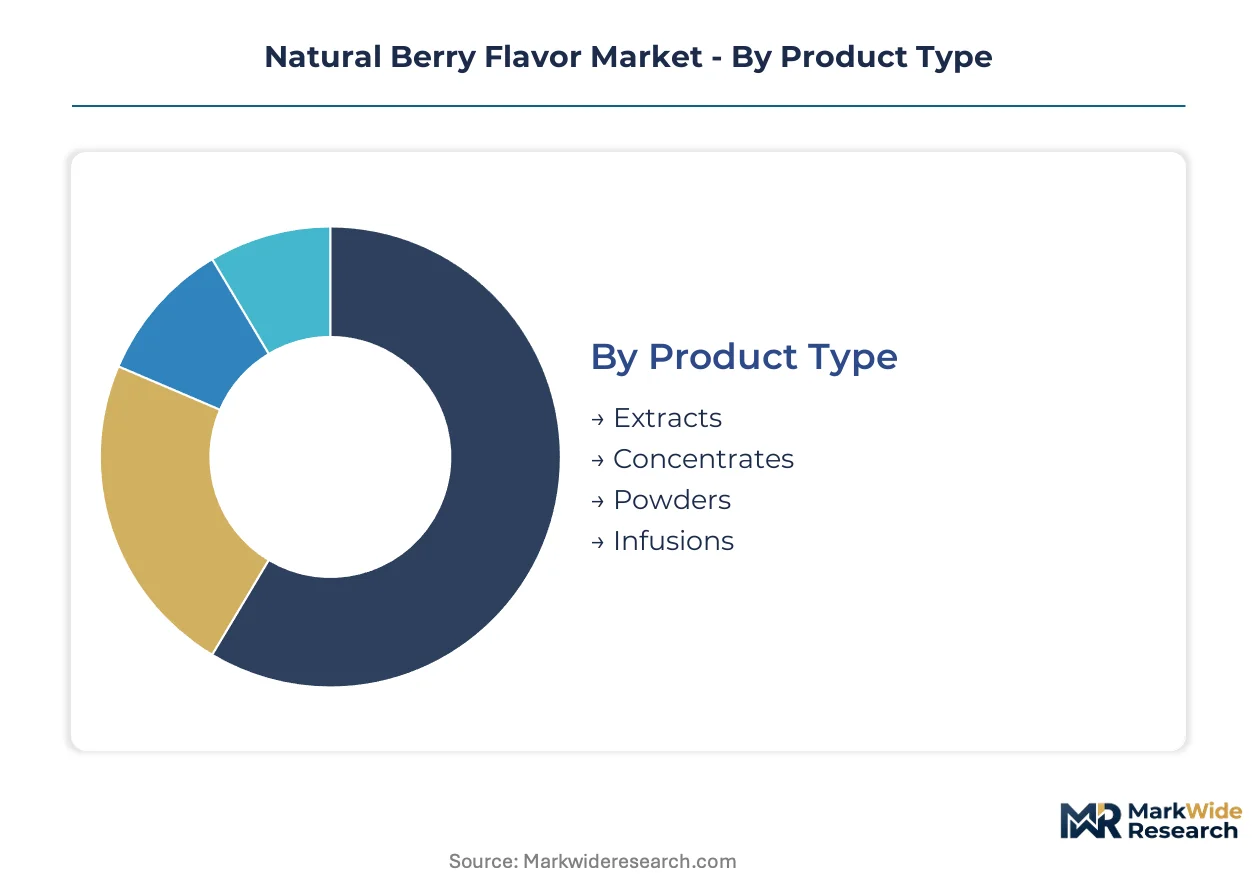
Natural berry flavor procurement flows through distinct channel architectures depending on product format and end-use specifications. Beverage formulators prioritize aqueous solubility and clean-label compatibility, while nutraceutical buyers demand standardized polyphenol content with batch-level traceability documentation.
Product Type:
Channel segmentation reveals concentrated procurement through beverage co-manufacturing networks for liquid formats, with powder systems flowing through bakery ingredient distributors.
- Extracts:Cold-pressed or solvent-free aromatic compounds standardized to specific anthocyanin content and Brix levels. Beverage manufacturers in Germany source these directly from extraction specialists to bypass traditional flavor house intermediation, driven by EFSA clean-label mandates compressing synthetic alternatives.
- Concentrates:Polyphenol-standardized preparations with elevated solids content for functional positioning. Nutraceutical end-users in France and Italy are adopting these at volumes rivaling legacy confectionery procurement, collapsing traditional buyer hierarchies.
- Powders:Spray-dried or freeze-dried formats for dry-mix applications.
- Infusions:Steeped preparations for premium beverage and artisanal food segments.
By volume, extracts lead. By expansion trajectory, concentrates are climbing the fastest.
End User:
Cost tier stratification separates premium-positioned nutraceutical buyers from volume-driven food manufacturers.
- Food & Beverage:Clean-label beverage brands accelerate procurement as synthetic dye bans tighten. Functional drink startups in German-speaking markets source polyphenol-standardized materials directly, embedding flavor specifications into processor co-manufacturing contracts.
- Nutraceuticals:Immune and cognitive health product manufacturers demand dual-function positioning with verified polyphenol content. FSSAI regulatory clarifications in India are opening ayurvedic supplement formulation opportunities for standardized concentrates.
- Bakery:Heat-stable applications requiring microencapsulation investments.
- Confectionery:Legacy procurement networks facing displacement from beverage vertical demand concentration.
Food & Beverage commands volume dominance. Nutraceuticals show the steepest share gain.
Application:
Application mix reflects thermal stability requirements and water-activity constraints across processing environments.
- Beverages:Aqueous matrices favoring high-solubility extracts with clean-label positioning. German formulators source concentrated anthocyanin preparations for functional drink applications, leveraging fermentation-assisted extraction methods to reduce solvent residues.
- Dairy Products:Direct injection systems at processor co-manufacturing lines eliminate intermediate handling. Spray-dried flavor integration extends shelf-life for yogurt applications while reducing oxidation exposure.
- Sauces:Acid-stable preparations for condiment matrices.
- Snacks:Heat-resistant formats demanding protective wall-system technologies.
Beverages anchor volume flows. Dairy applications are expanding most quickly through technical integration partnerships.
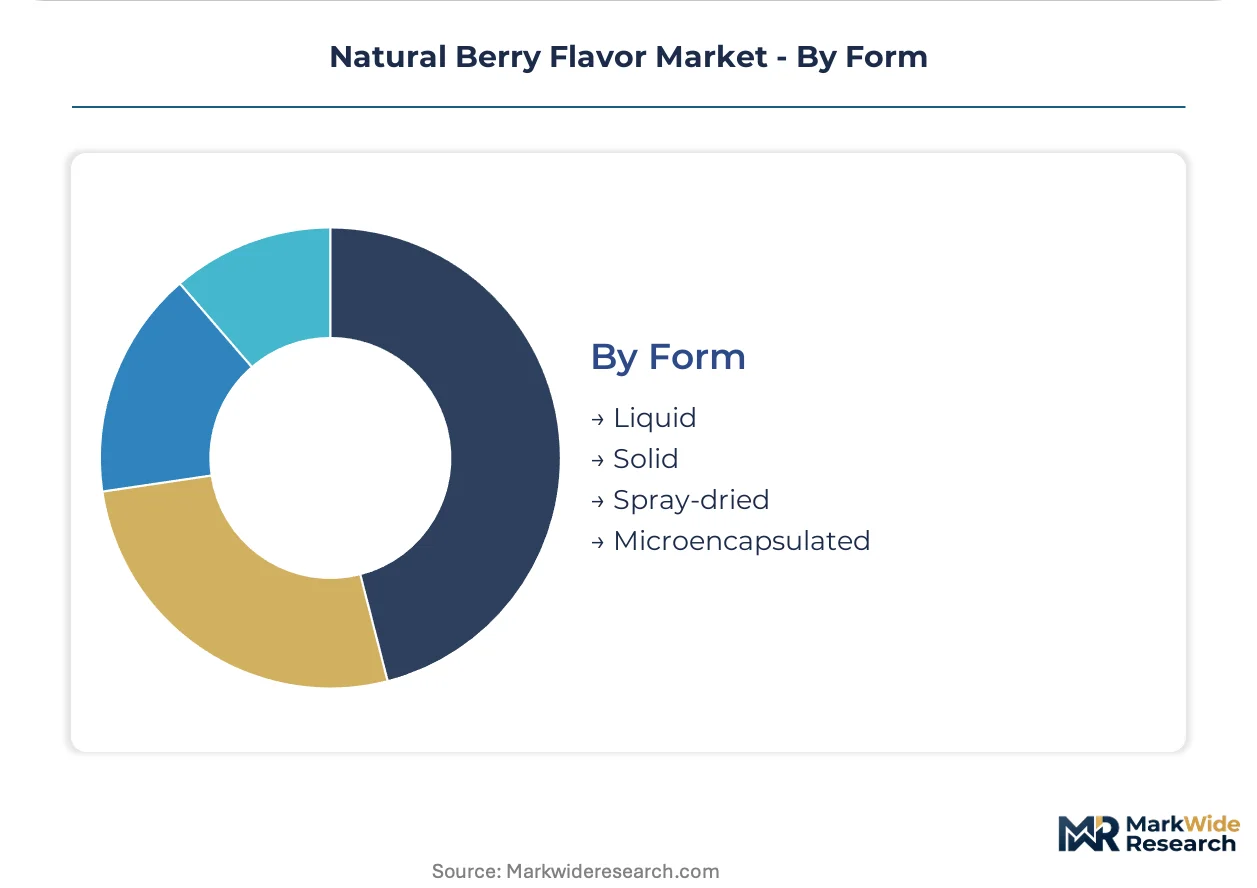
Form:
Margin structure varies sharply by processing complexity and protective technology requirements.
- Liquid:Standard aqueous or oil-based preparations for immediate incorporation.
- Solid:Crystallized or granulated formats for dry blending operations.
- Spray-dried:Atomized particles with modified starch or gum arabic carriers for extended shelf-life. Kerry Group PLC integrates these systems directly into dairy processor lines, compressing traditional distribution channels.
- Microencapsulated:Wall-system protected formats using lipid or protein matrices to shield volatile esters from thermal degradation above 60°C. Bakery and snack applications command premium pricing due to bioactivity preservation requirements.
Liquid forms dominate current procurement. Microencapsulated variants capture the widest margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals anchor European natural berry extract flows, handling concentrated anthocyanin shipments from Nordic foraging cooperatives before redistribution to German and French formulators.
Germany
Beverage co-manufacturing clusters in Bavaria and North Rhine-Westphalia source fermentation-assisted extracts directly from extraction specialists. EFSA clean-label mandates under the EU Food Improvement Agent Package compress synthetic flavor inventories. Munich-based functional drink startups embed polyphenol specifications into processor contracts, collapsing traditional distributor hierarchies.
France
Artisanal extract producers in Provence-Alpes-Côte d'Azur anchor deep R&D partnerships with flavor houses. ANSM novel food assessments and ECHA REACH compliance obligations shape supplier qualification protocols. Lyon and Paris Basin nutraceutical formulators qualify captive sourcing partnerships with Baltic foraging cooperatives for verified traceability.
Switzerland
Geneva and Basel pharmaceutical-nutraceutical corridors demand dual-function berry concentrates for immune-positioned products. Swissmedic quality standards exceed baseline EU requirements, creating premium tier separation. Zürich-based formulators integrate spray-dried systems directly into dairy processor lines.
United States
FDA GRAS self-affirmation pathways create divergent market access timelines favoring established players with dedicated regulatory infrastructure. California and New Jersey flavor innovation clusters source wild-harvest Vaccinium from Pacific Northwest foraging networks. Midwest dairy processors adopt direct injection systems for extended shelf-life yogurt applications.
India
FSSAI functional food regulations clarify health claim pathways for polyphenol concentrates in ayurvedic supplement formulations. Maharashtra and Karnataka nutraceutical manufacturing zones expand procurement of standardized berry extracts. Mumbai and Bangalore-based formulators leverage clarified regulatory pathways for dual-positioning immune and cognitive health products.
Natural Berry Flavor Market Competitive Environment
Concentration sits with integrated flavor houses possessing captive botanical networks and dedicated regulatory affairs infrastructure. Tiered competition separates multinational extract houses with multi-continent sourcing capabilities from regional specialists in fermentation-assisted processing and microencapsulation wall-system technologies. Strategic moves center on backward integration into wild-harvest supply partnerships and direct technical integration at processor co-manufacturing lines.
Among Swiss and French flavor specialists, Givaudan, Firmenich SA, and Kerry Group PLC exemplify divergent competitive positions. Givaudan represents the multi-continent captive sourcing archetype. Firmenich SA occupies a position anchored in artisanal European extract partnerships. Kerry Group PLC exemplifies technical integration at processor lines, compressing traditional distribution channels through direct dairy system embedding.
| Leading Market Players |
|---|
| Givaudan |
| Firmenich SA |
| Symrise AG |
| Kerry Group PLC |
| Sensient Technologies Corporation |
| International Flavors & Fragrances (IFF) |
| Takasago International Corporation |
| Archer Daniels Midland (ADM) |
| Robertet SA |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Nordic extraction facilities shapes both supply concentration and price floors for anthocyanin-standardized berry preparations. German beverage formulators absorb volume premiums to secure fermentation-assisted extracts under EFSA clean-label mandates, compressing margin structures for smaller processors lacking direct sourcing relationships.
Pricing Analysis
Volume-discount tiering separates multinational flavor houses from regional extraction specialists and artisanal producers. Premium-mid-economy pricing differentiation rests on polyphenol standardization grade and ECHA REACH registration status, with certified batches commanding substantial markups. Pricing pressure stems from beverage startup procurement volumes rivaling legacy confectionery buyers. Nutraceutical end-users show lowest price sensitivity due to dual-function health claim positioning, while bakery manufacturers face acute cost compression from microencapsulation wall-system investments.
Supply Chain Analysis
Finland, Sweden, and Estonia anchor wild-harvest Vaccinium and Ribes sourcing through foraging cooperatives. Downstream processing draws from cold-press extraction equipment, fermentation bioreactors, and spray-drying infrastructure concentrated in Germany and Switzerland. Single-source vulnerability concentrates in Baltic berry harvesting regions exposed to weather-driven volume volatility. Distribution runs through Rotterdam liquid bulk terminals for concentrated extracts, with direct technical integration at Bavarian and North Rhine-Westphalia co-manufacturing lines displacing traditional flavor house intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
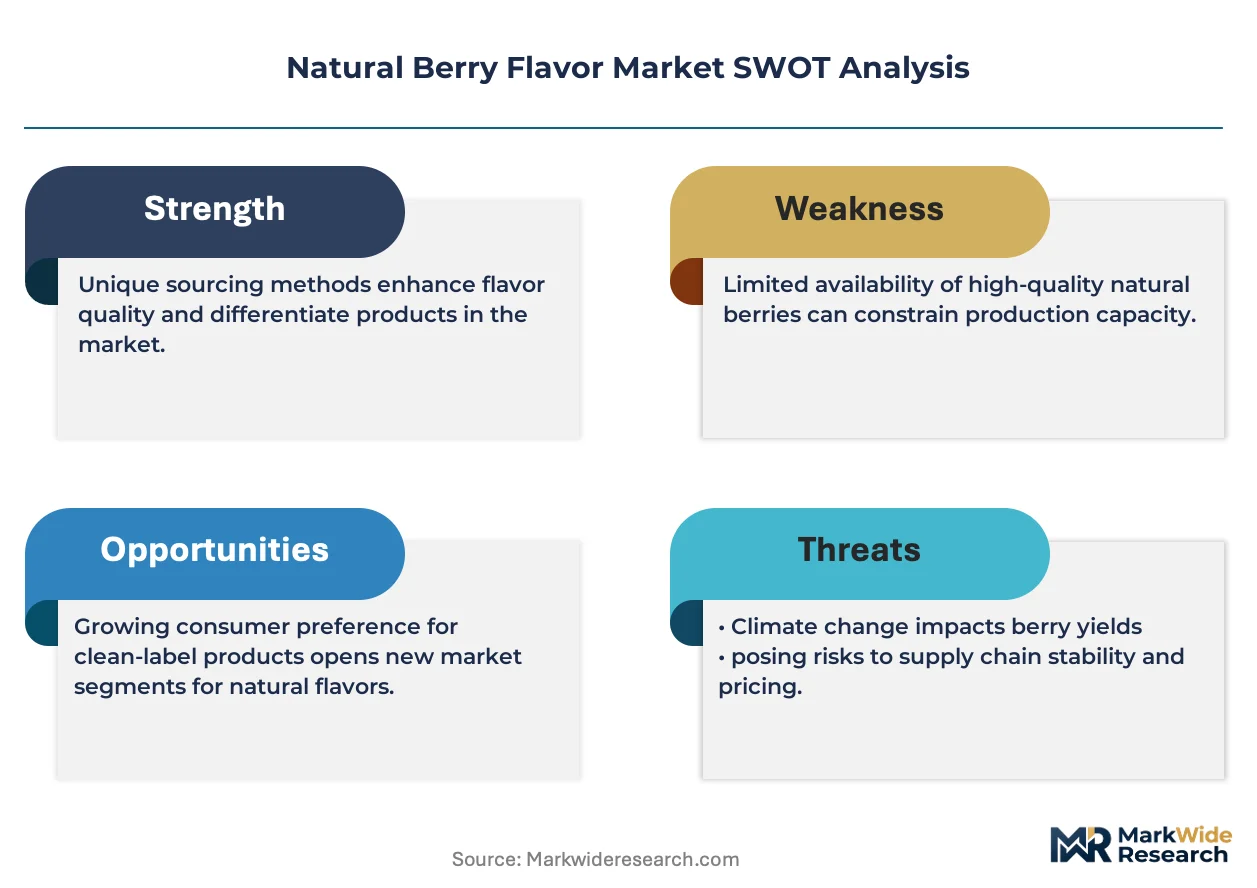
Natural berry flavor procurement constitutes a defensive-moat market where EFSA and ECHA regulatory entrenchment creates substantial switching costs for qualified suppliers. Network effects concentrate among extraction specialists with validated wild-harvest partnerships and novel food authorization track records.
For Market Incumbents: Secure captive sourcing partnerships with Nordic foraging cooperatives to defend against beverage startup vertical integration. Invest in fermentation-assisted extraction capacity additions in Germany to capture EFSA-driven synthetic substitution demand. Prioritize ECHA REACH registration maintenance for novel cultivar pipelines. For New Entrants and Emerging Players: FSSAI fast-track certification for polyphenol concentrates opens India nutraceutical white-space with clarified ayurvedic health claim pathways. Target Maharashtra and Karnataka manufacturing zones with direct technical service teams embedding specifications into processor contracts. Lead with spray-dried dairy integration capabilities to bypass established distribution networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among extraction specialists with multi-year beverage co-manufacturing agreements and regulatory affairs infrastructure. Long-term viability favors targets with demonstrated EFSA novel food authorization success and captive Baltic supply partnerships. Watch for EFSA guidance updates on botanical safety assessments as inflection indicators for qualification cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wild-Harvest Supply | Nordic foraging cooperative partnerships secure volume priority and pesticide metabolite compliance under EFSA traceability mandates. |
| Fermentation-Assisted Extraction Scale-Up | Enzymatic bioprocessing investments reduce solvent residues and unlock clean-label positioning for German beverage formulators. |
| Direct Technical Integration at Processor Lines | Spray-dried system embedding at dairy co-manufacturing facilities compresses traditional distributor margins and extends yogurt shelf-life. |
| EU Green Deal Bioeconomy Funding Capture | Circular extraction grants lower capital barriers for solvent-free infrastructure expansion in sustainable production scale-up. |
| Novel Food Authorization Pipeline Investment | EFSA safety opinion preparation for non-traditional berry cultivars freezes competitor product development cycles. |
Study Parameters
Initial hypotheses were tested against primary input from extraction facility operations managers, beverage formulation R&D directors, nutraceutical procurement leads, and EFSA regulatory affairs specialists and refined through secondary validation. Trade data from Eurostat customs filings, EFSA novel food application databases, ECHA REACH registration records, and FSSAI functional food notification logs anchored supply-side quantification. Bottom-up volume triangulation across product formats and end-use segments reconciled with top-down value estimates from flavor house financial disclosures.
Variance decomposition across the projection horizon isolated drivers by product type, end-user vertical, application matrix, and regional regulatory cluster. CAGRs were derived from segment-level volume growth trajectories and value-per-unit expansion patterns. Forecast inputs incorporated EFSA synthetic additive ban implementation timelines, FSSAI regulatory clarification milestones, and fermentation technology adoption curves in German-speaking markets.
Decision-makers should treat outputs as directional under sustained EFSA enforcement intensity and stable Baltic foraging yields; material deviation would warrant model refresh. Recalibration cycles align with material shifts in EFSA guidance updates, ECHA REACH cost structures, and FSSAI health claim pathway clarifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Flavor Drops Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Annatto Extract Market
Flavorings and Food Additives
Asia-Pacific Food Colorants Market
Flavorings and Food Additives
Flavored Butter and Oils Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Natural Flavors and Fragrances Market
Flavorings and Food Additives
All-Natural Flavors System Market
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
Cholic Acid Market
Flavorings and Food Additives
Edible Food Paints Market
Flavorings and Food Additives
Tangerine Extract Market