
 Global Eucalyptus Essential Oil Market | 2026-2036
Global Eucalyptus Essential Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Eucalyptus Essential Oil Market Foresight
Synthetic eucalyptus oil is repositioning cost structures in mass-market personal care, forcing steam-distilled grades toward premium positioning. Suzano leverages its South American pulp-to-oil supply chain to control raw material flows. Young Living Essential Oils anchors its competitive stance through direct-to-wellness-center distribution. Symrise AG differentiates via pharmaceutical-grade certification programs that secure API supplier status.
Eucalyptus essential oil comprises volatile compounds extracted from Eucalyptus globulus and related species, typically containing 70-90% eucalyptol (1,8-cineole) as the primary active constituent responsible for its therapeutic and antimicrobial properties. Steam-distilled organic grades command premium positioning in aromatherapy and pharmaceutical applications where residual solvent standards from EMA and FDA apply. The personal care application segment shows structural momentum as cosmetic manufacturers reformulate with natural antimicrobials to replace synthetic preservatives. Pharmaceutical companies represent the most concentrated end-user margin pool, with bulk drum packaging dominating volume procurement for API production.
EMA monographs and FDA GRAS listings govern pharmaceutical and food flavoring applications, while REACH registration in Europe mandates full toxicological dossiers for import volumes exceeding one tonne annually. Australia's APVMA regulates agricultural chemical claims for eucalyptus-based insect repellents, creating separate compliance pathways from therapeutic goods. Stakeholders must monitor evolving pharmacopeial standards across FDA, EMA, and TGA jurisdictions to anticipate specification changes that will redraw supplier qualification requirements.
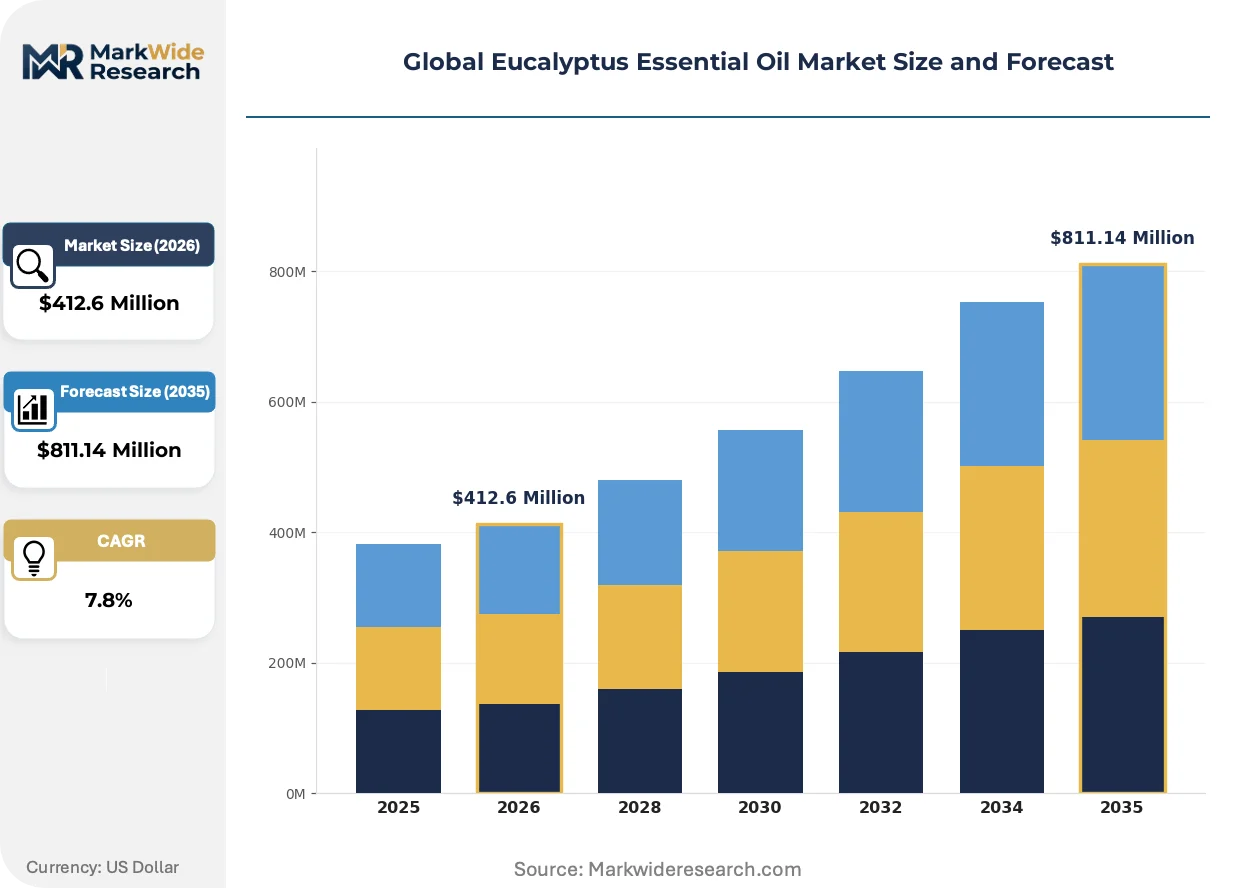
Market Dynamics
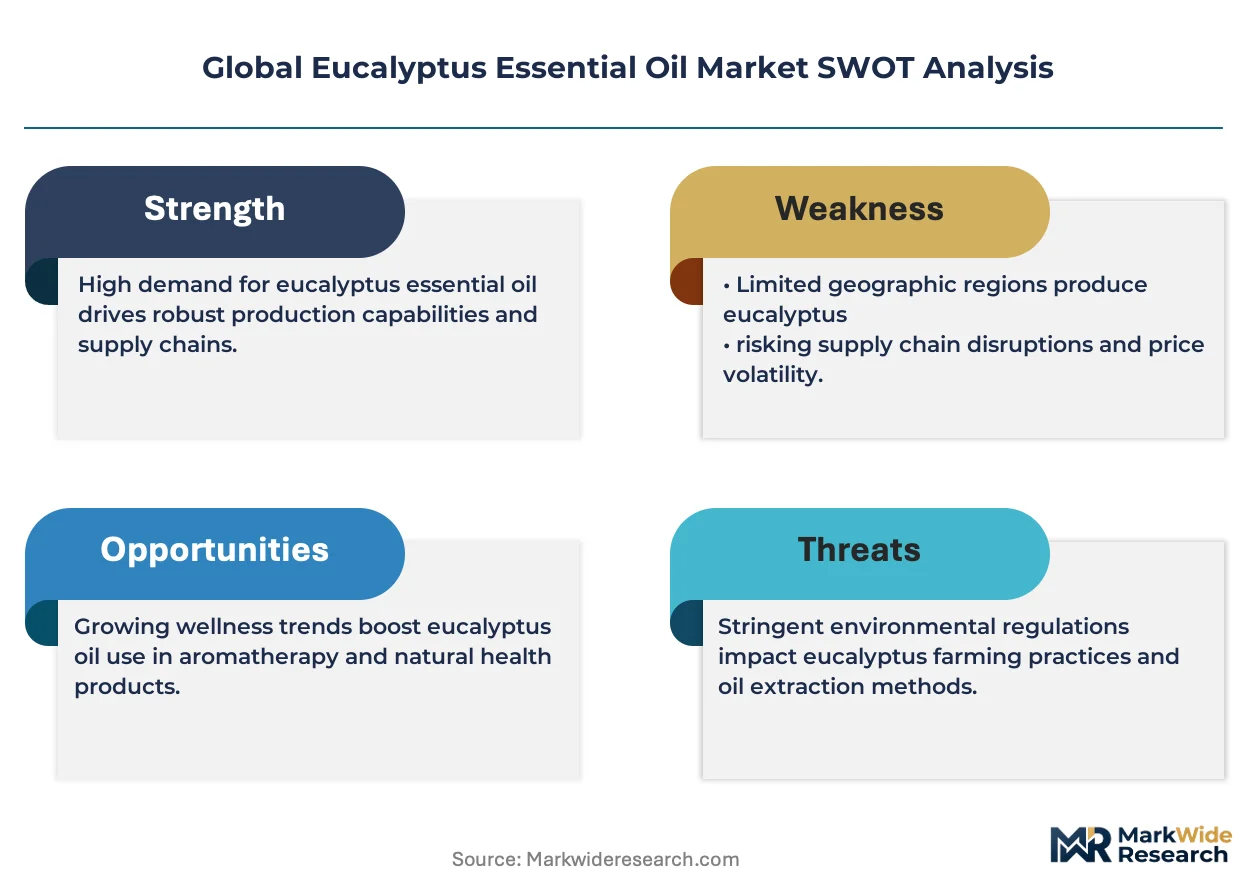
REACH compliance in Europe is tightening purity thresholds for essential oil imports, forcing extraction facilities to upgrade distillation infrastructure and pushing marginal suppliers out of pharmaceutical qualification pipelines.
Growth Catalysts
- Respiratory API Demand:Pharmaceutical manufacturers are expanding eucalyptus oil procurement for cough and cold formulations, with eucalyptol serving as a key active pharmaceutical ingredient in expectorant products.
- EMA Monograph Alignment:Harmonized pharmacopeial standards across European member states are reducing regulatory fragmentation and accelerating cross-border API approval timelines for certified suppliers.
- Steam Distillation Yield Improvements:Advanced column design and temperature control systems are boosting extraction efficiency from Eucalyptus globulus biomass, lowering unit production costs for organic grades.
Market Restraints
- Feedstock Concentration Risk:Plantation supply chains concentrate in Australia and select South American corridors, exposing processors to climate volatility and regional logistics disruptions.
- Synthetic Substitution Pressure:Lab-produced 1,8-cineole from petrochemical feedstocks undercuts natural oil pricing in mass-market personal care applications, compressing margins for conventional grades.
- REACH Dossier Burden:Full toxicological registration requirements for import volumes exceeding one tonne annually impose six-figure compliance costs that exclude smaller trading houses from European pharmaceutical supply chains.
Strategic Opportunities
- Indian Aromatherapy Expansion:Wellness center chains in Mumbai and Bangalore are building direct procurement relationships with Australian distillers, bypassing traditional import distributors.
- Natural Preservative Pivot:Cosmetic formulators in South Korea are replacing synthetic parabens with eucalyptus-derived antimicrobials in rinse-off products, creating specification demand for food-grade oil variants.
- Carbon-Neutral Certification:EU Green Deal-aligned carbon accounting frameworks offer premium positioning for plantation operators with verified reforestation and renewable energy credentials.
Industry Challenges
- Pharmacopeial Chemist Scarcity:Analytical laboratories face acute shortages of specialists trained in GC-MS fingerprinting for essential oil authentication, delaying batch release timelines.
- Multi-Jurisdiction Qualification Overlap:Simultaneous FDA GRAS, EMA monograph, and TGA therapeutic goods compliance requires redundant stability studies and specification documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Eucalyptus Essential Oil Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $811.14 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Synthetic, Steam Distilled, Solvent Extracted, Cold Pressed Application: Aromatherapy, Pharmaceuticals, Personal Care, Insect Repellent, Food Flavoring End User: Pharmaceutical Companies, Cosmetic Manufacturers, Food & Beverage Firms, Household Care Producers, Wellness Centers Packaging Type: Glass Bottles, Plastic Containers, Dropper Bottles, Spray Bottles, Bulk Drums |
| Companies Covered | Oil and Natural Gas Corporation Ltd, NOW Health Group Inc, Suzano, Biolandes SA, NHR Organic Oils, Eucatex, Young Living Essential Oils, Symrise AG, Montes del Plata, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Eucalyptus Essential Oil Market Shifts & Advancements
Supercritical CO2 extraction is disrupting traditional steam distillation economics while blockchain-enabled provenance tracking is rewiring buyer-supplier trust architectures in premium segments.
Supercritical CO2 extraction technology is decentralizing production geography by enabling smaller-scale, modular facilities to achieve pharmaceutical-grade purity without the capital intensity of legacy steam-distillation plants. Regional cooperatives in Portugal and Spain are deploying containerized units to process local Eucalyptus nitens harvests. This distributed model is compressing transportation costs and shortening farm-to-flask timelines for European API manufacturers.
REACH registration deadlines for full toxicological dossiers are forcing importers to consolidate supplier bases around pre-qualified Australian and Brazilian plantation operators with existing compliance infrastructure. The regulation is accelerating exit of spot-market traders and informal brokers from pharmaceutical-grade supply chains. German and French flavor houses are responding by locking multi-year offtake agreements with certified biomass processors.
Direct-to-wellness-center distribution models are displacing layered import-distributor-wholesaler networks in aromatherapy channels. Young Living and comparable suppliers are building proprietary logistics arms to serve yoga studios and spa chains in California and Texas. This channel compression is most visible in North American metropolitan corridors where wellness consumption concentrates and buyer sophistication around oil authentication runs highest.
Global Eucalyptus Essential Oil Market Segmentation
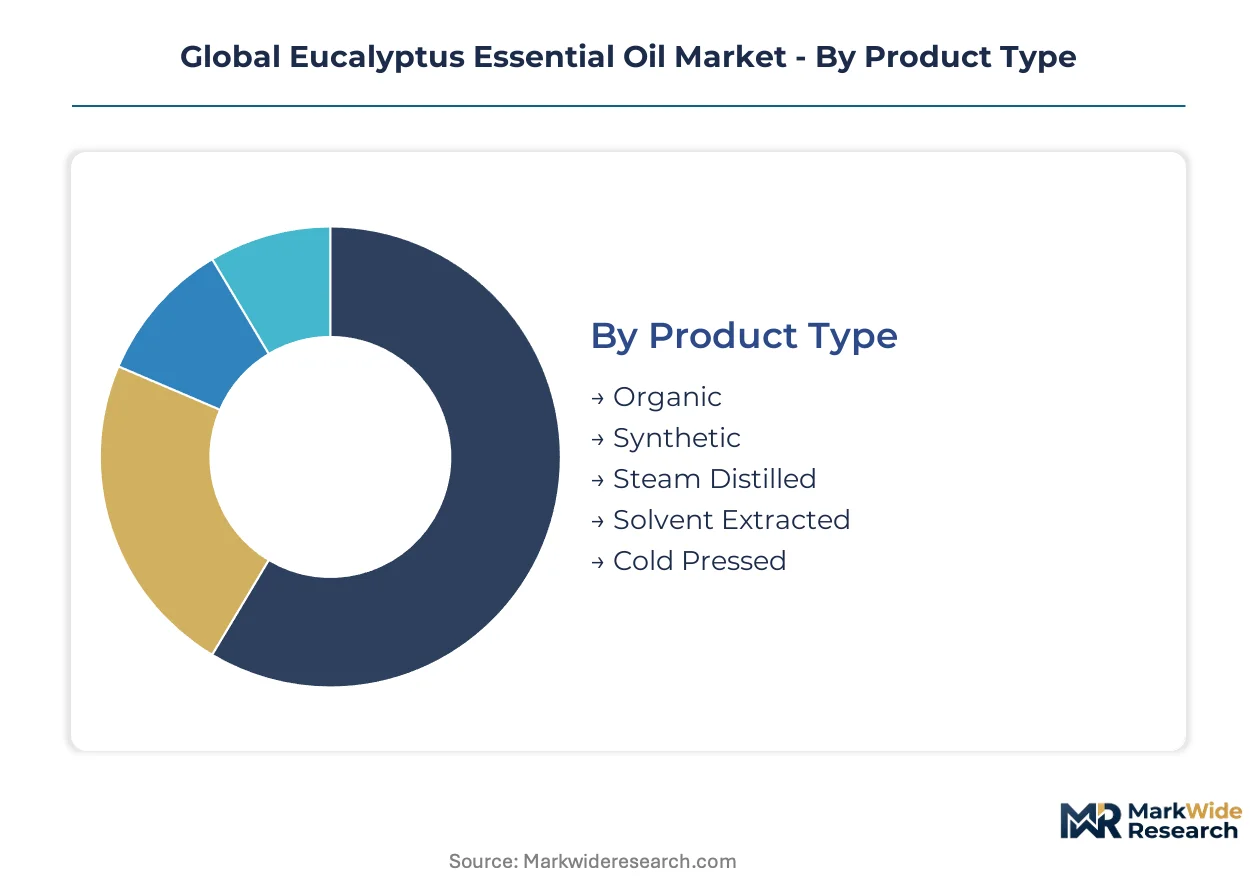
Segmentation in eucalyptus essential oil reveals how supply chain configuration and regulatory pathways split procurement behaviors across end-use industries. Distinct purity thresholds, packaging requirements, and certification demands create parallel commercial channels that rarely intersect.
Product Type:
Supply concentration around Australian plantation corridors favors steam-distilled organic grades, while synthetic alternatives exploit petrochemical feedstock security in Chinese and Indian chemical parks.
- Steam Distilled:Dominates pharmaceutical qualification pipelines with 70-90% eucalyptol content meeting EMA monograph specifications. Australian distillers in Victoria and New South Wales control the bulk of certified biomass, locking multi-year offtake agreements with European API manufacturers facing REACH compliance deadlines.
- Organic:Commands premium positioning in aromatherapy and wellness channels where USDA Organic and EU Organic certification justify price multiples. Demand concentrates in California and German metropolitan clusters where direct-to-consumer brands bypass traditional distribution tiers.
- Synthetic:Lab-produced 1,8-cineole from turpentine-derived feedstocks undercuts natural oil pricing in mass-market personal care applications across Brazil and Southeast Asia.
- Solvent Extracted:Hexane-based processes yield higher absolute oil volumes but face residual solvent limits under FDA GRAS and EMA frameworks, restricting use to industrial fragrance applications.
- Cold Pressed:Preserves volatile compound profiles for boutique cosmetic formulations in South Korea and Japan where MIIT and MFDS standards govern natural preservative claims.
Steam-distilled grades absorb the bulk of installed capacity; organic certification is expanding most quickly as EU Green Deal procurement criteria harden.
Application:
Cost tier stratification separates commodity fragrance inputs from therapeutic-grade specifications that command tenfold price differentials.
- Pharmaceuticals:Eucalyptol serves as an active pharmaceutical ingredient in expectorant formulations, with FDA GRAS and EMA monograph compliance mandatory for API supplier status. German and French generic drug manufacturers represent the most concentrated margin pool, procuring exclusively in bulk drum formats.
- Aromatherapy:Direct-to-wellness-center distribution models displace import-distributor networks in North American metropolitan corridors. Young Living and comparable suppliers build proprietary logistics arms to serve yoga studios and spa chains in Texas and California.
- Personal Care:Cosmetic formulators in South Korea replace synthetic parabens with eucalyptus-derived antimicrobials in rinse-off products, creating specification demand for food-grade oil variants.
- Insect Repellent:Australia's APVMA regulates agricultural chemical claims separately from therapeutic goods, creating distinct compliance pathways for plantation-based repellent manufacturers.
- Food Flavoring:Limited volumes serve confectionery and beverage applications where FEMA GRAS listings govern maximum permissible concentrations.
Pharmaceutical applications capture the steepest margin premiums; personal care antimicrobial substitution is gaining share fastest.
End User:
Customer type determines packaging format, batch size, and documentation intensity, with pharmaceutical companies demanding pharmacopeial certificates of analysis that wellness centers rarely request.
- Pharmaceutical Companies:Bulk drum procurement dominates, with stability studies and forced degradation data required for FDA, EMA, and TGA multi-jurisdiction filings. REACH-registered Australian suppliers capture the bulk of European API supply chains.
- Cosmetic Manufacturers:South Korean and French formulators drive demand for glass bottle and dropper formats, with carbon-neutral certification increasingly specified in RFPs.
- Food & Beverage Firms:Flavor houses in Switzerland and Germany source food-grade variants for chewing gum and cough drop applications.
- Household Care Producers:Mass-market cleaning product manufacturers in Brazil and India favor synthetic grades for cost-sensitive disinfectant formulations.
- Wellness Centers:Direct procurement relationships with Australian distillers are emerging in Mumbai and Bangalore, bypassing traditional import distributors.
Pharmaceutical companies absorb the bulk of high-purity capacity; wellness centers are expanding most quickly as channel compression accelerates.
Packaging Type:
Volume scale dictates format selection, with regulatory documentation requirements clustering around bulk pharmaceutical shipments and premium branding investments concentrated in retail-facing formats.
- Bulk Drums:Stainless steel and lined steel containers dominate API procurement, with tamper-evident seals and chain-of-custody documentation mandatory for pharmaceutical qualification.
- Glass Bottles:Amber and cobalt glass formats protect photosensitive compounds in aromatherapy and boutique cosmetic channels.
- Dropper Bottles:Calibrated glass pipettes serve precision dosing requirements in clinical aromatherapy and veterinary applications.
- Spray Bottles:Fine-mist atomizers target household care and natural insect repellent segments.
- Plastic Containers:HDPE and PET formats compete on cost in mass-market personal care, though essential oil compatibility limits polymer selection.
Bulk drums absorb the bulk of tonnage movement; dropper bottles are expanding most quickly as precision-dosing wellness products proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Australia's plantation belt concentrate extraction infrastructure near Victorian biomass corridors. Germany's REACH-registered importers anchor European pharmaceutical qualification pipelines. India's wellness center chains in Mumbai and Bangalore build direct procurement relationships with Australian distillers.
Australia
Pharmaceutical API manufacturers expand procurement from Eucalyptus globulus plantations in Victoria and New South Wales. The APVMA regulates agricultural chemical claims separately from TGA therapeutic goods standards. Distillers near Melbourne lock multi-year offtake agreements with European flavor houses facing REACH compliance deadlines.
Germany
Generic drug manufacturers in Baden-Württemberg and North Rhine-Westphalia dominate European eucalyptol API consumption. EMA monograph alignment reduces cross-border regulatory fragmentation for certified suppliers. Frankfurt-area flavor houses consolidate supplier bases around pre-qualified Australian plantation operators.
United States
Wellness center chains in California and Texas drive direct-to-consumer aromatherapy demand. FDA GRAS listings govern food flavoring applications while EPA registration applies to insect repellent formulations. Young Living builds proprietary logistics arms to serve yoga studios in metropolitan corridors.
South Korea
Cosmetic formulators in Seoul and Busan replace synthetic parabens with eucalyptus-derived antimicrobials. MFDS standards govern natural preservative claims in rinse-off products. R&D clusters in Gyeonggi Province specify food-grade oil variants for carbon-neutral certified formulations.
Brazil
Suzano leverages South American pulp-to-oil supply chains to control raw material flows for mass-market personal care. ANVISA pharmaceutical-grade certification programs secure API supplier status for export-oriented processors. São Paulo-state extraction facilities serve disinfectant manufacturers across Latin America.
Global Eucalyptus Essential Oil Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical qualification pipelines favoring integrated plantation operators and aromatherapy channels rewarding direct-to-wellness distribution. The vendor base clusters around three strategic archetypes: Australian biomass controllers with REACH-registered infrastructure, South American pulp-to-oil integrators, and North American wellness brands with captive logistics networks. Dominant competitive moves include backward integration into plantation assets and multi-year offtake agreements that lock pharmaceutical-grade capacity.
Within the plantation-integrated tier, Suzano exemplifies South American supply chain control, while Young Living Essential Oils anchors North American wellness distribution. Symrise AG occupies a position among European flavor houses consolidating around certified biomass processors. These three represent distinct competitive vectors: upstream raw material security, direct channel compression, and regulatory qualification depth.
| Leading Market Players |
|---|
| Oil and Natural Gas Corporation Ltd |
| NOW Health Group Inc |
| Suzano |
| Biolandes SA |
| NHR Organic Oils |
| Eucatex |
| Young Living Essential Oils |
| Symrise AG |
| Montes del Plata |
| Others |
Supply & Pricing Matrix
Family-owned plantation operators in Victoria and New South Wales anchor supply-side discipline, translating multi-generational land tenure into long-term contract pricing stability that shields pharmaceutical buyers from spot-market volatility. Their refusal to sell biomass at distressed rates creates floor pricing that synthetic alternatives struggle to undercut in certified-grade segments.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with German API manufacturers paying substantial markups for guaranteed quarterly delivery windows versus annual offtake commitments. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade certifications creates clear stratification. Cost compression in personal care tiers is intensifying because Brazilian synthetic producers exploit pulp-integrated feedstock security. Mass-market household care manufacturers exhibit highest price sensitivity, while FDA-registered drug sponsors accept premium positioning without negotiation.
Supply Chain Analysis
Skilled distillation technicians are scarce in Portuguese and Spanish regional cooperatives deploying modular supercritical CO2 units, constraining throughput expansion despite favorable biomass availability. Production gravity centers on Australia, Brazil, and select South American corridors. Feedstock supply draws from Eucalyptus globulus plantations, chemical-grade hexane for solvent extraction, and stainless steel drum packaging. Single-source vulnerability concentrates in Victorian biomass corridors exposed to drought cycles. Distribution runs through direct-to-wellness-center networks in North America and layered import-distributor channels elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as supercritical CO2 extraction displaces legacy steam-distillation infrastructure, rewarding early adopters with pharmaceutical-grade purity at reduced capital intensity.
For Market Incumbents: Cement API supplier status by locking multi-year offtake agreements with REACH-registered Australian plantation operators before competitor consolidation accelerates. Deepen upstream control over Eucalyptus nitens biomass in Iberian regional cooperatives to secure non-Australian supply hedges against climate volatility in Victoria corridors. Synthetic substitution from Chinese chemical parks represents the primary margin threat requiring defensive positioning. For New Entrants and Emerging Players: Capture white-space in Indian wellness center direct procurement, where Mumbai and Bangalore chains bypass traditional import distributors to source from Australian distillers. The aromatherapy channel offers lowest qualification barriers and fastest route to revenue. Lead with carbon-neutral certification storytelling to differentiate against established commodity suppliers in EU Green Deal-aligned RFPs. For Investors and Strategic Acquirers: REACH registration deadline acceleration is the leading indicator that pre-qualified Australian biomass processors will command scarcity premiums in European pharmaceutical supply chains. Long-term viability favors integrated plantation-to-extraction operators with existing compliance infrastructure over trading houses facing six-figure dossier burdens. Watch for German and French flavor house consolidation moves around certified biomass processors as the signal for valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Suzano's pulp-to-oil supply chain control secures raw material flows against feedstock volatility. |
| Multi-year Offtake Agreement | German API manufacturers lock pharmaceutical-grade capacity ahead of REACH compliance deadlines. |
| Direct-to-Wellness-Center Distribution | Young Living's proprietary logistics arms serve California yoga studios with compressed channel economics. |
| Carbon-Neutral Certification Program | EU Green Deal-aligned plantation operators capture premium positioning in European cosmetic RFPs. |
| Supercritical CO2 Technology Deployment | Portuguese regional cooperatives achieve pharmaceutical purity without legacy steam-distillation capital intensity. |
Research Methodology
Document review covered customs and trade data, EMA monograph filings, and APVMA agricultural chemical registrations, complemented by interviews with Australian plantation operators, German generic drug procurement leads, and South Korean cosmetic formulators. Secondary validation drew from TGA therapeutic goods standards, FDA GRAS listings, and REACH registration databases. Bottom-up biomass yield modeling and top-down API demand estimation provided cross-referenced triangulation.
Historical extraction capacity expansion patterns were cross-referenced against expert panel input from distillation equipment manufacturers and pharmaceutical qualification specialists. Segmentation modeling spanned product type, application, end user, and packaging format dimensions across the projection horizon. CAGRs were derived from demand elasticity analysis in respiratory API formulations and antimicrobial substitution trends in personal care. Forecast inputs incorporated steam-distillation yield improvement curves and supercritical CO2 adoption rates in European regional cooperatives.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pharmacopeial standard revisions across FDA, EMA, and TGA jurisdictions, climate volatility in Australian plantation belts, and synthetic 1,8-cineole cost curves in Chinese chemical parks. Material deviation in REACH enforcement intensity or Eucalyptus globulus biomass yields warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Farnesol Market
Flavorings and Food Additives
Mint Essential Oils Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market
Flavorings and Food Additives
United States Food Colorants Market
Flavorings and Food Additives
Menthol Market
Flavorings and Food Additives
Food Colorants Market
Flavorings and Food Additives
Natural Food Colors Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
Food Grade Menthol Crystal Market
Flavorings and Food Additives
Smoke Flavorings Market
Flavorings and Food Additives
Asia-Pacific Flavor and Fragrance Market
Flavorings and Food Additives
Africa Food Colorants Market
Flavorings and Food Additives
Botanical Flavors Market
Flavorings and Food Additives
Beverage Flavoring Agent Market
Flavorings and Food Additives
Cheese Flavor Market