
 Asia-Pacific Food Flavor Market | 2026-2036
Asia-Pacific Food Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food Flavor Market Outlook
Flavor customization services and subscription-based formulation support is consolidating around value-added technical partnerships rather than commodity supply. Givaudan leverages its regional innovation hubs to anchor bespoke savory development for processed food clients across ASEAN markets. Firmenich competes through deep specialization in natural extraction technologies, particularly for botanical and fermentation-derived profiles. Takasago International Corporation sustains manufacturing scale advantages in Japan while extending its technical service footprint into Australian and South Korean beverage applications.
Asia-Pacific food flavors comprise volatile and non-volatile compounds—esters, aldehydes, terpenes, and Maillard reaction products—typically dosed at 0.01% to 2.0% by weight to confer taste, aroma, or mouthfeel in finished goods. These formulations mask off-notes in plant proteins, extend shelf-life perception, and enable regional taste localization for multinational food brands. Natural flavor type commands premium positioning as clean label claims migrate from niche to mainstream across retail channels. Liquid form dominates high-volume beverage and dairy processing due to dispersion efficiency, though powder form grows fastest in convenience food and seasoning sachet formats where moisture stability determines logistics economics.
FSSAI in India enforces additive labeling and maximum permissible limits for synthetic flavor carriers, while China's SAMR and GB standards govern safety assessments and novel ingredient approvals with increasing stringency. Australia's FSANZ and New Zealand's parallel regime impose additional compositional transparency requirements that shape exporter formulation strategies. Stakeholders must monitor divergence between ASEAN harmonization initiatives and country-specific enforcement timelines when allocating regulatory compliance resources.
Market Dynamics
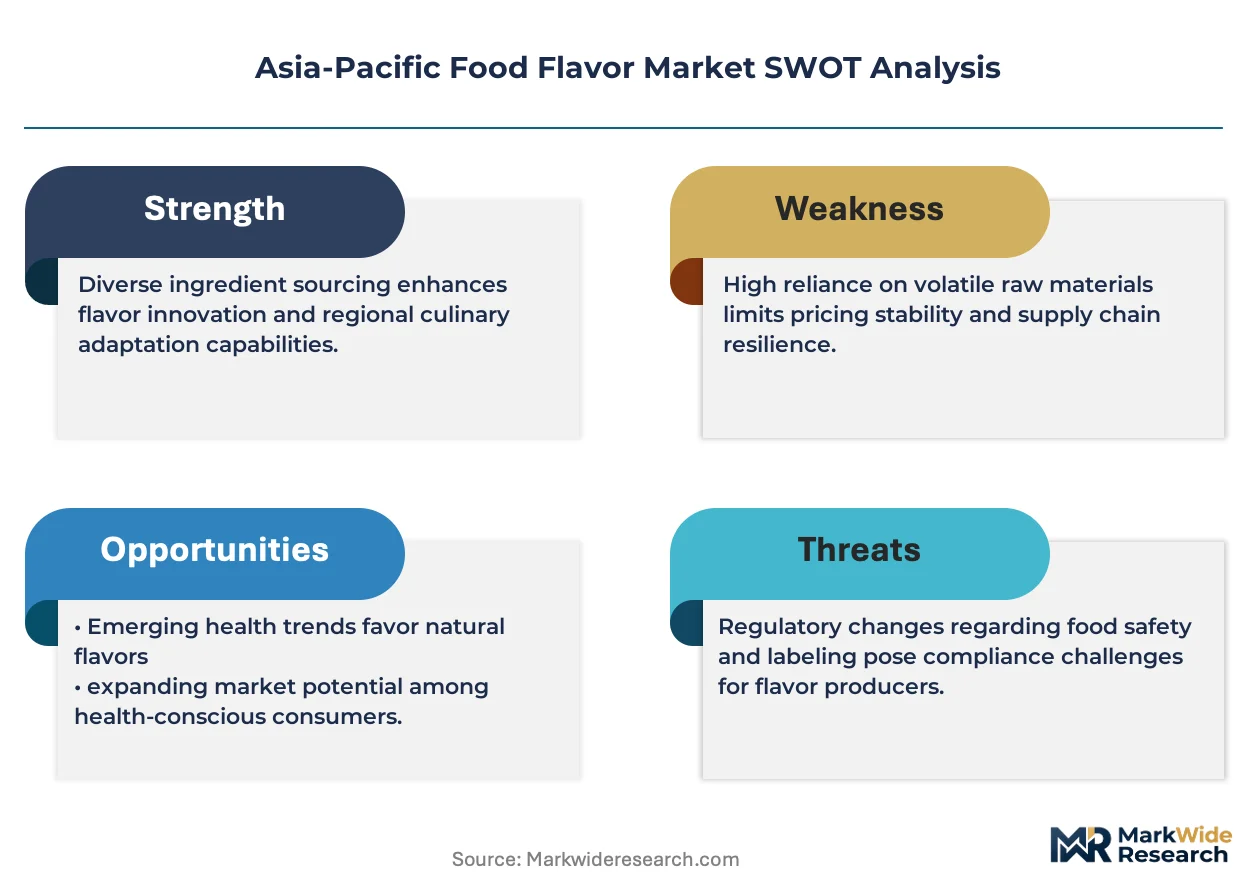
China's dual carbon goals and tightening MEE environmental standards are forcing reformulation cycles across the Asia-Pacific food flavor sector, compressing development timelines while elevating clean label requirements from niche positioning to baseline market entry.
Growth Catalysts
- Clean Label Mandates:China's SAMR and GB standards on additive transparency push manufacturers toward natural extraction methods. Reformulation services now anchor supplier-client relationships across processed food categories.
- ASEAN Snack Manufacturing:Southeast Asian instant noodle and savory snack producers absorb growing volumes of regional flavor systems. Localized taste profiles differentiate export-ready product lines.
- Dairy Application Expansion:India's FSSAI-compliant dairy sector integrates spice-derived and fruit-based flavors into traditional beverages. Regional botanical sources reduce import dependency for domestic processors.
Market Restraints
- Natural Ingredient Cost Volatility:Weather-dependent harvests of vanilla, citrus, and spice crops in Indonesia and Madagascar create input price instability. Synthetic alternatives face regulatory friction under tightening clean label regimes.
- Supply Concentration in Extraction Technology:Fermentation-derived and botanical extraction capabilities cluster in Japan and South Korea. Smaller ASEAN formulators remain dependent on imported intermediate compounds.
- Regulatory Divergence:Australia's FSANZ compositional transparency requirements differ from ASEAN harmonization timelines. Exporters maintain parallel formulation portfolios to satisfy non-aligned standards.
Strategic Opportunities
- Vietnam and Philippines Underpenetration:Emerging middle-class consumption in these markets outpaces local flavor manufacturing capacity. Technical service partnerships offer entry paths ahead of competitor facility investments.
- Plant Protein Masking Applications:Pea and soy protein off-notes in meat alternatives create demand for specialized savory masking systems. This application segment pulls formulation R&D away from traditional dairy and beverage anchors.
- India PLI Scheme Alignment:Production-linked incentives for food processing infrastructure reduce capital barriers for domestic flavor manufacturing. Regional spice supply chains integrate forward into finished flavor systems.
Industry Challenges
- Flavor Chemist Talent Scarcity:Natural extraction and fermentation process expertise concentrates in Japan and select Indian research institutes. Cross-border recruitment friction slows ASEAN facility technical staffing.
- Certification Timeline Compression:China's SAMR novel ingredient approval windows extend unpredictably. Product launch schedules absorb contingency buffers that strain working capital cycles.
- Legacy Equipment Integration:Powder form flavor production for convenience food sachets requires moisture-control retrofitting of liquid-optimized plant lines. Capital allocation debates delay format diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food Flavor Market |
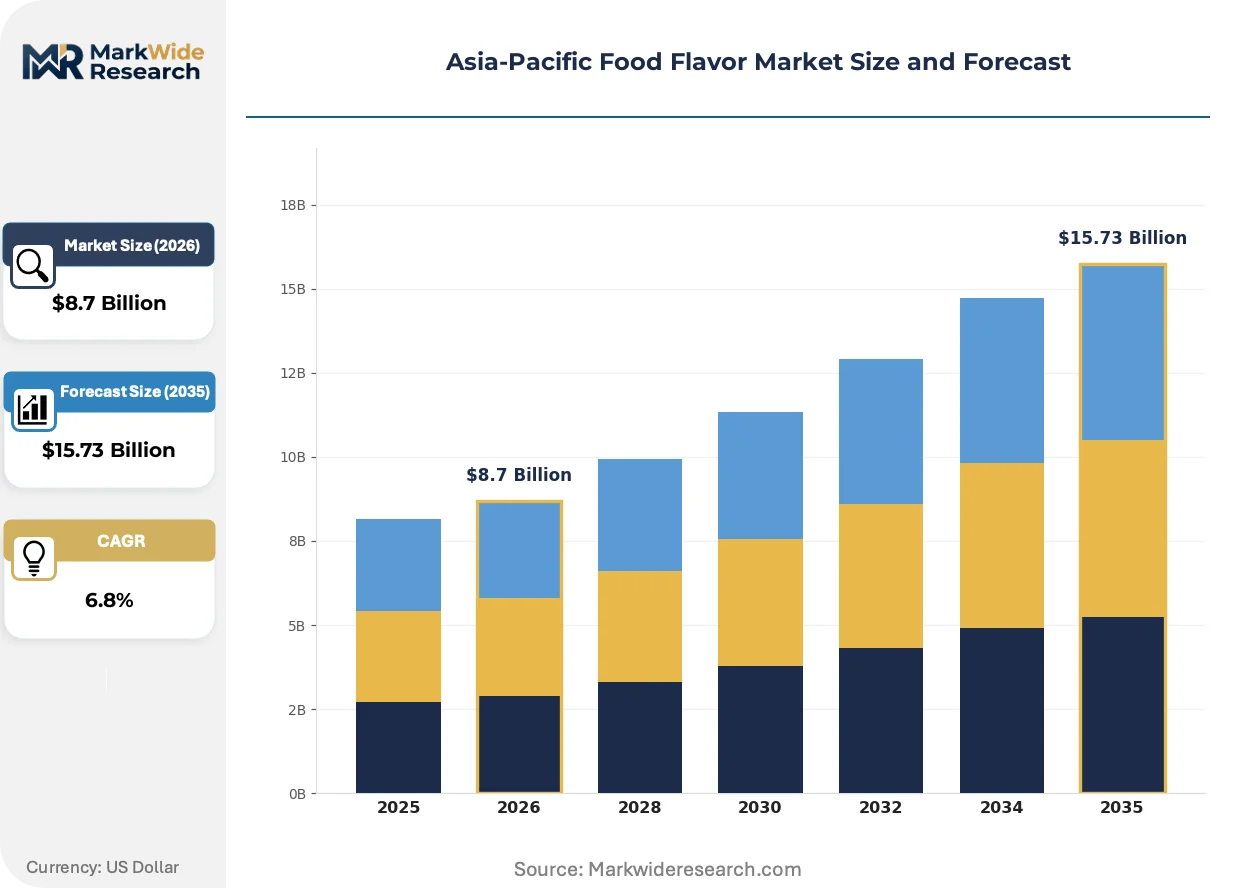
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Natural, Artificial, Organic, Clean Label Form: Liquid, Powder, Paste, Emulsion End User: Food & Beverage, Bakery, Dairy, Confectionery Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Givaudan, Firmenich, Symrise, Sensient Technologies Corporation, Kerry Group, International Flavors & Fragrances, Takasago International Corporation, Archer Daniels Midland Company, Huabao International Holdings Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food Flavor Market Strategic Shifts
Biotechnology-derived flavor compounds and precision fermentation are displacing conventional extraction methods, while regulatory fragmentation across the region forces parallel compliance architectures that reshape competitive investment priorities.
Precision fermentation for key aroma molecules is expanding into commercial-scale production of vanillin, lactones, and esters previously dependent on agricultural extraction. Japanese and South Korean biotechnology firms anchor capacity investments, with Australian beverage processors adopting these inputs ahead of ASEAN dairy manufacturers. This technology is compressing the cost differential between natural-labeled and synthetic compounds, forcing traditional botanical extractors to defend positioning through provenance storytelling rather than molecular equivalence.
China's MEE environmental compliance deadlines and dual carbon implementation timelines enforce solvent reduction mandates across flavor manufacturing facilities. Extraction process redesign toward supercritical CO2 and aqueous methods absorbs 18-24 month validation cycles. South Korean and Australian exporters to China pre-certify alternative process documentation to avoid customs detention at port of entry.
Direct technical service contracts between flavor houses and retail-ready food brands are displacing traditional distributor-mediated procurement in India and Southeast Asia. Large processed food manufacturers in Thailand and Indonesia negotiate formulation exclusivity in exchange for volume commitments. This channel shift concentrates R&D resource allocation toward anchor accounts while marginalizing mid-tier buyers from bespoke development access.
Asia-Pacific Food Flavor Market Segmentation
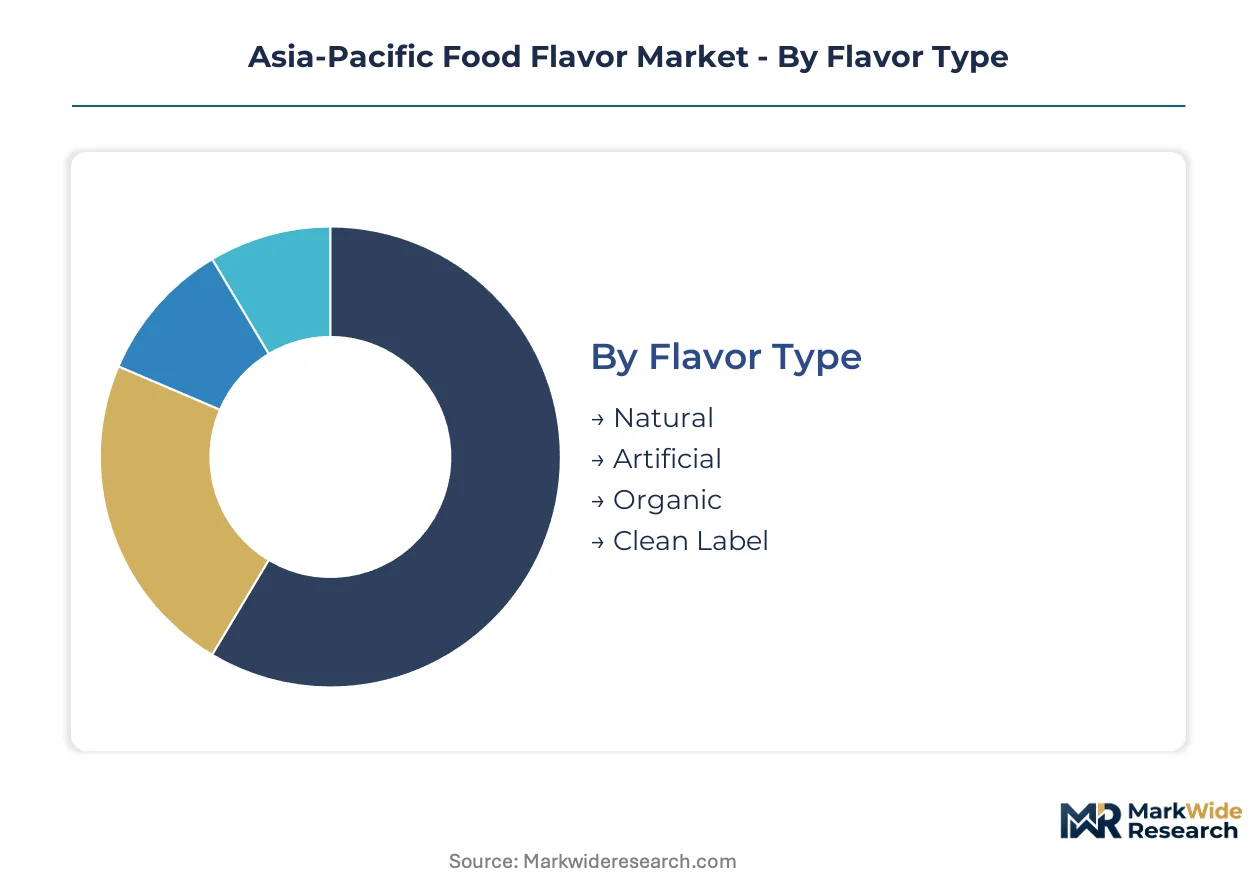
Segmentation in the Asia-Pacific food flavor market exposes where capital deployment, regulatory exposure, and technical capability cluster. Manufacturers allocate R&D budgets differently across flavor types, while form and end-use decisions determine equipment specialization and geographic sourcing strategies.
Flavor Type:
Natural extraction and fermentation infrastructure demands the heaviest upfront capital outlays, with clean label positioning requiring parallel certification investments.
- Natural:Botanical and fermentation-derived compounds require solvent recovery systems and supercritical CO2 extraction equipment. China's SAMR additive transparency mandates and MEE environmental compliance deadlines pull F&B manufacturers toward these systems, though Indonesian vanilla and Madagascar spice harvest volatility compresses margin predictability.
- Artificial:Synthetic esters, aldehydes, and terpenes offer cost stability and supply security through chemical synthesis routes. Reformulation away from these compounds accelerates under tightening FSSAI and GB standards, shrinking addressable share in premium retail channels.
- Organic:Certified organic extraction carries 30-40% input cost premiums and multi-year conversion timelines for agricultural suppliers. Australian FSANZ and New Zealand compositional transparency requirements create preferential market access for compliant systems.
- Clean Label:Consumer-facing positioning without E-number declarations depends on supplier process documentation and traceability systems. Indian dairy and traditional beverage processors absorb growing volumes as FSSAI enforcement tightens additive disclosure.
Natural absorbs the bulk of installed capacity; clean label is expanding most quickly.
Form:
Moisture stability requirements and dispersion economics determine logistics infrastructure investments and customer switching costs.
- Liquid:High-volume beverage and dairy processing favors liquid dispersion efficiency. Japanese and South Korean biotechnology firms anchor fermentation-derived liquid capacity serving ASEAN manufacturers.
- Powder:Spray-drying and encapsulation equipment for convenience food sachets and seasoning packets requires moisture-control retrofitting of liquid-optimized plant lines. India's PLI-aligned food processing infrastructure reduces capital barriers for domestic powder production.
- Paste:Concentrated flavor systems for bakery and confectionery applications offer extended shelf-life through water activity control. Thai and Indonesian processed food manufacturers negotiate formulation exclusivity for anchor paste supply contracts.
- Emulsion:Oil-in-water systems stabilize volatile aroma compounds in heat-processed applications. Australian beverage processors adopt these ahead of ASEAN dairy manufacturers seeking off-note masking in plant protein formulations.
Liquid commands the deepest installed base; powder climbs the fastest as convenience food manufacturing scales.
End User:
Application-specific formulation complexity and regulatory touchpoint density shape customer concentration and service intensity.
- Food & Beverage:Broadest application scope spanning carbonated drinks, ready-to-drink teas, and functional beverages. China's dual carbon goals force solvent reduction mandates across manufacturing facilities serving this segment.
- Bakery:Heat-stable encapsulation systems and Maillard reaction products dominate technical requirements. Vietnamese and Philippine emerging middle-class consumption outpaces local flavor manufacturing capacity.
- Dairy:India's FSSAI-compliant sector integrates spice-derived and fruit-based flavors into lassi, chaas, and flavored milk. Regional botanical sources reduce import dependency for domestic processors.
- Confectionery:Sugar reduction trends drive demand for mouthfeel modifiers and taste enhancement systems. Japanese extraction technology clusters serve premium positioning in South Korean and Australian markets.
Food & Beverage captures the largest formulation service allocation; dairy gains share fastest on India infrastructure expansion.
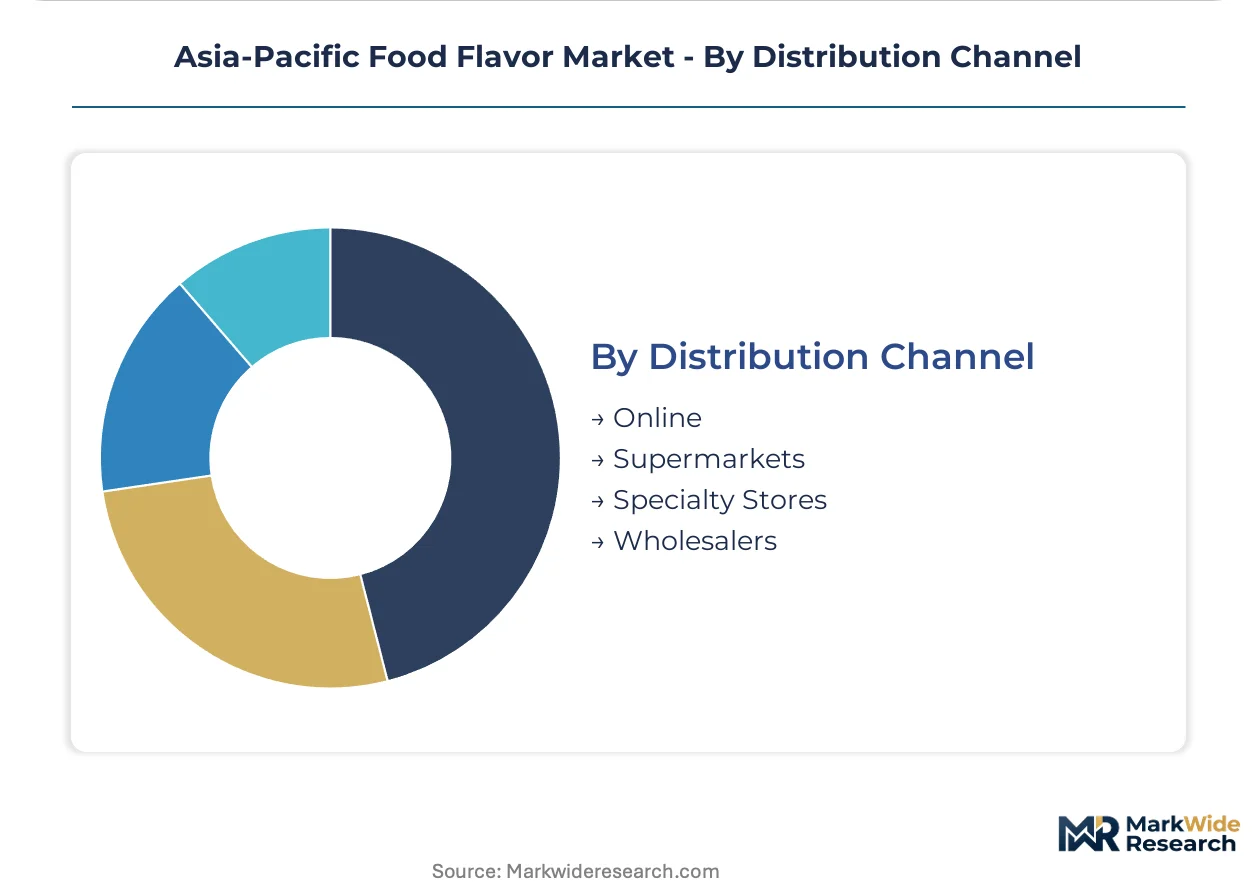
Distribution Channel:
Channel selection determines working capital cycles, technical service depth, and price transparency.
- Online:E-procurement platforms reduce search costs for mid-tier buyers excluded from direct flavor house relationships. Australian and New Zealand compositional documentation requirements favor suppliers with digitized certification libraries.
- Supermarkets:Retail-ready food brands in Thailand and Indonesia negotiate formulation exclusivity through direct technical service contracts displacing traditional distributor mediation.
- Specialty Stores:Artisan and premium positioning channels absorb small-batch natural extraction outputs with provenance storytelling. Japanese botanical extractors defend positioning against fermentation-derived alternatives through origin narratives.
- Wholesalers:Volume-driven commodity supply serves cost-sensitive instant noodle and savory snack producers across Southeast Asia. Price volatility in natural ingredients compresses wholesaler margin buffers.
Wholesalers retain the deepest volume relationships; online channels steepen their expansion trajectory on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates fermentation-derived flavor production capacity while India and Southeast Asian markets absorb the bulk of regional consumption growth. This production-consumption divide shapes supplier investment priorities and technical service deployment across the Asia-Pacific food flavor sector.
China
Dual carbon goals and MEE environmental compliance deadlines compress manufacturing timelines for solvent-based extraction facilities. SAMR's novel ingredient approval windows extend unpredictably, forcing exporters to pre-certify alternative process documentation. Yangtze River Delta biotechnology clusters anchor commercial-scale precision fermentation for vanillin and lactone production.
India
FSSAI-compliant dairy processors integrate spice-derived flavors into lassi, chaas, and traditional beverages at accelerating volumes. PLI scheme incentives for food processing infrastructure reduce capital barriers for domestic flavor manufacturing expansion. Maharashtra and Gujarat host forward-integrated operations linking regional spice supply chains to finished flavor systems.
Japan
Tokyo and Osaka metropolitan areas concentrate natural extraction and fermentation process expertise that ASEAN formulators recruit aggressively. METI-supported biotechnology investments sustain capacity leadership in precision-derived aroma molecules. Chubu region manufacturing facilities export intermediate compounds to South Korean and Australian beverage processors.
Thailand
Instant noodle and savory snack manufacturers absorb growing volumes of localized taste profiles for export-ready product lines. Direct technical service contracts displace traditional distributor mediation for large processed food brands. Bangkok-centered formulation partnerships offer entry paths ahead of competitor facility investments in Vietnamese and Philippine markets.
Australia
FSANZ compositional transparency requirements shape exporter formulation strategies for premium retail channels. Beverage processors adopt fermentation-derived inputs ahead of ASEAN dairy manufacturers seeking clean label positioning. Sydney and Melbourne clusters specialize in emulsion systems for plant protein off-note masking applications.
Asia-Pacific Food Flavor Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Asia-Pacific food flavor sector. Manufacturing scale advantages cluster in Japanese and South Korean biotechnology facilities, while formulation-centric relationships concentrate around regional innovation hubs in Singapore and Shanghai. Three archetypes dominate: integrated fermentation specialists, botanical extraction traditionalists, and technical service-forward custom houses. Competitive moves center on direct anchor account contracting and backward integration into regional spice and botanical supply chains.
Among Switzerland-based flavor houses, Givaudan and Firmenich exemplify the technical service-forward archetype through bespoke savory development and natural extraction specialization respectively. Takasago International Corporation anchors Japanese manufacturing scale advantages while extending technical service footprints into Australian and South Korean beverage applications. These three occupy positions that concentrate R&D resource allocation toward formulation exclusivity negotiations with large processed food manufacturers across ASEAN markets.
| Leading Market Players |
|---|
| Givaudan |
| Firmenich |
| Symrise |
| Sensient Technologies Corporation |
| Kerry Group |
| International Flavors & Fragrances |
| Takasago International Corporation |
| Archer Daniels Midland Company |
| Huabao International Holdings Limited |
| Others |
Value Chain & Pricing Dynamics
Indonesian vanilla futures and Madagascar spice harvest benchmarks cascade through Asia-Pacific food flavor supply chains into three-tier pricing structures across premium, standard, and economy levels. China's MEE solvent reduction mandates and SAMR certification timelines compress margin buffers for botanical extractors while fermentation-derived alternatives command stability premiums.
Pricing Analysis
Margin tightening in natural extraction tiers reflects weather-dependent harvest volatility and multi-year organic certification timelines. Three-tier pricing structure across premium, standard, and economy levels stratifies by clean label certification depth, with FSSAI-compliant systems commanding premiums over baseline GB-standard formulations. Cost-down pressure on synthetic alternatives accelerates because tightening additive transparency regimes shrink addressable retail channels. Mid-tier ASEAN snack manufacturers exhibit highest price sensitivity; Japanese beverage processors demonstrate lowest sensitivity due to fermentation-derived input adoption.
Supply Chain Analysis
Freight cost differentials between Japanese biotechnology clusters and ASEAN manufacturing hubs shape regional sourcing decisions for liquid flavor concentrates. Supply concentrates in Japan, South Korea, and China, with fermentation-derived intermediates drawing from Yangtze River Delta and Osaka metropolitan production bases. Vanilla pods from Madagascar, citrus oils from Indonesia, and spice extracts from India constitute critical raw material dependencies. Single-source vulnerability in precision fermentation capacity creates structural risk. Distribution runs through direct technical service contracts for anchor accounts and wholesaler-mediated volume supply for commodity snack producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where China's SAMR novel ingredient approval windows and MEE environmental deadlines erect barrier-to-entry moats favoring pre-certified incumbents with documented alternative process portfolios.
For Market Incumbents: Deploy backward integration into regional spice supply chains to secure input cost stability against Indonesian and Madagascar harvest volatility. Anchor formulation exclusivity contracts with Thai and Indonesian processed food manufacturers before competitor technical service investments materialize. Fermentation-derived substitutes threaten traditional botanical extractor positioning.
For New Entrants and Emerging Players: Direct technical service partnerships with Vietnamese and Philippine dairy processors offer entry paths ahead of established flavor house facility investments. White-space concentrates in plant protein masking applications for meat alternative manufacturers and FSSAI-compliant traditional beverage formulations. Prioritize subscription-based formulation support over commodity supply to differentiate from incumbent wholesaler relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation technology specialists with SAMR pre-certification documentation in China's Yangtze River Delta corridor. Long-term viability hinges on biotechnology-derived compound cost convergence with agricultural extraction. Monitor SAMR approval timeline compression as inflection signal for working capital stress among import-dependent ASEAN formulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Spice Supply | Maharashtra and Gujarat operations reduce import dependency for Indian dairy processors. |
| Precision Fermentation Capacity Expansion | Japanese biotechnology clusters anchor commercial-scale vanillin and lactone production. |
| Direct Technical Service Contracts | Bangkok-centered partnerships displace distributor mediation for ASEAN snack manufacturers. |
| SAMR Pre-Certification Investment | Alternative process documentation prevents customs detention at Chinese port of entry. |
| Plant Protein Masking R&D Allocation | Sydney and Melbourne emulsion systems address pea and soy off-notes in meat alternatives. |
Study Parameters
Trade flow databases, customs records, and FSSAI additive disclosure filings formed the secondary backbone of this analysis. Primary interviews with flavor chemists at Japanese biotechnology firms, procurement leads at Thai instant noodle manufacturers, regulatory affairs specialists navigating SAMR approval windows, and technical directors at Indian dairy processors combined with secondary validation. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
Historical trendline analysis across flavor type, form, and end-use dimensions established baseline growth trajectories over the projection horizon. Segmentation modeling captured natural versus artificial type splits, liquid versus powder form economics, and dairy versus beverage application intensity. CAGRs derived from regression-adjusted trend extrapolation incorporating PLI scheme infrastructure incentives and MEE compliance deadline impacts.
Caveats apply where SAMR approval timeline extensions, Indonesian spice harvest failures, or fermentation technology cost breakthroughs could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Feed Flavors, Sweeteners and Natural Enhancers Market
Flavorings and Food Additives
Lemon Extract Market
Flavorings and Food Additives
Global Ginger Extract Market
Flavorings and Food Additives
Cocoa Extract Market
Flavorings and Food Additives
Africa Food Colorants Market
Flavorings and Food Additives
Chicken Flavor Market
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
Food Flavors Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Natural Flavor Extract Market
Flavorings and Food Additives
Vanilla Oleoresin Market
Flavorings and Food Additives
Caralluma Extract Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Russia Food Flavor and Enhancer Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market