
 Quillaia Extracts Market | 2026-2036
Quillaia Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Quillaia Extracts Market Outlook
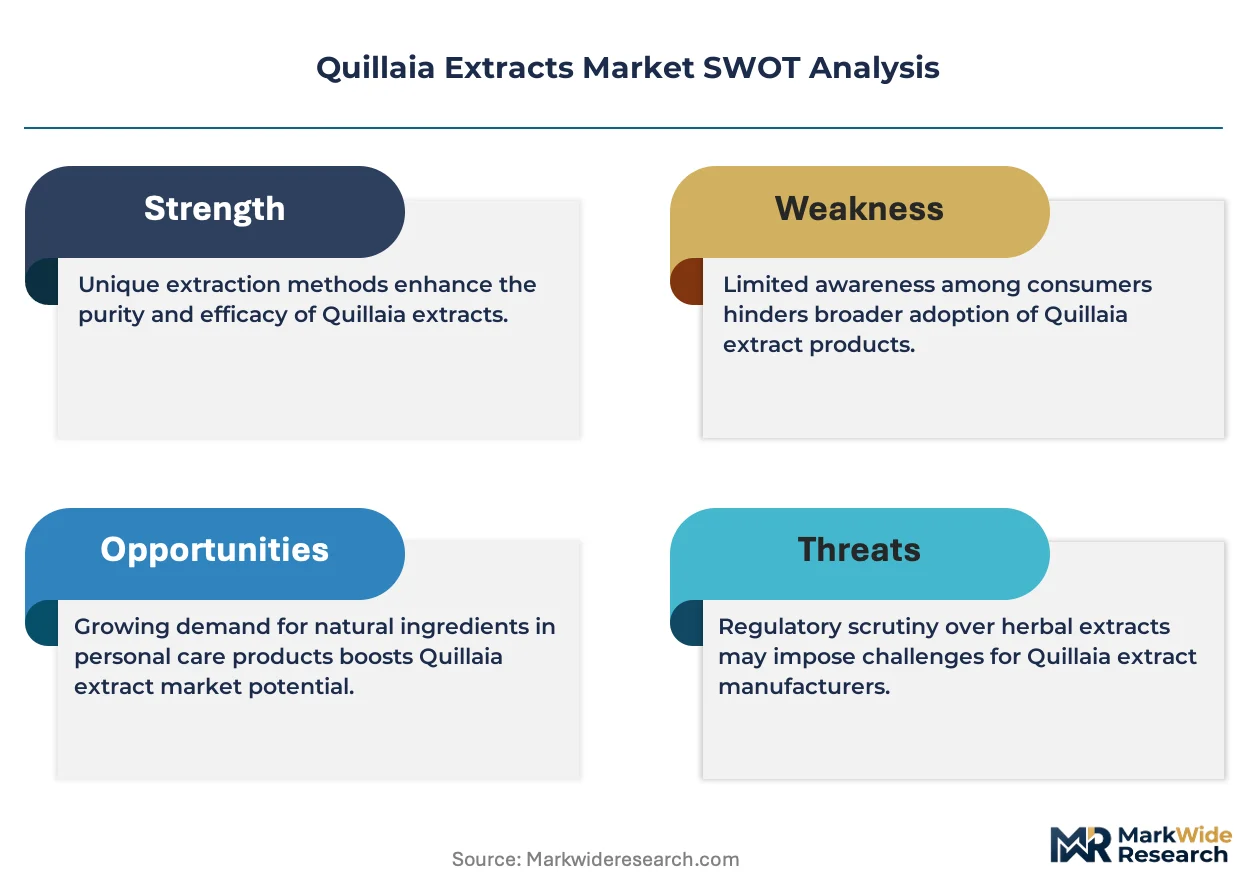
Technical-grade formulation services is consolidating around value-added extract refinement rather than commodity bark sales. Desert King International leverages vertical integration from Chilean forest concessions through extraction facilities to secure supply continuity. Givaudan SA anchors premium positioning through flavor-application laboratories that convert raw extract into beverage-ready emulsions. Ingredion Incorporated competes on manufacturing scale across multiple hydrocolloid categories including quillaia-derived foaming systems.
Quillaia extract comprises triterpenoid saponins, primarily quillaic acid glycosides, recovered through aqueous extraction of Quillaja saponaria Molina bark and standardized to 10-20% saponin content for commercial use. Its primary purpose centers on natural surfactant functionality, generating stable foam structures in carbonated beverages and emulsion stability in food systems. Liquid extract dominates volume flows due to direct dosing compatibility with beverage production lines, while powder extract captures margin pools through higher concentration and reduced logistics costs. Emulsifier applications lead pharmaceutical and cosmetics uptake where quillaia replaces synthetic polysorbates in vaccine adjuvants and topical formulations.
Chile's CONAF forestry service regulates wild harvest quotas under native forest protection statutes, while the FDA governs GRAS status for food-grade saponin levels in US-bound products. EFSA reviews novel food applications for purified quillaia extract in European markets, creating divergence in approval timelines across destination geographies. Stakeholders must monitor regulatory harmonization between Chilean sustainable harvest certification and importer-country food additive standards to anticipate supply chain reconfiguration requirements.
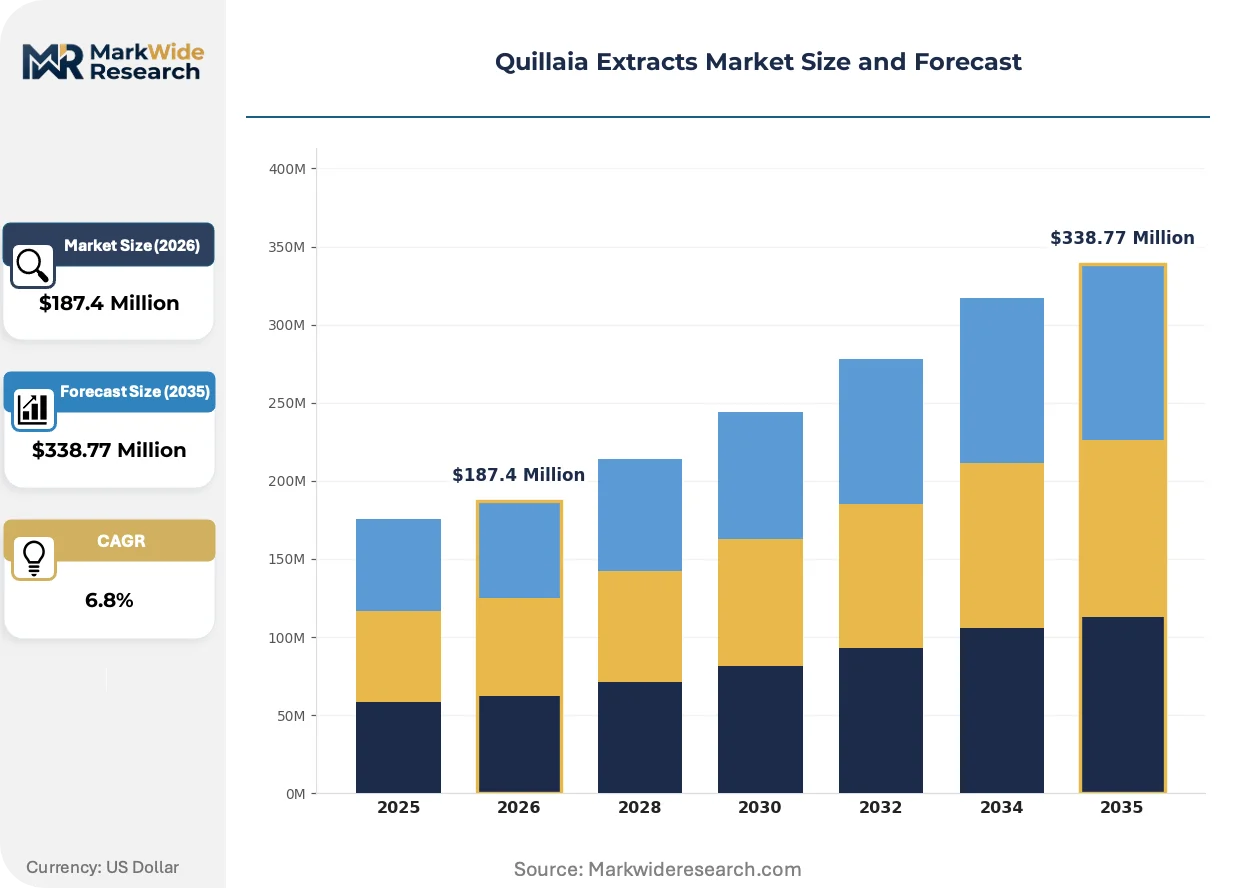
Market Dynamics
Chile's CONAF harvest quotas and FDA GRAS certification requirements are creating a bifurcated supply environment where certified extract commands structural premiums over unrefined bark. This regulatory layering favors processors with in-house laboratory capabilities and direct Chilean forest concessions.
Growth Catalysts
- Clean-label beverage mandates:US and EU formulators are substituting quillaia saponins for synthetic polysorbates in carbonated drinks. This specification pull is accelerating contract volumes with Chilean extractors holding organic certifications.
- Vaccine adjuvant qualification:Pharmaceutical manufacturers are validating quillaia-derived QS-21 alternatives in mRNA booster formulations. EMA's accelerated assessment pathway for novel adjuvant substances is compressing approval timelines for qualified suppliers.
- Araucanía extraction cluster:Concentrated wild quillay populations in Chile's southern zone enable integrated harvesting-to-extraction operations. Proximity between forest concessions and processing facilities reduces bark degradation during transport.
Market Restraints
- Raw bark input volatility:Wild harvest quotas under Chile's Native Forest Law constrain annual bark availability. CONAF's conservative yield estimates limit expansion beyond existing concession boundaries.
- Geographic supply concentration:Over 80% of commercial extraction occurs within 200 kilometers of Temuco. Climate stress and fire risk in the Araucanía Region threaten multi-year inventory planning.
- Technical standardization gaps:No harmonized ISO method exists for saponin content verification. Divergent analytical protocols between Chilean exporters and US/EU importers create batch rejection risk at port.
Strategic Opportunities
- Underpenetrated cosmetics vertical:Korean and Japanese skincare formulators are testing quillaia emulsifiers in clean beauty lines. MFDS and PMDA cosmetic ingredient pre-approvals would unlock Northeast Asian contract manufacturing demand.
- Cultivation-to-extraction transition:Chilean research stations are piloting quillay plantation establishment. Domestication programs could reduce wild harvest dependency while satisfying FSC chain-of-custody requirements for European buyers.
- Carbonated functional drinks:Adaptogenic beverage startups in California and Colorado are specifying foam-stable natural extracts for CBD and nootropic formulations. This application expansion sits outside traditional beer and soft drink procurement channels.
Industry Challenges
- Phytochemical analytical talent scarcity:Specialized HPLC-ELSD technicians capable of triterpenoid saponin quantification are concentrated in Santiago and Valparaíso. Regional extraction facilities face recruitment competition from pharmaceutical QC labs.
- Dual certification timeline compression:Simultaneous pursuit of USDA Organic and EU Organic logos requires parallel audits by Chile's SAG and accredited EU control bodies. Documentation burden extends commercialization timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quillaia Extracts Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder Extract, Tablet Form, Granules End Use Industry: Beverage, Food, Cosmetics, Pharmaceuticals Application: Emulsifier, Foaming Agent, Flavoring Agent, Stabilizer Packaging Type: Bulk Packaging, Retail Packaging, Tetra Pak, Glass Containers |
| Companies Covered | Desert King International, Quillaja Green Biosolutions, Garuda International, Inc., Chile Botanics S.A., Givaudan SA, Ingredion Incorporated, Baja Yucca Company, Nexira SAS, Naturex SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quillaia Extracts Market Strategic Shifts
Supercritical CO2 extraction and membrane filtration are displacing conventional aqueous boiling methods, yielding higher-purity saponin fractions with reduced solvent residues. This processing shift is reshaping capital deployment patterns among mid-scale processors.
Membrane filtration technology is consolidating around ceramic microfiltration systems for saponin concentration and polyphenol removal. German and Italian equipment suppliers are installing skid-mounted units at Chilean extraction sites. Beverage-grade extract specifications are tightening as a result, compressing margins for processors relying on legacy evaporation equipment.
EFSA's ongoing novel food assessment for purified quillaia extract is creating regulatory divergence with FDA's established GRAS notification pathway. European formulators face formulation freeze periods pending EFSA opinion publication. This timeline asymmetry is redirecting near-term R&D investment toward US-market product launches rather than simultaneous transatlantic registration.
Long-term supply agreements are replacing spot market bark purchases among major extract consumers. Procurement departments at multinational flavor houses now require 36-month visibility into Chilean concession harvest projections. This contract structuring is visible most acutely in California-based beverage brand supply chains, where sustainability audit requirements mandate documented chain-of-custody from specific Araucanía harvest zones.
Quillaia Extracts Market Segmentation
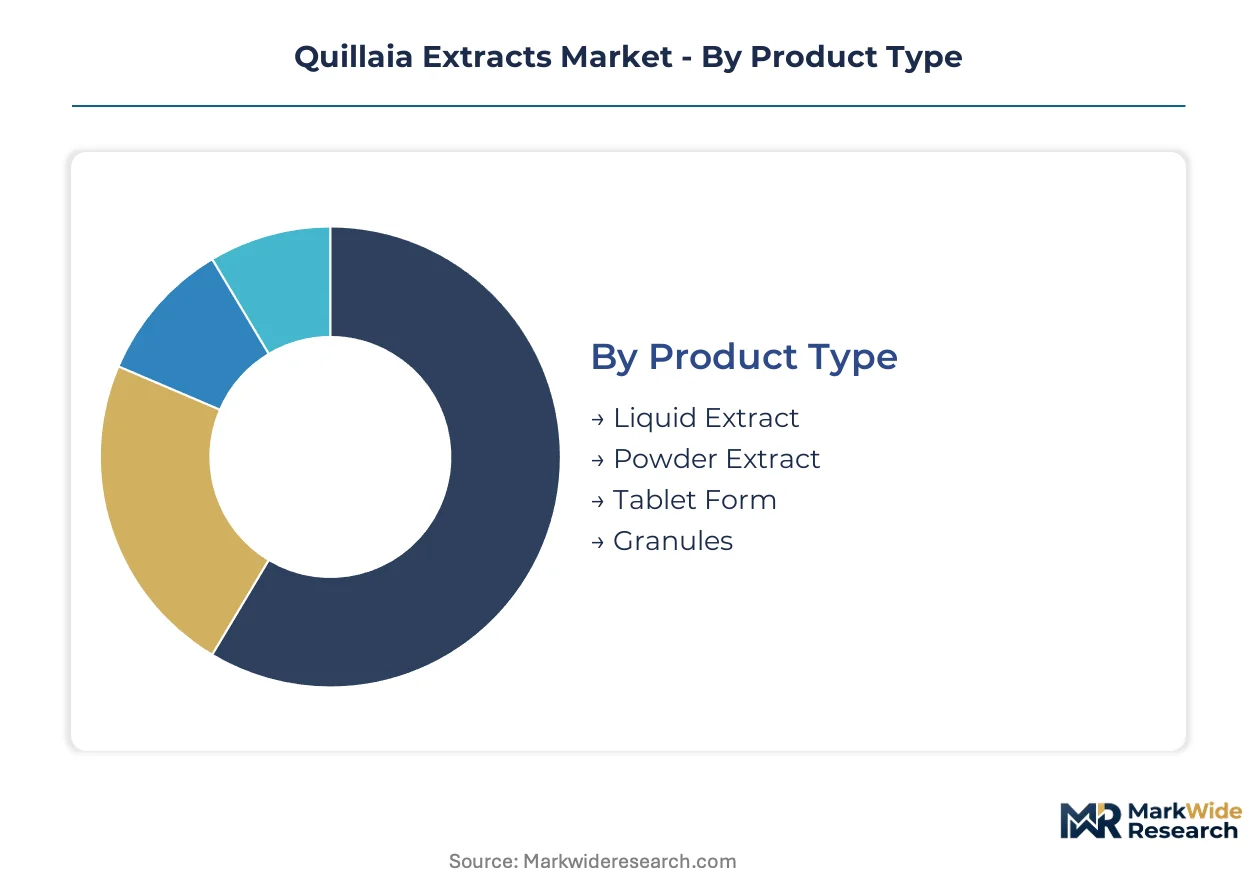
Quillaia extract specifications diverge sharply across downstream applications, with pharmaceutical-grade saponin fractions commanding distinct certification requirements from beverage-grade emulsions. Procurement teams segment supplier qualifications by end-use regulatory burden rather than extract concentration alone.
Product Type:
FDA GRAS notification applies to liquid and powder extracts for food use, while pharmaceutical tablet forms require USP-NF monograph compliance and EMA certification for European distribution.
- Liquid Extract:Aqueous solutions standardized to 10-20% saponin content enable direct-line dosing in carbonated beverage production. Beverage manufacturers in California and Colorado specify liquid formats for craft beer and functional drink foam stability, though refrigerated transport from Chilean extraction facilities adds logistics complexity.
- Powder Extract:Spray-dried concentrates achieve 50-80% saponin purity with reduced moisture activity for extended shelf life. Powder formats dominate pharmaceutical procurement for vaccine adjuvant formulation, where precise mass dosing supersedes liquid handling convenience.
- Tablet Form:Compressed excipient matrices target nutraceutical channels with standardized quillaia saponin dosing.
- Granules:Intermediate agglomerated particles bridge powder handling efficiency with liquid reconstitution flexibility.
Leading the category by volume: Liquid Extract. Growing fastest: Powder Extract.
End Use Industry:
Cost stratification separates commodity beverage contracts from premium pharmaceutical supply agreements, with cosmetics emerging as a mid-tier value pool.
- Beverage:Carbonated soft drink and craft beer manufacturers drive baseline demand for foam-positive natural surfactants. Clean-label procurement mandates from US and EU brand owners are consolidating supplier relationships around Chilean extractors holding dual organic certifications.
- Pharmaceutical:QS-21 adjuvant applications and synthetic polysorbate replacement in mRNA formulations attract development-stage investment. EMA's accelerated assessment pathway compresses approval timelines for qualified suppliers targeting European vaccine manufacturing.
- Food:Emulsifier applications in baked goods and confectionery require lower saponin concentrations than pharmaceutical grades.
- Cosmetics:Korean and Japanese skincare formulators test quillaia emulsifiers in clean beauty lines pending MFDS and PMDA cosmetic ingredient pre-approvals.
Highest margin concentration: Pharmaceutical. Expanding most quickly: Cosmetics.
Application:
Functional performance requirements dictate extract refinement intensity, with emulsifier specifications demanding tighter saponin homogeneity than foaming applications.
- Foaming Agent:Natural surfactant properties generate stable foam structures in carbonated beverages through triterpenoid saponin interface activity. Craft brewers specify Chilean-sourced quillaia for persistent head retention without synthetic additive labeling.
- Emulsifier:Oil-water stabilization in vaccine adjuvants and topical formulations replaces synthetic polysorbates. Pharmaceutical manufacturers validate quillaia-derived alternatives under FDA CBER guidance for novel adjuvant substances.
- Flavoring Agent:Bitter taste modulation applications leverage quillaia's inherent sensory profile at sub-foaming concentrations.
- Stabilizer:Viscosity modification in food systems employs lower-purity extract fractions.
Dominant application by volume: Foaming Agent. Steepest expansion trajectory: Emulsifier.
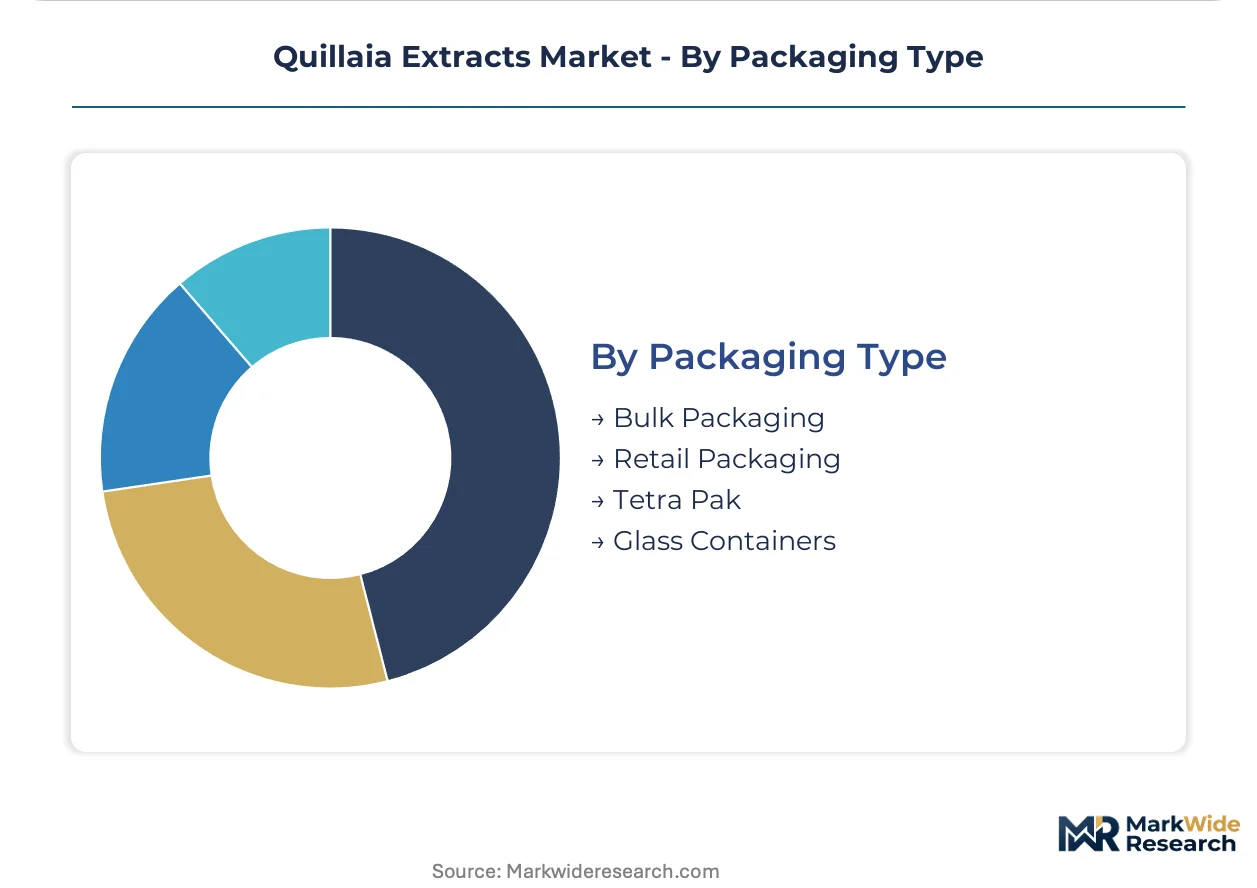
Packaging Type:
Supply chain configuration separates industrial-scale bulk logistics from retail-channel unit economics, with aseptic formats capturing pharmaceutical and premium beverage segments.
- Bulk Packaging:Drum and intermediate bulk container formats serve high-volume beverage and food manufacturing with minimized per-unit packaging cost. California-based procurement departments require 36-month visibility into Chilean concession harvest projections for bulk contract structuring.
- Tetra Pak:Aseptic carton systems enable extended shelf life for liquid extract distribution to remote processing facilities. European beverage co-packers specify Tetra Pak for quillaia emulsion pre-mixes requiring ambient storage stability.
- Retail Packaging:Consumer-facing unit doses target nutraceutical and specialty food channels.
- Glass Containers:Inert barrier properties protect high-value pharmaceutical extracts from oxidation and moisture ingress.
Primary volume channel: Bulk Packaging. Gaining share fastest: Tetra Pak.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Temuco anchors global quillaia extract supply, with Chile's Araucanía Region hosting over 80 percent of commercial extraction capacity within 200 kilometers of this southern Chilean city.
Chile
Wild quillay bark harvest quotas under CONAF's Native Forest Law constrain annual raw material availability. The Araucanía Region concentrates integrated harvesting-to-extraction operations where Desert King International and Chile Botanics S.A. maintain captive forest concessions. Temuco-based processing facilities reduce bark degradation through minimal transport distances.
United States
California craft brewers and Colorado functional beverage startups drive specification demand for foam-stable natural extracts. FDA GRAS notification requirements for food-grade saponin levels govern import compliance. Procurement departments at multinational flavor houses now require 36-month visibility into Chilean concession harvest projections for contract structuring.
Germany
Membrane filtration equipment suppliers from Germany install ceramic microfiltration systems at Chilean extraction sites to upgrade saponin concentration capabilities. REACH compliance obligations for imported botanical extracts create documentation burdens for German distributors. Hamburg serves as the primary European entry point for bulk liquid extract shipments.
France
Nexira SAS and Naturex SA maintain extraction and formulation operations targeting pharmaceutical and cosmetics applications. ANSM oversight applies to vaccine adjuvant substances incorporating quillaia-derived saponins. Lyon-based flavor laboratories convert raw extract into beverage-ready emulsions for European brand owners.
South Korea
Seoul skincare formulators test quillaia emulsifiers in clean beauty product lines pending MFDS cosmetic ingredient pre-approvals. Import demand concentrates on high-purity powder extracts for topical formulation stability. Busan port logistics handle Northeast Asian distribution for Chilean-sourced material.
Quillaia Extracts Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the quillaia extract value chain. The market structure separates vertically integrated Chilean forest concession holders from specialized extraction technology licensors and multinational flavor houses. Three archetypes dominate: captive supply operators controlling bark-to-extract pipelines, equipment-integrated processors deploying membrane filtration upgrades, and application-focused formulators converting raw saponins into end-use emulsions. Competitive moves concentrate on backward integration into Chilean forest concessions and technology licensing partnerships for supercritical CO2 extraction methods.
Among Chilean-based operators, Desert King International exemplifies the captive supply archetype through forest concession holdings, while Chile Botanics S.A. occupies a position within the regional extraction tier. Givaudan SA represents the application-focused formulator group, converting raw extract into beverage-ready systems without direct bark sourcing exposure.
| Leading Market Players |
|---|
| Desert King International |
| Quillaja Green Biosolutions |
| Garuda International, Inc. |
| Chile Botanics S.A. |
| Givaudan SA |
| Ingredion Incorporated |
| Baja Yucca Company |
| Nexira SAS |
| Naturex SA |
| Others |
Value Chain & Pricing Dynamics
Chile's Native Forest Law harvest quotas gate qualified supply access and premium-tier pricing power for compliant extractors. CONAF-certified concessions command structural premiums over unverified bark sources, while FDA GRAS notification requirements add regulatory layering that favors processors with in-house laboratory capabilities.
Pricing Analysis
Yield-linked pricing anchors contract structures, with beverage-grade liquid extract premiums tied to foam stability performance metrics and pharmaceutical-grade powder extract pricing indexed to QS-21 adjuvant purity thresholds. Three-tier pricing structure across premium, standard, and economy levels separates FSC chain-of-custody certified extract from conventional organic grades and uncertified commodity bark. Cost compression in standard-tier liquid extract is intensifying because membrane filtration technology upgrades at Chilean processing sites are expanding higher-purity supply. Craft beverage manufacturers in California demonstrate highest price sensitivity due to thin margin structures, while pharmaceutical adjuvant developers show lowest sensitivity given qualification switching costs.
Supply Chain Analysis
Refrigerated ocean freight from Valparaíso to Los Angeles and Hamburg adds 12-18% landed cost premiums for liquid extract formats versus powder alternatives. Supply concentrates in Chile's Araucanía Region, with secondary processing nodes in France and secondary distribution hubs in Germany and the United States. Wild quillay bark, aqueous extraction solvents, and spray-drying energy inputs constitute the core input dependencies. Single-source vulnerability runs through Temuco-based integrated operations where climate stress and fire risk threaten multi-year inventory planning. Distribution runs through long-term offtake contracts with 36-month visibility requirements replacing spot market purchases among multinational flavor houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quillaia extract procurement operates as a cost-of-compliance story where Chile's CONAF harvest quotas and dual organic certification requirements erect barrier-to-entry moats favoring incumbent processors with captive forest concessions.
For Market Incumbents: Deepen backward integration into additional Araucanía forest concessions to secure raw bark access ahead of quota tightening. Invest in supercritical CO2 extraction capacity to defend margin position against membrane filtration technology licensors. Prioritize simultaneous USDA Organic and EU Organic certification maintenance to sustain premium-tier pricing access against emerging Chilean competitors.
For New Entrants and Emerging Players: Korean cosmetic ingredient distributors offer the most penetrable channel partnership pathway given pending MFDS pre-approval demand for clean beauty emulsifiers. Target white-space opportunities in Colorado adaptogenic beverage formulations and Japanese topical skincare applications. Pursue toll manufacturing arrangements with established Chilean extractors to bypass concession ownership barriers while building formulation expertise.
For Investors and Strategic Acquirers: EMA accelerated assessment pathway approvals for novel quillaia-derived vaccine adjuvants are the leading indicator that pharmaceutical-grade extraction capacity will command scarcity premiums. Position acquisition screening around mid-scale Chilean processors with existing CONAF concessions and installed membrane filtration infrastructure. Monitor EFSA novel food opinion publication timelines as the critical signal for European market entry viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forest Concessions | Captive quillay bark supply secures CONAF quota allocation priority against competing processors. |
| Membrane Filtration Technology Licensing | German and Italian equipment partnerships upgrade saponin concentration capabilities at Chilean extraction sites. |
| Dual Organic Certification Investment | Parallel USDA Organic and EU Organic audits satisfy California procurement department sustainability mandates. |
| Pharmaceutical Adjuvant Qualification | FDA CBER guidance compliance opens mRNA booster formulation contracts with vaccine manufacturers. |
| Long-term Supply Agreement Structuring | 36-month visibility contracts with beverage brand owners reduce spot market price volatility exposure. |
Study Parameters
Multi-period observation of CONAF harvest quota allocations, FDA GRAS notification filings, and EFSA novel food assessment timelines anchored the trend analysis, supplemented by interviews with Chilean forest concession operators, extraction facility technical directors, California beverage procurement managers, and European flavor house formulation chemists. Secondary validation drew from Chile's CONAF native forest statistics, US FDA GRAS notice inventory, EFSA scientific opinions, and customs trade flow records. Bottom-up segment sizing triangulated against top-down industry value chain estimates.
Segment-weighting across product type, end-use industry, application, and packaging format dimensions structured the analytical framework over the projection horizon. CAGRs were derived from regression analysis of historical volume flows and elasticity-adjusted demand projections. Forecast inputs incorporated CONAF quota trajectory assumptions, EMA adjuvant approval pathway timelines, and membrane filtration technology adoption curves at Chilean processing facilities.
Caveats apply where CONAF quota reductions, EFSA adverse opinions, or Araucanía climate events could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization progress and certification audit throughput capacity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Savory Extract Market
Flavorings and Food Additives
Original and Flavored Syrup Market
Flavorings and Food Additives
Valencene Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Royal Jelly Extract Market
Flavorings and Food Additives
China Food Colorants Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Hops Essential Oil Market
Flavorings and Food Additives
Smoke Flavorings Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Global Natural Food Colorants Market
Flavorings and Food Additives
FTNF Flavors Market
Flavorings and Food Additives
Dairy Flavors Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Poria Cocos Extract Market
Flavorings and Food Additives
De Oiled Lecithin Market