
 Tangerine Extract Market | 2026-2036
Tangerine Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Tangerine Extract Market Analytics
Flavor-as-a-service contracting is expanding as beverage and nutraceutical buyers shift from spot purchasing to multi-year supply agreements with embedded technical support. Symrise AG leverages its integrated citrus processing network to anchor long-term contracts with European bottlers. Givaudan competes through specialized extraction technology that sustains terpene profile consistency across harvest seasons. NOW Foods Inc differentiates via direct-to-manufacturer channels that control quality verification from orchard to final concentrate.
Tangerine extract comprises volatile oils, flavonoids, and limonene derived from Citrus reticulata peel through cold-press or solvent extraction, yielding standardized concentrations between 5:1 and 10:1 for industrial flavoring and fragrance applications. Organic and oil formats command premium positioning as cosmetic and pharmaceutical buyers prioritize solvent-free certification and traceable peel sourcing. Powder and conventional grades occupy volume-driven segments where food manufacturers prioritize cost stability over extraction method provenance.
EFSA purity standards, USDA organic certification requirements, and REACH chemical safety registrations collectively determine which extract suppliers gain formulation access in regulated end-use categories. FDA GRAS self-affirmation pathways and FSSC 22000 food safety certifications further segment market access between established processors and emerging entrants. Stakeholders must monitor evolving pesticide maximum residue limits in key citrus-growing jurisdictions to preempt supply disqualification risks.
Market Dynamics
Clean-label mandates from EFSA are compressing formulation timelines for European beverage manufacturers, forcing rapid substitution of synthetic flavoring with verified natural tangerine extract. This regulatory pressure is consolidating procurement around certified Italian and Spanish processing clusters that can document peel-to-concentrate traceability.
Growth Catalysts
- REACH chemical safety registrations:ECHA compliance requirements favor established extractors with toxicology dossiers, creating asymmetric access for certified suppliers versus unregistered competitors.
- Cold-press extraction technology:Solvent-free methods satisfy cosmetic and pharmaceutical buyer specifications for volatile oil integrity, expanding addressable market beyond food applications.
- Beverage formulator consolidation:Multi-brand bottlers in Germany and France are centralizing flavor procurement under single technical service contracts with embedded quality verification.
Market Restraints
- Citrus peel input volatility:Weather-driven yield fluctuations in Sicily and Valencia concentrate regions transmit directly to extract pricing, compressing processor margins.
- Substitution by synthetic limonene:Petrochemical-derived alternatives at 40-60% cost discount capture volume-driven segments where certification premiums are unrecoverable.
- EFSA maximum residue limits:Pesticide threshold tightening for processed citrus products disqualifies peel sourced from non-EU orchards lacking integrated pest management documentation.
Strategic Opportunities
- Pharmaceutical API applications:Flavonoid standardization for anti-inflammatory formulations opens higher-margin segments beyond commodity flavoring.
- Direct-to-manufacturer digital channels:Quality-verified extractors bypass distributor markups by serving mid-size cosmetic compounders through specialized e-procurement platforms.
- EU Green Deal bioeconomy incentives:Circular processing of peel waste into multiple extract fractions qualifies for green transition financing, reducing effective production costs.
Industry Challenges
- FSSC 22000 certification timelines:12-18 month audit cycles delay market entry for emerging processors, freezing competitive dynamics among incumbent suppliers.
- Terpenoid profile standardization:Harvest-to-harvest variation in volatile oil composition requires costly blending operations to meet customer specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tangerine Extract Market |
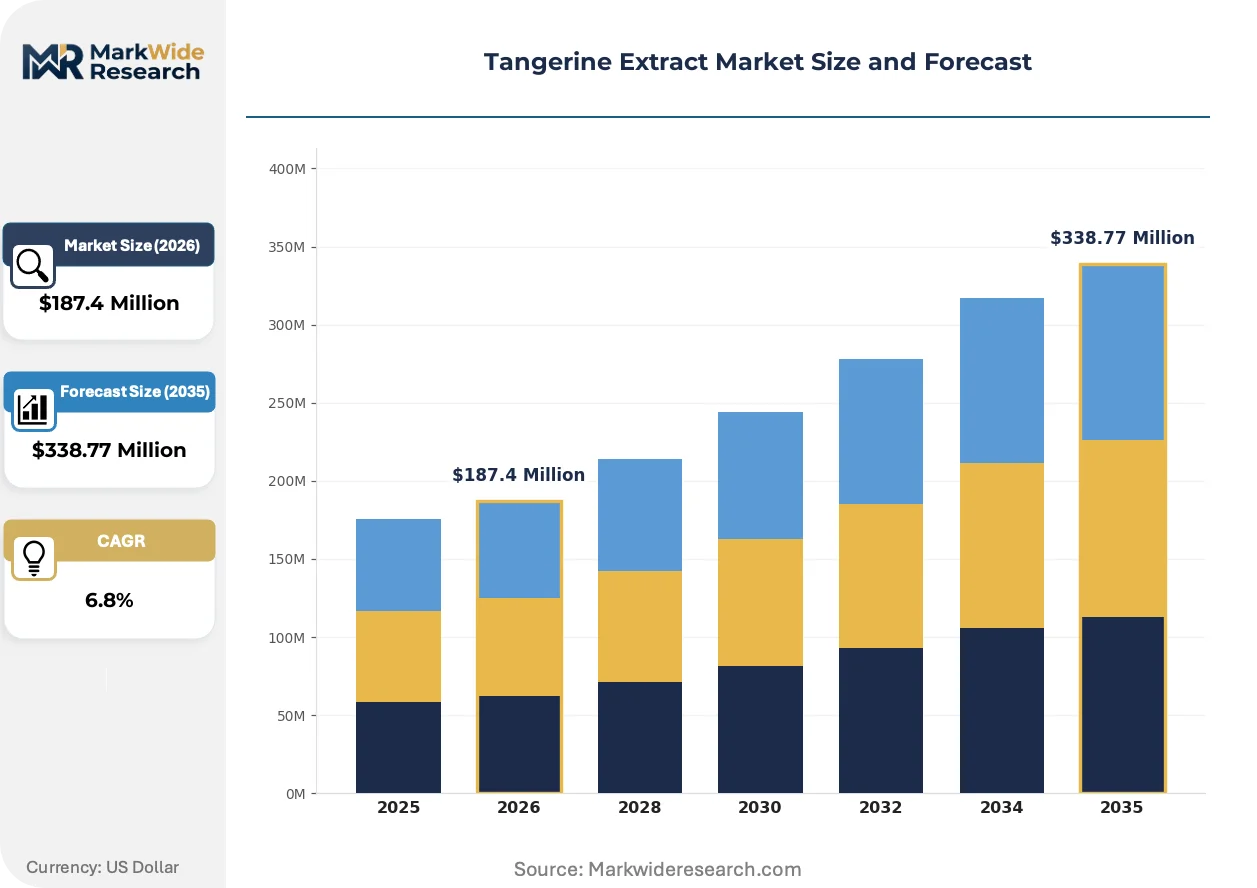
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Powder, Oil Application: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals End User: Food Manufacturers, Cosmetic Companies, Health Supplement Firms, Research Institutions Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores |
| Companies Covered | Young Living Essential Oils, NOW Foods Inc, Bluegrass Dairy & Food, Lionel Hitchen Ltd, Symrise AG, Givaudan, doTERRA International, Kanegrade, Vita-Pakt Citrus Products Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tangerine Extract Market Evolving Landscape
Supercritical CO2 extraction systems are replacing traditional solvent methods across European processing facilities, driven by pharmaceutical and cosmetic buyer requirements for residue-free certification. This equipment transition is compressing the technical gap between artisanal and industrial production scales.
Supercritical CO2 extraction technology is consolidating quality differentiation in the premium extract segment. Pharmaceutical compounders in Switzerland and Germany specify CO2-derived concentrates for topical formulations requiring zero solvent residue. The technology is consolidating supplier tiers by raising capital barriers to precision terpene recovery.
EFSA's evolving purity standards for natural flavoring additives are forcing reformulation of legacy beverage products. Processors must now document peel provenance through orchard-level traceability systems to maintain formulation approvals. Ready-to-drink tea and functional water categories face the steepest compliance reconfiguration costs.
Flavor-as-a-service contracting is displacing spot purchasing among mid-size European bottlers. Technical support embedded in multi-year supply agreements includes sensory profiling and stability testing that buyers previously sourced separately. German and Austrian private-label manufacturers show the fastest adoption velocity for this bundled procurement model.
Tangerine Extract Market Segmentation
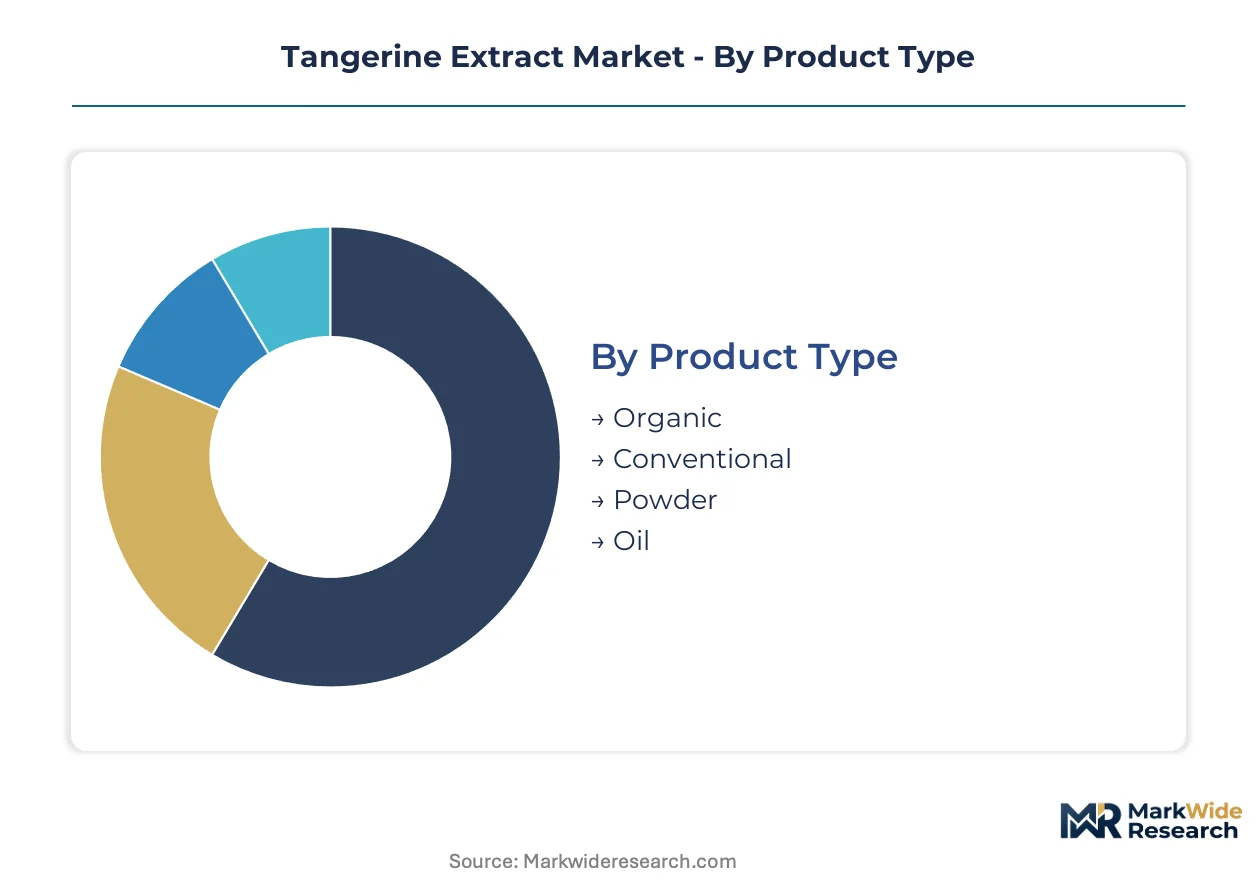
Segmentation in the tangerine extract market reflects divergent buyer priorities across certification requirements, extraction methods, and end-use specifications. Understanding these divisions enables suppliers to align production investments with margin profiles and regulatory access tiers.
Product Type:
Cold-press and solvent extraction technologies create distinct quality tiers that map directly to buyer willingness to pay for residue-free certification.
- Organic:Peel sourced from certified orchards under integrated pest management protocols. EFSA maximum residue limits and USDA organic certification requirements concentrate demand among European beverage formulators and Swiss pharmaceutical compounders seeking formulation access in regulated categories.
- Oil:Volatile oil concentrates standardized between 5:1 and 10:1 ratios through cold-press extraction. Cosmetic manufacturers in Germany and fragrance houses in France prioritize this format for terpene profile consistency in topical formulations.
- Powder:Spray-dried concentrates serving volume-driven food manufacturing segments where cost stability outweighs extraction method provenance.
- Conventional:Solvent-extracted grades capturing price-sensitive applications with less stringent certification requirements.
Mature deployment sits with Conventional grades. Newer deployment is concentrated in Organic formats.
Application:
End-use specifications create divergent margin profiles based on purity thresholds and documentation requirements.
- Food & Beverage:Clean-label mandates from EFSA are compressing formulation timelines for natural flavoring substitution. Italian and Spanish bottlers centralize procurement under multi-year technical service contracts with embedded quality verification.
- Pharmaceuticals:Flavonoid standardization for anti-inflammatory formulations demands REACH chemical safety registrations and toxicology dossiers that favor established extractors with ECHA compliance.
- Cosmetics:Supercritical CO2 extraction requirements from Swiss and German compounders drive residue-free certification premiums.
- Nutraceuticals:Health supplement firms source through direct-to-manufacturer channels controlling orchard-to-concentrate traceability.
Volume concentration remains in Food & Beverage. Steepest expansion trajectory is occurring in Pharmaceuticals.
End User:
Customer scale and technical capability determine procurement channel selection and contract structure preferences.
- Food Manufacturers:Multi-brand bottlers in Germany and France leverage consolidated flavor procurement under flavor-as-a-service contracting models with embedded sensory profiling.
- Cosmetic Companies:Mid-size compounders in Austria and Switzerland adopt specialized e-procurement platforms to bypass distributor markups.
- Health Supplement Firms:Direct sourcing from certified Italian and Spanish processing clusters anchors supply security.
- Research Institutions:Small-batch requirements for bioactivity studies prioritize documented terpenoid profiles over volume pricing.
Contract standardization is most advanced with Food Manufacturers. Procurement innovation is concentrated among Cosmetic Companies.
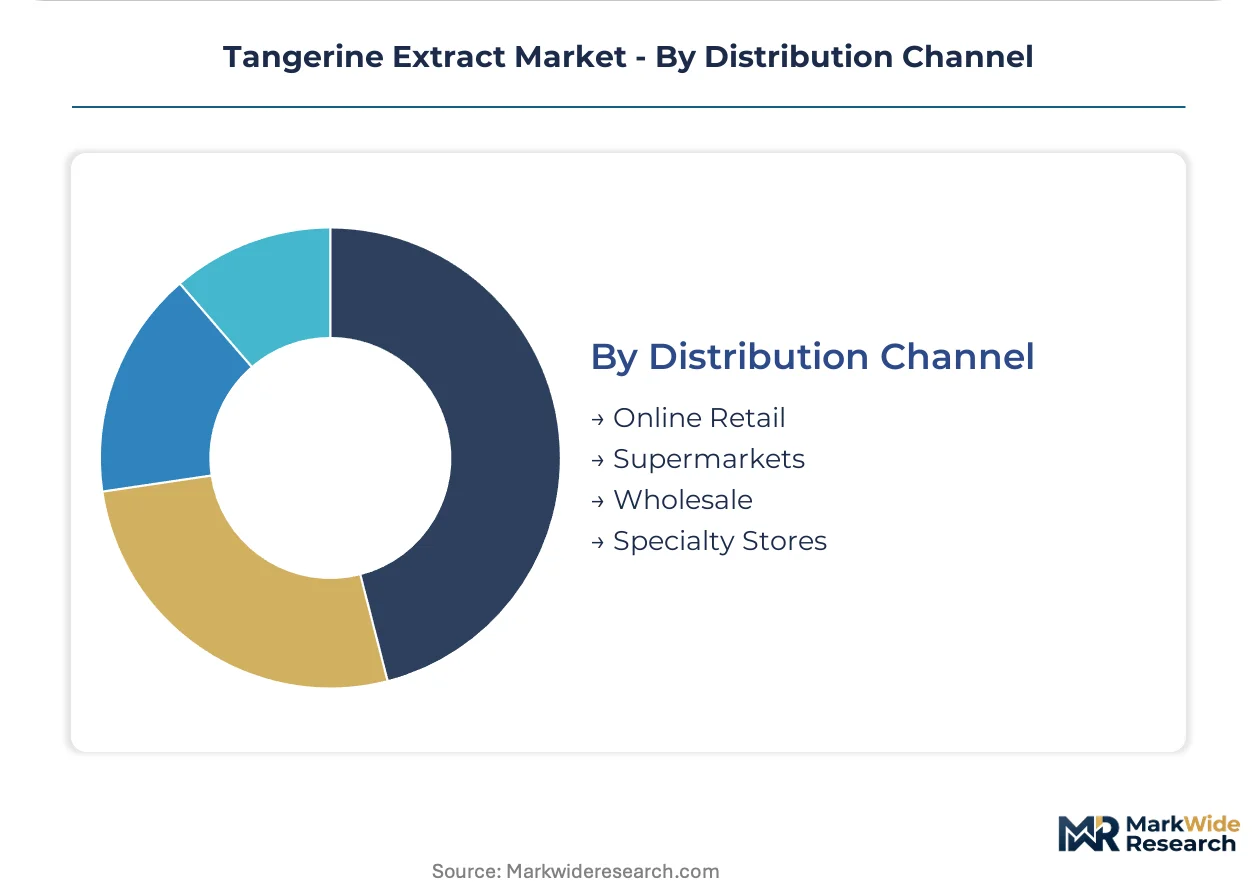
Distribution Channel:
Channel selection reflects buyer scale, urgency requirements, and quality verification needs.
- Wholesale:Volume procurement by major beverage formulators leverages long-term supply agreements with technical support embedded.
- Online Retail:Digital platforms enable mid-size cosmetic compounders to access quality-verified extractors without distributor intermediation.
- Specialty Stores:Artisanal extractors serving research institutions and small-batch nutraceutical producers.
- Supermarkets:Limited penetration given industrial concentration of extract demand.
Established volume flows through Wholesale. Channel experimentation is most active in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Valencia anchors European tangerine extract processing through integrated citrus clusters that supply certified concentrate to beverage formulators across Germany and France. Italian processors in Sicily and Calabria compete on organic certification density. Supply security concerns are driving procurement concentration toward documented peel-to-concentrate traceability systems.
Italy
Sicilian citrus processors supply cold-press oil to Swiss pharmaceutical compounders seeking EFSA-compliant natural flavoring. EU Green Deal bioeconomy incentives subsidize circular peel waste processing in Catania and Syracuse. Calabrian organic orchards under integrated pest management protocols concentrate procurement interest from German beverage bottlers.
Spain
Valencia's citrus processing corridor dominates conventional extract volume for European food manufacturers prioritizing cost stability. EFSA maximum residue limit enforcement disqualifies peel from non-EU sources lacking documentation. Andalusian supercritical CO2 installations serve cosmetic formulators in France and Germany demanding solvent-free certification.
Germany
Bavarian and North Rhine-Westphalian beverage bottlers centralize flavor procurement under multi-year technical service contracts with embedded sensory profiling. REACH chemical safety registration requirements favor established extractors with ECHA toxicology dossiers. German private-label manufacturers show fastest adoption of flavor-as-a-service contracting models.
Switzerland
Swiss pharmaceutical compounders in Basel and Zurich specify supercritical CO2-derived concentrates for topical formulations requiring zero solvent residue. Swissmedic regulations on natural product purity drive premium positioning for documented terpenoid profiles. Geneva-based fragrance houses source standardized volatile oils for high-margin cosmetic applications.
France
Parisian and Lyonnaise cosmetic manufacturers prioritize terpene consistency in cold-press tangerine oil for topical formulations. ANSM oversight of cosmetic ingredient safety reinforces demand for certified organic grades. Provençal natural product distributors serve mid-size compounders through specialized e-procurement platforms bypassing traditional wholesale channels.
Tangerine Extract Market Competitive Landscape
Capital-heavy processors with captive citrus supply compete with asset-light formulators sourcing through contract extraction networks. Market structure consolidates around three tiers: integrated flavor houses with multi-regional processing networks, specialized citrus processors with geographic concentration, and artisanal extractors serving niche certification segments. Dominant competitive moves include backward integration into orchard operations to secure peel supply, and technology licensing agreements for supercritical CO2 extraction systems.
Within the integrated flavor house tier, Symrise AG and Givaudan exemplify archetypes competing on extraction technology and technical service bundling. NOW Foods Inc occupies a position among direct-to-manufacturer specialists controlling quality verification channels. Young Living Essential Oils and doTERRA International sit within the wellness-oriented segment where organic certification and traceable sourcing anchor premium positioning.
| Leading Market Players |
|---|
| Young Living Essential Oils |
| NOW Foods Inc |
| Bluegrass Dairy & Food |
| Lionel Hitchen Ltd |
| Symrise AG |
| Givaudan |
| doTERRA International |
| Kanegrade |
| Vita-Pakt Citrus Products Co |
| Others |
Value Network & Pricing Analysis
Clean-label mandates from EFSA are compressing formulation timelines for European beverage manufacturers, forcing rapid substitution of synthetic flavoring with verified natural tangerine extract and concentrating procurement around certified Italian and Spanish processing clusters that can document peel-to-concentrate traceability.
Pricing Analysis
Margin tightening in conventional grades reflects weather-driven yield fluctuations in Sicily and Valencia that transmit directly to extract pricing. Three-tier pricing structure across organic, cold-press oil, and conventional solvent-extracted levels separates certified segments from volume-driven applications. Cost-down pressure on powder formats accelerates because petrochemical-derived synthetic limonene alternatives capture price-sensitive buyers at substantial discounts. Food manufacturers represent the most price-sensitive segment, while Swiss pharmaceutical compounders demonstrate minimal price elasticity for supercritical CO2-derived concentrates.
Supply Chain Analysis
Direct-to-manufacturer channels handle quality-verified demand from mid-size cosmetic compounders in Austria and Switzerland. Geographic supply concentration centers on Italy, Spain, and limited Swiss processing installations. Raw material dependencies include Citrus reticulata peel from integrated pest management orchards, cold-press extraction equipment, and supercritical CO2 systems. Single-source vulnerability around Valencia's citrus processing corridor creates concentration risk for European beverage formulators. Distribution runs through wholesale long-term supply agreements with embedded technical support for major bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA maximum residue limits function as a cost-of-compliance moat, freezing competitive dynamics among incumbent suppliers with documented traceability systems while disqualifying emerging processors lacking integrated pest management documentation.
For Market Incumbents: Lock in multi-year flavor-as-a-service contracts with German and Austrian private-label manufacturers before FSSC 22000 certification timelines allow new entrants to qualify. Deepen upstream control over Sicilian and Calabrian organic orchards to secure peel supply against weather-driven input volatility. Prioritize supercritical CO2 capacity additions in Andalusia to capture cosmetic and pharmaceutical premium segments. For New Entrants and Emerging Players: EU Green Deal bioeconomy incentives in Italy open a window for circular peel waste processing ventures that qualify for green transition financing. Target mid-size cosmetic compounders in France through specialized e-procurement platforms where distributor bypass models remain underpenetrated. Lead with direct-to-manufacturer quality verification channels controlling orchard-to-concentrate traceability. For Investors and Strategic Acquirers: The window for entry favors specialized citrus processors with geographic concentration in Valencia or Sicily and existing ECHA REACH registrations. Long-term viability hinges on consolidation plays that assemble toxicology dossiers and cold-press extraction capabilities across harvest-to-harvest variation management. Monitor EFSA purity standard evolution for processed citrus products as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Operations | Captive peel supply from Sicilian integrated pest management orchards secures EFSA-compliant formulation access. |
| Supercritical CO2 Capacity Expansion | Andalusian installations serve Basel pharmaceutical compounders demanding zero solvent residue certification. |
| Flavor-as-a-Service Contracting | Embedded sensory profiling and stability testing locks in German multi-brand bottler procurement centralization. |
| EU Green Deal Bioeconomy Certification | Circular peel waste processing qualifies for green transition financing in Catania and Syracuse clusters. |
| Direct-to-Manufacturer Digital Platform | Quality-verified extractors bypass distributor markups serving mid-size Austrian cosmetic compounders. |
Research Methodology
Trade databases, EFSA regulatory filings, and citrus industry association reports formed the secondary backbone of this analysis. Primary interviews with Italian and Spanish citrus processing plant managers, German beverage procurement leads, Swiss pharmaceutical compounders, and French cosmetic R&D directors validated demand-side assumptions. Bottom-up volume modeling across extraction technology tiers and top-down market sizing through end-use consumption patterns enabled triangulation.
Historical trendline analysis of cold-press and solvent extraction capacity deployments informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, application, and distribution channel alongside extraction method provenance as an industry-specific dimension. CAGRs were derived from weighted average growth contributions across certified and conventional grade tiers, with inputs including EFSA compliance timeline acceleration and supercritical CO2 adoption rates among Swiss and German buyers.
The model assumes a particular technology adoption path; alternative pathways for supercritical CO2 extraction would alter the outlook if pharmaceutical buyers relax zero-residue requirements. Practitioners should monitor EFSA maximum residue limit enforcement tightening and weather patterns in Sicilian and Valencian growing regions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Vanilla Bean Market
Flavorings and Food Additives
Mint Essential Oils Market
Flavorings and Food Additives
Edible Food Paints Market
Flavorings and Food Additives
Natural Food Colors Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Royal Jelly Extract Market
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Natural and Organic Flavors Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
Fiber Syrup Market
Flavorings and Food Additives
Smoke Flavorings Market