
 US Flavors Market | 2026-2036
US Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
US Flavors Market Intelligence
The shift toward clean-label natural flavor systems is reorganizing product development priorities across the US food and beverage industry. Givaudan leverages its extensive research into taste modulation and sugar reduction technologies. International Flavors & Fragrances Inc. specializes in complex flavor profiles for the expanding beverage and dairy alternatives sectors. Sensient Technologies Corporation differentiates through its control of natural color and flavor ingredient sourcing.
US flavors are complex chemical preparations, derived from natural sources or synthesized, designed to impart or modify taste and aroma in consumer products. These formulations, often containing essential oils, extracts, or specific aromatic compounds, are critical for achieving consistent product profiles in mass production. Natural flavors command a premium and represent the fastest-growing category, driven by consumer demand for transparency. The beverage application remains the largest consumer, while demand for encapsulated forms is rising for use in snack foods and oral care.
The US Food and Drug Administration (FDA) strictly governs flavor ingredients, primarily through its Generally Recognized as Safe (GRAS) notification and listing process. Concurrently, the USDA's National Organic Program sets the standards for flavors used in products labeled as organic, impacting ingredient sourcing and processing methods. Future competitiveness depends on navigating the evolving definitions of 'natural' and investing in technologies that support clean-label claims without compromising taste.
Market Dynamics
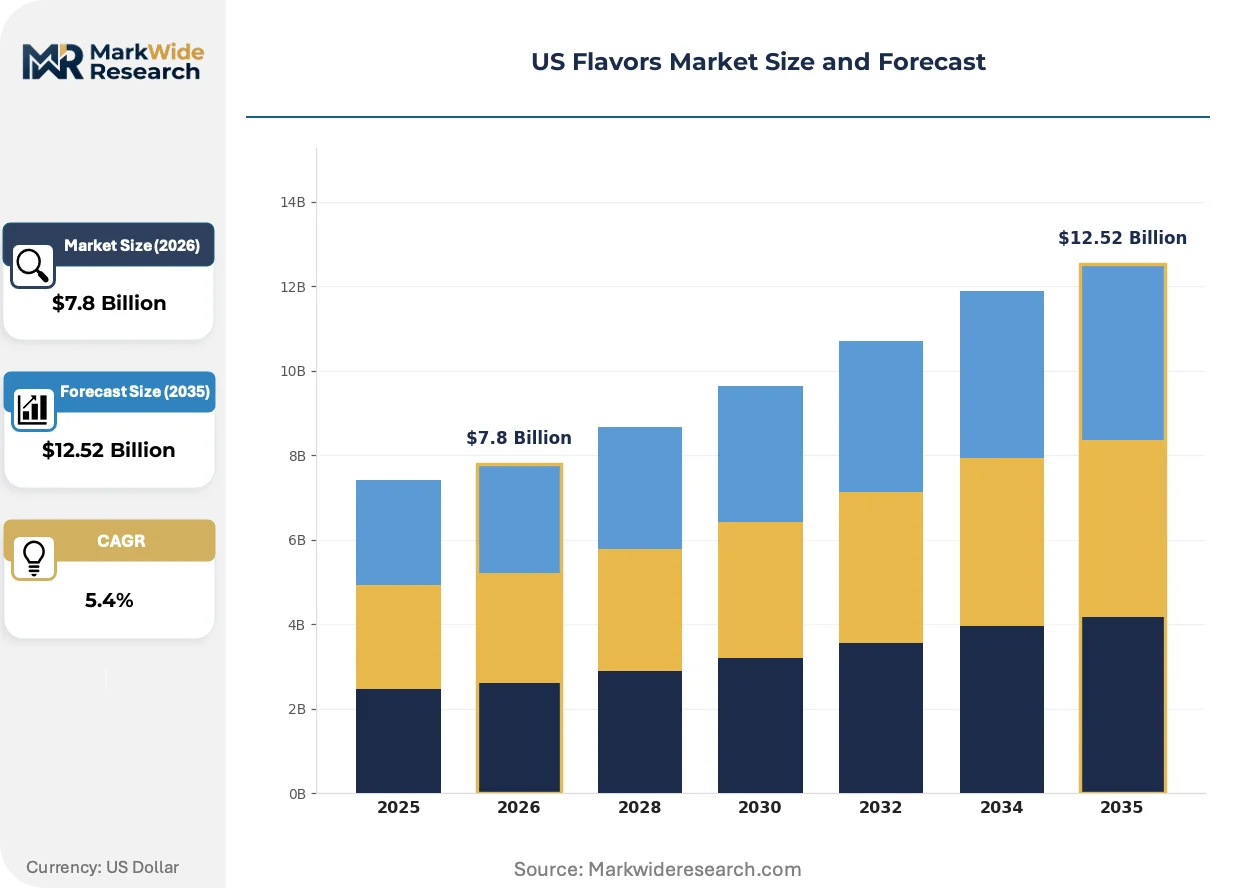
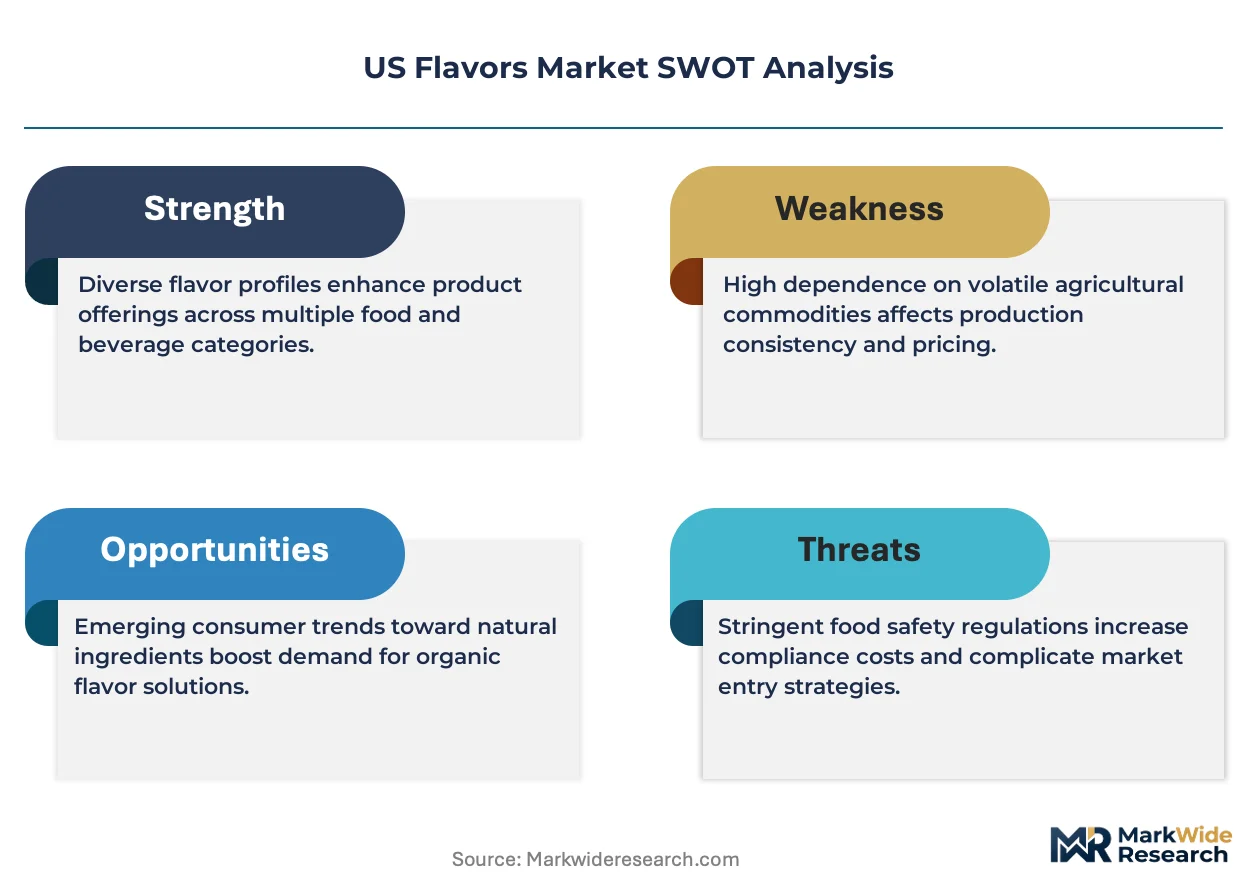
The US flavors market is defined by a structural shift toward clean-label formulations. This movement, driven by consumer demand for transparency, is concentrating R&D investment on natural ingredient sourcing and advanced taste modulation technologies.
Growth Catalysts
- Plant-Based Alternatives:Consumer adoption of dairy and meat alternatives, particularly in West Coast markets, requires sophisticated flavor systems to mimic traditional tastes and mask off-notes from plant proteins.
- FDA Clean Labeling:The FDA's scrutiny of ingredient lists and GRAS notifications encourages manufacturers to reformulate products with natural flavors, creating a clear market pull for certified ingredients.
- Encapsulation Technology:Demand for longer shelf life and flavor stability in snack foods and powdered beverages is driving the use of encapsulated flavors, which protect volatile compounds during processing.
Market Restraints
- Raw Material Volatility:The supply of key natural ingredients, such as vanilla and citrus extracts, is subject to climate-related disruptions and price fluctuations, impacting formulation costs and consistency.
- Technical Hurdles:Replicating the intensity and stability of certain synthetic flavors using only natural compounds remains a significant challenge, especially under high-heat processing conditions in baking.
- Regulatory Ambiguity:The lack of a single, legally binding definition of 'natural' from the FDA creates compliance risks and potential for consumer mistrust, complicating marketing claims.
Strategic Opportunities
- Functional Beverages:Developing flavor solutions for the functional beverage space, including masking bitter notes from adaptogens and nootropics, offers a significant growth avenue.
- AI-Powered Formulation:Leveraging artificial intelligence for predictive flavor pairing and rapid prototyping can accelerate product development cycles and uncover novel taste combinations.
- Organic Certification:Expanding portfolios of USDA-certified organic flavors meets demand from CPG brands targeting premium consumer segments and specific retail channels.
Industry Challenges
- Talent Scarcity:A shortage of skilled flavorists proficient in both the creative art and the scientific constraints of natural-only formulation is a primary operational bottleneck for flavor houses.
- Supply Chain Transparency:Establishing and documenting full traceability for botanical ingredients to meet stringent clean-label and organic certification standards is complex and costly for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Flavors Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
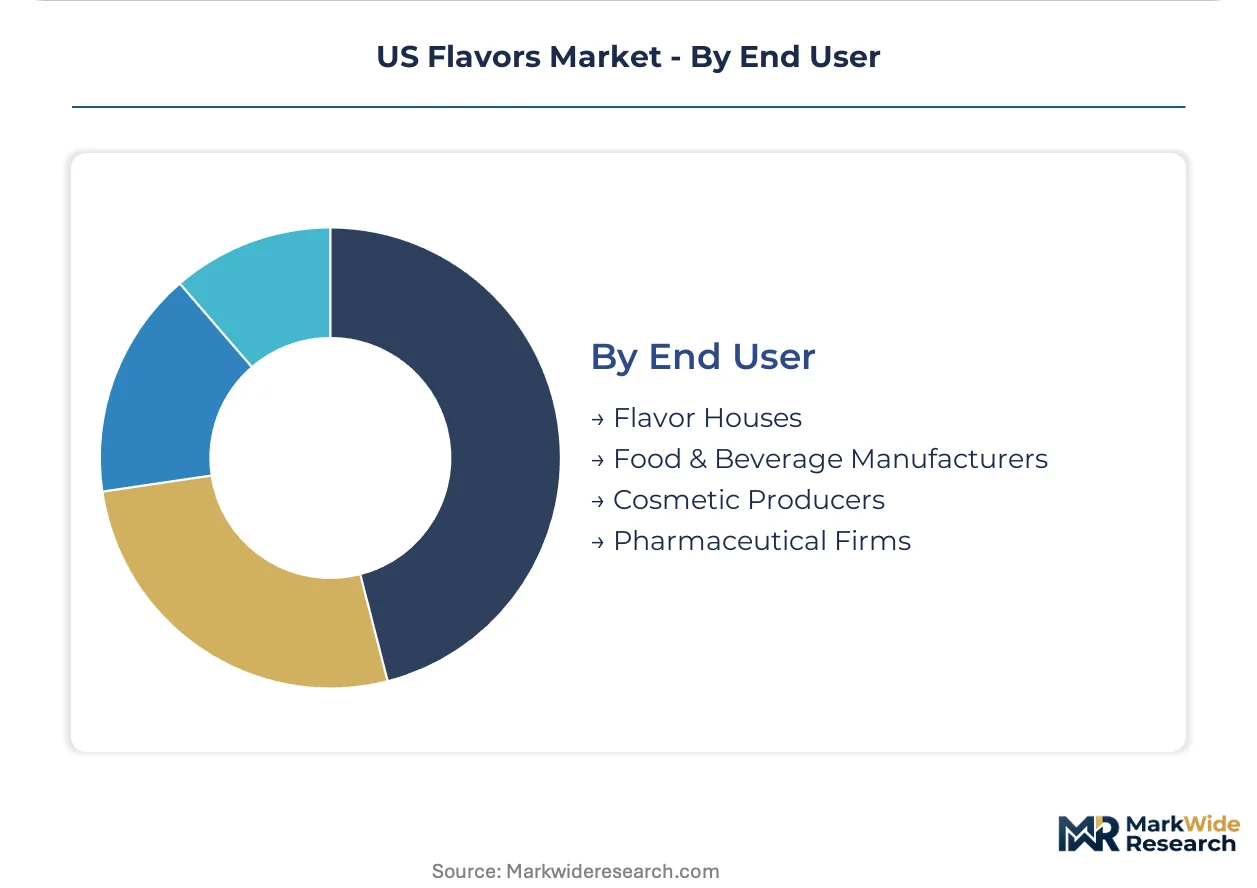
| Segmentation | Flavor Type: Natural, Artificial, Nature-Identical, Organic, Specialty Application: Confectionery, Beverages, Dairy Alternatives, Snack Foods, Oral Care Form: Liquid, Powder, Encapsulated, Emulsion, Oleoresin End User: Flavor Houses, Food & Beverage Manufacturers, Cosmetic Producers, Pharmaceutical Firms |
| Companies Covered | Givaudan, International Flavors & Fragrances Inc., Symrise AG, DSM-Firmenich AG, Kerry Group, Sensient Technologies Corporation, Archer Daniels Midland Company, Firmenich SA, Takasago International Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Flavors Market Strategic Shifts & Innovations
A primary tension in the US flavors industry is between the demand for authentic, natural taste profiles and the need for scalable, process-stable solutions. This dynamic is reshaping how flavors are created, regulated, and commercialized.
Taste modulation technology allows for the targeted reduction of sugar, salt, and bitterness. Food and beverage manufacturers are adopting these systems to meet consumer preferences for healthier products. This development is bifurcating the market between advanced systems for new product innovation and cost-effective modulators for reformulating legacy brands.
The FDA’s ongoing re-evaluation of chemical substances under the GRAS framework is forcing a continuous review of flavor formulations. This pressure accelerates the phase-out of certain synthetic compounds, increasing R&D in natural alternatives. The beverage sector is most affected, actively seeking compliant, plant-derived ingredients.
Direct-to-manufacturer co-creation is displacing transactional, distributor-mediated sales models. CPG brands now embed flavor house teams early in product development to accelerate innovation and ensure a unique taste profile. This collaborative approach is most prominent in food and beverage hubs like Austin and the San Francisco Bay Area.
US Flavors Market Segmentation

The US flavors market segmentation clarifies the diverse product offerings and end-user requirements that drive innovation and competitive strategies. Understanding these distinct categories helps manufacturers align product development with consumer preferences and regulatory mandates.
Flavor Type:
Regulatory distinctions significantly shape the US flavors market, influencing how various flavor types are developed and commercialized for consumer products.
- Natural:These flavors derive exclusively from natural sources like spices, fruits, vegetables, or fermented products. Consumer demand for transparency and clean labels is concentrating their use across the beverage and dairy alternative segments.
- Organic:Certified organic flavors adhere to USDA National Organic Program standards, ensuring ingredients are processed without synthetic pesticides or fertilizers. Demand for these premium flavors is concentrating in health-conscious consumer markets on the West Coast.
- Artificial:Synthetically produced chemical compounds mimic natural flavors, offering consistent profiles and cost-effectiveness. The snack food industry widely uses artificial flavors for their stability and intensity.
- Nature-Identical:These flavors are chemically identical to substances found in nature but are produced synthetically. They offer a balance of cost-effectiveness and familiar taste profiles.
- Specialty:This category includes custom-blended or unique flavor systems designed for niche applications or specific product differentiation. Specialty flavors provide unique taste experiences for premium product lines.
Natural flavors handle the majority of throughput; Organic flavors are the fastest mover on share.
Application:
The functional requirements of diverse product applications dictate the specific flavor profiles and delivery systems required by manufacturers.
- Beverages:This segment includes soft drinks, juices, functional drinks, and alcoholic beverages, requiring water-soluble and heat-stable flavor systems. Beverages represent the largest consumer segment for US flavors, with significant demand for fruit and botanical profiles.
- Dairy Alternatives:Plant-based milks, yogurts, and cheeses demand complex flavor solutions to mask off-notes from proteins and mimic traditional dairy tastes. West Coast markets are concentrating demand for sophisticated flavor systems in this category.
- Confectionery:Candies, chocolates, and baked goods utilize a wide array of flavors, often requiring heat-stable and fat-soluble formulations. The confectionery sector prioritizes vibrant and long-lasting taste experiences.
- Snack Foods:Chips, crackers, and savory snacks employ powdered and encapsulated flavors for consistent seasoning and extended shelf life. Flavor innovation in snack foods often focuses on bold and ethnic profiles.
- Oral Care:Toothpastes, mouthwashes, and chewing gums require specific flavor compounds for freshness and palatability. Mint and fruit flavors dominate the oral care segment.
Beverages drive the largest volume consumption, while Dairy Alternatives exhibit the steepest expansion trajectory.
Form:
Delivery format considerations are crucial for maintaining flavor integrity and extending product shelf life across different manufacturing processes.
- Encapsulated:Flavors are encased in a protective matrix, improving stability, extending shelf life, and controlling release. Demand for encapsulated forms is rising for use in snack foods and powdered beverages.
- Liquid:These flavors are typically oil or water-soluble, offering ease of incorporation into many food and beverage systems. Liquid forms are widely used due to their versatility and cost-effectiveness.
- Powder:Flavors are dried and powdered, suitable for dry mixes, snack seasonings, and applications requiring low moisture. Powdered forms offer stability and convenient handling.
- Emulsion:Oil-based flavors are dispersed in a water phase, creating stable and often cloudy liquid preparations. Emulsions are frequently used in beverage applications for visual appeal and flavor delivery.
- Oleoresin:Concentrated extracts from spices and herbs, containing both flavor and often color components. Oleoresins provide intense, authentic profiles for savory applications.
Liquid flavors command significant market volume, with Encapsulated forms rapidly climbing in market share.
End User:
The structural dynamics of the US food and beverage industry determine the procurement channels and innovation priorities for flavor ingredients.
- Food & Beverage Manufacturers:This segment includes large-scale producers of packaged foods, beverages, and convenience items. These manufacturers are the primary purchasers of flavor ingredients for mass production.
- Flavor Houses:Companies specializing in flavor creation, research, and production, supplying custom and proprietary blends to various industries. Flavor houses are central to innovation in taste modulation and clean-label solutions.
- Cosmetic Producers:Manufacturers of personal care products like lotions, perfumes, and lip balms use flavors for aroma and consumer appeal. The cosmetic industry seeks specific, often subtle, aromatic profiles.
- Pharmaceutical Firms:Pharmaceutical companies incorporate flavors to mask bitter tastes in medications, particularly for pediatric formulations. Palatability is a key driver for flavor selection in pharmaceuticals.
Food & Beverage Manufacturers constitute the primary purchasing segment, and Flavor Houses are expanding their direct co-creation partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US flavors market exhibits a complex trade balance, importing specialized raw materials while exporting advanced flavor systems to global markets. Domestic production largely serves the nation's vast food and beverage industry, with regulatory compliance defining market access. This dynamic interplay shapes regional manufacturing and consumption patterns across the United States.
California
Consumer demand for plant-based alternatives and natural flavors drives significant innovation in California. The state's strict environmental regulations often influence ingredient sourcing and processing methods for flavor manufacturers. Food and beverage manufacturing hubs in the San Francisco Bay Area and Los Angeles concentrate R&D efforts for clean-label dairy and meat alternatives.
New York Metro
The New York Metro area experiences strong demand for functional beverage flavors and specialty food applications. The FDA's ongoing GRAS reviews impact flavor formulation strategies for consumer products distributed from this region. Innovation in taste modulation technologies often originates from flavor houses and food tech startups located in New York City.
Midwest
Midwestern states, particularly Illinois and Ohio, show consistent demand for cost-effective, stable flavors for snack foods and processed dairy. USDA organic certification standards guide ingredient selection for manufacturers targeting the organic segment in this agricultural heartland. Major food processing centers like Chicago serve as significant procurement hubs for bulk flavor ingredients.
Texas
Texas demonstrates rising demand for beverage flavors, especially in the functional and ready-to-drink categories. State-level initiatives promoting food processing investment contribute to new manufacturing capacity requiring diverse flavor profiles. Food and beverage production facilities around Dallas and Houston are expanding their portfolios with novel taste combinations.
US Flavors Market Key Industry Players
Listed leaders compete with private specialists across flavor innovation and supply chain control within the US market. The industry structure shows a mix of large, diversified flavor houses and smaller, niche ingredient providers. Strategic archetypes include global giants offering full-service solutions and specialized firms focusing on natural or organic flavors. Companies frequently engage in strategic partnerships and portfolio diversification to maintain market relevance.
Within the global flavor innovation tier, Givaudan and International Flavors & Fragrances Inc. exemplify companies with extensive research and development capabilities and broad product portfolios. These firms leverage their expertise to develop complex flavor profiles for high-growth segments like dairy alternatives and functional beverages. Their market presence extends across various application areas, from beverages to snack foods. Sensient Technologies Corporation, another key player, represents an archetype focused on integrated natural color and flavor ingredient sourcing, supporting clean-label product development across diverse applications. These companies consistently adapt their offerings to evolving consumer preferences and regulatory mandates.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances Inc. |
| Symrise AG |
| DSM-Firmenich AG |
| Kerry Group |
| Sensient Technologies Corporation |
| Archer Daniels Midland Company |
| Firmenich SA |
| Takasago International Corporation |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for natural ingredients lock in both supply access and price visibility for flavor manufacturers. This strategic contracting mitigates volatility from agricultural commodity markets, ensuring consistent input costs for complex flavor systems.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing within the US flavors market. Pricing stratifies across premium, standard, and economy tiers based on certification level, such as USDA organic, and customization requirements. Raw material volatility from climate events exerts upward pricing pressure on natural flavors. Food and beverage manufacturers seeking cost-effective solutions are highly price-sensitive, while specialty product lines prioritize unique flavor profiles over cost.
Supply Chain Analysis
Stable inventory levels are critical for flavor houses, given the extended lead times for certain botanical extracts. The supply of key natural ingredients concentrates in specific geographies, including Madagascar for vanilla and Brazil for citrus. Raw material dependencies include essential oils, fruit extracts, and specific aromatic compounds. Climate-related disruptions present a structural risk to the consistent supply of these agricultural inputs. Distribution channels primarily involve direct co-creation partnerships with CPG brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US flavors market is an early-cycle expansion story, driven by the sustained adoption of plant-based alternatives across consumer segments.
For Market Incumbents:Consolidate strategic partnerships with CPG brands to accelerate co-creation of novel flavor systems. Invest heavily in R&D for advanced taste modulation technologies to counter synthetic flavor phase-out by the FDA. Secure long-term supply of certified natural and organic ingredients to mitigate raw material volatility. Expand regional manufacturing capabilities in food and beverage hubs to optimize distribution.
For New Entrants and Emerging Players:Lead with specialized flavor solutions for the functional beverage sector, focusing on masking off-notes from adaptogens. Target underpenetrated segments like premium organic snacks with USDA-certified flavor portfolios. Leverage AI-powered formulation platforms to offer rapid prototyping and unique taste combinations. Establish direct-to-manufacturer sales models, bypassing traditional distributor networks for greater agility.
For Investors and Strategic Acquirers:The market sits at an early-growth phase that favors specialized ingredient providers with strong intellectual property. Long-term viability rests on sustained consumer demand for clean-label and natural products. Focus acquisition strategies on niche flavor houses excelling in natural ingredient sourcing or advanced encapsulation technologies. The clarity of the FDA's definition of 'natural' will be a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Enhances production scale for high-demand natural flavors, reducing lead times for CPG partners. |
| Green Manufacturing Transition | Aligns flavor production with sustainability goals, appealing to environmentally conscious brands and consumers. |
| Long-term Supply Agreement | Secures consistent access to critical natural raw materials, stabilizing input costs for manufacturers. |
| Joint Venture | Accelerates R&D in areas like AI-powered formulation through shared expertise and resources. |
| Product Launch | Introduces innovative flavor systems tailored for functional beverages, capturing growth in a premium segment. |
Research Approach
Operator-level perspectives from flavorists, R&D directors at CPGs, regulatory compliance officers, and ingredient procurement managers anchored the qualitative base of this analysis. Primary interviews were triangulated with secondary validation from FDA GRAS listings, USDA organic standards, industry association reports, and academic literature on taste science. This approach ensured both bottom-up and top-down insights into market dynamics.
Sensitivity analysis framed the forecast framework, modeling various scenarios across the analysis window. The study segmented the market by flavor type, application, form, end user, and regional consumption patterns. Compound annual growth rates were derived from historical trends and projected market drivers, with consumer preference shifts and regulatory changes serving as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside predictable raw material supply or a stable regulatory environment would require recalibration. Forecasts reflect these assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Flavor Emulsions Market
Flavorings and Food Additives
Natural Berry Flavor Market
Flavorings and Food Additives
Edible Food Paints Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Mandarin Oil Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market
Flavorings and Food Additives
Flavor and Flavor Enhancers Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
Quillaia Extracts Market
Flavorings and Food Additives
Canola Lecithin Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Vanillin Market
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
Menthol Market