
 Chicory Products Market | 2026-2036
Chicory Products Market Size, Share, and Industry Trends Forecast 2026-2036
Chicory Products Market Outlook
Precision fermentation and enzymatic extraction is reshaping how inulin and oligofructose are isolated from chicory roots, replacing conventional hot-water methods with higher-yield bioprocessing. Cosucra Groupe Warcoing leverages proprietary membrane filtration to sustain premium-grade inulin output from its Belgian processing facilities. BENEO GmbH anchors European supply through integrated chicory farming across Belgium and Chile. Cargill Incorporated competes on global distribution scale, extending modified chicory fiber into North American bakery and beverage channels.
Chicory products encompass processed derivatives from Cichorium intybus roots and leaves, typically containing 15-20% inulin by fresh weight, extracted through diffusion, purification, and spray-drying into soluble dietary fiber ingredients for fat replacement and prebiotic enrichment. The food industry segment dominates volume as clean-label formulators replace synthetic additives with chicory-derived texturizers in dairy alternatives and baked goods. Nutraceuticals represents the fastest-expanding end-user category, with dietary supplements incorporating chicory extract for gut microbiome positioning. Roasted chicory maintains steady retail penetration as a caffeine-free coffee alternative, though margin pools increasingly favor high-purity chicory root powder for industrial contract manufacturing.
EFSA evaluates prebiotic health claims for chicory inulin under EU Regulation 1924/2006, while FDA recognizes inulin as generally recognized as safe for food use, shaping formulation confidence across Atlantic markets. BIS standards in India and China's GB food additive specifications govern import quality for chicory extract entering Asian processing chains. Stakeholders must monitor evolving novel food approvals in ASEAN jurisdictions and assess backward integration into chicory seed genetics to secure yield consistency against climate variability.
Market Dynamics
Precision fermentation and enzymatic extraction are compressing traditional hot-water diffusion timelines, forcing processors to retool Belgian and Dutch facilities for higher-yield bioprocessing or cede margin to membrane-filtration leaders.
Growth Catalysts
- EU F-Gas Regulation:Tightened extraction standards accelerate capital deployment into closed-loop solvent recovery systems, advantaging processors with captive engineering capabilities.
- Clean-label dairy alternatives:Formulators in plant-based yogurt and ice cream categories specify chicory inulin for fat-mimetic texture without synthetic stabilizers.
- Belgian-Dutch cultivation clusters:Integrated seed-to-extract supply chains in Flanders and Zeeland reduce transport spoilage and secure fresh-root throughput for industrial-scale inulin production.
Market Restraints
- Chicory root input volatility:Weather-induced yield fluctuations in Belgium's Flemish Region transmit directly to inulin spot pricing, compressing processor margins during poor harvest cycles.
- Supply concentration risk:Three Belgian processors control majority European high-purity inulin output, creating single-source vulnerability for North American nutraceutical contract manufacturers.
- Substitution threat from resistant starch:Modified potato and tapioca starches achieve comparable fat-replacement functionality at lower input cost in cost-optimized bakery applications.
Strategic Opportunities
- ASEAN novel food approvals:Singapore and Thailand regulators are evaluating chicory inulin for expanded food additive status, opening formulation partnerships with regional dairy processors.
- Precision fermentation convergence:Combining enzymatic hydrolysis with continuous membrane filtration enables custom oligofructose chain-length profiles for targeted microbiome applications.
- Direct-to-manufacturer e-procurement:Specialty ingredient platforms are disintermediating traditional distributor layers, allowing mid-size chicory processors to capture margin from nutraceutical formulators.
Industry Challenges
- Bioprocess engineering talent scarcity:Enzymatic extraction facilities in Belgium and the Netherlands compete for fermentation specialists against broader pharmaceutical and industrial biotechnology sectors.
- Novel food dossier timelines:EFSA health claim substantiation for prebiotic positioning requires 18-24 month evaluation cycles, delaying product launch schedules for targeted gut health positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chicory Products Market |
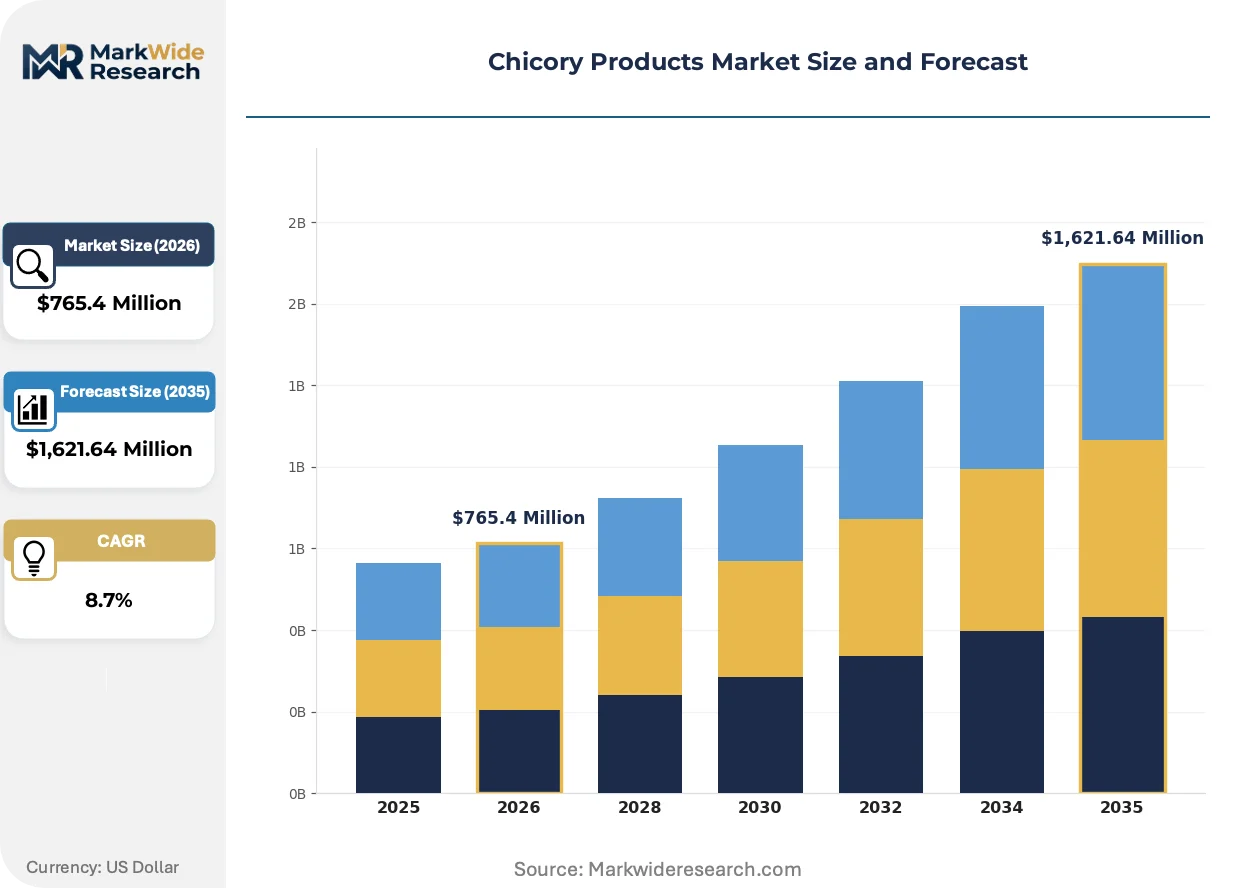
| Market Size in 2026 | $765.4 Million |
| Market Size in 2035 | $1,621.64 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicory Root Powder, Chicory Extract, Roasted Chicory, Chicory Leaf End User: Food Industry, Beverage Industry, Nutraceuticals, Retail Consumers Application: Beverages, Bakery Products, Dietary Supplements, Confectionery Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Cosucra Groupe Warcoing, BENEO GmbH, Cargill Incorporated, Agrana Beteiligungs-AG, Sensus, Ingredion Incorporated, Südzucker Group, Delecto Foods Pvt Ltd, Pioneer Chicory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chicory Products Market Strategic Shifts
Extraction technology, regulatory claim pathways, and procurement digitization are simultaneously reshaping how chicory processors capture value and how formulators source prebiotic ingredients.
Membrane filtration technology is migrating from niche premium-grade production to standard industrial throughput as Cosucra and comparable processors scale ceramic and polymeric systems across Belgian facilities. Mid-size nutraceutical manufacturers now specify membrane-purified inulin for microbiome supplement lines, compressing the price premium between diffusion-extracted and filtration-refined grades. This migration from thermal to mechanical separation is enabling energy cost reductions of roughly one-third while tightening batch-to-batch inulin chain-length consistency.
EFSA's evolving interpretation of EU Regulation 1924/2006 on prebiotic health claims is forcing chicory processors to fund human intervention studies rather than rely on compositional data alone. The industrial consequence is a bifurcation between dossier-investment leaders and commodity-grade suppliers restricted to fiber-content labeling. Nutraceutical applications in Germany and France face the tightest claim scrutiny, pushing formulators toward consortium-funded clinical trials shared across multiple chicory extract suppliers.
Ingredient procurement through specialized B2B platforms is fragmenting traditional distributor concentration as North American bakery and beverage manufacturers conduct direct supplier audits of Belgian extraction facilities. This channel disintermediation is compressing quote-to-contract timelines from quarterly to monthly cycles while forcing processors to maintain real-time inventory visibility. The shift is most visible in United States contract manufacturing, where clean-label mandates accelerate sourcing decisions beyond traditional distributor relationship timelines.
Chicory Products Market Segmentation
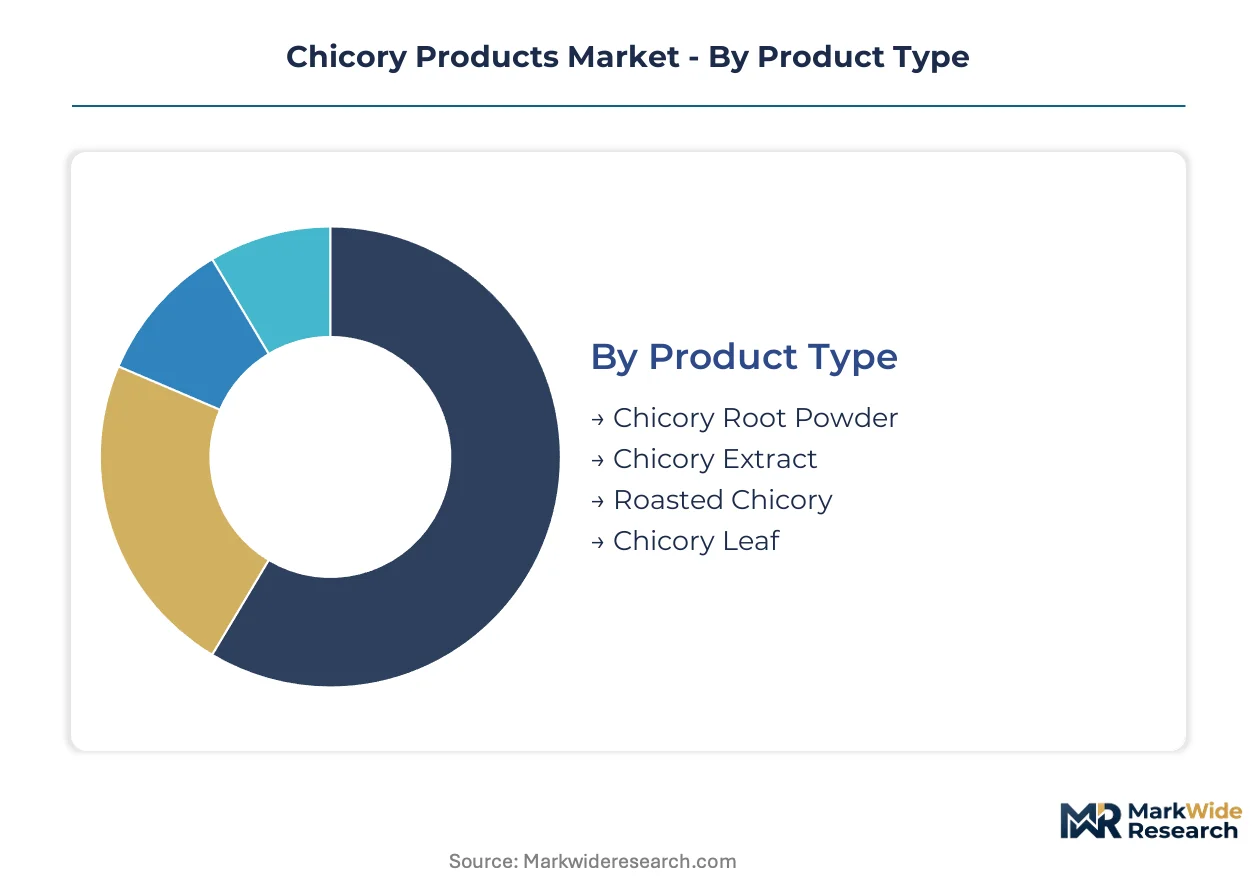
Chicory product differentiation tracks closely with extraction purity and functional positioning across industrial and consumer channels. Formulators select grades based on inulin chain-length profiles, thermal stability requirements, and clean-label certification needs.
Product Type:
Industrial buyers source across a functional spectrum spanning raw agricultural inputs to refined prebiotic isolates.
- Chicory Root Powder:Coarsely milled dried roots retain 15-20% inulin content and serve as cost-effective fiber fortification in pet food and animal feed formulations. Demand concentrates in German compound feed manufacturers seeking EU Green Deal-compliant ingredient sourcing.
- Chicory Extract:Standardized inulin and oligofructose concentrates undergo hot-water diffusion or membrane filtration purification for 80-95% soluble fiber content. Belgian processors supply high-purity grades to French dairy alternative formulators replacing synthetic hydrocolloids.
- Roasted Chicory:Caramelized root granules deliver coffee-like flavor profiles without caffeine for direct-to-consumer beverage substitution. German and Dutch retail chains maintain shelf space for traditional consumption patterns.
- Chicory Leaf:Fresh and dried leaf products supply regional culinary markets and specialty salad processors in Belgium and northern France with bitter greens positioning.
The dominant share belongs to chicory extract, while chicory root powder is closing the gap fastest through feed industry contract volumes.
End User:
Customer sophistication ranges from commodity procurement offices to clinical-trial-backed nutraceutical marketers.
- Food Industry:Industrial bakeries and dairy processors specify chicory inulin for fat mimetic texture in clean-label reformulations. Dutch plant-based cheese manufacturers drive contract demand for certified-organic grades.
- Beverage Industry:Functional drink formulators incorporate oligofructose for prebiotic positioning in gut-health positioned SKUs. German mineral water brands source Belgian-extracted inulin for fiber-fortified sparkling lines.
- Nutraceuticals:Capsule and powder supplement manufacturers require EFSA-compliant health claim substantiation for microbiome marketing. Clinical trial investment separates dossier-leaders from commodity fiber suppliers in this segment.
- Retail Consumers:Direct purchasers of roasted chicory and leaf products maintain traditional consumption patterns with limited price elasticity for organic certification.
Food industry procurement generates the highest absolute volumes, though nutraceuticals commands the steepest expansion trajectory through premium pricing power.
Application:
Formulation requirements diverge sharply between thermal processing stability and cold-solubility needs.
- Beverages:Instant solubility and neutral flavor profiles enable fiber fortification without sensory compromise. Belgian inulin processors supply German functional drink manufacturers with agglomerated grades for dry-mix dispersion.
- Bakery Products:Heat-stable inulin maintains prebiotic activity through proofing and baking cycles while contributing crumb softness. French industrial bakeries specify long-chain inulin for reduced-fat viennoiserie applications.
- Dietary Supplements:Capsule and sachet formats demand precise chain-length standardization for label claim consistency. EFSA evaluation timelines for prebiotic positioning constrain new product development cycles.
- Confectionery:Low-calorie bulk sweetener replacement in sugar-free chocolates and gummies leverages inulin's humectant properties. Dutch confectionery exporters source membrane-purified grades for premium positioning.
Beverages capture the largest formulation volume, with bakery products expanding most quickly through clean-label fat replacement mandates.
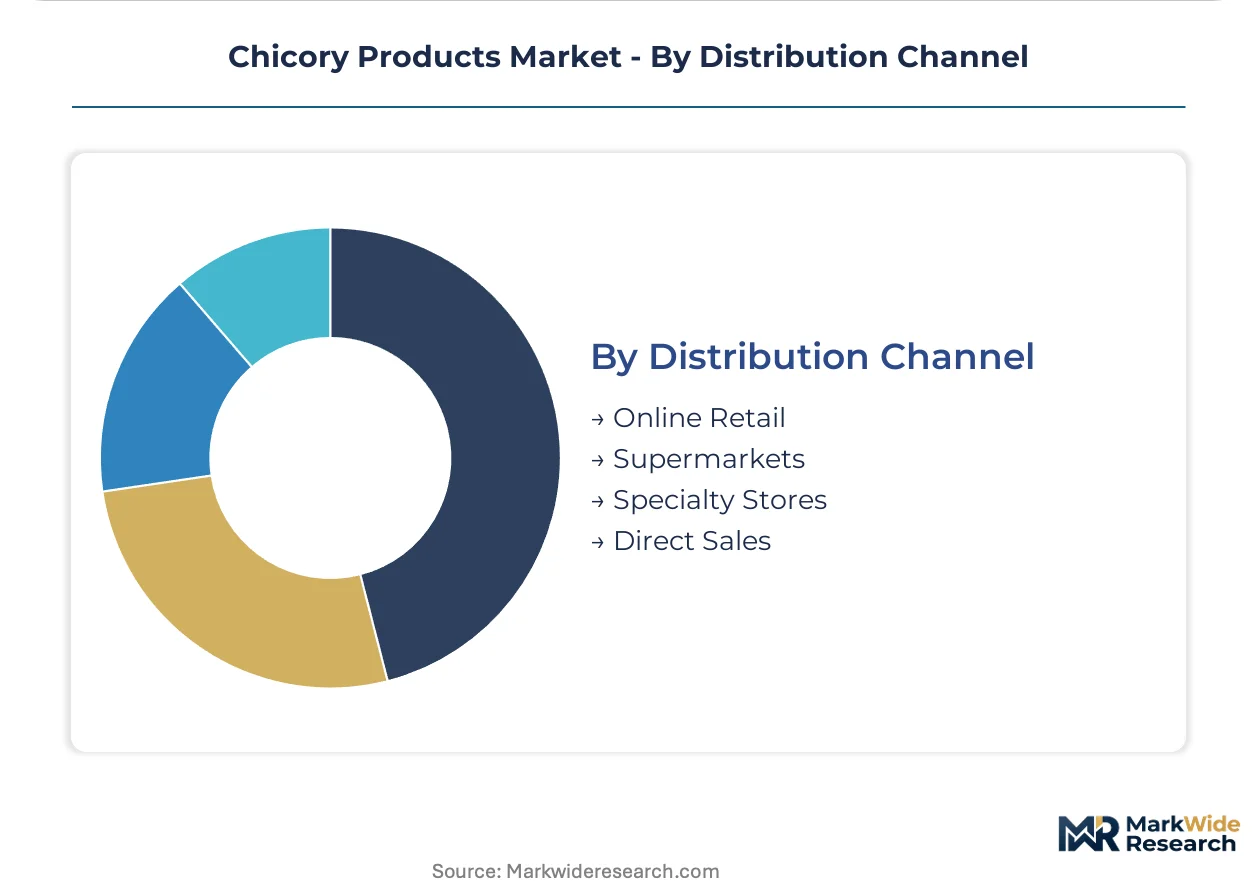
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to extraction facilities.
- Online Retail:Direct-to-consumer platforms serve roasted chicory and small-format supplement buyers with subscription replenishment models. German e-commerce penetration for specialty ingredients exceeds other European markets.
- Supermarkets:Mass retail distribution concentrates on roasted chicory and pre-packaged leaf products with established household penetration. Belgian retail consolidation limits shelf access for emerging brands.
- Specialty Stores:Health food and organic retailers stock premium-grade inulin supplements and artisanal roasted products. Dutch organic chains maintain dedicated chicory sections for traditional consumption.
- Direct Sales:Industrial processors contract directly with Belgian and Dutch extraction facilities for bulk inulin with customized chain-length specifications. This channel bypasses distributor margins for volume commitments above 20 metric tons annually.
Direct sales dominates industrial volume, while online retail is gaining share fastest through nutraceutical subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian processors export high-purity inulin to North American nutraceutical contract manufacturers, while Dutch cultivation clusters supply German dairy alternative formulators. This trade-flow corridor concentrates value capture in the Benelux extraction belt.
Germany
Plant-based yogurt and ice cream manufacturers specify chicory inulin for fat-mimetic texture in clean-label reformulations. EFSA evaluates prebiotic health claims under EU Regulation 1924/2006, creating dossier-investment barriers for new entrants. The North Rhine-Westphalia industrial belt hosts compound feed manufacturers sourcing EU Green Deal-compliant chicory root powder.
Belgium
Flemish Region chicory cultivation clusters support integrated seed-to-extract supply chains for industrial-scale inulin production. The EU F-Gas Regulation tightens extraction process standards, advantaging processors with captive engineering capabilities. Cosucra Groupe Warcoing leverages proprietary membrane filtration at its Warcoing facilities to sustain premium-grade output.
Netherlands
Zeeland cultivation areas reduce transport spoilage through proximity to Rotterdam port logistics for Asian export. Dutch plant-based cheese manufacturers drive contract demand for certified-organic chicory inulin grades. Specialty ingredient platforms in Amsterdam accelerate direct-to-manufacturer e-procurement, disintermediating traditional distributor layers.
United States
Clean-label bakery and beverage mandates accelerate sourcing decisions beyond traditional distributor relationship timelines. FDA recognition of inulin as generally recognized as safe shapes formulation confidence for contract manufacturers. Chicago and Minneapolis industrial corridors host bakery processors specifying heat-stable inulin for reduced-fat applications.
India
BIS standards govern import quality for chicory extract entering Asian processing chains through Mumbai and Chennai ports. Dietary supplement manufacturers incorporate chicory extract for gut microbiome positioning in domestic nutraceutical lines. Maharashtra-based compounders source chicory root powder for pet food fiber fortification.
Chicory Products Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure consolidating around membrane-filtration technology leaders and precision fermentation adopters. Three Belgian processors control majority European high-purity inulin output, creating tiered supply concentration. Strategic archetypes span integrated cultivation-extraction operators, toll-processing specialists, and global distribution platforms. Dominant competitive moves include backward integration into chicory seed genetics and capacity expansion into ASEAN novel food approval corridors.
Within the integrated cultivation-extraction tier, Cosucra Groupe Warcoing and BENEO GmbH exemplify European-origin operators with proprietary processing positions. Cargill Incorporated represents the global distribution archetype, extending modified chicory fiber into North American channels. These three anchors illustrate the competitive spectrum from captive Belgian-Dutch supply chains to transcontinental ingredient platforms.
| Leading Market Players |
|---|
| Cosucra Groupe Warcoing |
| BENEO GmbH |
| Cargill Incorporated |
| Agrana Beteiligungs-AG |
| Sensus |
| Ingredion Incorporated |
| Südzucker Group |
| Delecto Foods Pvt Ltd |
| Pioneer Chicory |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Belgian membrane-filtration facilities is tightening inulin spot pricing and forcing North American nutraceutical contract manufacturers into longer-term offtake commitments with premium-grade processors.
Pricing Analysis
Cost-plus contracts indexed to chicory root futures dominate industrial procurement, with Belgian processors layering membrane-purification premiums atop base agricultural inputs. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant health claim dossiers from commodity fiber grades. Cost compression in standard-grade extracts is intensifying because resistant starch substitutes achieve comparable fat-mimetic functionality at lower input cost. Pet food compounders exhibit highest price sensitivity, while nutraceutical formulators absorb premiums for clinical-trial-backed prebiotic positioning.
Supply Chain Analysis
EU F-Gas Regulation restrictions on solvent recovery technology are limiting extraction capacity expansion to processors with captive engineering capabilities, concentrating high-purity inulin output in Belgium, the Netherlands, and select Chilean operations. Supply chains draw from Flemish Region chicory cultivation clusters, enzymatic hydrolysis catalysts, and ceramic membrane filtration systems. Single-source vulnerability runs through three Belgian processors controlling majority European high-purity output. Distribution runs through direct sales contracts for industrial volumes above twenty metric tons annually, bypassing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward North American nutraceutical contract manufacturers consolidating procurement through direct supplier audits of Belgian extraction facilities, fragmenting traditional distributor concentration.
For Market Incumbents: Build regulatory dossier moats by funding EFSA-compliant human intervention studies that commodity-grade suppliers cannot replicate. Anchor capacity expansion in Chilean cultivation corridors to diversify climate exposure beyond Belgian Flemish Region harvest volatility. Deepen backward integration into chicory seed genetics to secure yield consistency against weather-induced input fluctuations threatening margin stability. For New Entrants and Emerging Players: Establish a beachhead in ASEAN novel food approval corridors where Singapore and Thailand regulators are evaluating expanded chicory inulin additive status with less entrenched incumbent presence. Target Indian dietary supplement manufacturers seeking BIS-compliant chicory extract for domestic gut microbiome positioning. Deploy specialty ingredient e-procurement platforms to disintermediate distributor layers and capture margin from mid-size nutraceutical formulators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated cultivation-extraction operators with proprietary membrane-filtration positions serving multi-year industrial offtake contracts. Long-term viability over a five-to-ten year window favors processors with captive Belgian-Dutch supply chains and precision fermentation engineering capabilities. Monitor ASEAN novel food approval timelines as inflection signals for geographic expansion value creation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Genetics | Captive chicory breeding programs in Belgium secure yield consistency against climate variability. |
| Precision Fermentation Capacity Expansion | Enzymatic hydrolysis facilities in the Netherlands enable custom oligofructose chain-length profiles. |
| ASEAN Novel Food Dossier Investment | Singapore regulator engagement opens formulation partnerships with regional dairy processors. |
| Direct E-Procurement Platform Launch | Amsterdam-based specialty ingredient platforms disintermediate traditional distributor layers. |
| Closed-Loop Solvent Recovery Retrofit | EU F-Gas Regulation compliance secures operating permits for Belgian extraction facilities. |
Study Parameters
Desk research of EU Novel Food Catalogue filings, FDA GRAS notifications, and BIS import quality standards preceded structured interviews with extraction plant managers, nutraceutical procurement directors, dairy alternative formulators, and membrane filtration equipment suppliers. Secondary validation drew from customs trade data, EFSA health claim evaluation records, and SEC filings of publicly traded ingredient processors. Bottom-up volume estimates triangulated against top-down market sizing across the projection horizon.
Assumptions held fixed include EFSA regulatory interpretation stability, Belgian-Dutch cultivation cluster productivity, and membrane filtration technology diffusion rates; variables stress-tested comprised chicory root yield volatility, ASEAN approval timelines, and resistant starch substitution elasticity. The analytical framework modeled product type, end user sophistication, application thermal stability requirements, and distribution channel structure. CAGRs derived from segment-level growth rate reconciliation with macro-level market expansion, incorporating precision fermentation adoption curves and clean-label reformulation intensity in dairy alternatives.
Stress conditions across chicory harvest yields, EFSA claim evaluation cycles, and ASEAN regulatory approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding extraction technology diffusion and end-user procurement consolidation. Material shifts in EU F-Gas Regulation enforcement stringency or breakthrough resistant starch functionality would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Pine Bark Extract Market
Flavorings and Food Additives
FTNF Flavors Market
Flavorings and Food Additives
Edible Food Paints Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
Citrus Oil Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Menthol Market
Flavorings and Food Additives
Flavor Masking Agents Market
Flavorings and Food Additives
Asia-Pacific Food Colorants Market
Flavorings and Food Additives
Ylang Ylang Extract Market
Flavorings and Food Additives
Global Chicory Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Natural Flavors Market