
 Global Acerola Extracts Market | 2026-2036
Global Acerola Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acerola Extracts Market Foresight
The EU Green Deal is rebalancing procurement priorities across European nutraceutical supply chains. DSM leverages its integrated biotechnology platforms to secure standardized ascorbic acid profiles from tropical sources. Kemin Industries Inc. anchors its position through vertical control over extraction and formulation stages. Naturex (Givaudan) differentiates via deep specialization in clean-label botanical extracts for cosmetic and food applications.
Acerola extract is a concentrated preparation derived from Malpighia emarginata fruit, typically standardized to 17-25% natural vitamin C content through spray-drying or low-temperature processing, serving primarily as a clean-label alternative to synthetic ascorbic acid in fortified products. Powder form dominates commercial volumes due to superior stability and blending compatibility across dry-mix applications. Dietary Supplements represents the most mature revenue pool, while Functional Beverages is expanding fastest as beverage producers reformulate with natural antioxidant claims. Supercritical CO2 extraction commands premium positioning despite higher capital requirements, as cosmetic manufacturers prioritize solvent-free certification.
FDA GRAS status and EFSA Novel Food catalog listings govern market access pathways for acerola-derived ingredients in the United States and European Union respectively, with Brazil's ANVISA providing additional pharmacopeial standards for domestic export-grade material. ISO 22000 and HACCP protocols shape manufacturing audits for international buyers sourcing from Latin American processing facilities. Stakeholders must monitor evolving botanical authentication requirements and extraction method disclosure mandates as clean-label enforcement tightens across multiple jurisdictions.
Market Dynamics
The EU Green Deal's botanical sustainability criteria are compressing extraction compliance timelines while concentrating procurement around certified Brazilian processing clusters near Fortaleza and São Paulo state.
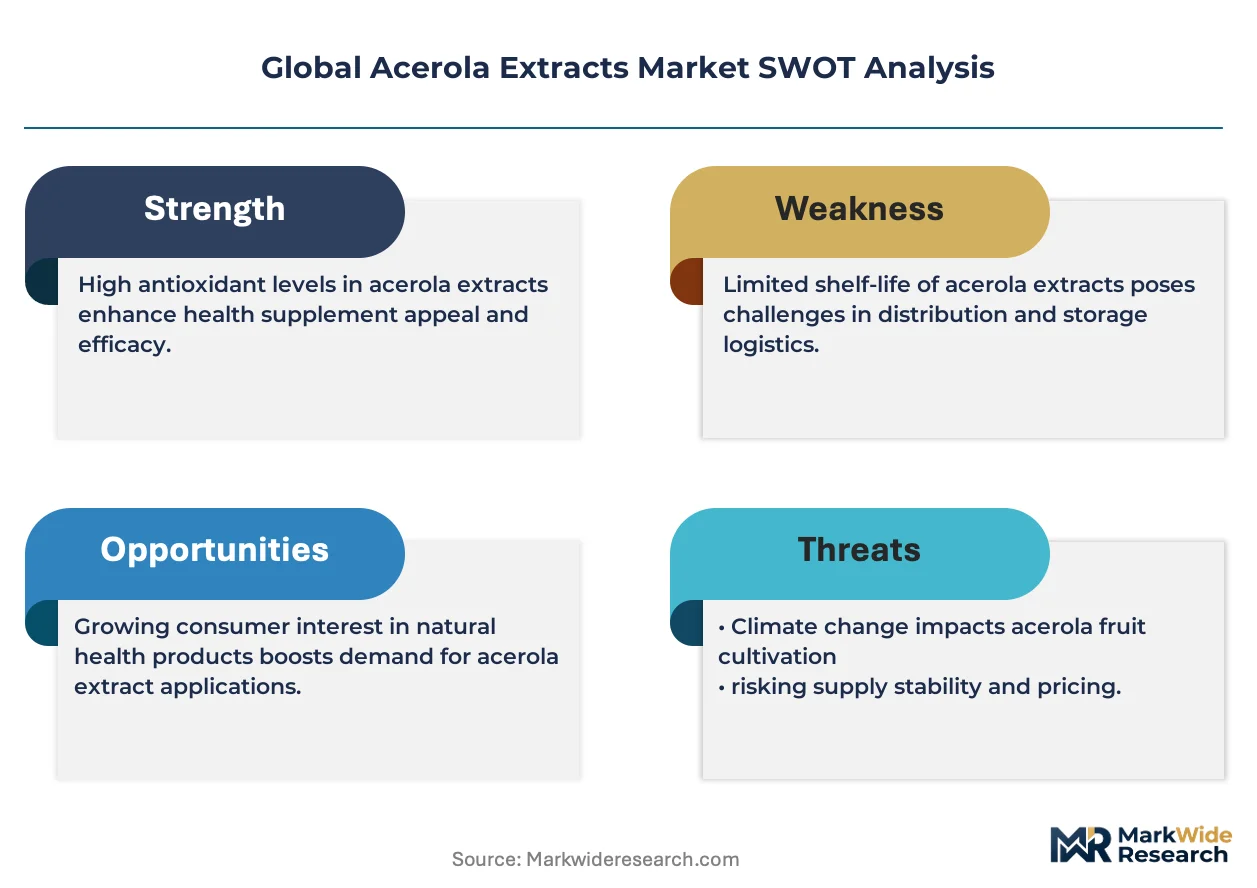
Growth Catalysts
- Clean-label vitamin C demand:Dietary supplement manufacturers are reformulating with natural acerola extracts to replace synthetic ascorbic acid in fortified products, driven by consumer ingredient transparency preferences.
- EU Green Deal alignment:The framework's botanical sustainability mandates are creating preferential market access for extraction facilities meeting solvent-free certification and carbon footprint disclosure standards.
- Supercritical CO2 adoption:Cosmetic formulators are specifying this extraction method for premium antioxidant applications, expanding addressable volume in skin care and personal care segments.
Market Restraints
- Raw material concentration:Over 80% of commercial acerola cultivation sits within Brazil's northeastern growing belt, exposing supply continuity to localized climate volatility and logistics disruption.
- Input cost volatility:Energy-intensive spray-drying and low-temperature processing stages face electricity price fluctuation, compressing margin structures for mid-scale processors.
- Synthetic ascorbic acid substitution:Fermentation-derived vitamin C from Chinese biotechnology platforms maintains cost advantages in mass-market fortified foods, limiting acerola penetration in price-sensitive categories.
Strategic Opportunities
- Functional beverage expansion:Natural antioxidant positioning is opening formulation partnerships with ready-to-drink and sports beverage producers seeking clean-label differentiation in North American and European markets.
- EFSA Novel Food catalog optimization:Accelerated regulatory clearance pathways for standardized extract grades are enabling faster product launches across EU member states.
- Cosmetic grade premiumization:Solvent-free certification and organic cultivation protocols are commanding 40-60% price premiums in dermocosmetic applications, expanding revenue per kilogram for compliant suppliers.
Industry Challenges
- ISO 22000 audit complexity:Latin American processing facilities face extended certification timelines and recurring compliance costs to maintain international buyer qualification.
- Botanical authentication requirements:Evolving DNA barcoding and phytochemical fingerprinting standards are forcing investment in analytical infrastructure and third-party verification partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acerola Extracts Market |
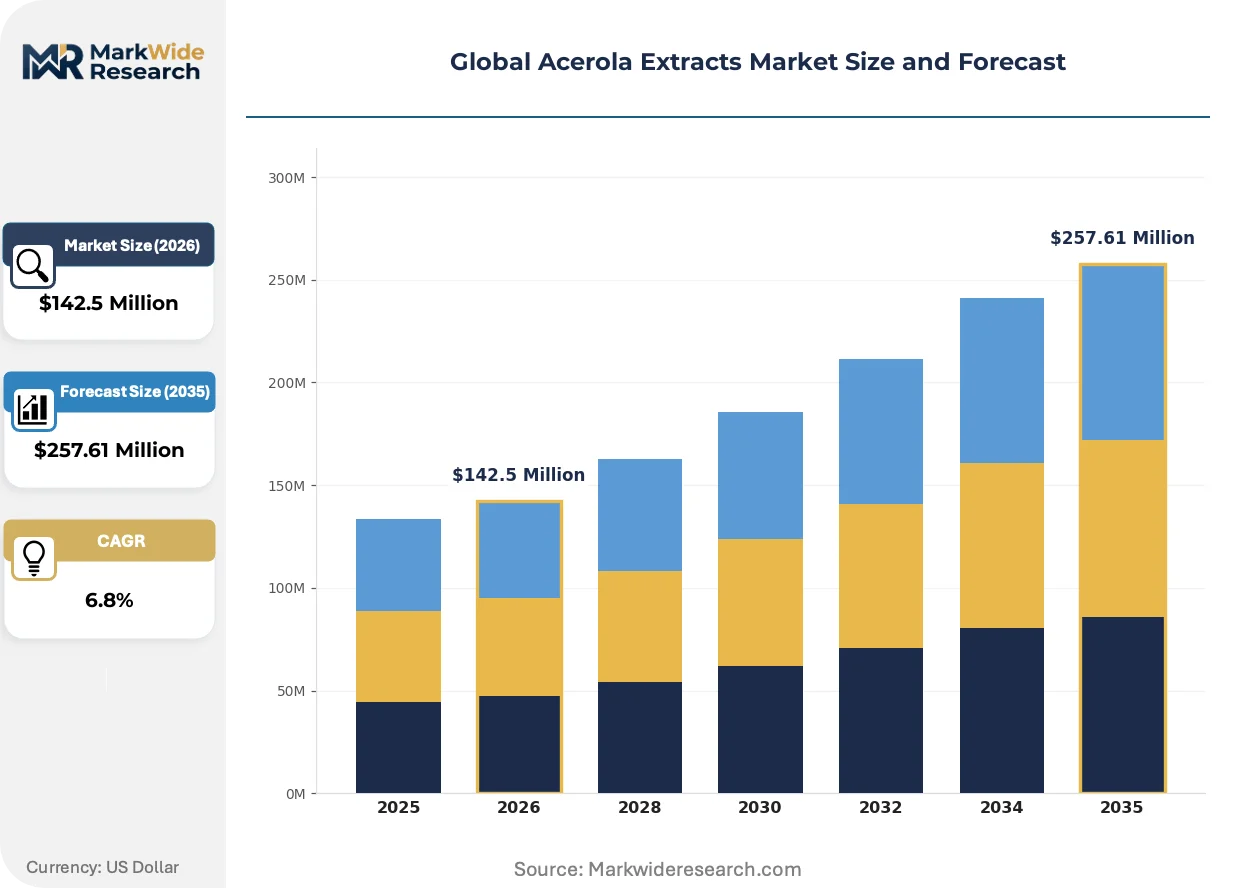
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Powder, Liquid Concentrate, Capsules, Tablets, Gummies Application: Dietary Supplements, Cosmetics, Functional Beverages, Food Additives, Pharmaceuticals Extraction Method: Solvent Extraction, Cold Pressing, Freeze Drying, Supercritical CO2, Enzyme-Assisted Extraction End User: Nutraceutical Companies, Cosmetic Manufacturers, Beverage Producers, Pharmaceutical Firms, Food Processing Units |
| Companies Covered | DSM, Kemin Industries Inc., Dohler GmbH, Naturex (Givaudan), The Green Labs LLC, NutriBotanica, Foodchem International Corporation, Duas Rodas, International Flavors and Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acerola Extracts Market Shifts & Advancements
Extraction technology convergence and regulatory disclosure mandates are reshaping competitive differentiation, with sustainability certification becoming a gating factor for premium segment participation.
Supercritical CO2 extraction systems are integrating solvent-free processing capabilities with automated pressure-temperature control modules. Cosmetic manufacturers in France and Germany are specifying this technology for antioxidant serum formulations. The equipment upgrade cycle is compressing payback periods for Brazilian processors serving EU export contracts.
EFSA Novel Food catalog listings are tightening botanical origin documentation requirements for acerola-derived ingredients. European importers are now demanding batch-level phytochemical certificates and cultivation GPS coordinates. Dietary supplement brands are reformulating procurement specifications to preempt compliance gaps ahead of enforcement deadlines.
Direct sourcing contracts between extract processors and end-use formulators are displacing traditional trader intermediaries in high-volume transactions. Functional beverage producers in the United States are negotiating multi-year supply agreements with Fortaleza-based processors. This channel compression is concentrating procurement expertise within buyer technical teams and squeezing margin capture for regional distributors.
Global Acerola Extracts Market Segmentation
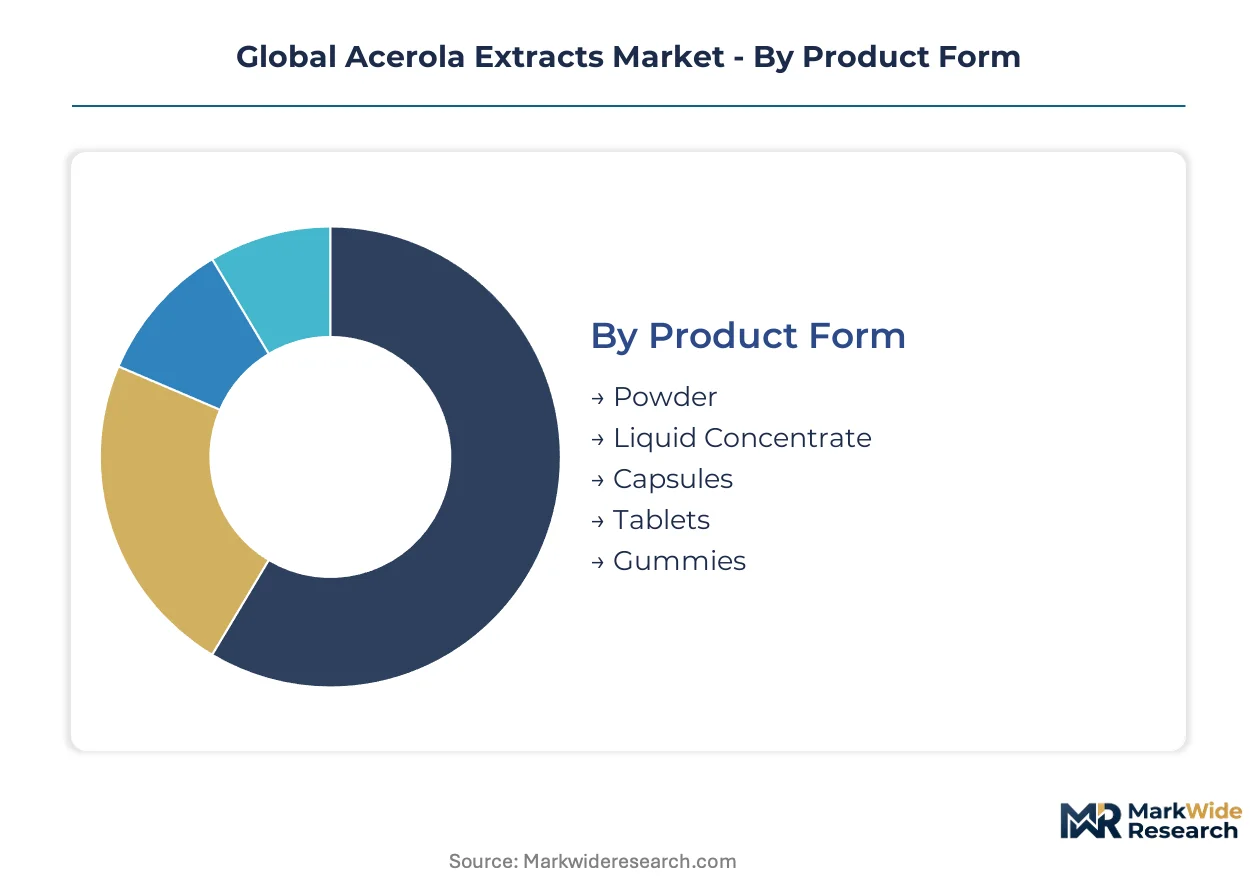
Acerola extract specifications diverge sharply across end-use categories, with pharmaceutical and cosmetic applications demanding solvent-free certification while food-grade material tolerates broader processing parameters. Certification burdens segment procurement timelines and capital requirements unevenly across the value chain.
Product Form:
Powder forms carry FDA GRAS and EFSA Novel Food catalog requirements for food fortification, while gummies and capsules face additional stability testing protocols for moisture-sensitive vitamin C matrices.
- Powder:Spray-dried or low-temperature processed material standardized to 17-25% natural vitamin C content. Demand concentrates in dry-mix dietary supplements and fortified food applications across the United States and Germany, driven by superior stability and blending compatibility in high-speed manufacturing lines.
- Liquid Concentrate:Aqueous or glycerin-based solutions with shorter shelf life requiring cold-chain logistics. Beverage producers in France and Japan specify this format for ready-to-drink antioxidant formulations, constrained by oxidation sensitivity during distribution.
- Capsules:Encapsulated powder targeting precision dosing in nutraceutical applications. Brazil's ANVISA pharmacopeial standards govern export-grade capsule specifications.
- Tablets:Compressed powder with binding agents for chewable or swallowable delivery. Direct compression equipment compatibility shapes procurement specifications.
- Gummies:Gelatin or pectin matrix with heat-sensitive vitamin C requiring low-temperature incorporation. Children's supplement lines in North America drive format innovation.
Leading the category by volume: Powder. Growing fastest: Gummies.
Application:
Cosmetic and pharmaceutical segments command premium pricing through ISO 22000 and HACCP audit requirements, while food additive applications compete on cost efficiency with synthetic ascorbic acid benchmarks.
- Dietary Supplements:The most mature revenue pool encompassing tablets, capsules, and powders for immune support positioning. Reformulation activity in the United States and European Union accelerates as brands replace synthetic ascorbic acid with natural acerola claims.
- Functional Beverages:Natural antioxidant positioning in ready-to-drink and sports drinks. Beverage producers in Brazil and Mexico negotiate direct sourcing contracts with Fortaleza processors, bypassing traditional trader intermediaries.
- Cosmetics:Antioxidant serums and dermocosmetic applications requiring solvent-free certification. Supercritical CO2 extraction specifications from French and German manufacturers drive equipment upgrades at Brazilian processing facilities.
- Food Additives:Fortification of juices, cereals, and dairy alternatives. Price competition with fermentation-derived vitamin C from Chinese biotechnology platforms limits penetration.
- Pharmaceuticals:Standardized extract grades for therapeutic vitamin C deficiency protocols. ANVISA pharmacopeial standards and EMA quality documentation requirements extend approval timelines.
Volume leadership: Dietary Supplements. Steepest expansion trajectory: Functional Beverages.
Extraction Method:
Capital intensity and certification eligibility split the category, with supercritical CO2 and enzyme-assisted methods requiring specialized infrastructure while solvent extraction faces tightening EU Green Deal disclosure mandates.
- Supercritical CO2:Solvent-free processing with automated pressure-temperature control modules. Cosmetic manufacturers in Germany and France specify this technology for premium antioxidant serum formulations, compressing payback periods for equipment upgrades at São Paulo state processing clusters.
- Solvent Extraction:Ethanol or water-based processing with higher throughput and lower capital requirements. Mid-scale Brazilian processors serving food additive markets rely on this method despite tightening botanical sustainability criteria.
- Cold Pressing:Mechanical juice extraction preserving heat-sensitive bioactives. Limited commercial scale due to lower vitamin C concentration yields.
- Freeze Drying:Lyophilization for highest-grade powder with minimal thermal degradation. Energy-intensive operations face electricity price volatility in Brazilian processing regions.
- Enzyme-Assisted Extraction:Cellulase or pectinase treatments improving yield from fruit pulp. Emerging adoption for organic-certified material targeting premium cosmetic applications.
Premium positioning: Supercritical CO2. Fastest capacity additions: Enzyme-Assisted Extraction.
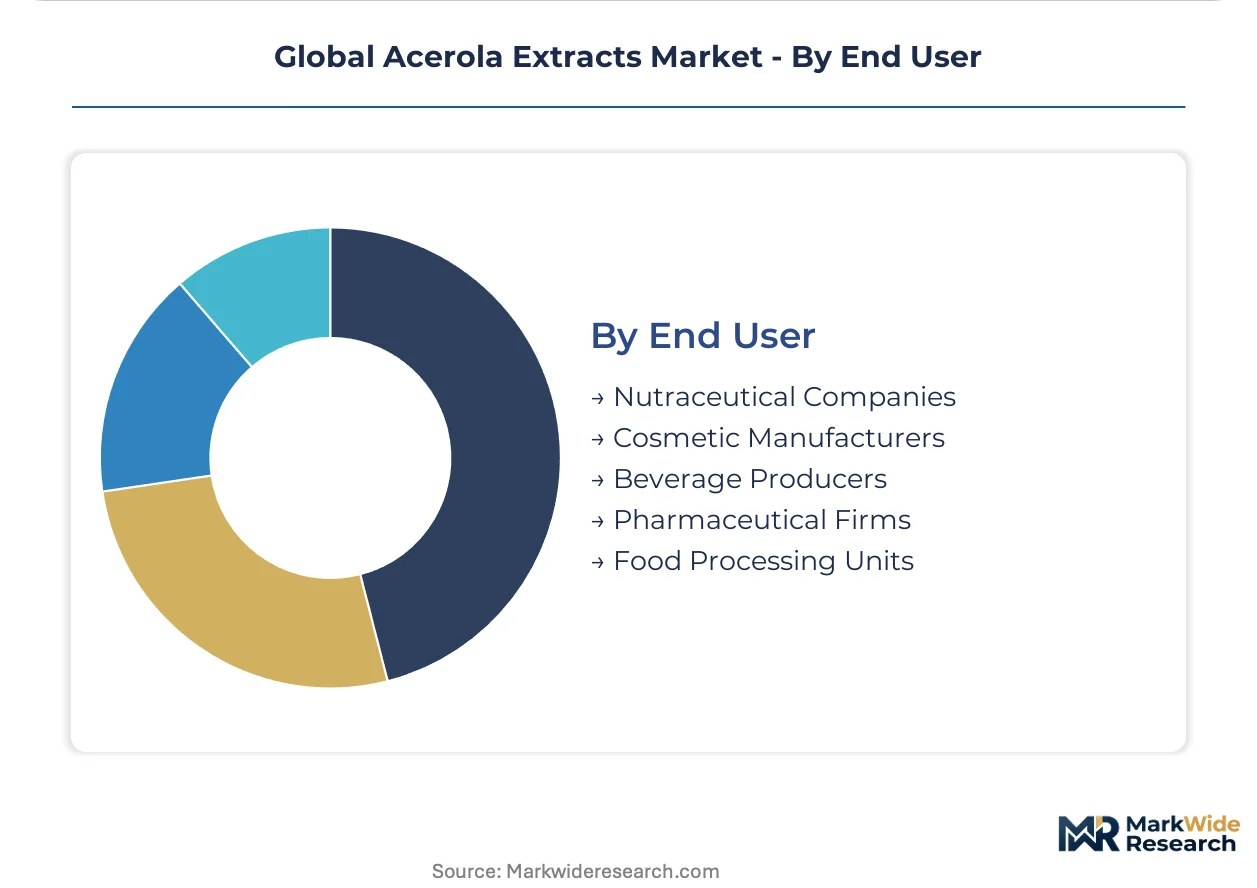
End User:
Procurement sophistication varies by buyer technical capabilities, with nutraceutical and pharmaceutical firms conducting direct audits while food processors rely on distributor certification packages.
- Nutraceutical Companies:Formulators of vitamin C supplements and multivitamin complexes. DSM and Kemin Industries anchor demand through integrated biotechnology platforms and vertical control over extraction stages.
- Cosmetic Manufacturers:Dermocosmetic and personal care brands specifying solvent-free certification. Givaudan's Naturex division deep-specializes in clean-label botanical extracts for this buyer segment.
- Beverage Producers:Ready-to-drink and sports beverage formulators seeking natural antioxidant claims. Direct multi-year supply agreements with Fortaleza-based processors displace regional distributors.
- Pharmaceutical Firms:Therapeutic-grade vitamin C suppliers requiring batch-level phytochemical certificates and cultivation GPS coordinates under tightening EFSA Novel Food documentation.
- Food Processing Units:Juice, cereal, and dairy alternative fortification operations. Price sensitivity limits acerola penetration against synthetic ascorbic acid in mass-market categories.
Dominant procurement volume: Nutraceutical Companies. Fastest contract growth: Beverage Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortaleza anchors global acerola extract supply through its northeastern Brazilian growing belt, with São Paulo state processing clusters handling downstream standardization for export markets. European and North American formulators source predominantly from these Brazilian hubs, while Asian demand routes through direct procurement contracts with established processors.
Brazil
Dietary supplement manufacturers and cosmetic formulators drive import demand from Fortaleza-based processors and São Paulo state extraction facilities. ANVISA pharmacopeial standards govern export-grade material certification for international buyers. The Ceará state corridor around Fortaleza concentrates organic cultivation protocols, while São Paulo state clusters specialize in supercritical CO2 equipment upgrades for EU cosmetic contracts.
United States
Functional beverage producers and nutraceutical brands reformulate with natural vitamin C claims, displacing synthetic ascorbic acid in immune support positioning. FDA GRAS status enables rapid ingredient adoption across fortified food and supplement categories. Direct sourcing agreements with Brazilian processors are compressing distributor margins in high-volume transactions.
Germany
Cosmetic manufacturers specify solvent-free extraction certification for antioxidant serum formulations targeting premium dermocosmetic segments. EFSA Novel Food catalog requirements are tightening batch-level documentation demands for acerola-derived ingredients. Processing equipment suppliers in Baden-Württemberg are integrating automated pressure-temperature control modules for supercritical CO2 systems exported to Brazilian facilities.
France
Clean-label botanical extract demand from Paris-based cosmetic houses and Lyon-region nutraceutical formulators is reshaping procurement specifications. EU Green Deal sustainability criteria are compressing compliance timelines for extraction method disclosure. Naturex's specialized operations exemplify deep vertical control over clean-label supply chains serving cosmetic and food applications.
Japan
Beverage producers specify liquid concentrate formats for ready-to-drink antioxidant formulations requiring cold-chain distribution integrity. METI standards and JIS quality protocols extend approval timelines for novel ingredient introductions. Tokyo-based trading houses are negotiating multi-year supply agreements directly with Fortaleza processors to secure volume commitments.
Global Acerola Extracts Market Competitive Landscape
The competitive structure tilts toward biotechnology-integrated specialists with captive extraction infrastructure. Market participation clusters around three archetypes: multinational life-science conglomerates with standardized ingredient platforms, mid-scale regional processors with geographic cultivation proximity, and botanical extract specialists with deep cosmetic industry relationships. Dominant competitive moves include backward integration into cultivation controls and technology licensing partnerships for solvent-free processing certification.
Within the biotechnology-integrated tier, DSM and Kemin Industries exemplify platform-scale players with upstream control over extraction standardization. Naturex, operating within Givaudan's broader portfolio, occupies a specialist position in clean-label botanical extracts for cosmetic and food end-uses. Among Brazil-based processors, Duas Rodas represents regional-scale fabrication anchored to northeastern cultivation belts. These three archetypes—platform conglomerate, botanical specialist, and regional processor—capture distinct margin pools based on certification depth and customer technical requirements.
| Leading Market Players |
|---|
| DSM |
| Kemin Industries Inc. |
| Dohler GmbH |
| Naturex (Givaudan) |
| The Green Labs LLC |
| NutriBotanica |
| Foodchem International Corporation |
| Duas Rodas |
| International Flavors and Fragrances Inc. |
| Others |
Supply & Pricing Matrix
Family-owned processors across Brazil's northeastern cultivation belt anchor supply continuity through patient capital allocation, insulating extraction facilities from quarterly earnings pressure while reinforcing long-term contract discipline with European and North American buyers. This ownership pattern concentrates pricing power among established Fortaleza-based operators who capture premiums through ANVISA-certified export grades and solvent-free processing credentials demanded by German cosmetic manufacturers.
Pricing Analysis
Outcome-based pricing anchors the premium tier, with supercritical CO2-extracted material commanding substantial markups for cosmetic applications where batch-level phytochemical certificates guarantee antioxidant potency. Three-tier pricing structure across premium, standard, and economy levels stratifies by extraction method certification and organic cultivation protocol compliance. Pricing pressure stems from fermentation-derived synthetic ascorbic acid cost advantages in mass-market fortified foods. Food processing units exhibit highest price sensitivity, while cosmetic manufacturers accept premium positioning for solvent-free certification.
Supply Chain Analysis
Dual-sourcing requirements from DSM and Kemin Industries force Brazilian processors to maintain redundant qualification pathways across Fortaleza and São Paulo state facilities. Supply concentrates in Brazil, with secondary processing hubs in Germany and France serving EU cosmetic formulation demand. Raw material dependencies include tropical fruit pulp, electricity for spray-drying operations, and supercritical CO2 equipment components. Single-source vulnerability concentrates in Brazil's northeastern growing belt exposure to localized climate volatility. Distribution runs through direct long-term offtake contracts displacing traditional trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology is displacing legacy solvent-based processing as EU Green Deal disclosure mandates tighten, compressing payback periods for equipment upgrades and reshaping competitive differentiation around carbon footprint documentation.
For Market Incumbents: Extend backward integration into organic cultivation protocols around Fortaleza to secure ANVISA-certified export volumes ahead of tightening EFSA Novel Food documentation requirements. DSM and Kemin Industries exemplify platform-scale defense through captive extraction standardization and multi-year supply agreement lock-in with beverage producers. Capacity additions in São Paulo state supercritical CO2 clusters reinforce positioning against enzyme-assisted extraction entrants. For New Entrants and Emerging Players: Mid-scale functional beverage producers in Mexico and Japan represent underserved buyer archetypes seeking natural antioxidant claims without incumbent minimum order requirements. White-space concentration sits in liquid concentrate cold-chain logistics for ready-to-drink formulations, plus enzyme-assisted extraction for organic-certified cosmetic applications. Direct processor relationships with Tokyo-based trading houses offer fastest qualification pathway. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Brazilian processors with ANVISA certification and existing EU buyer relationships in Ceará state corridor. Long-term viability across the next decade hinges on supercritical CO2 equipment deployment and solvent-free certification maintenance. The inflection signal to watch is EFSA enforcement of batch-level GPS coordinate documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Equipment Upgrade | Automated pressure-temperature modules from Baden-Württemberg suppliers compress payback periods for São Paulo processors. |
| EFSA Novel Food Catalog Optimization | Accelerated regulatory clearance enables faster product launches across EU member states for standardized extract grades. |
| Direct Sourcing Contract Negotiation | Multi-year agreements between Fortaleza processors and US beverage producers displace regional distributor margins. |
| Organic Cultivation Protocol Investment | Ceará state corridor expansion secures ANVISA-certified export material for premium cosmetic applications. |
| Enzyme-Assisted Extraction Adoption | Cellulase and pectinase treatments improve yield for organic-certified material targeting dermocosmetic segments. |
Research Methodology
Independent corroboration across extraction facility technical directors, nutraceutical procurement leads, and cosmetic formulation chemists underwrites the qualitative findings on supercritical CO2 adoption patterns. Primary interviews with DSM and Kemin Industries platform specialists, Duas Rodas plant managers, and Naturex regulatory affairs directors combined with secondary validation from ANVISA pharmacopeial standards, EFSA Novel Food catalog listings, and ISO 22000 audit documentation. Bottom-up volume triangulation against top-down expenditure analysis reconciles processor capacity disclosures with end-use demand segmentation.
Comparable-period anchoring to historical vitamin C substitution trends and clean-label reformulation cycles shaped the projection framework across the analysis window. Segmentation dimensions modeled include extraction method capital intensity, application certification requirements, end-user procurement sophistication, and regional regulatory cluster alignment. CAGRs derived from fitted growth curves incorporating dietary supplement maturity indicators and functional beverage expansion trajectories. Industry-specific inputs encompass electricity price volatility in Brazilian processing regions and EU Green Deal compliance timeline compression.
Revisions become necessary when EFSA enforcement of botanical authentication requirements accelerates, ANVISA export-grade standards tighten, or synthetic ascorbic acid cost advantages expand in Chinese biotechnology platforms. Deviation in EU Green Deal disclosure mandate implementation schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
North America Flavors and Fragrances Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Citrus Flavors Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Original and Flavored Syrup Market
Flavorings and Food Additives
Citrus Extract Market
Flavorings and Food Additives
North America Vanilla and Vanillin Market
Flavorings and Food Additives
Egypt Food Colorants Market
Flavorings and Food Additives
Flavoring Oil Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
Lemon Oil Market
Flavorings and Food Additives
Mandarin Oil Market
Flavorings and Food Additives
United States Food Flavor Market