
 Citrus-Based Sugar-Reduction Flavor Modulators Market | 2026-2036
Citrus-Based Sugar-Reduction Flavor Modulators Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus-Based Sugar-Reduction Flavor Modulators Market Insights
The EU Green Deal's Farm to Fork strategy is pivoting European food and beverage formulation toward botanical sugar alternatives. Givaudan leverages its integrated citrus terpene supply chain to secure consistent raw material access across Mediterranean growing regions. dsm-firmenich anchors its position through dedicated biotechnology platforms that convert citrus peel waste into high-purity flavonoid extracts. Kerry Group competes by extending its taste-modulation portfolio into clean-label bakery applications where sugar reduction challenges are most acute.
Citrus-based sugar-reduction flavor modulators comprise volatile and non-volatile compounds extracted from citrus peel, pulp, and leaf matrices, primarily limonene, citral, linalool, and bioflavonoids, functioning through sweetness potentiation, bitterness masking, and temporal flavor profile modification to enable 15-50% sugar reduction without artificial sweeteners. The limonene and citral product categories dominate current volume due to established extraction infrastructure and broad regulatory acceptance, while flavonoid segments sustain premium positioning through documented antioxidant co-benefits that support health claim substantiation. Application concentration in beverages reflects the category's high sugar visibility and consumer willingness to accept modified taste profiles in liquid formats, whereas confectionery and dairy represent higher-margin expansion zones where texture-sugar interdependencies create steeper formulation barriers.
The FDA Nutrition Innovation Strategy and WHO Guideline on Sugars Intake collectively shape product development priorities by establishing measurable reduction benchmarks that manufacturers must document. EFSA's evolving position on botanical health claims creates compliance complexity for European suppliers seeking dual-function positioning. REACH and F-Gas Regulation govern solvent-based extraction chemistries and processing emissions, respectively, influencing capital allocation toward supercritical CO2 and cold-press methods. Stakeholders must monitor pending FDA guidance on the term "natural" as it applies to enzymatically modified citrus extracts, since definitional shifts would immediately recalibrate competitive advantage between conventional and biotech-derived supply routes.
Market Dynamics
Clean-label mandates from the FDA and WHO sugar-reduction targets are forcing beverage manufacturers to source limonene and citral extracts at scale, compressing formulation timelines while expanding procurement volumes.
Growth Catalysts
- WHO Guideline on Sugars Intake:Measurable reduction benchmarks drive documented substitution protocols across carbonated drink portfolios.
- Cold-press extraction infrastructure:Capital deployment in Mediterranean processing facilities secures higher-purity terpene yields with lower solvent residues.
- Beverage reformulation:Major brands deploy limonene-citral blends to achieve 20-50% sugar reduction without artificial sweetener backlash.
Market Restraints
- Citrus peel supply concentration:Spanish and Italian growing regions dominate raw material availability, creating weather-dependent volume risk.
- REACH solvent compliance:Traditional hexane extraction faces phase-out pressure, requiring capital-intensive supercritical CO2 retooling.
- Texture-sugar interdependencies:Confectionery and dairy applications face steeper barriers than beverages due to structural binding requirements.
Strategic Opportunities
- EU Green Deal Farm to Fork:Circular economy incentives reward citrus waste valorization into flavonoid extracts.
- Bakery segment penetration:Clean-label bread and pastry applications remain underdeveloped relative to beverage saturation.
- Biotechnology convergence:Enzymatic modification of citrus matrices enables novel sweetness potentiation pathways.
Industry Challenges
- Flavor chemist talent scarcity:Formulation expertise bridging botanical extraction and taste modulation commands premium compensation.
- FDA "natural" definitional uncertainty:Pending guidance on enzymatically modified extracts creates product positioning risk.
- EFSA health claim substantiation:Dual-function positioning requires clinical documentation that extends commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus-Based Sugar-Reduction Flavor Modulators Market |
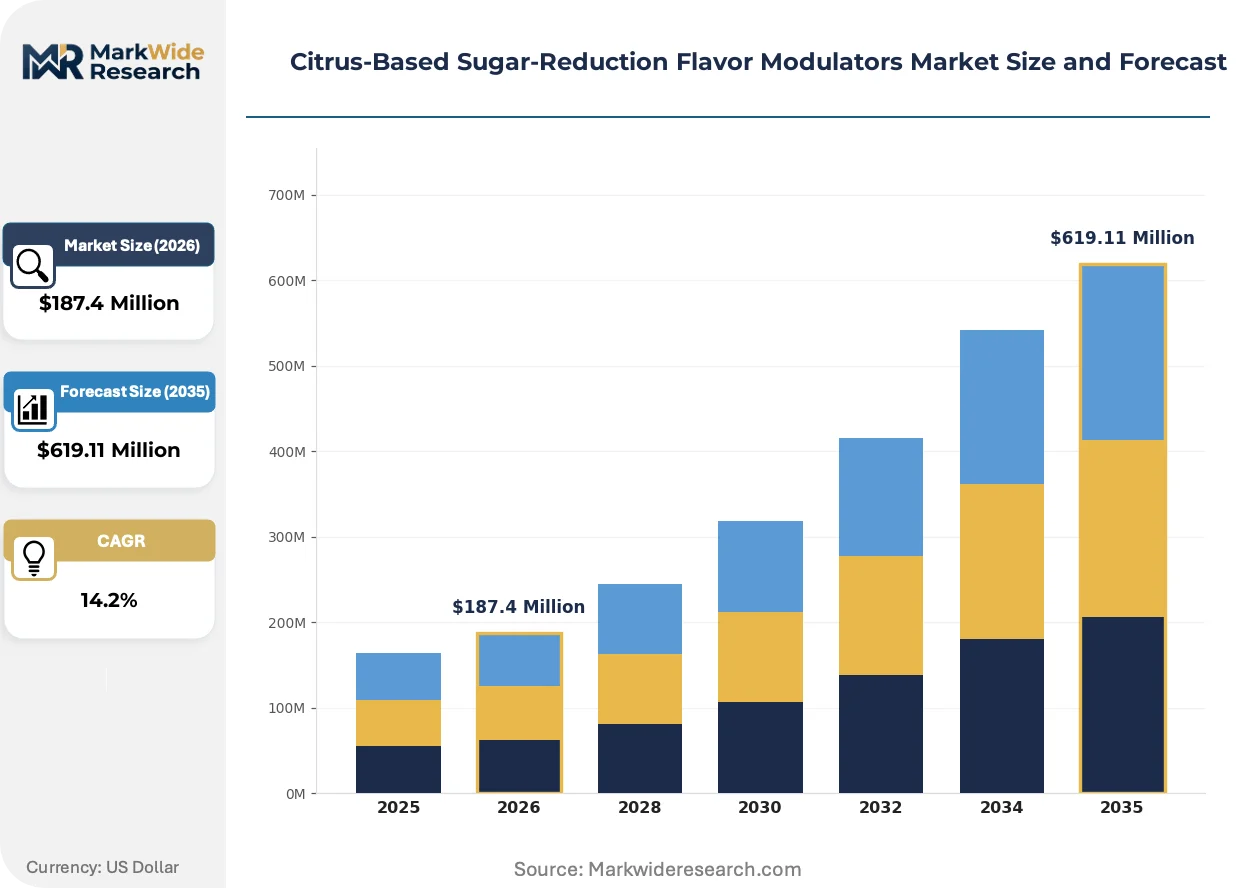
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Limonene, Citral, Linalool, Flavonoids, Terpenes Application: Beverages, Confectionery, Dairy Products, Bakery, Nutraceuticals End User: Food & Beverage Manufacturers, Ingredient Suppliers, Contract Manufacturers, Health Supplement Companies Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Foodservice Channels |
| Companies Covered | Givaudan, dsm-firmenich, Kerry Group, International Flavors & Fragrances, Symrise, Sensient Technologies, Tate & Lyle, Ingredion, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus-Based Sugar-Reduction Flavor Modulators Market Trends and Innovations
Supercritical CO2 extraction is displacing solvent-based methods across Mediterranean processing facilities, while enzymatic biotransformation unlocks novel flavonoid glycosides with enhanced sweetness potentiation.
Supercritical CO2 extraction systems now dominate new capital deployment in Spanish and Italian citrus processing. Beverage manufacturers specify this method to secure clean-label positioning and eliminate residual solvent concerns. The technology is converging with terpene fractionation to enable precise limonene-citral ratio control for customized sweetness profiles.
REACH F-Gas Regulation governs solvent emissions and processing chemistry across European extraction facilities. Compliance costs favor larger processors with integrated carbon capture, compressing the supplier base toward scaled operators. Cold-press and supercritical methods gain share as hexane alternatives face regulatory sunset.
Direct procurement contracts between beverage brands and citrus processors are shortening traditional ingredient distribution channels. Large manufacturers now secure multi-year terpene supply agreements with named Mediterranean cooperatives. This pattern is most visible in the United States, where 20% sugar reduction commitments have compressed supplier qualification timelines.
Citrus-Based Sugar-Reduction Flavor Modulators Market Segmentation
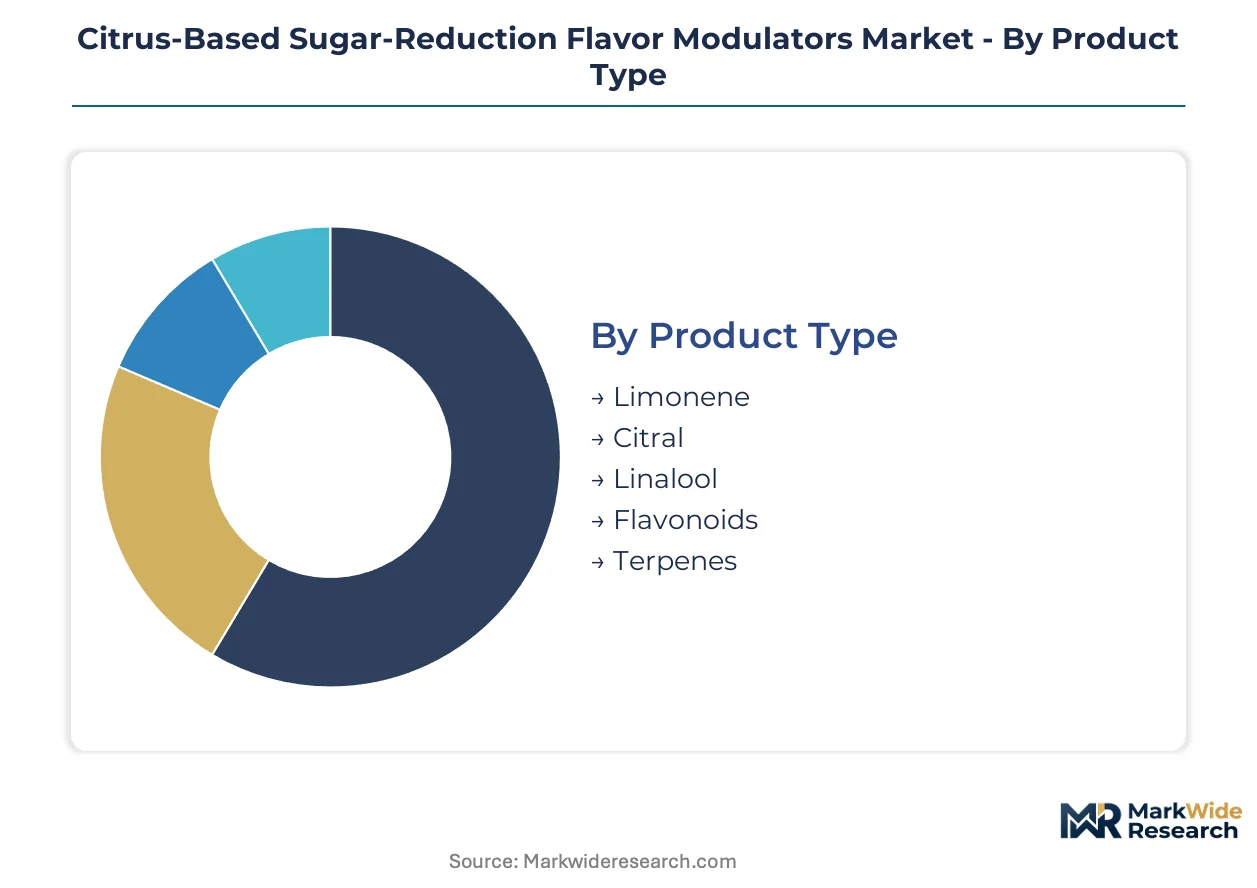
Citrus-based sugar-reduction flavor modulators serve distinct technical requirements across extraction chemistry, formulation application, and procurement relationships. Segmentation reveals where procurement volumes concentrate versus where margin expansion potential resides.
Product Type:
Reformulation cycles favor terpene profiles with established sweetness potentiation data, creating upgrade pressure on legacy extraction specifications.
- Limonene:The dominant cyclic monoterpene extracted from citrus peel oil through cold-press or steam distillation. Beverage manufacturers in the United States specify limonene for carbonated drink reformulations targeting 20% sugar reduction benchmarks under FDA guidance.
- Citral:A mixture of geranial and neral aldehydes delivering pronounced lemon aroma with documented bitterness-masking properties. European dairy processors leverage citral for reduced-sugar yogurt applications where clean-label positioning commands premium shelf placement.
- Linalool:Acyclic monoterpene alcohol with floral-citrus notes supporting temporal flavor extension in reduced-sugar matrices.
- Flavonoids:Polyphenolic compounds from citrus peel waste valorization, positioned for dual-function health claim substantiation.
- Terpenes:Broad-spectrum citrus oil fractions including pinene and myrcene for customized modulation blends.
Volume placements concentrate in limonene; the faster expansion belongs to flavonoids.
Application:
Cost-tier differentiation separates commodity beverage formulations from premium-positioned nutraceutical applications where co-benefit substantiation justifies ingredient premiums.
- Beverages:Carbonated drinks, juices, and functional waters represent the primary deployment channel. Major brands specify limonene-citral blends to achieve measurable sugar reduction without artificial sweetener backlash.
- Confectionery:Hard candies and gummies face acute texture-sugar interdependencies that steepen formulation barriers relative to liquid applications.
- Dairy Products:Yogurt and flavored milk applications in Europe leverage citral for bitterness masking when reducing added sugars.
- Bakery:Bread and pastry segments remain underdeveloped relative to beverage saturation, presenting clean-label expansion opportunities.
- Nutraceuticals:Dietary supplements and functional foods command premium positioning through documented antioxidant co-benefits.
Procurement volumes cluster in beverages; nutraceuticals capture the steepest expansion trajectory.
End User:
Customer-type concentration tilts toward integrated food and beverage manufacturers with captive formulation capabilities versus outsourced production.
- Food & Beverage Manufacturers:Large integrated processors with in-house R&D facilities and direct procurement relationships with Mediterranean citrus cooperatives.
- Ingredient Suppliers:Specialized distributors providing terpene blends and technical formulation support to mid-tier manufacturers.
- Contract Manufacturers:Third-party producers serving private-label brands with specification-driven terpene sourcing.
- Health Supplement Companies:Niche formulators prioritizing flavonoid-rich extracts for dual-function positioning in dietary supplements.
Supply relationships concentrate with food and beverage manufacturers; health supplement companies are gaining share fastest.
Distribution Channel:
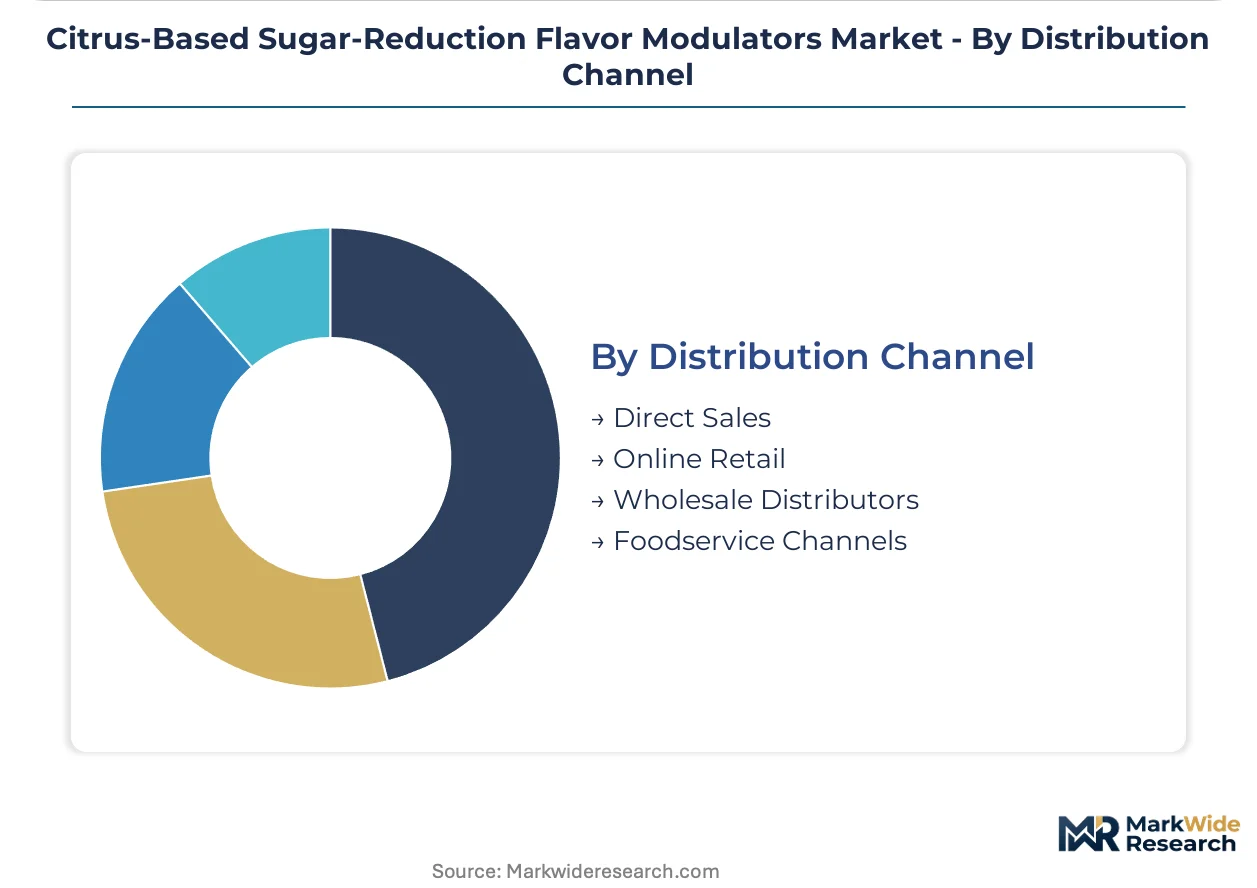
Supply chain configuration determines pricing transparency and technical service intensity, with direct sales capturing high-volume relationships.
- Direct Sales:Multi-year supply agreements between citrus processors and major beverage brands, compressing traditional distribution layers.
- Online Retail:Digital procurement platforms serving small-batch nutraceutical formulators and specialty food producers.
- Wholesale Distributors:Regional intermediaries holding terpene inventory for mid-tier manufacturers lacking direct sourcing scale.
- Foodservice Channels:Institutional and foodservice ingredient supply for commercial bakery and beverage operations.
Transaction volumes concentrate in direct sales; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Valencia anchors Mediterranean citrus processing capacity, with Spanish cooperatives supplying limonene and citral extracts to North American beverage reformulators under compressed procurement timelines.
United States
Beverage manufacturers in California and Georgia deploy limonene-citral blends to meet 20% sugar reduction commitments under FDA Nutrition Innovation Strategy guidance. The FDA's pending "natural" definition creates positioning uncertainty for enzymatically modified extracts. Chicago-based formulation labs accelerate supplier qualification for direct Mediterranean procurement contracts.
Germany
REACH F-Gas Regulation drives supercritical CO2 retooling across Baden-Württemberg extraction facilities, eliminating hexane residues from terpene production. EFSA health claim substantiation requirements complicate dual-function flavonoid positioning for dietary supplement applications. Cologne ingredient distributors consolidate terpene inventory for mid-tier European manufacturers.
Italy
Sicilian and Calabrian growing regions supply cold-pressed citrus oils to dairy processors seeking citral for reduced-sugar yogurt formulations under EU Green Deal Farm to Fork incentives. ECHA compliance costs favor scaled operators with integrated carbon capture. Milan-based flavor houses extend technical service capabilities into clean-label bakery applications.
China
Jiangxi and Sichuan provinces expand citrus peel processing for domestic beverage reformulation as SAMR tightens added-sugar labeling requirements. GB standards for natural food additives create import substitution pressure on Mediterranean terpene suppliers. Shanghai ingredient traders broker supercritical extraction technology licensing agreements with European equipment vendors.
Brazil
São Paulo state citrus processors valorize peel waste into flavonoid extracts for nutraceutical export markets. ANVISA's evolving natural ingredient framework creates compliance complexity for imported terpene specifications. Campinas research institutes collaborate with multinational beverage brands on tropical citrus varietal development for proprietary modulation profiles.
Citrus-Based Sugar-Reduction Flavor Modulators Market Competitive Landscape
Premium-margin players sit above commodity-margin players across extraction purity tiers, with supercritical CO2 specialists commanding 15-25% price premiums over solvent-based suppliers. The vendor base compresses toward scaled Mediterranean processors with REACH-compliant infrastructure and direct procurement relationships with beverage manufacturers. Three archetypes dominate: integrated flavor houses with captive citrus supply chains, biotechnology platforms converting peel waste into high-value flavonoids, and regional extraction specialists serving private-label formulators. Competitive moves concentrate on backward integration into Spanish and Italian growing cooperatives and portfolio extension from beverages into underpenetrated bakery segments.
Within the integrated flavor house tier, Givaudan and dsm-firmenich exemplify divergent supply chain strategies—Givaudan through Mediterranean terpene integration and dsm-firmenich through dedicated biotechnology platforms. Kerry Group occupies a position bridging taste-modulation expertise with clean-label bakery application development. International Flavors & Fragrances and Symrise represent scale-driven competitors with broad ingredient portfolios spanning volatile and non-volatile citrus compounds. These five entities anchor the competitive structure, with Sensient Technologies, Tate & Lyle, Ingredion, and Cargill sitting within adjacent ingredient categories that partially overlap sugar-reduction solution sets.
| Leading Market Players |
|---|
| Givaudan |
| dsm-firmenich |
| Kerry Group |
| International Flavors & Fragrances |
| Symrise |
| Sensient Technologies |
| Tate & Lyle |
| Ingredion |
| Cargill |
| Others |
Pricing and Supply Chain Analysis
Limonene spot prices from Mediterranean peel oil markets cascade through three distinct procurement tiers, compressing margins for solvent-dependent processors while rewarding supercritical CO2 operators with clean-label premiums. Beverage manufacturers in the United States and Germany now specify extraction-method certifications in purchasing contracts, forcing price stratification that separates REACH-compliant suppliers from legacy hexane operators.
Pricing Analysis
Outcome-based pricing anchored to documented sugar-reduction efficacy separates premium terpene suppliers from commodity blenders. Three-tier pricing structure across certified-supercritical, cold-press standard, and solvent-based economy levels reflects extraction purity and residual compliance. Cost compression in the economy tier intensifies as REACH F-Gas Regulation accelerates hexane phase-out capital requirements. Mid-tier beverage manufacturers exhibit highest price sensitivity, while nutraceutical formulators absorb premiums for flavonoid co-benefit substantiation.
Supply Chain Analysis
Flavor chemist scarcity in Valencia and Calabrian processing clusters constrains capacity expansion despite terpene feedstock abundance. Supply draws from Spanish citrus cooperatives, Italian cold-press specialists, and emerging Brazilian peel valorization facilities. Single-source vulnerability concentrates in Mediterranean weather-dependent harvest cycles. Distribution runs through direct procurement contracts between beverage brands and named cooperatives, compressing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction systems are displacing legacy solvent infrastructure, creating asymmetric repositioning windows for capital-rich incumbents and technology-licensing entrants.
For Market Incumbents: Extend backward integration into Sicilian and Calabrian growing cooperatives to secure captive limonene supply against weather-driven price spikes. Accelerate enzymatic biotransformation R&D to preempt FDA "natural" definition shifts that could recalibrate competitive advantage between conventional and biotechnology-derived supply routes. For New Entrants and Emerging Players: Begin with clean-label bakery applications in Germany and Italy, where sugar-reduction formulation expertise remains scarce relative to saturated beverage channels. License supercritical extraction technology from European equipment vendors rather than building captive processing capacity. Target health supplement companies seeking dual-function flavonoid positioning with documented antioxidant co-benefits. For Investors and Strategic Acquirers: Distressed-cycle entries favor biotechnology platforms with enzymatic modification capabilities in Baden-Württemberg and Shanghai licensing corridors, where REACH compliance costs compress smaller solvent-dependent operators. Long-term viability hinges on regulatory arbitrage between FDA and EFSA positioning frameworks. Monitor pending FDA guidance on enzymatically modified citrus extracts as inflection indicator for valuation recalibration across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Growing Cooperatives | Captive supply from Valencia and Calabrian cooperatives insulates against weather-driven raw material volatility. |
| Supercritical CO2 Capacity Expansion | REACH F-Gas Regulation compliance enables clean-label positioning with beverage manufacturers specifying residue-free extraction. |
| Enzymatic Biotransformation Licensing | Technology transfer agreements with Shanghai traders accelerate novel flavonoid glycoside commercialization pathways. |
| Bakery Segment Technical Service Buildout | Milan-based flavor houses extend formulation expertise into underpenetrated clean-label bread and pastry applications. |
| Direct Procurement Contract Structuring | Multi-year supply agreements with United States beverage brands compress supplier qualification timelines and distribution layers. |
Research Methodology
Document review covered EFSA health claim submissions, REACH registration dossiers, and FDA Nutrition Innovation Strategy guidance documents, complemented by interviews with extraction facility technical directors, beverage formulation chemists, Mediterranean citrus cooperative procurement managers, and clean-label ingredient distributors. Secondary validation drew from customs trade data, EU Farm to Fork strategy impact assessments, and SAMR food additive regulatory filings. Bottom-up terpene volume estimates triangulated against top-down beverage reformulation targets across the analysis window.
Segment-level outputs across extraction chemistry, application category, and end-user type were modeled using demand-side procurement surveys and supply-side capacity assessments. CAGRs were derived from weighted regression against documented sugar-reduction commitments and regulatory compliance timelines. Forecast inputs incorporated WHO guideline implementation trajectories, supercritical equipment deployment pipelines, and enzymatic technology licensing patterns.
Underlying measurement precision varies by segment; limonene and citral volume estimates carry tighter precision than emerging flavonoid categories where commercialization timelines remain uncertain. Forecasts reflect assumptions regarding FDA "natural" definition continuity, REACH enforcement intensity, and Mediterranean climatic stability. Material deviation in EFSA health claim substantiation requirements or supercritical CO2 capital cost curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Rose Water Market
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
Fiber Syrup Market
Flavorings and Food Additives
Chicken Flavor Market
Flavorings and Food Additives
Global Anthocyanin Market
Flavorings and Food Additives
Japan Food Colorants Market
Flavorings and Food Additives
Hops Essential Oil Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Bitter Apricot Extract Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
Citrus Extract Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Original and Flavored Syrup Market