
 Citrus Concentrate Market | 2026-2036
Citrus Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
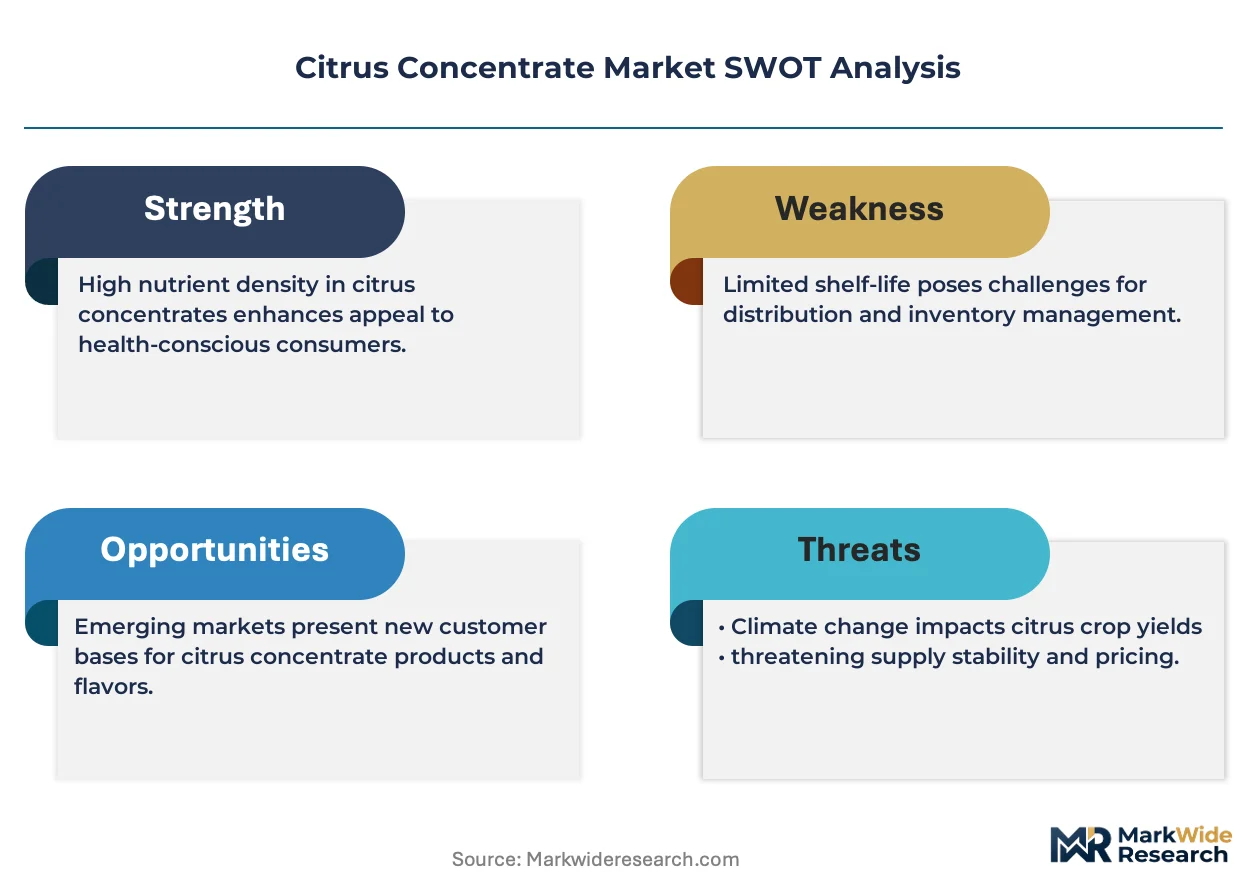
Citrus Concentrate Market Analysis
Multi-format bundling is broadening buyer choice as suppliers pair frozen concentrate with bag-in-box packaging for foodservice clients. Citrosuco S.A. leverages its integrated Brazilian citrus estates to control raw material flows from orchard to export terminal. Symrise AG differentiates through flavor-house expertise, combining concentrate supply with tailored extraction protocols for beverage manufacturers. Döhler anchors European demand with beverage compound systems that incorporate single-strength citrus bases into finished formulations.
Citrus concentrate denotes fruit juice processed through evaporation to remove water content, yielding soluble solids levels typically between 65 and 72 degrees Brix for orange variants, then reconstituted or deployed as an industrial ingredient in beverages, confectionery, and dairy applications. Frozen concentrate retains dominant volume share among product types due to established cold-chain infrastructure and extended shelf stability, while single-strength formats capture margin pools from clean-label beverage lines seeking minimal processing claims. Powdered concentrate represents the fastest-growing product type as spray-drying advances reduce thermal degradation of volatile aromatic compounds.
The FDA governs concentrate safety through juice hazard analysis critical control point rules, while EFSA and ECHA standards in Europe enforce pesticide residue thresholds and processing aid disclosures that elevate compliance costs for exporters. Brazilian MAPA inspection protocols and USDA grade standards collectively shape import-access conditions across North American and European destination markets. Stakeholders must monitor evolving cold-chain energy regulations and water-use restrictions in major growing regions to secure supply continuity.
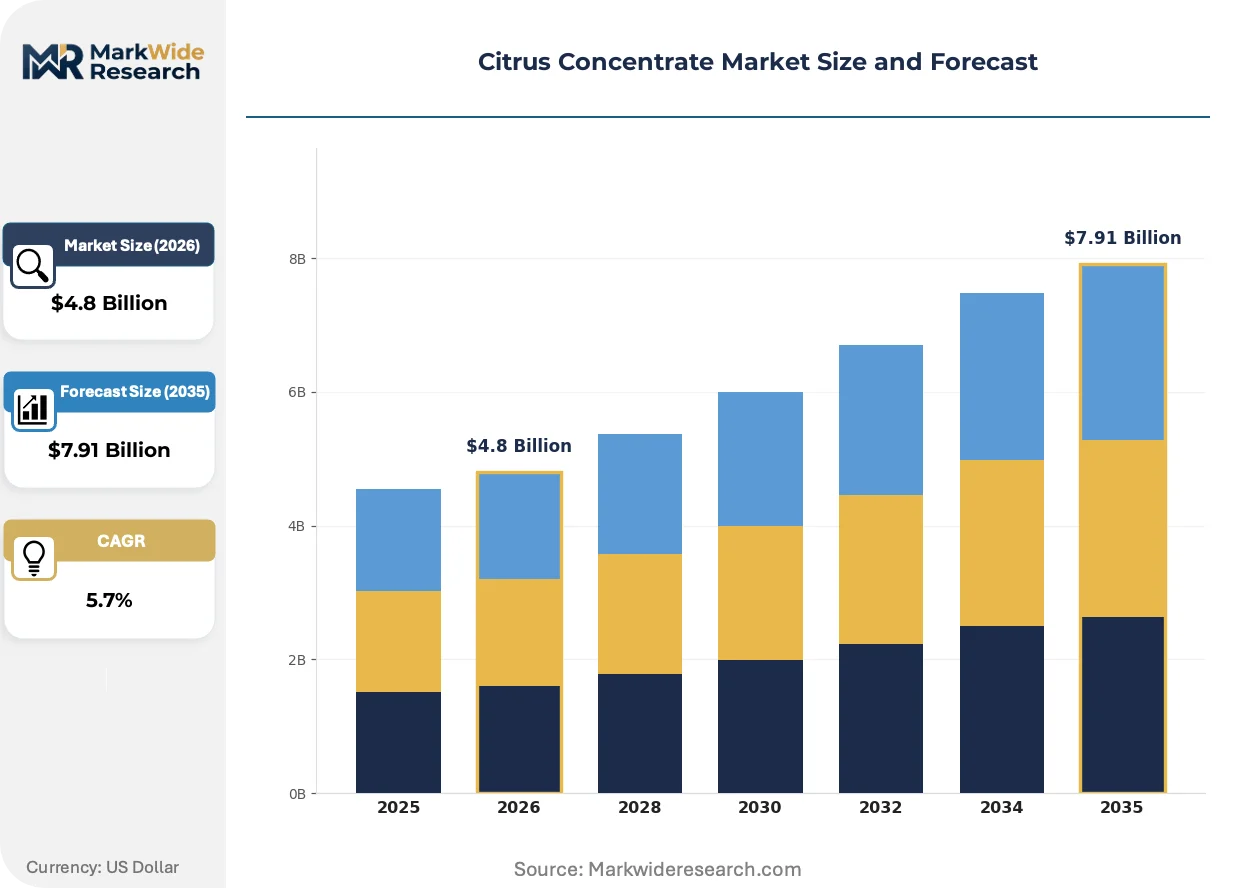
Market Dynamics
Supply consolidation in Brazilian citrus estates is compressing raw material availability for non-integrated processors, while EU F-Gas Regulation compliance costs are reshaping cold-chain investment priorities across European concentrate facilities.
Growth Catalysts
- Clean-label beverage mandates:North American retailers are demanding not-from-concentrate and single-strength formats for premium private-label juice lines, pulling concentrate suppliers toward minimal-processing certifications.
- Spray-drying technology advances:Reduced thermal degradation of volatile aromatic compounds in powdered concentrate production is opening confectionery and nutraceutical applications previously closed to citrus ingredients.
- REACH compliance infrastructure:European processing facilities that have already absorbed ECHA registration costs for extraction aids and processing chemicals now hold cost advantages in cross-border trade.
Market Restraints
- Input cost volatility:Brazilian orange crop yields swing with HLB citrus greening disease pressure and irregular rainfall patterns, destabilizing raw material pricing for non-integrated buyers.
- Supply concentration risk:São Paulo state estates controlled by two major integrated producers dominate global frozen concentrate export volumes, creating single-source vulnerability for foodservice distributors.
- Regulatory friction:EU F-Gas Regulation phasedowns on hydrofluorocarbon refrigerants are forcing cold-chain retrofits that extend lead times for temperature-controlled concentrate shipments.
Strategic Opportunities
- Underpenetrated geography:Southeast Asian beverage manufacturers in Vietnam and Indonesia remain reliant on imported single-strength orange juice, creating white space for regional concentrate-to-beverage processing partnerships.
- Emerging application:Powdered citrus concentrates are displacing artificial flavor systems in plant-based dairy alternatives, with oat and almond milk processors seeking clean-label acidulation.
- Regulatory tailwind:India's FSSAI tightened fruit juice labeling standards are pushing domestic bottlers toward concentrate-based formulations that can meet stricter soluble solids and additive disclosure rules.
Industry Challenges
- Cold-chain capex intensity:Frozen concentrate storage and transport requires continuous refrigeration infrastructure that strains working capital for mid-scale distributors expanding into emerging markets.
- Certification timeline compression:EFSA novel food approvals for new citrus varietal concentrates and extraction byproducts face 18-24 month evaluation windows that delay product launch schedules.
- Legacy equipment integration:European processors retrofitting evaporator systems for F-Gas compliance must reconcile new thermal efficiency standards with existing bag-in-box filling line configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Concentrate Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Concentrate, Single Strength, Powdered, NFC Juice End User: Beverage Manufacturers, Food Processors, Bakery, Exporters Packaging Type: Drum, Tetra Pak, Bag-in-Box, Bulk Tanker Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Citrosuco S.A., Symrise AG, Cargill Incorporated, Takasago International Corporation, Sunkist Growers Inc., Archer Daniels Midland Company, Döhler, Cutrale, Louis Dreyfus Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Concentrate Market Emerging Trajectories
Processing technology diffusion and regulatory chemistry requirements are fragmenting traditional concentrate supply relationships while creating new entry points for specialized extraction houses and regional bottling partnerships.
Membrane filtration systems are decentralizing evaporator capacity away from centralized Brazilian mega-facilities toward regional processing hubs in Mexico, Spain, and South Africa. Mid-scale beverage compounders in these markets are adopting reverse osmosis and aroma recovery units that previously required capital scales only major integrators could deploy. This geographic redistribution of processing capability is compressing freight costs for European and North American buyers while fragmenting historical supply relationships anchored in São Paulo export terminals.
EU F-Gas Regulation phasedown schedules are forcing refrigerant transitions in cold-chain logistics that cascade into concentrate storage economics. Processors must replace hydrofluorocarbon systems with ammonia or CO2 alternatives that demand facility redesigns and extended commissioning periods. Brazilian exporters shipping frozen concentrate to Rotterdam and Hamburg face the steepest compliance cost gradients, while Moroccan and Spanish suppliers with shorter EU transit distances capture relative advantage in landed cost calculations.
Foodservice distributors are consolidating purchase specifications around dual-format suppliers capable of delivering both frozen concentrate and aseptic single-strength products under unified quality certifications. Large contract caterers and quick-service chains in the United States are reducing vendor counts from four or five to two or three approved suppliers, with technical service capabilities and traceability documentation outweighing price in selection criteria. This consolidation pattern is most pronounced in institutional channels serving schools and healthcare facilities where USDA grade standards and FDA juice HACCP compliance are non-negotiable entry requirements.
Citrus Concentrate Market Segmentation
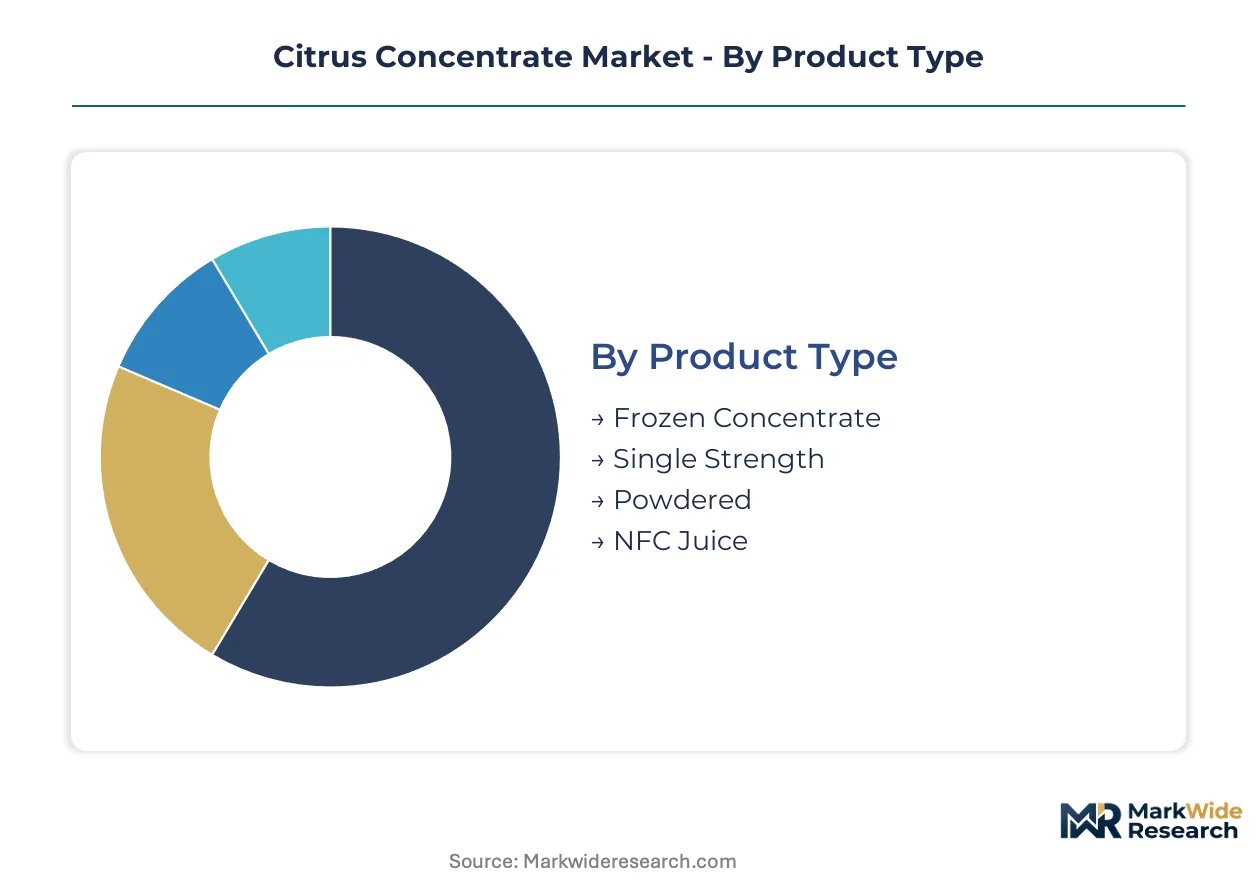
Citrus concentrate suppliers structure their portfolios around thermal stability requirements and customer scale. Product format selection determines cold-chain investment, while packaging and channel choices reflect whether buyers operate as integrated beverage compounders or distributed foodservice networks.
Product Type:
Frozen concentrate commands volume leadership through established refrigerated infrastructure, while powder formats capture premium expansion from clean-label applications.
- Frozen Concentrate:Evaporated to 65–72 degrees Brix and flash-frozen for industrial reconstitution. Brazilian exporters in São Paulo state anchor supply for North American beverage manufacturers seeking bulk input for private-label juice lines.
- Single Strength:Unconcentrated juice preserved through pasteurization or aseptic processing. European beverage compounders in Spain and Germany prioritize this format for premium not-from-concentrate claims that satisfy EFSA labeling expectations.
- Powdered:Spray-dried concentrate with reduced thermal degradation of volatile aromatics. Functional food processors in nutraceutical and confectionery segments drive adoption.
- NFC Juice:Not-from-concentrate format with minimal processing credentials. Clean-label mandates from US retailers propel procurement for premium chilled juice portfolios.
Today's leader: Frozen Concentrate. Tomorrow's challenger: Powdered.
End User:
Scale and formulation complexity separate integrated compounders from ingredient buyers seeking standardized inputs.
- Beverage Manufacturers:Large-scale compounders blend concentrate bases with flavor systems, acidulants, and fortificants. Döhler and Symrise supply these operators with integrated compound systems that incorporate citrus bases into finished formulations.
- Food Processors:Manufacturers of sauces, dressings, and prepared meals require consistent acid profiles and color stability. Bag-in-box packaging dominates procurement specifications for mid-volume production runs.
- Bakery:Citrus concentrates provide moisture retention and flavor in industrial baking applications. Powdered formats gain preference for dry mix incorporation.
- Exporters:Trading houses and regional distributors aggregate concentrate for re-export to secondary markets. Bulk tanker and drum shipments characterize this channel.
Beverage Manufacturers consolidate purchasing power. Food Processors expand fastest as prepared meal segments multiply.
Packaging Type:
Thermal exposure tolerance and handling automation determine format selection across the value chain.
- Drum:Steel or plastic containers for frozen concentrate storage. Cold-chain distributors in Rotterdam and Hamburg maintain drum inventory for foodservice reprocessors.
- Tetra Pak:Aseptic cartons for single-strength and NFC products. European retail channels specify this format for shelf-stable juice distribution.
- Bag-in-Box:Flexible pouches within corrugated shells for foodservice dispensing. US contract caterers consolidate vendor lists around suppliers offering unified bag-in-box certifications.
- Bulk Tanker:Refrigerated road and ocean containers for high-volume concentrate movement. Citrosuco and Cutrale deploy dedicated tanker fleets from Brazilian export terminals.
Bag-in-Box dominates foodservice. Bulk Tanker anchors intercontinental trade.
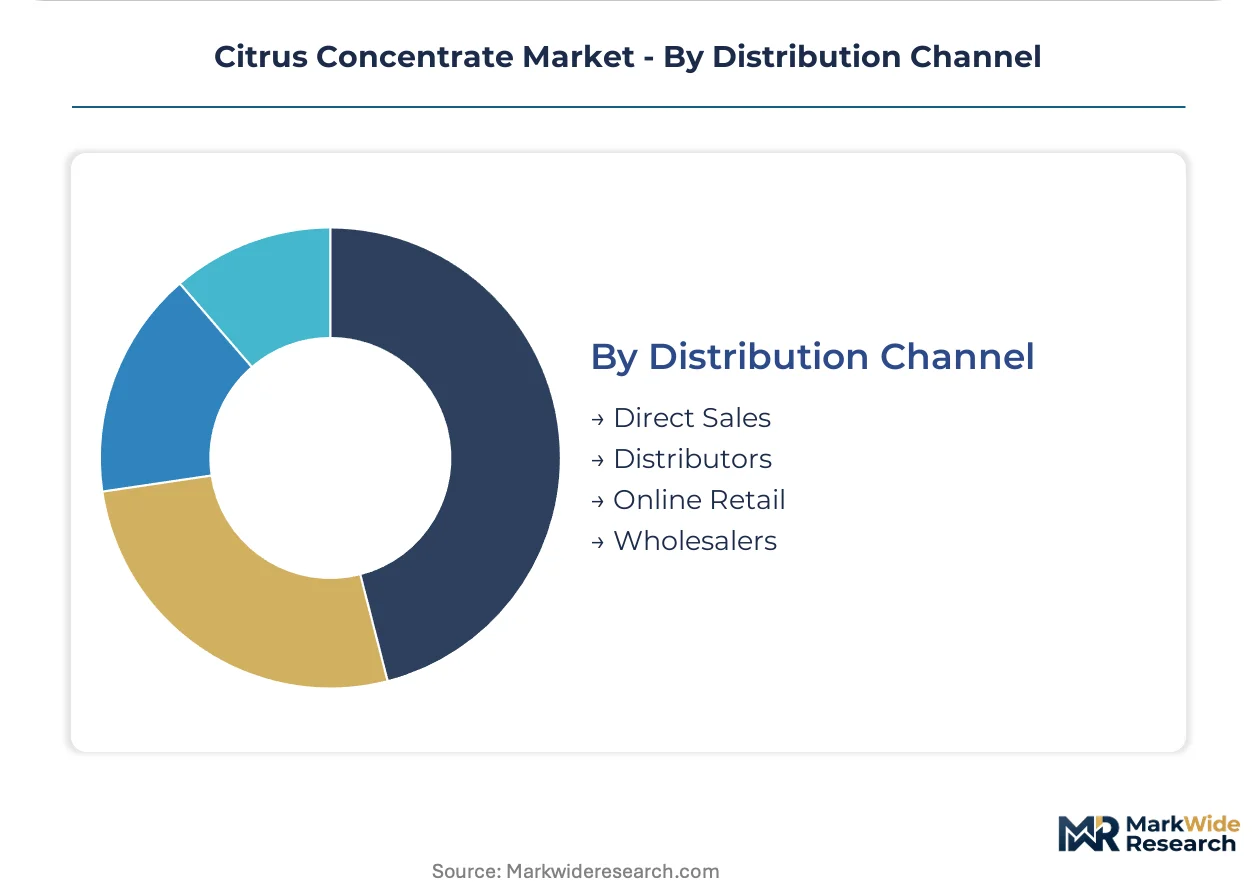
Distribution Channel:
Traceability documentation and technical service capabilities increasingly outweigh price in channel selection.
- Direct Sales:Long-term contracts between integrated producers and major beverage compounders. Citrosuco's estate-to-terminal integration enables direct allocation to multinational customers.
- Distributors:Regional intermediaries holding refrigerated inventory for smaller processors. EU F-Gas compliance costs compress margins for distributors operating aging cold-chain assets.
- Online Retail:Emerging channel for specialty and organic concentrate variants. Limited to ambient-stable powdered formats given logistics constraints.
- Wholesalers:Aggregators serving fragmented foodservice and bakery accounts. Consolidation pressure reduces approved supplier counts from five to two or three in US institutional channels.
Direct Sales captures volume concentration. Distributors face margin compression from regulatory compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil pioneered industrial-scale citrus concentrate production during the 1960s, establishing São Paulo state as the foundational processing cluster that still shapes global supply patterns today.
Brazil
Integrated estate operators in São Paulo state control upstream orange supply for frozen concentrate export. MAPA inspection protocols enforce phytosanitary standards that condition North American and European market access. São Paulo's Araraquara processing corridor hosts the densest concentration of evaporator capacity outside Florida.
United States
Florida's diminished orange crop has shifted procurement dependence toward Brazilian imports for beverage manufacturing. FDA juice HACCP rules mandate pathogen control systems that elevate processing costs for domestic reconstitution facilities. California's Central Valley now anchors NFC and single-strength production for West Coast chilled juice distribution.
Germany
Beverage compounders in Hamburg and Frankfurt source concentrate bases for European private-label juice formulations. ECHA REACH registration requirements for processing aids create compliance cost barriers for non-EU exporters. The Port of Rotterdam cold-chain hub serves German distributors with Brazilian frozen concentrate shipments.
Spain
Mediterranean citrus estates in Valencia province supply regional processors with late-season orange varieties for single-strength extraction. EU F-Gas Regulation phasedowns are forcing refrigerant transitions in Murcia and Seville storage facilities. Spanish processors leverage shorter EU transit distances against Brazilian competitors on landed cost calculations.
India
Domestic beverage bottlers in Maharashtra and Karnataka are reformulating around concentrate inputs to meet FSSAI tightened labeling standards. Import tariffs on orange juice concentrate protect local Nagpur sweet orange processors from Brazilian price competition. Pune-based contract manufacturers are emerging as regional blending hubs for Southeast Asian re-export.
Citrus Concentrate Market Vendor Landscape
Premium-margin players sit above commodity-margin players across integration depth and cold-chain control capabilities. The supplier base organizes into three tiers: estate-integrated Brazilian exporters commanding raw material access, European flavor houses bundling concentrate with formulation services, and regional distributors holding refrigerated inventory for fragmented foodservice accounts. Consolidation pressure favors dual-format suppliers capable of delivering frozen concentrate alongside aseptic single-strength products. Capacity expansion in membrane filtration and spray-drying capabilities represents the dominant competitive move.
Among estate-integrated Brazilian operators, Citrosuco S.A. and Cutrale occupy positions defined by captive orchard supply and dedicated export terminal infrastructure. Symrise AG and Döhler exemplify the European compounder archetype, anchoring demand through integrated beverage formulation systems rather than commodity concentrate supply. These named entities represent the structural poles between upstream agricultural control and downstream technical service capabilities.
| Leading Market Players |
|---|
| Citrosuco S.A. |
| Symrise AG |
| Cargill Incorporated |
| Takasago International Corporation |
| Sunkist Growers Inc. |
| Archer Daniels Midland Company |
| Döhler |
| Cutrale |
| Louis Dreyfus Company |
| Others |
Supply Flow & Price Mechanics
Large beverage compounders in North America and Europe command volume-based contract structures that anchor pricing stratification across premium, standard, and economy tiers. Their procurement consolidation toward dual-format suppliers capable of delivering frozen concentrate alongside aseptic single-strength products compresses margins for regional distributors unable to match unified certification packages.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates estate-integrated Brazilian exporters from regional distributors and spot-market traders. Price differentiation rests on cold-chain certification grade and volume scale, with USDA grade standards and FDA juice HACCP compliance commanding measurable premiums. Cost compression in the economy tier is intensifying because EU F-Gas Regulation retrofits extend lead times for temperature-controlled shipments. Foodservice distributors show highest price sensitivity, while multinational beverage manufacturers prioritize technical service capabilities over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with São Paulo state estates controlled by Citrosuco and Cutrale, which anchor global frozen concentrate export volumes. Geographic supply concentration centers on Brazil, Spain, and the United States, with raw material dependencies drawing from Brazilian orange crops, Mediterranean late-season varieties, and Florida's diminished but still relevant processing infrastructure. Supply chain risk manifests as tariff exposure from India's import duties on orange juice concentrate. Distribution runs through dedicated bulk tanker fleets from Brazilian export terminals to Rotterdam and Hamburg cold-chain hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where clean-label beverage mandates pull procurement toward minimal-processing certifications and traceability documentation. The shift from artificial flavor systems to powdered citrus concentrates in plant-based dairy alternatives exemplifies premium specification demand.
For Market Incumbents: Lock in estate-to-terminal integration advantages by expanding membrane filtration capacity in regional processing hubs beyond São Paulo. Secure USDA grade standards and FDA juice HACCP certifications as non-negotiable entry requirements for institutional channels serving schools and healthcare facilities. Add spray-drying capabilities to capture functional food segment expansion in confectionery and nutraceutical applications.
For New Entrants and Emerging Players: India's FSSAI tightened fruit juice labeling standards opens a window for concentrate-based formulation partnerships with domestic bottlers in Maharashtra and Karnataka. Target Southeast Asian beverage manufacturers in Vietnam and Indonesia through regional blending hubs in Pune. Establish technical service capabilities around bag-in-box packaging and unified quality certifications to differentiate from commodity traders.
For Investors and Strategic Acquirers: European flavor houses are the most active acquirer in this space, seeking backward integration into citrus estate assets to secure raw material flows. The acquisition target archetype is mid-scale regional processors with existing ECHA REACH registration infrastructure and established distributor relationships. Watch for inflection when EU F-Gas Regulation compliance costs trigger distressed asset opportunities among aging cold-chain operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Decentralizes evaporator capacity from São Paulo toward regional hubs in Mexico and Spain. |
| Spray-Drying Technology Investment | Captures confectionery and nutraceutical demand with reduced thermal degradation of volatile aromatics. |
| Estate-to-Terminal Integration | Secures captive orange supply for Brazilian exporters facing HLB citrus greening disease pressure. |
| Dual-Format Supplier Certification | Meets foodservice distributor consolidation toward unified frozen and aseptic product portfolios. |
| Regional Blending Hub Development | Positions Pune and Southeast Asian partners for FSSAI-compliant re-export to fragmented markets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with beverage compounder procurement directors, cold-chain logistics operators, and ECHA regulatory compliance officers with secondary validation. Primary sources included citrus estate operations managers, foodservice distributor category buyers, and spray-drying technology specialists. Secondary data drew from USDA grade standards documentation, FDA juice HACCP guidance, EU F-Gas Regulation phasedown schedules, and Brazilian MAPA inspection protocols. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Historical reference periods anchored the forecast window to pre-pandemic baseline demand patterns and post-regulatory-adjustment supply configurations. The analytical framework modeled product type, end user, packaging format, and distribution channel dimensions across the projection horizon. CAGRs derived from segment-level growth rate blending and cross-referencing with input cost trajectories. Forecast inputs included Brazilian orange crop yield volatility indices and EU cold-chain retrofit completion timelines.
Revisions become necessary when HLB citrus greening disease pressure materially alters São Paulo state yield assumptions or when EU F-Gas Regulation enforcement accelerates beyond modeled phasedown schedules. Forecasts reflect documented assumptions about clean-label mandate adoption curves and spray-drying technology diffusion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Argentina Food Flavor and Enhancer Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Bergamot Extract Market
Flavorings and Food Additives
Lemon Extract Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Dairy Flavors Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
Mint Essential Oils Market
Flavorings and Food Additives
Soy Sauce Powder Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Natural Food Colors Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
United States Food Colorants Market